
 Asia-Pacific Surveillance Analog Camera Market | 2026-2036
Asia-Pacific Surveillance Analog Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Surveillance Analog Camera Market Insights
Modular kit bundling of cameras with digital video recorders is pivoting procurement patterns across municipal and commercial buyers in the Asia-Pacific Surveillance Analog Camera Market. Hikvision Digital Technology Co., Ltd leverages its integrated manufacturing scale to dominate bundled system tenders across Chinese provincial projects. Panasonic Corporation anchors its position through specialized ruggedized configurations for Japan's railway and port authorities. Dahua Technology Co., Ltd competes aggressively on channel control, extending distributor incentives that lock in small-to-mid enterprise deployments across Southeast Asia.
Asia-Pacific surveillance analog cameras transmit video signals through coaxial cable infrastructure without IP encoding, typically operating at resolutions up to 1080p via HD-TVI or HD-CVI protocols to serve legacy security installations where full network replacement costs prove prohibitive. HD-TVI segments sustain the largest installed base across budget-conscious municipal retrofits in India and Indonesia, while AHD formats capture growing share among Thailand's hospitality sector where compatibility flexibility matters. CVBS endpoints occupy declining but residual demand from Vietnam's rural government facilities with decades-old coaxial plant.
China's SAMR enforces GB standards that mandate electromagnetic compatibility and environmental durability testing for analog security equipment sold domestically, while India's BIS certification regime blocks non-compliant imports at customs checkpoints. Japan's METI-administered JIS standards shape product specifications for earthquake-resistant mounting and thermal tolerance in industrial settings. Stakeholders must monitor whether India's PLI scheme for electronics manufacturing expands to cover analog camera components, potentially redirecting supply chain investment toward domestic assembly capacity.
Market Dynamics
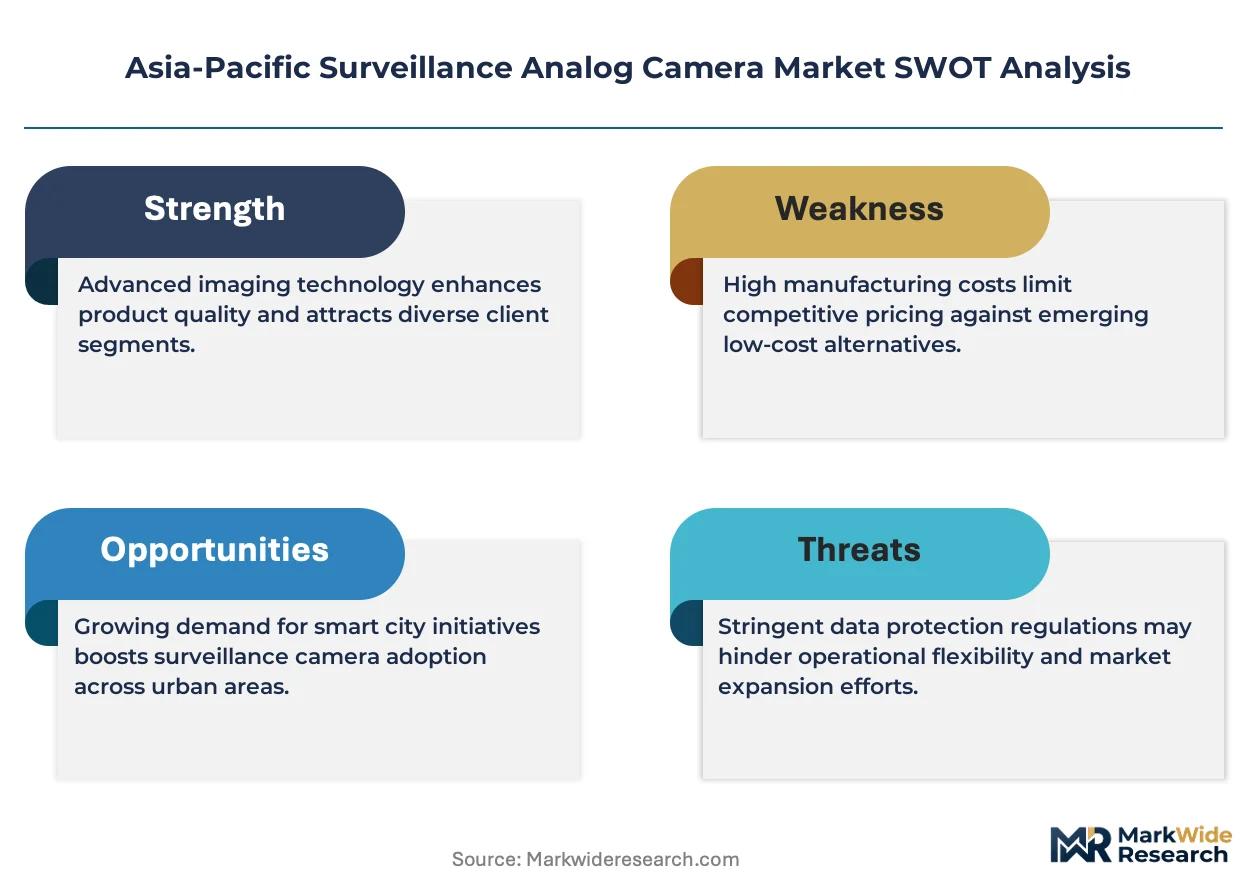
Legacy coaxial infrastructure across Southeast Asian municipalities locks in analog-over-coax procurement cycles despite IP alternatives, while India's BIS certification and China's GB standards erect compliance barriers that filter supplier participation.
Growth Catalysts
- Smart City Mandates:India's urban infrastructure modernization drives sustained tender volumes for HD-TVI bundled systems across municipal surveillance deployments.
- Transportation Corridor Upgrades:Indonesia's railway and highway authorities prioritize cost-effective analog retrofits over full network replacements in budget-constrained expansion zones.
- HD-TVI Protocol Dominance:Backward compatibility with existing coaxial plant preserves analog camera relevance in India's tier-2 and tier-3 city deployments.
Market Restraints
- Copper Cable Input Volatility:Fluctuating copper prices compress margins for coaxial-dependent system integrators serving price-sensitive municipal buyers.
- IP Camera Substitution:Declining unit costs of networked surveillance equipment erode analog's total-cost-of-ownership advantage in greenfield installations.
- Cross-Border Compliance Friction:India's BIS certification blocks non-compliant imports at customs, lengthening supplier qualification timelines for foreign manufacturers.
Strategic Opportunities
- Vietnam Rural Government Facilities:CVBS endpoint demand persists in remote provincial installations where decades-old coaxial infrastructure defies replacement economics.
- Thailand Hospitality Sector:AHD format flexibility captures growing share among hotels and resorts requiring multi-protocol compatibility without infrastructure overhaul.
- PLI Scheme Expansion:India's production-linked incentive scheme for electronics manufacturing may extend to analog camera components, redirecting supply chain investment toward domestic assembly capacity.
Industry Challenges
- HD-TVI/AHD/CVBS Protocol Fragmentation:Incompatible signaling standards force integrators to maintain multi-format inventory and diagnostic expertise, inflating project complexity.
- Certification Timeline Compression:China's SAMR electromagnetic compatibility testing and India's BIS laboratory queues extend product launch cycles by quarters.
- Legacy System Integration:Hybrid deployments combining analog endpoints with digital recorders demand specialized engineering talent scarce across Southeast Asian system integrator channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Surveillance Analog Camera Market |
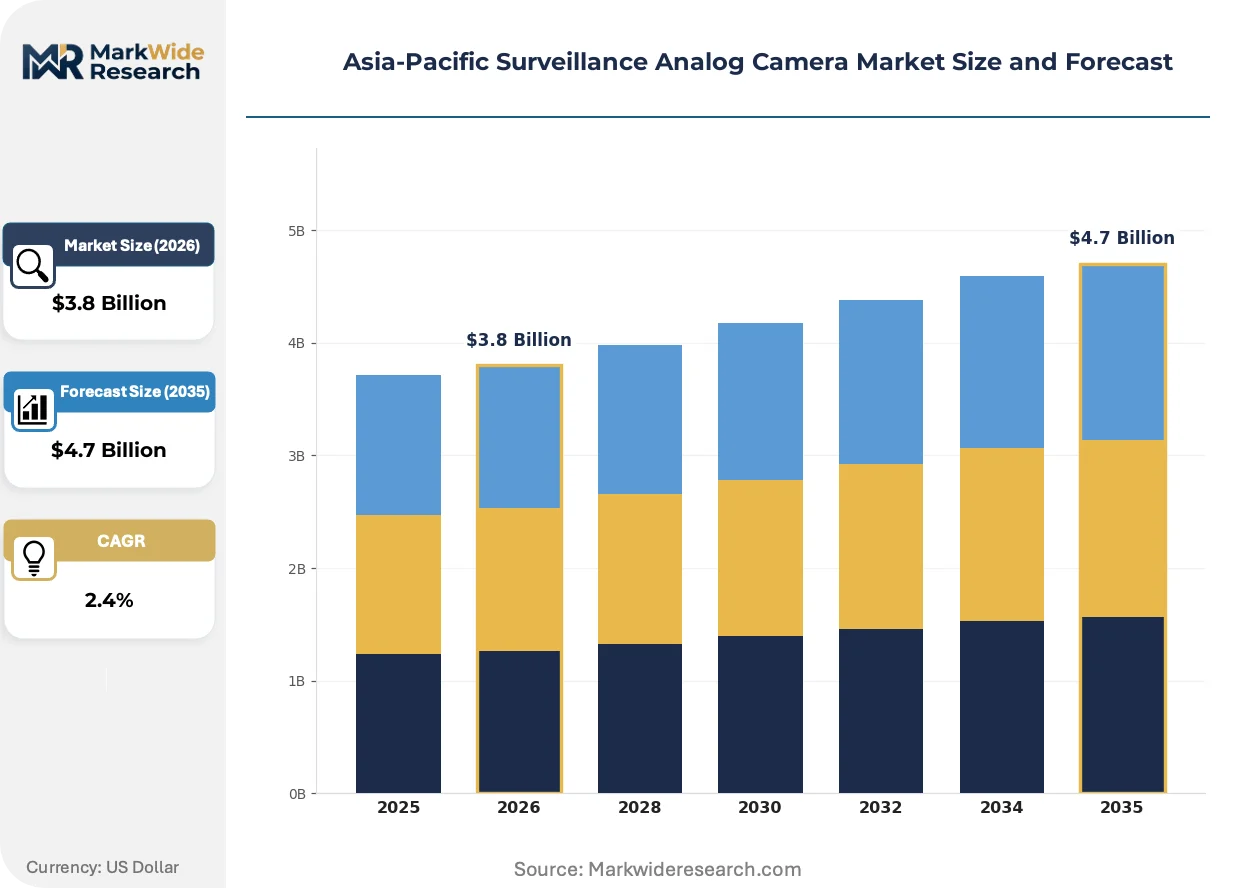
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $4.7 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HD-CVI, HD-TVI, AHD, CVBS End User: Retail, Hospitality, Transportation, Government Installation Type: Indoor, Outdoor, Hybrid, Mobile Technology: Infrared, Low Light, PTZ, Wireless |
| Companies Covered | Zhejiang Uniview Technologies Co., Ltd, Panasonic Corporation, Hikvision Digital Technology Co., Ltd, Axis Communications, Sony Corporation, Dahua Technology Co., Ltd, Bosch Sicherheitssysteme GmbH, Honeywell International Inc, Hanwha Vision, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Surveillance Analog Camera Market Trends and Innovations
Signal processing advances and procurement model evolution are compressing analog's functional gap with IP systems while reshaping how municipal and commercial buyers source surveillance infrastructure across the Asia-Pacific region.
HD-TVI signal encoding is expanding into higher resolution tiers previously exclusive to networked cameras, enabling 1080p transmission over standard coaxial cable without infrastructure replacement. Municipal retrofit contractors in Indonesia and the Philippines are adopting these enhanced endpoints at accelerating pace to meet specification requirements without triggering capital expenditure approvals for full network overhauls. This capability expansion is compressing the performance differential that previously drove greenfield projects toward IP-exclusive designs.
China's SAMR enforcement of GB standards for electromagnetic compatibility and environmental durability is tightening product qualification thresholds for equipment sold domestically. Manufacturers must submit to mandatory testing protocols that extend development cycles and eliminate marginal suppliers from provincial tender participation. Japanese industrial buyers under METI-administered JIS standards are responding with earthquake-resistant mounting specifications that analog camera vendors must engineer to maintain railway and port authority contracts.
Municipal procurement offices across India and Indonesia are unbundling camera-DVR kits that previously shipped as integrated systems, forcing suppliers to price components separately and compete on individual line-item value. This disaggregation disrupts the bundled margin structures that dominant manufacturers leveraged to lock in multi-year municipal contracts. The pattern is most visible in India's smart city surveillance deployments where tender transparency rules now mandate component-level bidding to prevent single-source lock-in.
Asia-Pacific Surveillance Analog Camera Market Segmentation
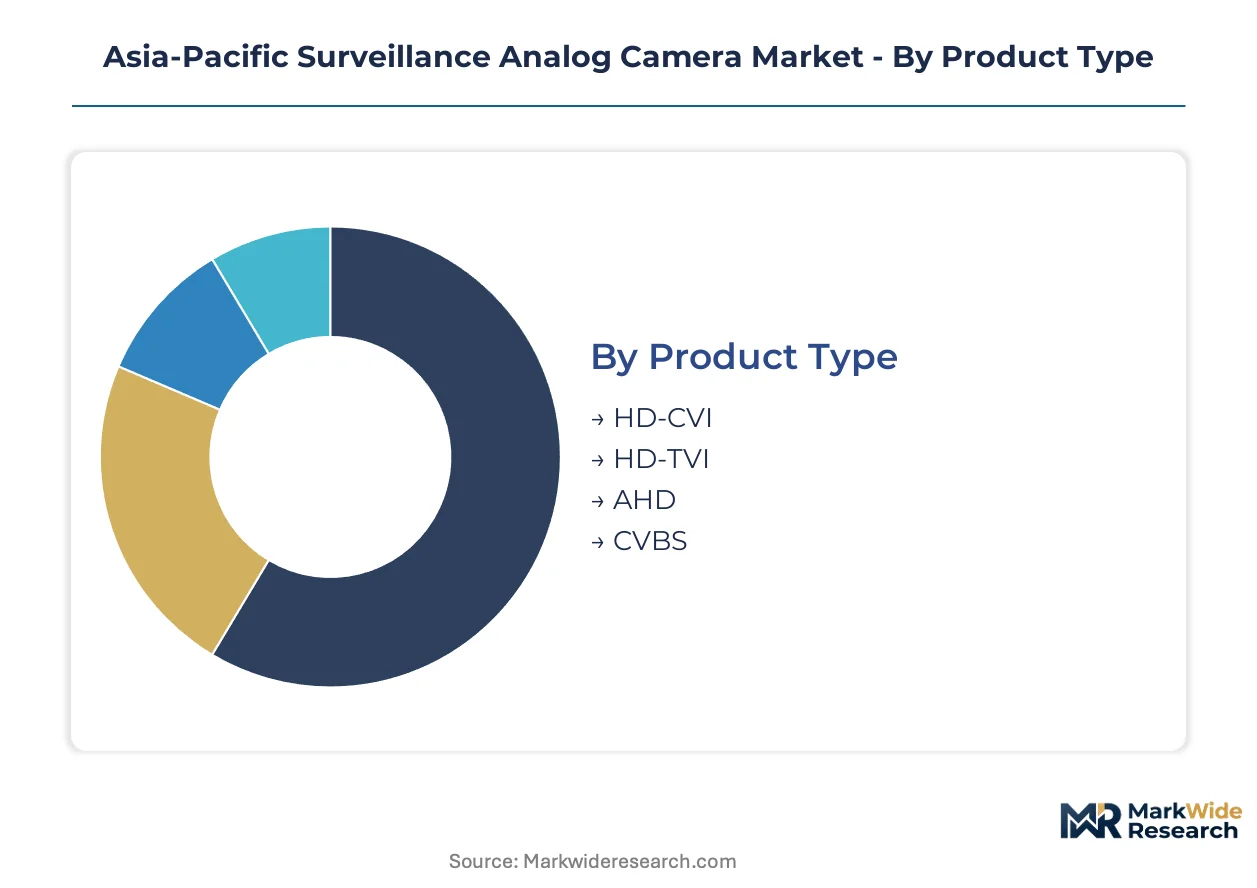
Protocol compatibility and infrastructure legacy dictate procurement decisions across Asia-Pacific surveillance analog camera deployments. Municipal buyers prioritize backward-compatible formats that avoid coaxial replacement costs, while commercial end-users balance specification flexibility against integration complexity.
Product Type:
HD-TVI commands the volume tier through municipal retrofit dominance, while AHD captures premium positioning via hospitality flexibility.
- HD-TVI:Transmits uncompressed 1080p video over standard coaxial cable using time-division multiplexing. India's tier-2 and tier-3 smart city deployments drive sustained tender volumes for HD-TVI bundled systems where infrastructure replacement budgets remain constrained.
- HD-CVI:Employs differential signal processing to extend transmission distances without repeaters. China's provincial security projects under SAMR GB standards certification favor HD-CVI for its electromagnetic compatibility performance in high-interference urban environments.
- AHD:Offers multi-protocol compatibility that reduces inventory complexity for Thailand's hotel and resort integrators serving mixed-format legacy installations.
- CVBS:Persists in Vietnam's rural government facilities where decades-old coaxial plant defies capital expenditure approval for infrastructure overhaul.
Today's leader: HD-TVI. Tomorrow's challenger: AHD.
End User:
Government contracts anchor procurement scale, while hospitality's protocol flexibility demands reshape supplier margin structures.
- Government:Municipal surveillance tenders across India and Indonesia specify HD-TVI systems for smart city and transportation corridor deployments. BIS certification requirements and GB standards compliance filter supplier participation, extending qualification timelines for foreign manufacturers.
- Hospitality:Thailand's hotel sector favors AHD format flexibility for multi-protocol compatibility without infrastructure replacement. Property developers prioritize rapid deployment over resolution maximization in greenfield resort construction.
- Transportation:Indonesia's railway authorities prioritize cost-effective analog retrofits over full network replacements in budget-constrained expansion zones.
- Retail:Small-to-mid enterprise deployments across Southeast Asia concentrate on HD-TVI bundled kits with digital video recorders for loss prevention applications.
Government procurement concentrates volume. Hospitality applications expand fastest.
Installation Type:
Outdoor specifications dominate municipal specification sheets, while mobile deployments emerge in transportation monitoring applications.
- Outdoor:Weather-resistant housings with IP66 ratings serve Indonesia's highway authority corridor upgrades and India's urban perimeter surveillance. SAMR GB standards mandate environmental durability testing for electromagnetic compatibility in coastal and industrial zones.
- Indoor:Compact dome configurations target Thailand's hospitality sector and retail loss prevention deployments where aesthetic integration matters.
- Hybrid:Combines analog endpoints with digital recorder infrastructure to bridge legacy and modern surveillance requirements.
- Mobile:Vibration-resistant mounting systems serve railway and port authority deployments under Japan's METI-administered JIS standards for earthquake tolerance.
Outdoor installations lock in municipal demand. Mobile configurations gain transportation sector traction.
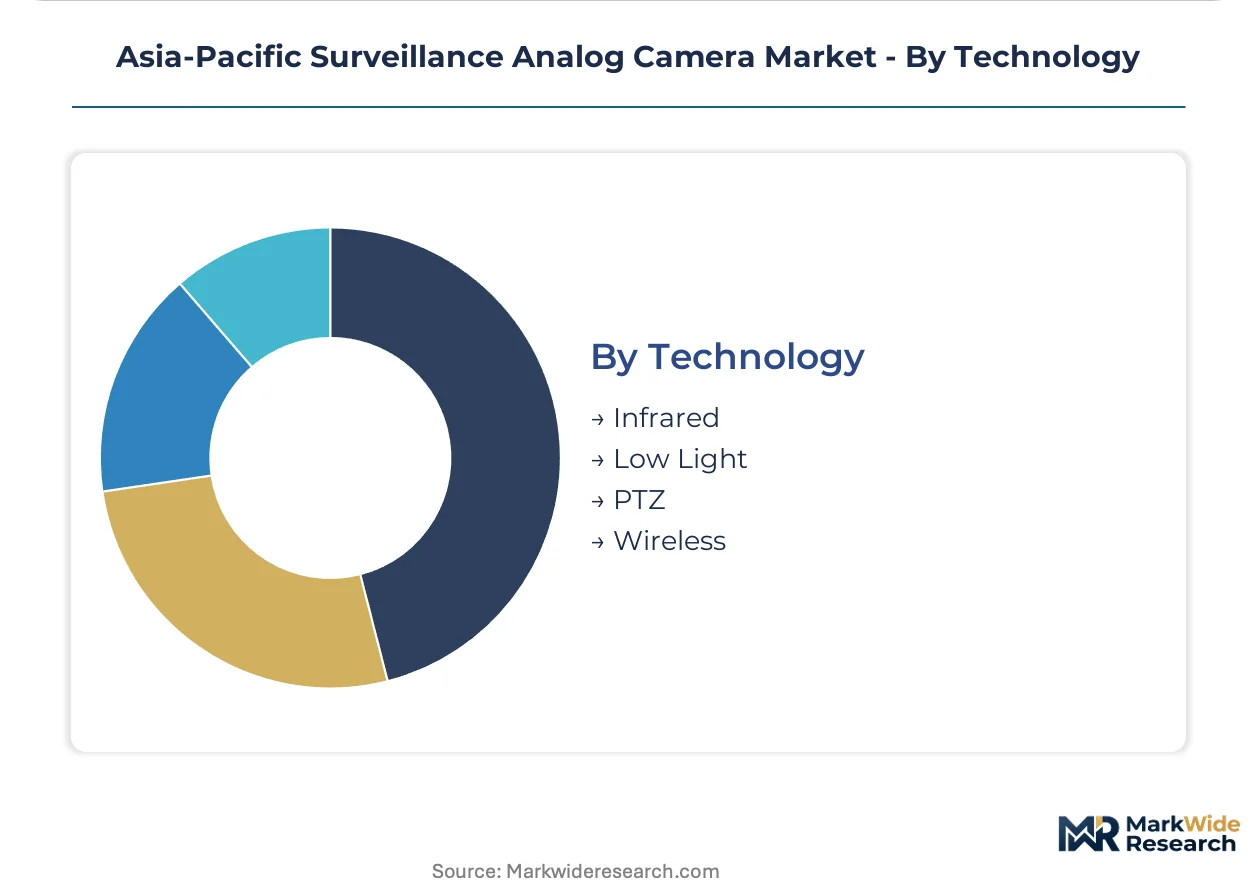
Technology:
Infrared capability separates baseline from premium tier offerings, while PTZ functionality commands specification priority in perimeter applications.
- Infrared:850nm and 940nm wavelength options enable night vision capture without visible illumination. India's municipal tenders increasingly specify minimum infrared range requirements for 24-hour surveillance coverage in smart city deployments.
- PTZ:Pan-tilt-zoom mechanisms with preset patrol patterns serve Indonesia's port authority perimeter monitoring where operator-controlled surveillance replaces fixed-position coverage gaps.
- Low Light:Starlight sensors extend usable imaging into near-dark conditions without active infrared illumination for Thailand's hospitality sector aesthetic requirements.
- Wireless:Analog-over-wireless bridge solutions address temporary deployment scenarios and retrofit constraints where coaxial cable routing proves impractical.
Infrared dominates specification sheets. PTZ commands premium positioning in perimeter applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surveillance analog camera manufacturing scaled first through Japanese industrial conglomerates in the 1980s, then migrated to Chinese coastal provinces as component ecosystems matured. Today procurement concentrates in four national markets where legacy coaxial infrastructure, regulatory certification regimes, and municipal budget cycles sustain analog-over-coax demand despite IP alternatives.
China
Provincial security projects under SAMR GB standards certification drive HD-CVI procurement for electromagnetic compatibility in high-interference urban corridors. Yangtze River Delta manufacturing clusters supply integrated bundled systems to municipal tender winners. Shenzhen and Hangzhou anchor production of HD-TVI chipsets that feed Southeast Asian retrofit markets.
India
Tier-2 and tier-3 smart city deployments sustain HD-TVI tender volumes where infrastructure replacement budgets remain constrained. BIS certification requirements block non-compliant imports at customs checkpoints, extending foreign supplier qualification timelines. Maharashtra and Karnataka state governments concentrate perimeter surveillance procurement for urban infrastructure modernization.
Indonesia
Railway and highway authorities prioritize cost-effective analog retrofits over full network replacements in budget-constrained expansion zones. Transportation corridor upgrades across Java and Sumatra specify weather-resistant outdoor configurations with IP66 ratings. Jakarta municipal tenders unbundle camera-DVR kits under new transparency rules mandating component-level bidding.
Japan
METI-administered JIS standards shape earthquake-resistant mounting and thermal tolerance specifications for railway and port authority contracts. Kanto region railway operators specify vibration-resistant mobile configurations for rolling stock surveillance. Osaka-Kobe port clusters demand ruggedized analog endpoints for perimeter monitoring where salt corrosion accelerates equipment replacement cycles.
Thailand
Hospitality sector developers favor AHD format flexibility for multi-protocol compatibility without infrastructure overhaul in greenfield resort construction. Bangkok hotel chains and Phuket resort operators prioritize rapid deployment over resolution maximization. Eastern Economic Corridor infrastructure projects incorporate hybrid analog-digital configurations bridging legacy and modern surveillance requirements.
Asia-Pacific Surveillance Analog Camera Market Competitive Landscape
The competitive structure tilts toward integrated manufacturing conglomerates with captive component supply and provincial government relationships. Three archetypes dominate: scale-driven bundled system suppliers, specialized ruggedized equipment fabricators, and channel-controlled distributors serving small-to-mid enterprise segments. M&A activity concentrates on vertical integration into coaxial cable and digital video recorder manufacturing. Strategic partnerships between chipset designers and municipal tender winners lock in multi-year procurement cycles.
Within the integrated manufacturing tier, Hikvision Digital Technology Co., Ltd and Dahua Technology Co., Ltd exemplify scale-driven bundled system suppliers with provincial project dominance. Panasonic Corporation occupies a position among specialized ruggedized equipment fabricators serving railway and port authority specifications. These three anchors represent divergent competitive vectors: manufacturing scale, specialized engineering, and channel control.
| Leading Market Players |
|---|
| Zhejiang Uniview Technologies Co., Ltd |
| Panasonic Corporation |
| Hikvision Digital Technology Co., Ltd |
| Axis Communications |
| Sony Corporation |
| Dahua Technology Co., Ltd |
| Bosch Sicherheitssysteme GmbH |
| Honeywell International Inc |
| Hanwha Vision |
| Others |
Pricing and Supply Chain Analysis
Captive component manufacturing across China's Yangtze River Delta anchors pricing power for integrated suppliers serving municipal tender markets. Hikvision Digital Technology Co., Ltd and Dahua Technology Co., Ltd leverage in-house HD-TVI chipset production to compress bundled system costs below channel-dependent competitors, while India's BIS certification requirements force foreign suppliers to absorb extended qualification timelines that erode margin flexibility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ruggedized mobile configurations for Japan's railway authorities from basic HD-TVI endpoints for India's tier-3 municipal deployments. Price differentiation hinges on electromagnetic compatibility certification tier under SAMR GB standards and after-sales service bundling. Cost compression in standard-tier municipal contracts intensifies because copper cable input volatility squeezes system integrator margins. India's smart city procurement offices exhibit highest price sensitivity, while Thailand's hospitality developers prioritize rapid deployment over unit cost minimization.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Hangzhou, and Guangzhou anchor hub-and-spoke patterns feeding Southeast Asian retrofit markets. Manufacturing concentrates in China, Taiwan, and South Korea for image sensors and signal processing chipsets. Raw material dependencies draw from copper cable suppliers in Jiangsu province and polycarbonate housing fabricators in Zhejiang. Single-source vulnerability around HD-TVI protocol licensing from Techpoint Inc. threatens supply continuity for non-captive manufacturers. Distribution runs through authorized distributor networks serving Indonesia's transportation corridor contractors and India's state-level system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in premium-tier mobile configurations and certified component bundling as municipal procurement disaggregation forces suppliers to capture value through specification differentiation rather than volume lock-in.
For Market Incumbents: Cement provincial government relationships through pre-certified HD-CVI bundled systems that compress competitor qualification timelines under SAMR GB standards. Deepen backward integration into coaxial cable manufacturing to offset copper price volatility squeezing system integrator partners. Defend against IP camera substitution by emphasizing infrastructure replacement cost avoidance in India's tier-2 city tenders. For New Entrants and Emerging Players: Begin with Vietnam's rural government facilities where CVBS endpoint demand persists and foreign supplier presence remains thin. Target Thailand's hospitality sector AHD deployments where multi-protocol flexibility matters more than manufacturing scale. Pursue white-label partnerships with established distributors locked out of Hikvision and Dahua channel programs. For Investors and Strategic Acquirers: Consolidation pressure builds where BIS certification bottlenecks strand undercapitalized foreign suppliers in India's customs queues. Long-term viability favors manufacturers with captive chipset supply and provincial tender relationships extending across multiple analysis windows. Acquisition target archetype: mid-scale HD-CVI specialists with SAMR pre-certification and dormant distributor relationships in Indonesia. Watch for India's PLI scheme expansion announcement as inflection signal redirecting supply chain investment toward domestic assembly capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Investment | Early SAMR GB standards compliance secures provincial tender participation before competitors clear laboratory queues. |
| Backward Integration | In-house coaxial cable production insulates margin structures from copper commodity volatility hitting system integrators. |
| Channel Partnership Lock-in | Exclusive distributor incentives across Southeast Asia capture small-to-mid enterprise deployments beyond municipal tender reach. |
| Protocol Licensing Acquisition | Direct HD-TVI or HD-CVI technology access eliminates royalty burdens and accelerates product development cycles. |
| Hybrid System Engineering | Analog-digital bridge expertise commands premium positioning in Indonesia's transportation corridor upgrades. |
Research Methodology
Multiple input streams — municipal tender documentation, distributor inventory audits, and chipset supply chain interviews — were reconciled to construct market size estimates. Primary discussions with system integrator procurement heads, state government surveillance project officers, and SAMR certification laboratory directors informed demand-side validation. Secondary sources included India's BIS public certification database, Indonesia's LPSE tender portal disclosures, and China Customs trade flow records. Bottom-up channel checks across tier-2 and tier-3 cities were cross-referenced against top-down manufacturing output estimates from Yangtze River Delta industrial zone reports.
Historical shipment patterns from 2019 through 2024 were cross-referenced against panel input from procurement directors at India's smart city special purpose vehicles and Indonesia's railway authority engineering divisions. Segmentation modeling incorporated protocol type, end-use vertical, installation environment, and certification tier across the projection horizon. CAGRs were derived from regression analysis of tender volume trends and infrastructure budget allocation patterns. Forecast inputs included copper price trajectory assumptions and IP camera substitution elasticity coefficients specific to municipal retrofit economics.
Several conditions sit outside the modeled scope, including potential PLI scheme coverage expansion, abrupt IP camera cost discontinuities, and geopolitical trade restriction escalations affecting component flows. Forecasts reflect documented assumptions around infrastructure replacement budget continuity and certification timeline stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Mexico Video Surveillance Market
Video Surveillance Systems
In-Vehicle Video Surveillance Market
Video Surveillance Systems
Europe Surveillance Camera Market
Video Surveillance Systems
Europe Video Surveillance Systems Market
Video Surveillance Systems
United States Surveillance Analog Camera Market
Video Surveillance Systems
Asia Pacific Surveillance IP Camera Market
Video Surveillance Systems
Video Surveillance Software Market
Video Surveillance Systems
Asia-Pacific Surveillance Storage Market
Video Surveillance Systems
North America Crawler Camera System Market
Video Surveillance Systems
Mexico Surveillance IP Camera Market
Video Surveillance Systems
Video Surveillance and Vsaas Market
Video Surveillance Systems
United States Surveillance Camera Market
Video Surveillance Systems
Crawler Camera System Market
Video Surveillance Systems
India Video Surveillance Market
Video Surveillance Systems
Camera Alarm System Market
Video Surveillance Systems
3D Surveillance Software Market