
 Body Protection Equipment Market | 2026-2036
Body Protection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Body Protection Equipment Market Analysis
Project finance and operating lease structures for PPE procurement is fragmenting traditional ownership models across industrial end users. MSA Safety Incorporated leverages its rental and managed service programs to sustain recurring revenue streams in heavy manufacturing. Honeywell International Inc. anchors its position through backward integration into advanced material science for ballistic and thermal protection systems.
Body protection equipment encompasses helmets, gloves, vests, and goggles engineered from polycarbonate, Kevlar, and nylon composites to absorb impact, resist penetration, and shield against thermal, chemical, or ballistic hazards in occupational environments. Helmets manufactured through injection-molded polycarbonate shells with multi-density EPS liners dominate procurement volumes across construction and warehousing end users. Kevlar-reinforced gloves and vests command premium positioning in manufacturing and utilities where ANSI cut-level and ASTM flame-resistance certifications determine contract eligibility.
OSHA enforces 29 CFR 1910.132 general industry standards for hazard assessment and equipment selection, while the EU PPE Regulation 2016/425 mandates CE marking and notified body certification for market access across member states. ISO 45001 occupational health management systems and ANSI Z89.1 head protection standards further shape product design cycles and testing protocols for multinational suppliers. Stakeholders must monitor evolving state-level adoption of OSHA-aligned rules in the United States and the trajectory of EU harmonized standards under the CSRD due diligence framework to anticipate compliance cost shifts and certification bottlenecks.
Market Dynamics
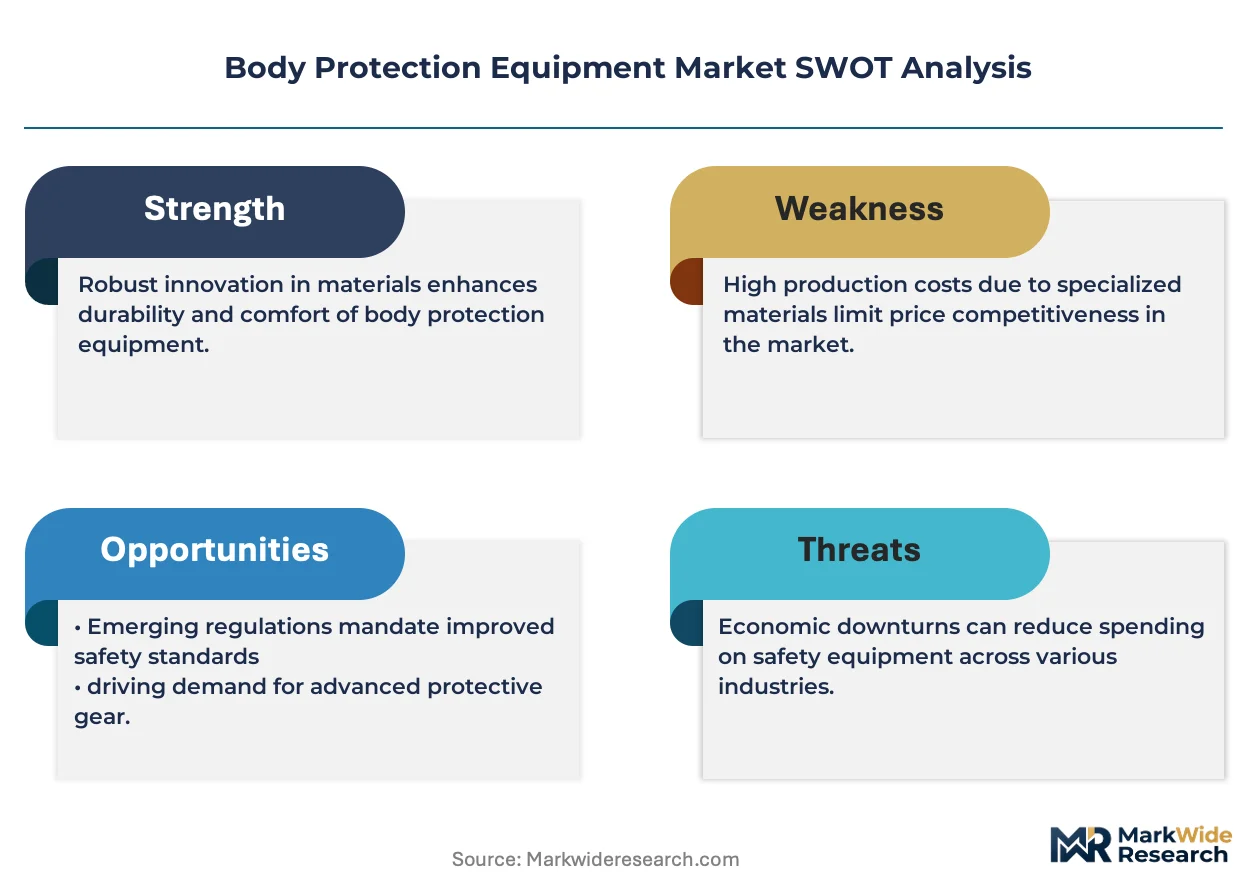
Composite material substitution is compressing traditional polycarbonate dominance as Kevlar-nylon hybrids penetrate construction and manufacturing procurement specifications.
Growth Catalysts
- OSHA 29 CFR 1910.132 enforcement:Mandatory hazard assessment protocols in US manufacturing and warehousing are accelerating replacement cycles for non-compliant legacy equipment.
- Construction sector expansion:Infrastructure investment across China, India, and the United States is driving procurement of ANSI Z89.1-certified helmets and cut-resistant glove systems.
- Advanced composite manufacturing:Injection-molded multi-density EPS liner technology is enabling lighter head protection with superior impact absorption ratings.
Market Restraints
- Aramid fiber cost volatility:Kevlar and Twaron raw material prices fluctuate with petrochemical feedstock markets, squeezing margin structures for ballistic and cut-resistant product lines.
- CE marking bottlenecks:EU PPE Regulation 2016/425 notified body capacity constraints are extending certification timelines for Asian manufacturers seeking European market access.
- Technical limitation in thermal-barrier integration:Current material science cannot simultaneously optimize flame resistance, breathability, and weight below 300 grams for full-coverage vests.
Strategic Opportunities
- India industrial safety enforcement:State-level adoption of BIS standards and factory inspectorate expansion in Maharashtra and Gujarat is creating first-time buyer markets for certified equipment.
- Rental and managed service programs:Heavy manufacturing and utilities are shifting from capital purchase to operating lease models for high-turnover glove and helmet inventories.
- Sensor-embedded PPE convergence:Integration of IoT impact detection and biometric monitoring into hard hats is opening premium positioning for connected worker safety platforms.
Industry Challenges
- Certification timeline compression:ANSI and ASTM testing protocol updates are forcing suppliers to maintain parallel certification tracks across multiple standard revisions.
- Specialized polymer compounding expertise:Shortage of materials engineers capable of formulating custom polycarbonate-ABS blends for region-specific impact requirements is constraining product development velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Body Protection Equipment Market |
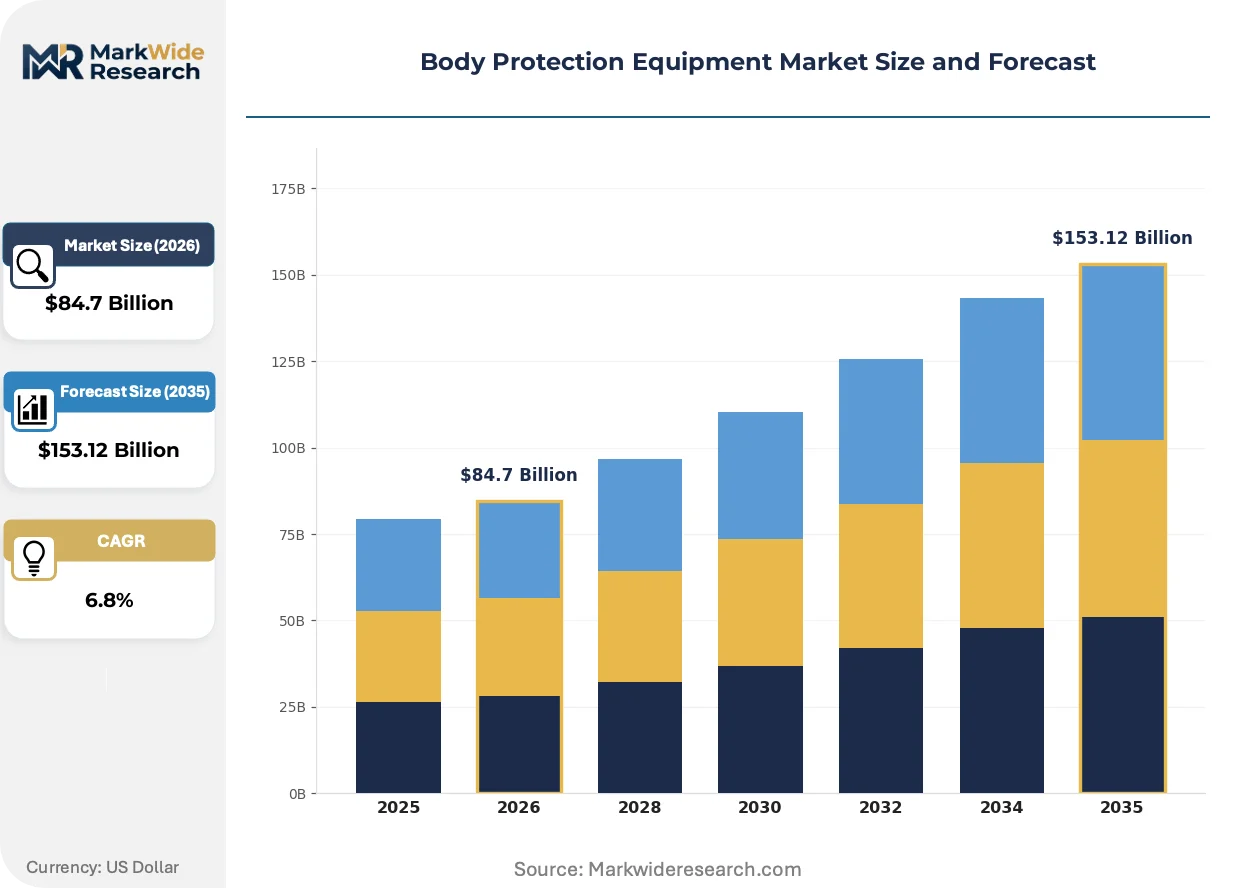
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $153.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helmets, Gloves, Vests, Goggles End User: Construction, Manufacturing, Healthcare, Warehousing Material: Polycarbonate, Nylon, Leather, Kevlar Certification: ANSI, ISO, CE, ASTM |
| Companies Covered | 3M, Honeywell International Inc., DuPont, MSA Safety Incorporated, Ansell Ltd., Lakeland Industries Inc., Alpha Pro Tech, Radians Inc., Protective Industrial Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Body Protection Equipment Market Emerging Trajectories
Material science breakthroughs and regulatory harmonization pressures are actively restructuring competitive advantage in protective equipment manufacturing.
Non-Newtonian shear-thickening fluid liners integrated into soft body armor are rendering obsolete traditional rigid plate designs for law enforcement and private security applications. US municipal police departments and European border control agencies are piloting these systems at scale. The technology is compressing the weight-performance tradeoff that previously segmented premium and standard ballistic protection tiers.
EU PPE Regulation 2016/425 module B+C2 conformity assessment routes are forcing Asian exporters to establish European Economic Area-based quality assurance partnerships. Industrial glove manufacturers in China and Vietnam face expanded surveillance audit obligations. The heaviest compliance burden falls on cut-resistant sleeve and apron suppliers serving German automotive assembly plants.
Buyer consolidation among multinational construction and logistics operators is compressing supplier rosters and unbundling after-sales service from equipment procurement. Tier-one contractors in the United States and Australia now demand vendor-managed inventory with usage-based billing. This pattern is most visible in warehousing and e-commerce fulfillment center networks where glove consumption rates vary seasonally.
Body Protection Equipment Market Segmentation
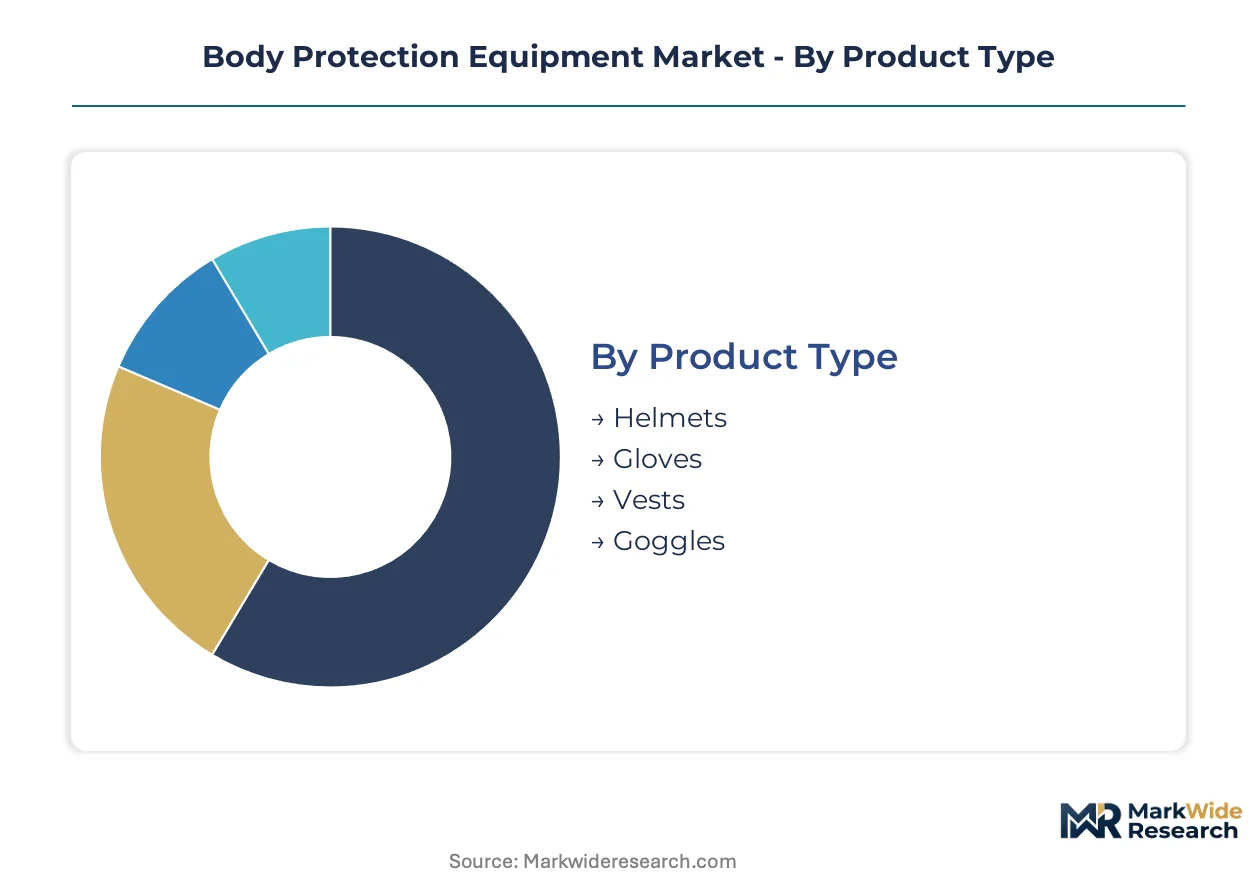
Procurement patterns across body protection equipment diverge sharply by hazard exposure, regulatory environment, and material substitution economics. Understanding segment boundaries clarifies where certification premiums command pricing power versus where commodity dynamics erode margin.
Product Type:
Mature injection-molded categories dominate procurement volumes while emerging composite technologies reshape performance tiers.
- Helmets:Multi-density EPS liners bonded to polycarbonate or ABS shells absorb impact energy through controlled compression. Construction procurement in the United States and China concentrates ANSI Z89.1 Type I and Type II classifications, with state-level OSHA enforcement accelerating replacement of legacy suspension systems.
- Gloves:Kevlar-nylon hybrids and nitrile-dipped cut-resistant layers protect against mechanical hazards in manufacturing and warehousing. German automotive assembly plants and Japanese electronics fabrication facilities specify EN 388 Level 5 cut resistance, squeezing out leather alternatives in precision handling applications.
- Vests:Soft armor panels using aramid or UHMWPE fibers provide ballistic and stab protection for security and law enforcement.
- Goggles:Polycarbonate lenses with anti-fog and anti-scratch coatings seal against chemical splash and particulate hazards in laboratory and industrial settings.
Helmets retain volume leadership across industrial end uses; gloves hold the steepest expansion curve as cut-resistant specifications penetrate warehousing and logistics networks.
End User:
Cost tier stratification separates capital-intensive infrastructure investment from high-turnover consumable procurement.
- Construction:Infrastructure investment in India, the United States, and China drives bulk procurement of ANSI Z89.1 helmets and steel-toe protective footwear. Tier-one contractors in Australia and Canada now mandate vendor-managed inventory with usage-based billing for high-consumption items.
- Manufacturing:Automotive, electronics, and food processing facilities specify chemical-resistant gloves and impact-rated eyewear under ISO 45001 management systems. Japanese automotive OEMs and German machine tool producers enforce the strictest certification requirements.
- Healthcare:Biocontainment and splash protection requirements concentrate demand in surgical masks, face shields, and disposable gowns.
- Warehousing:E-commerce fulfillment centers in the United States and China consume cut-resistant gloves at seasonal peaks, favoring rental and managed service programs over capital purchase.
Construction anchors absolute procurement value; warehousing is expanding most quickly as logistics automation intensifies hand-protection requirements.
Material:
Supply concentration in petrochemical feedstocks and aramid fiber production shapes cost volatility and regional sourcing strategies.
- Polycarbonate:Injection-molded shells for helmets and eyewear leverage bisphenol-A derived resins with high optical clarity and impact resistance. Chinese resin producers and Saudi petrochemical complexes supply feedstock for Asian and European molding operations.
- Kevlar:DuPont's para-aramid fiber commands premium positioning in ballistic vests and cut-resistant gloves despite price volatility tied to petrochemical markets. United States municipal police departments and European border agencies specify Kevlar-reinforced soft armor over generic alternatives.
- Nylon:Polyamide fibers provide abrasion resistance and moisture management in glove liners and textile-based protection.
- Leather:Natural hide materials persist in welding and heavy manufacturing applications requiring heat resistance and durability.
Polycarbonate maintains volume dominance across head and eye protection; Kevlar captures the highest value per kilogram in specialized hazard applications.
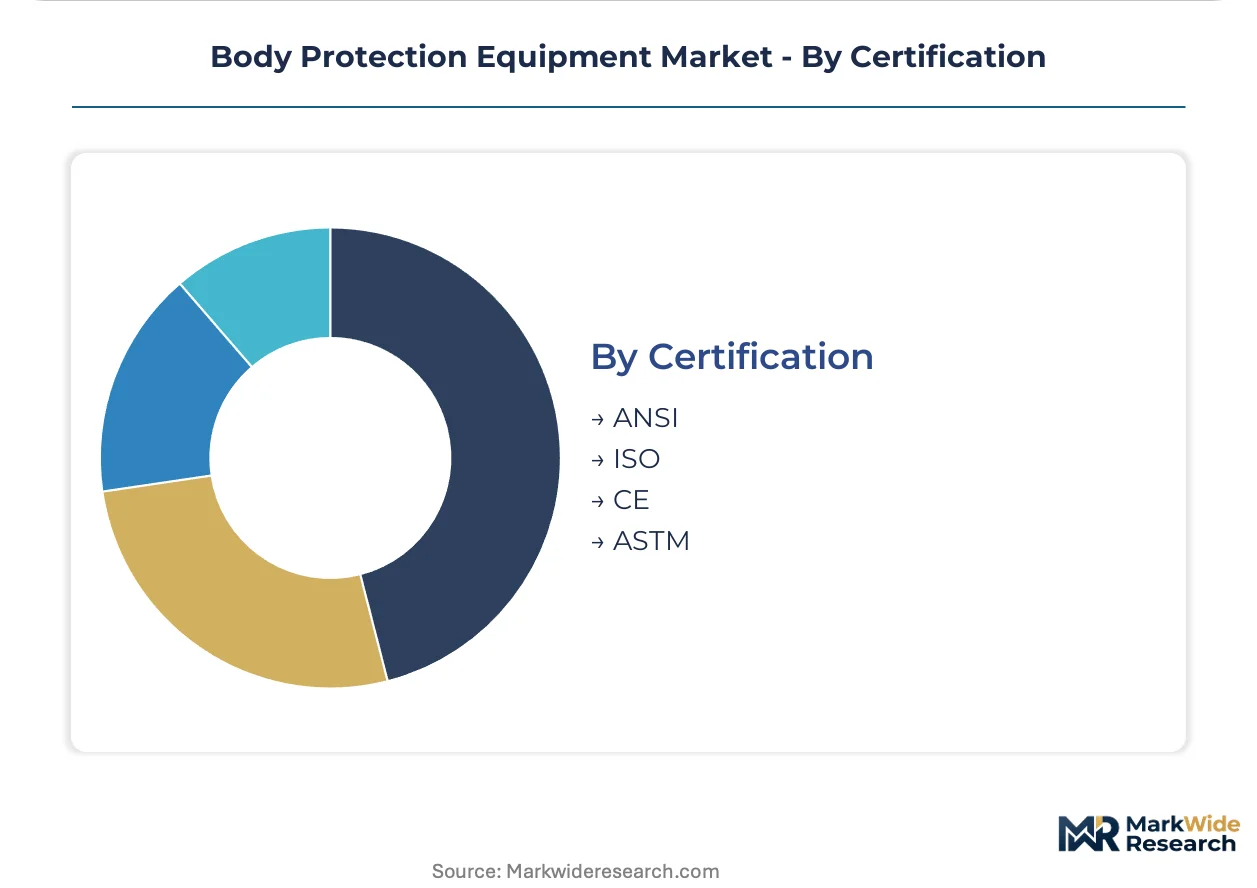
Certification:
Geography determines which testing protocols gate market access and command procurement preference.
- ANSI:American National Standards Institute protocols for head protection (Z89.1), eye protection (Z87.1), and hand protection (ISEA 105) determine contract eligibility for United States federal and state infrastructure projects. California and New York public works departments reject non-ANSI equipment.
- CE:EU PPE Regulation 2016/425 mandates notified body certification for market access across European member states. German automotive and French aerospace manufacturers require Module B+C2 conformity assessment routes, extending timelines for Asian suppliers.
- ISO:International Organization for Standardization frameworks for occupational health management (45001) and specific protective equipment shape multinational corporate procurement policies.
- ASTM:American Society for Testing and Materials flame-resistance and impact standards complement ANSI specifications in specialized applications.
ANSI certification governs the largest single-country procurement pool; CE marking requirements are climbing fastest as European supply chain due diligence tightens under CSRD frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational construction contractors and automotive OEMs concentrate procurement authority in specific industrial corridors where regulatory enforcement and infrastructure investment align.
United States
Federal infrastructure spending and state-level OSHA enforcement drive helmet and glove replacement cycles. California and New York public works departments mandate ANSI Z89.1 certification for all head protection. The Permian Basin oilfield cluster in Texas consumes flame-resistant vests under 29 CFR 1910.132 hazard assessment protocols.
China
Domestic manufacturing scale and intensifying industrial safety enforcement expand demand for cut-resistant gloves and composite helmets. GB standards alignment with ISO frameworks accelerates certification for construction sector procurement. Yangtze River Delta factory inspectorates in Jiangsu and Zhejiang provinces enforce first-time PPE compliance for electronics manufacturing.
Germany
Automotive assembly plants and machine tool producers specify EN 388 Level 5 cut-resistant gloves under EU PPE Regulation 2016/425. Module B+C2 conformity assessment routes extend certification timelines for Asian suppliers. Baden-Württemberg's automotive corridor around Stuttgart demands vendor-managed inventory with usage-based billing for high-turnover protection equipment.
India
State-level BIS standards adoption in Maharashtra and Gujarat creates first-time buyer markets for certified industrial safety equipment. Factory inspectorate expansion accelerates compliance requirements for construction and manufacturing. The Delhi-Mumbai Industrial Corridor infrastructure projects drive bulk procurement of ANSI-equivalent helmets and steel-toe protective footwear.
Japan
Electronics fabrication facilities and automotive OEMs enforce JIS standards for chemical-resistant gloves and impact-rated eyewear. METI industrial safety guidelines shape corporate procurement policies under ISO 45001 management systems. The Kansai manufacturing belt around Osaka concentrates precision handling applications requiring EN 388 Level 5 certified protection.
Body Protection Equipment Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement hierarchies. The vendor base separates into three tiers: multinational conglomerates with backward integration into material science, mid-scale specialists with regional certification expertise, and commodity assemblers serving price-sensitive construction markets. Dominant competitive moves include strategic partnerships with notified bodies for CE marking acceleration and portfolio diversification into sensor-embedded connected worker platforms.
Within the multinational conglomerate tier, Honeywell International Inc. and 3M occupy positions anchored by captive supply of advanced polymers and global distribution infrastructure. MSA Safety Incorporated exemplifies the rental-service archetype, sustaining recurring revenue through managed equipment programs rather than capital sales. DuPont represents the material-science anchor, supplying Kevlar fiber to downstream armor and glove fabricators while maintaining brand premiums in ballistic protection specifications.
| Leading Market Players |
|---|
| 3M |
| Honeywell International Inc. |
| DuPont |
| MSA Safety Incorporated |
| Ansell Ltd. |
| Lakeland Industries Inc. |
| Alpha Pro Tech |
| Radians Inc. |
| Protective Industrial Products |
| Others |
Supply Flow & Price Mechanics
Shanghai-Ningbo port freight corridors transmit petrochemical feedstock volatility directly into Kevlar pricing spreads, compressing margins for cut-resistant glove manufacturers while amplifying cost-plus contract indexation for polycarbonate helmet suppliers serving North American construction procurement.
Pricing Analysis
Cost-plus contracts with aramid fiber indexation dominate long-term supply agreements for ballistic vest and cut-resistant glove procurement. Price differentiation separates CE-marked premium tiers from ANSI-compliant standard offerings, with German automotive buyers paying certification premiums above warehousing volume purchasers. Pricing pressure stems from Kevlar and Twaron raw material volatility tied to benzene derivative markets. Tier-one construction contractors in the United States exhibit lowest price sensitivity, while Indian state infrastructure projects drive aggressive commodity-tier negotiation.
Supply Chain Analysis
Contract manufacturing concentrates in Jiangsu and Zhejiang provinces, where injection molding specialists serve polycarbonate helmet production for domestic and export markets. Raw material dependencies center on Saudi petrochemical complexes for bisphenol-A resins, DuPont's Kevlar fiber from Richmond and Maydown facilities, and Chinese nylon-6 production from Sinopec affiliates. Single-source vulnerability in para-aramid fiber supply creates procurement risk for ballistic protection lines. Distribution runs through industrial safety distributors with vendor-managed inventory programs replacing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market approaches a platform-economics inflection as sensor-embedded PPE interoperability standards enable connected worker ecosystems, shifting value capture from equipment sales to recurring safety-data subscriptions.
For Market Incumbents: Entrench position through backward integration into advanced polymer compounding and captive Kevlar weaving capacity, defending against Chinese composite material substitution. Prioritize notified body partnership investments to accelerate CE marking timelines and compress Asian competitor market access. Sensor-platform R&D represents the critical capability lever for recurring revenue transition.
For New Entrants and Emerging Players: Maharashtra and Gujarat state-level BIS enforcement creates first-time certified equipment demand among Indian manufacturing SMEs previously served by unorganized suppliers. Target warehousing rental-service programs with usage-based billing models, bypassing capital-sales barriers against established distributors. Go-to-market through industrial safety platform partnerships enables rapid scale without direct channel buildout.
For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate industrial divisions with dormant certification assets and underutilized molding capacity. Five-to-ten year viability hinges on connected PPE platform adoption curves and regulatory harmonization momentum. Monitor EU CSRD supply chain due diligence enforcement intensity as inflection signal for compliance-premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive resin formulation secures margin control against petrochemical volatility. |
| CE Marking Acceleration Partnership | Notified body relationships compress Asian competitor European market access timelines. |
| Sensor-Platform R&D Investment | IoT impact detection enables recurring subscription revenue from construction contractors. |
| Rental-Service Program Expansion | Usage-based billing models displace capital sales in high-turnover glove categories. |
| India State-Level Certification Push | BIS compliance investment captures first-time buyer markets in Maharashtra and Gujarat. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured interviews with safety procurement managers at tier-one construction contractors, industrial glove manufacturing plant directors, notified body certification auditors, and polymer compounding R&D leads. Secondary validation drew from OSHA enforcement action databases, EU PPE Regulation 2016/425 notified body registers, customs trade data for polycarbonate and aramid fiber shipments, and SEC 10-K filings from listed industrial safety equipment suppliers. Bottom-up segment sizing triangulated against top-down macroeconomic elasticity assumptions.
Calibration anchored volume projections to construction sector capital expenditure trajectories and manufacturing employment indices across the analysis window. Segmentation modeling incorporated product type, material composition, certification tier, and end-use industry vertical. CAGRs derived from historical replacement cycle analysis and regulatory enforcement intensity scoring. Industry-specific inputs included ANSI Z89.1 adoption velocity and EU CSRD supply chain due diligence implementation timelines.
Practitioners should monitor aramid fiber spot price movements, notified body capacity utilization rates, and state-level OSHA adoption patterns for early signals of forecast revision. Quarterly review of CE marking timeline extensions, Indian factory inspectorate expansion rates, and connected PPE pilot program scale is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Diving and Survival Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Radar Speed Gun Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Electronic Siren Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Guns Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
Hazardous Disposal Bag Market
Safety Equipment and Personal Protective Equipment (PPE)
Armoured Thermocouple Market
Safety Equipment and Personal Protective Equipment (PPE)
Cargo Security Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Power Air Purifying Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Bulletproof Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Prefilled Safety Device Market
Safety Equipment and Personal Protective Equipment (PPE)
US Industrial Barrier Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Machine Guarding Fence Market
Safety Equipment and Personal Protective Equipment (PPE)
Padlock Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Riot Control Equipment Market