
 Germany Video Surveillance Market | 2026-2036
Germany Video Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Video Surveillance Market Insights
High-resolution 4K specification-tier uptake is rotating the Germany video surveillance market toward premium hardware refresh cycles. Bosch Security Systems GmbH leverages its Stuttgart engineering base to sustain domestic manufacturing credibility. Dallmeier Electronic GmbH & Co. KG anchors the premium casino and airport niche through specialized fisheye analytics. Mobotix AG differentiates with decentralized edge-storage architecture that reduces bandwidth load for rural deployments.
Video surveillance encompasses networked camera systems, digital video recorders, and sensor arrays that capture, transmit, and store visual data for security monitoring and operational oversight. IP-based camera systems typically operate at H.265 compression with Power-over-Ethernet connectivity, enabling real-time facial recognition and behavioral analytics for commercial and critical infrastructure protection. Cameras dominate hardware value pools as German organizations prioritize lens quality and low-light performance over basic recorder upgrades. Cloud-Based technology represents the fastest-expanding architecture as mid-sized commercial end users shift from on-premise NVR maintenance to subscription-based remote management. Government end users maintain the largest installed base, though Industrial applications in chemical and automotive plants show the steepest adoption slope due to process-safety integration requirements.
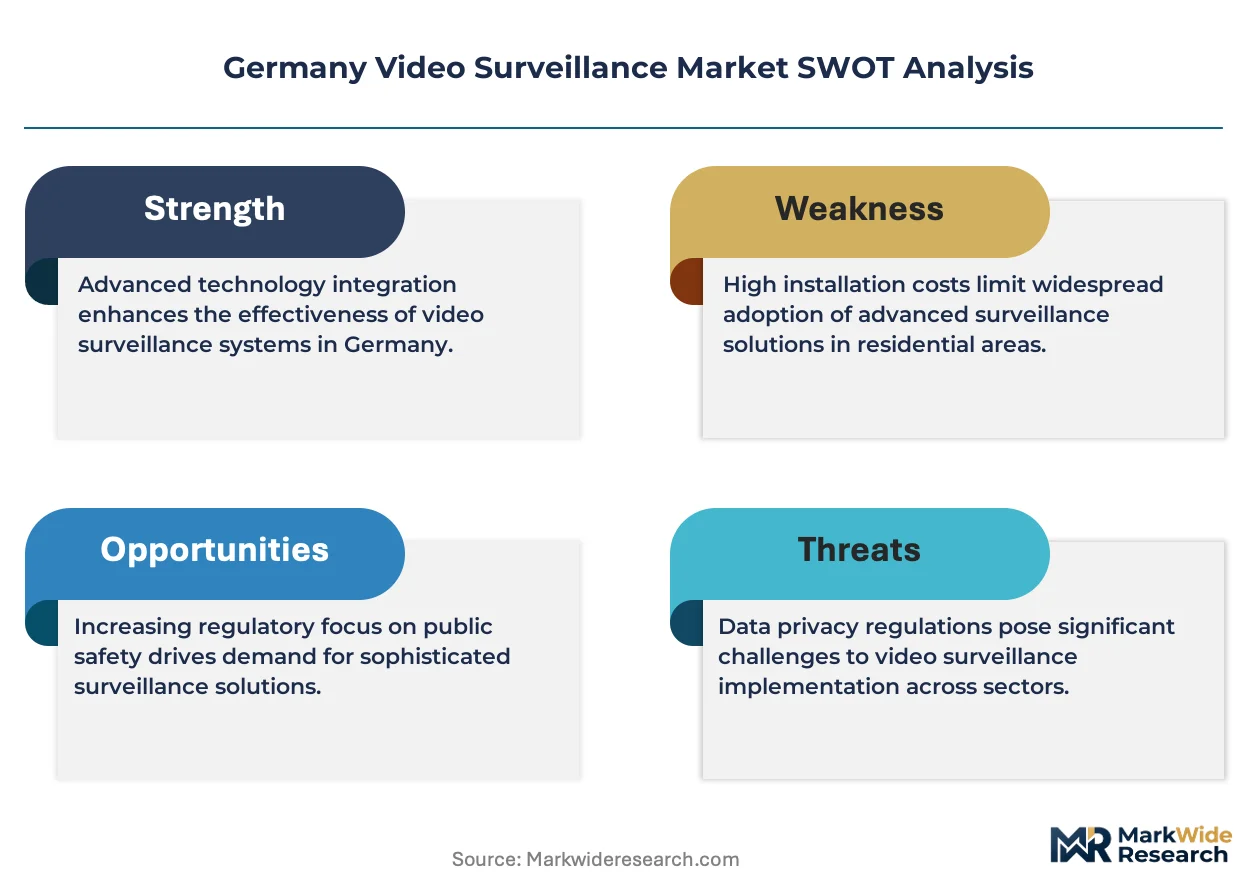
The EU AI Act restricts biometric identification in public spaces, compelling vendors to reengineer analytics modules for German law enforcement and transport buyers. GDPR mandates from the CNIL-equivalent German data protection authorities enforce strict retention limits and encryption standards that elevate procurement specifications. KBA guidelines for rail and road infrastructure further specify failover redundancy and cybersecurity certification for transit-sector deployments. Stakeholders must weigh compliance-driven cost premiums against the operational flexibility of AI-enhanced analytics platforms as regulatory thresholds tighten.
Market Dynamics
GDPR enforcement from German data protection authorities and the EU AI Act are compressing procurement cycles, forcing municipal buyers to retire legacy analog systems ahead of depreciation schedules. Hardware vendors must now pre-certify edge-analytics modules for biometric compliance before transit authorities release tenders.
Growth Catalysts
- Critical infrastructure mandates:KBA guidelines for rail and road networks require redundant failover systems, compelling Deutsche Bahn and regional transport operators to upgrade station surveillance. Procurement volumes concentrate on Bavarian and North Rhine-Westphalian transit hubs.
- EU AI Act compliance:The regulation's biometric identification restrictions create replacement demand as law enforcement agencies seek reengineered analytics that preserve operational capability within legal boundaries.
- Industrial process-safety integration:Chemical and automotive plants in Baden-Württemberg and Lower Saxony deploy video analytics for perimeter monitoring synchronized with SCADA systems, linking physical security to operational technology infrastructure.
Market Restraints
- Silicon supply concentration:Image sensor fabrication concentrates in Taiwan and South Korea, exposing German integrators to lead-time volatility for 4K and thermal camera modules.
- GDPR retention limits:German data protection authorities enforce strict 72-hour deletion windows for non-investigatory footage, compressing storage hardware utilization rates and elevating total cost of ownership.
- Legacy analog sunk costs:Municipalities face stranded asset write-downs when replacing coaxial-based systems, slowing budget approval for full IP migrations despite regulatory pressure.
Strategic Opportunities
- Eastern federal state penetration:Saxony and Brandenburg exhibit camera density below western benchmarks, creating whitespace for integrators serving manufacturing corridors around Leipzig and Dresden.
- Cloud-architecture displacement:Mid-sized commercial end users in Hamburg and Munich trade on-premise NVR maintenance for subscription-based remote management, opening recurring revenue streams.
- Edge-storage convergence:Decentralized camera architectures reduce bandwidth requirements for rural deployments across Mecklenburg-Vorpommern, addressing infrastructure gaps that centralized systems cannot economically serve.
Industry Challenges
- Cybersecurity certification timelines:BSI certification for rail-sector deployments extends qualification periods, delaying revenue recognition for vendors targeting Deutsche Bahn tenders.
- Legacy system integration friction:Municipal operators in older cities like Cologne and Nuremberg confront protocol incompatibilities when layering AI analytics atop decades-old camera networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Video Surveillance Market |
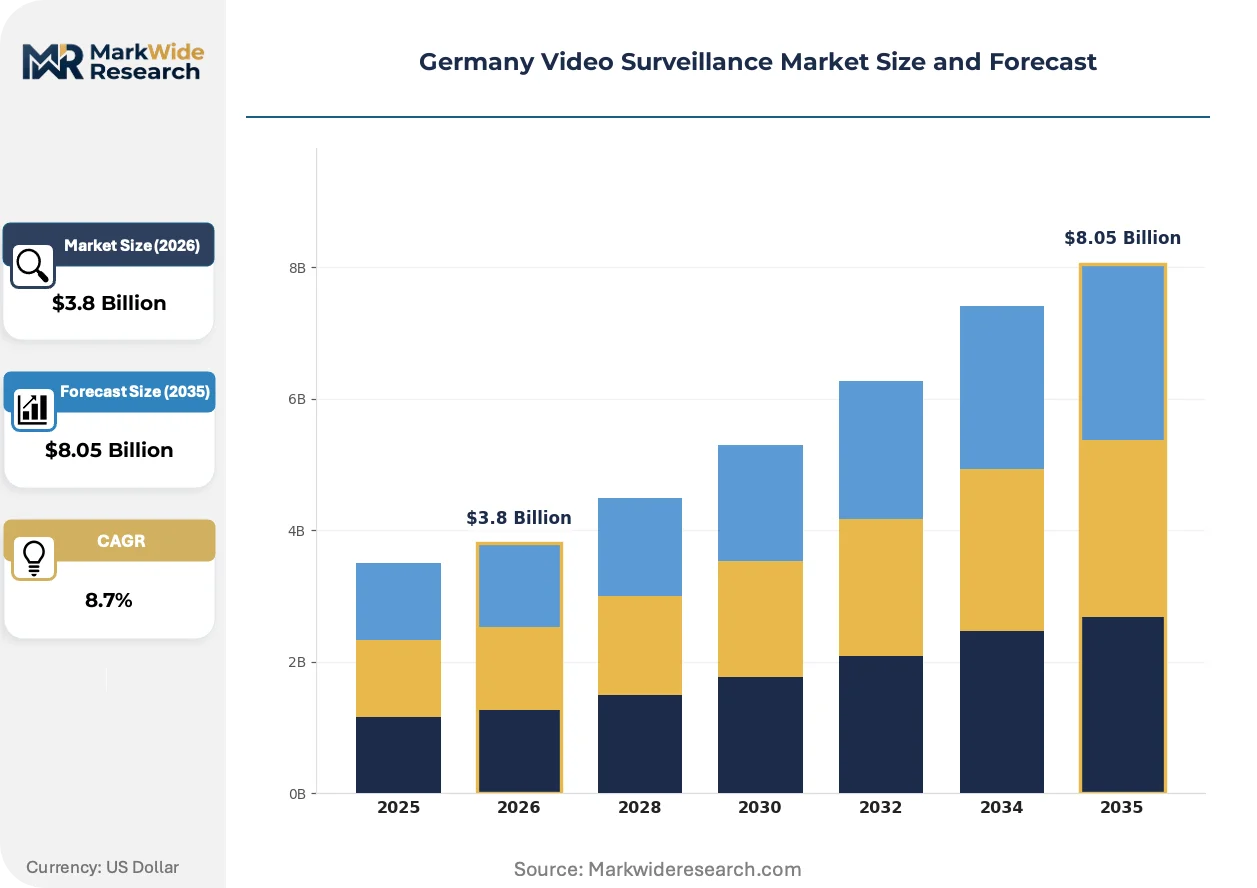
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cameras, Recorders, Sensors, Storage Devices Technology: Analog, IP, HD-SDI, Cloud-Based Application: Transportation, Retail, Banking, Education End User: Government, Commercial, Residential, Industrial |
| Companies Covered | Dallmeier Electronic GmbH & Co. KG, Hangzhou Hikvision Digital Technology Co. Ltd, Bosch Security Systems GmbH, Videotec SpA, Teledyne FLIR LLC, Axis Communications AB, ABUS Security Tech Germany, Grundig Security, Mobotix AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Video Surveillance Market Trends and Innovations
Hardware specification tiers are diverging as German buyers split between premium 4K deployments in critical infrastructure and cost-optimized alternatives for peripheral coverage. Analytics capabilities now determine vendor selection more than lens mechanics.
Edge-computing camera architectures are bifurcating the German market between centralized and decentralized storage paradigms. Industrial buyers in automotive plants adopt on-camera processing to minimize latency for safety-critical alerts. Municipal transit authorities favor this topology for station platforms where fiber backhaul remains uneconomical. The technology is compressing margins for traditional NVR manufacturers while elevating firmware and cybersecurity as competitive differentiators.
The EU AI Act's biometric restrictions are reshaping product roadmaps for vendors serving German law enforcement. Analytics modules must now demonstrate technical incapability of individual identification to qualify for public-space deployment. Transport operators in Berlin and Frankfurt respond by prioritizing crowd-density and behavioral anomaly detection over facial recognition, redirecting R&D investment toward pattern-based algorithms.
Commercial buyers are unbundling hardware procurement from service contracts, separating camera purchases from installation and maintenance agreements. Mid-sized retailers in Stuttgart and Düsseldorf now source equipment through distribution channels while negotiating managed services directly with specialized integrators. This pattern is most visible in the Rhine-Ruhr metropolitan region, where fragmented property ownership complicates single-vendor relationships.
Germany Video Surveillance Market Segmentation
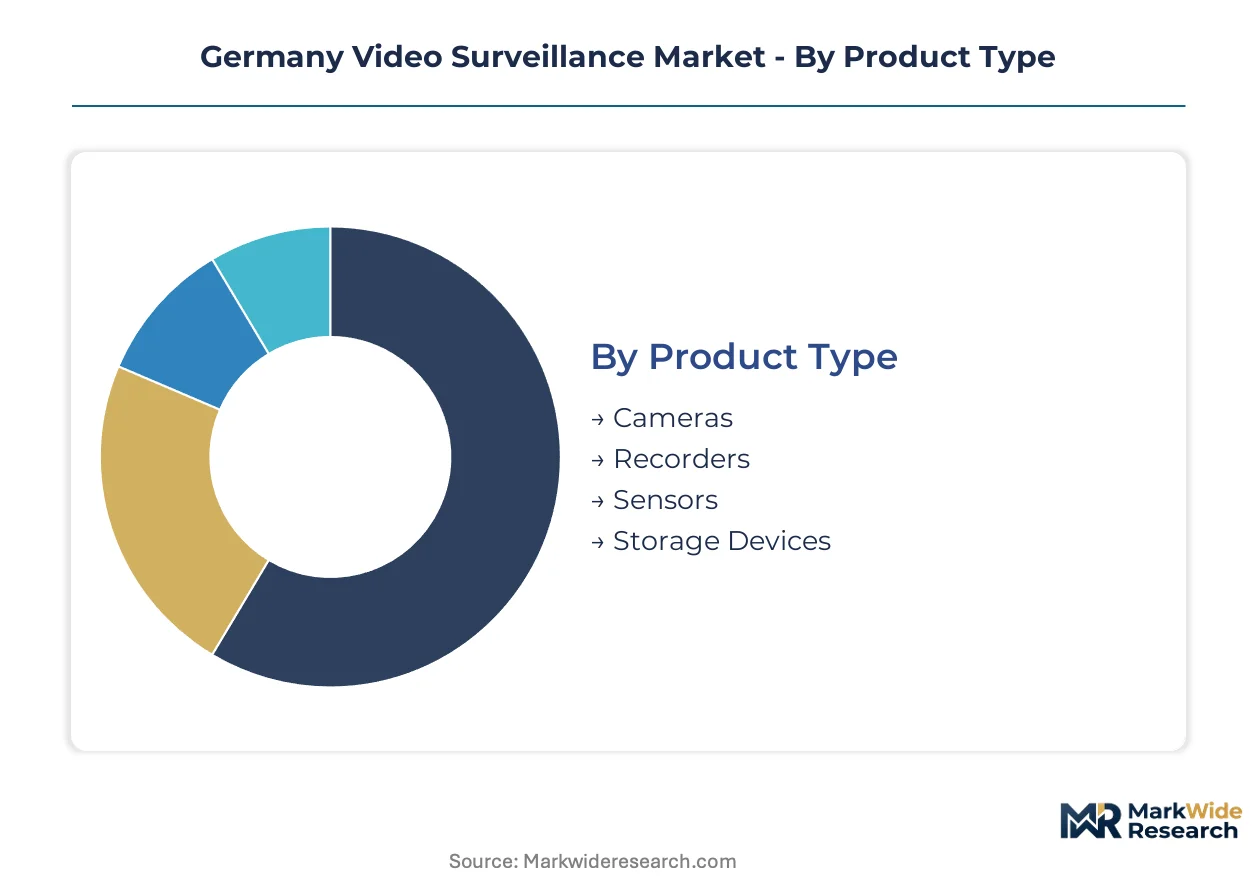
Segmentation in the Germany video surveillance market reveals how regulatory pressure and infrastructure age create divergent upgrade pathways across hardware categories, technology architectures, and end-use environments. Understanding these splits enables vendors to align certification investments with segments where compliance timelines are most compressed.
Product Type:
Cameras face intensifying substitution pressure from integrated edge-computing units that bundle storage and analytics, threatening standalone recorder margins.
- Cameras:Networked devices operating at H.265 compression with Power-over-Ethernet connectivity dominate hardware value pools. German organizations prioritize lens quality and low-light performance for critical infrastructure in Bavaria and North Rhine-Westphalia.
- Recorders:Digital video recorders and network video recorders capture, compress, and archive footage from multiple camera feeds. Demand concentrates in municipal transit authorities replacing analog systems ahead of GDPR-mandated deprecation schedules.
- Sensors:Thermal and motion-detection arrays extend coverage beyond visible-spectrum limitations. Chemical plants in Baden-Württemberg deploy these for perimeter monitoring synchronized with SCADA safety systems.
- Storage Devices:On-premise and edge-located storage hardware retains footage under strict encryption protocols. German data protection authorities enforce 72-hour deletion windows for non-investigatory footage, compressing utilization rates.
Cameras anchor the volume base while Cloud-Based integrated units gain share at the steepest rate.
Technology:
Technology stratification follows customer scale, with premium architectures commanding three-to-four-year replacement cycles versus decade-long analog depreciation.
- Analog:Coaxial-based systems with limited resolution and no native analytics capability. Municipalities face stranded asset write-downs when replacing these systems, slowing budget approval for full IP migrations.
- IP:Internet Protocol cameras transmit compressed video over Ethernet networks with embedded intelligence. Deutsche Bahn and regional transport operators prioritize IP upgrades for KBA-mandated failover redundancy in station deployments.
- HD-SDI:High-Definition Serial Digital Interface delivers uncompressed video over coaxial cabling for legacy infrastructure extensions. Broadcast-critical environments in Frankfurt and Berlin maintain limited deployments for zero-latency requirements.
- Cloud-Based:Subscription-managed architectures shift processing and storage to remote data centers. Mid-sized commercial end users in Hamburg and Munich trade on-premise NVR maintenance for recurring remote management contracts.
Analog systems retain residual installed base in eastern federal states while Cloud-Based architectures expand most quickly in metropolitan commercial segments.
Application:
Application segmentation tracks regulatory exposure, with transport and banking facing the strictest BSI and GDPR certification requirements.
- Transportation:Rail, road, and aviation surveillance governed by KBA guidelines for redundant failover and cybersecurity certification. Procurement volumes concentrate on Bavarian and North Rhine-Westphalian transit hubs.
- Retail:Loss-prevention and customer-flow analytics for storefront and warehouse environments. Mid-sized retailers in Stuttgart and Düsseldorf unbundle hardware procurement from managed service contracts.
- Banking:ATM monitoring and branch security with stringent encryption and retention protocols. Frankfurt's financial district drives specification-tier demand for premium 4K deployments.
- Education:Campus safety and access control for universities and vocational institutions. GDPR compliance complexity limits deployment ambition in public school systems.
Transportation commands the premium specification tier while Retail delivers the broadest addressable customer base.
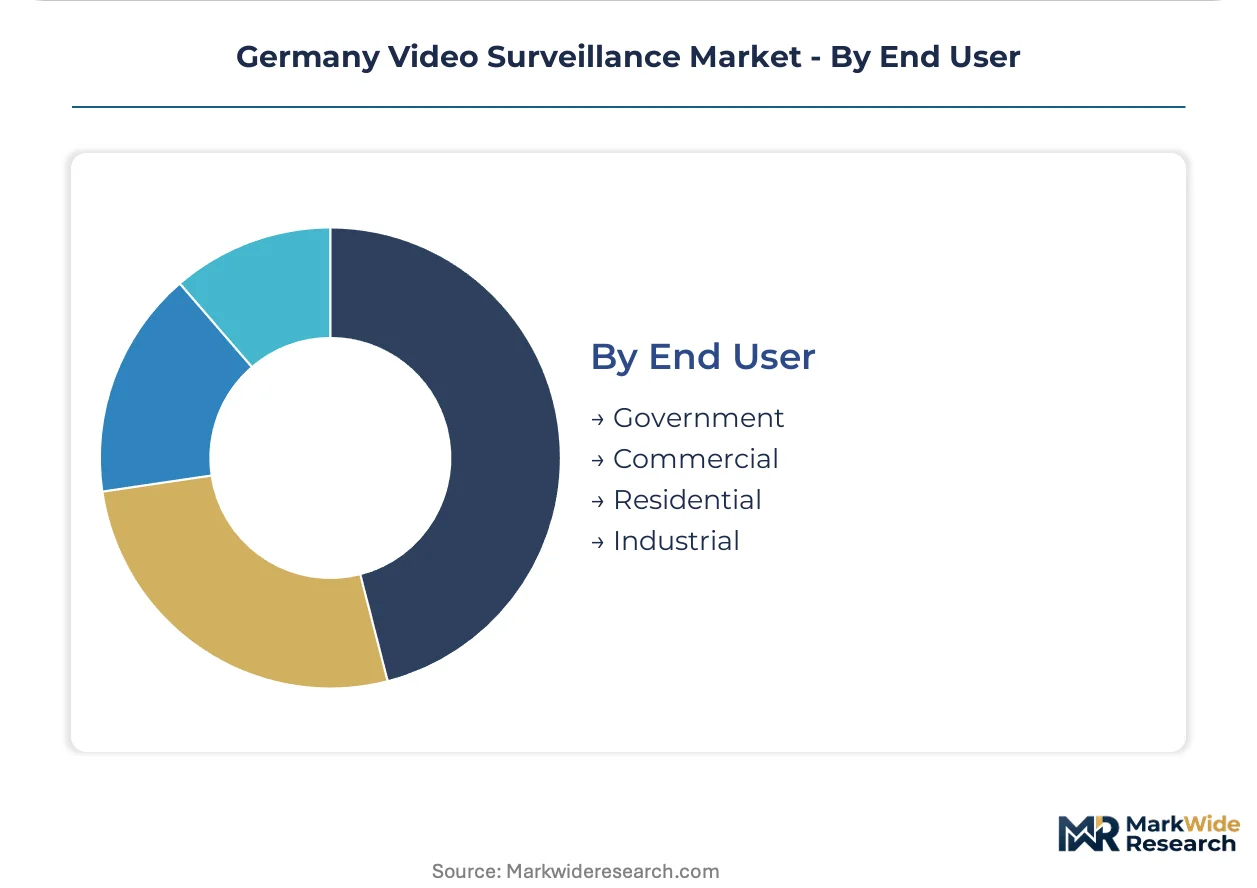
End User:
End user segmentation reflects divergent procurement authority, with centralized government tenders contrasting fragmented commercial decision-making.
- Government:Federal, state, and municipal security agencies with formal tender processes and extended qualification periods. German data protection authorities and the EU AI Act compress procurement cycles for biometric-compliant systems.
- Commercial:Retail chains, office complexes, and hospitality operators with distributed property ownership. The Rhine-Ruhr metropolitan region exhibits fragmented relationships complicating single-vendor consolidation.
- Residential:Single-family and multi-unit dwelling installations for personal security. Rural deployments across Mecklenburg-Vorpommern favor decentralized edge-storage architectures to overcome bandwidth constraints.
- Industrial:Chemical, automotive, and manufacturing plants integrating physical security with operational technology. Process-safety requirements in Baden-Württemberg and Lower Saxony drive the steepest adoption slope for analytics-linked systems.
Government maintains the largest installed base while Industrial applications climb the fastest on process-safety integration mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Image sensor fabrication concentrates in Taiwan and South Korea, exposing German integrators to lead-time volatility for 4K and thermal camera modules. Domestic deployment patterns split between western industrial corridors and eastern expansion zones. Regulatory pressure from the EU AI Act and GDPR enforcement compresses procurement cycles unevenly across federal states.
Bavaria
Munich anchors premium specification demand for casino and airport surveillance deployments. KBA guidelines for rail infrastructure mandate redundant failover systems, compelling Deutsche Bahn to upgrade station networks. The Stuttgart engineering corridor sustains domestic manufacturing credibility for security hardware vendors.
North Rhine-Westphalia
Cologne and Düsseldorf drive transit-hub camera density with fragmented commercial property ownership complicating single-vendor relationships. GDPR retention limits from German data protection authorities enforce strict encryption standards for banking sector procurement. The Rhine-Ruhr metropolitan region exhibits the broadest addressable customer base for retail loss-prevention analytics.
Baden-Württemberg
Automotive plants in Stuttgart deploy video analytics for perimeter monitoring synchronized with SCADA safety systems. Process-safety integration requirements elevate demand for edge-computing camera architectures. Chemical facilities across the state link physical security to operational technology infrastructure.
Lower Saxony
Industrial applications in chemical and manufacturing plants show steep adoption slopes for analytics-linked systems. Municipal operators confront protocol incompatibilities when layering AI analytics atop decades-old camera networks in older cities. Rural deployments favor decentralized edge-storage architectures to overcome bandwidth constraints.
Saxony
Camera density remains below western benchmarks, creating whitespace for integrators serving manufacturing corridors around Leipzig and Dresden. Eastern federal state penetration opportunities concentrate in mid-sized commercial end users shifting from on-premise NVR maintenance to subscription-based remote management. Cloud-architecture displacement opens recurring revenue streams for specialized service providers.
Germany Video Surveillance Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the German video surveillance market. The vendor base splits between premium-tier specialists commanding certification-driven procurement and scale-oriented manufacturers serving price-sensitive commercial segments. Three archetypes dominate: domestic engineering-led system integrators, Asian volume manufacturers, and European niche specialists. Competitive moves concentrate on portfolio diversification toward edge-computing architectures and strategic partnerships for cloud-based service delivery.
Among Germany-based security technology providers, Bosch Security Systems GmbH, Dallmeier Electronic GmbH & Co. KG, and Mobotix AG occupy distinct positioning within the premium tier. Bosch leverages its Stuttgart engineering base to sustain domestic manufacturing credibility for critical infrastructure tenders. Dallmeier anchors the specialized casino and airport niche through fisheye analytics expertise. Mobotix exemplifies the decentralized edge-storage architecture that reduces bandwidth load for rural deployments across Mecklenburg-Vorpommern. These three German GmbH and AG structures represent the domestic engineering archetype against Asian volume competitors and European specialists.
| Leading Market Players |
|---|
| Dallmeier Electronic GmbH & Co. KG |
| Hangzhou Hikvision Digital Technology Co. Ltd |
| Bosch Security Systems GmbH |
| Videotec SpA |
| Teledyne FLIR LLC |
| Axis Communications AB |
| ABUS Security Tech Germany |
| Grundig Security |
| Mobotix AG |
| Others |
Pricing and Supply Chain Analysis
Sixteen-week lead times for 4K image sensors from Taiwan and South Korea concentrate procurement power with distributors holding buffer inventory, compressing margins for German integrators while elevating spot-market premiums for expedited delivery.
Pricing Analysis
GDPR and the EU AI Act dictate the pricing tier structure across the German video surveillance market. Three-tier pricing separates BSI-certified premium systems for rail infrastructure from standard IP configurations for commercial retail and economy-grade analog replacements for municipal budget constraints. Price differentiation rests on cybersecurity certification grade and domestic engineering content, with Stuttgart-manufactured units commanding brand premiums over Asian imports. Cost compression in the standard tier is intensifying because mid-sized commercial buyers unbundle hardware from service contracts and source through distribution channels. Municipal government tenders exhibit the highest price sensitivity due to stranded analog asset write-downs, while Deutsche Bahn and chemical plant operators in Baden-Württemberg prioritize failover redundancy over unit cost.
Supply Chain Analysis
Inventory buffers of 60-90 days for thermal and 4K image sensors mask underlying concentration risk in Taiwan, South Korea, and Japan. German integrators draw from Taiwanese foundries for CMOS sensors, South Korean memory for edge-storage modules, and Japanese optics for precision lens assemblies. Raw material dependencies span rare-earth elements for thermal imaging substrates, high-purity silicon for sensor wafers, and copper for Power-over-Ethernet cabling. Single-source vulnerability in advanced node fabrication exposes procurement timelines to geopolitical disruption. Distribution runs through specialized security integrators serving vertical-specific certification requirements, with direct OEM relationships reserved for volume transit and critical infrastructure tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The German video surveillance market sits at an inflection where edge-computing architectures and EU AI Act biometric restrictions are compressing replacement cycles and reordering competitive advantage toward firmware and cybersecurity capabilities.
For Market Incumbents: Shield domestic manufacturing credibility by deepening Stuttgart engineering presence for BSI-certified rail tenders while accelerating edge-analytics pre-certification to capture GDPR-mandated municipal replacement demand. Prioritize backward integration into camera module assembly to reduce Taiwan sensor lead-time exposure. Channel control through specialized integrator partnerships defends margin position against unbundled procurement trends in the Rhine-Ruhr commercial segment. For New Entrants and Emerging Players: Differentiate on decentralized edge-storage architectures for bandwidth-constrained rural deployments across Mecklenburg-Vorpommern and Lower Saxony. Target cloud-architecture displacement in Hamburg and Munich mid-sized commercial accounts where subscription-based remote management replaces on-premise NVR maintenance. Pursue eastern federal state penetration in Saxony and Brandenburg manufacturing corridors where camera density remains below western benchmarks and incumbent relationships are less entrenched. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-driven recurring revenue play because GDPR retention limits and AI Act biometric restrictions institutionalize replacement cycles and elevate service contract attach rates. Acquisition targets should display edge-computing firmware expertise and existing BSI or KBA certification pathways rather than pure hardware scale. Monitor Deutsche Bahn tender release velocity as the signal indicating whether procurement compression accelerates or stabilizes.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Firmware Development | On-camera processing reduces latency for SCADA-integrated safety alerts in Stuttgart automotive plants. |
| BSI Certification Pathway Investment | Rail-sector cybersecurity approval unlocks Deutsche Bahn station upgrade tenders in Bavaria. |
| Cloud-Architecture Service Launch | Subscription remote management captures Munich and Hamburg mid-sized commercial NVR displacement. |
| Eastern Federal State Distribution Buildout | Leipzig and Dresden manufacturing corridors offer whitespace below western camera density benchmarks. |
| Biometric-Compliant Analytics Reengineering | Technical incapability demonstration for individual identification preserves law enforcement market access under EU AI Act. |
Research Methodology
A standing panel of security technology procurement officers at Deutsche Bahn and regional transport operators, municipal IT directors, plant engineers at Baden-Württemberg automotive facilities, and specialized integrators serving the Rhine-Ruhr metropolitan region provided ongoing calibration across primary interview cycles. Secondary validation drew from BSI certification databases, KBA infrastructure guidelines, EU AI Act regulatory filings, German federal procurement portals, and customs records for image sensor imports. Bottom-up unit economics for camera, recorder, and storage device categories were triangulated against top-down market sizing from government security spending disclosures and industrial capital expenditure tracking.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning product type, technology architecture, application vertical, and end-user procurement authority, with additional granularity for certification tier and domestic versus imported manufacturing origin. CAGRs were derived from replacement cycle compression analysis under GDPR and AI Act timelines, layered with industrial process-safety integration adoption curves for chemical and automotive verticals.
Forecasts assume regulatory continuity in EU AI Act implementation and German data protection authority enforcement; material policy shifts or BSI certification timeline extensions would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
China Surveillance Camera Market
Video Surveillance Systems
Canada Surveillance IP Camera Market
Video Surveillance Systems
Concealed Weapon Detection Systems Market
Video Surveillance Systems
Germany Surveillance Analog Camera Market
Video Surveillance Systems
India Surveillance Camera Market
Video Surveillance Systems
Mexico Video Surveillance Market
Video Surveillance Systems
United Arab Emirates Surveillance Camera Market
Video Surveillance Systems
China Surveillance Storage Market
Video Surveillance Systems
France Video Surveillance Market
Video Surveillance Systems
CCTV Camera Market
Video Surveillance Systems
Security Camera Software Market
Video Surveillance Systems
Coastal Surveillance Systems Market
Video Surveillance Systems
Asia-Pacific Surveillance Camera Market
Video Surveillance Systems
India Video Surveillance Market
Video Surveillance Systems
Asia Pacific Surveillance IP Camera Market
Video Surveillance Systems
North America Smart Home Security Cameras Market