
 North America Pedestrian Detection Systems Market | 2026-2036
North America Pedestrian Detection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pedestrian Detection Systems Market Analytics
Aftermarket calibration and software update revenue is tilting toward tier-one suppliers with embedded AI stacks. Mobileye sustains technology leadership through its EyeQ chipset architecture and mapping integration. Continental AG leverages its radar-camera fusion platforms to anchor supply relationships with premium OEMs. Robert Bosch GmbH competes across the full sensor stack, from ultrasonic modules to lidar units.
Pedestrian detection systems integrate multi-sensor arrays—typically forward-facing cameras operating at 30-120 frames per second, millimeter-wave radar at 76-81 GHz, and increasingly solid-state lidar—to classify human movement patterns and trigger autonomous braking or steering interventions. Camera systems dominate current OEM fitments due to mature supply chains and declining CMOS sensor costs, while sensor fusion architectures represent the fastest-growing technology segment as automakers pursue redundancy for SAE Level 2+ autonomy. Machine learning deployment concentrates in neural network training for edge-case recognition—occluded pedestrians, nighttime detection, non-standard gait patterns—where margin pools accrue to firms with proprietary datasets.
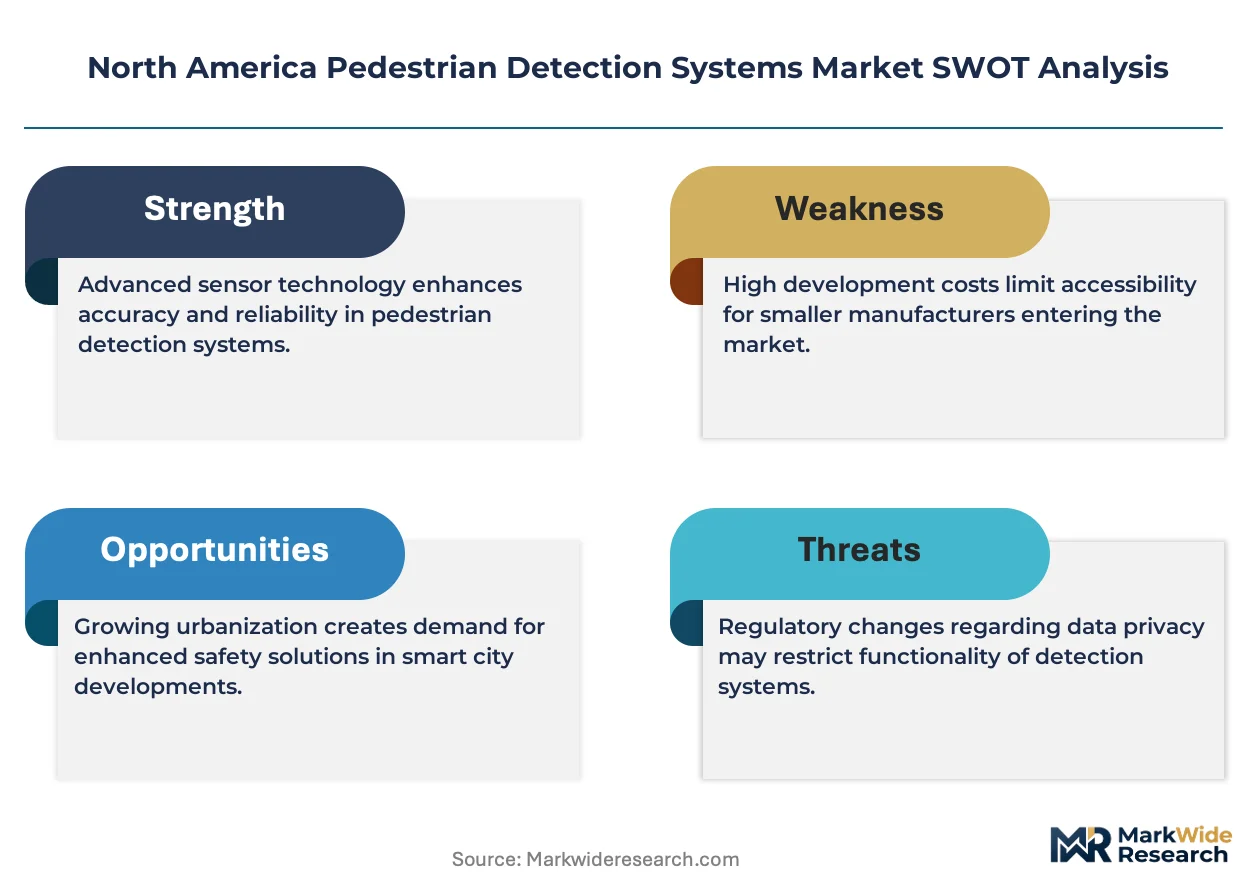
NHTSA's automatic emergency braking mandate for light vehicles and FMVSS performance requirements shape product development timelines and testing protocols across the United States. Transport Canada and Mexico's economic ministry coordinate cross-border type-approval standards that influence supplier certification costs. IIHS testing criteria for pedestrian crash prevention ratings directly steer OEM procurement priorities. Stakeholders must monitor regulatory divergence between federal mandates and state-level autonomous vehicle deployment rules, particularly as California and Arizona advance separate testing frameworks.
Market Dynamics
NHTSA's automatic emergency braking mandate is compressing development timelines across the North American supplier base, forcing tier-one manufacturers to accelerate sensor fusion validation while maintaining cost discipline on light-duty vehicle platforms.
Growth Catalysts
- FMVSS Performance Requirements:Federal Motor Vehicle Safety Standards mandate pedestrian crash avoidance capabilities, compelling OEMs to integrate multi-sensor arrays across model year lineups.
- Autonomous Vehicle Testing Corridors:California and Arizona deployment zones generate real-world training data that improves edge-case detection algorithms for nighttime and occluded pedestrian scenarios.
- Insurance Institute Protocols:IIHS pedestrian crash prevention ratings directly steer fleet procurement decisions among commercial vehicle operators seeking premium discounts.
Market Restraints
- CMOS Sensor Cost Volatility:Forward-facing camera modules depend on semiconductor supply chains concentrated in East Asian foundries, exposing tier-one suppliers to input price swings.
- Millimeter-Wave Spectrum Allocation:FCC frequency coordination for 76-81 GHz automotive radar creates certification bottlenecks that extend product launch timelines.
- LiDAR Unit Substitution Pressure:Solid-state lidar alternatives threaten to displace established radar-camera fusion architectures in premium vehicle segments.
Strategic Opportunities
- Mexico Manufacturing Integration:Cross-border type-approval alignment between Transport Canada and Mexico's economic ministry reduces supplier certification burden for integrated North American production.
- Aftermarket Calibration Services:Collision repair networks and independent service centers present untapped channels for software update revenue outside OEM captive distribution.
- Sensor Fusion Convergence:Neural network training at the edge is hybridizing camera, radar, and thermal inputs to enable redundant perception stacks for SAE Level 2+ autonomy.
Industry Challenges
- Edge-Case Dataset Scarcity:Machine learning teams face persistent gaps in training data for non-standard gait patterns and adverse weather pedestrian detection.
- Multi-Sensor Integration Complexity:Synchronizing 30-120 frames per second camera feeds with radar returns demands specialized embedded systems engineering talent in short supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pedestrian Detection Systems Market |
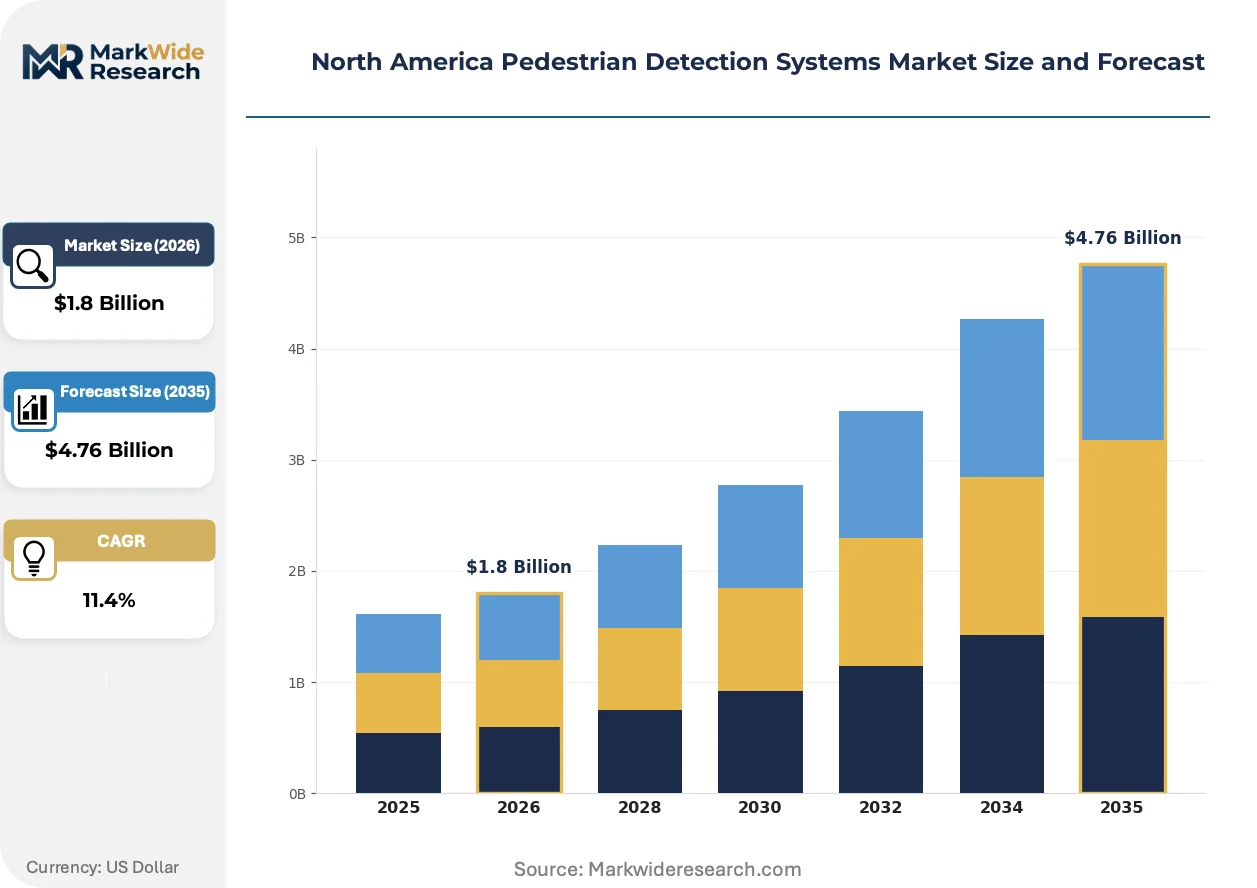
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radar Sensors, Lidar Sensors, Camera Systems, Ultrasonic Sensors Technology: Artificial Intelligence, Image Processing, Sensor Fusion, Machine Learning Application: Automotive Safety, Traffic Management, Smart Cities, Fleet Management End User: OEMs, Fleet Operators, Municipalities, Transportation Agencies |
| Companies Covered | Robert Bosch GmbH, Continental AG, Mobileye, DENSO Corporation, Visteon Corporation, Toyota Motor Corporation, Autoliv, Aptiv, Magna, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pedestrian Detection Systems Market Evolving Landscape
Perception architecture is fragmenting across competing sensor modalities, with software-defined validation cycles displacing hardware-centric development roadmaps. Tier-one suppliers now compete on neural network training throughput rather than component specifications alone.
Sensor fusion platforms are hybridizing discrete camera, radar, and solid-state lidar inputs into unified perception stacks. Detroit Three automakers are adopting these architectures fastest on full-size truck and SUV platforms where packaging constraints are least severe. The technology is hybridizing tier-one supplier margins away from discrete component sales toward integrated software licensing.
NHTSA's automatic emergency braking mandate for light vehicles tightens performance thresholds annually, forcing recertification of existing sensor calibrations. IIHS testing protocols now include nighttime pedestrian scenarios that earlier validation suites excluded. Commercial fleet operators in the United States are responding by demanding predictive maintenance integration with detection system health monitoring.
Service unbundling is fragmenting traditional OEM-tied maintenance relationships. Independent collision repair chains in California and Texas are acquiring calibration equipment to capture post-collision sensor realignment revenue. This channel shift is most visible among commercial vehicle fleets operating across multiple state jurisdictions where dealer network density varies.
North America Pedestrian Detection Systems Market Segmentation
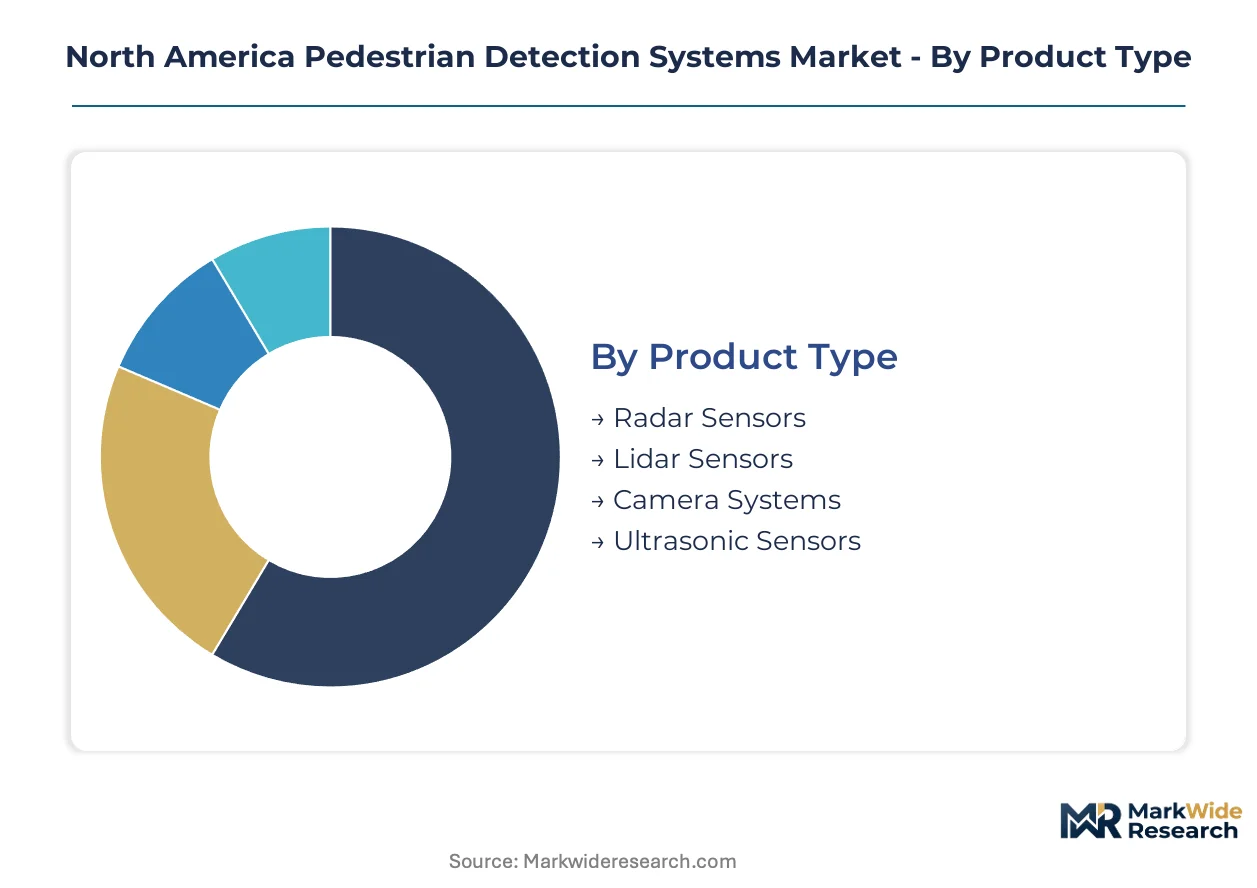
Pedestrian detection systems fragment across sensor modalities, processing architectures, deployment contexts, and procurement channels. Each segmentation axis reveals distinct margin structures, certification requirements, and competitive dynamics that shape supplier strategy across the North American automotive and smart infrastructure sectors.
Product Type:
The use-case spectrum spans highway-speed autonomous braking to low-speed parking assistance, with each sensor modality occupying distinct performance and cost tiers.
- Radar Sensors:Millimeter-wave units operating at 76-81 GHz provide velocity measurement and all-weather reliability. Demand concentrates in full-size truck platforms from Detroit Three automakers where NHTSA AEB mandates drive fitment rates.
- Camera Systems:Forward-facing CMOS arrays capture 30-120 frames per second for edge-case classification. California and Arizona autonomous vehicle testing corridors generate concentrated procurement for high-resolution units with thermal augmentation.
- Lidar Sensors:Solid-state and mechanical scanning units enable precise depth mapping for urban autonomous operation.
- Ultrasonic Sensors:Short-range acoustic modules dominate parking assistance and low-speed maneuvering applications.
Established volume favors camera systems; emerging adoption favors lidar sensors.
Technology:
Processing architectures differentiate by computational location, training data requirements, and regulatory traceability demands.
- Artificial Intelligence:Deep neural networks trained on proprietary datasets enable real-time pedestrian classification with sub-100-millisecond latency. Fleet operators in Texas and California demand AI-enabled systems for insurance premium reductions tied to IIHS ratings.
- Sensor Fusion:Hybrid processing of camera, radar, and lidar inputs creates redundant perception stacks for SAE Level 2+ autonomy. Premium OEMs in Michigan and Ontario are expanding sensor fusion procurement fastest on luxury SUV platforms.
- Image Processing:Traditional computer vision algorithms without machine learning inference reduce hardware costs for price-sensitive light-duty segments.
- Machine Learning:Edge-optimized models enable incremental performance improvements through over-the-air updates.
Hardware margins favor sensor fusion; software recurring revenue favors artificial intelligence.
Application:
Deployment contexts range from captive automotive integration to open-access municipal infrastructure with diverging procurement cycles and technical specifications.
- Automotive Safety:Integrated AEB and collision avoidance systems represent the dominant revenue pool. United States light-duty and commercial vehicle production lines drive procurement concentration among tier-one suppliers with embedded AI stacks.
- Smart Cities:Intersection monitoring and pedestrian analytics platforms serve municipal traffic optimization. Canadian municipalities in Ontario and British Columbia are piloting smart city deployments with federal infrastructure funding.
- Traffic Management:Highway and arterial monitoring systems feed centralized control centers for incident response.
- Fleet Management:Commercial vehicle operators deploy aftermarket retrofit kits for regulatory compliance across multi-state operations.
Automotive integration delivers current volume concentration; smart city infrastructure offers the steepest expansion trajectory.
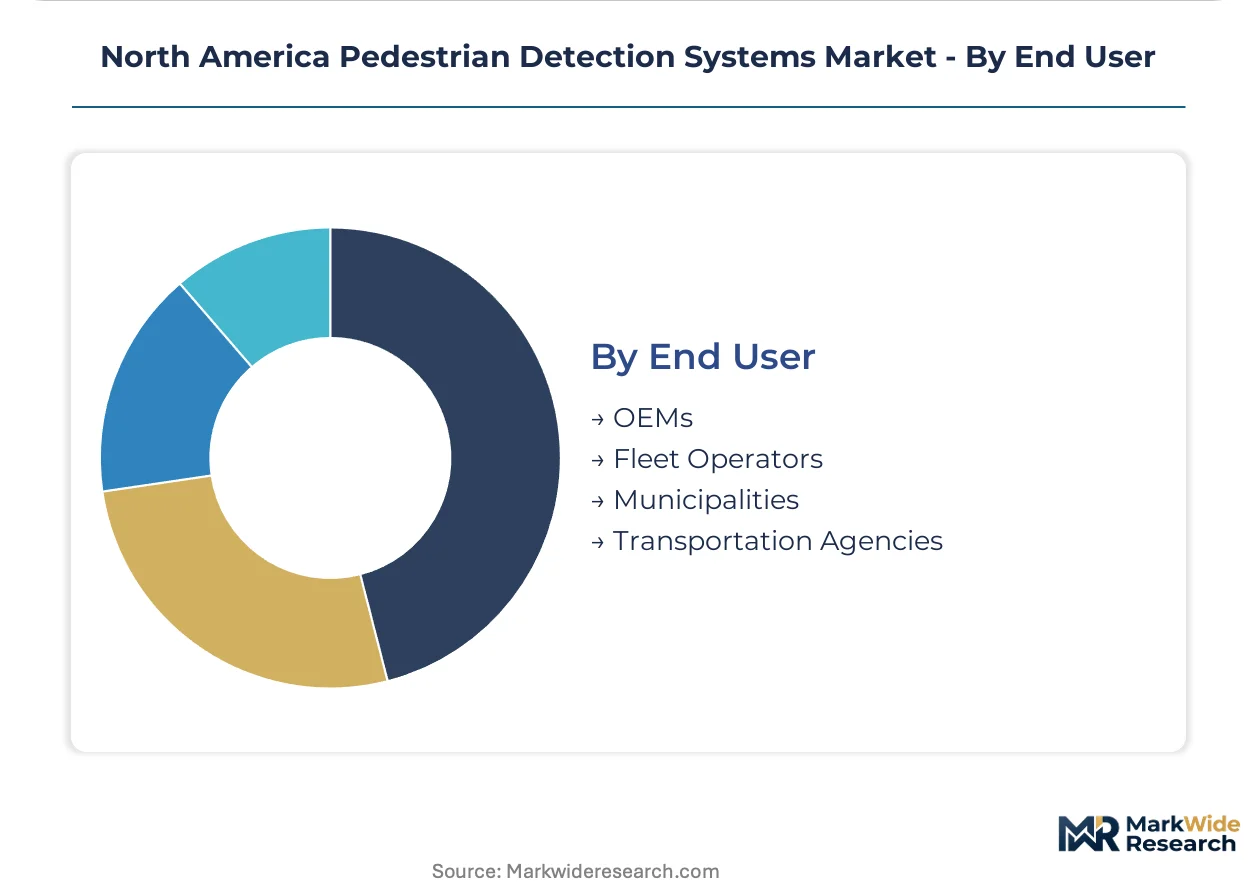
End User:
Procurement authority fragments across vehicle manufacturers, commercial operators, and government entities with distinct specification authority and contract structures.
- OEMs:Vehicle manufacturers specify integrated sensor suites during platform development. Detroit Three automakers and California-based autonomous vehicle developers anchor demand through multi-year supply agreements with tier-one radar-camera fusion specialists.
- Fleet Operators:Commercial vehicle and logistics companies purchase aftermarket systems and calibration services. Texas and California-based trucking fleets are driving independent collision repair network expansion for post-collision sensor realignment.
- Municipalities:City and county governments procure intersection and corridor monitoring infrastructure.
- Transportation Agencies:State and provincial departments of transportation deploy highway monitoring and work zone protection systems.
OEM relationships lock in component margins; fleet aftermarket channels capture software update revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes pedestrian detection systems through integrated OEM fitments and aftermarket calibration channels, while Canada and Mexico concentrate procurement in cross-border manufacturing corridors and municipal smart-city pilots.
United States
Detroit Three automakers anchor demand through multi-year supply agreements for radar-camera fusion platforms. NHTSA's automatic emergency braking mandate for light vehicles compresses development timelines across tier-one suppliers. California and Arizona autonomous vehicle testing corridors generate concentrated procurement for high-resolution camera systems with thermal augmentation.
Canada
Transport Canada coordinates cross-border type-approval standards that reduce supplier certification burden for integrated North American production. Federal infrastructure funding supports smart city deployments in Ontario and British Columbia municipalities. The Ontario automotive corridor concentrates sensor fusion procurement for luxury SUV platforms manufactured for export.
Mexico
Mexico's economic ministry aligns vehicle safety regulations with FMVSS requirements to facilitate integrated continental supply chains. The Bajío Region and Nuevo León anchor manufacturing integration for tier-one radar and camera module assembly. Cross-border logistics corridors generate aftermarket calibration demand for commercial fleets operating multi-state routes.
North America Pedestrian Detection Systems Market Competitive Landscape
Capability concentration sits with tier-one suppliers possessing embedded AI stacks and proprietary neural network training datasets; scale advantage sits with diversified automotive component conglomerates spanning full sensor portfolios. The market structure tilts toward consolidation as sensor fusion architectures displace discrete component sales. Three strategic archetypes dominate: chipset specialists with mapping integration, radar-camera fusion platform providers, and full-stack sensor conglomerates. Competitive moves center on neural network training throughput expansion and strategic partnerships for edge-case dataset acquisition.
Among diversified automotive component conglomerates, Robert Bosch GmbH, Continental AG, and Mobileye occupy distinct positions within the competitive hierarchy. Bosch exemplifies the full-stack archetype through its span from ultrasonic modules to solid-state lidar. Continental AG represents the radar-camera fusion specialist tier with supply relationships anchored in premium OEM channels. Mobileye sits within the chipset and mapping integration segment, sustaining technology leadership through proprietary EyeQ architecture deployment.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Mobileye |
| DENSO Corporation |
| Visteon Corporation |
| Toyota Motor Corporation |
| Autoliv |
| Aptiv |
| Magna |
| Others |
Value Network & Pricing Analysis
Undercapacity in East Asian CMOS foundries is compressing tier-one supplier margins while simultaneously elevating pricing power for semiconductor-integrated radar-camera fusion modules sold to Detroit Three automakers facing NHTSA AEB mandate deadlines.
Pricing Analysis
Long-term offtake agreements dominate procurement between tier-one suppliers and Detroit Three OEMs, locking in volume commitments for radar-camera fusion platforms while spot-market transactions persist for aftermarket calibration services. Pricing stratifies across premium, standard, and economy tiers based on neural network training dataset depth and IIHS certification tier. Cost compression in standard-tier camera modules is intensifying because CMOS sensor supply constraints force tier-two suppliers toward lower-margin image processing alternatives. Fleet operators exhibit highest price sensitivity, while premium OEMs purchasing SAE Level 2+ sensor fusion stacks demonstrate lowest elasticity.
Supply Chain Analysis
Upstream feedstock for CMOS image sensors draws from Taiwan, South Korea, and Japan, with 76-81 GHz radar chip fabrication concentrated in Germany and the United States. Millimeter-wave radar modules rest on gallium arsenide substrates, specialized RF components, and automotive-grade packaging materials. Single-source vulnerability in East Asian foundry capacity creates certification bottleneck exposure for tier-one suppliers facing FMVSS recertification timelines. Distribution runs through OEM captive supply chains for integrated fitments, while independent collision repair networks capture aftermarket calibration revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NHTSA's escalating AEB performance thresholds constitute a regulatory inflection compressing development cycles, positioning neural network training throughput as the decisive capability differentiator in this high-growth disruption.
For Market Incumbents: Insulate proprietary dataset advantages through exclusive edge-case data partnerships with California and Arizona autonomous vehicle testing operators. Deepen backward integration into CMOS sensor packaging to reduce exposure to East Asian foundry volatility. Lock in multi-year radar-chip supply agreements with German RF specialists before FCC spectrum allocation bottlenecks tighten further.
For New Entrants and Emerging Players: Pursue aftermarket calibration services in Texas and California where commercial fleet density exceeds dealer network coverage. Target smart city infrastructure deployments in Ontario and British Columbia municipalities accessing federal infrastructure funding. Lead with thermal-augmented camera retrofit kits for existing commercial vehicle fleets seeking IIHS-rated insurance premium reductions.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among tier-one suppliers with embedded AI stacks and over-the-air software update capabilities. Five-to-ten-year viability favors firms controlling proprietary pedestrian gait-pattern datasets rather than component manufacturers. Watch for NHTSA rulemaking on nighttime pedestrian detection performance as the signal indicating which sensor fusion architectures will dominate procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Integration | Unifies camera, radar, and lidar inputs into redundant perception stacks for SAE Level 2+ autonomy mandates. |
| Neural Network Training Partnership | Secures exclusive edge-case datasets from California and Arizona autonomous vehicle testing corridors. |
| Aftermarket Calibration Network Expansion | Captures post-collision sensor realignment revenue from Texas and California commercial fleet operators. |
| CMOS Supply Agreement Diversification | Reduces single-source exposure to Taiwan and South Korea foundry capacity constraints. |
| Smart City Infrastructure Pilot | Positions intersection monitoring platforms for Ontario and British Columbia municipal procurement cycles. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, tier-one supplier procurement directors, aftermarket collision repair network operators, and commercial fleet maintenance managers. Secondary validation drew from NHTSA FMVSS filings, IIHS test protocol documentation, vehicle production databases, and FCC spectrum allocation records. Bottom-up segmentation modeling triangulated against top-down market sizing across sensor modality, processing architecture, and deployment context.
Calibration against historical fitment rates and regulatory mandate phase-in schedules anchored volume projections across the analysis window. Segmentation dimensions modeled include sensor modality, processing architecture, vehicle platform class, OEM tier positioning, and regional production cluster. CAGRs derived from fitted adoption curves incorporating NHTSA AEB mandate compliance deadlines and IIHS rating incentive effects. Forecast inputs included semiconductor supply lead times and cross-border type-approval harmonization progress.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, semiconductor capital expenditure cycles, or federal infrastructure appropriations would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timing and technology cost curves. Cross-checking against IHS Markit vehicle registration data and supplier earnings disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Mexico Video Surveillance Market
Video Surveillance Systems
People Counting System Market
Video Surveillance Systems
Surveillance Camera Systems Market
Video Surveillance Systems
Brazil Surveillance Camera Market
Video Surveillance Systems
Japan Surveillance Storage Market
Video Surveillance Systems
Wireless Home Security Camera Market
Video Surveillance Systems
Night Vision Camera Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Storage Market
Video Surveillance Systems
Asia-Pacific Surveillance Analog Camera Market
Video Surveillance Systems
Wireless Video Surveillance Market
Video Surveillance Systems
Smart Outdoor Cameras Market
Video Surveillance Systems
Smart Security Camera Market
Video Surveillance Systems
Central Monitoring Station Market
Video Surveillance Systems
Night Vision System (NVS) Market
Video Surveillance Systems
United States Surveillance Storage Market
Video Surveillance Systems
Asia-Pacific Surveillance Storage Market