
 Rugged Thermal Cameras Market | 2026-2036
Rugged Thermal Cameras Market Size, Share, and Industry Trends Forecast 2026-2036
Rugged Thermal Cameras Market Intelligence
Skilled infrared sensor engineering talent is bifurcating the competitive landscape as defense primes and commercial security vendors compete for the same limited pool of thermal imaging specialists. Teledyne FLIR leverages its vertically integrated detector fabrication to control supply timelines for cooled and uncooled arrays. L3Harris Technologies anchors its position through long-term military contracts requiring ITAR-compliant manufacturing footprints. Leonardo DRS specializes in vehicle-mounted platforms for armored ground systems, occupying a niche with stringent shock and vibration specifications.
Rugged thermal cameras combine uncooled or cooled infrared focal plane arrays with hardened enclosures rated for extreme temperatures, humidity, and mechanical shock, typically operating in spectral bands from 7-14 micrometers for long-wave detection or 3-5 micrometers for mid-wave applications. Handheld configurations dominate volume shipments for firefighting and industrial inspection crews requiring portability in confined or elevated environments. Cooled technology commands premium positioning in military surveillance and long-range target identification where thermal sensitivity below 25 millikelvin distinguishes performance tiers. Drone-mounted systems represent the fastest-growing product configuration as UAV platforms expand beyond reconnaissance into infrastructure and agricultural monitoring.
FDA oversight of thermal cameras marketed for medical screening during public health emergencies has created dual-use compliance requirements for manufacturers serving both industrial and healthcare-adjacent channels. FCC equipment authorization governs radio-frequency data links in wireless thermal camera systems deployed for perimeter security and mobile command operations. Military end users navigate ITAR and EAR export control frameworks that restrict detector technology transfer, directly shaping supplier eligibility for international procurement. Stakeholders must monitor evolving defense budget priorities and dual-use technology control lists to anticipate demand shifts between commercial and classified applications.
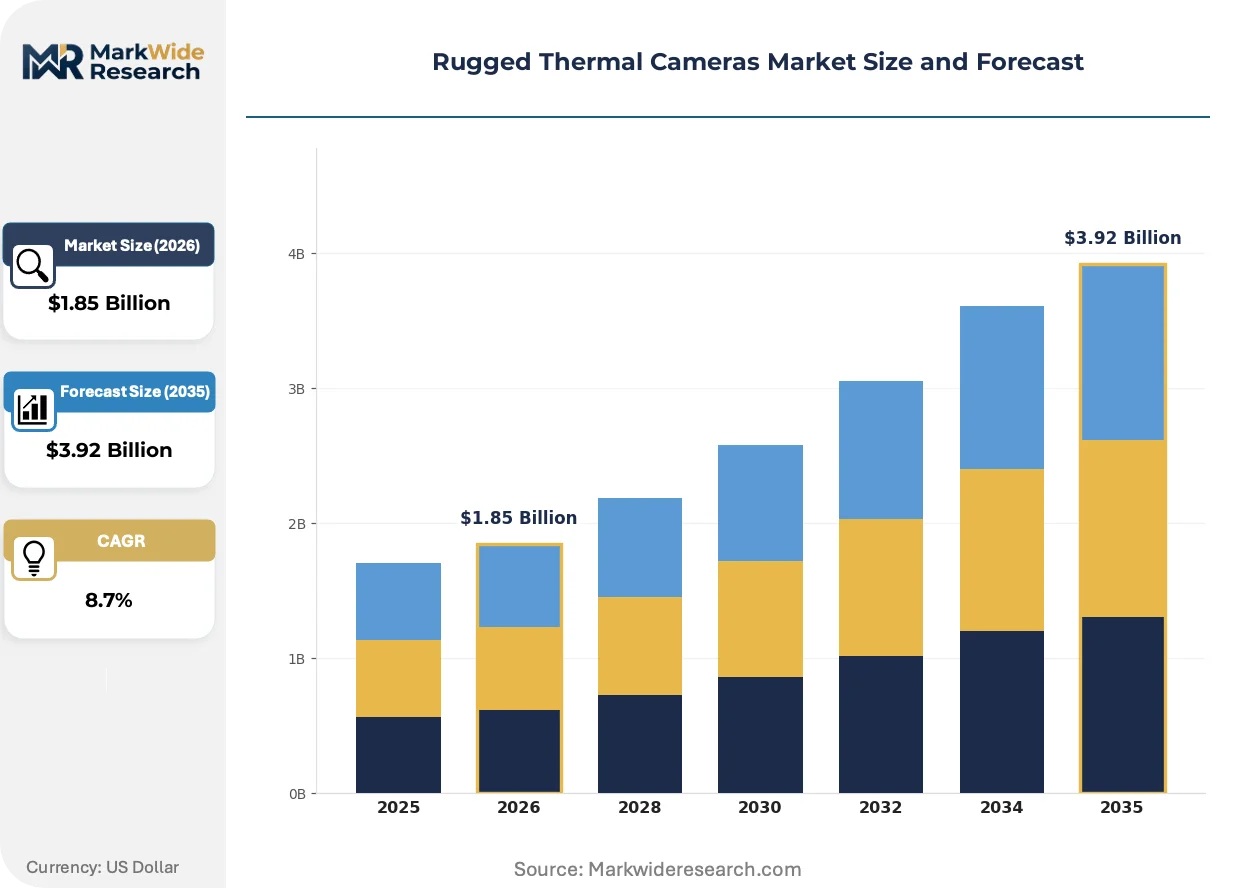
Market Dynamics
Defense procurement concentration around cooled infrared arrays is compressing supplier margins while uncooled microbolometer diffusion opens volume tiers for commercial security and industrial inspection segments.
Growth Catalysts
- Border security infrastructure mandates:US Customs and Border Protection fleet modernization programs are replacing legacy night-vision equipment with multi-spectral thermal systems for remote surveillance corridors.
- RoHS and REACH substance restrictions:European environmental compliance is accelerating lead-free solder and mercury-free detector transitions, forcing process upgrades that favor established defense contractors with captive metallization lines.
- Wildfire response agency budgets:California Department of Forestry and Fire Protection aerial operations are expanding thermal-equipped helicopter and drone contracts for hotspot detection in rugged terrain.
Market Restraints
- Germanium substrate supply concentration:Optical-grade germanium refining capacity clusters in China and Russia, exposing detector manufacturers to export restriction risks and price volatility for long-wave infrared lenses.
- ITAR-controlled detector technology:US State Department export licensing creates 90-180 day approval delays for international shipments of cooled focal plane arrays, disqualifying suppliers from fast-turn procurement cycles.
- Silicon wafer cost inflation:Uncooled microbolometer fabrication depends on 8-inch CMOS foundry capacity shared with automotive and consumer electronics, creating allocation competition during semiconductor shortage periods.
Strategic Opportunities
- India industrial safety compliance:Factory inspectorate mandates under BIS certification for hazardous area monitoring are creating first-time thermal camera installations in petrochemical and steel plants.
- Drone-mounted agricultural monitoring:Vineyard and orchard operators in France and Italy are adopting UAV-borne thermal systems for irrigation stress mapping, displacing handheld spot measurements.
- EU AI Act automated surveillance restrictions:Biometric identification limitations in public spaces are redirecting security procurement toward non-identifying thermal analytics for perimeter intrusion detection.
Industry Challenges
- IR sensor engineering talent scarcity:Defense primes and commercial security vendors compete for the same limited pool of thermal imaging specialists with microbolometer design experience.
- IP67 environmental sealing certification timelines:Third-party testing laboratory backlogs extend product launch schedules by 4-6 months for handheld configurations targeting firefighting applications.
- Legacy analog video integration:Municipal emergency response fleets require NTSC/PAL output compatibility that complicates digital-first product architectures and adds non-recurring engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rugged Thermal Cameras Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed, Handheld, Drone-mounted, Vehicle-mounted Technology: Uncooled, Cooled, Hybrid, Dual-Sensor End User: Military, Firefighting, Search & Rescue, Industrial Inspection Application: Surveillance, Building Inspection, Wildlife Monitoring, Energy Audits |
| Companies Covered | Teledyne FLIR, L3Harris Technologies, Axis Communications, Seek Thermal, Opgal Optronic Industries, Fluke Corporation, Leonardo DRS, Hikvision, Bosch Security Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rugged Thermal Cameras Market Strategic Shifts & Innovations
Uncooled detector technology is compressing unit economics while hardened enclosure standards proliferate across defense, industrial, and first responder segments. Three developments are restructuring competitive positioning.
Wafer-level packaging for vanadium oxide microbolometers is miniaturizing die footprints while preserving noise-equivalent temperature differential performance. Firefighting equipment manufacturers are adopting these compact arrays for helmet-mounted displays that previously required cooled technology. The shift is collapsing price tiers between professional and entry-level thermal imagers for confined-space rescue operations.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon refrigerants are forcing cooled detector manufacturers to transition Stirling engine cooling systems toward alternative working fluids. Industrial process monitoring segments in Germany and France face compliance deadlines that favor suppliers with certified low-global-warming-potential cooling architectures. Military procurement remains exempt but dual-use suppliers are converging on single cooling platform designs to streamline production.
Equipment-as-a-service contracting is displacing capital purchase models for municipal fire departments and infrastructure inspection firms. Leasing providers bundle thermal camera hardware with cloud-based image analysis subscriptions, transferring obsolescence risk from agency budgets to vendor balance sheets. This shift concentrates most visibly in US metropolitan fire districts facing pension fund pressure and compressed capital equipment cycles.
Rugged Thermal Cameras Market Segmentation
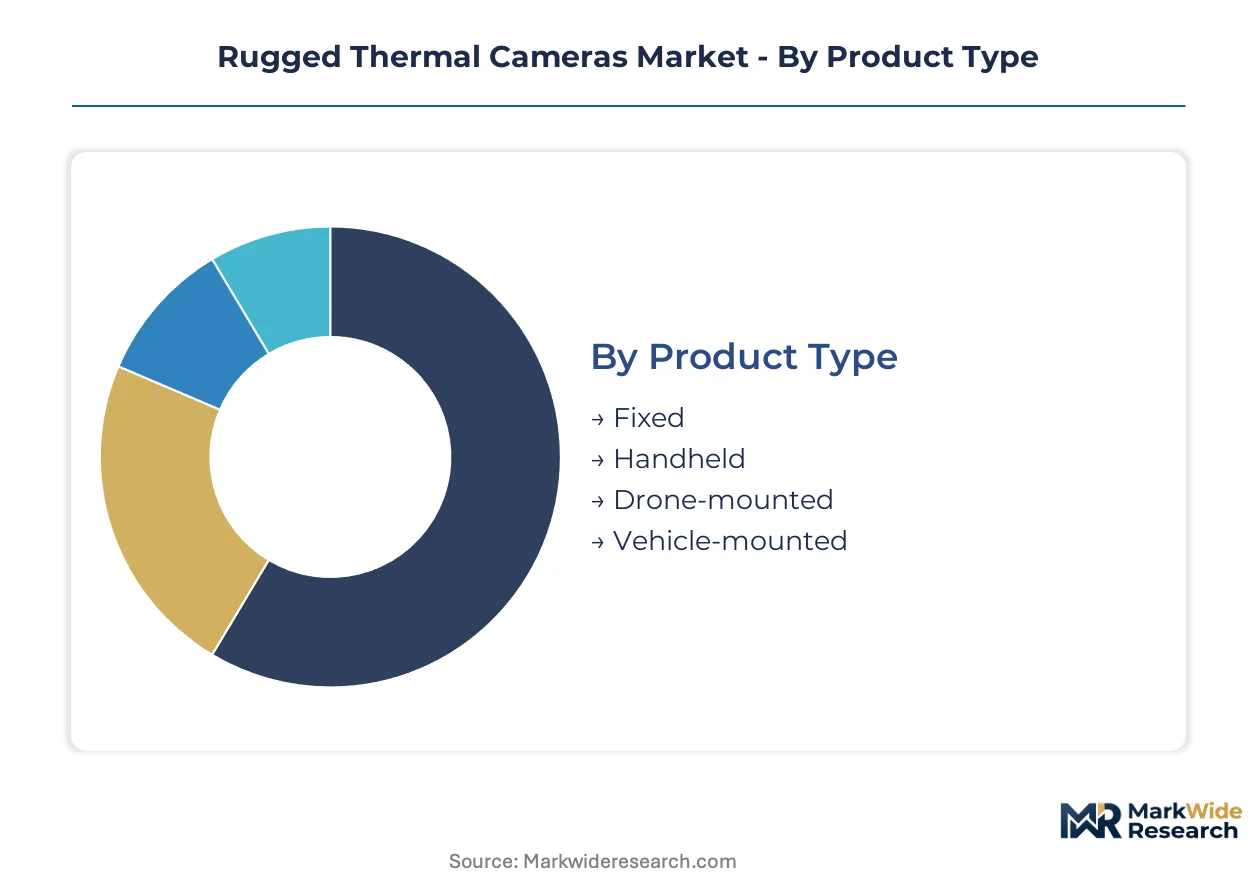
Product configurations in rugged thermal cameras serve vastly different operational constraints, from confined-space portability to long-range vehicle integration. Technology tiers separate premium military procurement from commercial volume markets. End-user specialization drives certification requirements that fragment supplier eligibility across defense, emergency response, and industrial channels.
Product Type:
Drone-mounted systems face the most intense substitution pressure as satellite thermal imaging and fixed-wing aerial platforms compete for infrastructure and agricultural monitoring contracts.
- Handheld:Compact enclosures with IP67 sealing and integrated displays serve firefighting crews and industrial inspectors operating in elevated or confined environments. US wildfire response agencies and European building maintenance firms are standardizing on these units for rapid deployment scenarios. Handheld configurations anchor the volume base while drone-mounted systems gain share at the steepest rate.
- Drone-mounted:Lightweight gimbal-stabilized payloads under 500 grams enable UAV platforms for vineyard stress mapping and power line inspection. French and Italian agricultural operators are displacing handheld spot measurements with these aerial systems.
- Fixed:Permanently installed perimeter security installations with weatherized housings protect critical infrastructure sites. Border security corridors in the United States deploy these for persistent wide-area surveillance.
- Vehicle-mounted:Shock-isolated turret systems integrate with armored ground platforms for military reconnaissance. Leonardo DRS specializes in this niche with stringent vibration specifications.
Volume concentrates in portable configurations while aerial platforms expand most quickly across commercial applications.
Technology:
Cost tier stratification separates defense procurement from commercial security markets, with foundry capacity competition driving uncooled volume economics.
- Uncooled:Vanadium oxide microbolometers fabricated on 8-inch CMOS lines deliver noise-equivalent temperature differentials sufficient for most security and inspection tasks. Wafer-level packaging is miniaturizing die footprints for helmet-mounted firefighting displays previously requiring cooled technology.
- Cooled:Stirling-engine focal plane arrays achieve thermal sensitivity below 25 millikelvin for long-range target identification. ITAR export licensing creates 90-180 day approval delays that disqualify suppliers from fast-turn international procurement cycles.
- Hybrid:Combined uncooled and cooled architectures optimize power consumption for extended-duration drone missions. These systems bridge performance gaps in dual-use military-commercial procurement.
- Dual-Sensor:Fused thermal-visible imagers enhance situational awareness for search and rescue operations in low-visibility conditions. Municipal emergency fleets value the redundant detection channels.
Uncooled technology dominates shipment volumes while cooled arrays retain premium positioning in classified military programs.
End User:
Customer type maturity varies sharply, with industrial inspection representing first-time adoption curves and military procurement following predictable modernization cycles.
- Military:Long-term ITAR-compliant contracts require captive manufacturing footprints and controlled detector technology transfer. NATO fleet modernization programs are expanding cooled infrared array budgets.
- Firefighting:Equipment-as-a-service leasing is displacing capital purchases in US metropolitan fire districts facing pension fund pressure. Cloud-based image analysis subscriptions transfer obsolescence risk to vendor balance sheets.
- Search & Rescue:Compact handheld units with NTSC/PAL analog output compatibility integrate with legacy municipal emergency response fleets. Digital-first architectures face non-recurring engineering costs for this segment.
- Industrial Inspection:Factory inspectorate mandates under India's BIS certification are creating first-time thermal camera installations in petrochemical and steel plants. Hazardous area monitoring compliance drives this emerging demand.
Industrial inspection climbs the fastest as regulatory mandates penetrate developing manufacturing economies.
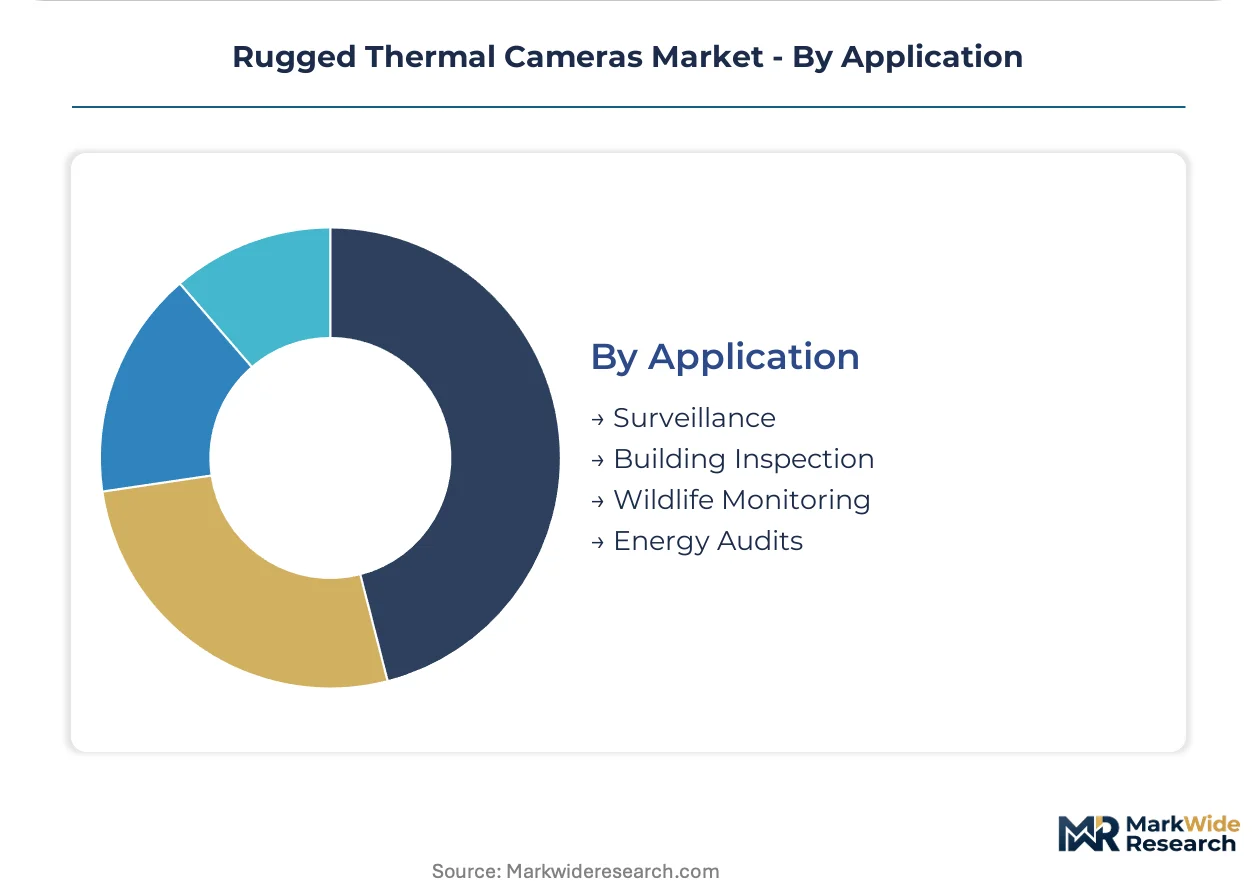
Application:
Geography concentration shapes demand patterns, with border security infrastructure concentrated in the United States and energy audit programs expanding across European building retrofit mandates.
- Surveillance:Multi-spectral thermal systems with automated analytics replace legacy night-vision equipment in remote border corridors. EU AI Act biometric restrictions are redirecting procurement toward non-identifying thermal perimeter detection.
- Building Inspection:Energy audit programs in Germany and France leverage thermal imaging for building envelope leakage detection. F-Gas Regulation compliance deadlines favor suppliers with certified low-global-warming-potential cooling architectures.
- Wildlife Monitoring:Conservation researchers deploy handheld units for nocturnal species census in rugged terrain. Academic procurement follows grant funding cycles with extended evaluation periods.
- Energy Audits:Utility-sponsored residential and commercial efficiency programs standardize on uncooled imagers for rapid building assessment. California utilities are expanding contractor certification programs for these deployments.
Surveillance applications retain the largest installed base while building inspection gains share fastest through European regulatory energy efficiency mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in US defense procurement corridors while European industrial buyers extract volume discounts through consolidated tendering. German and French border security agencies negotiate multi-year framework agreements that compress supplier margins compared to American agency spot purchasing.
United States
US Customs and Border Protection fleet modernization drives multi-spectral thermal system deployment across remote surveillance corridors. FCC equipment authorization governs radio-frequency data links in wireless perimeter security installations. California Department of Forestry and Fire Protection aerial operations in Sacramento and Riverside counties expand thermal-equipped helicopter contracts for rugged terrain hotspot detection.
Germany
Industrial process monitoring segments in the Ruhr Valley and Bavaria face EU F-Gas Regulation compliance deadlines for low-global-warming-potential cooling architectures. REACH substance restrictions accelerate lead-free solder transitions favoring established defense contractors with captive metallization lines. Stuttgart and Munich industrial clusters source vehicle-mounted systems for armored ground platform integration.
France
Vineyard and orchard operators in Bordeaux and Champagne regions adopt UAV-borne thermal systems for irrigation stress mapping. EU AI Act biometric identification limitations redirect security procurement toward non-identifying thermal analytics for perimeter intrusion detection. Lyon and Toulouse aerospace clusters concentrate cooled detector manufacturing for dual-use military-commercial applications.
India
Factory inspectorate mandates under BIS certification create first-time thermal camera installations in petrochemical and steel plants. DGFT export licensing frameworks shape supplier eligibility for international procurement cycles. Gujarat and Maharashtra industrial corridors in Vadodara and Mumbai deploy handheld units for hazardous area monitoring compliance.
United Kingdom
Municipal emergency response fleets in Greater London and the Midlands require NTSC/PAL analog output compatibility complicating digital-first product architectures. CE marking and UKCA post-Brexit conformity assessments extend certification timelines for firefighting equipment manufacturers. Manchester and Birmingham security technology clusters focus on fixed perimeter installations for critical infrastructure protection.
Rugged Thermal Cameras Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where vertically integrated detector fabricators command supply timeline control while volume assemblers compete on unit economics. The vendor base separates into three strategic archetypes: defense primes with ITAR-compliant manufacturing footprints, commercial security specialists with rapid product iteration capabilities, and industrial instrumentation incumbents leveraging distribution scale. Dominant competitive moves include backward integration into detector fabrication and strategic partnerships with UAV platform manufacturers for aerial payload integration.
Among US-based defense contractors, Teledyne FLIR and L3Harris Technologies exemplify the vertically integrated archetype through in-house production of cooled and uncooled arrays. Leonardo DRS occupies a position within the vehicle-mounted specialization tier, anchoring supply relationships for armored ground system integration. These three entities represent distinct competitive vectors: detector fabrication control, long-term military contract anchoring, and niche shock-isolation engineering respectively.
| Leading Market Players |
|---|
| Teledyne FLIR |
| L3Harris Technologies |
| Axis Communications |
| Seek Thermal |
| Opgal Optronic Industries |
| Fluke Corporation |
| Leonardo DRS |
| Hikvision |
| Bosch Security Systems |
| Others |
Cost & Logistics Intelligence
CMOS foundry scale economies at 8-inch wafer nodes concentrate uncooled microbolometer production among a handful of integrated device manufacturers, compressing unit costs for volume tiers while preserving premium pricing power for ITAR-compliant cooled array suppliers serving classified defense programs. This scale concentration simultaneously anchors price floors for commercial security segments and sustains margin capture for military-grade detector fabrication.
Pricing Analysis
Configured-to-order pricing for vehicle-mounted turret systems with shock-isolation engineering commands substantial premiums over standard handheld units. Three-tier pricing structure across premium, standard, and economy levels separates ITAR-compliant cooled arrays from commercial uncooled imagers and entry-level firefighting helmets. Cost compression in the uncooled tier is intensifying because wafer-level packaging miniaturization collapses die footprints without performance sacrifice. Municipal fire departments exhibit highest price sensitivity through equipment-as-a-service leasing adoption, while military procurement demonstrates lowest sensitivity due to mission-critical specifications.
Supply Chain Analysis
China and Russia anchor optical-grade germanium refining capacity for long-wave infrared lenses, while Taiwan and South Korea dominate 8-inch CMOS foundry output for uncooled microbolometer fabrication. Detector manufacturing draws from germanium substrates, vanadium oxide thin films, and mercury-cadmium-telluride epitaxial wafers. Single-source vulnerability concentrates in germanium supply chains exposed to export restriction risks. Distribution runs through defense prime direct contracts, industrial instrumentation distributors, and emerging UAV platform integration partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microbolometer design expertise scarcity constrains supplier expansion across both defense and commercial channels, with foundry allocation competition and ITAR compliance requirements filtering market entry. This capability bottleneck rewards incumbents with captive talent pipelines while elevating acquisition premiums for engineering-intensive targets.
For Market Incumbents: Consolidate detector fabrication control through backward integration into vanadium oxide thin-film deposition or captive germanium lens polishing capacity. Deepen ITAR-compliant manufacturing footprints to defend against emerging commercial security vendors poaching military contracts. Prioritize certification investment for EU F-Gas Regulation compliance to capture building inspection retrofits in Germany and France. For New Entrants and Emerging Players: Lead with drone-mounted payload miniaturization targeting agricultural monitoring in French and Italian vineyard regions where UAV-borne thermal systems displace handheld measurements. Exploit underpenetrated industrial safety compliance in Indian petrochemical corridors under BIS certification mandates. Pursue platform integration partnerships with established UAV manufacturers rather than direct hardware competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated detector fabricators with dual-use military-commercial product architectures. Long-term viability rests on suppliers bridging cooled and uncooled technology portfolios as wafer-level packaging erodes traditional performance tier boundaries. Watch Stirling engine cooling system alternative fluid certifications as inflection indicator for dual-use supplier consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Wafer-Level Packaging Scale-Up | Miniaturized vanadium oxide arrays collapse price tiers for helmet-mounted firefighting displays. |
| ITAR-Compliant Manufacturing Footprint Expansion | Captive production lines secure defense prime eligibility for NATO fleet modernization programs. |
| Low-GWP Cooling Architecture Certification | EU F-Gas Regulation compliance unlocks German and French industrial process monitoring segments. |
| UAV Platform Integration Partnership | Gimbal-stabilized payload co-development captures agricultural monitoring share in Bordeaux vineyards. |
| Equipment-as-a-Service Contracting Model | Cloud-based image analysis subscriptions transfer obsolescence risk from municipal fire department budgets. |
Research Approach
The analysis maps cooled infrared arrays, uncooled microbolometers, hybrid architectures, and dual-sensor configurations, each validated through procurement officers at defense primes, thermal imaging engineering directors, firefighting equipment manufacturers, and industrial safety compliance consultants. Primary interviews with these stakeholders combined with secondary validation from ITAR licensing databases, EU F-Gas Regulation compliance registries, BIS certification filings, and semiconductor foundry utilization disclosures. Bottom-up shipment modeling and top-down defense budget allocation triangulation anchored volume estimates.
Consistency checks against external benchmarks validated projections across the analysis window through cross-referencing with customs trade data for germanium substrate flows and CMOS foundry capacity reports. Segmentation dimensions modeled include product configuration, detector technology tier, end-user vertical, and application intensity. CAGRs derived from installed base replacement cycles, regulatory compliance deadline clustering, and platform substitution elasticities in drone-mounted versus handheld deployments.
The analysis sits within stated boundaries; outcomes outside sustained NATO defense spending levels, stable germanium export flows, or uninterrupted CMOS foundry allocation would require recalibration. Forecasts reflect assumptions regarding ITAR licensing timeline stability, EU AI Act biometric restriction permanence, and wildfire response agency budget continuity. Recalibration cycles align with material shifts in defense procurement prioritization, semiconductor capacity expansion announcements, or environmental regulation phase-down schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Hosted Video Surveillance Market
Video Surveillance Systems
Global GCC Video Surveillance Storage Market
Video Surveillance Systems
In-Vehicle Video Surveillance Market
Video Surveillance Systems
CCTV Camera Market
Video Surveillance Systems
Japan Surveillance Analog Camera Market
Video Surveillance Systems
Germany Surveillance IP Camera Market
Video Surveillance Systems
3D Surveillance Software Market
Video Surveillance Systems
Wireless Home Security Camera Market
Video Surveillance Systems
Japan Surveillance Camera Market
Video Surveillance Systems
AI CCTV Market
Video Surveillance Systems
Global CCTV Market
Video Surveillance Systems
Homeland Security Surveillance Camera Market
Video Surveillance Systems
Canada Surveillance IP Camera Market
Video Surveillance Systems
United Kingdom Surveillance Camera Market
Video Surveillance Systems
Japan Surveillance IP Cameras Market
Video Surveillance Systems
Video Surveillance and Vsaas Market