
 Camera Alarm System Market | 2026-2036
Camera Alarm System Market Size, Share, and Industry Trends Forecast 2026-2036
Camera Alarm System Market Analytics
Subscription-based leasing and security-as-a-service financing is rewriting capital deployment patterns for mid-sized buyers who previously deferred upgrades. Hangzhou Hikvision Digital Technology Co., Ltd. leverages integrated manufacturing scale across sensor and NVR lines. Bosch Security Systems GmbH anchors European certification standards for data-handling hardware. Axis Communications AB specializes in edge-computing camera architectures that reduce bandwidth costs.
A camera alarm system integrates video capture hardware with intrusion detection logic, typically processing feeds through on-device analytics or centralized management platforms at frame rates exceeding 30fps and resolutions from 2MP to 8MP. Its primary commercial purpose centers on real-time threat verification, reducing false dispatch rates that plague standalone audio sensors. Wireless connectivity and smart detection technology command expanding margin pools as installers prioritize minimal cabling and AI-enabled object classification. The residential application segment matures around DIY installation kits, while institutional buyers drive specification complexity through multi-site federation requirements.
The EU AI Act, GDPR, and CE marking framework collectively mandate algorithmic transparency and data retention limits for systems deployed in European public spaces. The FCC in the United States governs wireless transmission spectra that underpin cordless camera deployments, while China's MIIT issues GB standards for network-connected security devices. Stakeholders must monitor divergence between regional AI governance regimes when designing unified product platforms.
Market Dynamics
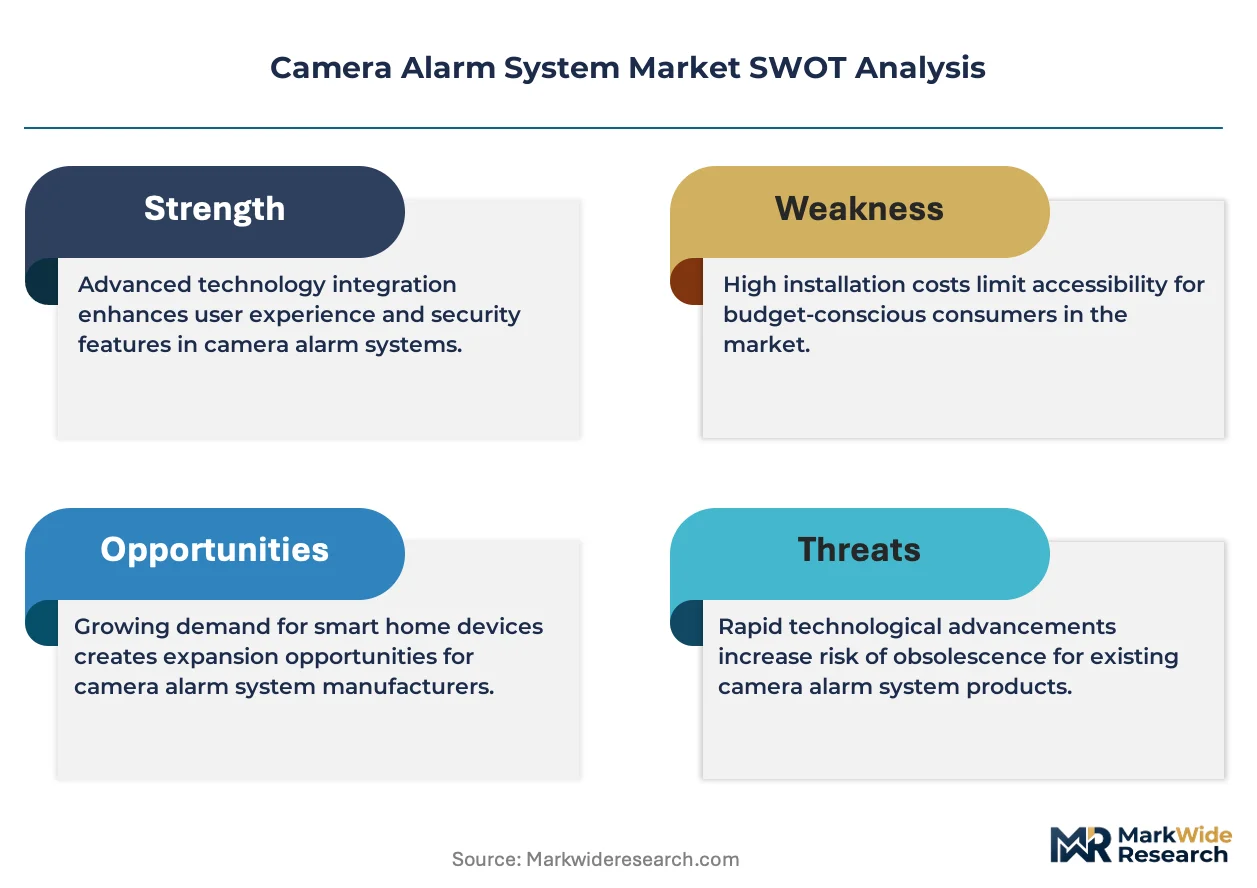
The EU AI Act and GDPR are forcing hardware refresh cycles across European deployments while subscription-based security-as-a-service financing rewrites capital deployment patterns for mid-sized buyers.
Growth Catalysts
- Algorithmic transparency mandates:The EU AI Act requires explainable AI in public-space surveillance, accelerating replacement of legacy black-box systems with auditable edge-computing architectures.
- Smart detection convergence:AI-enabled object classification at the camera level reduces bandwidth costs and false dispatch rates, pulling demand from standalone audio sensor networks.
- China's MIIT GB standards:Network-connected security device certification requirements in China are consolidating domestic supply chains and driving export-compatible manufacturing scale.
Market Restraints
- CMOS sensor supply concentration:Image sensor fabrication concentrates among Taiwanese and South Korean foundries, exposing camera OEMs to geopolitical supply disruptions.
- FCC spectrum licensing friction:Cordless camera deployments in the United States face unpredictable wireless transmission spectrum allocation timelines.
- Cloud storage substitution pressure:Hybrid cloud-NVR architectures threaten pure on-premise NVR vendors as buyers prioritize remote accessibility over local redundancy.
Strategic Opportunities
- DIY residential underpenetration:Self-installation kits for single-family homes remain nascent outside North America, particularly in German and Japanese markets where professional installation dominates.
- Multi-site federation demand:Institutional buyers managing distributed property portfolios seek unified management platforms spanning hundreds of endpoints.
- Edge-AI and 5G convergence:Low-latency cellular connectivity combined with on-device inference enables battery-powered deployments without fixed infrastructure.
Industry Challenges
- Embedded systems talent scarcity:Shortage of firmware engineers capable of optimizing neural network inference on resource-constrained camera SoCs delays product roadmaps.
- CE-GDPR-AI Act compliance stacking:European certification requires sequential hardware validation against three overlapping regulatory frameworks, extending time-to-market by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camera Alarm System Market |
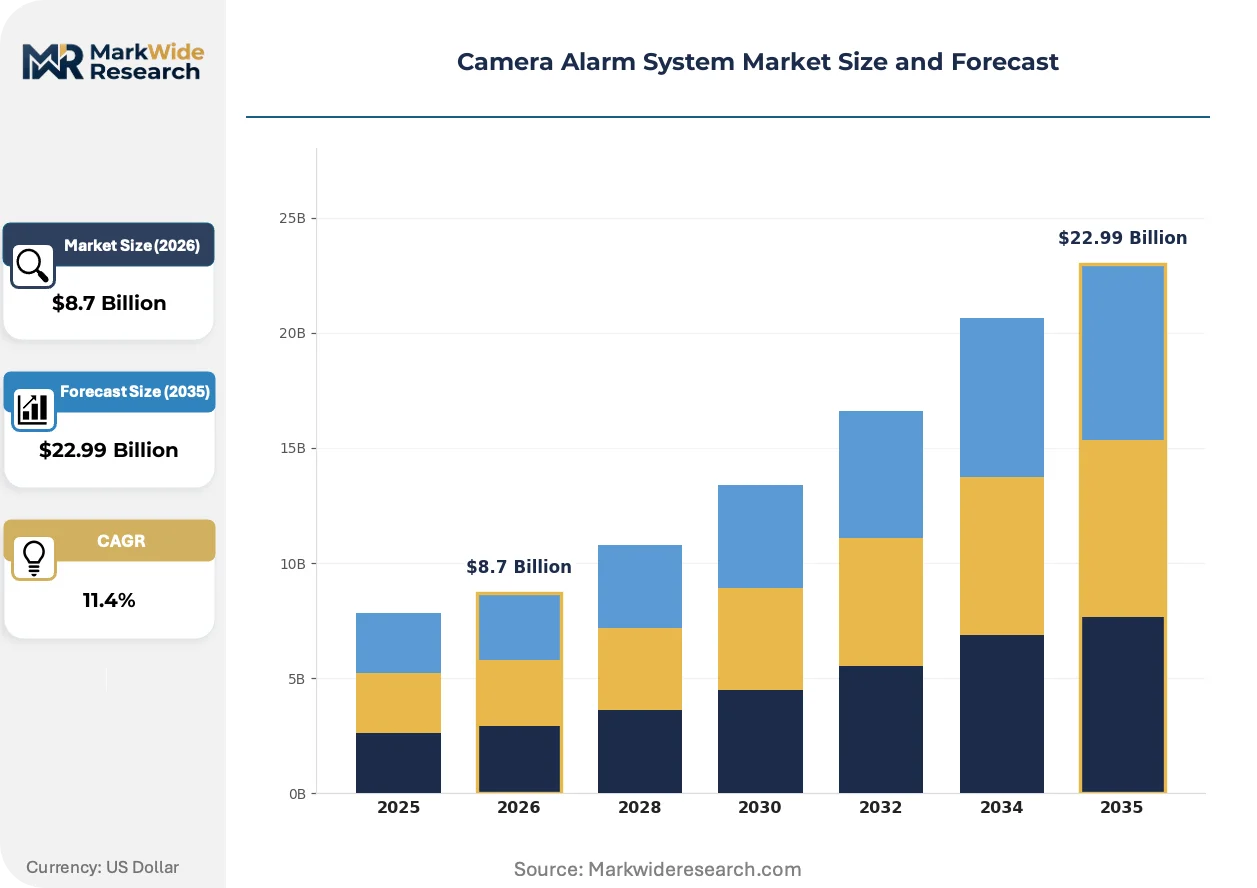
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired, Wireless, Hybrid, PoE Application: Residential, Commercial, Industrial, Institutional Technology: Infrared, Night Vision, HD, Smart Detection End User: Homeowners, Property Managers, Business Owners, Security Firms |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd., Dahua Technology Co., Ltd., Bosch Security Systems GmbH, Axis Communications AB, Honeywell International Inc., Johnson Controls, Hanwha Vision, ADT Inc., Arlo Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camera Alarm System Market Evolving Landscape
Video analytics processing is decentralizing from centralized servers to camera-edge silicon, compressing infrastructure requirements while elevating real-time response capabilities.
Edge-computing camera architectures are migrating from centralized NVR-dependent topologies toward distributed inference nodes. Large commercial property managers in the United States and Germany are piloting 4K@60fps devices with on-device person-vehicle-package classification. This migration from server-centric to edge-native processing is collapsing bandwidth requirements and enabling wireless-only deployments in retrofit-heavy urban cores.
The EU AI Act's risk-based classification system is mandating human-in-the-loop verification for biometric identification functions in public spaces. Hardware vendors must now document algorithmic decision pathways and implement automatic logging with 30-day retention limits. High-traffic transportation hubs and municipal surveillance networks across France, Germany, and Italy are most affected, with procurement specifications now requiring CE marking plus algorithmic impact assessments.
Security-as-a-service financing is displacing capital purchase models among mid-sized commercial buyers. Leasing arrangements bundling hardware, installation, and cloud storage are capturing facilities management departments previously deferring upgrades due to budget constraints. This shift is most visible in United States multi-tenant office buildings and German retail chains, where OpEx preference now dominates RFP evaluation criteria.
Camera Alarm System Market Segmentation
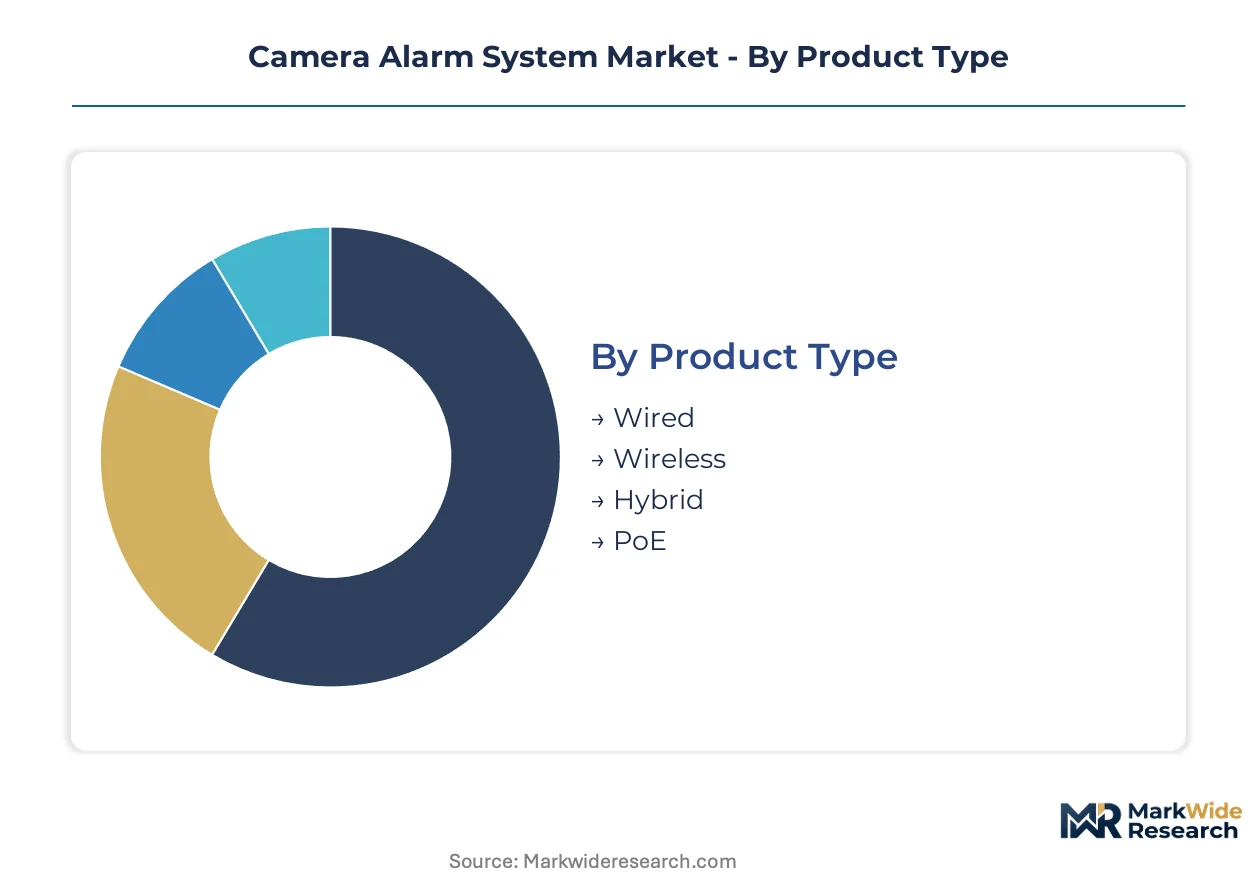
Camera alarm system purchasing decisions hinge on infrastructure constraints, regulatory exposure, and operational scale. Segmentation reveals how technology choices diverge across property types and buyer sophistication levels.
Product Type:
Deployment topology determines installation labor, power redundancy, and cybersecurity exposure across the use-case spectrum.
- Wired:Coaxial or Ethernet-based fixed connections deliver uninterrupted power and signal integrity for high-security facilities. Demand concentrates in German industrial campuses and US data centers where electromagnetic interference resilience outweighs retrofit costs.
- Wireless:Battery or WiFi-enabled units eliminate conduit runs, accelerating deployment in heritage buildings and leased commercial spaces. Property managers in United States multi-tenant offices favor cordless flexibility for rapid reconfiguration between tenants.
- Hybrid:Dual-path architectures combine wired backbone reliability with wireless edge extensibility. Infrastructure modernization projects in Chinese smart cities deploy hybrid topologies to bridge legacy analog zones with IP-native expansion.
- PoE:Power-over-Ethernet consolidates data and electrical delivery through single-cable drops, reducing switchgear complexity. German commercial retrofits specify PoE to minimize electrical permitting delays.
The dominant share belongs to Wired systems in institutional procurement, while Wireless is closing the gap fastest among mid-sized commercial buyers.
Application:
Security specification intensity tracks asset value, occupancy patterns, and liability exposure across property categories.
- Residential:Single and multi-family dwellings prioritize discrete aesthetics, mobile app integration, and cloud subscription economics. DIY installation kits from Hangzhou Hikvision Digital Technology Co., Ltd. and Bosch Security Systems GmbH dominate United States suburban markets where homeowner self-configuration reduces total cost of ownership.
- Commercial:Retail, office, and hospitality properties demand centralized monitoring, integration with access control, and GDPR-compliant data handling. German retail chains and US multi-tenant buildings specify federated management platforms spanning dispersed endpoints.
- Industrial:Manufacturing and logistics facilities require explosion-rated housings, thermal imaging, and vibration-resistant mounting. China's MIIT GB standards certification governs network-connected device deployment in heavy industrial zones.
- Institutional:Government, healthcare, and education campuses mandate encrypted transmission, audit logging, and human-in-the-loop verification under EU AI Act risk classifications. French transportation hubs and Italian municipal networks lead specification complexity.
Commercial deployments generate the highest absolute revenue, though Institutional specifications command the steepest expansion trajectory as algorithmic transparency mandates proliferate.
Technology:
Image capture and processing capabilities determine detection accuracy, bandwidth consumption, and storage economics.
- Infrared:Passive thermal detection identifies heat signatures through obscurants including smoke, foliage, and darkness. Perimeter security at German chemical facilities and US critical infrastructure sites relies on infrared for zero-light threat verification.
- Night Vision:Image intensification amplifies ambient starlight or moonlight for monochrome scene reconstruction. Lower-cost residential installations in Japan and residential exurban United States deploy night vision where active illumination is prohibited.
- HD:1080p to 4MP resolution streams enable facial recognition and license plate capture at operational distances. Chinese urban surveillance networks standardize on HD minimums for evidentiary admissibility.
- Smart Detection:On-device neural networks classify persons, vehicles, and packages without server round-trips. Axis Communications AB edge-computing architectures reduce bandwidth costs for wireless-only deployments in bandwidth-constrained environments.
Smart Detection is gaining share fastest as AI-enabled object classification displaces motion-only triggering, while HD remains the baseline specification across all buyer tiers.
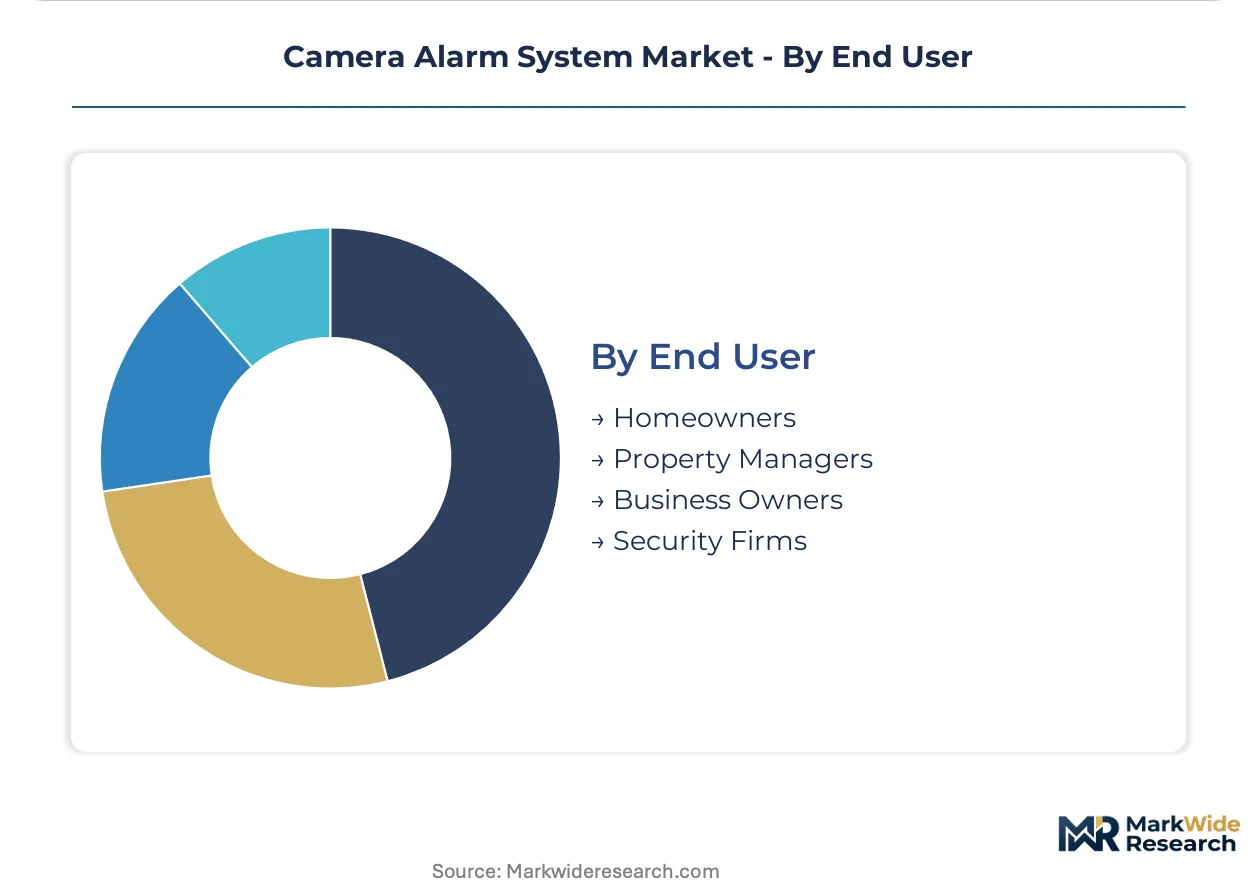
End User:
Procurement authority and technical sophistication shape vendor engagement models and support requirements.
- Homeowners:Individual consumers prioritize subscription bundling, smartphone alerts, and minimal configuration. German and Japanese markets lag United States penetration due to professional installation cultural preferences.
- Property Managers:Facilities professionals managing multi-site portfolios require unified dashboards, tenant privacy controls, and OpEx-aligned leasing structures. US and German commercial real estate investment trusts drive security-as-a-service financing adoption.
- Business Owners:Small and mid-sized enterprises balance upfront capital constraints against insurance premium reductions from verified alarm response. China's private manufacturing sector favors domestic MIIT-certified suppliers for cost and compliance alignment.
- Security Firms:Monitoring service providers specify interoperability standards, central station automation APIs, and false alarm liability minimization. French and Italian municipal contractors face EU AI Act biometric identification restrictions in public space deployments.
Property Managers control the largest addressable spend, while Security Firms are climbing fastest as monitoring centralization consolidates fragmented buyer demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German industrial procurement where CE-GDPR-AI Act compliance stacking extends validation cycles, while Chinese manufacturing clusters exploit MIIT GB standardization to compress unit economics for export-compatible production.
United States
Multi-tenant office buildings and data centers drive specification intensity through FCC-governed wireless spectrum deployments and OpEx-aligned security-as-a-service financing. The FCC regulates cordless camera transmission spectra with unpredictable allocation timelines. Greater Boston and Pacific Northwest technology corridors pilot 4K edge-computing architectures with on-device inference.
Germany
Industrial campuses and retail chains mandate electromagnetic interference resilience and algorithmic transparency under overlapping regulatory frameworks. The EU AI Act requires explainable AI in public-space surveillance alongside GDPR data retention limits. Bavaria's automotive supplier parks and North Rhine-Westphalia chemical facilities anchor continental demand for PoE retrofit specifications.
China
Smart city infrastructure modernization and private manufacturing sector expansion consolidate domestic supply chains around network-connected security device certification. MIIT issues GB standards governing surveillance hardware interoperability and cybersecurity. Yangtze River Delta and Pearl River Delta manufacturing clusters scale export-compatible sensor and NVR production.
France
Transportation hubs and municipal surveillance networks face stringent biometric identification restrictions requiring human-in-the-loop verification. The EU AI Act risk-based classification system mandates automatic logging with 30-day retention limits. Île-de-France transit authorities and Provence-Alpes-Côte d'Azur port facilities lead procurement specification complexity.
Japan
Professional installation cultural preferences suppress DIY residential penetration despite aging demographics and single-family security demand. METI oversees industrial standards for network-connected devices while local fire codes restrict active illumination. Kanto and Kansai metropolitan areas concentrate facilities management procurement for multi-site federation platforms.
Camera Alarm System Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensor modules and edge silicon. Market structure tilts toward consolidated manufacturing scale among vertically integrated Asian electronics conglomerates, with European and North American vendors differentiating through certification compliance and software integration. Three archetypes dominate: integrated manufacturing conglomerates controlling sensor-to-NVR value chains, regional certification specialists anchoring data-handling hardware standards, and edge-computing architects optimizing distributed inference topologies. Competitive moves concentrate on backward integration into CMOS sensor supply and strategic partnerships with cloud infrastructure providers.
Among integrated manufacturing conglomerates, Hangzhou Hikvision Digital Technology Co., Ltd. and Dahua Technology Co., Ltd. exemplify scale-driven platform control spanning domestic certification alignment and export-compatible production. Bosch Security Systems GmbH occupies a position within the European certification specialist archetype, anchoring data-handling hardware validation against CE-GDPR-AI Act frameworks. Axis Communications AB represents the edge-computing architecture tier, specializing in distributed inference nodes that reduce bandwidth dependency for wireless-only deployments.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Dahua Technology Co., Ltd. |
| Bosch Security Systems GmbH |
| Axis Communications AB |
| Honeywell International Inc. |
| Johnson Controls |
| Hanwha Vision |
| ADT Inc. |
| Arlo Technologies Inc. |
| Others |
Value Network & Pricing Analysis
Taiwanese and South Korean CMOS sensor foundries anchor upstream supply concentration, directing margin pools toward camera OEMs with captive semiconductor procurement or long-term foundry partnerships. Pricing power downstream fragments across certification tiers, with EU-compliant hardware commanding substantial premiums over baseline export variants.
Pricing Analysis
Configured-to-order pricing for institutional-grade systems with CE-GDPR-AI Act compliance stacking spreads 40-60 percent above standard SKUs lacking algorithmic transparency documentation. The dominant structure stratifies across premium, standard, and economy tiers, with differentiation driven by certification grade and after-sales service bundling. Cost compression in wireless residential tiers is intensifying because Chinese manufacturing clusters exploit MIIT GB standardization to compress unit economics. Small and mid-sized enterprises exhibit highest price sensitivity, while German industrial campuses and US data centers demonstrate lowest sensitivity due to liability-driven specification rigidity.
Supply Chain Analysis
Export-control regimes restricting advanced semiconductor manufacturing equipment to Chinese entities are forcing supply chain reconfiguration toward Taiwan, South Korea, and domestic Chinese foundry expansion. Image sensor fabrication draws from specialized CMOS wafer production, edge-AI silicon, and precision optical lens assemblies. Single-source vulnerability concentrates in sub-10nm sensor die production where two foundries control effective capacity. Distribution runs through authorized security integrators in developed markets and direct OEM channels in price-sensitive regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Camera alarm system markets present a service-attach opportunity where security-as-a-service financing and cloud storage subscriptions expand revenue per endpoint faster than hardware shipment growth alone.
For Market Incumbents: Insulate high-margin institutional accounts through backward integration into edge-AI silicon design and exclusive certification partnerships with European notified bodies. Subscription-based leasing models from emerging cloud-native competitors threaten installed-base stickiness. Priority levers include captive supply of neural network-optimized SoCs and multi-year service contracts with automatic refresh clauses. For New Entrants and Emerging Players: German and Japanese DIY residential segments remain underpenetrated relative to North American adoption curves, presenting white-space targets for self-installation kits with localized app interfaces. Professional installation cultural preferences in these markets resist direct-to-consumer channels, suggesting partnership routes through electrical retailers and insurance bundling programs as the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed security-as-a-service platforms consolidating fragmented monitoring central stations across US metropolitan markets. Long-term viability across the analysis window hinges on recurring revenue density per subscriber and cloud infrastructure scale economies. The signal to watch is consolidation velocity among regional monitoring providers as central station automation APIs become table stakes.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Silicon Development | On-device inference reduces bandwidth costs for wireless deployments in bandwidth-constrained German urban cores. |
| Security-as-a-Service Platform Launch | OpEx-aligned financing captures US multi-tenant office buildings previously deferring capital upgrades. |
| EU Certification Fast-Track | CE-GDPR-AI Act compliance stacking accelerates time-to-market for institutional procurement in French transportation hubs. |
| Hybrid Cloud-NVR Integration | Remote accessibility features displace pure on-premise vendors in mid-sized commercial buyer segments. |
| Multi-Site Federation Partnership | Unified management platforms address distributed property portfolio requirements of US and German real estate investment trusts. |
Research Methodology
A standing panel of security systems integrators, facilities management directors, cloud infrastructure procurement officers, and regulatory compliance leads provided ongoing calibration throughout the study. Primary interviews with property managers and OEM product strategists combined with secondary validation from FCC spectrum allocation filings, MIIT GB standard publications, EU AI Act implementation guidance, and customs trade data for image sensor imports. Bottom-up endpoint shipment modeling and top-down security spending allocation triangulated market sizing across wired, wireless, hybrid, and PoE deployment topologies.
Scenario-bracketing around regulatory implementation timelines and foundry capacity expansion schedules anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product topology, application intensity, end-user procurement authority, and regional regulatory cluster. CAGRs derived from elasticity-adjusted replacement cycle analysis and greenfield penetration curves for edge-AI architectures. Neural network inference optimization roadmaps and 5G module cost trajectories served as industry-specific forecast inputs.
Practitioners should monitor MIIT export license expansions, EU AI Act enforcement variance across member states, and FCC spectrum reallocation proceedings for early signals of forecast revision. Forecasts reflect assumptions regarding foundry capacity allocation and regulatory compliance cost trajectories. Material shifts in semiconductor export control scope or biometric identification restriction tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Smart Doorbell Camera Market
Video Surveillance Systems
Middle East and Africa Video Surveillance Market
Video Surveillance Systems
India Surveillance Analog Camera Market
Video Surveillance Systems
India Surveillance Storage Market
Video Surveillance Systems
Global Video Surveillance Systems Market
Video Surveillance Systems
Italy Video Surveillance Market
Video Surveillance Systems
Japan Video Surveillance Market
Video Surveillance Systems
Japan Surveillance Analog Camera Market
Video Surveillance Systems
United States Surveillance Analog Camera Market
Video Surveillance Systems
Europe Surveillance Camera Market
Video Surveillance Systems
Night Vision Outdoor Camera Market
Video Surveillance Systems
Canada Surveillance IP Camera Market
Video Surveillance Systems
China Surveillance Storage Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Systems Market
Video Surveillance Systems
Wireless Security Camera Market
Video Surveillance Systems
People Counting System Market