
 Night Vision Outdoor Camera Market | 2026-2036
Night Vision Outdoor Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Night Vision Outdoor Camera Market Analytics
E-commerce and direct-to-installer channels is rewriting how night vision outdoor cameras reach end users. Hikvision leverages its vertically integrated manufacturing to dominate bulk municipal procurement across Asia. Dahua Technology anchors its position through deep R&D investment in dual-spectrum fusion algorithms. Axis Communications specializes in open-platform architectures that appeal to enterprise security integrators in Europe and North America.
Night vision outdoor cameras are electro-optical devices that amplify ambient light or detect infrared radiation to render visible images in near-total darkness, typically operating across wavelengths from 700 nanometers to 14 micrometers depending on sensor technology. These systems serve perimeter surveillance, threat detection, and situational awareness for facilities requiring continuous monitoring regardless of illumination conditions. Wireless camera configurations are capturing the fastest expansion as battery and solar power integration reduces trenching costs for remote deployments. Thermal imaging technology commands premium positioning where absolute darkness or camouflage defeat conventional infrared illumination, while low-light sensors retain volume leadership in cost-sensitive residential and small commercial segments.
The FCC regulates radio frequency emissions from wireless camera systems under Part 15 rules, constraining transmission power and frequency allocation for unlicensed outdoor operation. The EU AI Act imposes algorithmic transparency requirements on cameras with embedded analytics, affecting how European vendors design edge-processing architectures. Stakeholders must monitor evolving cybersecurity certification mandates from NIST and ETSI, as networked outdoor cameras face escalating firmware integrity requirements that will separate compliant suppliers from excluded market participants.
Market Dynamics
Wireless transmission architectures are fragmenting procurement patterns as the FCC's Part 15 rules force redesigns of unlicensed radio frequency modules, while thermal-enabled units capture municipal budgets across smart city corridors in Singapore, Dubai, and Barcelona.
Growth Catalysts
- Smart city infrastructure mandates:Singapore, Dubai, and Barcelona are accelerating thermal-enabled camera procurement for perimeter surveillance, creating concentrated demand pipelines for dual-spectrum systems.
- FCC Part 15 compliance pathways:The unlicensed radio frequency rules are forcing architectural standardization that reduces certification costs for wireless outdoor deployments.
- Critical facility hardening:Energy and transportation facilities across Germany, Japan, and the United Arab Emirates are mandating continuous darkness-capable monitoring regardless of illumination conditions.
Market Restraints
- Sensor supply concentration:Advanced low-light and thermal sensor fabrication concentrates among a handful of Asian foundries, exposing procurement to single-source fragility.
- EU AI Act algorithmic transparency:The European Union's embedded analytics disclosure requirements impose compliance friction that slows edge-processing feature rollouts.
- Silicon germanium substrate volatility:Thermal imaging detector materials face price instability that compresses margin structures for mid-tier equipment vendors.
Strategic Opportunities
- Remote solar-battery integration:Wireless configurations with captive power are eliminating trenching costs for perimeter deployments in geographically dispersed critical infrastructure.
- NIST cybersecurity certification:The firmware integrity mandates are creating a compliance wedge that separates certified suppliers from excluded market participants.
- Dual-spectrum fusion algorithms:Convergence of thermal detection with low-light amplification is opening premium positioning for facilities requiring absolute darkness penetration.
Industry Challenges
- ETSI cybersecurity timeline compression:The European Telecommunications Standards Institute's networked device certification requirements are forcing accelerated firmware validation cycles that strain engineering bandwidth.
- Legacy analog integration friction:Hybrid deployments combining IP night vision with existing coaxial infrastructure create protocol translation complexity that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Night Vision Outdoor Camera Market |
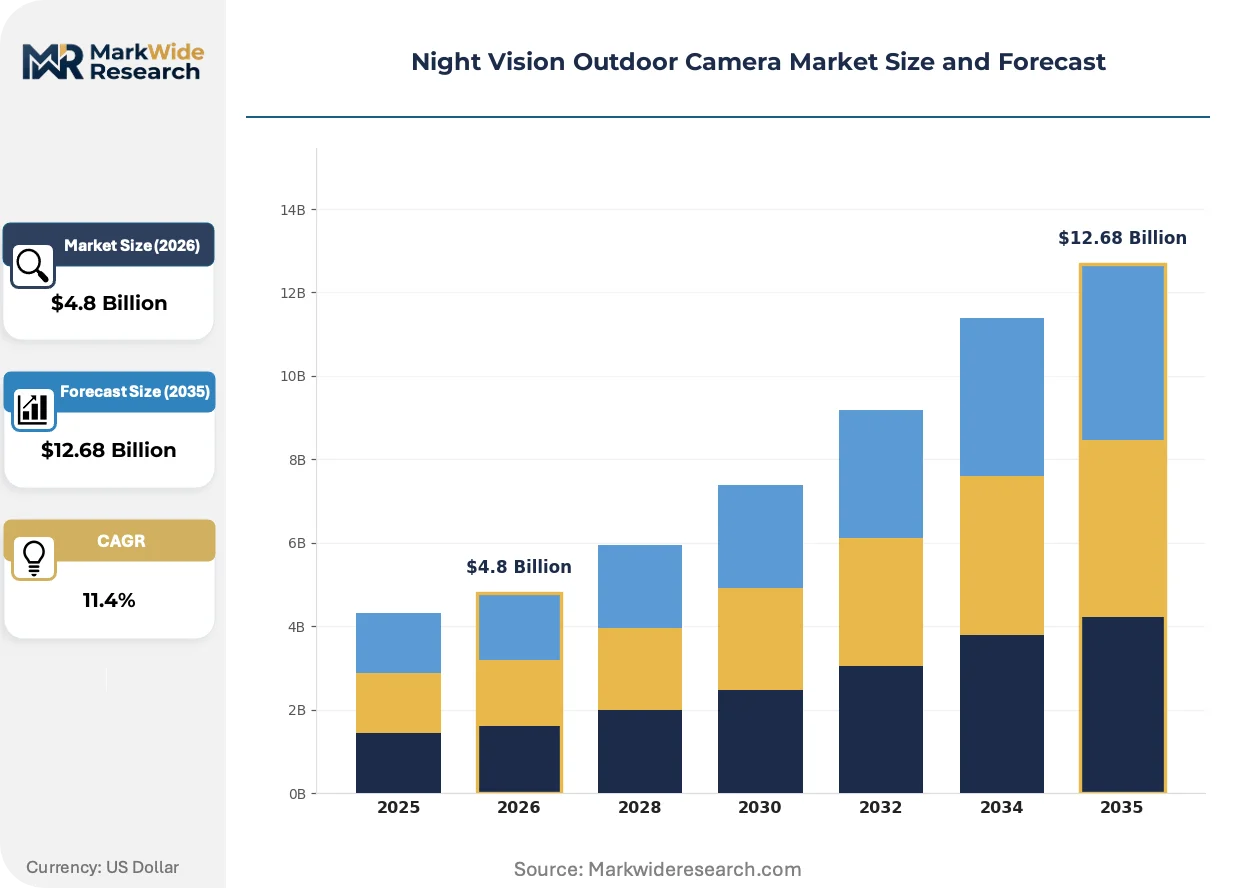
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Cameras, Wireless Cameras, Bullet Cameras, Dome Cameras Technology: Infrared, Thermal Imaging, Low-Light, Optical End User: Residential, Commercial, Government, Industrial Installation: Permanent, Temporary, Pole-Mounted, Wall-Mounted |
| Companies Covered | Hikvision, Dahua Technology, Axis Communications, Teledyne FLIR, Bosch Security Systems, Lorex Technology, Hanwha Techwin, Arlo, Uniview, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Night Vision Outdoor Camera Market Evolving Landscape
Edge-processing architectures are rewriting how video analytics execute, with regulatory pressure and channel disintermediation converging to compress traditional hardware-centric business models.
Multi-spectral sensor fusion is virtualizing the traditional divide between thermal and low-light imaging. Critical energy facilities in Germany and the United Arab Emirates are adopting unified detection platforms that eliminate redundant camera installations. The technology is virtualizing procurement decisions by collapsing separate thermal and infrared budget lines into single capital allocations.
The EU AI Act is imposing algorithmic transparency mandates on cameras with embedded person-detection or behavior-classification capabilities. European vendors are redesigning edge-processing architectures to document decision pathways for audit trails. Enterprise security integrators in Germany and France are prioritizing open-platform systems that permit third-party verification of inference logic.
Direct-to-installer channels are displacing traditional distributor hierarchies for mid-volume commercial deployments. Municipal procurement offices in Singapore and Barcelona are establishing direct vendor relationships that bypass regional security equipment wholesalers. This pattern concentrates most visibly in smart city infrastructure projects where specification standardization permits centralized bulk purchasing.
Night Vision Outdoor Camera Market Segmentation
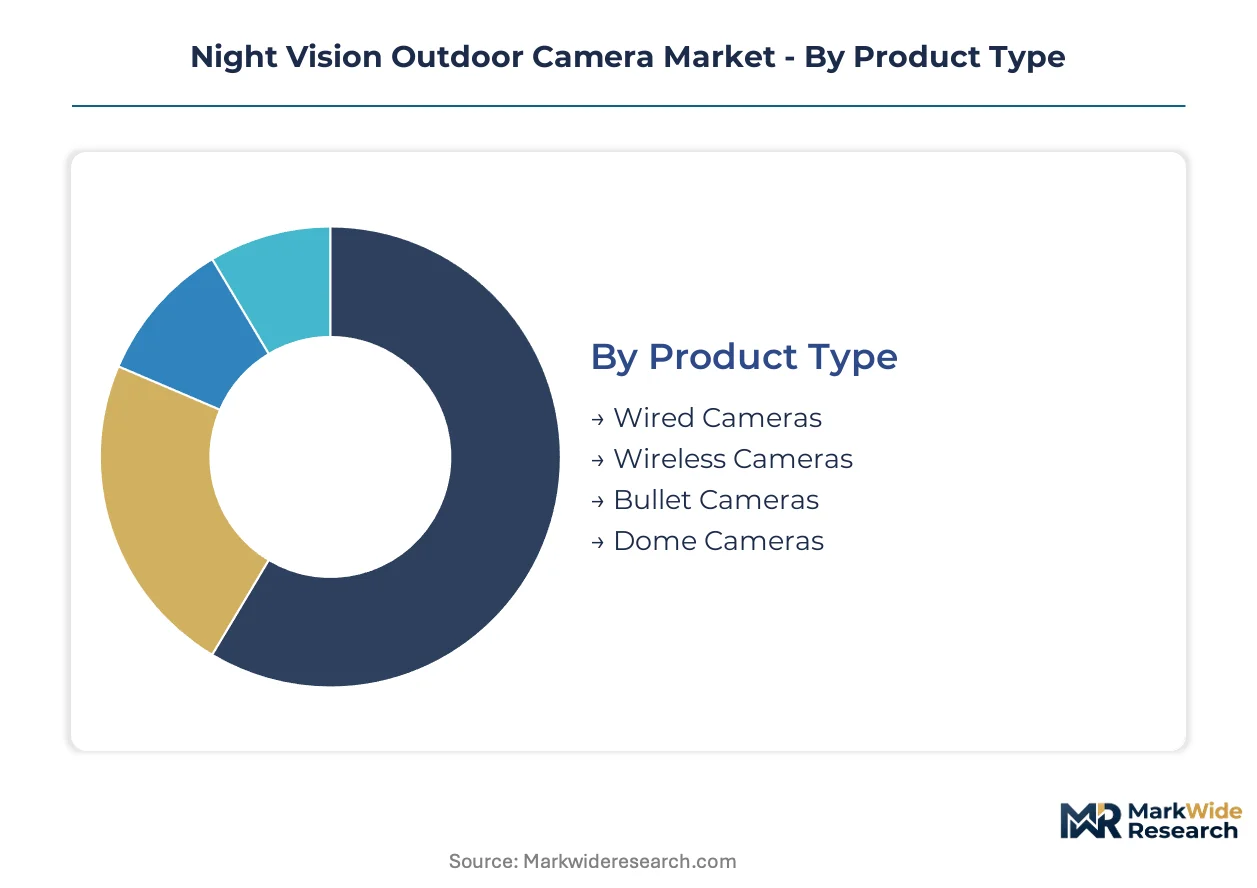
Segmentation in night vision outdoor cameras reveals how procurement priorities diverge across infrastructure types and operational constraints. Each dimension exposes distinct margin structures, installation complexity, and regulatory exposure that reshape vendor positioning.
Product Type:
After-sales service intensity varies sharply across form factors, with wireless configurations demanding firmware update subscriptions and battery replacement logistics that wired installations avoid entirely.
- Wired Cameras:Copper or fiber-connected systems deliver uninterrupted power and data transmission for facilities with established infrastructure. Critical energy installations across Germany and Japan specify these for perimeter hardening where signal continuity is non-negotiable.
- Wireless Cameras:Battery and solar-integrated units eliminate trenching costs for remote deployments. Singapore's smart city corridors are procuring these aggressively for geographically dispersed monitoring points where grid connection is prohibitively expensive.
- Bullet Cameras:Cylindrical housings with weather-sealed casings suit exposed outdoor mounting. These dominate residential perimeter applications where cost sensitivity limits specification complexity.
- Dome Cameras:Vandal-resistant enclosures with 360-degree coverage capability. Transportation facilities in the United Arab Emirates favor these for passenger zone monitoring requiring tamper-proof positioning.
Wired cameras hold the largest share; momentum sits with wireless configurations.
Technology:
Technology selection drives sensor supply chain exposure and algorithmic compliance burdens differently across the four approaches.
- Infrared:Active near-infrared illumination systems using LED arrays at 850nm or 940nm wavelengths. Residential and small commercial segments in cost-sensitive markets rely on these for basic darkness penetration where thermal premiums are unjustified.
- Thermal Imaging:Passive long-wave infrared detection measuring emitted radiation rather than reflected light. Critical infrastructure operators in Dubai and Barcelona are specifying these for absolute darkness and camouflage-defeating surveillance.
- Low-Light:Starlight and super-starlight sensors amplifying minimal ambient illumination without active emission. These retain volume leadership across municipal procurement in Singapore where street lighting provides residual photon availability.
- Optical:Conventional visible-spectrum imaging dependent on supplemental lighting infrastructure. Legacy industrial facilities with existing high-mast lighting continue deploying these for cost containment.
Low-Light sensors dominate procurement volume; thermal imaging commands the steepest expansion trajectory.
End User:
End user type determines cybersecurity certification stringency and procurement channel access, with government and industrial segments imposing validation requirements that exclude uncertified vendors.
- Residential:Single-family and multi-unit dwellings prioritizing DIY installation and cloud subscription economics. Direct-to-installer channels are capturing this segment through e-commerce platforms that bypass traditional security distributors.
- Commercial:Retail, hospitality, and office facilities requiring liability-grade documentation. These buyers balance performance against insurance underwriting requirements that mandate minimum resolution and retention standards.
- Government:Municipal, federal, and defense installations with classified or sensitive zone protection. FCC Part 15 compliance and NIST cybersecurity certification are mandatory gatekeepers for vendor participation.
- Industrial:Manufacturing, energy, and transportation facilities with hazardous environment specifications. Germany's critical energy infrastructure mandates continuous darkness-capable monitoring regardless of illumination conditions.
Government procurement holds the largest installed base; industrial applications are climbing the fastest.
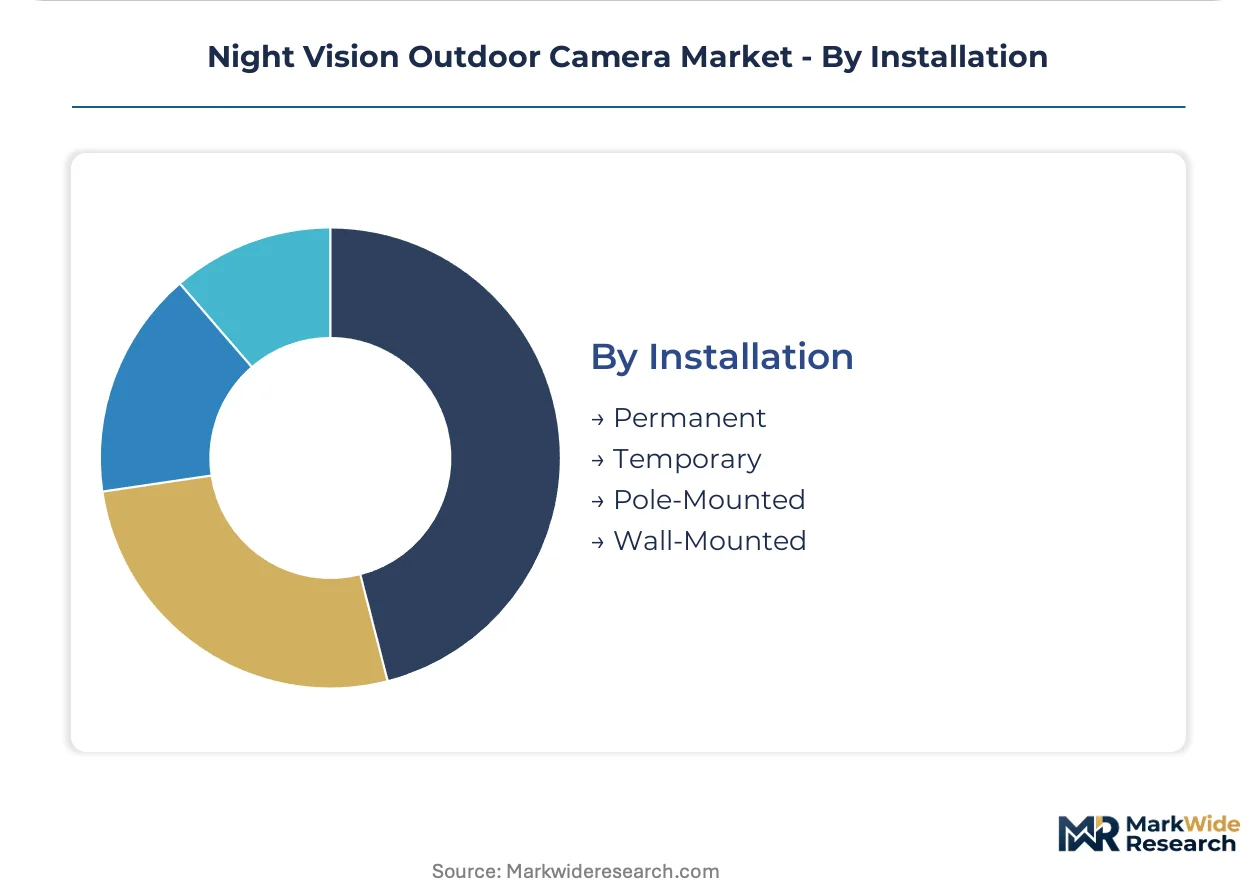
Installation:
Installation method constrains deployment velocity and labor cost structure, with temporary and pole-mounted configurations enabling rapid response to evolving threat landscapes.
- Permanent:Fixed infrastructure with embedded conduit and structural integration. These dominate greenfield critical facility construction where camera positioning is architecturally specified.
- Temporary:Rapid-deploy units for event security, construction phases, or emergency response. Barcelona's smart city pilots use these for festival perimeter management and infrastructure testing.
- Pole-Mounted:Elevated positioning on existing utility or dedicated masts for wide-area coverage. Transportation corridors across Japan specify these for roadway and rail monitoring.
- Wall-Mounted:Building-integrated attachment at entry points and facade perimeters. Commercial and residential segments favor these for constrained sites lacking pole infrastructure.
Permanent installations retain the largest share; temporary configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC's Part 15 rules for unlicensed radio frequency devices anchor procurement patterns in the United States, while municipal infrastructure investments in Singapore, Dubai, and Barcelona concentrate demand for thermal-enabled surveillance systems across three continents.
United States
Critical energy facilities and transportation hubs drive procurement of darkness-capable monitoring systems. The FCC's Part 15 compliance pathways are forcing architectural standardization for wireless transmission modules. Texas and California industrial corridors are deploying solar-battery integrated units for remote perimeter hardening.
Germany
Industrial automation mandates and critical infrastructure protection requirements accelerate specification of continuous monitoring systems. The EU AI Act imposes algorithmic transparency requirements on embedded analytics architectures. The Ruhr industrial basin and Bavarian manufacturing zones are procuring dual-spectrum fusion systems for absolute darkness penetration.
Japan
Railway and roadway monitoring specifications demand elevated pole-mounted configurations with signal continuity guarantees. METI guidelines influence cybersecurity certification requirements for networked outdoor cameras. Tokyo-Osaka transportation corridors are standardizing on low-light sensors with residual photon amplification.
Singapore
Smart city infrastructure mandates are accelerating thermal-enabled camera procurement for geographically dispersed monitoring points. The country's national telecommunications regulator shapes wireless spectrum allocation for municipal deployments. Marina Bay and Jurong Lake District pilots are establishing direct vendor relationships that bypass regional security equipment wholesalers.
United Arab Emirates
Transportation facility hardening and passenger zone protection specifications favor vandal-resistant dome configurations. MOHAP and local infrastructure authorities coordinate procurement standards for critical facility surveillance. Dubai's smart city corridors are specifying thermal imaging systems for camouflage-defeating perimeter detection.
Night Vision Outdoor Camera Market Competitive Landscape
Vertically integrated manufacturers and open-platform specialists split the market into distinct procurement channels. The vendor base organizes around three strategic archetypes: bulk municipal suppliers, enterprise security integrators, and residential direct-to-installer brands. Consolidation pressures are intensifying as NIST cybersecurity certification requirements separate compliant suppliers from excluded participants. Dominant competitive moves include backward integration into sensor fabrication and strategic partnerships for dual-spectrum algorithm development.
Within the vertically integrated tier, Hikvision and Dahua Technology exemplify manufacturing-scale archetypes that dominate bulk procurement across Asian municipal corridors. Axis Communications occupies a position among open-platform specialists appealing to enterprise security integrators in Europe and North America. These three anchors represent contrasting approaches to regulatory compliance, channel architecture, and technology portfolio construction.
| Leading Market Players |
|---|
| Hikvision |
| Dahua Technology |
| Axis Communications |
| Teledyne FLIR |
| Bosch Security Systems |
| Lorex Technology |
| Hanwha Techwin |
| Arlo |
| Uniview |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor's container rate volatility feeds directly into landed cost spreads between Asian-manufactured thermal sensors and European-assembled finished units, compressing margin buffers for mid-tier vendors while amplifying pricing power among vertically integrated producers with captive fab capacity.
Pricing Analysis
The customization-premium spread separates configured-to-order municipal procurement from standard residential SKUs by a factor reflecting NIST cybersecurity certification overhead and dual-spectrum algorithm licensing. Three-tier pricing structure across premium, standard, and economy levels stratifies around thermal fusion capability, FCC Part 15 pre-certification status, and after-sales firmware subscription bundling. Pricing pressure stems from silicon germanium substrate cost instability in thermal detector fabrication, eroding margins for vendors without backward integration into sensor production. Government and industrial buyers exhibit lowest price sensitivity due to mandated compliance thresholds, while residential segments drive volume through cost-optimized infrared illumination systems.
Supply Chain Analysis
Upstream feedstock concentration in indium antimonide and vanadium oxide microbolometer materials centers on Japanese and Chinese specialty chemical producers, with germanium lens substrates drawing from refined output in Germany and Russia. Advanced CMOS fabrication for low-light sensors rests on Taiwanese and South Korean foundry capacity, while thermal core assembly concentrates in Chinese and Vietnamese contract manufacturing. Single-source vulnerability in uncooled microbolometer die supply exposes procurement timelines to foundry allocation decisions. Distribution runs through direct municipal contracting in Singapore and Dubai, enterprise security integrators in Germany, and e-commerce platforms penetrating residential North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The night vision outdoor camera market is recovering from cyclical inventory destocking in municipal procurement channels, with smart city infrastructure budget resets in Singapore and Barcelona providing the demand inflection.
For Market Incumbents: Pre-empt margin compression in mid-tier thermal imaging by accelerating backward integration into microbolometer fabrication and securing long-term indium antimonide supply agreements with Japanese chemical suppliers. Lock in NIST cybersecurity certification ahead of ETSI timeline compression to exclude uncertified competitors from German and UAE industrial tenders. For New Entrants and Emerging Players: Build out white-space presence in temporary rapid-deploy configurations for event security and construction-phase monitoring, where Barcelona's festival infrastructure pilots demonstrate unmet demand. Target solar-battery integrated wireless units for remote critical infrastructure in Texas and California industrial corridors, leveraging direct-to-installer channel bypass of traditional security distributors. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate industrial electronics parents seeking to divest non-core security hardware divisions ahead of EU AI Act compliance cost recognition. Position acquisitions around five-to-ten year visibility in smart city infrastructure replacement cycles. Monitor FCC Part 15 certification backlogs as inflection signal for vendor capacity constraints and pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Spectrum Algorithm Development | Enables premium positioning for Dubai and Barcelona perimeter hardening tenders requiring absolute darkness penetration. |
| NIST Cybersecurity Certification | Creates compliance wedge separating approved vendors from excluded participants in US government procurement. |
| Solar-Battery Integration Partnership | Eliminates trenching costs for remote deployments across Texas and California critical infrastructure corridors. |
| Direct Municipal Contracting | Bypasses distributor markup in Singapore and Barcelona smart city bulk procurement standardization. |
| Microbolometer Backward Integration | Reduces silicon germanium substrate price exposure compressing mid-tier thermal imaging margins. |
Research Methodology
Cross-validation between primary interviews with municipal procurement officers, enterprise security integrators, thermal sensor fabrication engineers, and FCC certification consultants anchors the qualitative findings against secondary validation from FCC Part 15 equipment authorization databases, ETSI cybersecurity standard drafts, smart city infrastructure tender documents in Singapore and Barcelona, and SEC filings from vertically integrated camera manufacturers. Bottom-up unit shipment estimates triangulate against top-down infrastructure budget allocations across critical energy and transportation facilities.
Calibration against historical procurement cycles in German industrial automation and Japanese railway monitoring establishes baseline elasticity assumptions across the projection horizon. Segmentation dimensions modeled include product architecture, sensor technology type, end-user compliance tier, installation permanence, and regional regulatory cluster. CAGRs derive from installed base replacement velocity, smart city infrastructure pipeline conversion rates, and technology substitution patterns between thermal and low-light systems. Forecast inputs incorporate silicon germanium spot price trajectories and municipal bond issuance trends for public surveillance capital expenditure.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese vertically integrated manufacturers or unexpected FCC spectrum reallocation would shift outcomes beyond modeled ranges. Cross-checking against customs shipment data from Taiwanese CMOS foundries and German thermal core exporters is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Canada Surveillance Camera Market
Video Surveillance Systems
Hosted Video Surveillance Market
Video Surveillance Systems
Connected Enterprise Video Surveillance Solutions Market
Video Surveillance Systems
Smart Outdoor Cameras Market
Video Surveillance Systems
AI in Video Surveillance Market
Video Surveillance Systems
Europe Video Surveillance As a Service Market
Video Surveillance Systems
United States Surveillance Camera Market
Video Surveillance Systems
United Kingdom Video Surveillance Market
Video Surveillance Systems
Asia-Pacific Surveillance Camera Market
Video Surveillance Systems
Aircraft Video Surveillance Systems Market
Video Surveillance Systems
Camera Alarm System Market
Video Surveillance Systems
Asia-Pacific Surveillance Storage Market
Video Surveillance Systems
Middle East and Africa Surveillance IP Cameras Market
Video Surveillance Systems
Global CCTV Market
Video Surveillance Systems
Video Surveillance Market
Video Surveillance Systems
China Video Surveillance Market