
 Europe Wireless Broadband in Public Safety Market | 2026-2036
Europe Wireless Broadband in Public Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wireless Broadband in Public Safety Market Insights
The capital-intensity gap between spectrum-owning infrastructure vendors and software-centric equipment suppliers is bifurcating competitive tiers in Europe's public safety broadband sector. Nokia Corporation leverages its end-to-end 5G portfolio to anchor large-scale national deployments for first responder networks. Motorola Solutions sustains its position through specialized mission-critical voice-to-data migration solutions. Cisco Systems competes by extending enterprise-grade security architectures into hardened public safety edge environments.
Wireless broadband in public safety denotes dedicated high-capacity data networks operating across licensed LTE, 5G NR, and satellite frequencies to deliver real-time video, geolocation, and interoperable messaging for emergency response coordination. These systems require sub-50 millisecond latency, AES-256 encryption, and 99.999% availability to support command-center dispatch and field-unit synchronization during multi-agency incidents. LTE technology dominates current infrastructure refresh cycles as agencies phase out circuit-switched TETRA investments. The End User dimension shows police departments generating the largest procurement volumes, while Emergency Medical Services represents the fastest-growing adoption segment due to telemedicine and ambulance telemetry integration. Hybrid deployment models are capturing expanding margin pools by combining sovereign core networks with commercial radio access layer sharing.
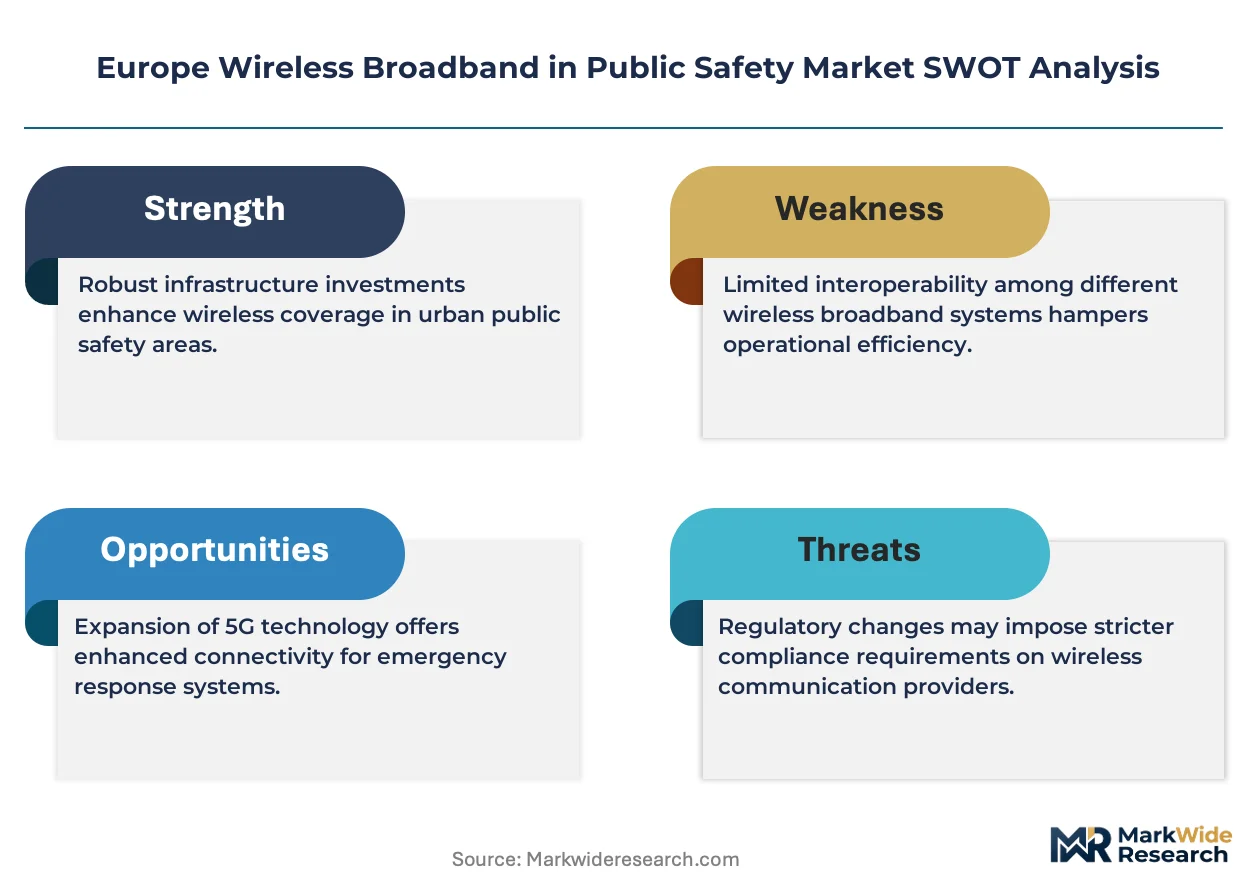
The European Union Agency for Cybersecurity (ENISA) mandates certification under the Cybersecurity Act for critical communications infrastructure, directly shaping vendor qualification timelines and procurement specifications. The European Electronic Communications Code harmonizes spectrum allocation for public protection and disaster relief across member states, reducing cross-border interoperability barriers. REACH and RoHS compliance requirements constrain hardware material selections for ruggedized field equipment. Stakeholders must monitor the EU's proposed Critical Entities Resilience Directive for expanded operator obligations and funding mechanisms.
Market Dynamics
The migration from circuit-switched TETRA to packet-based LTE and 5G NR is decomposing legacy procurement patterns across European public safety agencies, forcing infrastructure decisions that must simultaneously satisfy national sovereignty requirements and cross-border interoperability mandates under the European Electronic Communications Code.
Growth Catalysts
- EU Cybersecurity Act mandates:ENISA certification requirements for critical infrastructure communications are accelerating vendor qualification standards and locking in compliant suppliers for multi-year national deployments.
- Nordic system modernization:Sweden, Norway, and Finland are retiring legacy TETRA investments in favor of broadband-capable networks supporting real-time video and telemedicine applications for emergency medical services.
- 5G NR mission-critical slicing:Network slicing technology enables dedicated bandwidth allocation for first responders on shared commercial infrastructure, reducing sovereign network build-out costs.
Market Restraints
- Spectrum scarcity and auction costs:Licensed 700 MHz and 3.5 GHz bands command premium reserve prices in national auctions, compressing capital available for core network deployment.
- Vendor concentration in radio access equipment:European public safety agencies depend heavily on a narrow base of infrastructure suppliers capable of delivering hardened, sub-50 millisecond latency equipment.
- REACH and RoHS material constraints:Hazardous substance restrictions limit component sourcing for ruggedized field devices, extending hardware qualification timelines.
Strategic Opportunities
- Eastern European greenfield deployments:Poland and Romania lack legacy TETRA lock-in, enabling direct-to-5G network architectures without voice-to-data migration complexity.
- Hybrid commercial-sovereign models:Network sharing agreements with mobile operators allow police forces to offload radio access layer costs while retaining encrypted core control.
- EU Critical Entities Resilience Directive:Proposed funding mechanisms and expanded operator obligations will channel public investment toward hardened backup power and satellite failover capabilities.
Industry Challenges
- Mission-critical voice interoperability:LTE broadband networks must replicate TETRA's instant group call functionality, requiring complex codec standardization across multi-vendor environments.
- Cybersecurity certification bottlenecks:ENISA's Common Criteria evaluation timelines stretch 18-24 months, delaying procurement schedules for agencies with fixed budget cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wireless Broadband in Public Safety Market |
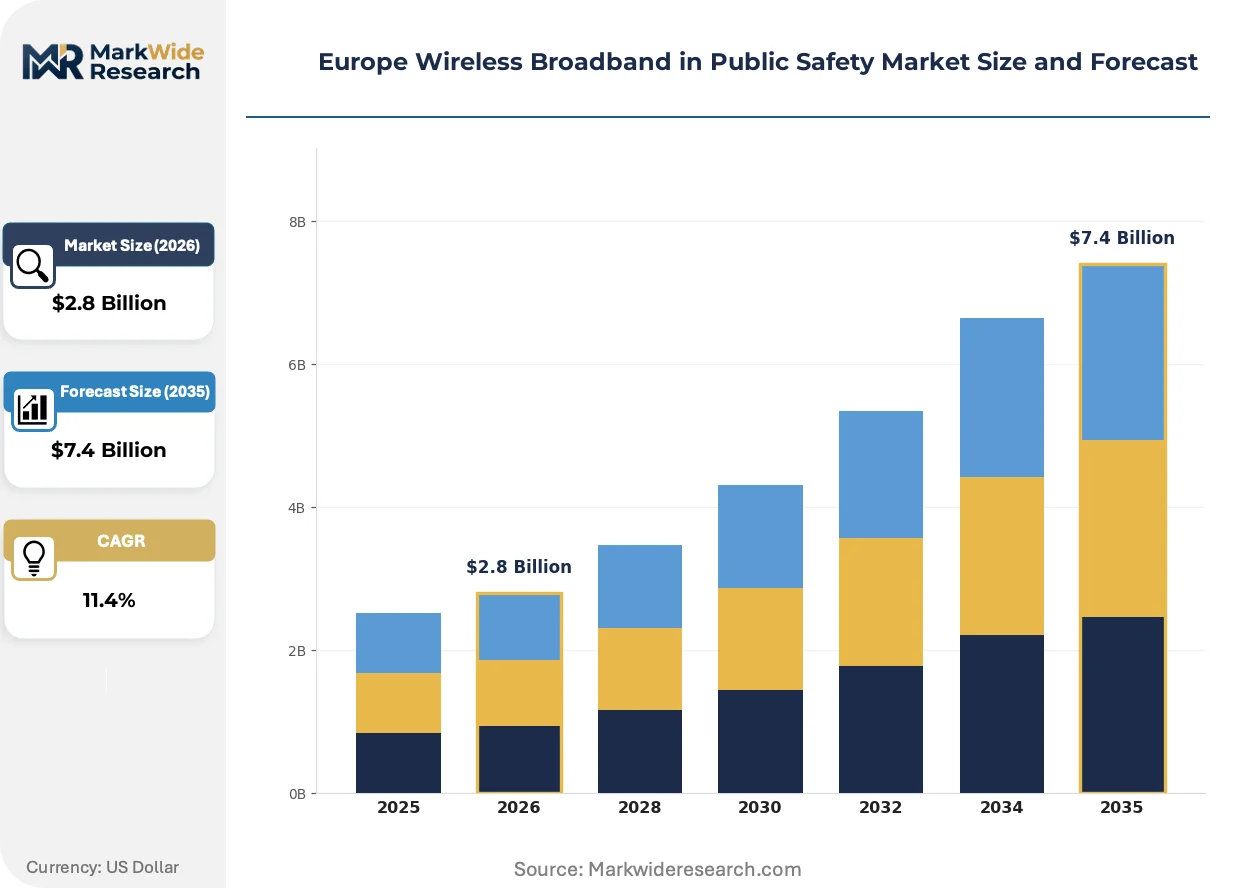
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LTE, 5G, Wi-Fi, Satellite End User: Police, Fire Departments, Emergency Medical Services, Security Agencies Application: Disaster Management, Surveillance, Communication, Coordination Deployment Model: Public, Private, Hybrid, Community |
| Companies Covered | Telefonaktiebolaget LM Ericsson, Nokia Corporation, Motorola Solutions, Cisco Systems, Airbus Defence and Space, Huawei Technologies, Juniper Networks, Extreme Networks, Aruba Networks, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wireless Broadband in Public Safety Market Trends and Innovations
European public safety broadband is pivoting from proprietary network silos toward modular, standards-based architectures. This shift is compressing equipment replacement cycles and redistributing value capture across the technology stack.
Software-defined radio (SDR) platforms are decomposing traditional hardware-centric procurement by separating physical layer functions from application logic. German federal police and French Gendarmerie are trialing SDR-enabled devices that reconfigure via over-the-air updates. This technology is decomposing vendor lock-in and enabling multi-network roaming across TETRA, LTE, and satellite constellations.
The EU's proposed Critical Entities Resilience Directive is mandating redundant connectivity paths and minimum service continuity standards for public safety operators. Industrial consequence includes mandatory satellite backup integration and hardened edge computing nodes. Nordic agencies are responding fastest, embedding resilience requirements into current tender specifications ahead of formal adoption.
Consolidated framework agreements are displacing single-vendor procurement across British and Dutch emergency services. Purchasing cooperatives aggregate demand across police, fire, and ambulance trusts, extracting volume pricing and standardized service level terms. This concentration is most visible in the Netherlands, where the national public safety communication authority negotiates centralized infrastructure contracts on behalf of regional forces.
Europe Wireless Broadband in Public Safety Market Segmentation
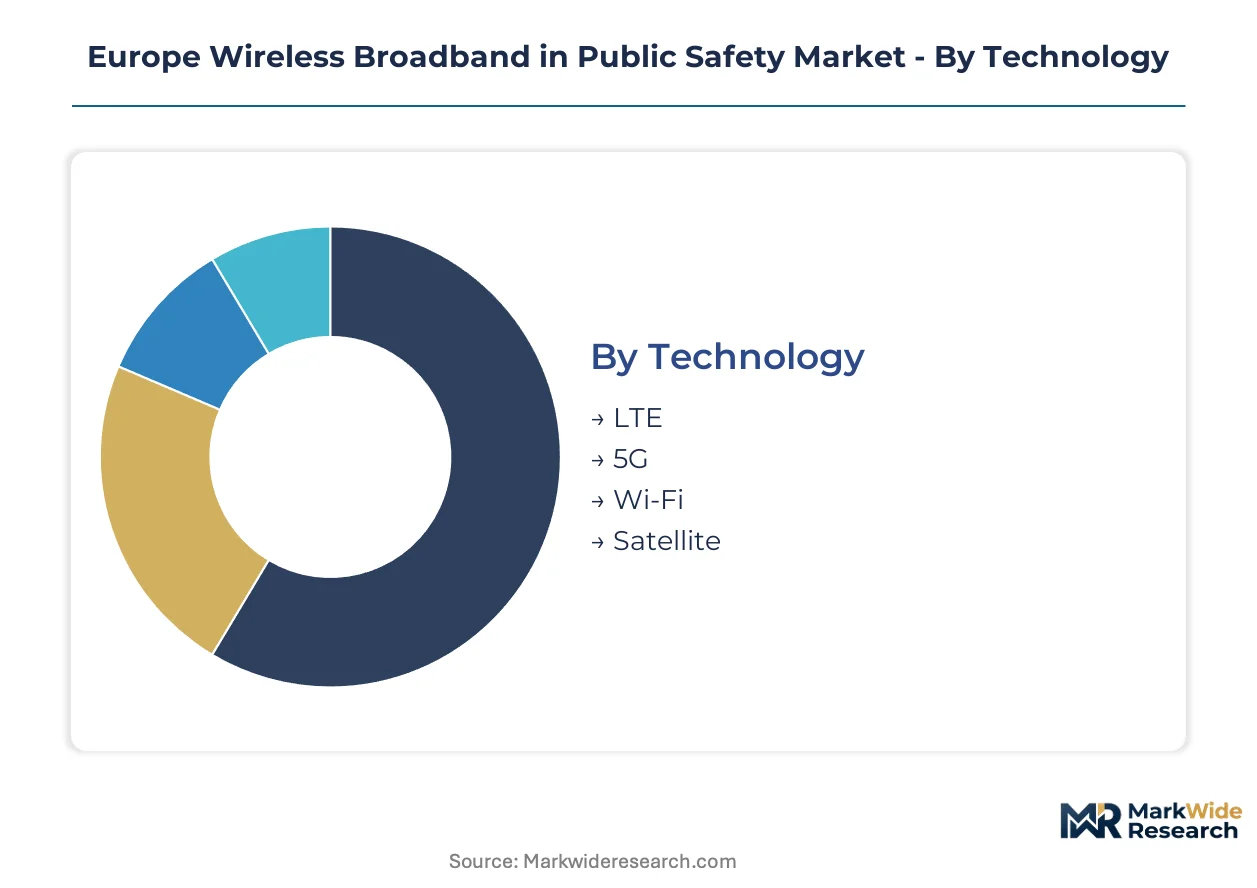
Segmentation in Europe's public safety broadband market reveals how procurement priorities diverge across agencies with varying legacy infrastructure burdens and mission-critical requirements. Understanding these divisions exposes where substitution pressures and modernization budgets concentrate.
Technology:
LTE equipment faces intensifying substitution pressure as 5G NR slicing capabilities mature and satellite constellations achieve commercial reliability for emergency failover.
- LTE:Packet-based infrastructure delivering sub-50 millisecond latency across licensed 700 MHz bands. Police forces in Germany and France anchor current procurement volumes as they phase out circuit-switched TETRA systems, constrained by ENISA certification timelines for mission-critical voice replication.
- 5G:New Radio architectures enabling network slicing for dedicated first responder bandwidth. Nordic agencies in Sweden and Norway are deploying 5G-first strategies, bypassing LTE transition costs entirely through direct-to-broadband tenders.
- Wi-Fi:Unlicensed spectrum solutions for command-center and temporary incident perimeters. British emergency services integrate hardened Wi-Fi 6E for indoor facility coverage where cellular penetration fails.
- Satellite:Geostationary and LEO constellations providing backup connectivity for rural disaster zones. The EU Critical Entities Resilience Directive is accelerating mandatory satellite integration into Dutch and Finnish tender specifications.
LTE retains volume leadership; 5G holds the steepest expansion curve.
End User:
Cost tier differentiation separates agencies with sovereign network mandates from those accepting commercial infrastructure sharing.
- Police:Largest procurement volumes driven by real-time video streaming, biometric identification, and encrypted group communications. French Gendarmerie and German federal police command multi-billion-euro national network contracts with end-to-end encryption requirements.
- Fire Departments:Specialized need for thermal imaging data transmission and building penetration in subterranean environments. Austrian and Swiss fire services prioritize ruggedized equipment with extended battery life for prolonged incident duration.
- Emergency Medical Services:Telemedicine and ambulance telemetry integration are expanding fastest. Finnish and Danish EMS agencies lead ambulance-to-hospital video consultation deployments over broadband networks.
- Security Agencies:Counter-terrorism and critical infrastructure protection units with enhanced cybersecurity tiers. Belgian and Dutch security services mandate sovereign core networks with zero commercial operator access.
Police retain volume leadership; Emergency Medical Services holds the steepest expansion curve.
Application:
Application maturity correlates directly with regulatory mandate strength across member states.
- Disaster Management:Multi-agency coordination requiring cross-border interoperability under the European Electronic Communications Code. Italian and Greek civil protection agencies prioritize satellite backup and mesh networking for earthquake and wildfire response.
- Surveillance:High-definition video streaming from body-worn cameras and drone feeds. Spanish and Portuguese police forces are scaling centralized video evidence platforms with cloud storage integration.
- Communication:Mission-critical voice and data services replacing legacy TETRA group calls. British emergency services struggle with codec standardization across multi-vendor LTE environments.
- Coordination:Geolocation and resource dispatch optimization. Polish and Romanian agencies deploy greenfield coordination platforms without legacy system migration constraints.
Communication retains volume leadership; Disaster Management holds the steepest expansion curve.
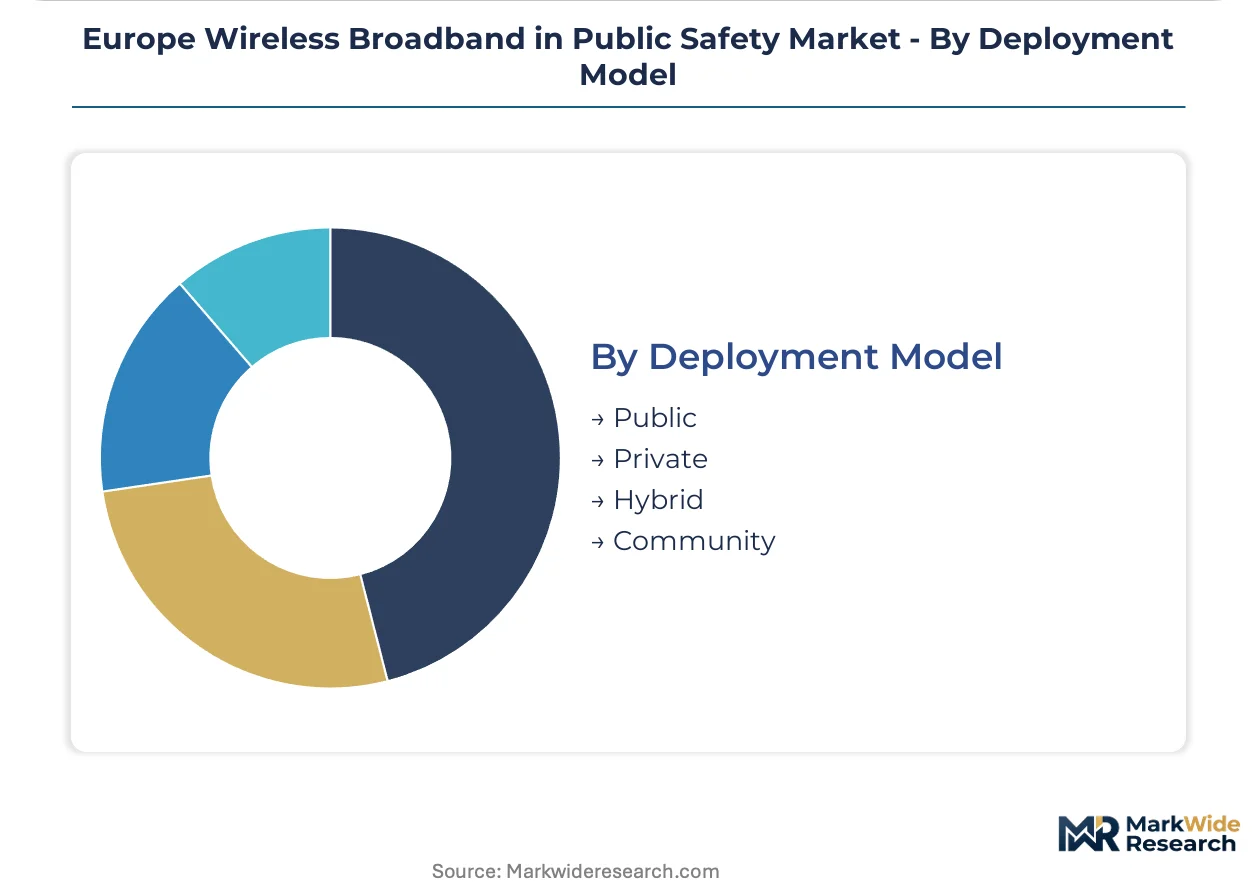
Deployment Model:
Supply concentration in radio access equipment favors hybrid architectures that blend sovereign control with commercial cost efficiency.
- Public:Commercial mobile operator networks with priority access agreements. French police forces negotiate roaming contracts with Orange and SFR for rural coverage extension.
- Private:Wholly owned infrastructure satisfying national sovereignty requirements. German federal structures mandate private cores with encrypted local breakout points.
- Hybrid:Sovereign core networks with shared radio access layer. Dutch national public safety communication authority consolidates demand across regional forces into centralized hybrid tenders with KPN and VodafoneZiggo.
- Community:Localized networks for isolated municipalities or critical facility clusters. Alpine regions in Austria and Switzerland deploy community models for mountain rescue coordination where commercial coverage gaps persist.
Hybrid retains volume leadership; Community holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany's sovereign network tenders exceeds that in Poland's commercial-sharing arrangements by substantial margins, reflecting divergent national security mandates across the continent.
Germany
The German federal police and Gendarmerie command multi-billion-euro national broadband contracts with end-to-end encryption requirements. The Cybersecurity Act mandates ENISA certification for all critical infrastructure communications equipment. Bavaria anchors procurement concentration, with Munich-based system integrators coordinating large-scale LTE-to-5G migration timelines.
France
French emergency services prioritize real-time video streaming and biometric identification platforms for urban policing. The ANSSI national cybersecurity agency enforces supplementary certification layers beyond baseline EU requirements. The Paris-Île-de-France corridor concentrates vendor qualification facilities and interoperability testing laboratories.
Sweden
Swedish agencies are retiring legacy TETRA investments in favor of direct-to-5G architectures without intermediate LTE transition costs. The Swedish Post and Telecom Authority harmonizes spectrum allocation with neighboring Nordic regulators. Stockholm hosts regional headquarters for infrastructure vendors serving the broader Scandinavian modernization wave.
Netherlands
Dutch emergency services aggregate demand through centralized purchasing cooperatives covering police, fire, and ambulance trusts. The national public safety communication authority negotiates hybrid deployment contracts with commercial operators. The Randstad conurbation concentrates command-center infrastructure and network operations centers.
Poland
Polish public safety agencies deploy greenfield broadband networks without legacy voice-system migration constraints. The national regulator UKE allocates 700 MHz and 3.5 GHz bands for mission-critical services under harmonized EU frameworks. Warsaw anchors regional procurement coordination for Eastern European agencies seeking sovereign network architectures.
Europe Wireless Broadband in Public Safety Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Europe's public safety broadband sector. Infrastructure vendors with end-to spectrum portfolios dominate sovereign network tenders requiring hardened sub-50 millisecond latency equipment. Software-centric suppliers capture margin pools in security architecture and edge computing layers. The market structure bifurcates between integrated system providers and specialized component suppliers. Competitive moves concentrate on strategic partnerships for hybrid commercial-sovereign deployments and ENISA certification acceleration.
Within the integrated infrastructure tier, Telefonaktiebolaget LM Ericsson and Nokia Corporation exemplify the archetype of end-to-end 5G portfolio providers anchoring large-scale national deployments. Motorola Solutions occupies a position representing specialized mission-critical voice-to-data migration capabilities. These three entities sit within the vendor base qualified for multi-year framework agreements across German, French, and Nordic procurement channels.
| Leading Market Players |
|---|
| Telefonaktiebolaget LM Ericsson |
| Nokia Corporation |
| Motorola Solutions |
| Cisco Systems |
| Airbus Defence and Space |
| Huawei Technologies |
| Juniper Networks |
| Extreme Networks |
| Aruba Networks |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four-month ENISA certification lead times compress vendor qualification pipelines and amplify pricing power for pre-certified infrastructure suppliers across German and French sovereign network tenders. Inventory strategies favor strategic stockpiling of radio access equipment by Nordic agencies facing REACH and RoHS material constraints on ruggedized field devices.
Pricing Analysis
The customization-premium spread separates configured-to-order sovereign core networks from standard commercial radio access layer equipment. Project-based long-term contracting dominates procurement, with price differentiation hinging on ENISA certification tier and volume scale under national framework agreements. Cost compression in commercial-sharing tiers is intensifying because mobile operators absorb radio access layer build-out expenses. Municipal police forces exhibit highest price sensitivity; security agencies with zero-commercial-access mandates show least.
Supply Chain Analysis
Strategic stockpiling of hardened sub-50 millisecond latency equipment prevails over just-in-time approaches given certification bottlenecks and material restriction compliance timelines. Manufacturing concentrates in Finland, Sweden, and Germany for radio access network components. Supply chains draw from rare earth elements for power amplifiers, specialized substrates for antenna arrays, and AES-256 encryption chipsets. Single-source vulnerability in qualified radio frequency component suppliers poses structural risk. Distribution runs through national system integrators coordinating multi-agency framework deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. ENISA certification timelines and national sovereignty mandates create switching costs that lock agencies into multi-year supplier relationships.
For Market Incumbents: Fortify ENISA certification pipelines to accelerate qualification timelines ahead of competitor entry. Deepen backward integration into sovereign core network software stacks to defend margin position against software-centric challengers. Capacity expansion in Bavaria and Stockholm anchors regional service delivery for German and Nordic modernization waves.
For New Entrants and Emerging Players: ENISA certification fast-tracks through partnership with established testing laboratories in Paris-Île-de-France offer entry pathways. Eastern European greenfield deployments in Poland and Romania present most penetrable geography absent legacy TETRA migration complexity. Target ambulance telemetry and telemedicine integration as fastest-growing EMS segment with lower sovereign network mandates.
For Investors and Strategic Acquirers: Carve-out targets emerge from defense conglomerates with dormant public safety communication divisions. Long-term viability centers on suppliers capable of spanning TETRA-to-LTE-to-5G migration cycles without technology discontinuity. Monitor EU Critical Entities Resilience Directive adoption timelines as inflection indicator for satellite backup and edge resilience investment flows.
| Strategic Initiative | Industry Significance |
|---|---|
| ENISA Certification Acceleration | Shortens vendor qualification timelines and locks in multi-year national framework agreements. |
| Hybrid Commercial-Sovereign Deployment | Combines encrypted core control with Orange and KPN radio access cost efficiencies. |
| Software-Defined Radio Platform Launch | Enables German federal police and French Gendarmerie multi-network roaming across TETRA, LTE, and satellite. |
| Satellite Backup Integration | Satisfies Dutch and Finnish mandatory resilience requirements under proposed EU directive. |
| Purchasing Cooperative Consolidation | Aggregates British and Dutch police, fire, and ambulance demand for standardized service levels. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with network operations center directors, public safety procurement officers, ENISA certification specialists, and infrastructure vendor account managers; and secondary validation against European Electronic Communications Code harmonization documents, national regulatory filings with Bundesnetzagentur and ANSSI, and customs data on hardened equipment imports. Bottom-up and top-down triangulation cross-checked equipment shipment volumes against agency budget appropriations.
Across the analysis window, the forecasting framework modeled technology substitution curves, end-user procurement concentration, deployment model cost structures, and application maturity timelines. CAGRs derived from segmented adoption rate differentials between legacy TETRA replacement and greenfield 5G-first strategies. Spectrum auction timing and ENISA certification pipeline throughput served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained EU cybersecurity mandate enforcement and stable spectrum allocation harmonization; material deviation would warrant model refresh. Revision becomes warranted when ENISA evaluation timelines or Critical Entities Resilience Directive funding mechanisms cross threshold shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
Global Public Safety and Security Market
Public Safety
Public Safety LTE Market
Public Safety
Global IoT for Public Safety Market
Public Safety
Outdoor Public Safety Market
Public Safety
Public Safety Market
Public Safety
Global Public Safety in Building Wireless Das System Market
Public Safety
Voice Evacuation Systems Market
Public Safety
Latin America Public Safety Market
Public Safety
Counter Terror and Public Safety Technology Market
Public Safety
Europe Road Safety Market
Public Safety
Public Safety in-Building Wireless Distributed Antenna System (DAS) Market
Public Safety
Crime Risk Report Market
Public Safety
Global Public Safety Solution Market
Public Safety
Europe Public Safety Market
Public Safety
North America Road Safety Market
Public Safety
LAMEA Wireless Broadband in Public Safety Market