
 Central Monitoring Station Market | 2026-2036
Central Monitoring Station Market Size, Share, and Industry Trends Forecast 2026-2036
Central Monitoring Station Market Outlook
UL 864 certification for control units and accessories is rotating as a primary gatekeeper for vendor eligibility in North American central monitoring deployments. GE Healthcare leverages its installed base of patient monitoring ecosystems to sustain recurring service contracts across integrated health networks. Philips Healthcare anchors its position through backward integration into sensor hardware and real-time data analytics platforms. Nihon Kohden competes on specialized neonatal and critical-care monitoring configurations that differentiate its central station architecture.
A central monitoring station aggregates multi-parameter physiological data from bedside devices, displaying real-time waveforms and alarm conditions across networked displays with latency thresholds typically below two seconds for critical alerts. Cloud-based systems are capturing the fastest expansion as hospitals prioritize scalable architectures that reduce on-premises infrastructure overhead. Healthcare facilities represent the dominant end-user segment, absorbing the majority of installed capacity, while IoT devices are emerging as the connectivity layer enabling seamless device integration across distributed care environments.
FDA 510(k) pathways govern premarket notification for central monitoring software and hardware, while HIPAA mandates encryption and access controls for patient data transmission across networked stations. The EU MDR imposes stricter clinical evidence requirements on patient-monitoring systems sold in European member states, lengthening approval timelines but raising barriers to entry. Stakeholders must monitor how evolving cybersecurity frameworks from NIST and IEC 80001 reshape product development priorities and post-market surveillance obligations.
Market Dynamics
Hospital consolidation across the United States is compressing procurement cycles and favoring vendors capable of enterprise-scale central monitoring deployments with unified service architectures.
Growth Catalysts
- HIPAA-mandated encryption standards:Healthcare facilities must upgrade legacy monitoring networks to meet federal data security requirements, creating replacement demand for compliant centralized architectures.
- Neonatal intensive care units:Specialized critical-care configurations are expanding installed bases in tertiary hospitals requiring multi-parameter physiological aggregation.
- Cloud-native architectures:Scalable infrastructure models reduce on-premises overhead and accelerate deployment timelines for integrated health networks.
Market Restraints
- Semiconductor supply concentration:Sensor chipset availability remains vulnerable to fabrication capacity constraints in East Asian foundry networks.
- FDA 510(k) pathway friction:Premarket notification timelines for Class II medical devices extend product validation cycles and defer revenue recognition.
- Wireless telemetry substitution:Point-of-care monitoring devices with standalone alarm capabilities reduce dependency on centralized station architectures in smaller facilities.
Strategic Opportunities
- EU MDR clinical evidence requirements:Stricter European approval protocols raise competitive barriers, creating first-mover advantages for vendors with established conformity assessment documentation.
- Home-based acute care:Remote patient monitoring extensions into residential settings open new addressable demand beyond traditional hospital deployments.
- Edge computing convergence with 5G:Low-latency connectivity enables real-time waveform transmission without dedicated bedside-to-station cabling infrastructure.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in IEC 80001 risk management for networked medical devices remains concentrated among experienced practitioners.
- Legacy system integration complexity:Heterogeneous device fleets from multiple manufacturers require proprietary middleware development for unified alarm management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Central Monitoring Station Market |
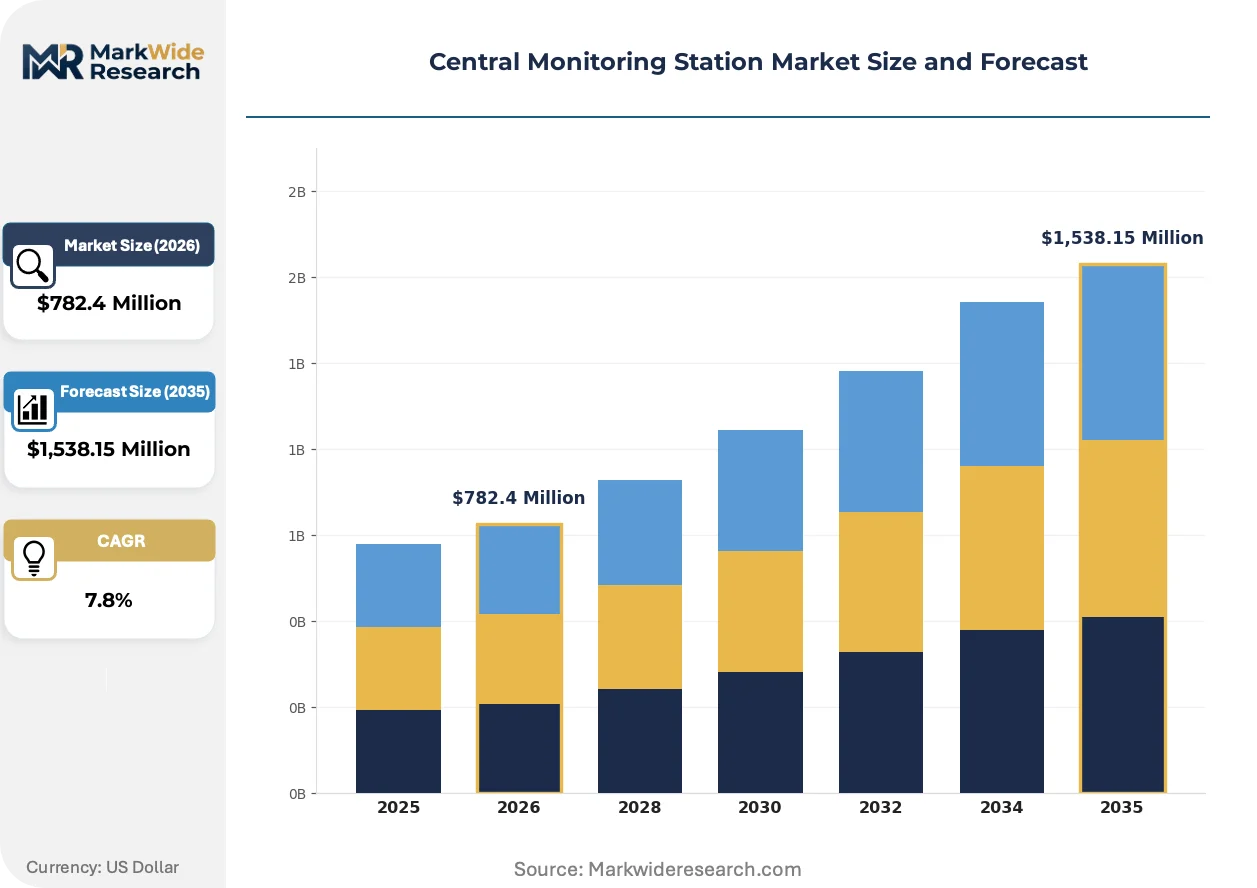
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $1,538.15 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Monitoring Services, Management Solutions, Emergency Response, Analysis Tools Technology: Cloud-Based Systems, On-Premises Solutions, IoT Devices, Data Analytics Platforms End User: Healthcare Facilities, Financial Institutions, Industrial Plants, Residential Buildings Installation: Remote Installation, On-Site Setup, Integrated Systems, Legacy Upgrades |
| Companies Covered | GE Healthcare, Philips Healthcare, Nihon Kohden, Cerner, Mediana, Criticare Systems, Lepu Medical Technology, Fukuda Denshi, MindRay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Central Monitoring Station Market Strategic Shifts
Real-time data analytics platforms are redefining how physiological signals transform into actionable clinical intelligence across distributed care environments.
Artificial intelligence inference engines are fragmenting traditional alarm management workflows by enabling predictive deterioration alerts before threshold breaches occur. Academic medical centers in the United States are piloting these algorithms in surgical recovery units. The technology is fragmenting vendor competitive positioning by shifting differentiation toward software-layer clinical decision support rather than hardware fidelity alone.
FDA cybersecurity guidance for networked medical devices is mandating software bill of materials disclosure and vulnerability management protocols throughout product lifecycles. Manufacturers must now embed security update capabilities into central monitoring architectures at design phase. Critical access hospitals with limited IT infrastructure face disproportionate compliance burdens relative to integrated delivery networks with dedicated security operations centers.
Consolidated purchasing through group purchasing organizations is compressing vendor negotiation leverage and standardizing equipment specifications across multi-hospital systems. Smaller regional manufacturers are losing access to procurement committees controlled by national contracting entities. This concentration is most visible in the southeastern United States where hospital system mergers have reduced independent facility decision-making autonomy.
Central Monitoring Station Market Segmentation
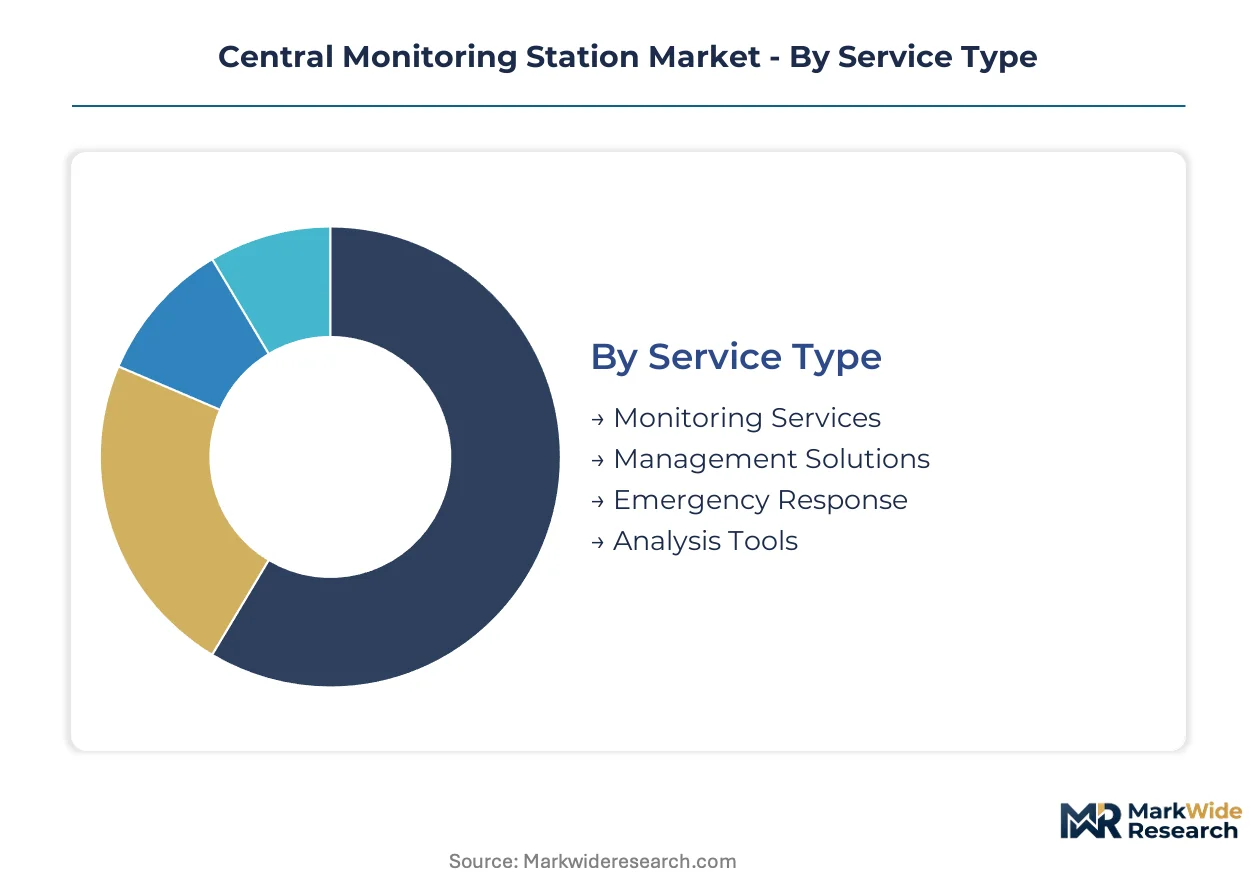
Central monitoring station procurement flows through distinct channel configurations that reshape how vendors position hardware, software, and service bundles. Segment boundaries determine pricing architecture, implementation complexity, and long-term contract structures across integrated health networks and industrial operators.
Service Type:
Monitoring services flow through recurring revenue contracts with multi-year service level agreements, while management solutions and emergency response deploy through capital expenditure channels with distinct margin profiles.
- Monitoring Services:Continuous physiological surveillance delivered via networked bedside-to-station telemetry with 24/7 operator coverage. Tertiary hospitals in the United States concentrate demand here as consolidation creates enterprise-scale contracts requiring unified alarm management across dozens of facilities.
- Management Solutions:Software platforms centralizing device fleet administration, firmware distribution, and compliance documentation. Financial institutions are expanding adoption as HIPAA-mandated encryption requirements force upgrades to centralized access control architectures.
- Emergency Response:Automated dispatch protocols triggered by threshold breaches in critical care environments. Industrial plants leverage these for hazardous environment worker safety.
- Analysis Tools:Post-hoc waveform review and trend reporting for quality improvement initiatives. Academic medical centers drive niche demand.
Monitoring services dominate installed base. Management solutions are where expansion concentrates.
Technology:
Cost tier stratification separates premium cloud-native deployments from economy on-premises configurations, with hybrid architectures capturing mid-market health systems seeking phased migration paths.
- Cloud-Based Systems:Scalable infrastructure eliminating on-site server maintenance with subscription-based pricing. Healthcare facilities across the United States are expanding adoption fastest as IT overhead reduction becomes a board-level priority for integrated delivery networks.
- On-Premises Solutions:Dedicated hardware installations with full data sovereignty and sub-millisecond latency for critical alarm pathways. Defense-sector hospitals and certain European facilities with strict data residency mandates maintain preference here.
- IoT Devices:Distributed sensor networks enabling seamless device integration across distributed care environments. Home-based acute care extensions are emerging as a new demand vector.
- Data Analytics Platforms:Real-time inference engines transforming physiological signals into predictive clinical intelligence. Pilot deployments in surgical recovery units are validating algorithm performance.
On-premises solutions anchor legacy infrastructure. Cloud-based systems are climbing the fastest.
End User:
Application-specific requirements fragment procurement specifications, with healthcare facilities demanding IEC 80001 risk management compliance while industrial operators prioritize environmental hazard detection.
- Healthcare Facilities:Hospitals, clinics, and long-term care centers requiring FDA 510(k)-cleared patient monitoring networks. Hospital consolidation across the United States compresses procurement cycles and favors vendors with enterprise-scale deployment capabilities.
- Financial Institutions:Data centers and trading floors requiring environmental and security monitoring with SOC 2 compliance. Demand concentrates in major metropolitan hubs with dense financial services presence.
- Industrial Plants:Manufacturing and process facilities monitoring equipment health and worker safety in hazardous zones. OSHA compliance mandates drive replacement cycles.
- Residential Buildings:Smart home and multi-tenant security systems with centralized alarm aggregation. Property management companies standardize specifications across portfolios.
Healthcare facilities absorb majority installed capacity. Residential buildings represent the steepest expansion trajectory.
Installation:
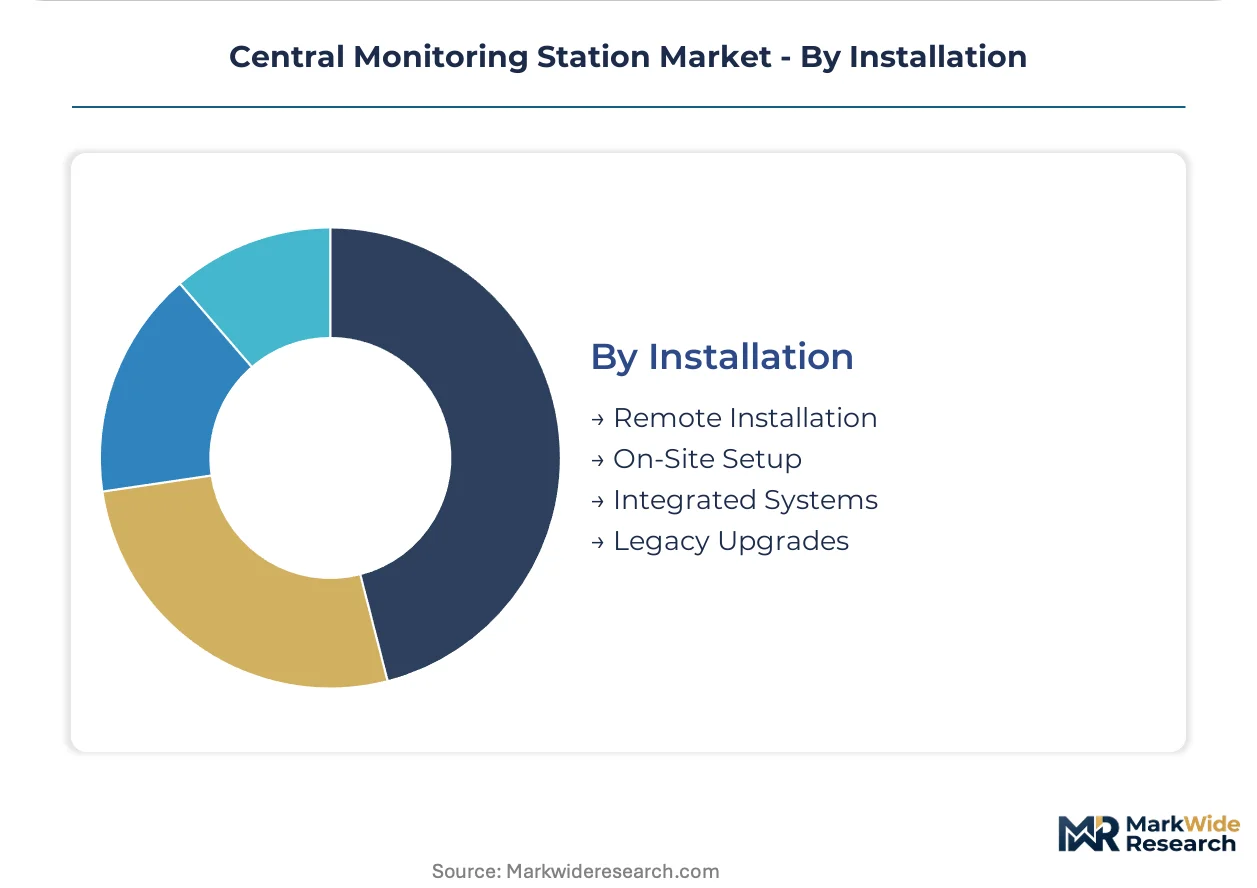
Customer type and internal IT maturity determine implementation channel, with integrated delivery networks favoring remote deployment while critical access hospitals require on-site engineering support.
- Remote Installation:Cloud-native platforms deployed via virtualized infrastructure with minimal physical presence. Large health systems with dedicated biomedical engineering teams prefer this channel for speed and cost control.
- On-Site Setup:Full hardware commissioning with local network integration and staff training. Smaller facilities with limited IT infrastructure rely on vendor field engineers.
- Integrated Systems:Unified deployments combining monitoring, analytics, and emergency response in single-vendor architectures. Group purchasing organizations increasingly specify these bundles.
- Legacy Upgrades:Phased migrations preserving existing bedside device investments while modernizing central station software. HIPAA-mandated encryption requirements are accelerating these projects.
On-site setup dominates current deployment volume. Remote installation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
HIPAA-mandated encryption standards and hospital consolidation incentives are redirecting procurement budgets toward enterprise-scale central monitoring architectures across major healthcare markets.
United States
Tertiary hospital networks in the Southeast and Midwest are compressing vendor negotiation cycles through group purchasing organization consolidation. FDA 510(k) clearance timelines for Class II medical devices extend validation protocols, favoring established suppliers with regulatory expertise. The Greater Boston and North Carolina Research Triangle clusters concentrate pilot deployments of AI-augmented alarm management systems.
Germany
Industrial plant operators and university hospitals drive dual demand for worker safety and patient monitoring networks. EU MDR clinical evidence requirements lengthen approval timelines but elevate barriers against non-compliant imports. The Baden-Württemberg medical technology corridor around Stuttgart anchors manufacturing and R&D concentration for sensor hardware integration.
Japan
Aging demographic pressures expand NICU and critical-care capacity in tertiary facilities, requiring specialized multi-parameter physiological aggregation. PMDA regulatory frameworks govern software-as-medical-device classifications for cloud-native monitoring platforms. The Kansai region surrounding Osaka maintains dense supplier ecosystems for precision sensor component fabrication.
China
Hospital infrastructure modernization programs accelerate replacement of legacy bedside-to-station telemetry in tier-one cities. NMPA medical device registration rules tighten post-market surveillance obligations for networked patient monitoring systems. The Yangtze River Delta cluster spanning Shanghai and Jiangsu Province concentrates domestic manufacturing capacity for IoT-enabled distributed sensor networks.
India
Medical device parks under PLI scheme incentives attract component assembly investments for export-oriented monitoring hardware. CDSCO import licensing requirements create procurement friction for non-domestic central station vendors. The Karnataka medical technology corridor around Bangalore hosts emerging software development centers for real-time data analytics platforms.
Central Monitoring Station Market Competitive Environment
Player mix skews toward diversified health technology conglomerates with installed base advantages and specialized critical-care equipment manufacturers with niche configuration expertise. Market structure exhibits moderate consolidation around vendors capable of enterprise-scale deployment with unified service architectures. Three archetypes dominate: integrated health technology platforms, specialized physiological monitoring specialists, and regional system integrators with local regulatory navigation capabilities. Competitive moves concentrate on backward integration into sensor hardware and strategic partnerships for AI-augmented clinical decision support layers.
Within the integrated platform tier, GE Healthcare and Philips Healthcare exemplify archetypes leveraging ecosystem breadth to sustain recurring service contracts across multi-facility networks. Nihon Kohden occupies a position representing specialized critical-care configuration expertise, particularly in neonatal and high-acuity monitoring segments where physiological parameter differentiation commands premium positioning.
| Leading Market Players |
|---|
| GE Healthcare |
| Philips Healthcare |
| Nihon Kohden |
| Cerner |
| Mediana |
| Criticare Systems |
| Lepu Medical Technology |
| Fukuda Denshi |
| MindRay |
| Others |
Value Chain & Pricing Dynamics
UL 864 certification for control units and accessories gates both vendor qualification and price differentiation simultaneously, creating tiered access where certified incumbents command premium positioning while uncertified challengers face exclusion from North American hospital procurement committees. This regulatory threshold compresses margins for mid-tier suppliers unable to absorb validation costs while enabling certified leaders to sustain service-contract premiums across integrated delivery networks.
Pricing Analysis
Certification level (FDA 510(k)-cleared versus uncertified) creates the primary spread between premium and economy tiers in central monitoring station procurement. Three-tier pricing structure across premium, standard, and economy levels reflects UL 864 compliance status, cloud-native versus on-premises architecture, and bundled after-sales service intensity. Cost compression in the standard tier is intensifying because group purchasing organizations consolidate specifications across multi-hospital systems. Critical access hospitals exhibit highest price sensitivity due to constrained capital budgets, while tertiary academic medical centers prioritize clinical functionality over unit economics.
Supply Chain Analysis
East Asian foundry networks in Taiwan and South Korea anchor semiconductor fabrication for precision sensor chipsets deployed in multi-parameter bedside devices. Component sourcing draws from Japanese precision electronics for analog front-end modules, German industrial sensors for environmental monitoring variants, and domestic Chinese assembly for IoT-enabled distributed networks. Single-source vulnerability concentrates in advanced node semiconductor capacity, where geopolitical friction threatens fabrication continuity. Distribution runs through direct vendor-to-health-system contracts for enterprise deployments, with regional system integrators handling smaller facility implementations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in IEC 80001 risk management for networked medical devices remains scarce among experienced practitioners, constraining vendor scaling and creating defensive moats for incumbents with established biomedical engineering teams. This capability gap shapes competitive dynamics across procurement cycles and post-market surveillance obligations.
For Market Incumbents: Consolidate installed base advantages through backward integration into sensor hardware, capturing margin pools currently flowing to third-party component suppliers. Deepen enterprise service contracts by embedding AI-augmented alarm management layers that increase switching costs for integrated health networks. Wireless telemetry substitution from point-of-care devices threatens centralized station architectures in smaller facilities, requiring tiered product portfolio responses. For New Entrants and Emerging Players: Home-based acute care extensions represent the most penetrable white-space where incumbents under-serve residential monitoring demand with hospital-calibrated product architectures. Target critical access hospitals in the southeastern United States with simplified cloud-native deployments that reduce IT infrastructure burdens relative to integrated delivery network solutions. Pursue partnership-based go-to-market models with regional system integrators possessing established biomedical engineering capabilities. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cloud-native platform development as subscription pricing models require sustained R&D investment before recurring revenue maturation. Long-term viability favors vendors with demonstrated FDA 510(k) clearance velocity and established GPO contract positioning. Acquisition target archetype: specialized critical-care monitoring specialists with neonatal configuration expertise and EU MDR conformity documentation. Monitor FDA cybersecurity guidance enforcement patterns as inflection indicator for compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates market access for Class II medical device software and hardware platforms. |
| EU MDR Conformity Assessment | Creates first-mover advantages in European member states with elevated clinical evidence barriers. |
| Hospital System Partnership | Secures enterprise-scale deployment contracts through consolidated procurement committees. |
| Software Companion Development | Enables predictive deterioration alerts that differentiate alarm management workflows. |
| Reimbursement Strategy | Aligns remote patient monitoring extensions with CMS billing code expansions. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR conformity databases, hospital procurement records, and GPO contract disclosures. Primary interviews engaged biomedical engineering directors, hospital purchasing committee members, central station operators, and regulatory affairs specialists across integrated delivery networks and critical access facilities. Bottom-up demand modeling triangulates against top-down market sizing from equipment shipment data and service contract value analysis.
Segmentation dimensions modeled include service type (monitoring services, management solutions, emergency response, analysis tools), technology architecture (cloud-based, on-premises, IoT-enabled, analytics-integrated), end-user category (healthcare facilities, financial institutions, industrial plants, residential buildings), and installation channel (remote, on-site, integrated, legacy upgrade). CAGRs derive from regression analysis against hospital consolidation velocity, regulatory approval timeline trends, and IT infrastructure investment patterns across the projection horizon. Industry-specific inputs incorporate HIPAA encryption mandate compliance deadlines and semiconductor supply availability indices.
Material uncertainties — FDA cybersecurity guidance enforcement intensity, EU MDR approval timeline extensions, East Asian foundry capacity allocation shifts — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained hospital consolidation incentives and cloud-native architecture preference trajectories. Recalibration cycles align with material shifts in regulatory compliance cost structures and supply chain concentration events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Security Cameras (IR Illuminator) Market
Video Surveillance Systems
Germany Surveillance Analog Camera Market
Video Surveillance Systems
Japan Video Surveillance Market
Video Surveillance Systems
Employee Monitoring Solutions (Automated) Market
Video Surveillance Systems
CCTV Camera Market
Video Surveillance Systems
AI CCTV Market
Video Surveillance Systems
City Surveillance Market
Video Surveillance Systems
Canada Surveillance IP Camera Market
Video Surveillance Systems
3D Surveillance Software Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Systems Market
Video Surveillance Systems
Europe Video Surveillance Systems Market
Video Surveillance Systems
Mexico Video Surveillance Market
Video Surveillance Systems
Asia Pacific Surveillance IP Camera Market
Video Surveillance Systems
Europe Surveillance IP Camera Market
Video Surveillance Systems
Global Video Surveillance Systems Market
Video Surveillance Systems
Homeland Security Surveillance Camera Market