
 United States Surveillance Storage Market | 2026-2036
United States Surveillance Storage Market Size, Share, and Industry Trends Forecast 2026-2036
United States Surveillance Storage Market Insights
Direct sales channels to government integrators is fragmenting as cloud service providers and managed security vendors build alternative procurement pathways. Seagate Technology leverages vertically integrated HDD manufacturing to dominate surveillance-optimized drive supply. Western Digital sustains competitive positioning through heat-assisted magnetic recording R&D investments. Dell Technologies anchors enterprise hybrid storage deployments across federal security installations.
Surveillance storage encompasses dedicated disk arrays, solid-state tiers, and cloud repositories engineered for continuous write workloads, multi-stream ingest, and forensic retrieval latency under 500 milliseconds. The architecture serves law enforcement, transportation authorities, and commercial security operations requiring chain-of-custody data integrity. Network Video Recorder and cloud storage segments capture margin expansion as analog-to-IP transition accelerates. Hybrid storage configurations retain relevance in regulated environments demanding local custody with cloud disaster recovery. Digital Video Recorder demand contracts in legacy municipal systems facing replacement cycles.
FAA security directives, FBI Criminal Justice Information Services encryption standards, and state-level body camera retention laws shape procurement specifications and compliance costs. NHTSA regulations on commercial vehicle event recorders extend storage obligations across transportation fleets. Stakeholders must monitor evolving Federal Risk and Authorization Management Program certification requirements for cloud-based evidence management.
Market Dynamics
Federal video retention mandates and the obsolescence of analog Digital Video Recorder infrastructure are forcing municipal procurement offices into accelerated replacement cycles. Cloud service providers are capturing evidence management workflows previously dominated by on-premise Network Video Recorder deployments.
Growth Catalysts
- FBI Criminal Justice Information Services encryption standards:Law enforcement agencies must upgrade storage systems to meet CJIS compliance, triggering hardware refresh cycles across state and local departments.
- Smart city deployments in Texas, California, and Florida:Metropolitan transit authorities and critical infrastructure operators are procuring petabyte-scale storage for real-time video analytics and forensic retrieval.
- Heat-assisted magnetic recording:Advanced HDD technology enables higher-density surveillance-optimized drives, reducing data center footprint for continuous write workloads.
Market Restraints
- Flash memory cost volatility:Solid-state storage tiers face input cost pressure from NAND supply concentration in East Asian foundries, constraining hybrid architecture adoption.
- Federal Risk and Authorization Management Program certification timelines:Cloud-based evidence management vendors encounter 12-18 month FedRAMP authorization delays, slowing federal procurement velocity.
- Legacy DVR technical debt:Municipalities with constrained capital budgets face integration friction when bridging analog coaxial infrastructure with IP-based storage architectures.
Strategic Opportunities
- State-level body camera retention laws:Illinois, New York, and Pennsylvania have enacted multi-year video retention mandates, expanding addressable storage demand for police departments.
- Edge-to-cloud tiering:Transportation authorities are deploying distributed storage nodes that synchronize with central repositories, creating new system integration revenue streams.
- Commercial vehicle event recorders:NHTSA regulations extend storage obligations to fleet operators, opening transportation verticals beyond traditional security applications.
Industry Challenges
- Forensic data scientist shortage:Agencies lack personnel trained in chain-of-custody protocols for video evidence admissibility in court proceedings.
- Hybrid storage certification complexity:Vendors must simultaneously satisfy CJIS encryption, FedRAMP cloud, and state public records access requirements.
- Multi-vendor integration:Camera manufacturers, video management software providers, and storage vendors operate on incompatible API frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Surveillance Storage Market |
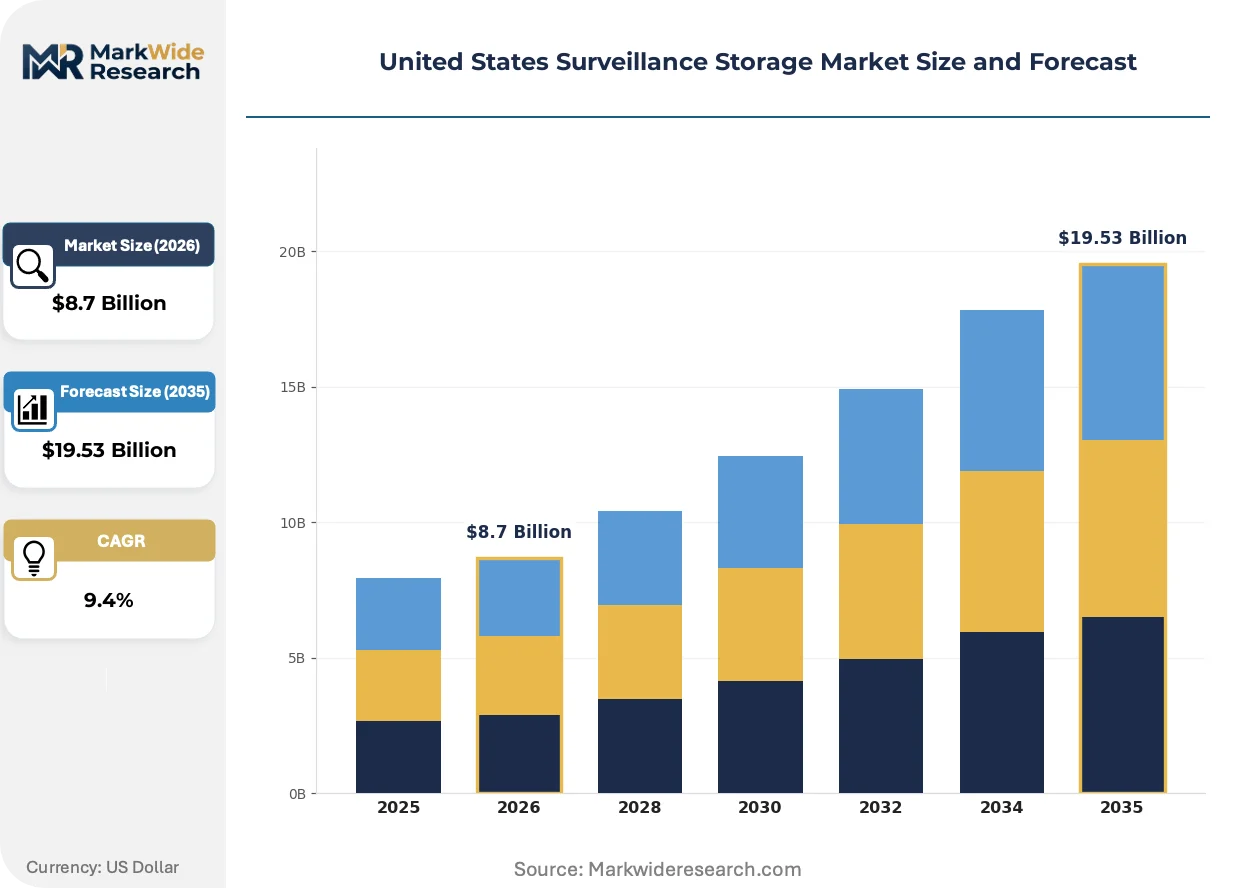
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Network Video Recorder, Digital Video Recorder, Cloud Storage, Hybrid Storage End User: Retail, Transportation, Government, Education Technology: IP Cameras, Analog Cameras, Wireless Cameras, Thermal Cameras Distribution Channel: Direct Sales, Online Retail, Resellers, System Integrators |
| Companies Covered | Seagate Technology, Western Digital, Dell Technologies, Hewlett Packard Enterprise, NetApp Inc, IBM, Quantum Corporation, Hitachi Vantara, Genetec, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Surveillance Storage Market Trends and Innovations
Artificial intelligence inference at the storage layer is compressing forensic search times from hours to seconds. This capability is reshaping procurement specifications across federal security installations and metropolitan police departments.
Object storage architectures with embedded video analytics are digitizing evidence review workflows. FBI field offices and large metropolitan police departments are piloting these systems for facial recognition and license plate retrieval. The technology is digitizing the discovery process for criminal prosecutors who previously relied on manual video review.
FAA security directives for airport perimeter surveillance are mandating encrypted storage with sub-500-millisecond retrieval latency. Airport authorities in Atlanta, Dallas-Fort Worth, and Los Angeles are consolidating standalone NVR installations into centralized storage area networks. These facilities are deploying air-gapped backup systems to satisfy federal continuity requirements.
Subscription-based evidence management is displacing capital-intensive on-premise procurement. State and local agencies in budget-constrained jurisdictions are adopting per-camera-per-month pricing from managed security vendors. This shift is most pronounced in Midwestern municipalities facing pension fund pressures and deferred infrastructure maintenance.
United States Surveillance Storage Market Segmentation
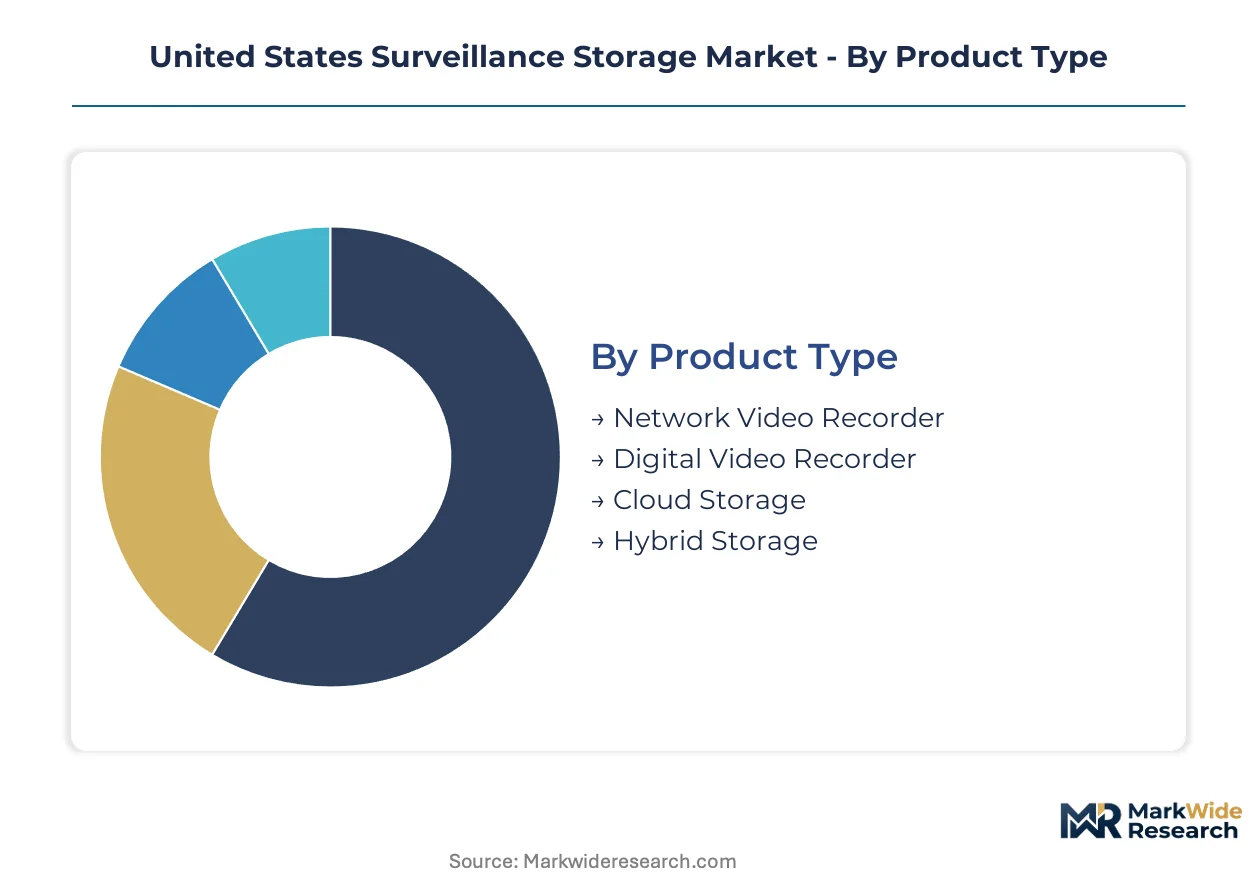
Storage procurement patterns diverge sharply across product architectures, end-use risk profiles, and camera technology generations. Each segmentation dimension carries distinct compliance obligations, capacity scaling requirements, and vendor qualification barriers that reshape competitive positioning.
Product Type:
Cost tier determines procurement pathway and operational expenditure structure for surveillance storage buyers.
- Network Video Recorder:Purpose-built appliances ingest IP video streams with RAID redundancy and forensic search indexing. Demand concentrates in Texas metropolitan police departments replacing aging DVR fleets under CJIS encryption mandates.
- Cloud Storage:Subscription repositories with FedRAMP authorization enable evidence sharing across jurisdictional boundaries. California smart city deployments in Los Angeles and San Francisco are rotating procurement toward operational expenditure models to bypass capital budget constraints.
- Digital Video Recorder:Legacy coaxial-based systems face accelerated replacement cycles as analog camera support ends.
- Hybrid Storage:Local NVR tiers with cloud disaster recovery retain relevance in regulated environments demanding chain-of-custody continuity.
Network Video Recorder holds installed capacity. Cloud Storage is rotating up the share rankings.
End User:
Application risk tier dictates encryption standards, retention periods, and retrieval latency specifications.
- Government:Federal, state, and local agencies operate under FBI Criminal Justice Information Services encryption standards with multi-year retention mandates. Illinois and New York body camera laws are expanding petabyte-scale procurement for state police evidence management.
- Transportation:NHTSA commercial vehicle regulations and FAA airport security directives impose sub-500-millisecond retrieval requirements. Dallas-Fort Worth and Atlanta airport authorities are consolidating standalone installations into centralized storage area networks.
- Retail:Loss prevention departments prioritize cost-optimized capacity over forensic performance.
- Education:Campus safety departments balance budget constraints against state-mandated retention periods for incident footage.
Government commands compliance premium pricing. Transportation is expanding most quickly as fleet and aviation regulations tighten.
Technology:
Camera generation determines ingest bandwidth, compression protocols, and storage tier optimization requirements.
- IP Cameras:H.265-encoded streams with 4K resolution drive petabyte-scale centralized storage demand. Florida critical infrastructure protection programs in Miami and Tampa are deploying high-density disk arrays for real-time analytics workloads.
- Wireless Cameras:Battery-powered edge devices with local SD caching synchronize to central repositories over cellular or mesh networks. Transportation authorities are piloting distributed nodes for bridge and tunnel monitoring.
- Analog Cameras:Coaxial-based legacy infrastructure requires encoder bridges for IP storage integration.
- Thermal Cameras:Specialized perimeter detection systems generate lower bit-rate streams but demand encrypted archival for FAA security compliance.
IP Cameras dominate new installation volume. Wireless Cameras are climbing the fastest as edge-to-cloud architectures mature.
Distribution Channel:
Customer type and procurement scale determine channel economics and vendor relationship structures.
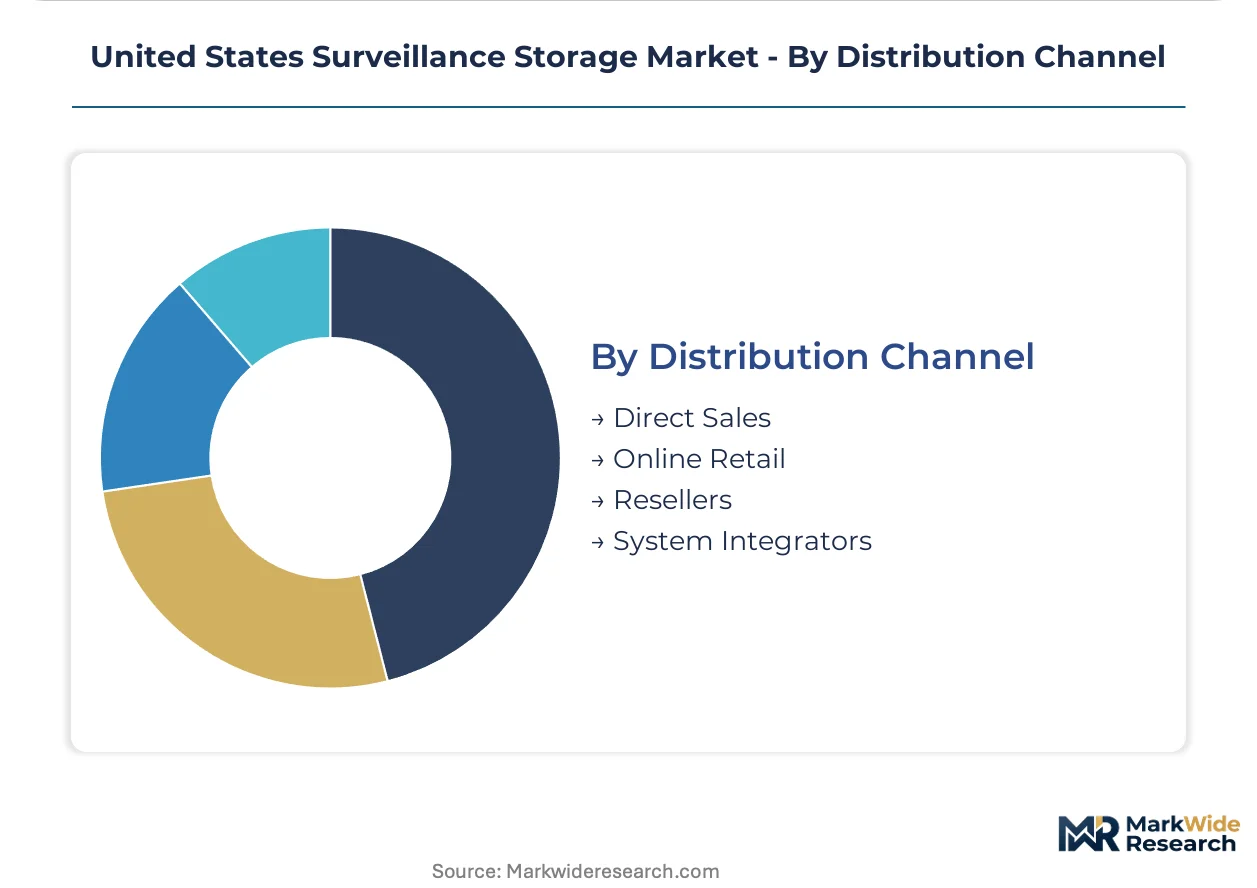
- System Integrators:Turnkey deployment specialists bundle storage with video management software and camera hardware. Federal security installations rely on cleared integrators for classified facility deployments.
- Direct Sales:Manufacturer relationships with large municipal and state agencies bypass margin-stacking intermediaries. Seagate and Western Digital maintain dedicated government sales teams for surveillance-optimized drive procurement.
- Resellers:Regional distributors serve mid-market commercial security operators with inventory availability and technical support.
- Online Retail:E-commerce platforms capture small-scale commercial and residential replacement demand.
System Integrators capture project complexity premium. Direct Sales is gaining share fastest as petabyte-scale procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas commands premium pricing for petabyte-scale federal security installations while Florida municipalities operate under tighter procurement constraints. California's operational expenditure models bypass capital budget limitations entirely. The Southwest corridor concentrates heat-assisted magnetic recording deployments where data center footprint reduction drives vendor selection.
Texas
Dallas-Fort Worth and Houston metropolitan police departments are replacing aging DVR fleets under CJIS encryption mandates. The state's critical infrastructure protection programs channel federal homeland security funding into centralized storage area networks. Austin's smart city transit authority procures real-time video analytics infrastructure with sub-500-millisecond retrieval specifications.
California
Los Angeles and San Francisco authorities rotate procurement toward cloud-based evidence management to circumvent municipal capital budget freezes. State-level privacy regulations impose additional encryption layers on body camera retention systems. The Bay Area hosts pilot deployments of AI inference at the storage layer for facial recognition workloads.
Florida
Miami and Tampa critical infrastructure operators deploy high-density disk arrays for port and airport perimeter surveillance. FAA security directives mandate encrypted archival with air-gapped backup continuity. State procurement offices face integration friction bridging legacy analog coaxial infrastructure with IP-based architectures.
Illinois
Chicago Police Department multi-year body camera retention laws expand addressable storage demand beyond traditional security applications. State police evidence management requires chain-of-custody continuity across hybrid local-cloud configurations. The Northeast Corridor connects to federal CJIS databases through FedRAMP-authorized repositories.
New York
Metropolitan Transit Authority consolidates standalone NVR installations into centralized repositories for subway and bus fleet monitoring. State-level retention mandates exceed federal minimums, extending storage obligations to five-year archival horizons. Upstate municipalities adopt subscription-based per-camera-per-month pricing from managed security vendors.
United States Surveillance Storage Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with dedicated manufacturing scale. The vendor base organizes around three strategic archetypes: vertically integrated drive manufacturers, enterprise hybrid storage deployers, and cloud-native evidence management platforms. Consolidation pressures favor players with CJIS-compliant encryption portfolios and FedRAMP authorization velocity. Competitive moves concentrate on backward integration into surveillance-optimized HDD production and strategic partnerships with cleared federal integrators.
Within the component manufacturing tier, Seagate Technology and Western Digital occupy positions defined by captive supply of heat-assisted magnetic recording platforms. Dell Technologies anchors the enterprise hybrid deployment segment across federal security installations. These three exemplify the bifurcation between upstream drive supply and downstream system integration, with each archetype facing distinct margin pressures from cloud storage displacement and analog-to-IP transition acceleration.
| Leading Market Players |
|---|
| Seagate Technology |
| Western Digital |
| Dell Technologies |
| Hewlett Packard Enterprise |
| NetApp Inc |
| IBM |
| Quantum Corporation |
| Hitachi Vantara |
| Genetec |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in heat-assisted magnetic recording HDD fabrication across the Southwest corridor is compressing component pricing while elevating supplier bargaining power for long-term procurement contracts. Texas and California data center operators leverage this utilization slack to negotiate volume discounts on petabyte-scale surveillance storage deployments.
Pricing Analysis
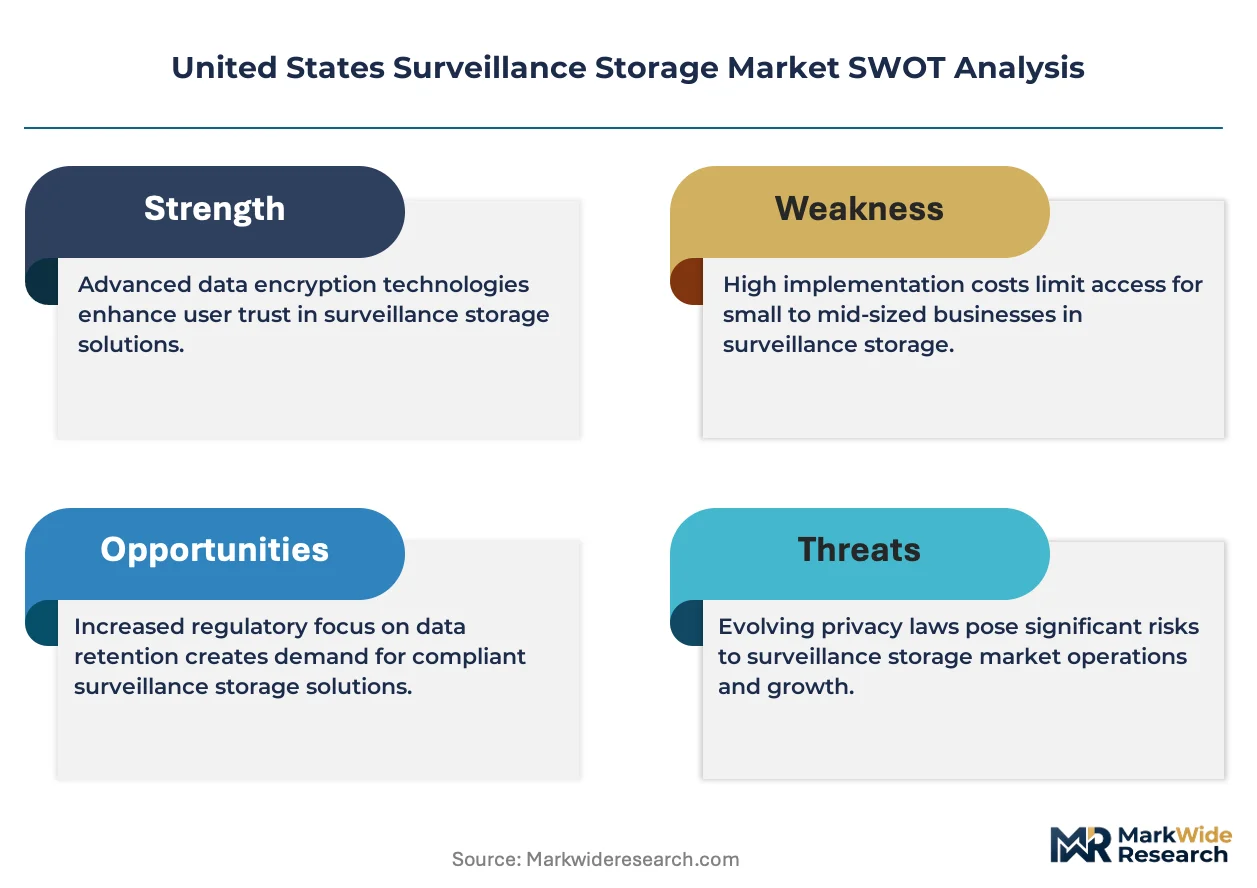
Configured-to-order pricing for CJIS-compliant hybrid storage systems commands a 40-60% premium over standard NVR appliances lacking FedRAMP authorization. Three-tier pricing structure across premium, standard, and economy levels stratifies by encryption certification grade and forensic retrieval latency specifications. Cost compression in cloud storage tiers is intensifying because hyperscalers are absorbing infrastructure overhead to capture evidence management workflows. Municipal procurement offices exhibit highest price sensitivity, while federal security installations prioritize compliance over unit economics.
Supply Chain Analysis
Extended payment terms from system integrators to drive manufacturers now stretch 90-120 days, reflecting working capital pressure from municipal budget cycles. Component supply concentrates in Malaysia, Thailand, and Mexico for PCB assembly and enclosure fabrication, while magnetic media and read-write heads source from Singapore and Japan. NAND flash supply rests on fabrication concentration in South Korea and Taiwan, creating single-source vulnerability for solid-state storage tiers. Distribution runs through cleared federal integrators for classified facility deployments and direct manufacturer relationships for large-scale municipal procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across state-level body camera retention mandates, where compliance heterogeneity creates specialized vendor niches beyond standardized federal specifications.
For Market Incumbents: Harden encryption certification portfolios against emerging cloud-native evidence management platforms by accelerating FedRAMP authorization velocity. Deepen backward integration into surveillance-optimized HDD production to defend margin position against flash memory cost volatility. Secure exclusive partnerships with cleared system integrators serving FBI field office deployments.
For New Entrants and Emerging Players: Midwestern municipalities operating under pension fund constraints present the most penetrable geography for subscription-based per-camera-per-month pricing models. Target transportation authorities piloting edge-to-cloud tiering architectures for bridge and tunnel monitoring applications. Lead with managed security vendor positioning that bundles storage, software, and compliance services to bypass capital budget approval friction.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated component specialists with captive heat-assisted magnetic recording capacity and established CJIS compliance engineering teams. Long-term viability favors vendors bridging on-premise NVR heritage with cloud-native delivery capabilities. Monitor FedRAMP authorization pipeline velocity as the inflection signal for federal procurement share rotation.
| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Acceleration | Cloud providers compress 12-18 month timelines to capture federal evidence management workflows from on-premise incumbents. |
| Heat-Assisted Magnetic Recording Scale-Up | HDD manufacturers reduce data center footprint for continuous write workloads while maintaining cost advantage over solid-state tiers. |
| Edge-to-Cloud Tiering Partnerships | Transportation authorities deploy distributed storage nodes that synchronize with central repositories for bridge and tunnel monitoring. |
| CJIS Compliance Certification Investment | Storage vendors satisfy FBI encryption standards to qualify for state police body camera retention contract awards. |
| Subscription Revenue Model Transition | Managed security vendors displace capital-intensive procurement in budget-constrained Midwestern municipalities. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal police department IT directors, federal security installation procurement officers, airport authority technology managers, and cloud service provider solution architects. Secondary validation drew from FAA security directives, FBI Criminal Justice Information Services policy updates, NHTSA commercial vehicle regulations, state legislative databases tracking body camera retention laws, and SEC filings from publicly traded storage component manufacturers. Bottom-up unit deployment estimates across Texas, California, Florida, Illinois, and New York were triangulated against top-down federal homeland security funding allocations.
Calibration against historical analog-to-IP transition cycles and DVR replacement wave timing informed growth trajectory assumptions across the analysis window. Segmentation dimensions modeled include product architecture, end-user risk tier, camera technology generation, and distribution channel structure. CAGRs were derived from capacity expansion announcements, procurement contract awards, and vendor revenue disclosures. Forecast inputs incorporated petabyte-scale storage deployment timelines for smart city transit authorities and critical infrastructure protection programs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscale cloud providers or flash memory consortiums would shift outcomes. Macroeconomic deviation in municipal bond markets, regulatory acceleration in state privacy legislation, or breakthrough advances in AI inference compression would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
United States Surveillance Camera Market
Video Surveillance Systems
Commercial Aircraft Video Surveillance Systems Market
Video Surveillance Systems
Night Vision Outdoor Camera Market
Video Surveillance Systems
China Surveillance IP Camera Market
Video Surveillance Systems
Mini Security Camera Market
Video Surveillance Systems
Europe Video Surveillance Storage Market
Video Surveillance Systems
Germany Surveillance Analog Camera Market
Video Surveillance Systems
United Kingdom Surveillance Analog Camera Market
Video Surveillance Systems
Brazil Surveillance Camera Market
Video Surveillance Systems
North America Smart Home Security Cameras Market
Video Surveillance Systems
Concealed Weapon Detection Systems Market
Video Surveillance Systems
AI Surveillance System Market
Video Surveillance Systems
CCTV Camera Market
Video Surveillance Systems
Global CCTV Market
Video Surveillance Systems
Aircraft Video Surveillance Systems Market
Video Surveillance Systems
United Kingdom Video Surveillance Market