
 Concealed Weapon Detection Systems Market | 2026-2036
Concealed Weapon Detection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Concealed Weapon Detection Systems Market Analysis
Airport authorities are unwinding reliance on traditional checkpoint staffing models as public-sector buyers gain share in concealed weapon detection procurement. Smiths Detection Group Ltd. leverages decades of aviation security integration to sustain dominance in fixed-installation systems. Liberty Defense Holdings Ltd. specializes in next-generation millimeter wave arrays for high-throughput environments. Evolv Technology anchors the commercial segment with software-defined screening platforms deployed across retail and entertainment venues.
Concealed weapon detection systems integrate active and passive sensor technologies—millimeter wave scanners, thermal imagers, explosive trace detectors, and advanced metal detectors—to identify firearms, knives, and improvised threats beneath clothing without physical pat-downs. These systems operate at frequencies between 30 and 300 GHz, generating three-dimensional images that algorithmic classifiers analyze for anomaly flagging in real time. Fixed installations command the largest revenue pool across transportation hubs and government buildings, while portable and handheld configurations represent the fastest-expanding category as mobile security details proliferate at event management and temporary checkpoints. Millimeter wave technology leads R&D investment intensity, though explosive trace detection retains entrenched positions in aviation-regulated environments where regulatory certification timelines create durable vendor lock-in.
The TSA, DHS, and FAA collectively shape procurement standards through certified product lists and operational testing protocols that determine market access for domestic and foreign suppliers. NHTSA and FERC influence adjacent transit and critical infrastructure security grant flows that indirectly fund detection system deployments. Stakeholders must monitor evolving algorithmic bias testing requirements and interoperability mandates as federal agencies integrate weapon detection into layered physical-cyber security architectures.
Market Dynamics
Millimeter wave arrays are fragmenting legacy checkpoint architectures as TSA-certified passive screening displaces active metal detection across US aviation infrastructure.
Growth Catalysts
- Federal Transit Security Grants:NHTSA-administered funding streams now explicitly cover weapon detection procurement for subway and rail networks, expanding addressable infrastructure beyond aviation.
- Passive Millimeter Wave Maturation:30-300 GHz sensor arrays achieve real-time 3D imaging without physical pat-downs, satisfying throughput demands at high-volume entertainment venues.
- Layered Physical-Cyber Mandates:DHS interoperability requirements are accelerating integration of detection systems into unified security architectures across critical infrastructure.
Market Restraints
- Explosive Trace Certification Timelines:FAA operational testing protocols create 18-36 month vendor lock-in periods that freeze competitive entry in regulated aviation environments.
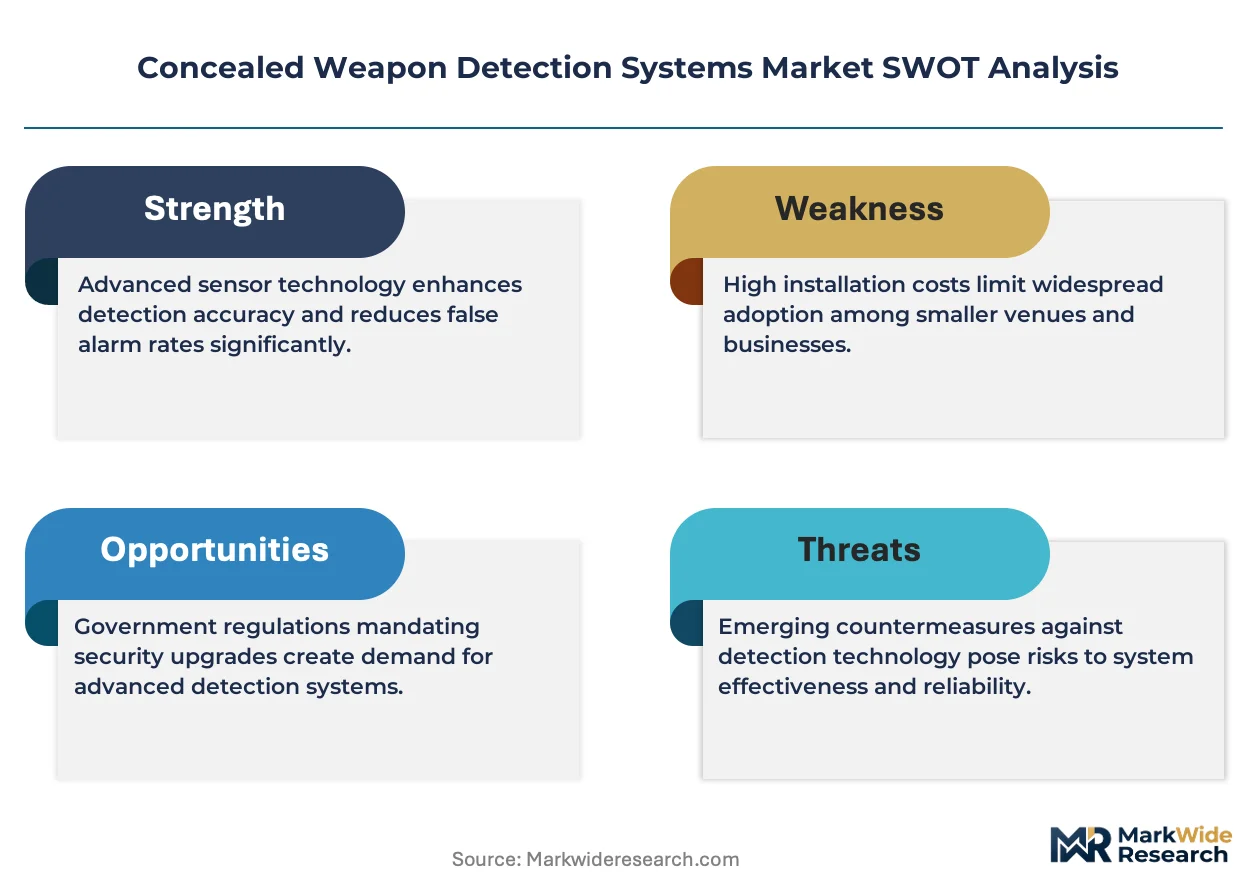
- Sensor Component Concentration:Gallium nitride semiconductor fabrication for millimeter wave transmitters concentrates in East Asian foundries, exposing supply vulnerability.
- Algorithmic Bias Validation Costs:Emerging federal requirements for demographic equity testing impose recurring R&D expenditure without standardized certification pathways.
Strategic Opportunities
- Retail and Entertainment Penetration:Software-defined screening platforms address liability-driven demand from US shopping mall operators and professional sports venues seeking frictionless entry.
- Portable Configuration Expansion:Handheld and mobile systems capture temporary checkpoint applications at music festivals and political events where fixed installation is economically unviable.
- EU AI Act Compliance Positioning:Biometric classification restrictions in European regulation create first-mover advantage for vendors with pre-certified anomaly-detection algorithms.
Industry Challenges
- Millimeter Wave Engineering Talent Scarcity:RF circuit design and antenna array optimization skills concentrate in defense contracting, constraining commercial product development pipelines.
- Legacy Metal Detector Replacement Complexity:Airport infrastructure retrofit requires phased deployment coordination with active checkpoint operations, extending sales-to-revenue cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concealed Weapon Detection Systems Market |
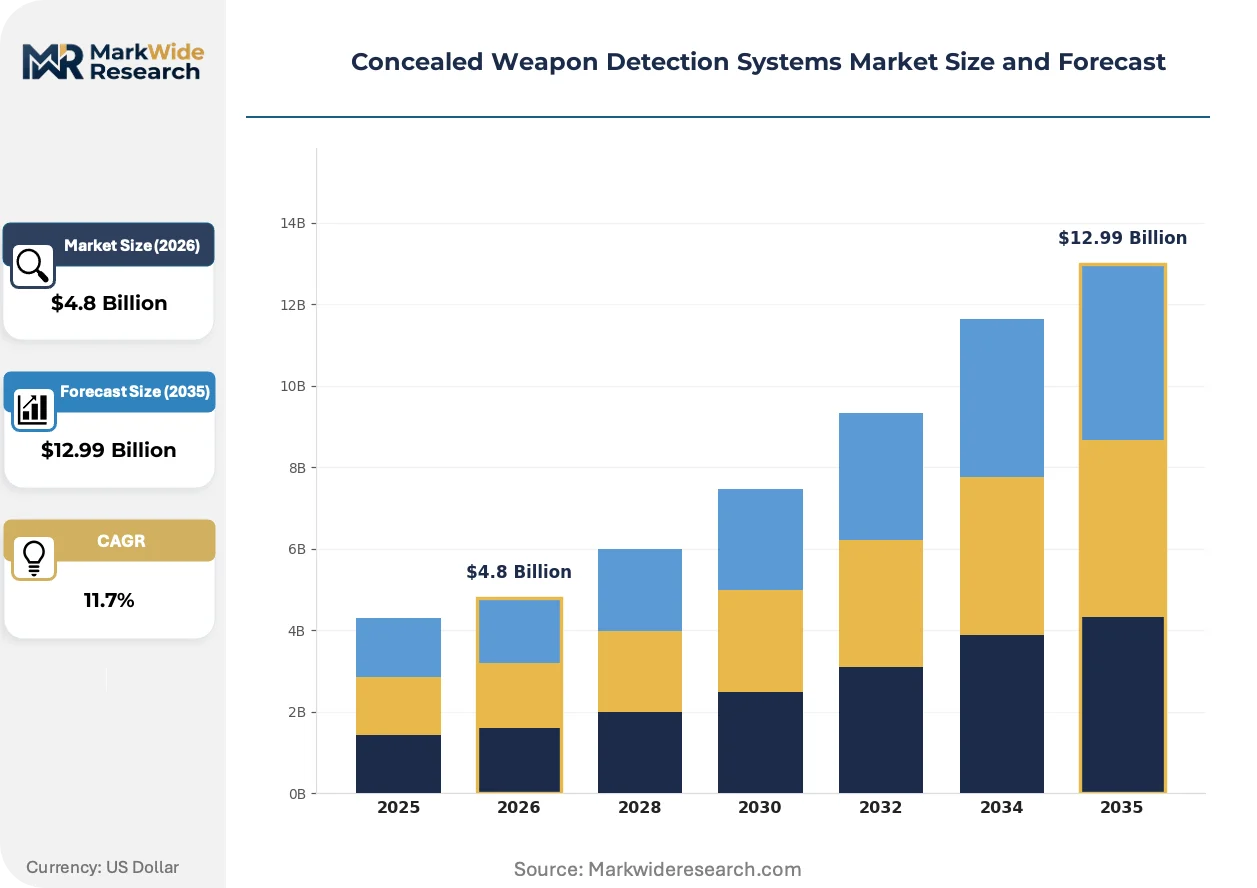
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Millimeter Wave, Explosive Trace Detection, Thermal Imaging, Metal Detection Installation: Fixed, Portable, Handheld, Vehicle-Mounted Application: Transportation Hubs, Government Buildings, Commercial Spaces, Educational Institutions End User: Public Sector, Retail Security, Event Management, Military |
| Companies Covered | QinetiQ Group plc, Astrophysics Inc., Smiths Detection Group Ltd., Athena Security Solutions Private Limited, Liberty Defense Holdings Ltd., Leidos Inc., Nuctech Company Limited, Evolv Technology, Rohde & Schwarz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concealed Weapon Detection Systems Market Emerging Trajectories
Sensor fusion architectures are compressing the boundary between detection and identification, enabling real-time threat classification without human image review.
Multi-static millimeter wave configurations are fragmenting conventional single-viewpoint scanner designs. Casino operators and stadium authorities deploy distributed antenna arrays that eliminate blind spots from concealed angles. This topology shift is fragmenting vendor specialization between hardware fabrication and software-defined reconstruction algorithms.
EU AI Act risk classification rules are redefining procurement specifications for biometric-enabled screening. Systems deploying automated person identification now face conformity assessment requirements that extend vendor certification timelines. European transit authorities are responding with explicit technical specifications that exclude facial recognition while preserving anomaly detection functionality.
Subscription-based hardware-as-a-service models are displacing capital purchase structures in commercial security procurement. US retail chains and hospitality groups now contract for per-screening fees rather than equipment ownership, transferring obsolescence risk to vendors. This financial restructuring is most visible in the franchise restaurant and grocery verticals where capital allocation prioritizes core operations over security infrastructure.
Concealed Weapon Detection Systems Market Segmentation
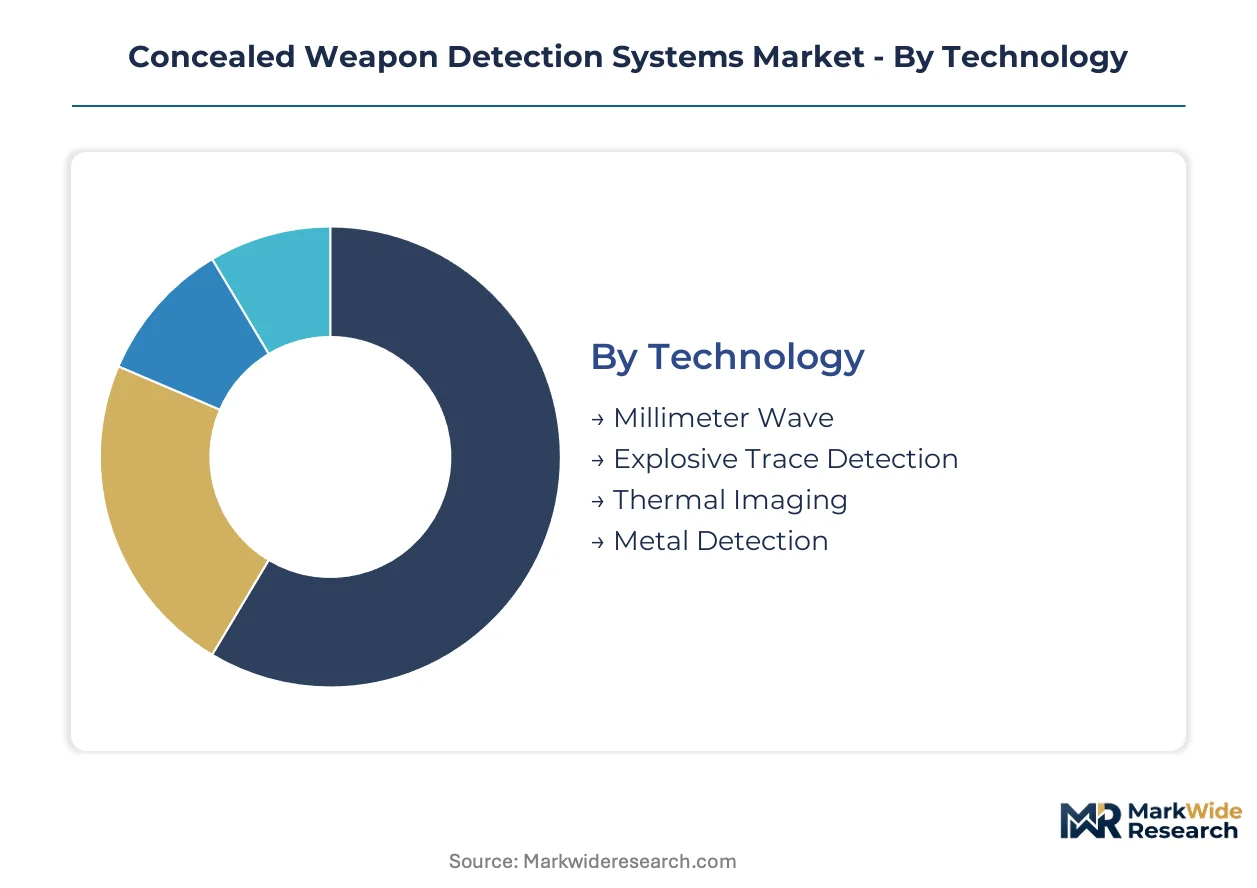
Technology differentiation and deployment flexibility determine procurement patterns across aviation, transit, and commercial security verticals. Vendors compete on throughput optimization, regulatory certification, and integration with layered physical-cyber architectures.
Technology:
Millimeter wave arrays dominate domestic procurement in US aviation and transit networks, while explosive trace detection retains entrenched positions in international regulated environments where certification timelines favor incumbent suppliers.
- Millimeter Wave:Passive 30-300 GHz sensor arrays generate real-time 3D imaging without physical pat-downs. TSA-certified deployments concentrate at US airport checkpoints and subway networks receiving NHTSA-administered security grants.
- Explosive Trace Detection:Ion mobility spectrometry and chemiluminescence systems detect residue compounds at parts-per-trillion sensitivity. FAA operational testing protocols create 18-36 month vendor lock-in periods that freeze competitive entry in regulated aviation environments.
- Thermal Imaging:Infrared focal plane arrays identify concealed objects through temperature differential analysis.
- Metal Detection:Active electromagnetic induction systems remain deployed at secondary screening positions and cost-constrained facilities.
Millimeter wave commands the established base. The steepest expansion runs through explosive trace detection as international aviation authorities modernize hold baggage screening infrastructure.
Installation:
Capital intensity and operational tempo shape deployment economics, with permanent infrastructure dominating transportation hubs and mobile configurations proliferating at temporary checkpoints.
- Fixed:Permanent gantry and portal installations integrate with building management systems and centralized security operations centers. Airport authorities and government buildings in the United States drive procurement volume through federal modernization mandates.
- Portable:Rapidly deployable tripod-mounted units enable temporary perimeter establishment. Event management companies and mobile security details across US entertainment venues and political gatherings generate recurring demand for lease-based deployment models.
- Handheld:Compact wand and panel configurations support secondary screening and targeted inspection protocols.
- Vehicle-Mounted:Integrated mobile command platforms extend detection capability to patrol and rapid response operations.
Fixed installations anchor revenue concentration. Portable configurations are climbing the fastest as subscription-based hardware-as-a-service models displace capital purchase structures in commercial security procurement.
Application:
Threat profile and throughput requirements segment demand, with aviation-regulated environments demanding certified performance and commercial spaces prioritizing frictionless passenger experience.
- Transportation Hubs:Airports, subway stations, and rail terminals require high-throughput passive screening integrated with access control and passenger flow management systems. US transit authorities leverage DHS interoperability requirements to unify detection architectures across multimodal infrastructure.
- Government Buildings:Federal courthouses, legislative facilities, and administrative centers mandate layered screening with audit-compliant logging. Security grant flows from FERC and adjacent critical infrastructure programs fund deployment at energy and communications facilities.
- Commercial Spaces:Retail malls, hospitality venues, and corporate campuses seek liability reduction through visible deterrence without operational disruption.
- Educational Institutions:K-12 and university campuses balance access convenience with emergency response preparedness.
Transportation hubs capture the dominant revenue share. Commercial spaces are gaining share fastest as US shopping mall operators and professional sports venues adopt software-defined screening platforms.
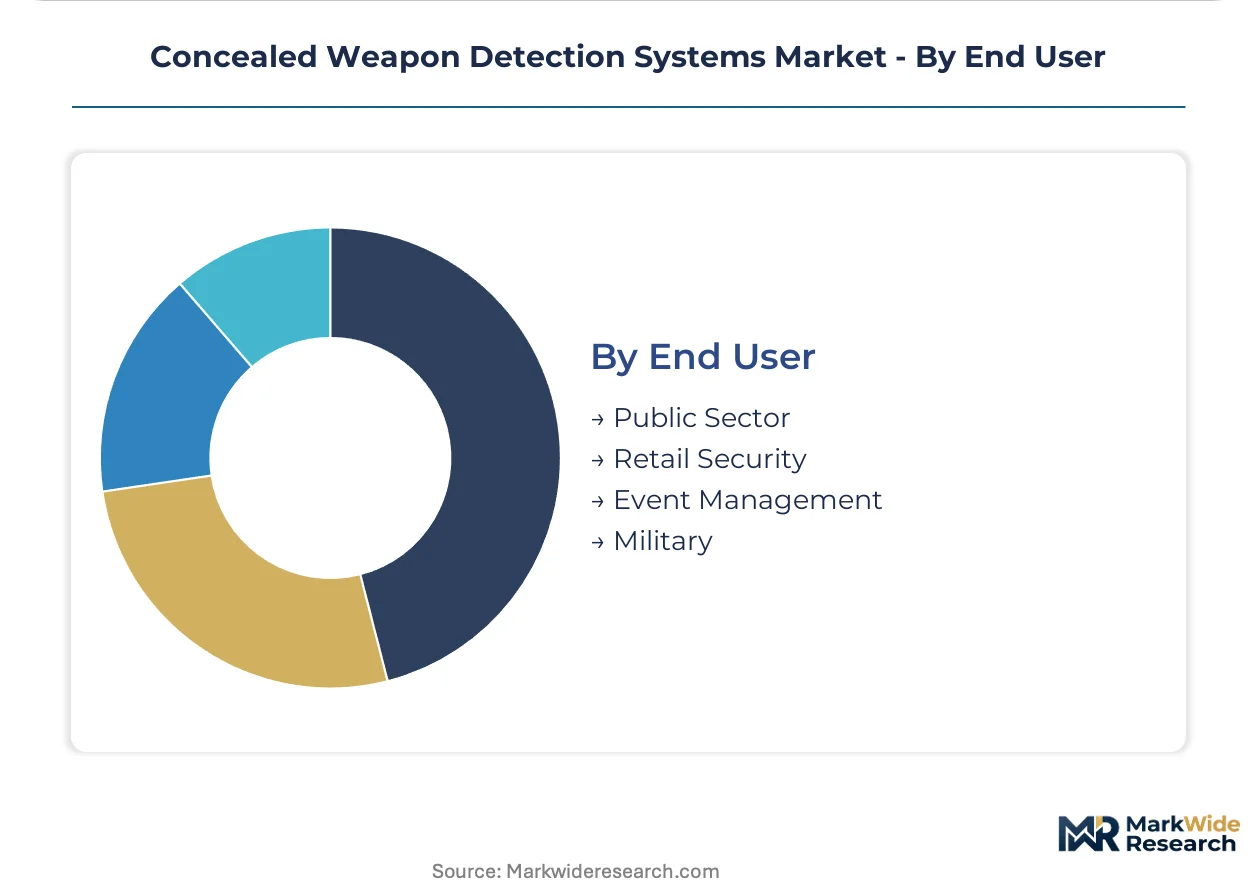
End User:
Budget authority and procurement methodology diverge sharply, with public-sector buyers emphasizing certification compliance and commercial operators prioritizing total cost of ownership and brand protection.
- Public Sector:TSA, DHS, and FAA-certified procurement lists determine vendor eligibility for aviation and critical infrastructure deployments. Federal transit security grants now explicitly cover weapon detection procurement for subway and rail networks, expanding addressable infrastructure beyond aviation.
- Retail Security:Loss prevention departments and shopping mall operators contract for per-screening fees rather than equipment ownership. US franchise restaurant and grocery verticals transfer obsolescence risk to vendors through subscription-based hardware-as-a-service structures.
- Event Management:Temporary checkpoint operators at music festivals and political events require rapid deployment and strike capabilities.
- Military:Force protection and base security applications demand hardened specifications and interoperability with existing command systems.
Public sector buyers dominate procurement volume. Retail security is expanding most quickly as liability-driven demand accelerates adoption of frictionless entry systems across US commercial venues.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israeli sensor technology flows into US aviation security infrastructure as federal modernization mandates reshape procurement corridors across North America and Europe. Millimeter wave arrays manufactured in East Asian foundries supply fixed installations at transportation hubs in Germany and the United Kingdom.
United States
TSA checkpoint modernization drives passive screening deployment at 450+ commercial airports while NHTSA-administered grants fund subway and rail network upgrades in New York, Chicago, and Washington DC. The FAA maintains certified product lists that determine vendor eligibility for aviation procurement. Dallas-Fort Worth and Atlanta Hartsfield-Jackson anchor fixed-installation demand as the busiest US airports phase out legacy metal detectors.
Germany
Federal Police procurement standards prioritize EU AI Act-compliant anomaly detection without biometric person identification at Frankfurt and Munich airports. The BSI issues technical guidelines for critical infrastructure security that influence detection system specifications at rail terminals and government buildings. Bavaria's security technology cluster around Munich hosts integration specialists serving European transit authorities.
United Kingdom
Transport for London expands millimeter wave deployment across Underground stations following Home Office counter-terrorism infrastructure grants. The UK National Screening Centre coordinates operational testing protocols that align with FAA-equivalent aviation security standards. Heathrow Airport anchors fixed-installation procurement volume as the UK's busiest aviation gateway.
China
Domestic aviation security modernization at Beijing Capital and Shanghai Pudong airports drives demand for indigenous millimeter wave systems. The MIIT establishes GB standards for electromagnetic compatibility that shape sensor array specifications. Shenzhen's electronics manufacturing ecosystem supplies gallium nitride semiconductor components for transmitter fabrication.
United Arab Emirates
Dubai International Airport's expansion plans incorporate passive screening infrastructure to maintain throughput at the world's third-busiest aviation hub. The country's national security regulator mandates layered detection architectures for critical infrastructure protection. Abu Dhabi's government district clusters procurement demand for fixed installations at federal administrative centers.
Concealed Weapon Detection Systems Market Vendor Landscape
Listed leaders compete with private specialists across certification-driven procurement channels, creating a tiered structure where regulatory compliance separates premium-tier vendors from commercial-market challengers. Aviation-certified suppliers command durable positions through FAA operational testing timelines that freeze competitive entry. Three archetypes dominate: legacy defense contractors with decades of government integration experience; millimeter wave technology specialists commercializing university research; and software-defined platform vendors serving retail and entertainment verticals. M&A activity concentrates on sensor fusion capabilities, while strategic partnerships with systems integrators accelerate deployment in transit networks.
Within the aviation-certified tier, Smiths Detection Group Ltd. and Liberty Defense Holdings Ltd. exemplify divergent strategic positions—one leveraging decades of checkpoint integration relationships, the other commercializing next-generation passive screening arrays. Evolv Technology occupies a distinct position among software-defined platform vendors, anchoring commercial segment penetration through subscription-based deployment models at US retail and entertainment venues.
| Leading Market Players |
|---|
| QinetiQ Group plc |
| Astrophysics Inc. |
| Smiths Detection Group Ltd. |
| Athena Security Solutions Private Limited |
| Liberty Defense Holdings Ltd. |
| Leidos Inc. |
| Nuctech Company Limited |
| Evolv Technology |
| Rohde & Schwarz |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at gallium nitride foundries in East Asia directly shapes both component scarcity and price floors for millimeter wave transmitter arrays. Scale advantages at these fabrication facilities concentrate supply leverage among a handful of semiconductor suppliers, forcing detection system vendors to absorb input volatility or pass through costs to certification-constrained buyers.
Pricing Analysis
Legacy metal detection systems trade at substantial discounts to TSA-certified millimeter wave arrays, while next-generation multi-static configurations command premiums approaching double the prior generation. Three-tier pricing structure across aviation-certified, transit-compliant, and commercial-grade levels separates procurement channels. Price differentiation hinges on FAA operational testing completion and throughput certification tier. Cost compression in commercial-grade systems is intensifying because retail buyers now demand subscription-based hardware-as-a-service models that transfer capital risk to vendors. Event management operators exhibit highest price sensitivity; aviation authorities with federal grant backing show least.
Supply Chain Analysis
Strategic stockpiling of gallium nitride wafers and RF components dominates inventory strategy among tier-one detection system vendors facing 18-24 month certification timelines. Supply concentrates in Taiwan, South Korea, and China for semiconductor fabrication, with Israel and the United States hosting sensor integration and algorithm development. Raw material dependencies span gallium nitride substrates, precision antenna substrates, and specialized RF connectors. Single-source vulnerability runs through East Asian foundry concentration for millimeter wave transmitters. Distribution runs through systems integrators with TSA/DHS certification relationships for public-sector procurement, and direct vendor relationships for commercial subscription deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent detection system vendors face substitution pressure from software-defined screening platforms that displace hardware-centric architectures with algorithm-driven threat classification. This technology shift threatens to commoditize sensor hardware while concentrating value capture in platform and analytics layers.
For Market Incumbents: Shield certification-driven revenue streams by accelerating FAA operational testing completion for next-generation millimeter wave arrays before software-defined entrants achieve equivalent regulatory standing. Deepen backward integration into gallium nitride semiconductor sourcing through long-term foundry partnerships in Taiwan and South Korea. Prioritize integration relationships with DHS-certified systems integrators to control transit network deployment channels against modular platform competitors.
For New Entrants and Emerging Players: Differentiate on algorithmic threat classification accuracy without biometric person identification to satisfy EU AI Act procurement specifications at Frankfurt and Munich airports. Target temporary checkpoint applications at music festivals and political events where fixed-installation economics fail and subscription-based portable deployment creates recurring revenue. Pursue white-space penetration in US retail verticals through per-screening fee structures that transfer obsolescence risk from capital-constrained buyers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vendors with completed FAA certification timelines and established DHS integration relationships over pre-revenue algorithm developers. Long-term viability through the technology substitution window rests on regulatory moat durability rather than hardware performance metrics. Acquisition target archetype: millimeter wave specialists with TSA-certified product lists and dormant explosive trace detection capabilities. Signal to watch: NHTSA grant allocation velocity for subway and rail network weapon detection as indicator of addressable infrastructure expansion beyond aviation.
| Strategic Initiative | Industry Significance |
|---|---|
| FAA Certification Completion | Operational testing protocols at FAA create 18-36 month vendor lock-in that freezes competitive entry. |
| Sensor Fusion Acquisition | Millimeter wave array vendors acquire thermal imaging capabilities to compress detection-identification boundary. |
| Subscription Model Transition | Hardware-as-a-service structures transfer obsolescence risk to vendors in US retail and hospitality verticals. |
| EU AI Act Compliance Positioning | Anomaly-detection algorithms without biometric classification gain first-mover advantage in European transit procurement. |
| GaN Foundry Partnership | Long-term supply agreements with Taiwan and South Korean semiconductor fabricators secure transmitter component access. |
Methodological Framework
A spread of perspectives from TSA procurement officers, DHS grant administrators, airport security directors, systems integration specialists, and commercial venue operators converged on the working assumptions governing detection system demand trajectories. Primary fieldwork combined structured interviews with secondary validation through FAA certified product list databases, NHTSA transit security grant disclosures, SEC filings of listed detection system vendors, EU procurement tender documentation, and industry association technical standards. Bottom-up segment sizing triangulated against top-down infrastructure investment flows across aviation, transit, and commercial verticals.
Segmentation dimensions modeled span technology type, installation configuration, application vertical, and end-user procurement methodology across the projection horizon. Technology splits capture millimeter wave, explosive trace detection, thermal imaging, and legacy metal detection platforms. Installation categories distinguish fixed, portable, handheld, and vehicle-mounted deployment economics. Analytical framework derived CAGRs from infrastructure modernization cycle timing, federal grant allocation velocity, and certification pipeline throughput. Forecast inputs incorporated TSA checkpoint replacement schedules, NHTSA transit security grant authorization trends, and EU AI Act implementation timelines affecting biometric-enabled screening procurement.
The analysis sits within stated boundaries; outcomes outside sustained federal transit security funding authorization or accelerated FAA certification timeline compression would require recalibration. Forecasts reflect assumptions regarding millimeter wave sensor cost curves, gallium nitride foundry capacity expansion, and algorithmic bias testing standardization. Practitioners should keep alternative scenarios live as NHTSA grant allocation priorities and EU AI Act conformity assessment requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Latin America Video Surveillance Market
Video Surveillance Systems
Video Surveillance and Vsaas Market
Video Surveillance Systems
CCTV Camera Market
Video Surveillance Systems
Global Mobile Video Surveillance Market
Video Surveillance Systems
Video Surveillance As a Service Market
Video Surveillance Systems
Inspection Camera System Market
Video Surveillance Systems
AI Surveillance Camera Market
Video Surveillance Systems
Germany Video Surveillance Market
Video Surveillance Systems
Cellular Interception Market
Video Surveillance Systems
Global CCTV Market
Video Surveillance Systems
Europe Video Surveillance Systems Market
Video Surveillance Systems
Middle East and Africa Video Surveillance Market
Video Surveillance Systems
United Arab Emirates Surveillance Camera Market
Video Surveillance Systems
North America Video Surveillance Systems Market
Video Surveillance Systems
Latin America Surveillance IP Cameras Market
Video Surveillance Systems
US Video Surveillance Market