
 Wine Barrel Market | 2026-2036
Wine Barrel Market Size, Share, and Industry Trends Forecast 2026-2036
Wine Barrel Market Intelligence
New cooperage investments in Eastern European countries like Hungary and Romania is narrowing the historical supply dominance of French forests. Tonnellerie François Frères Group leverages its extensive forest holdings to ensure a consistent supply of premium oak. Independent Stave Company differentiates through its research into wood science and toasting profiles. Oeneo SA competes on a global scale with a diversified portfolio including both barrels and alternative oak products.
A wine barrel is a vessel, traditionally made from oak staves, that has been toasted over fire to activate specific wood compounds. Its primary function is to facilitate the slow oxidation of wine while imparting complex flavors, aromas, and tannins during the aging process. French and American Oak materials dominate the market, while alternatives like Chestnut and Acacia serve niche, experimental winemakers. The 225-liter 'Bordeaux' barrel capacity remains the industry standard, though larger formats are gaining traction for certain wine styles.
Food contact material regulations, such as those enforced by the US FDA and the European Union's framework (EC) 1935/2004, govern the safety of wood used in barrel production. Rules surrounding Protected Designation of Origin (PDO) in Europe often mandate specific aging periods and barrel types, directly influencing regional demand. Winemakers and coopers must continually evaluate the trade-off between traditional barrel aging and the economic appeal of alternative oak products.
Market Dynamics
The central force shaping the wine barrel market is the pursuit of terroir expression and product premiumization by winemakers. This demand simultaneously fuels investment in traditional oak sourcing from historic forests and drives innovation in digital toasting technologies for precise flavor control.
Growth Catalysts
- Premium Wine Consumption:Demand from winemakers in established and emerging viticulture zones, including Argentina's Mendoza region and New Zealand's Marlborough, for barrels that impart unique flavor and aromatic complexity is a primary catalyst.
- Toasting Technology:Innovations in digital and convection toasting allow coopers to offer highly differentiated products, giving winemakers precise control over the levels of desired wood compounds like vanillin and eugenol.
- Sourcing Diversification:New cooperage investments in Eastern European countries, such as Hungary and Romania, are expanding the supply of high-quality oak, providing alternatives to the historically dominant and costly French oak forests.
Market Restraints
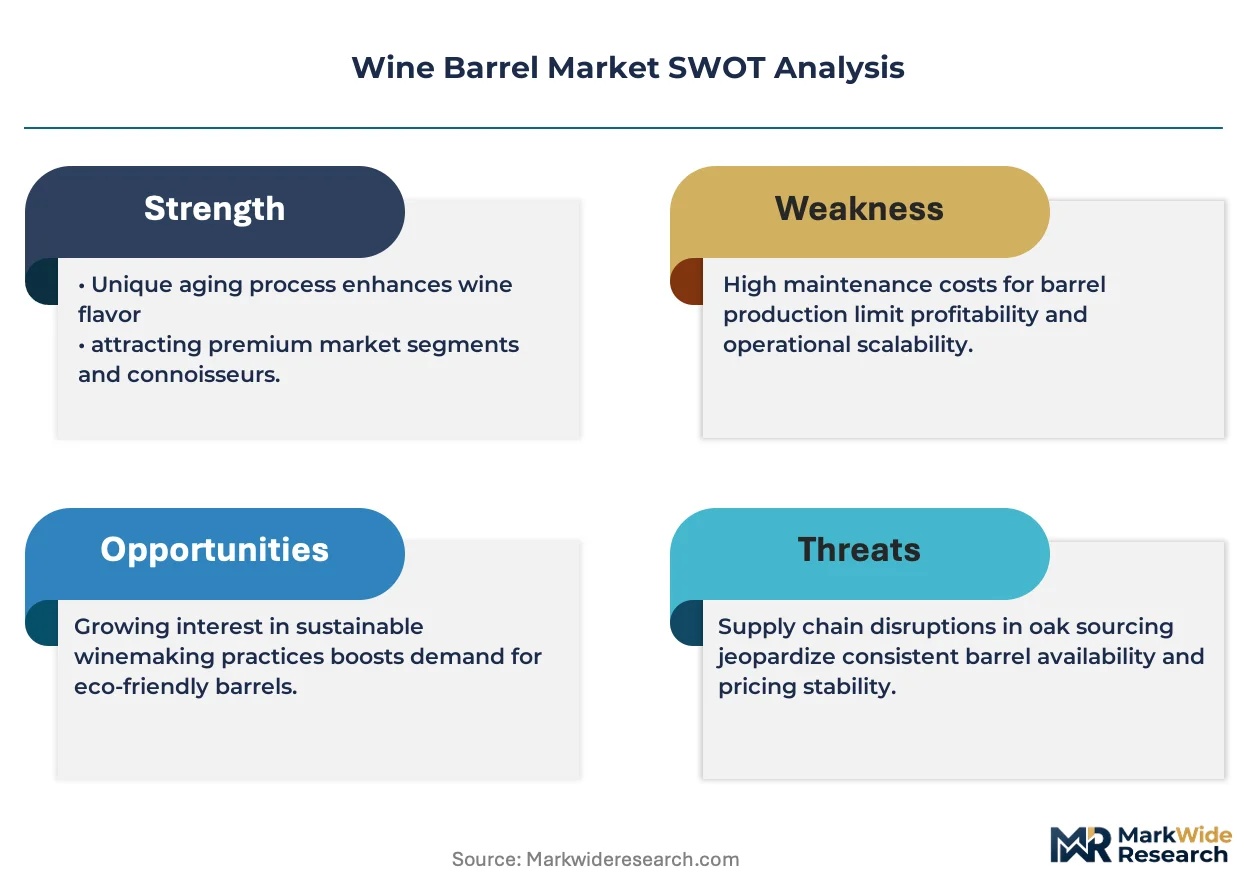
- Input Cost Volatility:The high and fluctuating cost of premium raw oak, particularly from select French forests, presents a significant structural barrier, as wood must be seasoned for years before use.
- Threat of Substitution:The economic appeal of alternative oak products, such as staves, chips, and powders, poses a persistent substitution threat, especially for entry-level and mid-tier wine production.
- Finite Raw Material Supply:The supply of old-growth oak trees suitable for high-quality barrel staves is finite and subject to environmental pressures and forestry management policies, creating a natural production ceiling.
Strategic Opportunities
- Emerging Viticulture Regions:Cooler climate wine regions in areas like England and Canada's Niagara Peninsula represent an untapped market for coopers as local wine production expands and seeks quality aging solutions.
- Alternative Wood Barrels:Niche woods such as Acacia and Chestnut offer opportunities to serve experimental winemakers who are seeking to create novel wine styles that stand apart from traditional oak-aged products.
- Barrel Refurbishment Services:A growing focus on sustainability and cost management creates an opportunity for a circular economy model based on barrel re-toasting, repair, and certified reuse programs for wineries.
Industry Challenges
- Artisan Skill Shortage:A significant operational challenge is the scarcity of skilled coopers, as the craft requires a long apprenticeship to master the traditional techniques of stave shaping, bending, and toasting.
- Regulatory Compliance:Coopers face the complex task of ensuring all wood materials comply with food contact regulations, such as the US FDA requirements and the European Union's framework (EC) 1935/2004.
- Complex Global Logistics:Transporting large, heavy, and climate-sensitive barrels from cooperages in Europe or North America to wineries in the Southern Hemisphere involves high costs and significant logistical coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wine Barrel Market |
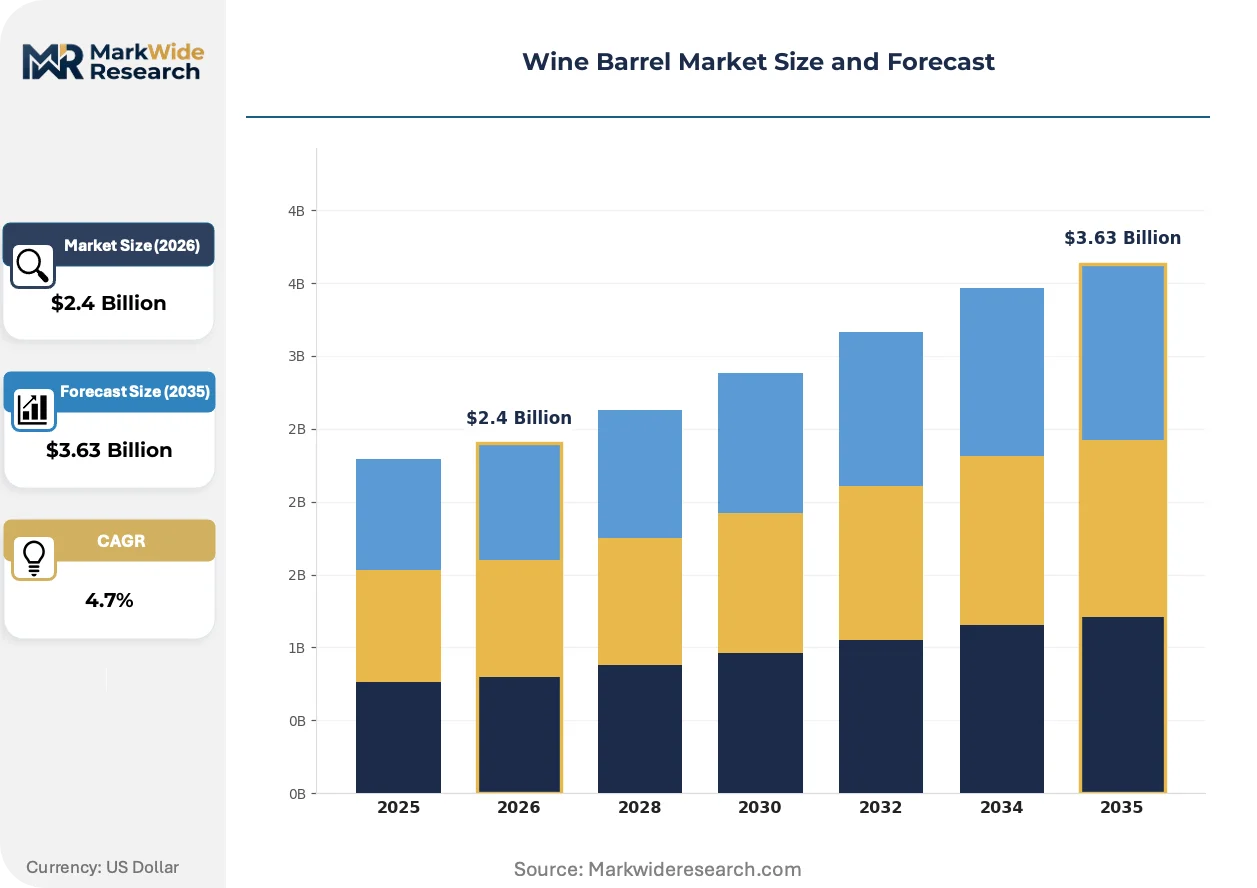
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.63 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Oak, Chestnut, Acacia, Chestnutwood, Cherrywood Capacity: 225 Liters, 300 Liters, 500 Liters, 600 Liters Application: Winemaking, Distilling, Aging, Storage End User: Winemakers, Distilleries, Vineyards, Cellar Operators |
| Companies Covered | Canton Cooperage, Nadalie, Oeneo SA, Bouchard Cooperages, World Cooperage, Tonnellerie François Frères Group, Seguin Moreau Napa Cooperage, Kelvin Cooperage, Independent Stave Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wine Barrel Market Strategic Shifts & Innovations
Technological advancements are reshaping the craft of coopering, creating a new synthesis of artisanal tradition and data-driven precision. This integration allows for unprecedented control over the barrel's impact on wine, moving beyond simple wood origin to scientifically calibrated flavor profiles.
Digital toasting and infrared sensor analysis provide coopers with exact control over the thermal degradation of wood lignin, cellulose, and hemicellulose. Premium wineries and large-scale producers are adopting these barrels to ensure consistency and achieve specific stylistic goals. This technology is hybridizing traditional craftsmanship with scientific repeatability, enabling the creation of barrels with highly predictable and customizable aromatic contributions.
European Union regulations for Protected Designation of Origin (PDO) directly influence regional barrel demand. These frameworks often mandate specific aging requirements, including the type of oak and minimum time in-barrel, to preserve the traditional character of wines from regions like Bordeaux or Chianti Classico. Wineries in these appellations must adhere to these rules, which reinforces demand for traditional barrels and limits the use of alternatives.
Wineries are increasingly exploring barrel leasing and rental programs as an alternative to the significant capital outlay required for outright purchase. This shift disrupts the traditional one-time sales model, creating a service-oriented revenue stream for coopers and third-party financial firms. The model is gaining significant traction among boutique producers in established regions like Sonoma County and new wineries in capital-sensitive emerging markets.
Wine Barrel Market Segmentation
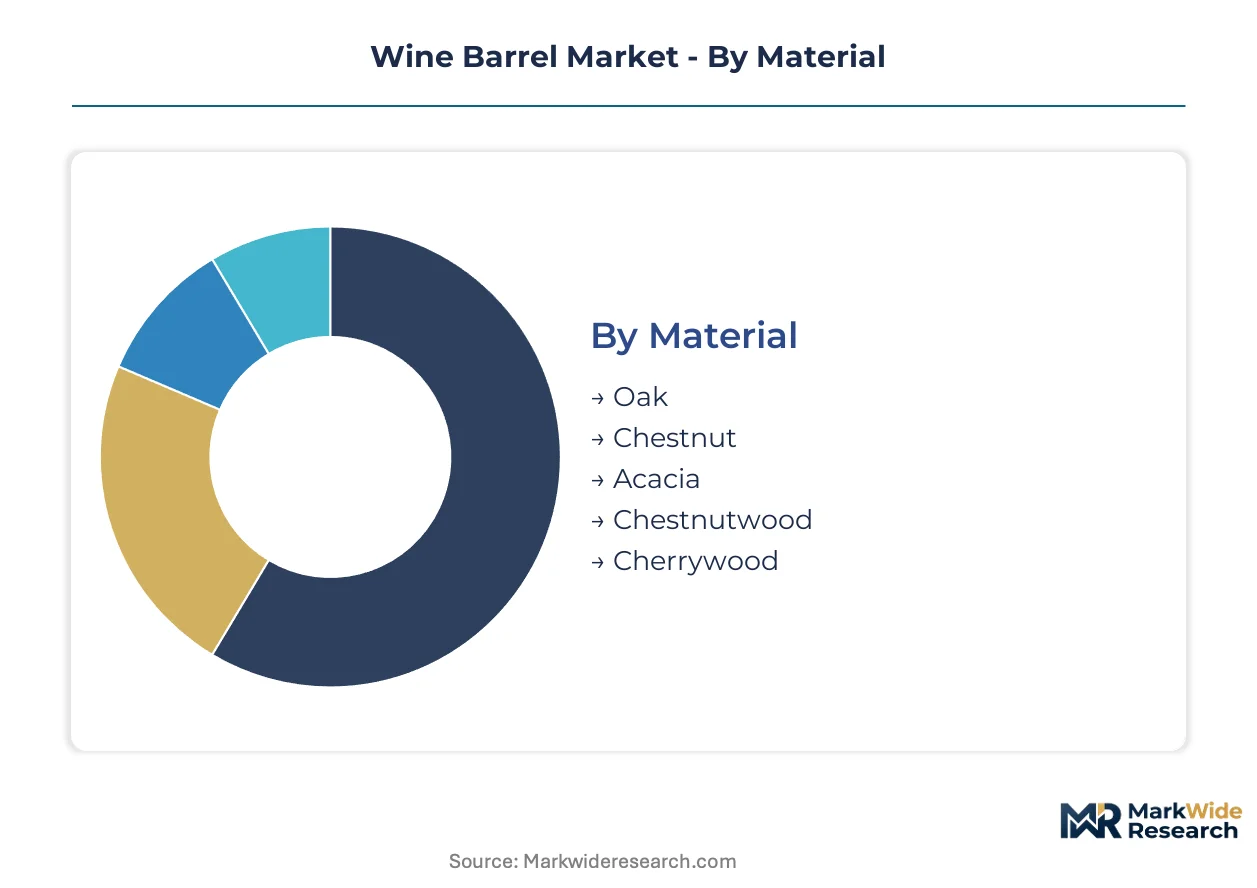
Segmentation within the wine barrel market provides crucial insights into the diverse needs and preferences of end-users, highlighting specific drivers for material selection, capacity requirements, and application-based demand. This detailed breakdown helps coopers and suppliers tailor their offerings and identify niche opportunities across the global viticulture landscape.
Material:
The choice of barrel material significantly impacts the required after-sales support, influencing factors like re-toasting potential, repair frequency, and long-term maintenance protocols for coopers.
- Oak:Traditionally crafted from Quercus species, oak barrels impart complex vanilla, spice, and toast notes to wine, crucial for premium winemaking in Bordeaux, France. Its dense grain and specific chemical compounds are highly valued.
- Acacia:Barrels made from Robinia pseudoacacia wood offer subtle aromatic contributions, often described as floral or nutty, without the strong oak tannins. Experimental winemakers in regions like Alsace use acacia for white wines.
- Chestnut:Chestnut wood provides less intense flavor profiles compared to oak, often used for aging specific traditional spirits or niche wines in parts of Italy.
- Chestnutwood:This material, similar to chestnut, is employed for its neutral influence on wine, allowing the grape's varietal character to remain prominent.
- Cherrywood:Cherrywood barrels are an emerging option, providing delicate fruit and spice notes, appealing to winemakers seeking unique flavor contributions.
Oak holds the largest share; momentum sits with Acacia.
Capacity:
Barrel capacity directly dictates the volume of wine aged per vessel, influencing cellar efficiency, oxidation rates, and overall production scale for wineries.
- 225 Liters:The Bordeaux barrique, standardized at 225 liters, remains the industry benchmark for red and white wine aging, offering a balanced surface-to-volume ratio for controlled oxidation. Wineries globally, from Napa Valley to Barossa, rely on this size for traditional aging.
- 500 Liters:Puncheons, typically 500 liters, provide a slower oxidation rate and less wood influence compared to smaller barrels, favored by winemakers for delicate varietals or extended aging periods in regions like Burgundy.
- 300 Liters:Hogsheads, at 300 liters, offer a compromise between the Bordeaux barrique and larger formats, suitable for specific wine styles requiring moderate wood integration.
- 600 Liters:Demi-muids, or 600-liter barrels, further reduce wood impact and are increasingly used for aging premium white wines or certain red varietals that benefit from minimal oak.
This segment sees 225 Liters dominating, while 500 Liters is expanding most quickly.
Application:
The specific application of wine barrels is determined by the end-user's production goals, whether for alcoholic fermentation or long-term maturation.
- Winemaking:Barrels are integral to the fermentation and initial maturation stages of wine, allowing for micro-oxygenation and the integration of wood compounds. Premium wineries in regions like Tuscany use barrels extensively for their flagship reds.
- Aging:This application focuses on the extended maturation of wine, where the barrel contributes to flavor development, tannin polymerization, and overall structural complexity over months or years. Many cellars in Rioja depend on barrel aging.
- Distilling:While primarily for wine, certain barrel types are also utilized in the distilling industry for aging spirits like whiskey or brandy, imparting distinct flavor profiles.
- Storage:Barrels serve as storage vessels for wine and other beverages, providing protection from light and temperature fluctuations while allowing for slow, controlled evolution.
Winemaking accounts for the largest share, with Aging showing significant growth.
End User:
End-user segments are differentiated by their operational scale and investment capacity, influencing the volume and type of barrels procured.
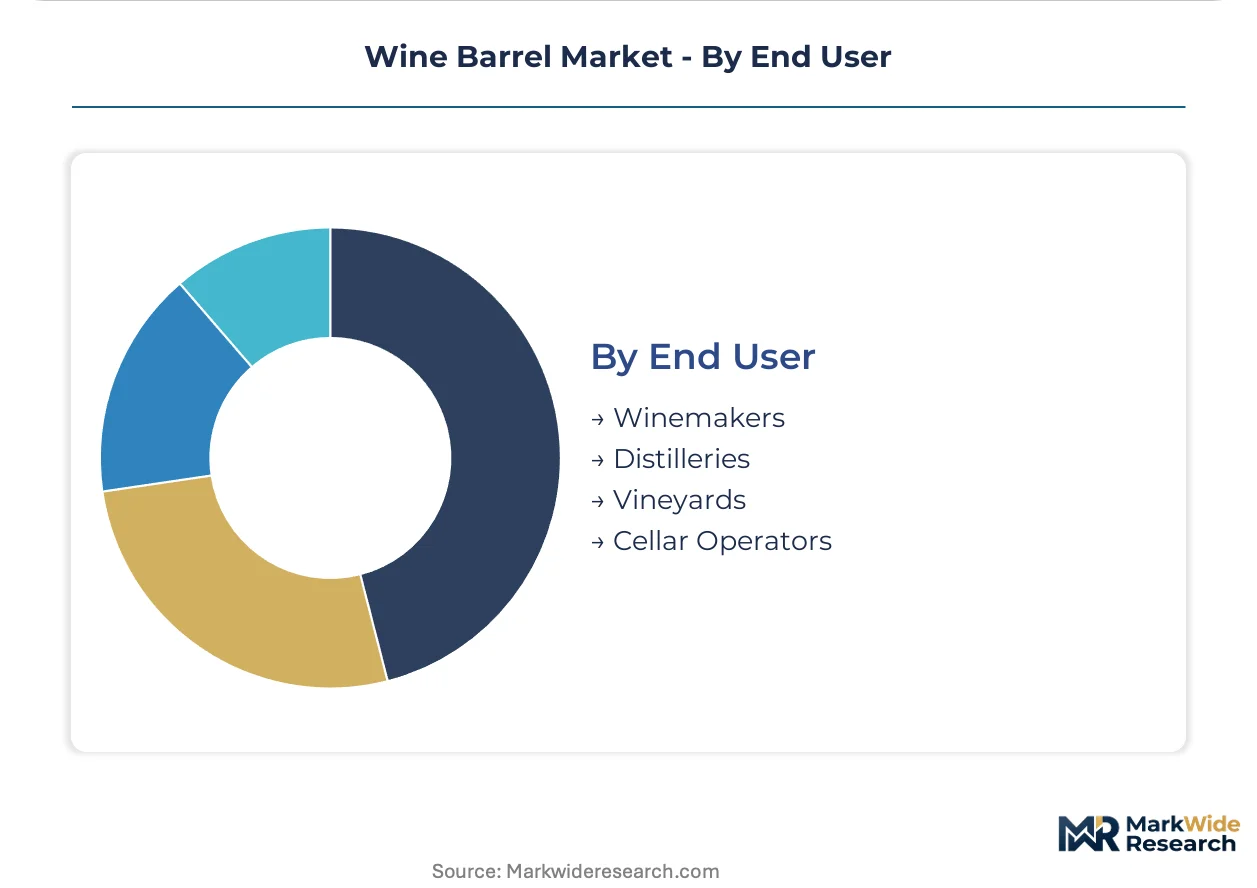
- Winemakers:These are the primary purchasers and users of wine barrels, selecting specific wood types and toast levels to craft their wines and achieve desired sensory profiles. Boutique producers in Oregon's Willamette Valley are key clients.
- Distilleries:While not their primary market, distilleries utilize wine barrels, often previously used, for aging spirits, benefiting from the residual wine characteristics and oak influence. Scotch whisky producers frequently employ ex-sherry or ex-bourbon barrels.
- Vineyards:Many vineyards, especially those with integrated winemaking operations, directly purchase barrels for their estate-bottled wines, ensuring quality control from grape to bottle.
- Cellar Operators:These entities manage wine storage and aging for multiple clients or large-scale operations, requiring a diverse inventory of barrels and expertise in barrel maintenance.
The dominant segment is Winemakers, while Distilleries is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Union's framework (EC) 1935/2004 significantly influences the wine barrel market, particularly through Protected Designation of Origin (PDO) rules. These regulations mandate specific aging periods and barrel types for regional wines, directly affecting demand dynamics. Emerging viticulture zones in the Southern Hemisphere are also driving new demand for quality cooperage products.
France
French regulations surrounding appellation d'origine contrôlée (AOC) often specify barrel aging requirements, sustaining demand for traditional oak. Premium winemakers in regions like Bordeaux consistently seek barrels that impart specific terroir characteristics. Cooperages in central France, particularly in areas like Burgundy, remain centers for high-quality oak barrel production and innovation.
United States
The US FDA governs food contact materials, ensuring the safety of wine barrels used by American wineries. Winemakers in California's Napa Valley and Oregon's Willamette Valley drive demand for both traditional French oak and innovative American oak profiles. Investment in digital toasting technologies by coopers located near major wine regions supports precise flavor control.
Italy
Italian DOCG (Denominazione di Origine Controllata e Garantita) rules often dictate barrel usage, preserving the character of wines from regions like Chianti Classico. Winemakers in Tuscany and Piedmont utilize diverse barrel sizes and wood types for their acclaimed red and white wines. Traditional cooperages in northern Italy continue to supply both domestic and international markets.
Argentina
Argentina's National Institute of Viticulture (INV) oversees winemaking practices, including barrel aging standards. The Mendoza region experiences substantial demand for wine barrels as its premium wine production expands. New cooperage investments and partnerships with international suppliers are common in this rapidly growing viticulture hub.
Hungary
Hungarian food safety regulations align with EU standards for wood products in contact with food. New cooperage investments in regions like Tokaj are expanding the supply of high-quality Eastern European oak. This diversification provides alternatives to traditional French sources, appealing to winemakers seeking cost-effective yet quality barrels.
Wine Barrel Market Key Industry Players
Specialized cooperage houses and diversified wood product manufacturers split the market for wine barrels. This structure includes both artisanal producers focused on traditional craftsmanship and larger entities leveraging technological advancements. Major competitive moves involve strategic partnerships with wineries and continuous innovation in wood science to achieve product differentiation.
Within the specialized cooperage segment, Tonnellerie François Frères Group leverages its extensive forest holdings to ensure a consistent supply of premium oak. Independent Stave Company occupies a position as a leader in wood science research, developing precise toasting profiles. Oeneo SA, a diversified French company, competes globally with a broad portfolio that includes both traditional barrels and alternative oak products.
| Leading Market Players |
|---|
| Canton Cooperage |
| Nadalie |
| Oeneo SA |
| Bouchard Cooperages |
| World Cooperage |
| Tonnellerie François Frères Group |
| Seguin Moreau Napa Cooperage |
| Kelvin Cooperage |
| Independent Stave Company |
| Others |
Cost & Logistics Intelligence
Transatlantic shipping lanes, a critical component for wine barrel logistics, introduce significant cost dynamics that influence both supply concentration and downstream price differentiation. Premium French oak barrels incur substantial freight charges when exported to Southern Hemisphere viticulture zones.
Pricing Analysis
French oak barrels command premium pricing globally, reflecting their historical prestige and specific terroir influence. The dominant pricing model remains per-unit transactional, though long-term contracts secure supply for large wineries. Price differentiation stems from wood origin, cooperage brand reputation, and the precision offered by digital toasting technologies. Pricing softness reflects increasing competition from cost-effective alternative oak products. Entry-level and mid-tier wineries exhibit higher price sensitivity compared to premium winemakers.
Supply Chain Analysis
European Union's framework (EC) 1935/2004, governing food contact materials, influences the sourcing and processing of wood for wine barrels. Geographic supply concentrates in France, the United States, and emerging Eastern European countries like Hungary. The supply chain relies heavily on high-quality oak wood (Quercus species), which requires years of seasoning. A structural risk is the finite supply of old-growth oak trees, creating a natural production ceiling. Distribution runs primarily through direct sales channels from cooperages to wineries globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wine barrel market is experiencing a high-growth disruption, driven by innovations in digital toasting technologies that offer unprecedented flavor control.
For Market Incumbents: Pre-empt market share erosion by investing heavily in advanced digital toasting research and development. Diversify oak sourcing to include high-quality Eastern European forests, reducing reliance on costly French oak. Consider strategic partnerships or acquisitions of smaller cooperages specializing in alternative wood types to mitigate the threat from substitution. Enhance after-sales support with barrel refurbishment services.
For New Entrants and Emerging Players: Cooler climate wine regions like England and Canada's Niagara Peninsula represent a significant geographic underpenetration. Target experimental winemakers seeking novel flavor profiles with niche woods such as Acacia and Chestnut. Develop flexible barrel leasing and rental programs to appeal to capital-sensitive boutique producers. Focus on sustainable practices and certified reuse programs as a go-to-market angle.
For Investors and Strategic Acquirers: Specialized cooperages with proprietary digital toasting intellectual property offer compelling long-term viability within the premium wine segment. These firms benefit from sustained demand for precise flavor control and product differentiation. A key signal to watch is the adoption rate of barrel leasing programs by established wineries, indicating a shift towards service-oriented models.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Digital Toasting R&D | This initiative enables coopers to offer highly differentiated products with precise flavor control for winemakers. |
| Expand Eastern European Oak Sourcing | Diversifying oak supply beyond traditional French forests provides cost-effective alternatives and reduces input volatility. |
| Develop Barrel Leasing Programs | Offering flexible financial models addresses capital outlay constraints for wineries and creates new revenue streams for coopers. |
| Offer Alternative Wood Barrel Lines | Introducing Acacia and Chestnut barrels caters to experimental winemakers seeking unique flavor contributions. |
| Establish Barrel Refurbishment Services | This service supports circular economy principles and provides cost management solutions for wineries. |
Research Approach
A spread of perspectives from winemakers, cooperage executives, forestry managers, and wine distributors converged on the working assumptions for this study. Primary interviews with industry stakeholders were validated against secondary data from regulatory bodies like the US FDA and the European Union's (EC) 1935/2004 framework, alongside industry association reports. A robust bottom-up and top-down triangulation approach ensured comprehensive market sizing.
The forecast framework analyzed demand-supply balance across the modeling period, segmenting the market by material, capacity, application, end user, and regional viticulture trends. Compound annual growth rates were derived by assessing historical trends and projected shifts in premium wine consumption and technological adoption. Global wine production volumes and premium wine consumption trends served as key industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large cooperage groups or alternative oak product manufacturers would shift outcomes. These projections reflect current market dynamics and regulatory landscapes. Material shifts in global trade policies or raw material availability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Mexico Tequila Market
Alcoholic Beverages
Premixed Margarita Market
Alcoholic Beverages
Australia Alcohol E-Commerce Market
Alcoholic Beverages
Single Serve Wine Market
Alcoholic Beverages
Wine Bags Market
Alcoholic Beverages
Global Wine Coolers Market
Alcoholic Beverages
Alcohol-Free Pineapple Beer Market
Alcoholic Beverages
Premium Spirit Market
Alcoholic Beverages
Middle East and Africa Kegs Market
Alcoholic Beverages
North America Soju Market
Alcoholic Beverages
Wine Cellar Market
Alcoholic Beverages
Microbrewery Supplies Market
Alcoholic Beverages
Gluten Free Alcoholic Drinks Market
Alcoholic Beverages
Global Beer Market
Alcoholic Beverages
Roasted Malt Market
Alcoholic Beverages
United States Spirits Market