
 North America Alcoholic Beverages Market | 2026-2036
North America Alcoholic Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
North America Alcoholic Beverages Market Analytics
Premiumization is bifurcating the North America alcoholic beverages landscape into distinct value strata. Anheuser-Busch InBev leverages its massive brewing infrastructure to dominate economy and mainstream lager segments across Mexico and the United States. Constellation Brands, Inc. anchors its portfolio in high-margin imported beer and premium wine, competing aggressively in the above-premium tier where consumer willingness to trade up remains resilient.
Alcoholic beverages comprise ethanol-containing drinks produced through fermentation of sugars by yeast or distillation, typically containing between 0.5% and 95% alcohol by volume depending on category and production method. These products serve commercial purposes spanning social consumption, food pairing, ceremonial use, and relaxation across on-premise and off-premise channels. Spirits commands the fastest expansion within product type segmentation as whiskey, tequila, and ready-to-drink cocktails attract younger demographics seeking flavor complexity and convenience. Cans within packaging type represents the structural growth vector, displacing glass bottles in outdoor and event-oriented consumption occasions while reducing shipping weight and breakage costs for distributors.
The Alcohol and Tobacco Tax and Trade Bureau enforces strict labeling, formula approval, and tax stamp requirements that shape product development timelines and market access costs for new entrants. State-level control boards in Pennsylvania and Utah maintain monopoly wholesale or retail structures that constrain distribution flexibility and inflate compliance overhead. The Food and Drug Administration oversees ingredient safety and allergen disclosure under the Food Safety Modernization Act, pressing manufacturers toward cleaner label formulations. Stakeholders must monitor evolving cannabis-alcohol crossover regulations and state-by-state direct-to-consumer shipping permissions that could redraw competitive boundaries without warning.
Market Dynamics
Premiumization is fragmenting the North American alcoholic beverages market into distinct value strata, as millennial consumers trade up toward craft spirits and ready-to-drink cocktails while legacy beer volumes stagnate in economy tiers. The Alcohol and Tobacco Tax and Trade Bureau's tightening labeling mandates are compressing product development timelines, forcing reformulation investments that favor scaled operators with dedicated compliance infrastructure.
Growth Catalysts
- Ready-to-drink cocktail expansion:Canned spirits-based beverages are capturing outdoor and event-oriented consumption occasions from traditional beer, with younger demographics driving trial velocity through convenience-store channels.
- State-level direct-to-consumer shipping liberalization:Easing restrictions in California, Texas, and Florida are enabling winery and distillery bypass of wholesale monopolies, opening incremental revenue streams.
- Tequila agave maturation cycles:Seven-to-ten-year cultivation timelines are creating scarcity premiums that support above-premium pricing architecture across the spirits category.
Market Restraints
- Glass supply concentration:Domestic container manufacturing capacity constraints in Mexico and the United States are elevating input costs and extending lead times for premium bottled products.
- Three-tier distribution lock-in:State control boards in Pennsylvania and Utah maintain monopoly wholesale structures that inflate compliance overhead and constrain route-to-market flexibility for new entrants.
- Cannabis substitution pressure:Legal recreational markets in California and Canada are diverting discretionary spending from alcohol among younger legal-age consumers.
Strategic Opportunities
- Florida on-premise recovery:Restaurant and bar reopening velocity in Miami and Orlando markets is outpacing national benchmarks, creating outsized volume capture potential for draft and by-the-glass programs.
- Non-alcoholic adjacent formulations:Functional beverages with adaptogens and nootropics are opening shelf-space negotiations with retailers seeking health-positioned alternatives.
- TTB formula approval digitization:Pending modernizations to the Alcohol and Tobacco Tax and Trade Bureau's COLA Online system could compress new product launch timelines from months to weeks.
Industry Challenges
- Master distiller talent scarcity:Specialized fermentation and aging expertise is concentrating at established producers, elevating compensation costs for craft-scale operations seeking credentialled production leadership.
- Legacy distributor integration:ERP system harmonization between acquired craft brands and parent-company wholesaler networks is delaying promotional execution and depleting working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Alcoholic Beverages Market |
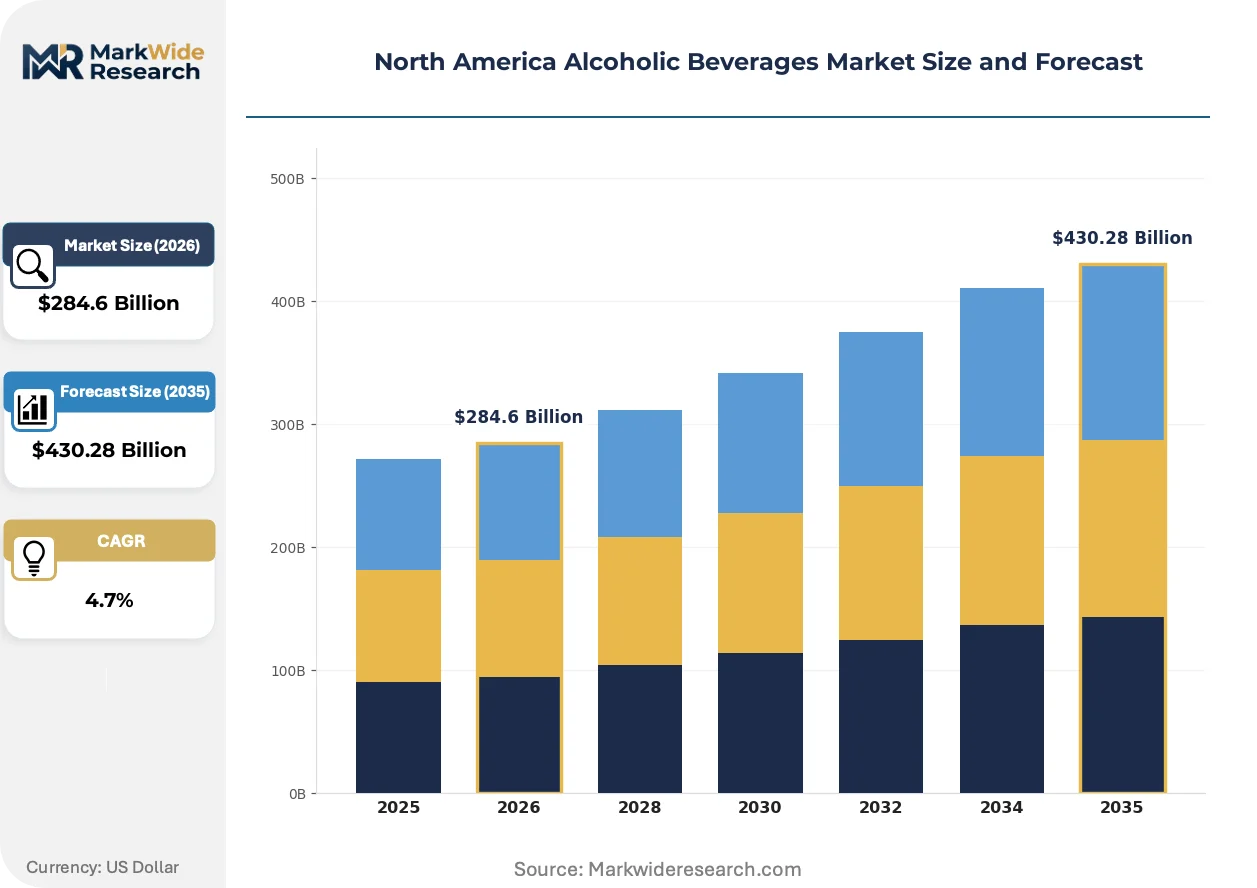
| Market Size in 2026 | $284.6 Billion |
| Market Size in 2035 | $430.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beer, Wine, Spirits, Cider Distribution Channel: Retail, Online, Supermarkets, Convenience Stores Packaging Type: Bottles, Cans, Kegs, Pouches Consumer Type: Women, Men, Millennials, Seniors |
| Companies Covered | Anheuser-Busch InBev, Constellation Brands, Inc., Molson Coors Beverage Company, Diageo PLC, Heineken NV, Pernod Ricard, Bacardi Limited, Brown-Forman Corporation, Suntory Global Spirits, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Alcoholic Beverages Market Evolving Landscape
Technology and regulatory pressure are converging to reshape how alcoholic beverages are formulated, packaged, and brought to market across North America. Three distinct vectors are compressing traditional competitive advantages while opening white space for agile operators.
Aluminum can lining technology is fragmenting the packaging hierarchy that has dominated spirits for generations. Barrier coatings now prevent flavor scalping and aluminum interaction, enabling 100% spirit-based products in single-serve formats. Millennials and Gen Z consumers are adopting these formats for beach, festival, and outdoor dining occasions at triple-digit velocity. The structural consequence is compressing glass bottle demand in above-premium tiers while elevating contract canning capacity scarcity.
The Alcohol and Tobacco Tax and Trade Bureau's updated labeling requirements for allergen and ingredient disclosure are forcing reformulation cycles across the industry. Manufacturers must now submit expanded formula documentation and await extended review periods before market release. Small-batch spirits and imported wine categories are most affected, with producers accelerating clean-label investments and building dedicated regulatory affairs functions to maintain launch cadence.
Consumer purchasing is rotating toward subscription and curated delivery models that bypass traditional retail discovery. Digital-native wine clubs and spirits discovery platforms are capturing trial budgets that previously flowed through liquor store browsing. California and New York urban markets exhibit the highest penetration of these models, where same-day delivery infrastructure and licensed courier networks enable impulse replacement of on-premise consumption occasions.
North America Alcoholic Beverages Market Segmentation
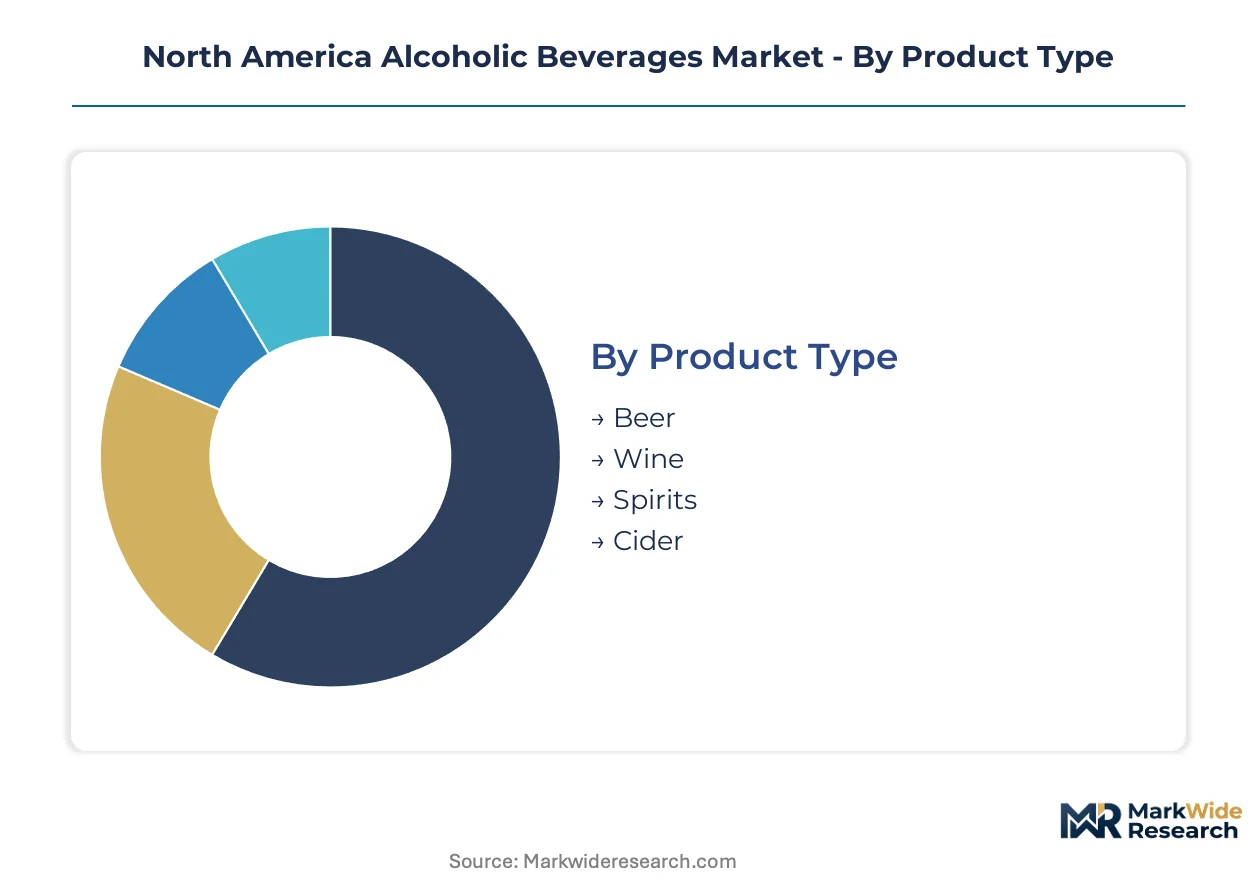
Channel mix dynamics in North American alcoholic beverages diverge sharply by segment velocity and margin structure. Spirits and ready-to-drink formats concentrate in convenience and e-commerce channels, while beer and wine retain stronger supermarket and on-premise penetration. Understanding these flow patterns enables targeted inventory placement and promotional spend allocation.
Product Type:
Retail and on-premise channels handle divergent product mixes based on consumption occasion and margin profile. Supermarkets dominate beer volume, while spirits concentrate in dedicated liquor stores and bars where staff guidance drives premium selection.
- Beer:Fermented grain beverages typically containing 4-6% alcohol by volume, spanning lager, ale, and stout styles. Volume concentrates in Texas, California, and Florida where sports-venue consumption and casual dining recovery outpace national benchmarks. Input cost pressure from malted barley and aluminum can sourcing compresses mainstream-tier margins.
- Spirits:Distilled ethanol products ranging from 20% to 95% alcohol by volume, including whiskey, vodka, tequila, and gin. Demand clusters in above-premium tiers across Miami, Los Angeles, and New York metro areas where cocktail culture and mixology programs elevate trade-up willingness. TTB formula approval timelines constrain new product velocity.
- Wine:Fermented grape products spanning still, sparkling, and fortified categories. California and New York urban markets exhibit strongest direct-to-consumer shipping adoption, bypassing traditional wholesale tiers.
- Cider:Fermented apple or pear-based beverages typically 4-8% alcohol by volume. Pacific Northwest and Northeast regional markets sustain craft-scale production clusters.
By volume, beer leads. By growth pace, spirits is ahead.
Distribution Channel:
Margin structures and regulatory compliance burdens vary dramatically across channel types, shaping where new entrants concentrate launch resources.
- Retail:Dedicated liquor stores and beverage alcohol retailers operating under state-specific licensing regimes. Pennsylvania and Utah state control board monopolies constrain independent operator participation and elevate compliance overhead.
- Online:Direct-to-consumer shipping platforms and third-party delivery services. California, Texas, and Florida liberalization trends are opening incremental revenue streams for wineries and distilleries bypassing wholesale tiers.
- Supermarkets:Grocery and hypermarket chains with beverage alcohol licenses. Beer and wine dominate shelf space allocation, with spirits penetration limited by state-level restrictions.
- Convenience Stores:Small-format retailers emphasizing single-serve and immediate consumption occasions. Ready-to-drink cocktails and premium beer in cans are gaining space allocation from traditional glass-bottle formats.
Supermarkets capture the highest absolute volume. Online channels are expanding most quickly.
Packaging Type:
Shipping economics and consumption occasion requirements dictate packaging selection across product categories and price tiers.
- Bottles:Glass containers dominating wine and premium spirits presentation. Domestic manufacturing capacity constraints in Mexico and the United States are extending lead times and elevating input costs for above-premium bottled products.
- Cans:Aluminum single-serve formats displacing glass in beer and ready-to-drink spirits. Outdoor and festival-oriented consumption occasions in California and Florida markets are driving triple-digit velocity for canned cocktails.
- Kegs:Stainless steel returnable containers for draft beer and cider. On-premise recovery in Miami and Orlando is accelerating keg demand for bar and restaurant programs.
- Pouches:Flexible film packaging for wine and ready-to-drink beverages. Camping and outdoor recreation markets in Pacific Northwest and Mountain West regions sustain niche adoption.
Bottles retain the highest value per unit. Cans are gaining share fastest.
Consumer Type:
Demographic targeting shapes formulation, packaging, and channel strategies with distinct engagement patterns across age and gender cohorts.
- Millennials:Consumers aged approximately 28-43 driving premiumization and craft discovery. Flavor complexity preferences and convenience-seeking behavior concentrate demand in ready-to-drink cocktails and above-premium spirits across urban coastal markets.
- Women:Female purchasers exhibiting stronger wine and spirits preference relative to beer, with above-average responsiveness to lower-calorie and lower-alcohol formulations. Rose wine and vodka-based ready-to-drink products capture disproportionate share.
- Men:Male consumers sustaining beer category volume, with whiskey and tequila gaining traction in spirits migration. Sports-venue and casual dining occasions retain stronger male skew.
- Seniors:Consumers aged 65+ maintaining established brand loyalties and traditional wine consumption patterns. Direct-to-consumer subscription models capture trial-resistant segments in established markets.
Men generate the highest per-capita volume. Millennials show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across North American markets. Canadian and Mexican consumers exhibit greater price sensitivity in economy beer tiers, while US coastal metros sustain premium-spirits trade-up with minimal volume loss to price increases.
United States
California, Texas, and Florida concentrate on-premise recovery velocity as Miami and Orlando restaurant reopenings outpace national benchmarks. The Alcohol and Tobacco Tax and Trade Bureau enforces tightening ingredient disclosure standards that compress product development timelines. Los Angeles and New York metro areas anchor above-premium spirits demand where cocktail culture elevates mixology-program adoption.
Canada
Provincial liquor board monopolies in Ontario and Quebec constrain distribution flexibility while sustaining price premiums through controlled retail channels. Health Canada oversees ingredient safety and allergen disclosure under the Food and Drugs Act, pressing manufacturers toward cleaner label formulations. British Columbia's craft distillery cluster in Vancouver and Victoria sustains small-batch production growth despite regulatory overhead.
Mexico
Jalisco's tequila agave cultivation cycles create seven-to-ten-year scarcity premiums that support above-premium pricing architecture across export markets. The country's federal consumer protection agency enforces labeling standards that align with US TTB requirements for cross-border shipments. Mexico City and Monterrey concentrate domestic consumption recovery and premium beer demand growth.
California
Direct-to-consumer shipping liberalization enables winery and distillery bypass of wholesale tiers, opening incremental revenue streams for premium producers. State-level cannabis legalization diverts discretionary spending among younger legal-age consumers, pressuring alcohol volume in urban coastal markets. San Francisco and Los Angeles sustain the highest penetration of subscription-based wine clubs and spirits discovery platforms.
Florida
Outdoor and event-oriented consumption occasions drive triple-digit velocity for canned ready-to-drink cocktails across Miami and Orlando markets. State-level regulatory frameworks permit broader retail licensing than Pennsylvania or Utah control-board structures. Tampa and Jacksonville support expanding craft brewery and distillery footprints as tourism recovery accelerates on-premise draft demand.
North America Alcoholic Beverages Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North American alcoholic beverages market. Mass-scale brewing infrastructure dominates economy and mainstream lager segments, while craft-scale distillation and specialty fermentation command premium-tier margins. Three strategic archetypes define competitive positioning: multinational brewers with integrated continental distribution, spirits-focused houses with aged-inventory depth, and regional craft operators with localized brand equity. Consolidation through acquisition and portfolio diversification into adjacent ready-to-drink formats constitute the dominant competitive moves reshaping market structure.
Within the multinational brewer archetype, Anheuser-Busch InBev and Molson Coors Beverage Company occupy positions defined by massive North American brewing infrastructure and route-to-market density. Among spirits-focused competitors, Diageo PLC exemplifies the aged-inventory house with diversified whiskey, tequila, and vodka holdings. Constellation Brands, Inc. represents the premium-import specialist with above-tier beer and wine concentration. These three anchors illustrate how scale, category focus, and geographic origin stratify competitive positioning without requiring specific product or financial claims.
| Leading Market Players |
|---|
| Anheuser-Busch InBev |
| Constellation Brands, Inc. |
| Molson Coors Beverage Company |
| Diageo PLC |
| Heineken NV |
| Pernod Ricard |
| Bacardi Limited |
| Brown-Forman Corporation |
| Suntory Global Spirits |
| Others |
Value Network & Pricing Analysis
TTB formula approval timelines gate both production scale-up and price-tier entry simultaneously. Extended review periods compress margins for small-batch spirits while favoring scaled operators with dedicated compliance infrastructure that can amortize regulatory costs across volume tiers.
Pricing Analysis
After-sales revenue through direct-to-consumer subscription models drives lifetime value capture for premium wineries and craft distilleries. Three-tier pricing structure across premium, standard, and economy levels separates allocated bourbon from mass-market vodka from private-label spirits. Cost compression in aluminum can sourcing is intensifying because beverage-grade container manufacturing concentrates in domestic facilities with limited expansion capacity. Convenience-store buyers exhibit highest price sensitivity, while mixology-program operators at coastal urban venues absorb premium markups with minimal volume elasticity.
Supply Chain Analysis
Strategic stockpiling of aged whiskey inventory dominates spirits production planning against just-in-time freshness requirements for beer. Agave cultivation in Mexico, barley farming in Canada, and corn production in the United States anchor raw material sourcing for tequila, craft beer, and bourbon respectively. Glass bottle manufacturing capacity constraints in Mexico and the United States create single-source vulnerability for premium bottled products. Distribution runs through state-controlled wholesale monopolies in Pennsylvania and Utah alongside independent distributor networks in California and Texas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ready-to-drink cocktail canning technology disruption is accelerating category expansion beyond traditional spirits packaging constraints. TTB labeling modernization pending in federal rulemaking creates regulatory inflection that will compress launch timelines for agile operators.
For Market Incumbents: Shield aged-spirits inventory depth against tequila agave scarcity cycles by securing long-term agricultural contracts in Jalisco. Vertical integration into aluminum can lining technology protects against contract canning capacity bottlenecks. Constellation Brands and Diageo PLC possess compliance infrastructure scale that TTB digitization will amplify disproportionately.
For New Entrants and Emerging Players: COLA Online fast-track certification for ready-to-drink formulations opens shelf-space negotiations with convenience retailers seeking canned cocktail innovation. Florida on-premise recovery velocity presents the most penetrable geography for draft and by-the-glass program entry. Direct-to-consumer shipping liberalization in California enables bypass of wholesale tier markups through subscription model launches.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed craft distillery aggregators holding fragmented regional brand portfolios across Pacific Northwest and Mountain West clusters. Five-to-ten year viability hinges on distributor integration completion and ERP harmonization with parent-company wholesaler networks. Watch for TTB formula approval digitization implementation as inflection signal that will compress new product launch timelines from months to weeks.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Shipping Expansion | California and Florida regulatory liberalization enables winery and distillery bypass of wholesale monopolies. |
| Aluminum Can Production Investment | Barrier coating technology unlocks 100% spirit-based single-serve formats for outdoor consumption occasions. |
| Craft Distillery Acquisition | Consolidation captures aged-inventory depth and master distiller talent concentrated at regional operators. |
| Subscription Platform Launch | Digital-native wine clubs capture trial budgets shifting from liquor store browsing in urban coastal markets. |
| Clean-Label Reformulation | TTB allergen disclosure mandates force ingredient transparency investments that favor scaled compliance infrastructure. |
Research Methodology
The analysis maps spirits, beer, wine, and ready-to-drink sub-sectors, each validated through master distillers, brewery operations directors, state control board administrators, and convenience-store category buyers. Bottom-up triangulation combines primary fieldwork with secondary validation against TTB formula approval databases, state liquor board procurement records, Nielsen retail audit data, and customs import filings for agave and malted barley.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, packaging format, distribution channel, and consumer demographic cohort. CAGRs were derived from trend extrapolation anchored in historical consumption patterns and regulatory shift assumptions. Forecast inputs incorporated tequila agave maturation cycles and aluminum can manufacturing capacity constraints.
Underlying assumptions cover on-premise consumption recovery velocity, direct-to-consumer shipping liberalization continuation, and TTB digitization implementation pace, with deviation risk concentrated in cannabis substitution trends and glass supply concentration. Revision becomes warranted when state-level regulatory frameworks cross threshold shifts in distribution tier access or formula approval timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Mexico Tequila Market
Alcoholic Beverages
Saffron Beer Market
Alcoholic Beverages
Beer Dispensing Machine Market
Alcoholic Beverages
Rose Wine Market
Alcoholic Beverages
Industrial Alcohol Market
Alcoholic Beverages
Fermented Beverages Market
Alcoholic Beverages
Asia-Pacific Kegs Market
Alcoholic Beverages
Canned Cocktails Market
Alcoholic Beverages
Beer Filter System Market
Alcoholic Beverages
Global Food-Grade Alcohol Market
Alcoholic Beverages
US Wine Market
Alcoholic Beverages
Wine Aerator Market
Alcoholic Beverages
Oak Barrel Alternatives Market
Alcoholic Beverages
Low-Alcohol Beer Market
Alcoholic Beverages
Cocktail Mixers Market
Alcoholic Beverages
Mead Beverage Market