
 North America Soju Market | 2026-2036
North America Soju Market Size, Share, and Industry Trends Forecast 2026-2036
North America Soju Market Outlook
TTB labeling and formula approval requirements for distilled spirits is recalibrating the cost-of-entry calculus for soju importers seeking to position flavored variants alongside traditional clear expressions. HiteJinro Co., Ltd. anchors its North American presence through established distribution partnerships with major beverage wholesalers. Lotte Chilsung Beverage Co. competes by extending its portfolio into fruit-infused soju formats tailored to younger palates. Chamisul Soju differentiates through premium positioning and sustained brand recognition among Korean-American consumers.
Soju denotes a Korean distilled spirit traditionally produced from rice, wheat, or barley with alcohol content typically ranging from 16% to 25% ABV, though modern industrial production often employs neutral grain spirits diluted with water and sweeteners. Its primary commercial purpose centers on social consumption occasions, from casual dining to nightlife venues, where lower alcohol intensity relative to whiskey or vodka supports extended session drinking. Flavored soju commands the fastest expansion trajectory as fruit-forward formulations attract entry-level drinkers, while clear soju maintains volume leadership through established Korean restaurant channels. Premium soju captures concentrated margin pools among consumers seeking artisanal, small-batch alternatives with provenance narratives.
The Alcohol and Tobacco Tax and Trade Bureau governs federal import permits, formula approvals, and COLA certification for all soju distributed in the United States, creating compliance bottlenecks that favor established importers with dedicated regulatory staff. State-level ABC boards in California, New York, and Texas impose additional licensing tiers that fragment market access and elevate working capital requirements for new entrants. Stakeholders must monitor evolving state-level ready-to-drink classification debates that could reclassify lower-ABV soju variants outside traditional spirits tax schedules.
Market Dynamics
The Alcohol and Tobacco Tax and Trade Bureau's COLA certification bottleneck is fragmenting competitive access, forcing importers to choose between capital-heavy compliance infrastructure or wholesale partnership dependency.
Growth Catalysts
- TTB Formula Approval Pathway:Established importers leveraging dedicated regulatory staff convert federal compliance into a scalable moat against undercapitalized entrants seeking flavored soju positioning.
- California Korean Diaspora Density:Los Angeles and Orange County restaurant clusters generate concentrated baseline demand that subsidizes expansion into adjacent metropolitan cocktail programs.
- Ready-to-Drink Reclassification Debates:State-level ABC board discussions around lower-ABV tax scheduling create potential margin relief for soju variants positioned outside traditional spirits brackets.
Market Restraints
- Neutral Grain Spirit Input Volatility:Industrial soju production's dependence on commodity ethanol exposes margin structures to energy-linked feedstock price swings.
- Federal Compliance Capital Intensity:TTB permit maintenance and formula approval timelines demand six-figure working capital reserves that exclude bootstrapped importers.
- Hard Seltzer Substitution Pressure:Fruit-forward soju competes directly with malt-based alternatives occupying identical lower-ABV, session-drinking occasions.
Strategic Opportunities
- Texas ABC Board Licensing Expansion:Underpenetrated Dallas and Houston on-premise channels offer first-mover positioning before Korean restaurant density reaches California saturation levels.
- Artisanal Rice Fermentation Revival:Premium small-batch producers leveraging heritage grain provenance narratives capture margin pools above industrial soju price floors.
- Direct-to-Retailer E-Commerce Channels:Post-pandemic beverage alcohol delivery frameworks enable bypass of traditional three-tier distribution gatekeepers in permissive jurisdictions.
Industry Challenges
- Flavor Chemist Talent Scarcity:Formulation expertise bridging Korean palate preferences with American fruit-forward expectations concentrates among a handful of specialized consultants.
- Multi-State Licensing Synchronization:California, New York, and Texas ABC board reciprocity gaps force parallel application tracks that compress cash conversion cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Soju Market |
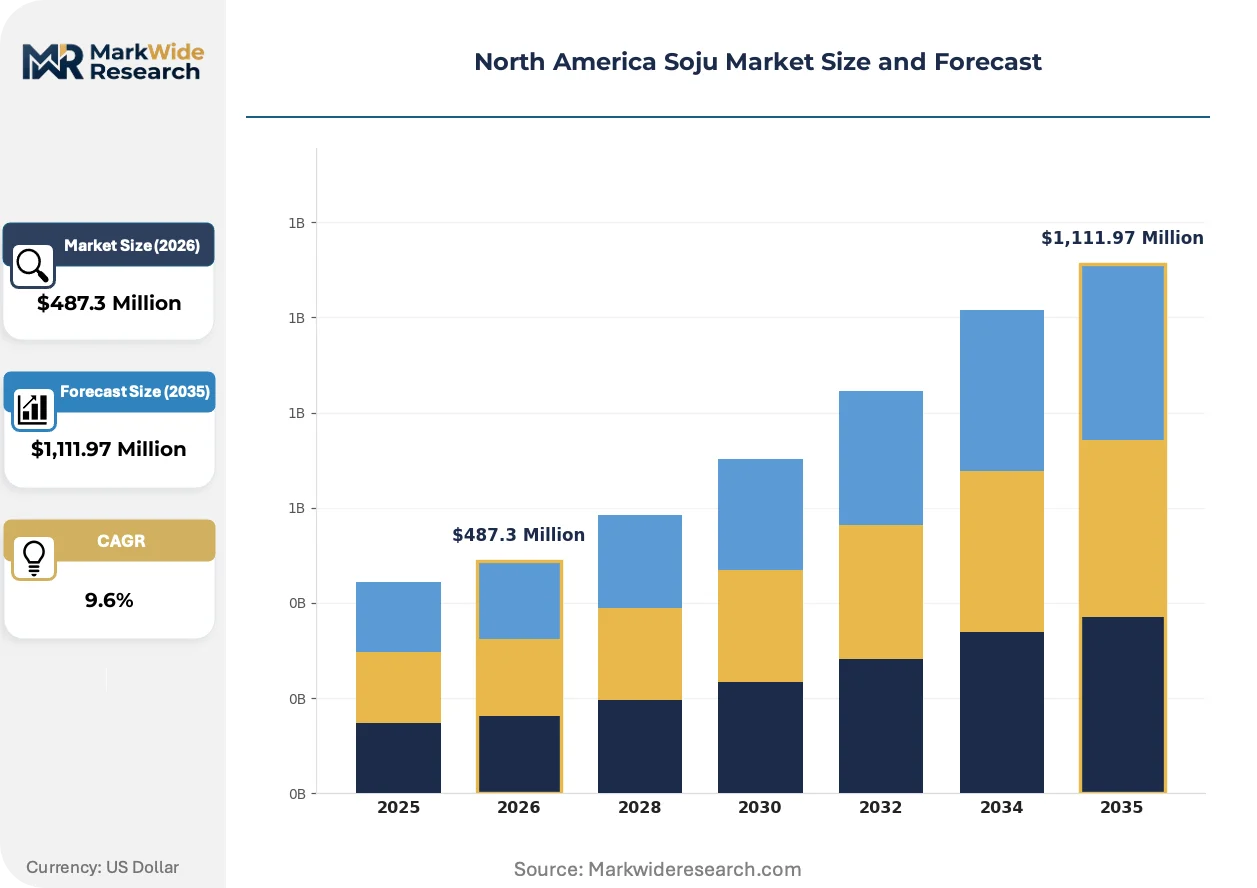
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,111.97 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Soju, Flavored Soju, Premium Soju, Organic Soju Packaging Type: Glass Bottles, PET Bottles, Tetra Packs, Cans Distribution Channel: Supermarkets, Online Retail, Restaurants, Specialty Stores End User: Consumers, Bars, Clubs, Events |
| Companies Covered | Chamisul Soju, Jeju Soju, HiteJinro Co., Ltd., C1 Soju, Muhak, Lotte Chilsung Beverage Co., Andong Soju, Hwayo, Charm Soju, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Soju Market Strategic Shifts
Product architecture and regulatory navigation are converging to reshape how soju penetrates beyond Korean restaurant anchor channels into mainstream beverage occasions.
Continuous fermentation monitoring systems is modularizing production scalability for mid-tier distillers seeking consistency across batch-scale flavor soju runs. California craft producers are adopting these platforms fastest, compressing quality assurance timelines from weeks to days. The technology is modularizing capital deployment, enabling smaller entrants to achieve industrial-grade output without legacy infrastructure investments.
The TTB's evolving stance on soju-adjacent product classification is forcing importers to pre-emptively bifurcate their portfolios between traditional spirits permits and potential ready-to-drink reclassification pathways. This regulatory uncertainty elevates legal counsel costs but also creates first-mover advantage for firms securing dual-track approvals. Flavored variants in the 12-16% ABV range face the most acute compliance recalibration pressure.
Younger consumers in Los Angeles and New York are rotating toward lower-ABV session formats that displace vodka and whiskey in group dining contexts. Korean-American restaurants are responding by unbundling soju from fixed menu pairings into à la carte cocktail program components. This behavioral pivot is most visible in Manhattan's Koreatown and Los Angeles' Koreatown-adjacent nightlife corridors.
North America Soju Market Segmentation
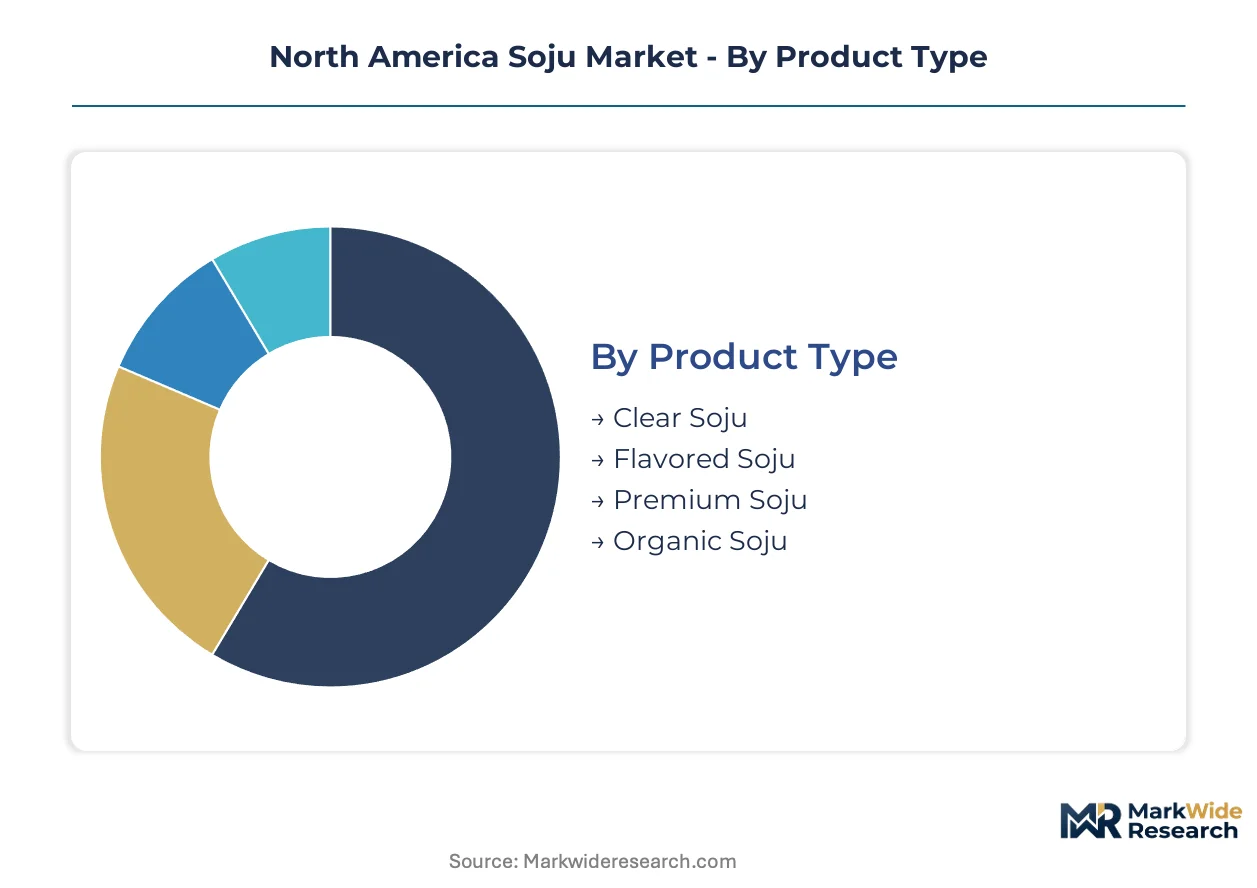
Soju's penetration beyond Korean restaurant channels demands granular segment targeting. Product architecture and packaging format choices determine whether brands capture session-drinking occasions or premium gifting markets.
Product Type:
Production infrastructure concentrates around industrial clear soju facilities, while flavor formulation capabilities fragment across smaller craft distillers.
- Clear Soju:Traditional unflavored expression distilled from rice, wheat, or neutral grain spirits at 16-20% ABV. Korean restaurants in Los Angeles and Orange County generate baseline volume that subsidizes expansion into mainstream cocktail programs.
- Flavored Soju:Fruit-infused variants at 12-16% ABV targeting entry-level drinkers with peach, grapefruit, and green apple profiles. Younger consumers in Manhattan Koreatown rotate toward these lower-ABV formats for extended social occasions.
- Premium Soju:Small-batch rice fermentation with provenance narratives and artisanal positioning.
- Organic Soju:Certified organic grain inputs appealing to health-conscious segments in California.
Today's leader: Clear Soju. Tomorrow's challenger: Flavored Soju.
Packaging Type:
Cost tier differentiation separates on-premise glass presentation from off-premise convenience formats.
- Glass Bottles:Premium 375ml and 750ml formats dominate Korean restaurant table service and craft cocktail bar programs. Los Angeles mixologists specify these for soju-based cocktail builds where visual presentation matters.
- PET Bottles:Lightweight 360ml and 500ml formats enable lower shipping costs and retail price points. Texas ABC board licensing expansion favors these for grocery channel penetration in Dallas and Houston.
- Tetra Packs:Shelf-stable formats for outdoor events and festival concessions.
- Cans:Single-serve 355ml formats competing with hard seltzers for beach and park consumption.
Glass commands margin. PET commands volume.
Distribution Channel:
Geographic concentration in California and New York fragments channel strategy across incompatible regulatory environments.
- Supermarkets:California grocery chains with dedicated beverage alcohol licenses stock flavored soju adjacent to wine and spirits. State-level ABC board reciprocity gaps force parallel stocking strategies in Texas.
- Online Retail:Post-pandemic delivery frameworks in permissive jurisdictions enable direct-to-consumer bypass of three-tier distribution. TTB label approval requirements create compliance bottlenecks for cross-state shipping.
- Restaurants:Korean-American establishments anchor baseline demand with à la carte soju programs.
- Specialty Stores:Asian grocery chains and boutique wine shops curate premium and craft expressions.
Restaurants anchor legitimacy. Online retail scales reach.
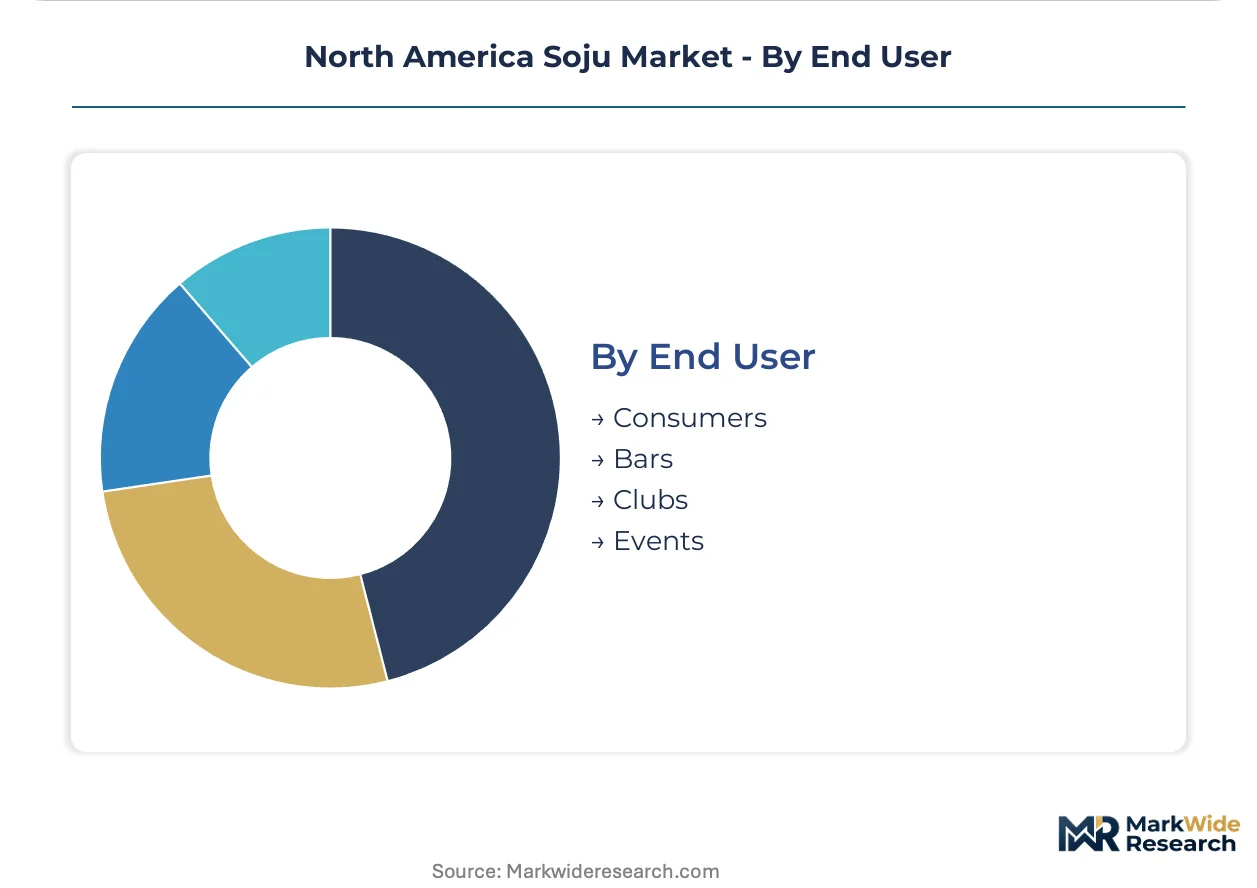
End User:
Application occasion separates session-drinking consumers from commercial volume buyers.
- Consumers:Individual purchasers for home consumption and private gatherings. Lower-ABV preferences concentrate among 21-34 demographic in urban coastal markets.
- Bars:On-premise accounts building soju-based cocktail menus. Manhattan and Los Angeles craft cocktail programs drive premium soju adoption.
- Clubs:Nightlife venues using soju for bottle service and mixed drinks.
- Events:Festival organizers and catering operations seeking session-friendly alternatives to whiskey and vodka.
Bars set trends. Consumers scale volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Korean-American bartenders and sommeliers in Los Angeles and New York anchor North American soju expertise, translating diaspora consumption patterns into mainstream cocktail program adoption. Their technical fluency with lower-ABV formats bridges Korean restaurant traditions and craft bar innovation. This talent concentration shapes geographic expansion priorities across the continent.
United States
California's Korean diaspora density in Los Angeles and Orange County generates concentrated baseline demand that subsidizes expansion into adjacent metropolitan cocktail programs. TTB formula approval requirements for distilled spirits create compliance bottlenecks that favor established importers with dedicated regulatory staff. Manhattan's Koreatown and Brooklyn craft cocktail bars drive premium soju adoption through à la carte program integration.
Canada
Toronto and Vancouver Korean restaurant clusters sustain steady import volumes for traditional clear expressions. Health Canada and provincial liquor boards impose parallel federal-provincial compliance tracks that elevate working capital requirements for new entrants. British Columbia's craft distillery licensing framework enables small-batch soju experimentation in Vancouver's fermentation-focused beverage scene.
Mexico
Mexico City and Monterrey hospitality venues show emerging interest in lower-ABV alternatives to tequila and mezcal for group dining occasions. COFEPRIS pharmaceutical and health regulations govern alcohol import registration, creating timeline uncertainty for Korean exporters seeking market entry. Guadalajara's upscale Korean barbecue restaurants anchor initial distribution trials for flavored soju variants.
North America Soju Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across North American soju distribution. HiteJinro Co., Ltd. and Lotte Chilsung Beverage Co. leverage multinational beverage portfolios to absorb TTB compliance costs, while smaller Korean distillers concentrate on heritage rice fermentation narratives. The market structure fragments between industrial-scale clear soju volume leaders and craft premium positioning aspirants. Dominant competitive moves include wholesale partnership dependency for regulatory navigation and flavor formulation diversification to capture younger consumer rotation.
Within the industrial-scale tier, HiteJinro Co., Ltd. anchors established distribution relationships with major North American beverage wholesalers. Lotte Chilsung Beverage Co. occupies a position exemplifying fruit-infused portfolio extension strategies targeting entry-level drinkers. Chamisul Soju represents premium positioning archetypes sustained through brand recognition among Korean-American consumer bases. These three entities collectively illustrate the competitive spectrum from volume-driven neutral grain spirit production to provenance-focused artisanal differentiation.
| Leading Market Players |
|---|
| Chamisul Soju |
| Jeju Soju |
| HiteJinro Co., Ltd. |
| C1 Soju |
| Muhak |
| Lotte Chilsung Beverage Co. |
| Andong Soju |
| Hwayo |
| Charm Soju |
| Others |
Value Chain & Pricing Dynamics
Family-owned Korean distillers with multi-generational rice fermentation heritage anchor supply-side discipline, converting scarce heritage grain access into pricing power that industrial neutral-grain-spirit producers cannot replicate. This ownership pattern concentrates premium tier pricing in California and New York while fragmenting economy tier competition among contract-manufactured imports.
Pricing Analysis
Bundled restaurant table-service pricing dominates Korean-American establishment channels, while unbundled à la carte cocktail program pricing captures margin in Manhattan and Los Angeles craft bars. Three-tier pricing structure across premium, standard, and economy levels separates heritage rice fermentation from industrial dilution from flavored entry variants. Pricing pressure stems from hard seltzer substitution in the 12-16% ABV fruit-forward segment, compressing slotting fees in California grocery chains. Entry-level consumers in Texas and Florida exhibit highest price sensitivity, while Korean-American diaspora consumers in Los Angeles show lowest sensitivity to provenance premiums.
Supply Chain Analysis
Domestic-content mandates in Korean agricultural policy shape heritage rice sourcing for premium soju, forcing North American importers to negotiate exclusive varietal contracts with designated Gyeongsangnam-do and Jeolla-do prefecture growers. Supply concentrates in South Korea for fermentation expertise, China for neutral grain spirit feedstock, and California for craft distillation experimentation. Raw material dependencies include designated short-grain rice varieties, tapioca-derived ethanol, and natural fruit extracts for flavor formulation. Single-source vulnerability runs through TTB-certified import permit holders with established formula approval track records. Distribution runs through three-tier beverage alcohol wholesalers in California, New York, and Texas, with direct-to-retailer e-commerce emerging in permissive jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America soju market reads as a late-cycle quality story, with consumer rotation toward lower-ABV session formats and artisanal provenance narratives displacing volume-driven industrial positioning.
For Market Incumbents: Extend regulatory compliance infrastructure into dual-track TTB and state ABC board approval capabilities, converting six-figure working capital requirements into scalable moats against bootstrapped flavor entrants. Deepen wholesale partnership dependency in Texas before Korean restaurant density reaches California saturation, securing first-mover shelf space in Dallas and Houston grocery channels. Neutral grain spirit input volatility represents the primary margin threat requiring backward integration into designated ethanol supply contracts. For New Entrants and Emerging Players: State-level ABC board ready-to-drink reclassification debates in California and New York open a window for 12-16% ABV flavored variants positioned outside traditional spirits tax schedules. White-space targets include Texas on-premise channels in underpenetrated Dallas and Houston Korean barbecue corridors, plus direct-to-retailer e-commerce bypass of three-tier gatekeepers in permissive jurisdictions. The most penetrable segment is fruit-forward soju in the 21-34 urban coastal demographic. Go-to-market angle should leverage heritage rice fermentation narratives for premium positioning in craft cocktail programs. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier craft distillers with existing TTB permits and Korean heritage grain sourcing relationships, trading at discounts to industrial-scale importers despite superior margin profiles. Long-term viability over the five-to-ten year window hinges on regulatory arbitrage capture and diaspora consumer loyalty translation into mainstream adoption. Acquisition target archetype: California-based craft producers with established Los Angeles restaurant channel relationships and scalable fermentation monitoring technology. The signal to watch is state-level ABC board finalization of lower-ABV tax reclassification rules, which would trigger portfolio repricing across flavored soju variants.| Strategic Initiative | Industry Significance |
|---|---|
| TTB Dual-Track Approval Securement | Pre-positions portfolios for potential ready-to-drink reclassification in California and New York. |
| Heritage Rice Sourcing Contracts | Locks in scarce Gyeongsangnam-do varietal access that underpins premium tier pricing power. |
| Texas ABC Licensing Expansion | Captures first-mover shelf space before Korean restaurant density reaches California saturation levels. |
| Continuous Fermentation Monitoring Adoption | Compresses quality assurance timelines for mid-tier distillers competing with industrial output consistency. |
| Direct-to-Retailer E-Commerce Launch | Bypasses three-tier distribution gatekeepers in permissive jurisdictions post-pandemic delivery framework maturation. |
Study Parameters
Multiple input streams — structured interviews with beverage alcohol importers, regulatory affairs specialists at TTB-permitted distributors, Korean-American restaurant operators, and craft cocktail program managers — were reconciled against secondary validation from TTB COLA certification databases, state ABC board licensing records, and customs import manifests. Primary fieldwork captured formula approval timeline experiences and wholesale partnership negotiation dynamics. Secondary sources included SEC filings from diversified Korean beverage conglomerates, California Department of Alcoholic Beverage Control enforcement data, and Nielsen retail audit information for flavored spirits categories. Bottom-up channel volume estimates triangulated against top-down import value reconstructions.
Historical consumption patterns across Korean-American restaurant channels and mainstream cocktail program adoption curves were cross-referenced against panel input from distributor sales executives and on-premise account buyers. The analytical framework modeled volume and value trajectories across product type, packaging format, distribution channel, and end-user occasion dimensions throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion constraints. Industry-specific forecast inputs included TTB permit approval queue lengths, Korean agricultural policy rice allocation schedules, and state-level ABC board staffing capacity for formula review.
Revisions become necessary when TTB regulatory stance shifts on soju-adjacent classification, Korean agricultural export policy disrupts heritage grain supply, or state-level tax reclassification debates resolve unexpectedly. Forecasts reflect documented assumptions about diaspora population growth, craft cocktail program expansion rates, and hard seltzer competitive intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Uganda Spirits Market
Alcoholic Beverages
Premix Bottled Cocktails Market
Alcoholic Beverages
Asia-Pacific Kegs Market
Alcoholic Beverages
Hogshead Barrel Market
Alcoholic Beverages
France Tequila Market
Alcoholic Beverages
Global Malt Market
Alcoholic Beverages
South Africa Tequila Market
Alcoholic Beverages
Brazil Alcohol E-Commerce Market
Alcoholic Beverages
Pressurized Wine Filter System Market
Alcoholic Beverages
Global Wine Market
Alcoholic Beverages
Instant Wine Chillers and Refreshers Market
Alcoholic Beverages
Ethanol Market
Alcoholic Beverages
Beer Filter System Market
Alcoholic Beverages
Still Wine Market
Alcoholic Beverages
Bright Beer Tank Market
Alcoholic Beverages
Dark Beer Market