
 Microbrewery Supplies Market | 2026-2036
Microbrewery Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Microbrewery Supplies Market Foresight
Premium-grade stainless steel specifications are redrawing capital expenditure patterns among craft producers. Krones AG leverages its bottling line expertise to anchor European supply chains. GEA Group sustains competitive positioning through specialized heat exchange systems for temperature-sensitive fermentation. Alfa Laval dominates membrane filtration subsystems that extend product shelf stability.
Microbrewery supplies encompass raw inputs, processing equipment, and packaging materials engineered to batch volumes typically below six thousand barrels annually, with stainless steel 304 or 316L grades specified for wort contact surfaces to prevent metallic contamination and ensure flavor integrity. Fermenters and cooling systems command the largest equipment-type margin pools due to precision temperature control requirements, while can-based packaging formats are capturing share from glass bottles as mobile canning lines reduce per-unit capital barriers. Online retail channels for consumables such as specialty yeasts and hop varietals are expanding fastest among distribution alternatives, though direct sales relationships persist for capital equipment purchases.
The EPA enforces wastewater discharge standards that compel smaller breweries to install on-site treatment or pre-treatment equipment, while FDA food-contact material regulations govern stainless steel surface finishes and sealing compounds. OSHA brewery safety standards shape facility layout and vessel access design for equipment manufacturers. Stakeholders must monitor evolving state-level water use restrictions and energy efficiency benchmarks that will determine equipment replacement timing and supplier qualification criteria.
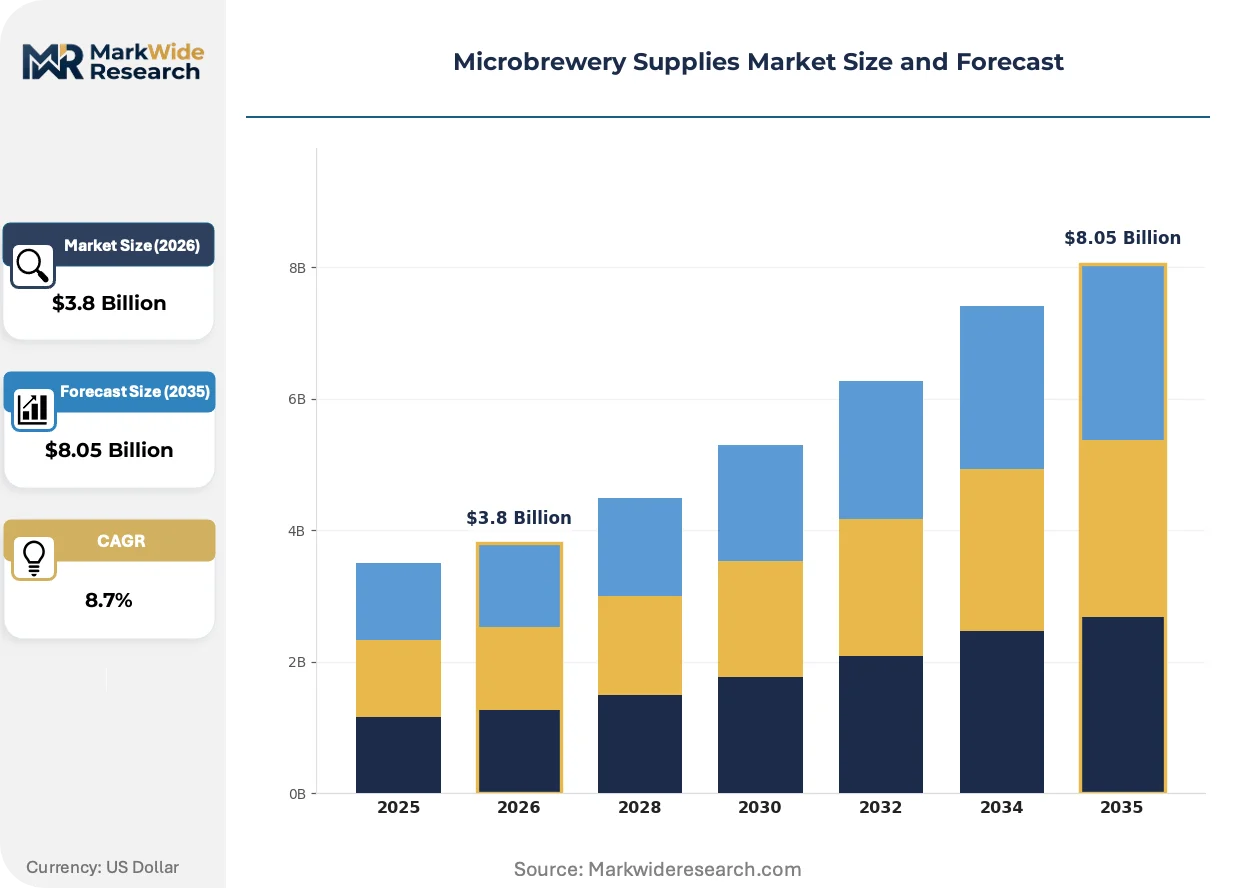
Market Dynamics
Water reclamation mandates from the EPA and state-level environmental agencies are compelling capital equipment replacement cycles among craft producers, forcing simultaneous upgrades across fermentation, cooling, and wastewater treatment subsystems.
Growth Catalysts
- Taproom Expansion:Craft brewpub operators are scaling small-batch capacity to serve on-premise consumption growth, driving repeat equipment procurement for vessels below fifty barrel capacity.
- EPA Wastewater Standards:Discharge regulations mandate on-site pre-treatment installation, creating mandatory demand for membrane bioreactors and solids separation equipment among sub-thousand barrel facilities.
- Mobile Canning Adoption:Contract canning services reduce per-unit packaging capital barriers, enabling smaller entrants to launch with leased lines rather than owned bottling infrastructure.
Market Restraints
- Nickel Price Volatility:Stainless steel 304 and 316L specifications tie equipment costs to London Metal Exchange nickel pricing, compressing margin visibility for fermenter and bright tank manufacturers.
- German Equipment Concentration:Precision brewing component supply clusters in Bavaria and Baden-Württemberg, exposing North American buyers to extended lead times and euro-denominated pricing exposure.
- Specialized Welding Shortage:ASME-certified pressure vessel fabrication requires orbital TIG welding expertise that outstrips current vocational training pipeline output in multiple producing regions.
Strategic Opportunities
- Australian Craft Saturation:Melbourne and Sydney microbrewery density creates aftermarket service and consumables demand exceeding domestic supplier coverage, opening channel entry for specialized yeast and hop varietal distributors.
- Heat Recovery Integration:Convergence of brewery chilling systems with building HVAC networks enables energy arbitrage for taproom operators in jurisdictions with time-of-use electricity pricing.
- Online Consumables Platforms:Direct-to-brewer e-commerce for specialty yeasts, laboratory media, and cleaning chemicals bypasses traditional distributor markups in fragmented secondary markets.
Industry Challenges
- Cross-Contamination Protocols:Gluten-free and non-alcoholic production lines require validated clean-in-place procedures that extend batch turnaround times and complicate multi-product facility scheduling.
- Legacy Control System Integration:Temperature monitoring and fermentation management software from incumbent vendors resists interoperability with newer IoT sensor networks, forcing expensive middleware development or full stack replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbrewery Supplies Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Malts, Hops, Yeasts, Additives Equipment Type: Brew Kettles, Fermenters, Bottling Lines, Cooling Systems Packaging Type: Bottles, Cans, Kegs, Growlers Distribution Channel: Online Retail, Wholesale, Direct Sales, Specialty Stores |
| Companies Covered | Krones AG, GEA Group, Alfa Laval, Criveller Group, BrauKon GmbH, Paul Mueller Company, Della Toffola SpA, ICC Northwest Inc, Portland Kettle Works, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbrewery Supplies Market Shifts & Advancements
Equipment modularization and sensor miniaturization are compressing minimum viable scale thresholds while fragmenting supplier relationships across previously integrated production lines.
Single-use bioreactor liners adapted from pharmaceutical fermentation are fragmenting stainless steel vessel demand among pilot-scale and seasonal breweries. Taproom operators in Colorado and Oregon are deploying disposable wort contact surfaces to eliminate CIP downtime between experimental batches. This technology is fragmenting capital allocation patterns by shifting expenditure from depreciable assets to recurring consumables budgets.
The EPA's pending effluent limitation guidelines for breweries will tighten biological oxygen demand and total suspended solids thresholds for direct discharge permits. Equipment suppliers are pre-certifying packaged treatment plants to expedite state permitting timelines. Smallest-volume producers in water-stressed jurisdictions including California and Arizona face the steepest compliance cost escalation.
Buying committees at multi-location craft groups are consolidating supplier relationships and demanding outcome-based equipment performance guarantees. Direct sales teams from Krones and GEA are responding with uptime-commitment service contracts that bundle maintenance chemicals and spare parts. This restructuring concentrates procurement leverage among the fifty largest US craft brewing groups while marginalizing smaller equipment dealers.
Microbrewery Supplies Market Segmentation
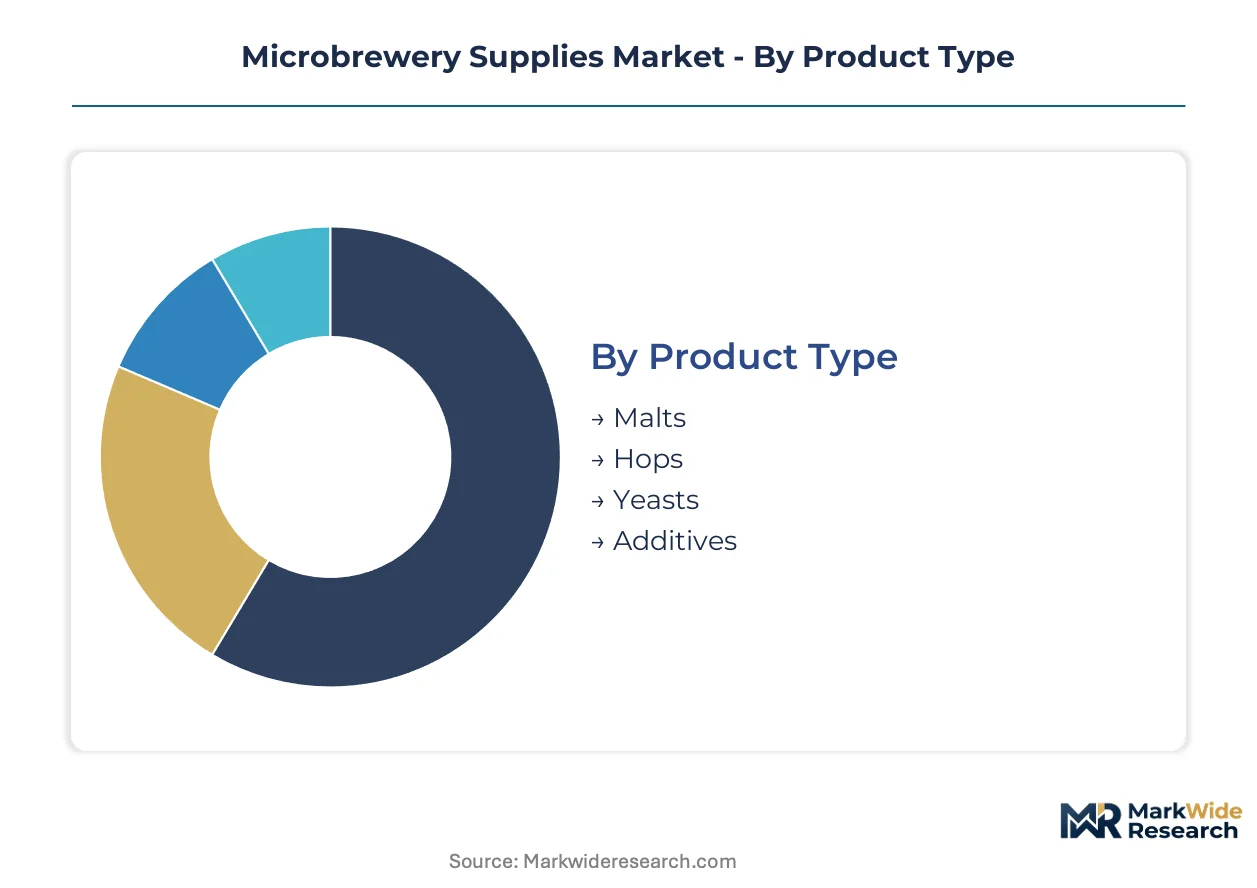
Segmentation in microbrewery supplies reveals divergent procurement patterns between capital equipment and recurring consumables. Equipment purchases concentrate among expanding taproom operators in water-stressed jurisdictions, while consumables flow through fragmented channels serving experimental batch programs.
Product Type:
Domestic malt production dominates North American supply, while specialty hop varietals and proprietary yeast strains flow through import-dependent channels from Germany, the Czech Republic, and Belgium.
- Malts:Base malt specifications follow regional barley cultivation patterns, with two-row and six-row varieties commanding distinct flavor profiles. Demand concentrates among mid-volume craft producers in the American Midwest and Canadian Prairies seeking consistent enzymatic conversion for standardized core brands.
- Hops:Aroma hop procurement has shifted toward varietal-specific contracts with Pacific Northwest growers, as Citra, Mosaic, and proprietary experimental cultivars displace traditional European bittering additions. German Hallertau and Czech Saaz imports retain niche positioning for lager authenticity.
- Yeasts:Liquid yeast cultures from specialized laboratories command premium positioning for strain purity and viability guarantees.
- Additives:Enzymes, fining agents, and flavor adjuncts serve gluten-reduced and non-alcoholic production lines requiring process intervention.
Malts command the established base. The steepest expansion runs through proprietary yeast cultures.
Equipment Type:
Capital allocation patterns split between fermentation capacity expansion and compliance-driven wastewater treatment installations.
- Fermenters:Stainless steel 304 and 316L vessels with glycol-jacketed temperature control represent the dominant capital expenditure category. Demand clusters among Colorado, Oregon, and North Carolina taproom operators scaling from pilot systems to production-scale batch consistency.
- Cooling Systems:Heat exchange and chiller integration with building HVAC networks enables energy arbitrage in jurisdictions with time-of-use electricity pricing. California and Arizona brewers prioritize water reclamation compatibility.
- Brew Kettles:Steam-fired and direct-fire configurations follow facility utility infrastructure and local fire code interpretations.
- Bottling Lines:Mobile canning services have displaced owned glass bottling infrastructure among entrants below thousand-barrel annual volume.
Fermenters anchor equipment revenue. Cooling systems are climbing the fastest as EPA wastewater standards tighten.
Packaging Type:
Format selection reflects distribution ambition—direct taproom sales favor kegs and growlers, while retail presence demands shelf-stable cans and bottles.
- Cans:Aluminum beverage cans with printed shrink-sleeve labeling have displaced glass for off-premise retail distribution. Mobile canning lines reduce capital barriers for seasonal and experimental releases among Vermont and Maine farmhouse breweries.
- Kegs:Stainless steel sixth-barrel and half-barrel configurations dominate on-premise draft service, with deposit-return logistics concentrated in urban taproom clusters.
- Bottles:Amber and clear glass retains positioning for Belgian-style and barrel-aged offerings requiring bottle conditioning.
- Growlers:Refillable glass and insulated stainless steel formats serve local direct-to-consumer traffic in states permitting off-sales from production facilities.
Kegs retain the installed on-premise base. Cans are gaining share fastest through retail channel expansion.
Distribution Channel:
Channel structure fragments between relationship-heavy capital equipment sales and transactional consumables procurement.
- Direct Sales:Capital equipment manufacturers including Krones and GEA maintain dedicated brewery industry sales teams for fermenter, bottling line, and heat exchange system procurement. Multi-location craft groups consolidate supplier relationships and demand uptime-commitment service contracts.
- Online Retail:Specialty yeast strains, laboratory media, and cleaning chemicals bypass traditional distributor markups through direct-to-brewer e-commerce. Australian and Canadian secondary markets show particular platform adoption.
- Wholesale:Regional distributors aggregate malt, hop, and packaging material procurement for mid-volume producers lacking direct supplier relationships.
- Specialty Stores:Local homebrew and pro-am supply retailers serve pilot-scale and nanobrewery segments with immediate availability.
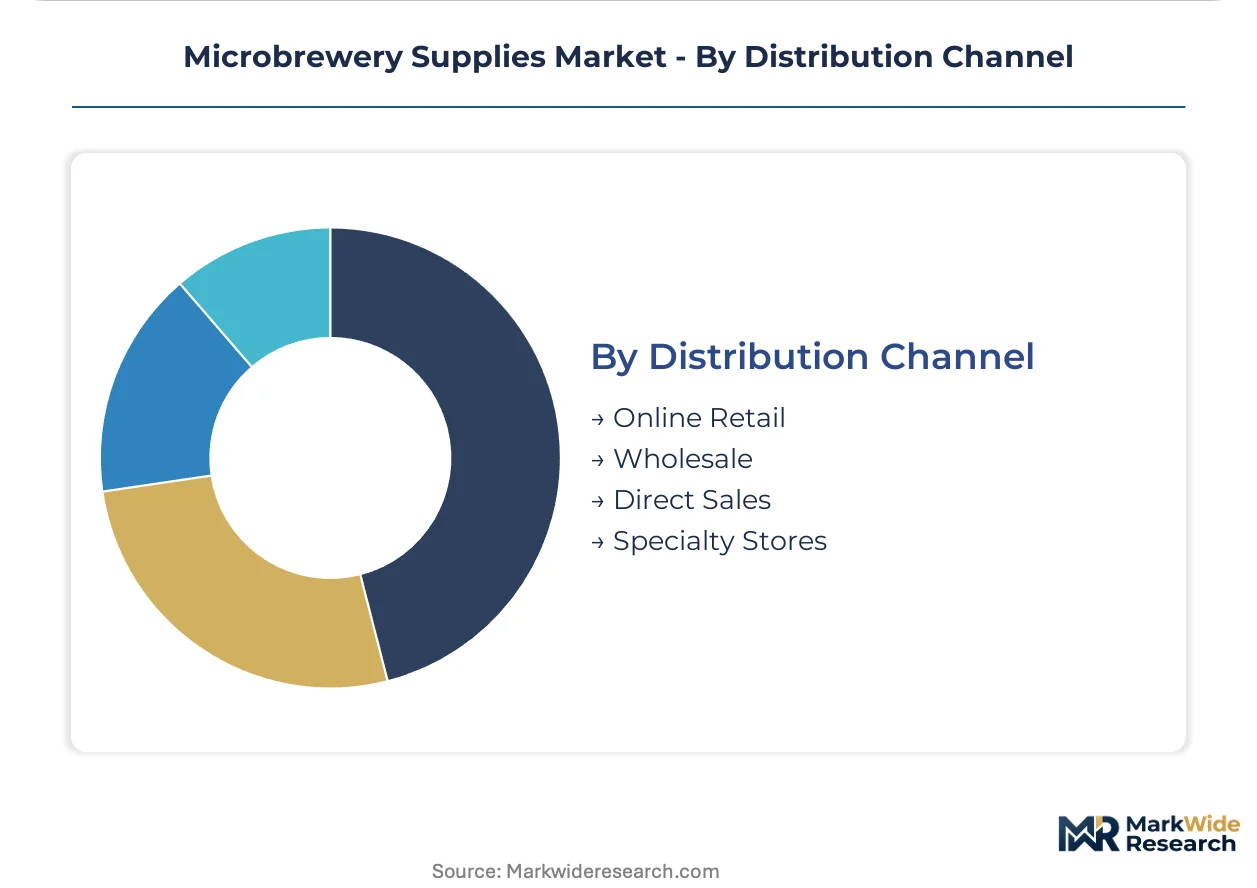
Direct sales dominate capital equipment. Online retail is expanding most quickly for consumables and replacement parts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication clusters in Bavaria and Baden-Württemberg supply precision brewing components worldwide, while craft beer consumption drives procurement cycles across three distinct national markets.
United States
Colorado, Oregon, and North Carolina taproom operators scale pilot systems to production capacity. The EPA enforces wastewater discharge standards compelling on-site pre-treatment installation. Denver and Portland brewery density creates concentrated demand for fermenters below fifty-barrel capacity.
Germany
Bavarian precision engineering dominates stainless steel vessel fabrication for temperature-sensitive fermentation. The EU Green Deal and REACH regulations govern food-contact surface finishes and sealing compounds. Munich and Stuttgart industrial clusters anchor European supply chains for glycol-jacketed systems.
Australia
Melbourne and Sydney microbrewery saturation exceeds domestic supplier coverage for aftermarket service. The TGA and state-level environmental agencies regulate water reclamation compatibility. Victoria and New South Wales craft density opens channel entry for specialty yeast and hop varietal distributors.
Microbrewery Supplies Market Competitive Landscape
Concentration sits with diversified industrial equipment conglomerates and specialized brewing fabricators. The vendor base splits between European precision engineering houses and North American regional specialists. Three archetypes dominate: stainless steel vessel fabricators, heat exchange system specialists, and integrated packaging line providers. Competitive moves center on geographic expansion into underserved secondary markets and outcome-based service contracts bundling maintenance with equipment sales.
Among German-based engineering conglomerates, Krones AG and GEA Group exemplify the integrated systems archetype, supplying bottling lines and fermentation infrastructure. Alfa Laval anchors the component specialist tier with membrane filtration subsystems. These three names represent distinct competitive positioning strategies within a market where direct sales relationships and uptime-commitment contracts determine procurement leverage.
| Leading Market Players |
|---|
| Krones AG |
| GEA Group |
| Alfa Laval |
| Criveller Group |
| BrauKon GmbH |
| Paul Mueller Company |
| Della Toffola SpA |
| ICC Northwest Inc |
| Portland Kettle Works |
| Others |
Supply & Pricing Matrix
Mobile canning services replacing owned bottling infrastructure simultaneously redraw supply geography toward contract packaging hubs and compress capital-equipment pricing power for traditional bottling line manufacturers. This substitution shifts brewery expenditure from depreciable stainless steel assets toward recurring operational budgets, fragmenting procurement leverage across multiple service providers rather than concentrating it with single-equipment vendors.
Pricing Analysis
EPA wastewater discharge standards dictate the pricing tier structure across fermentation and pre-treatment equipment categories. Three-tier pricing structure across premium ASME-certified, standard industrial-grade, and economy import-tier vessels reflects stainless steel grade differentiation and orbital welding certification levels. Cost compression in economy-tier fermenters is intensifying because nickel price volatility on the London Metal Exchange directly transfers to 304 and 316L vessel fabrication costs. Price-sensitive nano-breweries and pilot-scale entrants cluster in the economy tier, while multi-location craft groups with consolidated procurement negotiate premium-tier uptime-commitment service bundles.
Supply Chain Analysis
Port congestion on transatlantic lanes from Hamburg and Bremerhaven extends lead times for precision brewing components inbound to North American buyers. Equipment fabrication concentrates in Germany, the United States, and Australia, with Bavarian and Baden-Württemberg industrial clusters anchoring European glycol-jacketed system production. Raw material dependencies rest on Indonesian nickel ore, South African chromium, and domestic North American steel slab. Single-source vulnerability from concentrated German precision component supply exposes buyers to euro-denominated pricing swings. Distribution runs through direct sales teams for capital equipment and fragmented online retail channels for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water reclamation mandates from the EPA are accelerating equipment replacement cycles and opening white-space for compliance-integrated system providers. This regulatory inflection compresses decision timelines for capital procurement committees.
For Market Incumbents: Consolidate aftermarket service coverage in Australian metropolitan clusters where Melbourne and Sydney brewery density exceeds domestic supplier reach. Deepen backward integration into stainless steel vessel fabrication through captive orbital welding capacity to offset ASME-certified labor shortages. Bundle membrane bioreactor pre-certification with fermenter sales to capture EPA-driven compliance budgets.
For New Entrants and Emerging Players: Aftermarket consumables logistics gaps in Australian secondary markets present immediate channel entry opportunities for specialty yeast and hop varietal distributors. Target mobile canning service partnerships as the most penetrable segment for packaging equipment entrants lacking established bottling line references. Pursue direct-to-brewer e-commerce platforms to bypass traditional wholesale markups in fragmented Canadian and Australian markets.
For Investors and Strategic Acquirers: EPA pending effluent limitation guidelines reshape the acquisition landscape toward pre-certified wastewater treatment technology providers. Long-term viability over the coming decade hinges on regulatory compliance integration rather than pure equipment manufacturing scale. Monitor state-level water use restriction announcements in California and Arizona as the primary signal for compliance-driven equipment demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Outcome-Based Service Contracting | Uptime-commitment bundles from Krones and GEA capture multi-location craft group procurement consolidation. |
| Mobile Canning Partnership Network | Leased packaging lines reduce capital barriers for Vermont and Maine farmhouse brewery seasonal releases. |
| Heat Recovery System Integration | Converged brewery chilling with building HVAC enables energy arbitrage under time-of-use electricity pricing. |
| Online Consumables Platform Launch | Direct-to-brewer e-commerce for specialty yeasts bypasses traditional distributor markups in fragmented markets. |
| Pre-Certified Treatment Plant Packaging | EPA-aligned membrane bioreactor bundles expedite state permitting timelines for sub-thousand barrel facilities. |
Research Methodology
A spread of perspectives from taproom operators, equipment procurement directors, fermentation specialists, and aftermarket service managers converged on the working assumptions underlying this analysis. Primary field engagement with Colorado and Oregon brewery owners, Bavarian stainless steel fabricators, and Australian specialty ingredient distributors combined with secondary validation from EPA enforcement guidance documents, FDA food-contact material regulations, state-level water board filings, and customs trade data. Bottom-up equipment shipment tallies and top-down addressable market sizing triangulated on segment-level figures.
Segmentation dimensions modeled include product type, equipment category, packaging format, and distribution channel across the projection horizon. Fermenter and cooling system revenue streams were disaggregated by stainless steel grade specification and glycol-jacketed configuration. CAGRs were derived from replacement cycle analysis tied to EPA compliance deadlines and craft brewery expansion patterns. Industry-specific forecast inputs incorporated nickel price trajectory assumptions and ASME-certified welding capacity constraints.
Forecasts assume regulatory continuity in EPA wastewater enforcement and state-level water use restrictions; material policy shifts would require re-modeling of equipment replacement timing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Beer Filter System Market
Alcoholic Beverages
Brewing Supplies Market
Alcoholic Beverages
Spirits Market
Alcoholic Beverages
Crystal Malt Market
Alcoholic Beverages
Black Beer Market
Alcoholic Beverages
Germany Alcohol E-Commerce Market
Alcoholic Beverages
Beer Bottle Market
Alcoholic Beverages
Asia-Pacific Wine Market
Alcoholic Beverages
Global Wine Coolers Market
Alcoholic Beverages
North America Mezcal Market
Alcoholic Beverages
North America Spirits Market
Alcoholic Beverages
US Wine Market
Alcoholic Beverages
Brandy Flavor Market
Alcoholic Beverages
Alcoholic Ready-To-Drink (Rtds)/High Strength Premixes Market
Alcoholic Beverages
Asia-Pacific Kegs Market
Alcoholic Beverages
Port Wine Market