
 Global Beer Market | 2026-2036
Global Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Beer Market Analysis
Vietnam's Mekong Delta brewing corridor is fragmenting as new malt houses and packaging lines attract regional investment. Anheuser-Busch InBev leverages its Budweiser brand architecture to dominate premium draft placements across Ho Chi Minh City nightlife districts. Heineken sustains its position through captive supply of proprietary yeast strains and localized barley sourcing partnerships. Tsingtao Brewery Group anchors volume in Northeast Asian export channels while competing on price against European imports in Southeast Asian duty-free retail.
Beer is a fermented alcoholic beverage produced from malted cereal grains, hops, water, and brewer's yeast through controlled mashing, boiling, fermentation, and conditioning processes typically yielding alcohol content between 3% and 12% ABV. Its primary commercial purpose is serving as a standardized refreshment and social consumption product across on-trade hospitality and off-trade retail channels. Lager occupies the dominant volume position globally due to scalable continuous fermentation and extended shelf stability, while craft beer enthusiasts drive margin expansion through small-batch ale and stout premiums that command three-to-five-fold price multiples over mass-market equivalents. Distribution channel structure concentrates value in supermarkets and liquor stores for volume throughput, though online retail represents the fastest-growing route as direct-to-consumer subscription models bypass traditional wholesale markups.
EU Green Deal frameworks and REACH chemical standards constrain packaging material choices and water discharge protocols for breweries operating across Germany, Belgium, and the Netherlands. FDA labeling requirements and TTB formula approvals govern US import access and ingredient disclosure thresholds for foreign producers. China's SAMR enforces GB standards on alcohol content declaration and additive permissibility that shape formulation decisions for brands entering its domestic market. Stakeholders must monitor divergence between EU carbon border adjustments and emerging economy enforcement capacity as compliance costs reshape competitive access across priority export corridors.
Market Dynamics
EU Green Deal carbon targets are pressuring breweries to retrofit biogas capture systems, fundamentally restructuring capital allocation across European production assets while Southeast Asian on-trade expansion pulls capacity toward draft-focused configurations.
Growth Catalysts
- EU Green Deal decarbonization mandates:REACH chemical standards and carbon border adjustments compel German and Belgian breweries to invest in anaerobic digesters and heat recovery systems, creating compliance-driven equipment demand.
- Southeast Asian on-trade premiumization:Ho Chi Minh City and Bangkok nightlife districts expand draft beer portfolios, pulling malt suppliers and keg logistics providers into regional hub configurations.
- Proprietary yeast strain captive supply:Heineken's localized barley sourcing partnerships demonstrate how biological asset control secures flavor consistency and supply chain autonomy against commodity volatility.
Market Restraints
- Barley and malt input cost volatility:Climate-induced harvest variability across Australian and Canadian grain belts compresses margin predictability for lager-dependent volume producers.
- Glass and aluminum packaging concentration:Three European container manufacturers control two-thirds of specialty bottle supply, creating bottleneck risk for craft brewers requiring premium presentation formats.
- Non-alcoholic beverage substitution:Functional water and adaptogenic drink categories capture occasion-based consumption previously defaulting to beer, particularly among 25-34 demographic cohorts in urban China.
Strategic Opportunities
- Vietnam Mekong Delta brewing corridor fragmentation:New malt houses and packaging lines attract regional investment, enabling integrated production footprints that bypass import tariff exposure.
- Direct-to-consumer subscription channel emergence:Online retail bypasses traditional wholesale markups, allowing craft breweries to capture margin previously surrendered to distributor tiers.
- China SAMR GB standards alignment:Alcohol content declaration and additive permissibility rules favor established brands with compliance infrastructure over opportunistic entrants.
Industry Challenges
- Brewmaster and fermentation science talent scarcity:Specialized expertise in mixed-culture and spontaneous fermentation commands premium compensation, constraining craft brewery scale-up velocity.
- Legacy equipment integration with digital monitoring systems:Brownfield breweries face retrofit complexity when installing IoT-enabled tank sensors and predictive maintenance platforms alongside decades-old copper kettles.
- Water discharge protocol certification timelines:EPA and MEE permitting processes for brewery effluent treatment upgrades extend 18-24 months, delaying capacity expansion projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Beer Market |
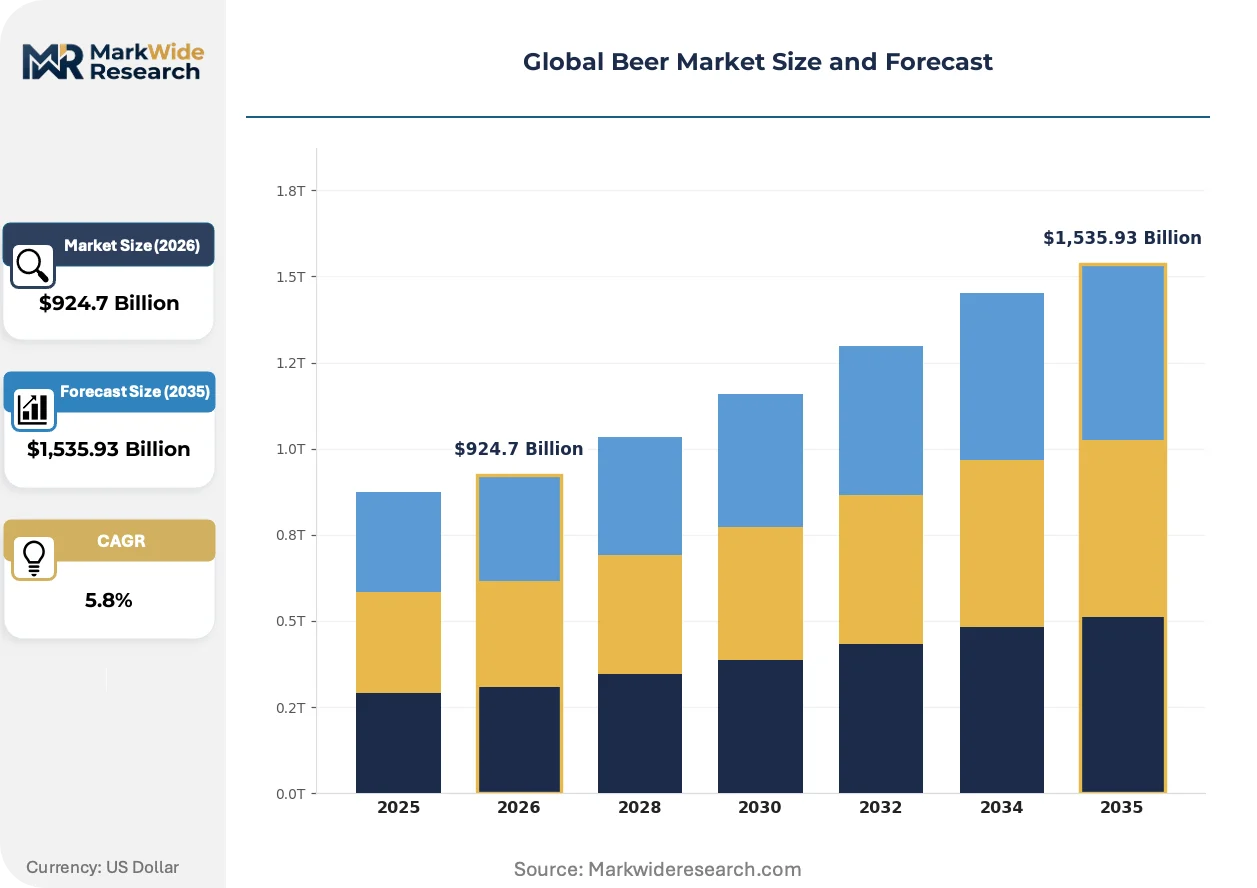
| Market Size in 2026 | $924.7 Billion |
| Market Size in 2035 | $1,535.93 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lager, Ale, Stout, Pilsner Distribution Channel: Supermarkets, Liquor Stores, Restaurants, Online Retail Consumer Type: Craft Beer Enthusiasts, Casual Drinkers, Connoisseurs, Occasional Consumers Serving Size: Pint, Bottle, Can, Pitcher |
| Companies Covered | Anheuser-Busch InBev, Heineken, China Resources Snow Breweries, Carlsberg Group, Molson Coors Beverage Company, Tsingtao Brewery Group, Asahi Group Holdings, Constellation Brands, Kirin Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Beer Market Emerging Trajectories
Digital instrumentation and biological process control are converging to reshape production economics, while regulatory frameworks and consumption patterns force simultaneous adaptation across formulation, packaging, and distribution architectures.
IoT-enabled fermentation monitoring systems are digitizing brewhouse operations through real-time specific gravity tracking and automated temperature modulation. Mid-size craft breweries in Colorado and Oregon deploy these platforms to reduce batch-to-batch variation and compress quality control labor hours. The technology is digitizing asset utilization rates by enabling predictive maintenance that prevents unplanned downtime during peak seasonal demand windows.
EU F-Gas Regulation phase-down schedules are accelerating brewery transitions from hydrofluorocarbon-based refrigeration to ammonia and CO2 cascade systems in cellaring and packaging halls. Belgian and Czech producers face compressed retrofit timelines as existing equipment reaches end-of-life against tightening leakage thresholds. Lager-focused facilities with extended cold storage requirements bear disproportionate compliance cost exposure compared to ale-oriented craft operations with shorter conditioning cycles.
Buyer concentration among consolidated hospitality groups is restructuring draft procurement into centralized beverage programs with exclusive pouring contracts. Independent bars and restaurants in London and Sydney lose negotiating leverage as property management companies bundle beer supply into master service agreements with volume commitments. Vietnam's urban hospitality corridor exhibits the most visible concentration, where district-level nightlife operators negotiate directly with Anheuser-Busch InBev and Heineken for tap handle exclusivity.
Global Beer Market Segmentation
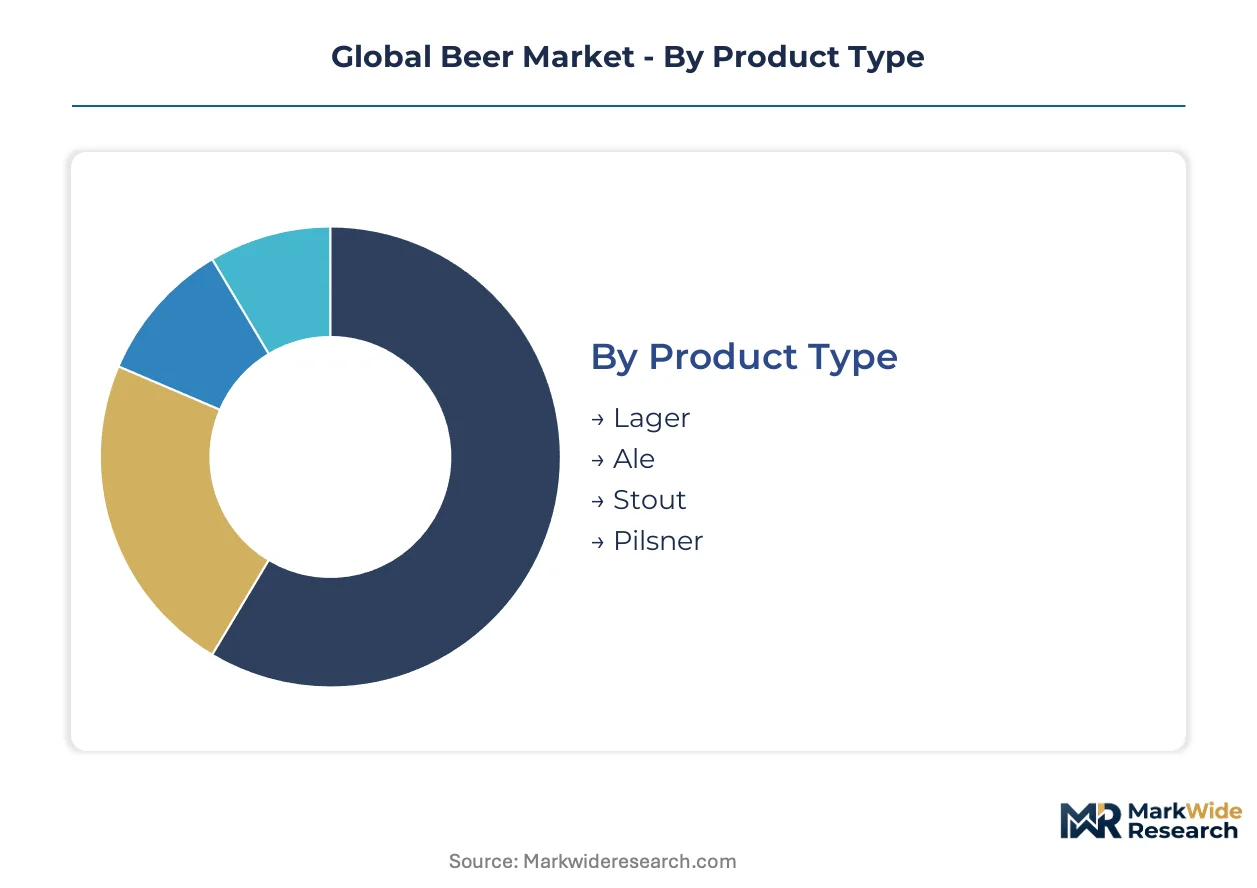
Segmentation reveals how production economics, channel access, and consumption occasions fragment revenue capture across the beer industry. Distinct technical specifications and buyer behaviors create divergent margin profiles that reward specialized positioning over undifferentiated scale.
Product Type:
Lager commands the shortest production cycle through continuous fermentation and rapid conditioning, while barrel-aged stout and mixed-culture ale extend inventory turns across months or years.
- Lager:Bottom-fermented at near-freezing temperatures using Saccharomyces pastorianus yeast strains, delivering crisp flavor profiles and extended shelf stability. Volume concentrates in Southeast Asian on-trade venues where Ho Chi Minh City nightlife operators negotiate exclusive tap placements with multinational brewers. EU Green Deal carbon mandates are accelerating brewery transitions to energy-efficient cold storage systems that disproportionately benefit lager-focused facilities with extended conditioning requirements.
- Ale:Top-fermented at ambient temperatures using Saccharomyces cerevisiae variants that produce ester-forward aromatic complexity. Craft breweries in Colorado and Oregon deploy IoT-enabled fermentation monitoring to reduce batch-to-batch variation in small-batch ale production. Proprietary yeast strain control, as demonstrated by Heineken's localized barley sourcing partnerships, secures flavor consistency against commodity input volatility.
- Stout:Dark-roasted malt bill with higher original gravity and extended maturation cycles.
- Pilsner:Pale lager subtype distinguished by Saaz hop bitterness and soft water chemistry requirements.
Lager anchors the volume base while ale gains share at the steepest rate.
Distribution Channel:
Channel economics stratify by working capital intensity, with supermarkets demanding extended payment terms and online retail compressing cash conversion through direct-to-consumer subscription models.
- Supermarkets:High-throughput retail format commanding slotting fees and promotional allowances that squeeze craft brewery margins. Buyer consolidation among European grocery chains creates asymmetric negotiating leverage over regional producers.
- Liquor Stores:Specialized off-trade channel with educated staff and curated assortment flexibility. Independent operators in Australia and Germany maintain category expertise that supports premium pricing for limited-release offerings.
- Restaurants:On-trade consumption occasion with highest per-unit margins and tied-house exclusivity pressures. Vietnam's urban hospitality corridor exhibits visible concentration where district-level nightlife operators negotiate directly with Anheuser-Busch InBev and Heineken for tap handle control.
- Online Retail:Fastest-expanding route as direct-to-consumer platforms bypass traditional wholesale markups and capture first-party consumption data.
Supermarkets and liquor stores collectively dominate volume throughput, yet online retail expands most quickly as subscription models reshape customer acquisition economics.
Consumer Type:
Purchase frequency and price elasticity diverge sharply across engagement levels, with enthusiasts accepting three-to-five-fold premiums over mass-market equivalents while occasional buyers remain anchored to promotional pricing.
- Craft Beer Enthusiasts:High-involvement segment prioritizing provenance, brewing technique transparency, and limited availability. This cohort drives margin expansion through small-batch premiums and direct brewery visitation.
- Casual Drinkers:Brand-loyal repeat purchasers seeking consistent refreshment without experimental exploration. Volume concentrates in standard lager and pilsner formats across supermarkets and mainstream on-trade venues.
- Connoisseurs:Discerning buyers evaluating technical execution, vintage variation, and food pairing compatibility. Belgium and Czech Republic production heritage commands disproportionate consideration within this segment.
- Occasional Consumers:Situational purchasers responsive to occasion-based marketing and social consumption cues. Functional water and adaptogenic drink categories capture occasion-based consumption previously defaulting to beer among 25-34 demographic cohorts in urban China.
Casual drinkers sustain volume foundations while craft beer enthusiasts command the steepest margin premiums.
Serving Size:
Packaging format selection directly shapes logistics economics, with keg return systems requiring circular infrastructure investment and aluminum can lines demanding minimum efficient scale thresholds.
- Pint:Standardized 568ml or 473ml draft measure dominating on-trade service. Ho Chi Minh City and Bangkok nightlife districts expand draft beer portfolios, pulling malt suppliers and keg logistics providers into regional hub configurations.
- Bottle:Premium presentation format constrained by three European container manufacturers controlling two-thirds of specialty supply. Brown glass provides UV protection for light-sensitive hop compounds.
- Can:Lightweight aluminum format with superior recycling rates and extended shelf life through complete light exclusion. EU F-Gas Regulation phase-down schedules accelerate transitions from hydrofluorocarbon-based refrigeration in canning line operations.
- Pitcher:Multi-serving vessel format concentrating in group consumption occasions and sports-oriented on-trade venues.
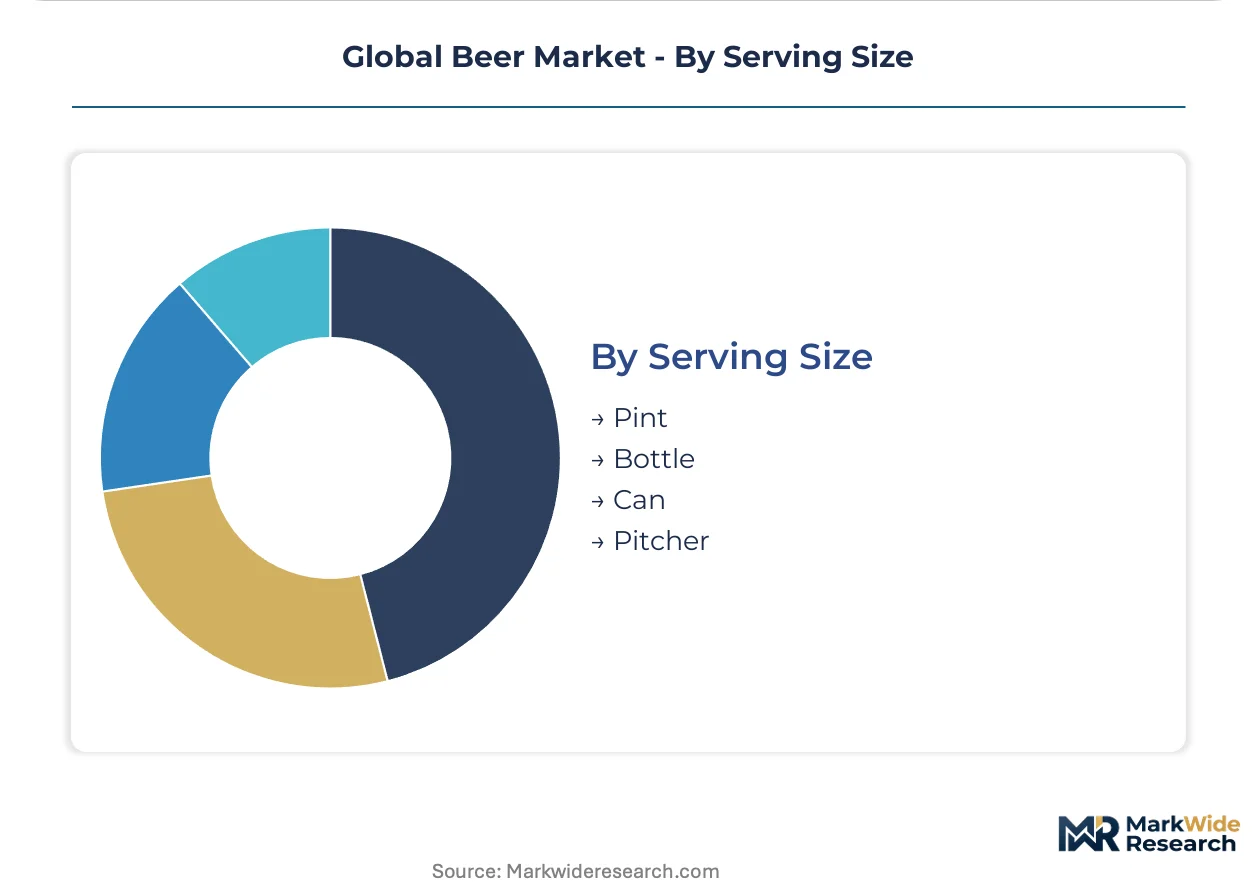
Can and bottle formats anchor off-trade volume while pint service maintains on-trade dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgian and Czech brewing heritage anchors European supply, while Vietnamese manufacturing expansion and Chinese consumption scale reshape volume distribution across the analysis window.
United States
Craft brewery proliferation in Colorado and Oregon drives demand for IoT-enabled fermentation monitoring systems. FDA labeling requirements and TTB formula approvals govern import access and ingredient disclosure thresholds for foreign producers. Mid-size facilities in the Pacific Northwest deploy predictive maintenance platforms to prevent unplanned downtime during peak seasonal windows.
Germany
Reinheitsgebot tradition sustains premium positioning for domestic lager and pilsner formats. EU Green Deal carbon targets and REACH chemical standards compel investment in anaerobic digesters and heat recovery systems across Bavarian production assets. Brownfield breweries in North Rhine-Westphalia face retrofit complexity when installing digital monitoring alongside legacy copper kettles.
Vietnam
Ho Chi Minh City nightlife operators negotiate exclusive tap placements with multinational brewers, pulling malt suppliers and keg logistics providers into Mekong Delta hub configurations. SAMR-equivalent national standards on alcohol content declaration shape formulation decisions for brands entering adjacent ASEAN markets. New malt houses and packaging lines attract regional investment, enabling integrated production footprints.
China
SAMR enforces GB standards on alcohol content declaration and additive permissibility that favor established brands with compliance infrastructure. Functional water and adaptogenic drink categories capture occasion-based consumption previously defaulting to beer among 25-34 demographic cohorts in urban centers. Tsingtao Brewery Group anchors volume in Northeast Asian export channels.
Belgium
Spontaneous fermentation expertise in lambic and Flemish red ale production commands premium compensation for specialized brewmasters. EU F-Gas Regulation phase-down schedules accelerate transitions from hydrofluorocarbon-based refrigeration to ammonia and CO2 cascade systems. Traditional producers in the Brussels corridor maintain mixed-culture capabilities that constrain scale-up velocity.
Global Beer Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base stratifies between consolidated multinationals with captive yeast strain libraries and fragmented craft operators dependent on third-party malt supply. Three archetypes dominate: heritage-brand volume producers, terroir-focused regional specialists, and technology-enabled craft scale-ups. Competitive moves concentrate on exclusive pouring contracts in concentrated hospitality corridors and backward integration into localized barley sourcing partnerships.
Among heritage-brand volume producers, Anheuser-Busch InBev and Heineken occupy positions defined by tap handle exclusivity negotiations across Southeast Asian nightlife districts. Tsingtao Brewery Group represents the scale-driven archetype, anchoring Northeast Asian export channel access. These three exemplify how biological asset control and captive supply arrangements secure flavor consistency against commodity input volatility.
| Leading Market Players |
|---|
| Anheuser-Busch InBev |
| Heineken |
| China Resources Snow Breweries |
| Carlsberg Group |
| Molson Coors Beverage Company |
| Tsingtao Brewery Group |
| Asahi Group Holdings |
| Constellation Brands |
| Kirin Holdings |
| Others |
Supply Flow & Price Mechanics
Barley and malt input cost volatility across Australian and Canadian grain belts compresses margin predictability while simultaneously widening pricing tier spreads between mass-market lager and craft ale categories. EU Green Deal carbon border adjustments and REACH chemical standards add compliance-driven cost layers that reshape procurement geography and supplier selection criteria across European brewing assets.
Pricing Analysis
EU Green Deal decarbonization mandates dictate the pricing tier structure by imposing differential compliance burdens across production scales. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale economies. Cost compression in the economy tier is intensifying because glass and aluminum packaging concentration among three European container manufacturers limits negotiation leverage for smaller brewers. Craft beer enthusiasts demonstrate the lowest price sensitivity, accepting three-to-five-fold premiums for barrel-aged and mixed-culture offerings, while casual drinkers anchor to promotional pricing in supermarket channels.
Supply Chain Analysis
Malted barley feedstock draws from Australian, Canadian, and Argentine grain belts where climate-induced harvest variability creates input cost instability. Specialized hop varieties from Germany and the Czech Republic, proprietary yeast strain libraries held by consolidated multinationals, and premium glass packaging from European container manufacturers constitute critical dependencies. Single-source vulnerability in specialty bottle supply creates bottleneck risk for craft brewers requiring premium presentation formats. Distribution runs through consolidated hospitality groups in Southeast Asian urban corridors and direct-to-consumer subscription platforms in North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital instrumentation platforms and biological process control systems are converging to create platform-economics inflection points where IoT-enabled fermentation monitoring and predictive maintenance reshape production economics and competitive moats.
For Market Incumbents: Harden biological asset control through captive yeast strain libraries and localized barley sourcing partnerships that secure flavor consistency against commodity volatility. Deepen channel control via exclusive pouring contracts in Vietnam's urban hospitality corridor where district-level nightlife operators negotiate tap handle exclusivity. Invest in anaerobic digester retrofits ahead of EU F-Gas Regulation phase-down deadlines to convert compliance burden into operational advantage. For New Entrants and Emerging Players: Mid-size craft breweries in Colorado and Oregon represent the most penetrable entry point for IoT-enabled fermentation monitoring system vendors seeking reference customers. Vietnam's Mekong Delta brewing corridor fragmentation enables integrated production footprints that bypass import tariff exposure for malt suppliers and packaging equipment providers. Direct-to-consumer subscription models offer the strongest go-to-market angle to capture margin previously surrendered to distributor tiers. For Investors and Strategic Acquirers: EU Green Deal carbon border adjustments reshape the acquisition landscape by favoring assets with existing biogas capture infrastructure over brownfield facilities requiring capital-intensive retrofit. Target craft scale-ups with proprietary mixed-culture fermentation capabilities and established direct-to-consumer channels for long-term viability. Watch for divergence between EU enforcement capacity and emerging economy compliance timelines as the signal indicating competitive access shifts across priority export corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Localized Barley Sourcing | Heineken's partnerships demonstrate how biological asset control secures supply chain autonomy against commodity volatility. |
| IoT-Enabled Fermentation Monitoring Deployment | Mid-size craft breweries in Colorado and Oregon reduce batch-to-batch variation through real-time specific gravity tracking. |
| Exclusive Pouring Contract Negotiation | Anheuser-Busch InBev leverages tap handle exclusivity across Ho Chi Minh City nightlife districts to dominate premium draft placements. |
| Biogas Capture System Retrofit | German and Belgian breweries convert EU Green Deal compliance mandates into operational advantage through anaerobic digester investment. |
| Direct-to-Consumer Subscription Launch | Online retail platforms bypass traditional wholesale markups and capture first-party consumption data previously held by distributors. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with brewmasters, malt procurement leads, on-trade beverage program managers, and fermentation science specialists; and secondary validation through customs and trade data, EU ETS carbon market disclosures, brewery SEC filings, and national alcohol regulatory databases. Bottom-up triangulation against top-down market sizing ensured consistency across volume and value estimates.
Forecast inputs considered product type segmentation across lager, ale, stout, and pilsner categories; distribution channel dynamics spanning supermarkets, liquor stores, restaurants, and online retail; and consumer type differentiation between craft enthusiasts, casual drinkers, connoisseurs, and occasional consumers. CAGRs were derived through regression analysis of historical volume trajectories adjusted for regulatory inflection points and channel shift elasticities across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in grain commodity prices, carbon credit market volatility, or hospitality sector recovery patterns would shift the trajectory. Quarterly review of EU ETS carbon price movements, ASEAN import tariff schedules, and China SAMR regulatory bulletins is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Global Craft Vodka Market
Alcoholic Beverages
Beer Line Cooling System Market
Alcoholic Beverages
Cordial Drink Market
Alcoholic Beverages
Global TCD Alcohol DM Market
Alcoholic Beverages
E-Commerce Liquor Market
Alcoholic Beverages
Cocktail Mixers Market
Alcoholic Beverages
Bright Beer Tank Market
Alcoholic Beverages
North America Soju Market
Alcoholic Beverages
Pinot Noir Market
Alcoholic Beverages
Premix Bottled Cocktails Market
Alcoholic Beverages
Electrolyte Beer Market
Alcoholic Beverages
Port Wine Market
Alcoholic Beverages
Barware Market
Alcoholic Beverages
Global Bourbon Market
Alcoholic Beverages
Brandy Flavor Market
Alcoholic Beverages
North America Alcoholic Beverages Market