
 Gluten Free Alcoholic Drinks Market | 2026-2036
Gluten Free Alcoholic Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten Free Alcoholic Drinks Market Foresight
Subscription-based replenishment and membership clubs for recurring gluten-free beer deliveries is restructuring how producers secure lifetime value from consumers with celiac disease or gluten sensitivity. Diageo plc leverages its global distribution infrastructure to place gluten-free variants in mainstream retail channels beyond specialty stores. Ghostfish Brewing Company anchors its competitive position through dedicated gluten-free facility operations that eliminate cross-contamination risk entirely.
Gluten free alcoholic drinks are beverages formulated without wheat, barley, rye, or other gluten-containing grains, typically produced through alternative grain bases such as sorghum, rice, millet, or quinoa, or through enzymatic processes that reduce gluten content below detectable thresholds, serving consumers with celiac disease, non-celiac gluten sensitivity, or elective dietary preferences. Beer dominates product type volume due to established brewing techniques for gluten-free grains, though ready-to-drink cocktails represent the fastest-expanding segment as convenience-oriented formulations attract younger demographics. Specialty stores capture premium margin pools through curated selection and educated staff, while online retailers compete on subscription mechanics and direct-to-consumer access.
The U.S. FDA enforces gluten-free labeling standards below 20 parts per million, compelling domestic and imported producers to validate supply chain integrity and testing protocols. The EU's regulation through EFSA and national bodies such as BfArM in Germany mandates equivalent thresholds with additional allergen disclosure requirements that shape export-ready formulation strategies. Stakeholders must monitor evolving enforcement patterns across multiple jurisdictions while building redundant certification pathways to sustain market access.
Market Dynamics
Enzymatic gluten degradation technology is compressing production timelines and broadening the addressable consumer base beyond celiac patients to elective gluten-avoiders, fundamentally restructuring competitive positioning between dedicated gluten-free facilities and converted conventional breweries.
Growth Catalysts
- FDA gluten-free labeling standard:The 20 parts per million threshold mandates validated testing protocols, compelling producers to invest in supply chain traceability systems that simultaneously unlock export eligibility to Australia and Germany.
- Millennial health-conscious consumption:This demographic cohort demonstrates elevated willingness-to-pay for certified beverages, driving hospitality channel penetration and specialty retail shelf-space expansion.
- Sorghum and quinoa brewing:Alternative grain processing advances enable flavor parity with conventional barley-based formulations, removing the historical taste penalty that constrained repeat purchase rates.
Market Restraints
- Input cost volatility:Sorghum and millet supply concentrates in drought-prone regions of Sub-Saharan Africa and South Asia, exposing margins to climate-driven harvest variability without futures market hedging mechanisms.
- Technical limitation:Enzymatic gluten reduction below detectable thresholds requires precise temperature and pH control that legacy brewing infrastructure cannot accommodate without substantial retrofit investment.
- Regulatory friction:EFSA allergen disclosure requirements exceed FDA stringency, forcing dual-formulation strategies or exclusion from German and broader EU distribution channels.
Strategic Opportunities
- Underpenetrated hospitality channels:Australian on-premise venues demonstrate accelerating certified gluten-free tap installation, creating first-mover advantage for producers securing exclusive distribution partnerships.
- Subscription replenishment mechanics:Direct-to-consumer recurring delivery models capture lifetime value from diagnosed celiac patients with predictable consumption patterns and elevated brand loyalty.
- Ready-to-drink cocktail convergence:Convenience-oriented formulations combining gluten-free spirits with natural mixers attract younger demographics outside traditional beer-centric occasions.
Industry Challenges
- Certification timeline compression:Third-party gluten-free validation from organizations like the Gluten Intolerance Group requires 6-12 month audit cycles that delay product launches and tie up working capital.
- Cross-contamination prevention capex:Dedicated facility construction or segregated production line installation demands upfront investment that mid-scale craft producers struggle to finance.
- Technical talent scarcity:Brewing chemists with specialized expertise in alternative grain enzymology command premium compensation, constraining formulation innovation at emerging competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten Free Alcoholic Drinks Market |
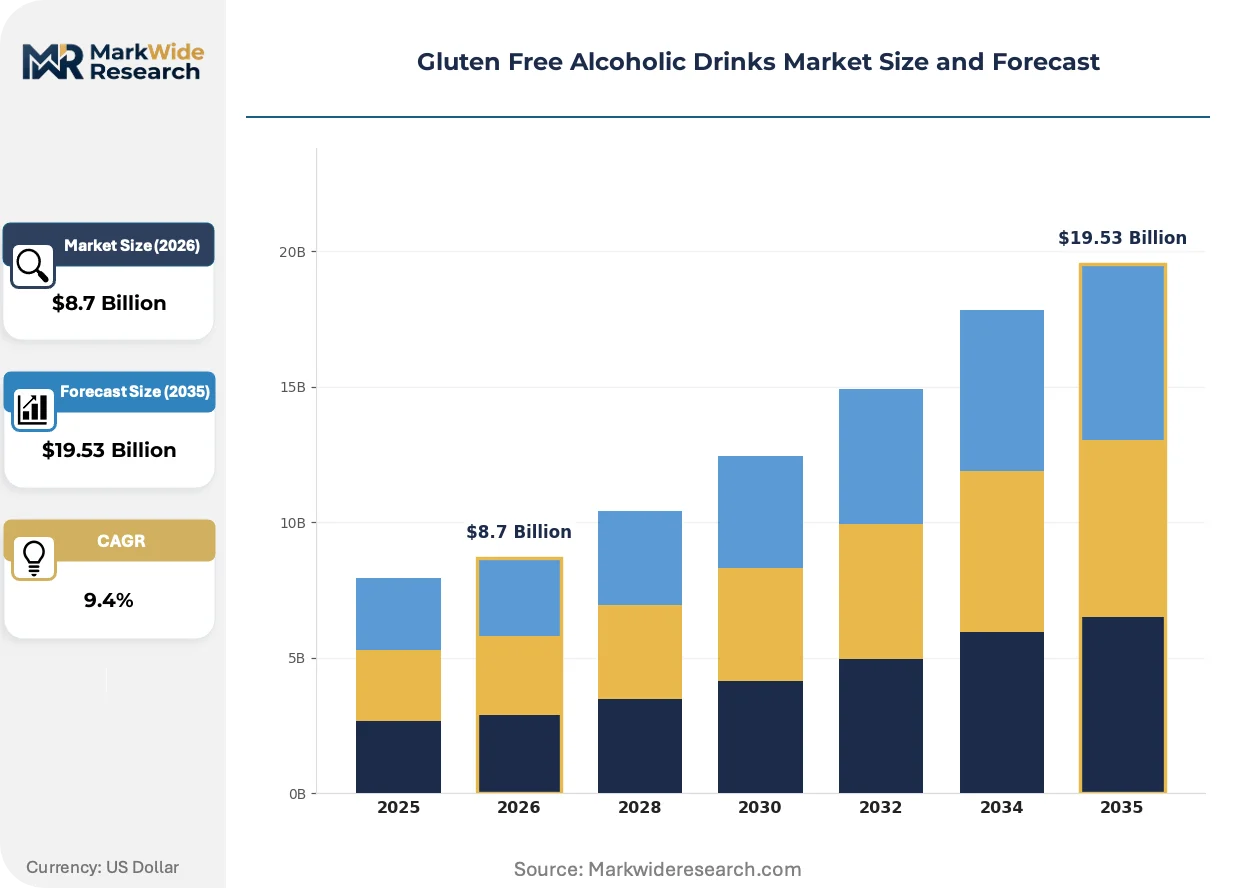
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beer, Wine, Spirits, Ready-to-Drink Cocktails, Ciders Distribution Channel: Supermarkets & Hypermarkets, Liquor Stores, Online Retailers, Hotels & Restaurants, Specialty Stores Consumer Demographic: Millennials, Gen Z, Health-Conscious Adults, Celiachs, Wellness Enthusiasts Production Method: Fermentation, Distillation, Cold Brew, Infusion, Carbonation |
| Companies Covered | Diageo plc, William Grant & Sons Ltd, Anheuser-Busch InBev, Glutenberg, Ghostfish Brewing Company, Estrella Damm Daura, Captain Morgan, Cabo Wabo, Omission Brewing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten Free Alcoholic Drinks Market Shifts & Advancements
Biotechnology and distribution mechanics are converging to eliminate the traditional trade-off between gluten-free certification and sensory quality, while regulatory harmonization efforts create new compliance architectures.
Enzymatic gluten hydrolysis using proline-specific endoproteases is overtaking dedicated gluten-free grain brewing as the preferred production pathway for major producers. Large-scale facilities in the United States and Germany deploy Brewers Clarex and similar enzyme systems to convert conventional barley mashes into sub-20 ppm finished products. This technology is overtaking facility-segregation approaches by eliminating capital intensity while preserving barley's flavor contribution.
REACH and EU FIC allergen labeling frameworks are tightening disclosure requirements for processed agricultural inputs. German BfArM enforcement actions against mislabeled "gluten-reduced" products have triggered industry-wide reformulation audits. Ready-to-drink cocktail manufacturers targeting German distribution are responding by securing dual FDA-EFSA certification pathways ahead of 2025 implementation deadlines.
Health-system referral networks are embedding certified gluten-free beverages into celiac disease management protocols. Australian gastroenterology clinics now direct newly diagnosed patients toward TGA-approved product registries, displacing self-directed trial-and-error purchasing. This behavior shift concentrates most visible in Sydney and Melbourne metropolitan clusters where specialty retail density supports immediate fulfillment of physician recommendations.
Gluten Free Alcoholic Drinks Market Segmentation
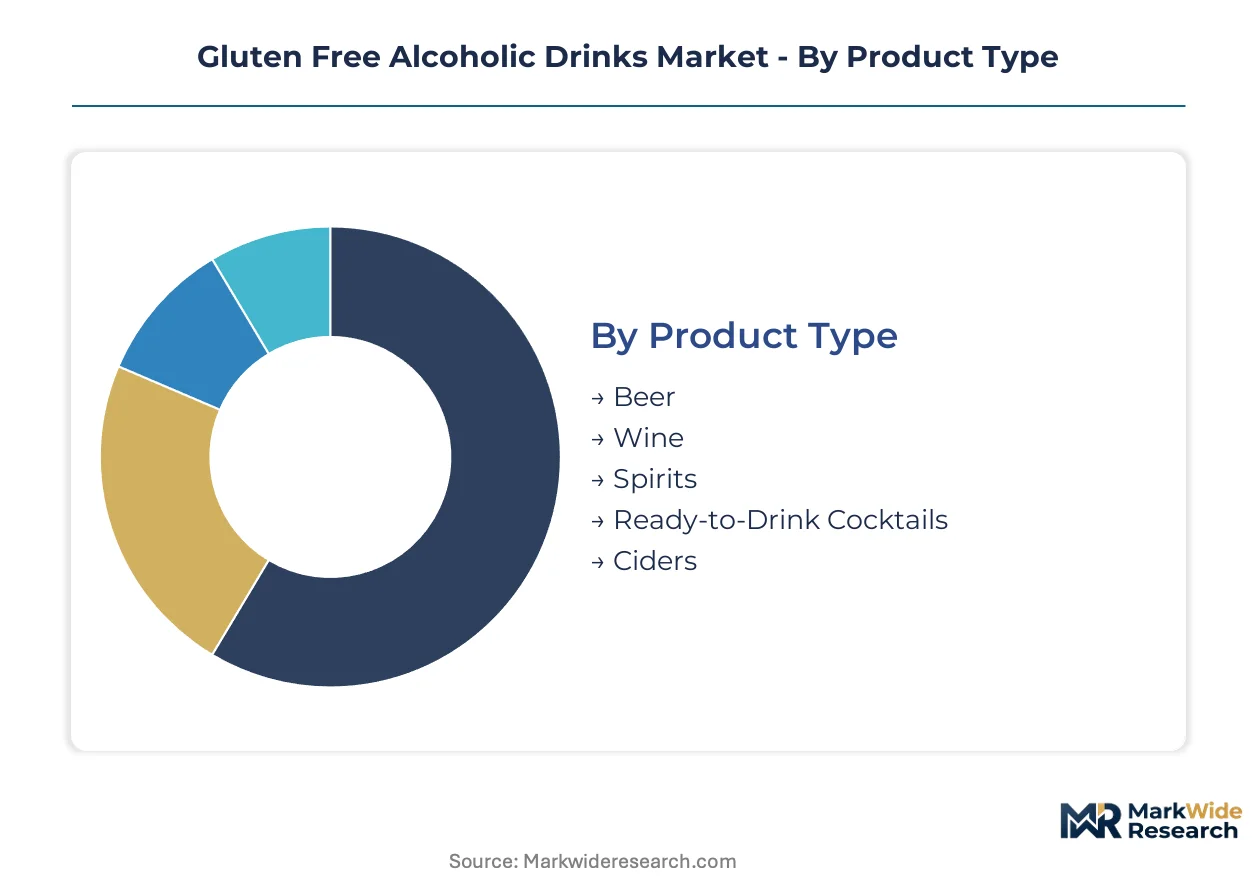
Segmentation in gluten-free alcoholic beverages determines formulation investment priorities, certification pathway selection, and channel-specific margin capture. Producers align R&D spending and facility configuration against the highest-value combinations of product type, production method, and consumer demographic.
Product Type:
Beer operates as a standalone category requiring dedicated gluten-free grain sourcing or enzymatic processing infrastructure, while spirits and ready-to-drink cocktails embed gluten-free claims within broader portfolio positioning.
- Beer:Sorghum, millet, and rice-based formulations dominate volume, with enzymatic gluten reduction using Brewers Clarex enabling barley-derived production without facility segregation. Demand concentrates in United States specialty retail and German on-premise channels where FDA and BfArM certification unlocks shelf placement.
- Ready-to-Drink Cocktails:Pre-mixed formulations combining gluten-free spirits with natural mixers attract convenience-seeking younger demographics outside traditional beer occasions. Australian hospitality venues in Sydney and Melbourne metropolitan clusters demonstrate accelerating tap installation for certified RTD lines.
- Wine:Naturally gluten-free status requires minimal processing adaptation, with producers emphasizing certification for celiac consumer reassurance.
- Spirits:Distillation inherently removes gluten proteins, though labeling claims demand validated supply chain documentation for FDA compliance.
- Ciders:Apple and pear-based fermentation bypasses grain inputs entirely, appealing to elective gluten-avoiders seeking flavor variety.
Beer leads volumes today; ready-to-drink cocktails are gaining share fastest.
Distribution Channel:
Channel selection determines margin structure and consumer education intensity, with specialty formats commanding premium pricing through curation while mass retail competes on accessibility.
- Specialty Stores:Curated selection and educated staff capture premium margins from diagnosed celiac patients seeking verified certification. United States and Australian specialty retailers maintain TGA and Gluten Intolerance Group validation registries that reduce consumer search costs.
- Online Retailers:Subscription mechanics and direct-to-consumer access enable recurring replenishment models that secure lifetime value from predictable consumption patterns. German e-commerce platforms face EFSA allergen disclosure requirements that exceed FDA stringency.
- Supermarkets & Hypermarkets:Mainstream shelf placement requires scaled production and national distribution infrastructure.
- Liquor Stores:State-level licensing variations in the United States create fragmented access patterns.
- Hotels & Restaurants:On-premise certification demands segregated tap systems and staff training protocols.
Specialty stores anchor premium pricing; online retailers show the steepest expansion trajectory.
Consumer Demographic:
Demographic targeting shapes formulation positioning, with diagnosed medical conditions driving certification requirements while elective preferences enable broader ingredient flexibility.
- Celiacs:Medically diagnosed patients require sub-20 ppm validated products with third-party certification, demonstrating highest brand loyalty and willingness-to-pay for supply chain transparency. Australian gastroenterology clinics in Sydney and Melbourne now direct newly diagnosed patients toward TGA-approved registries.
- Millennials:Health-conscious consumption patterns drive hospitality channel penetration and experimental flavor adoption across alternative grain bases.
- Gen Z:Convenience orientation and social media influence accelerate ready-to-drink cocktail trial rates.
- Health-Conscious Adults:Elective gluten avoidance permits formulation flexibility without stringent certification investment.
- Wellness Enthusiasts:Holistic lifestyle positioning aligns with natural ingredient and low-calorie variant preferences.
Celiacs command premium pricing consistency; millennials are expanding the addressable base most rapidly.
Production Method:
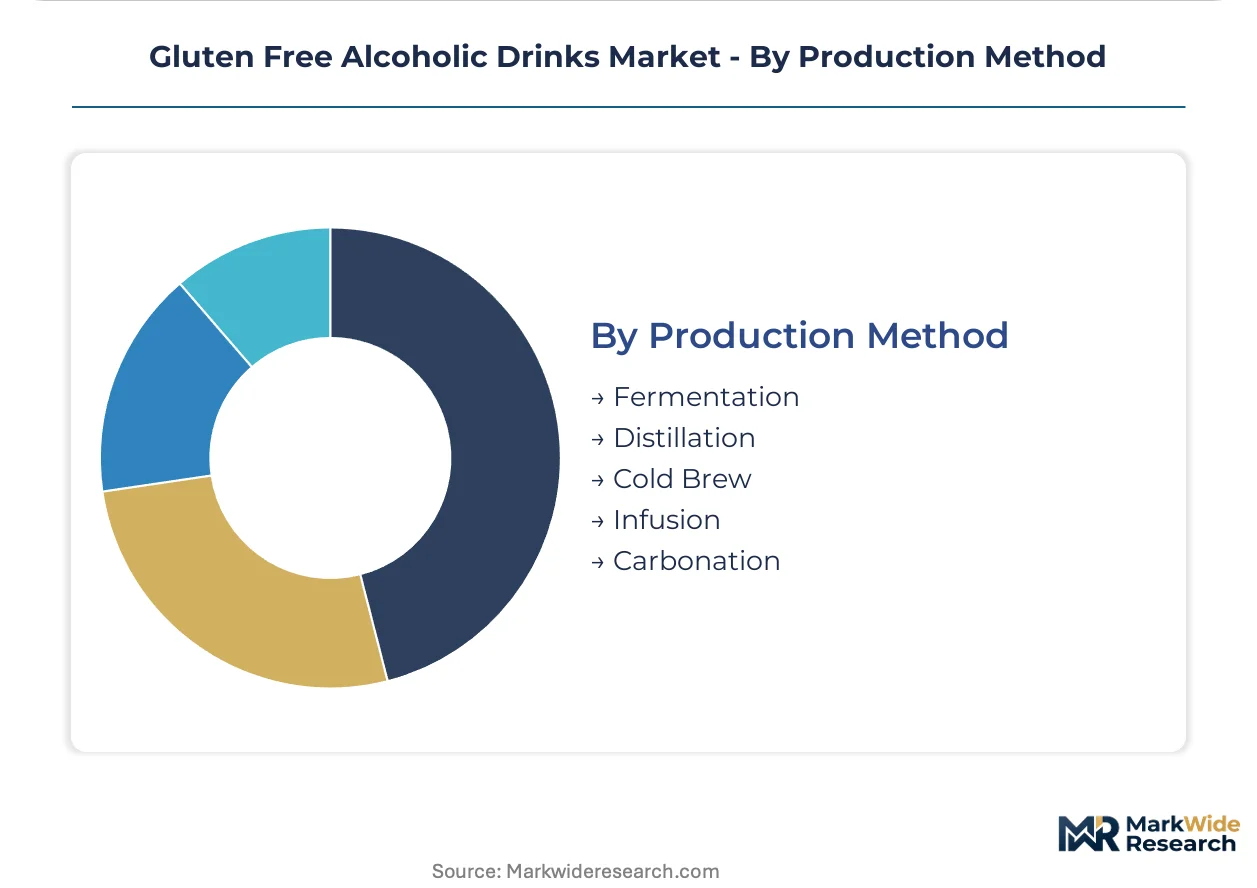
Method selection determines capital intensity and regulatory compliance architecture, with enzymatic approaches compressing timelines versus dedicated facility construction.
- Fermentation:Alternative grain fermentation using sorghum, quinoa, or millet requires specialized brewing chemists with enzymology expertise that commands premium compensation and constrains emerging competitor capacity.
- Distillation:Heat-based protein separation enables gluten-free spirit claims with validated input documentation rather than facility segregation.
- Cold Brew:Low-temperature extraction preserves volatile compounds in coffee and tea-based alcoholic formulations.
- Infusion:Flavor integration through botanical steeping accommodates small-batch craft positioning.
- Carbonation:Forced carbonation systems enable consistent texture in ready-to-drink formats.
Fermentation dominates current capacity; enzymatic modification within fermentation lines is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States regulatory stringency contrasts with Australia's health-system integration, creating divergent pathways for market penetration despite comparable per-capita consumption potential.
United States
Millennial health-conscious consumption and celiac patient advocacy groups drive specialty retail expansion. FDA's 20 parts per million gluten-free labeling standard mandates validated testing protocols that domestic and imported producers must satisfy. California and New York metropolitan clusters host the densest concentration of certified gluten-free tap installations in hospitality venues.
Germany
Beer culture heritage and diagnosed celiac prevalence create sustained demand for certified alternatives. BfArM enforcement actions against mislabeled gluten-reduced products have tightened compliance requirements beyond EFSA baselines. Bavaria and North Rhine-Westphalia anchor production capacity for enzymatic gluten reduction using Brewers Clarex systems.
Australia
Health-system referral networks embed certified beverages into celiac disease management protocols. TGA approval requirements for gluten-free claims exceed FDA stringency in documentation depth. Sydney and Melbourne metropolitan clusters demonstrate accelerating certified tap installation rates in on-premise venues.
United Kingdom
Free-from product proliferation in mainstream retail channels normalizes gluten-free alcoholic options. FSA allergen labeling guidance aligns with EU FIC frameworks while permitting national discretion in enforcement timing. London and Southeast England concentrate specialty retail density and direct-to-consumer subscription fulfillment infrastructure.
Gluten Free Alcoholic Drinks Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with dedicated gluten-free facilities commanding premium positioning against enzymatic conversion approaches. The vendor base organizes around three strategic archetypes: global beverage conglomerates leveraging distribution infrastructure, regional craft specialists operating certified segregated facilities, and contract brewers offering enzymatic processing services. Competitive moves concentrate on securing dual FDA-EFSA certification pathways and exclusive hospitality distribution partnerships in underpenetrated channels.
Within the multinational tier, Diageo plc and Anheuser-Busch InBev occupy positions defined by global distribution reach and portfolio diversification capabilities. Among dedicated craft specialists, Ghostfish Brewing Company exemplifies the certified segregated facility model that eliminates cross-contamination risk entirely. These three anchors represent divergent strategic bets on production methodology and channel access.
| Leading Market Players |
|---|
| Diageo plc |
| William Grant & Sons Ltd |
| Anheuser-Busch InBev |
| Glutenberg |
| Ghostfish Brewing Company |
| Estrella Damm Daura |
| Captain Morgan |
| Cabo Wabo |
| Omission Brewing Company |
| Others |
Supply & Pricing Matrix
EU FIC allergen labeling mandates gate qualified supply access and premium-tier pricing power by compelling dual-certification investment that only scaled producers can amortize across volume. Producers lacking parallel FDA and EFSA validation face automatic exclusion from German hospitality channels where TGA-equivalent documentation commands shelf placement premiums.
Pricing Analysis
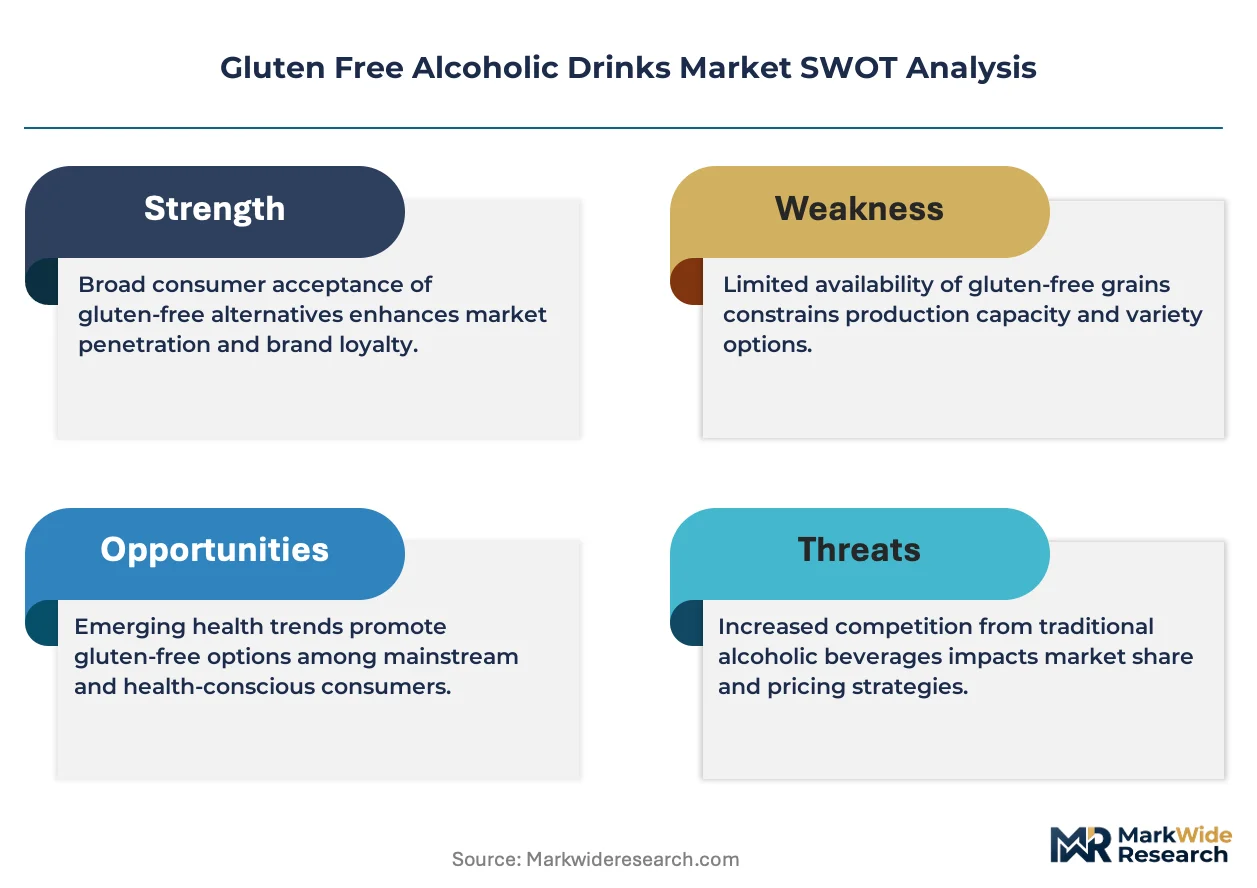
Capacity additions in the United States are reshaping price floors as enzymatic conversion facilities using Brewers Clarex systems expand output without dedicated gluten-free grain premiums. Three-tier pricing structure across certified-premium, standard-gluten-reduced, and economy-import tiers separates Ghostfish Brewing's segregated-facility products from Omission's enzyme-processed lines. Cost compression in the standard tier is intensifying because sorghum supply volatility from Sub-Saharan Africa exposes margins to climate-driven harvest failures. Diagnosed celiac patients demonstrate lowest price sensitivity due to medical necessity, while elective gluten-avoiders in the wellness segment drive volume through promotional responsiveness.
Supply Chain Analysis
Sorghum and millet supply rests on agricultural output from Sub-Saharan Africa, South Asia, and the United States Great Plains, with quinoa sourcing concentrating in Peru and Bolivia. Alternative grain procurement, enzyme inputs from Danish biotechnology suppliers, and segregated facility construction materials constitute critical dependencies. Single-source vulnerability in proline-specific endoprotease production creates bottleneck risk for enzymatic conversion pathways. Distribution runs through specialty retail chains in Sydney, Melbourne, and California metro clusters before expanding to mainstream supermarket placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where producers can capture margin spreads between FDA-regulated U.S. production and EFSA-stringent German pricing premiums.
For Market Incumbents: Anchor market position through exclusive distribution partnerships with Australian hospitality venues installing certified gluten-free tap systems. Secure backward integration into sorghum and quinoa sourcing through offtake agreements with drought-resilient farming cooperatives. Invest in dual FDA-EFSA certification pathways ahead of 2025 implementation deadlines to preempt regulatory exclusion from German channels.
For New Entrants and Emerging Players: TGA approval requirements in Australia open a window for health-system referral network penetration where gastroenterology clinics direct newly diagnosed patients toward certified product registries. Target ready-to-drink cocktail formulations in Sydney and Melbourne metropolitan clusters where convenience-oriented younger demographics accelerate trial rates. Pursue subscription replenishment mechanics that capture lifetime value from predictable celiac consumption patterns.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale craft specialists with segregated facility assets because certification timeline compression creates scarcity value for third-party-validated production capacity. Monitor enzymatic technology licensing deals as inflection indicators for production methodology shifts that could strand dedicated-facility investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Pathway | Parallel FDA and EFSA validation unlocks German hospitality channel access. |
| Subscription Replenishment Launch | Recurring delivery models secure lifetime value from diagnosed celiac patients. |
| Enzymatic Technology Licensing | Brewers Clarex deployment eliminates capital intensity of facility segregation. |
| Health-System Partnership | TGA-approved registry placement embeds products into clinical referral protocols. |
| Alternative Grain Backward Integration | Captive sorghum supply hedges climate-driven input cost volatility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brewing chemists, specialty retail category managers, hospitality procurement directors, and celiac patient advocacy group leaders with secondary validation against FDA gluten-free labeling guidance documents, EFSA allergen framework updates, TGA approval registries, and BfArM enforcement action records. Bottom-up demand modeling from diagnosed celiac prevalence and elective gluten-avoidance rates triangulated against top-down beverage industry production capacity assessments.
Segment-weighting applied product type, production method, distribution channel, and consumer demographic dimensions across the projection horizon. CAGRs derived from elasticity-adjusted volume trajectories incorporating hospitality channel penetration curves and subscription adoption patterns. Forecast inputs included enzymatic technology diffusion rates and health-system referral network expansion timelines.
Revisions become necessary when regulatory enforcement patterns shift, alternative grain harvest failures persist across multiple growing seasons, or enzymatic processing achieves sensory parity breakthroughs that displace dedicated facility demand. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Germany Tequila Market
Alcoholic Beverages
Alcoholic Drinks Market
Alcoholic Beverages
Beer Fermenter Market
Alcoholic Beverages
Microbrewery Supplies Market
Alcoholic Beverages
Mexico Tequila Market
Alcoholic Beverages
Fermented Beverages Market
Alcoholic Beverages
Brandy Market
Alcoholic Beverages
Rose Wine Market
Alcoholic Beverages
Hard Kombucha Market
Alcoholic Beverages
Woozy Bottle Market
Alcoholic Beverages
Middle East and Africa Fermented Drinks Market
Alcoholic Beverages
Yorker Spouts Market
Alcoholic Beverages
Rum Market
Alcoholic Beverages
Global Distillation System Market
Alcoholic Beverages
Vodka Market
Alcoholic Beverages
Global Food-Grade Alcohol Market