
 Wine Cellar Market | 2026-2036
Wine Cellar Market Size, Share, and Industry Trends Forecast 2026-2036
Wine Cellar Market Intelligence
The expansion into hospitality venues and wine bars from a traditional base in residential estates is repositioning the market’s customer profile. Wine Cellar Innovations specializes in large-scale custom designs for commercial clients, directly serving restaurateurs and hotels. Genuwine Cellars leverages its brand strength in the high-end residential segment. Vigilant Inc. competes by offering modular systems that appeal to both new private collectors and smaller commercial establishments.
A wine cellar is an engineered storage environment designed for the optimal aging and preservation of wine. These systems maintain precise temperature control and consistent humidity levels, preventing oxidation and cork degradation. While custom cellars for residential estates command the highest value per project, the freestanding cellars segment shows significant volume growth due to lower entry costs. The integration of smart monitoring technology represents a primary source of feature differentiation across all product types.
Component and system safety are governed by frameworks such as CE marking for electronics in Europe and UL certification for appliances in the United States. Energy efficiency regulations, including standards set by the US Department of Energy and EU energy labelling directives, are increasingly influencing the design of cooling and insulation systems. Manufacturers must now balance the demand for advanced, connected features with escalating requirements for energy performance and material sustainability.
Market Dynamics
The integration of smart monitoring technology is the central force shaping the wine cellar market. This convergence of IoT connectivity with stricter energy efficiency mandates from bodies like the US Department of Energy and the European Union is defining new product development cycles and feature differentiation.
Growth Catalysts
- Hospitality Sector Expansion:The integration of custom wine cellars into hotels, restaurants, and wine bars in metropolitan hubs like London and New York is creating a significant commercial demand stream beyond traditional residential projects.
- Smart Technology Integration:The adoption of IoT-enabled sensors for remote temperature, humidity, and inventory monitoring enhances wine preservation, appealing to both commercial venues and private collectors seeking advanced control and security.
- Growth in Private Collecting:An expanding base of new private collectors, particularly in markets like Hong Kong, is driving demand for smaller, modular systems that offer a lower entry point into fine wine storage.
Market Restraints
- High Capital Outlay:The significant upfront cost for custom-built cellars, including specialized cooling systems and insulation materials, remains a primary barrier for individual homeowners and smaller commercial establishments.
- Energy Efficiency Compliance:Increasingly stringent energy performance standards from the US Department of Energy and EU energy labelling directives add complexity and cost to cooling system design and manufacturing.
- Installation and Space Constraints:Custom cellar construction requires specialized labor and significant physical space, limiting viability in dense urban residential properties and pre-existing commercial buildings without renovation capacity.
Strategic Opportunities
- Modular System Development:Expanding offerings of pre-fabricated, modular wine cellar systems can capture the growing segment of new collectors and smaller restaurants who lack the budget or space for fully custom designs.
- Subscription-Based Monitoring:Developing subscription services for remote monitoring, inventory management software, and predictive maintenance provides a recurring revenue stream beyond initial hardware sales and installation.
- Targeting Emerging Fine Wine Hubs:Focusing sales and marketing efforts on rising fine wine markets such as Singapore and Dubai can capture new demand from a growing base of high-net-worth individuals and luxury hospitality venues.
Industry Challenges
- Certification and Testing Delays:Navigating the distinct and lengthy certification processes for UL in the United States and CE marking in Europe for electronic components creates operational hurdles and delays product launches.
- Sustainable Material Sourcing:Securing a consistent supply of sustainable and high-quality materials for insulation and racking, while managing cost pressures, presents a significant supply chain challenge for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wine Cellar Market |
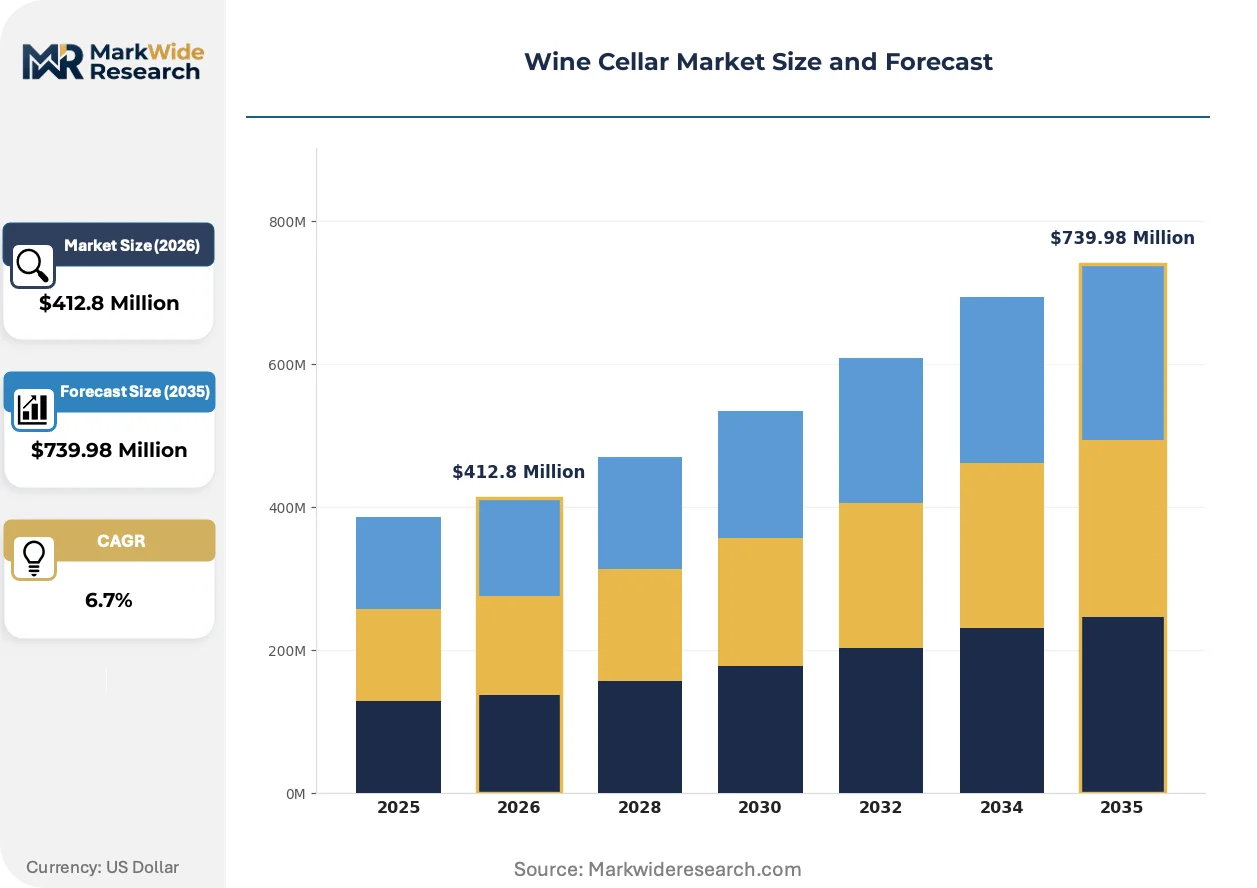
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $739.98 Million |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freestanding Cellars, Built-in Cellars, Modular Cellars, Custom Cellars Technology: Temperature Control, Humidity Control, Smart Monitoring, Insulation Systems, Ventilation Application: Residential Estates, Wine Bars, Hospitality Venues, Collectors’ Storage, Retail Outlets End User: Private Collectors, Restaurateurs, Beverage Distributors, Specialty Retailers, Enthusiast Clubs |
| Companies Covered | Vigilant Inc., Cellar Masters, Prestige Wine Cellars, Custom Wine Cellars, Wine Cellar Specialists, Genuwine Cellars, Wine Cellar Innovations, Retro Cellars, Kessick Wine Storage Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wine Cellar Market Strategic Shifts & Innovations
A fundamental shift from passive storage environments to active, data-driven management systems is underway. This evolution is driven by the convergence of digital technology with new regulatory pressures on energy consumption and material use, altering both product design and user expectations.
Cloud-connected sensor networks provide real-time data on temperature, humidity, and vibration. Commercial venues and private collectors are rapidly adopting these systems for enhanced preservation and inventory control. This integration of smart technology is decentralizing cellar management from a localized physical interface to globally accessible software platforms, enabling remote oversight and automated adjustments.
European F-Gas regulations and parallel initiatives by the US EPA mandate a phase-down of hydrofluorocarbon refrigerants. This forces manufacturers to redesign cooling systems to use alternative, lower-GWP refrigerants like R-600a. The transition impacts the entire cooling component supply chain, requiring significant R&D investment and product requalification.
Buyer preference is shifting from purely functional storage to aesthetically integrated design features, treating the wine cellar as a centerpiece of interior architecture. This trend moves beyond standard freestanding units, favoring custom glass-enclosed displays and unique material finishes. This demand is most prominent in the luxury residential and hospitality segments in cities like New York and London.
Wine Cellar Market Segmentation
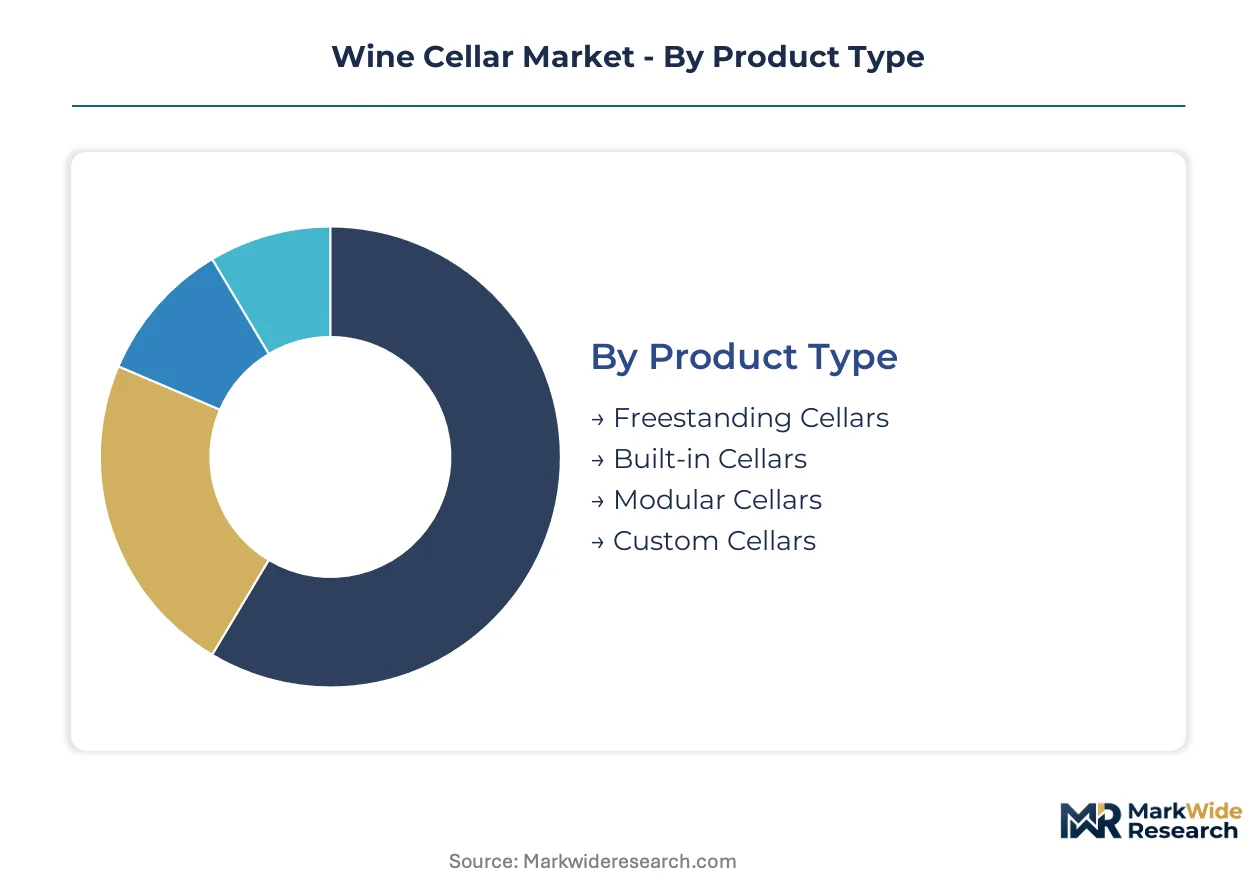
The wine cellar market diversifies across product designs, integrated technologies, and distinct end-use environments. Understanding these segments clarifies where value creation and demand concentration are occurring. This segmentation analysis identifies the specific characteristics driving purchasing decisions for both commercial and private clients.
Product Type:
Supply concentration in the wine cellar market reflects manufacturing specialization and installation complexity across various product types.
- Custom Cellars:These are bespoke, site-specific installations, often integrated into architectural plans for luxury residential estates or high-end hospitality venues. Demand concentrates in metropolitan areas like New York and London, driven by collectors seeking unique aesthetic integration and precise environmental control.
- Modular Cellars:Pre-fabricated units designed for flexible configuration and scalability, offering a balance between customization and ease of installation. New private collectors and smaller commercial establishments in growing markets like Hong Kong favor these systems due to their adaptability and lower entry cost.
- Freestanding Cellars:Self-contained, often plug-and-play units requiring no permanent installation.
- Built-in Cellars:Designed to integrate seamlessly into existing cabinetry or wall structures within residential or commercial spaces.
Custom Cellars absorbs the bulk of installed capacity; Modular Cellars is expanding most quickly.
Technology:
The application of specific technologies defines the performance and user experience within wine cellar systems.
- Smart Monitoring:This technology integrates IoT-enabled sensors for real-time data collection on temperature, humidity, and inventory levels, accessible via remote platforms. Commercial venues and private collectors in urban centers adopt these systems for enhanced preservation and operational efficiency.
- Temperature Control:These systems utilize refrigeration units to maintain a consistent, optimal temperature range within the cellar, crucial for preventing premature wine aging. Manufacturers are redesigning these systems to comply with energy efficiency regulations from the US Department of Energy and EU directives.
- Humidity Control:Specialized units regulate internal moisture levels, crucial for preventing cork shrinkage and oxidation.
- Insulation Systems:Materials and designs that minimize thermal transfer, ensuring stable internal conditions and energy efficiency for cooling units.
- Ventilation:Systems that circulate air within the cellar, preventing stale air and mold growth while maintaining consistent conditions.
Smart Monitoring technology is rapidly differentiating product offerings, while Temperature Control remains a foundational requirement for all wine cellars.
Application:
Customer type directly influences the scale, design, and feature requirements for wine cellar applications.
- Hospitality Venues:This segment includes hotels, restaurants, and clubs that integrate wine cellars for display, storage, and service, often requiring large-scale custom designs. Metropolitan hubs like London and New York drive this demand, focusing on aesthetic integration and inventory management.
- Residential Estates:Custom-built cellars within private homes, typically for high-net-worth individuals and serious wine collectors, prioritizing preservation and aesthetic value. These projects command the highest value per installation, particularly in established fine wine markets.
- Wine Bars:Establishments specializing in wine service, requiring efficient storage and display solutions, often with a focus on accessibility and presentation.
- Collectors’ Storage:Dedicated off-site facilities offering climate-controlled storage solutions for private collections, emphasizing security and optimal preservation.
- Retail Outlets:Commercial spaces using cellars for displaying and storing inventory, balancing optimal conditions with customer access and visual appeal.
Hospitality Venues are driving significant commercial demand, while Residential Estates continue to represent the highest value per project.
End User:
The maturity of end-user engagement with wine collecting and service dictates their specific needs from wine cellar solutions.
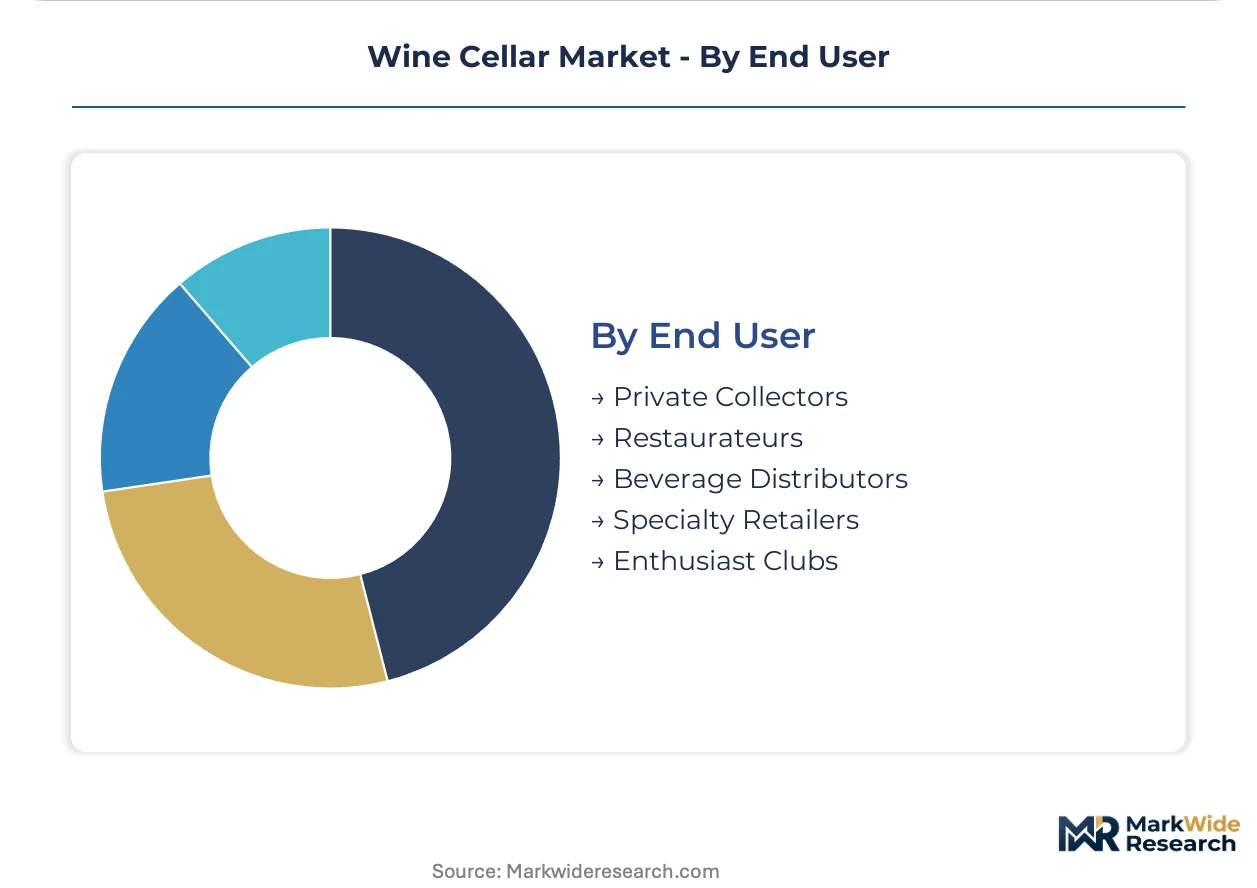
- Private Collectors:Individuals acquiring wine for personal consumption, investment, or long-term aging, ranging from new enthusiasts to seasoned connoisseurs. This segment drives demand for both high-end custom solutions and accessible modular systems, particularly in markets with expanding wealth.
- Restaurateurs:Owners and managers of dining establishments who require wine cellars for inventory management, display, and service. Their needs focus on operational efficiency, aesthetic integration, and precise environmental control to enhance the dining experience.
- Beverage Distributors:Wholesalers and logistics companies requiring large-scale, climate-controlled storage for transit and inventory management.
- Specialty Retailers:Stores focused on fine wine sales, needing controlled environments for product preservation and attractive display.
- Enthusiast Clubs:Groups or organizations providing shared storage facilities and educational resources for wine lovers.
Private Collectors form a broad customer base, and Restaurateurs represent a critical commercial segment for advanced wine storage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The wine cellar market exhibits a clear divide between established wine-producing regions and rapidly expanding consumption hubs. While traditional markets maintain demand for bespoke solutions, emerging economies are driving volume growth for accessible storage systems. This dynamic shapes regional investment and product development strategies.
United States
United States demand for wine cellars centers on luxury residential and high-end hospitality projects, particularly in metropolitan areas. The US Department of Energy's efficiency standards influence cooling system design and material choices for manufacturers. New York City and California's wine regions represent significant concentrations of both private collectors and commercial installations.
United Kingdom
United Kingdom's market for wine cellars is driven by aesthetic integration in luxury homes and commercial venues. CE marking requirements for electronic components ensure product safety and compliance across the region. London's fine dining scene and affluent residential areas drive substantial demand for custom installations.
Hong Kong
Hong Kong demonstrates robust demand for modular wine cellar systems among new private collectors. Local building codes and space constraints influence product design towards compact, efficient units. The city's dense urban environment fosters innovation in smaller-footprint storage solutions.
Singapore
Singapore's market is characterized by a growing base of high-net-worth individuals and luxury hospitality venues. Environmental regulations from the National Environment Agency guide the selection of refrigerants and insulation materials. The central business district and upscale residential developments are key areas for cellar installations.
United Arab Emirates
United Arab Emirates, particularly Dubai, shows strong demand for high-end custom wine cellars in luxury hospitality. Local energy efficiency standards impact cooling system specifications for large-scale projects. Dubai's expanding luxury hotel sector and private residences are primary drivers for bespoke cellar solutions.
Wine Cellar Market Key Industry Players
Top-tier vendors anchor the custom-built and high-end residential segments, while modular system providers cater to the expanding base of new collectors. The market features archetypes including large-scale commercial specialists, luxury residential providers, and adaptable modular system suppliers. Competitive moves often involve technology licensing for smart features and portfolio diversification into various product types.
Within the specialized custom design segment, Wine Cellar Innovations exemplifies capabilities in large-scale commercial projects, directly serving restaurateurs and hotels with bespoke installations. Genuwine Cellars occupies a strong position in the high-end residential market, leveraging its brand strength among affluent private collectors seeking aesthetic integration and precise environmental control. Vigilant Inc. represents providers offering modular systems that appeal to both new private collectors and smaller commercial establishments, focusing on adaptability and lower entry costs for fine wine storage.
| Leading Market Players |
|---|
| Vigilant Inc. |
| Cellar Masters |
| Prestige Wine Cellars |
| Custom Wine Cellars |
| Wine Cellar Specialists |
| Genuwine Cellars |
| Wine Cellar Innovations |
| Retro Cellars |
| Kessick Wine Storage Systems |
| Others |
Cost & Logistics Intelligence
The distinct tier divergence between bespoke custom cellars and accessible modular units fundamentally shapes both pricing power and supply chain configurations. Premium pricing aligns with unique architectural integration, while standardized units leverage volume-driven component sourcing.
Pricing Analysis
Shorter lead times for modular wine cellar systems attract lower price points compared to the premium commanded by custom, project-based installations. Pricing differentiates based on customization level and integrated smart monitoring technology. Upward pricing pressure stems from increasingly stringent energy efficiency regulations, particularly for cooling system components. New private collectors and smaller commercial venues exhibit higher price sensitivity, while high-net-worth residential estates and luxury hospitality venues prioritize bespoke solutions over cost.
Supply Chain Analysis
Skilled workforce availability for custom cellar installation concentrates in metropolitan hubs, particularly in North America and Europe. Component manufacturing for cooling systems primarily draws from China, Germany, and the United States. Key dependencies include low-GWP refrigerants and sustainable insulation materials. Commodity price volatility for these specialized materials presents a structural risk. Distribution runs through direct sales teams for custom projects and specialized dealer networks for modular and freestanding units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wine cellar market is rapidly becoming a vertical-integration race, with players actively pursuing control over smart monitoring technology development. Integrating IoT capabilities offers a significant downstream lever for recurring revenue.
For Market Incumbents: Cement existing market leadership by acquiring specialized smart monitoring technology firms, enhancing proprietary software platforms. Expand custom design and installation capabilities into emerging luxury hospitality markets like Dubai to counter new modular system providers. Invest in R&D for next-generation, F-Gas compliant cooling systems to mitigate regulatory threats and differentiate offerings.
For New Entrants and Emerging Players: Enter via modular, pre-fabricated wine cellar systems targeting new private collectors and smaller commercial establishments in dense urban areas. Focus on markets like Hong Kong and Singapore where space constraints favor compact solutions. A go-to-market angle emphasizing rapid deployment, remote monitoring, and accessible pricing can capture significant demand from this segment.
For Investors and Strategic Acquirers: Re-rating potential sits with specialist smart technology providers given the accelerating demand for data-driven wine preservation solutions. The market demonstrates long-term viability fueled by expanding fine wine collecting and luxury hospitality. Target acquisition archetypes include firms with proprietary IoT platforms or advanced sustainable cooling system IP. Watch for sustained growth in subscription-based remote monitoring services as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Diversification into Modular Systems | Captures new collector demand and expands market reach beyond custom installations. |
| Investment in Smart Monitoring R&D | Enhances feature differentiation and creates recurring revenue streams from service subscriptions. |
| Geographic Expansion into Emerging Luxury Hubs | Accesses new high-net-worth individuals and hospitality venues in untapped markets. |
| Supply Chain Optimization for Sustainable Materials | Addresses regulatory mandates and consumer preference for eco-friendly product designs. |
| Strategic Partnerships with Hospitality Design Firms | Integrates wine cellar solutions earlier into large-scale commercial project planning. |
Research Approach
Multi-period observation of luxury spending patterns and smart home technology adoption anchored the trend analysis, supplemented by interviews with key industry stakeholders. Primary research involved discussions with restaurateurs, private collectors, cellar designers, and cooling system engineers. Secondary validation drew from industry association reports, US Department of Energy standards, EU energy labelling directives, and architectural design publications. This approach ensured robust bottom-up and top-down triangulation of market insights.
An input-output matrix framing guided the market sizing and forecast models across the analysis window. Segmentation dimensions modeled included product type, integrated technology, application, end-user, and key metropolitan areas. Compound annual growth rates derived from historical data and projected demand drivers. Fine wine production volumes and high-net-worth individual growth rates served as critical forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid shifts in global economic stability or unforeseen regulatory changes. All forecasts reflect underlying assumptions regarding technology adoption and consumer spending. Material deviation in new energy efficiency mandates or critical component supply warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Middle East and Africa Kegs Market
Alcoholic Beverages
South America Alcoholic Beverages Market
Alcoholic Beverages
Rum Market
Alcoholic Beverages
Irish Whiskey Market
Alcoholic Beverages
Global Liquor Bottles Market
Alcoholic Beverages
Turkey Tequila Market
Alcoholic Beverages
Gin Market
Alcoholic Beverages
Cocktail Mixers Market
Alcoholic Beverages
Premixed Cocktail Shots Market
Alcoholic Beverages
Drinkware, Beverageware, and Barware Market
Alcoholic Beverages
Whey Based Vodka Market
Alcoholic Beverages
Alcoholic Ice Cream Market
Alcoholic Beverages
Europe Tequila Market
Alcoholic Beverages
Rose Wine Market
Alcoholic Beverages
Mezcal Market
Alcoholic Beverages
RTD Cocktails Market