
 Roasted Malt Market | 2026-2036
Roasted Malt Market Size, Share, and Industry Trends Forecast 2026-2036
Roasted Malt Market Analytics
European malting capacity is decoupling from commodity barley cycles as specialty roasting investments expand. Cargill Incorporated leverages integrated grain origination networks to secure premium barley streams for roasted malt production. Malteurop Group anchors its position through geographic proximity to major brewing customers across France and Germany. Boortmalt differentiates via Axéréal Group cooperative structure that links farmer contracts directly to specialty malt output.
Roasted malt comprises base malt subjected to controlled kilning or roasting at elevated temperatures, producing color development through Maillard reactions and caramelization while generating flavor compounds ranging from biscuit and toffee notes to intense coffee and burnt characteristics. The process typically operates between 100°C and 230°C depending on target color specification measured in European Brewing Convention units, with applications spanning beer color adjustment, flavor complexity addition, and distilling substrate preparation. Crystal malt occupies the largest volume position within product type segmentation due to its versatility across ale and lager styles, while chocolate malt commands premium positioning in stout and porter formulations where brewers seek intense roasted bitterness. Powdered form segments show structural expansion in baking and confectionery applications where precise dosing and solubility requirements favor fine particle distribution over traditional whole grain supply.
EU REACH regulations govern chemical substance registration in roasted malt processing aids and packaging contact materials, while FDA food safety standards apply to malt imports entering United States beverage and food manufacturing channels. Germany's BfR evaluates thermal process contaminants including acrylamide formation during high-temperature roasting stages, influencing equipment design and temperature protocol specifications across European production facilities. Organic certification frameworks under USDA National Organic Program and EU organic regulations create parallel supply chain requirements for maltsters serving craft segments. Stakeholders must monitor evolving maximum residue limits for mycotoxins and pesticide traces as importing jurisdictions tighten contaminant thresholds without harmonizing standards across regulatory zones.
Market Dynamics
Specialty malt roasting capacity is concentrating in producer-proximate clusters as craft brewers demand shorter lead times and certified provenance documentation, forcing malting groups to relocate roasting assets adjacent to barley growing regions rather than legacy port-based facilities.
Growth Catalysts
- EU organic regulations:Certification frameworks under EU organic regulations and USDA National Organic Program create parallel supply chains that command 15-30% price premiums across German and Belgian craft brewing segments.
- Maillard reaction control systems:Precision temperature and humidity management during kilning enables reproducible color specification in EBC units, allowing maltsters to serve multiple brewing customers from single production campaigns.
- Munich-Weimar corridor:Geographic concentration of traditional brewing clusters in Bavaria and Thuringia anchors procurement volumes for roasted specialty malts, with local maltsters capturing logistics advantages over distant competitors.
Market Restraints
- Barley input volatility:Premium malting barley supply concentrates in drought-exposed growing regions of France and Denmark, exposing roast malt producers to protein specification variance and crop insurance cost pass-through.
- Acrylamide formation thresholds:Germany's BfR evaluates thermal process contaminants during high-temperature roasting stages above 200°C, constraining color development protocols and requiring capital-intensive emission control retrofits.
- Black malt substitution:Patent malt and roasted barley extracts from flavor houses displace traditional roasted malt in cost-sensitive lager formulations, compressing volume in standard color adjustment applications.
Strategic Opportunities
- Distilling substrate expansion:Whiskey and craft spirits producers in Kentucky and Tennessee adopt roasted malt for flavor complexity, creating new demand verticals beyond traditional beer applications.
- Powdered malt confectionery channel:Fine particle distribution formats serve baking and chocolate manufacturing where precise dosing and solubility requirements favor malt-derived colorants over synthetic alternatives.
- EU Green Deal agricultural transition:Carbon farming incentives and regenerative agriculture mandates under EU Green Deal frameworks reward malting barley producers with certified low-carbon intensity, creating differentiated feedstock streams for premium roasting operations.
Industry Challenges
- Master maltster skill scarcity:Roasting expertise combining sensory evaluation with thermal engineering concentrates among aging workforce cohorts in traditional malting regions, constraining capacity expansion timelines.
- REACH registration timelines:Chemical substance documentation for novel processing aids and packaging contact materials extends 18-36 months, delaying formulation innovations and locking producers into legacy input suppliers.
- Legacy kiln retrofit complexity:Existing drum and tower roasting installations require staged automation upgrades to meet BfR emission protocols, fragmenting capital deployment across multi-year modernization programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roasted Malt Market |
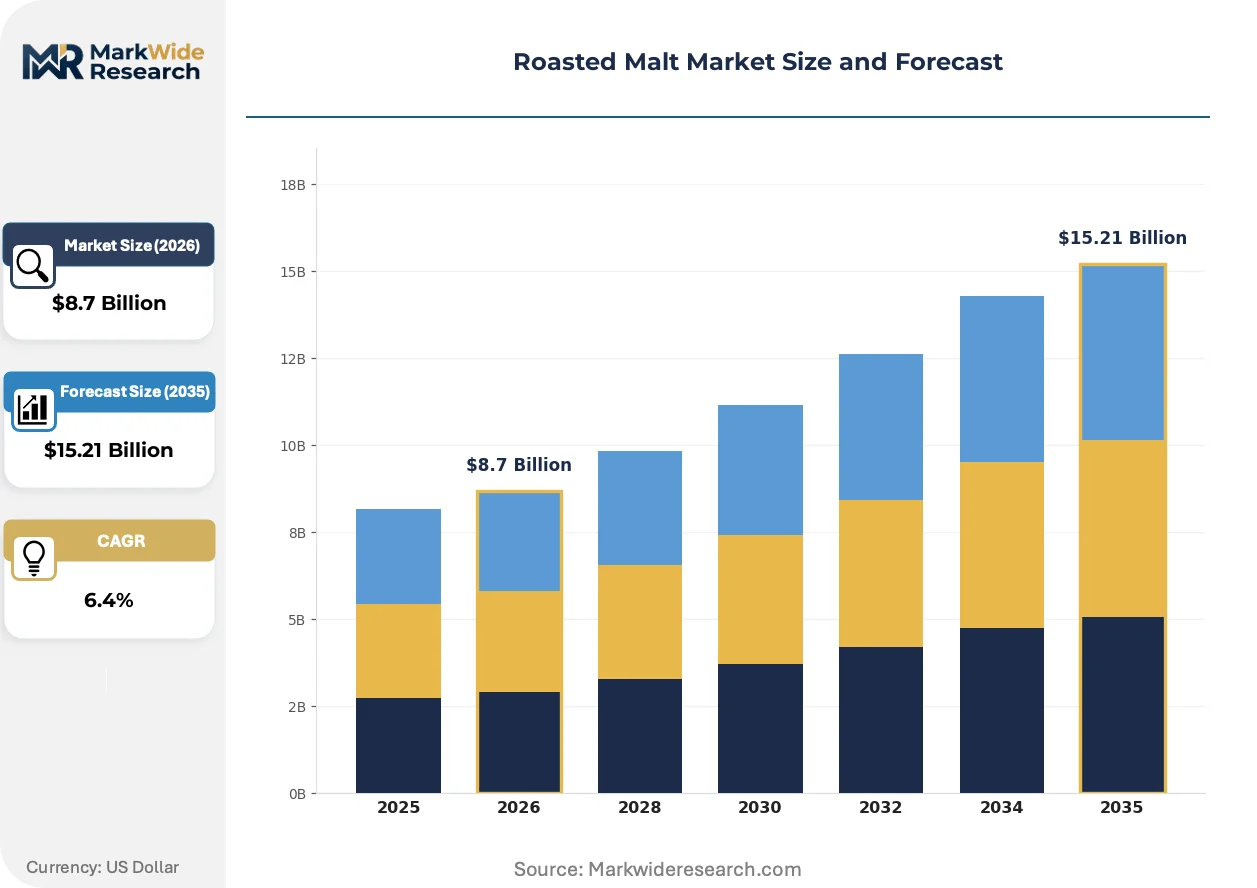
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pale Malt, Crystal Malt, Chocolate Malt, Black Malt End Use: Brewing, Distilling, Baking, Confectionery Form: Whole Grain, Crushed, Powdered, Liquid Quality Grade: Food Grade, Feed Grade, Organic, Others |
| Companies Covered | Cargill Incorporated, Malteurop Group, Boortmalt (Axéréal Group), GrainCorp Limited, Briess Malt & Ingredients, Simpsons Malt, Viking Malt, Muntons PLC, Great Western Malting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roasted Malt Market Evolving Landscape
Roasted malt production is bifurcating between heritage-protected traditional methods and digitally controlled precision roasting, with equipment suppliers embedding spectroscopic color monitoring and predictive moisture algorithms into new kiln designs.
Automated EBC spectrophotometry integrated with kiln atmosphere control is expanding into mainstream specialty malt operations. Mid-sized maltsters in Belgium and the Czech Republic deploy these systems to reduce batch-to-batch color variance from ±8 EBC to ±3 EBC. The technology is compressing quality assurance labor costs while enabling just-in-time roasting campaigns against confirmed brewery orders rather than speculative inventory builds.
REACH chemical safety standards governing processing aids and food contact materials are tightening contaminant documentation requirements across European roasting facilities. Maltsters must now register thermal process byproducts and packaging migration substances with ECHA, extending compliance timelines and favoring larger producers with dedicated regulatory affairs functions. German and French facilities are responding by consolidating supplier bases to reduce documentation burden per input stream.
Direct contracting between craft brewers and single-origin maltsters is displacing traditional distributor-mediated procurement in North American and European specialty segments. Small breweries in Oregon, Vermont, and Flanders now specify barley variety, growing region, and roasting protocol through bilateral agreements, bypassing commodity malt brokers. This pattern concentrates procurement relationships among maltsters with transparent farm-to-kettle traceability systems and certified organic handling capacity.
Roasted Malt Market Segmentation
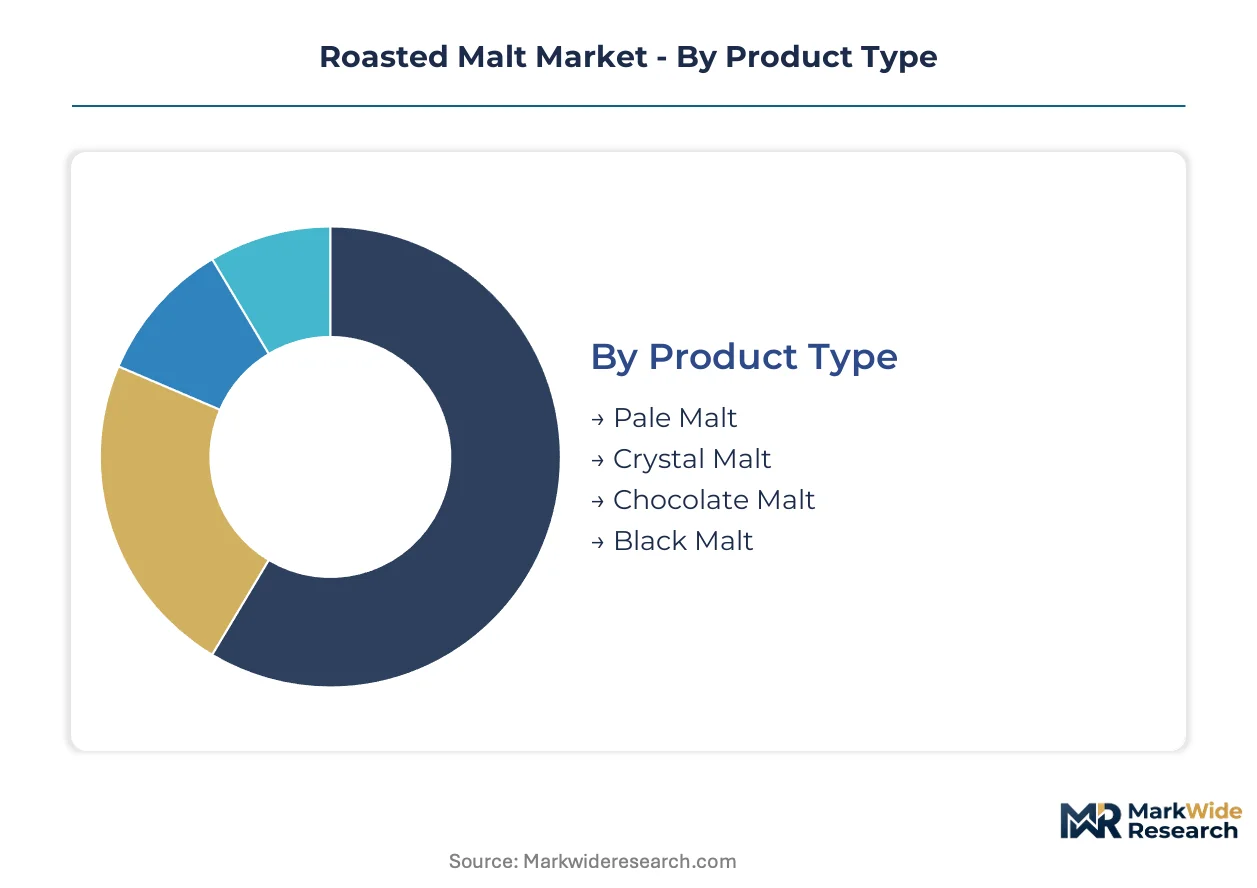
Roasted malt segmentation reflects divergent technical requirements across brewing, distilling, and food manufacturing channels. Specification precision in color development and particle distribution determines supplier selection more than commodity pricing.
Product Type:
Crystal malt occupies the largest volume position due to its versatility across ale and lager styles, while chocolate malt commands premium positioning in stout and porter formulations.
- Crystal Malt:Produced through controlled stewing followed by kilning, this segment develops glassy endosperm structures that release unfermentable sugars during mashing. Demand concentrates in Belgian and British ale traditions where residual sweetness balances hop bitterness. The Munich-Weimar corridor anchors procurement volumes for mid-color variants.
- Chocolate Malt:Roasted at temperatures approaching 220°C to develop intense coffee and burnt flavor profiles without excessive astringency. Kentucky and Tennessee whiskey producers adopt this grade for flavor complexity in craft spirits, creating new demand verticals beyond traditional beer applications.
- Pale Malt:Light roasting produces biscuit and toffee notes for color adjustment in premium lagers.
- Black Malt:High-temperature roasting generates intense bitterness for stout color correction; German BfR acrylamide thresholds constrain production protocols.
Crystal malt leads on scale; chocolate malt leads on momentum.
End Use:
Application requirements span enzymatic activity preservation, flavor compound stability, and precise dosing tolerances.
- Brewing:Craft breweries across Germany, Belgium, and the United States drive specialty roasted malt adoption for flavor differentiation. Crystal and chocolate variants serve color adjustment and complexity addition in ale and lager formulations, with direct contracting between brewers and single-origin maltsters displacing traditional distributor channels.
- Distilling:Whiskey producers in Kentucky and Tennessee adopt roasted malt for flavor complexity beyond traditional beer applications. The segment demands consistent fermentable extract yields alongside roasted character contribution.
- Baking:Powdered malt formats serve precise dosing requirements in bread and pastry applications where Maillard-active compounds enhance crust color development.
- Confectionery:Fine particle distribution formats favor malt-derived colorants over synthetic alternatives in chocolate manufacturing.
Brewing leads on scale; distilling leads on momentum.
Form:
Physical processing state determines handling economics and application compatibility across manufacturing channels.
- Powdered:Fine particle distribution enables precise dosing in baking and confectionery applications where solubility requirements favor homogeneous dispersion. The segment shows structural expansion as food manufacturers replace synthetic colorants with malt-derived alternatives.
- Whole Grain:Traditional supply format for brewing applications requiring intact husk material for lautering efficiency. German and Belgian craft segments maintain preference for whole grain procurement with specified roasting provenance.
- Crushed:Intermediate processing reduces milling requirements at brewery sites while preserving husk integrity for filtration.
- Liquid:Extract formats serve industrial beverage applications requiring standardized color and flavor dosing without solid handling infrastructure.
Whole grain leads on scale; powdered leads on momentum.
Quality Grade:
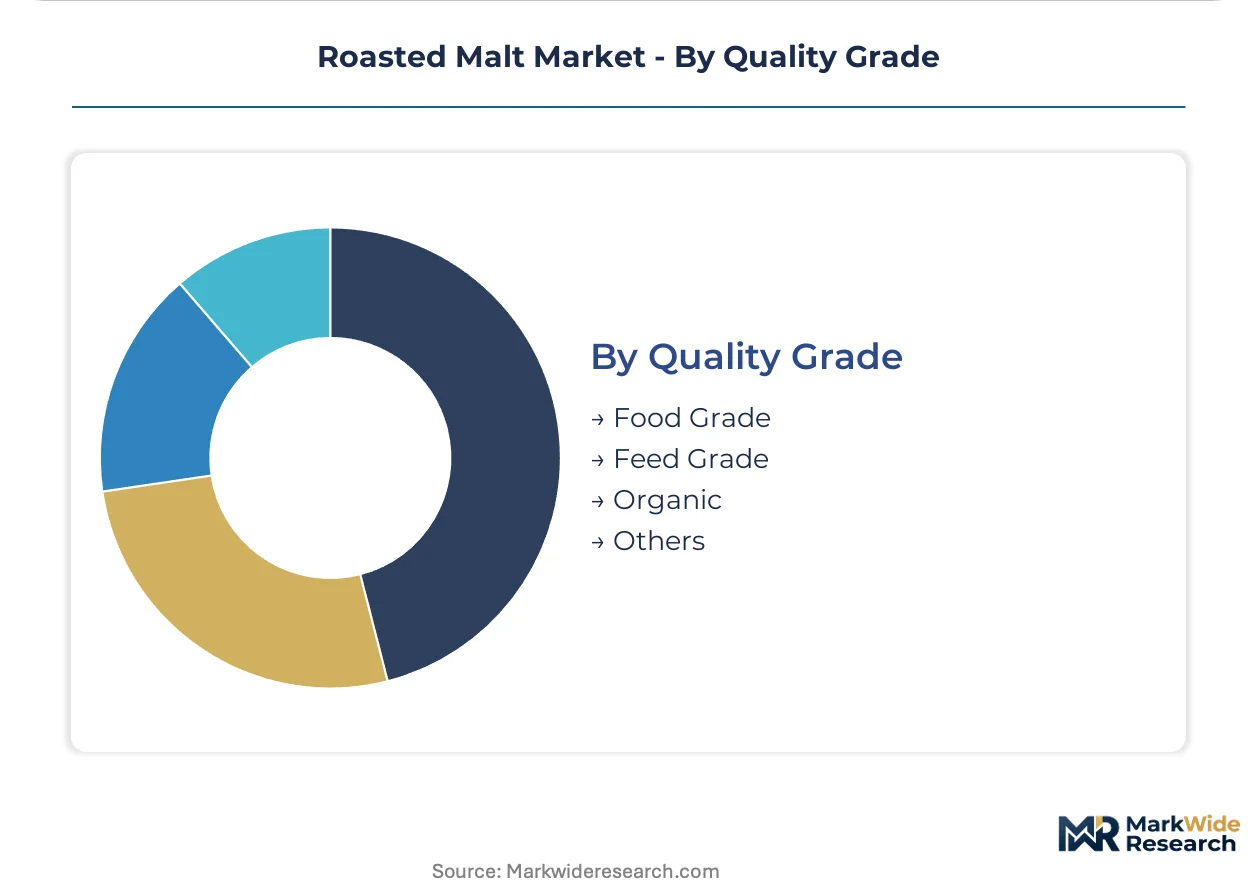
Certification frameworks create parallel supply chains with differentiated documentation requirements and price positioning.
- Organic:Certification under USDA National Organic Program and EU organic regulations commands 15-30% price premiums across German and Belgian craft brewing segments. Supply chain segregation requirements from farm to kettle favor maltsters with transparent traceability systems.
- Food Grade:Standard specification for beverage and food manufacturing channels governed by FDA food safety standards and EU REACH chemical substance registration. This grade encompasses the majority of volume through brewing and distilling applications.
- Feed Grade:Lower specification material for animal nutrition applications where color and flavor development requirements are minimal.
- Others:Specialty grades including heritage-protected designations and single-variety specifications serving niche craft segments.
Food grade leads on scale; organic leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redistributing roasted malt production capacity as EU REACH compliance burdens concentrate investment in jurisdictions with harmonized chemical safety frameworks. Producers migrate toward barley-growing regions with established organic certification infrastructure to capture traceability premiums.
Germany
Craft breweries in Bavaria and Thuringia anchor procurement volumes for specialty roasted malts, with the Munich-Weimar corridor commanding logistics advantages. Germany's BfR evaluates acrylamide formation thresholds above 200°C, constraining high-temperature roasting protocols and favoring capital-intensive producers with emission control retrofits. Malting clusters in Lower Saxony and Baden-Württemberg consolidate roasting assets adjacent to premium barley streams.
United States
Kentucky and Tennessee whiskey producers adopt chocolate malt for flavor complexity, creating distilling demand verticals beyond traditional beer applications. FDA food safety standards govern malt imports entering beverage and food manufacturing channels, with organic certification under USDA National Organic Program commanding 15-30% price premiums. Direct contracting between Oregon and Vermont craft brewers and single-origin maltsters displaces distributor-mediated procurement.
Belgium
Belgian ale traditions drive crystal malt consumption where residual sweetness balances hop bitterness. EU organic regulations create parallel supply chains favoring maltsters with transparent farm-to-kettle traceability systems. Flanders-based craft segments specify barley variety and roasting protocol through bilateral agreements, bypassing commodity brokers.
France
Malteurop Group leverages geographic proximity to major brewing customers across France and Germany. Drought-exposed growing regions in northern France concentrate premium malting barley supply, exposing roast malt producers to protein specification variance. The country's national agricultural regulator enforces evolving maximum residue limits for mycotoxins as importing jurisdictions tighten contaminant thresholds.
United Kingdom
Simpsons Malt and Muntons PLC anchor British specialty malt production serving domestic craft brewing expansion. Mid-sized maltsters deploy automated EBC spectrophotometry to reduce batch-to-batch color variance from ±8 EBC to ±3 EBC. Scottish and English brewing clusters demand certified provenance documentation, forcing roasting asset relocation adjacent to barley growing regions.
Roasted Malt Market Competitive Landscape
North American producers anchor one tier; European specialists hold integrated origination advantages through cooperative and corporate structures. The vendor base concentrates among grain-trading conglomerates with captive malting divisions and regional maltsters with farm-linked supply contracts. Three archetypes dominate: integrated agribusinesses controlling barley origination through elevator networks, cooperative-linked maltsters securing farmer contracts directly, and independent specialty roast houses serving craft segments. Competitive moves center on backward integration into premium barley streams and geographic relocation of roasting assets toward growing regions.
Within the integrated agribusiness tier, Cargill Incorporated represents the grain-origination archetype with elevator network control, while Malteurop Group exemplifies geographic proximity strategy to major brewing customers. Boortmalt occupies a position within cooperative-linked structures through its Axéréal Group parentage, anchoring farmer contract integration. These three entities collectively illustrate how supply chain configuration determines competitive positioning in specialty malt roasting.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Malteurop Group |
| Boortmalt (Axéréal Group) |
| GrainCorp Limited |
| Briess Malt & Ingredients |
| Simpsons Malt |
| Viking Malt |
| Muntons PLC |
| Great Western Malting |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between organic and conventional roasted malt creates parallel supply chains with divergent margin structures, as EU organic regulations and USDA National Organic Program compliance requirements force segregation investments that compound pricing power for certified producers while commodity-tier suppliers absorb barley input volatility without premium recapture mechanisms.
Pricing Analysis
Distributor margin layers compress as direct contracting between craft brewers and single-origin maltsters displaces traditional broker-mediated procurement. Pricing stratifies across organic, food-grade, and feed-grade tiers, with certification premiums of 15-30% in German and Belgian craft segments. Cost compression in black malt production is intensifying because Germany's BfR acrylamide thresholds constrain high-temperature roasting protocols. Large-scale brewing cooperatives exhibit lowest price sensitivity; independent craft brewers in Oregon and Vermont negotiate hardest on per-kilogram contracts.
Supply Chain Analysis
Dual-sourcing requirements from Kentucky and Tennessee whiskey producers mandate multi-supplier qualification for chocolate malt, forcing roasting operations to maintain redundant production lines. Supply concentrates in Germany, France, and Belgium where barley origination networks feed specialty kilning capacity. Production draws from premium malting barley streams, thermal energy inputs, and skilled master maltster labor pools. Single-source vulnerability concentrates in drought-exposed French growing regions. Distribution runs through malting groups with captive elevator networks and cooperative-linked farmer contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in roasted malt hinges on organic certification penetration and automated EBC spectrophotometry adoption, as precision roasting technology reduces batch-to-batch variance costs while certified provenance commands sustainable premium capture.
For Market Incumbents: Deploy backward integration into premium barley streams to secure protein specification control against climate-driven supply variance. Consolidate roasting assets adjacent to Bavaria and Thuringia brewing clusters to capture logistics advantages. Cargill Incorporated and Malteurop Group already anchor this pattern; smaller maltsters must match farm-linked contract structures or cede share to cooperative-linked competitors like Boortmalt. For New Entrants and Emerging Players: Craft spirits distributors in Kentucky and Tennessee represent the most penetrable channel partner type for chocolate malt supply, as whiskey producers adopt roasted malt for flavor complexity without established supplier lock-in. Target powdered malt formats for baking and confectionery applications where synthetic colorant replacement demand outpaces incumbent capacity. Lead with transparent farm-to-kettle traceability systems to bypass commodity broker layers. For Investors and Strategic Acquirers: Consolidation pressure builds where master maltster skill scarcity constrains capacity expansion timelines across traditional malting regions. The 5-10 year viability window favors acquisition of mid-sized Belgian and Czech maltsters with automated EBC spectrophotometry deployed. Signal to watch: REACH registration timeline extensions for novel processing aids that favor larger producers with dedicated regulatory affairs functions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Premium Barley Streams | Secures protein specification control against drought-exposed French growing region volatility. |
| Automated EBC Spectrophotometry Deployment | Reduces batch-to-batch color variance from ±8 EBC to ±3 EBC in Belgian and Czech facilities. |
| Organic Certification Infrastructure Investment | Captures 15-30% price premiums under EU organic regulations and USDA National Organic Program. |
| Roasting Asset Relocation to Growing Regions | Shortens lead times for Bavaria and Thuringia craft brewers demanding certified provenance. |
| Distilling Substrate Channel Development | Diversifies revenue beyond beer into Kentucky and Tennessee whiskey producer supply. |
Research Methodology
Bottom-up brewing and distilling demand modeling reconciled against top-down malting capacity tracking forms the analytical core. Primary interviews with master maltsters, craft brewery procurement leads, and whiskey production managers combined with secondary validation from customs records, SEC filings of grain-trading conglomerates, and EU REACH registration databases. Triangulation across stakeholder inputs and trade flow data ensures volume and value estimates reflect actual procurement patterns rather than capacity announcements.
Historical trendline analysis of specialty malt roasting capacity expansion and organic certification adoption rates informs projection parameters. Segmentation dimensions span product type, end-use application, physical form, and quality grade certification. CAGRs derive from fitted growth curves against confirmed brewery and distillery order backlogs, with barley yield variance and regulatory compliance cost trajectories as industry-specific forecast inputs across the modeling period.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal agricultural transition timelines and REACH chemical safety documentation burdens. Forecasts reflect assumptions regarding craft brewing demand sustainability and organic barley supply scalability. Deviation in Germany's BfR acrylamide threshold enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Rhum Agricole Market
Alcoholic Beverages
South America Wine Market
Alcoholic Beverages
Vodka Market
Alcoholic Beverages
Spain Alcohol E-Commerce Market
Alcoholic Beverages
Coffee Beer Market
Alcoholic Beverages
Cognac Market
Alcoholic Beverages
Absinthe Market
Alcoholic Beverages
Liqueurs Market
Alcoholic Beverages
Wine Chocolate Market
Alcoholic Beverages
Bayberry Wine Market
Alcoholic Beverages
Beer Dispensing Machine Market
Alcoholic Beverages
Grain Neutral Spirits Market
Alcoholic Beverages
Sparkling Red Wine Market
Alcoholic Beverages
Mini Brew Fermenter Market
Alcoholic Beverages
Middle East and Africa Alcoholic Beverage Market
Alcoholic Beverages
Gluten-Free Beer Market