
 Mexico Tequila Market | 2026-2036
Mexico Tequila Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Tequila Market Intelligence
Single-source estate agave supply is restructuring procurement across the Mexico Tequila Market as distillers retreat from volatile spot markets. Jose Cuervo leverages its vast Los Altos agave plantations to secure multi-year raw material continuity. Patrón sustains vertical integration from field to bottle, controlling quality consistency across its highland estate network. Herradura differentiates through on-site barrel cooperage, extending its aging program autonomy.
Tequila is a distilled spirit produced exclusively from Weber blue agave in designated Mexican states, with fermentation yielding alcohol content between 35-55% ABV and aging durations defining its classification grade. Blanco expressions lead volume throughput due to minimal barrel time and lower production cost, while Extra Añejo commands concentrated margin pools from ultra-premium collectors. Reposado occupies the largest middle-market position, bridging accessibility with oak-derived complexity for mainstream consumers.
CRT (Consejo Regulador del Tequila) enforces Denomination of Origin boundaries and NOM distillery registration, restricting legitimate production to five Mexican states. Mexico's Secretary of Economy coordinates export promotion frameworks that shape international market access for certified producers. Stakeholders must monitor CRT enforcement actions against non-compliant bottlers, as counterfeit erosion threatens premium price integrity across core export corridors.
Market Dynamics
Estate-level agave procurement is restructuring competitive positioning across the Mexico Tequila Market as distillers retreat from volatile spot markets and CRT certification requirements harden authenticity barriers.
Growth Catalysts
- CRT NOM Certification Expansion:The regulator's tightened distillery registration protocols are filtering counterfeit supply from premium export corridors. Certified producers gain price integrity in US and European channels.
- Highland Agave Terroir Concentration:Jalisco's Los Altos region commands sustained buyer loyalty for estate-distilled expressions. Soil elevation and mineral composition create non-replicable flavor profiles.
- Barrel-Aging Program Investment:On-site cooperage construction allows producers to control oak sourcing and toast profiles. Extended aging autonomy supports Extra Añejo margin capture.
Market Restraints
- Agave Price Volatility:Weber blue agave harvest cycles create seven-year boom-bust supply swings. Spot market dependency exposes non-integrated distillers to raw material cost spikes.
- Geographic Production Lock:CRT Denomination of Origin restricts legitimate tequila to five Mexican states. Land scarcity in optimal highland zones concentrates supply risk.
- Extended Certification Timelines:NOM registration and export permit processing creates 18-24 month market entry barriers. New entrants face working capital strain during compliance gaps.
Strategic Opportunities
- Guadalajara Premium Cocktail Channel:Specialty bars in the city center are expanding agave-forward programs. Direct-to-trade relationships bypass traditional distributor markups.
- CRT Export Promotion Frameworks:Mexico's Secretary of Economy coordinates international market access initiatives. Certified producers receive trade mission placement and duty advantage negotiation.
- Biomass Energy Recovery:Agave bagasse cogeneration systems are converging with distillery heat requirements. Renewable process energy reduces fossil fuel dependency in highland operations.
Industry Challenges
- Master Distiller Talent Scarcity:Traditional tahona stone milling and wild yeast fermentation expertise resides with aging practitioners. Succession gaps threaten artisanal production continuity.
- Cooperage Capex Intensity:On-site barrel construction requires 3-5 year oak seasoning inventory and specialized carpentry equipment. Aging program autonomy demands seven-figure facility investment.
- Counterfeit Erosion Response:CRT enforcement actions against non-compliant bottlers require continuous legal monitoring. Brand protection resources divert from product development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Tequila Market |
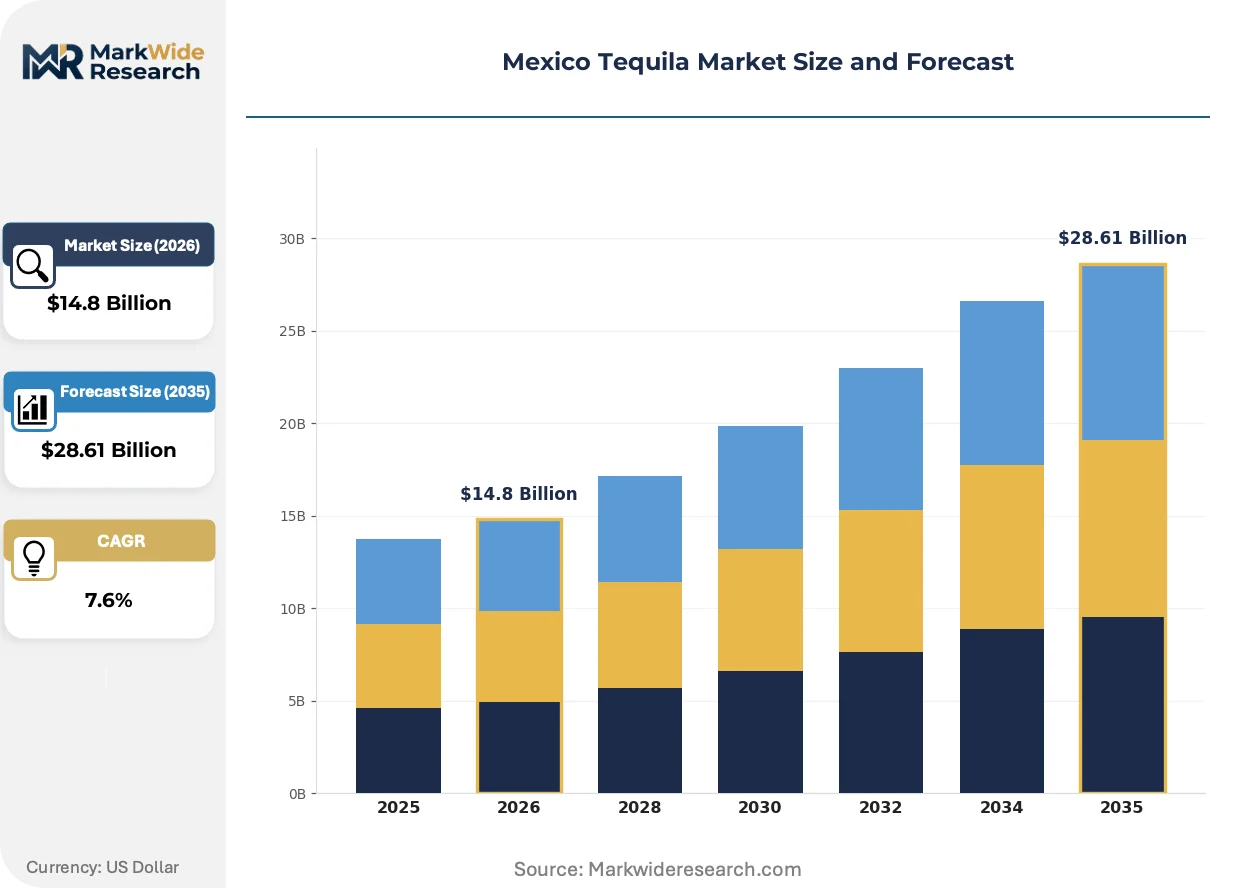
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $28.61 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blanco, Reposado, Añejo, Extra Añejo Packaging Type: Glass Bottle, PET Bottle, Tetra Pak, Can Distribution Channel: On-trade, Off-trade, Online Sales, Duty-Free Consumer Type: Millennials, Gen X, Baby Boomers, Tourists |
| Companies Covered | El Jimador, 1800 Tequila, Jose Cuervo, Cazadores, Sauza, Patrón, Espolòn, Herradura, Don Julio, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Tequila Market Strategic Shifts & Innovations
Agave cultivation and distillation technologies are absorbing precision agriculture methods that reshape raw material quality control and production consistency across the Mexico Tequila Market.
Diffuser extraction technology is absorbing high-pressure water processing to accelerate agave sugar release from piña cores. Large-scale distillers adopt this method for Blanco volume throughput. The technology is absorbing traditional tahona milling's cost structure, compressing artisanal producer margins at the standard-grade tier.
CRT's digital traceability mandate requires blockchain-integrated NOM certification for export-bound shipments. The policy creates real-time supply chain verification requirements. Small-batch distillers in Jalisco's highlands are responding with cooperative data infrastructure investments to maintain US market access.
Direct-to-consumer channel expansion is disrupting traditional three-tier distribution in Mexico City and Guadalajara urban cores. Boutique distillers now operate tasting room retail and subscription clubs. This pattern concentrates in metropolitan zones where regulatory enforcement permits limited self-distribution volumes.
Mexico Tequila Market Segmentation
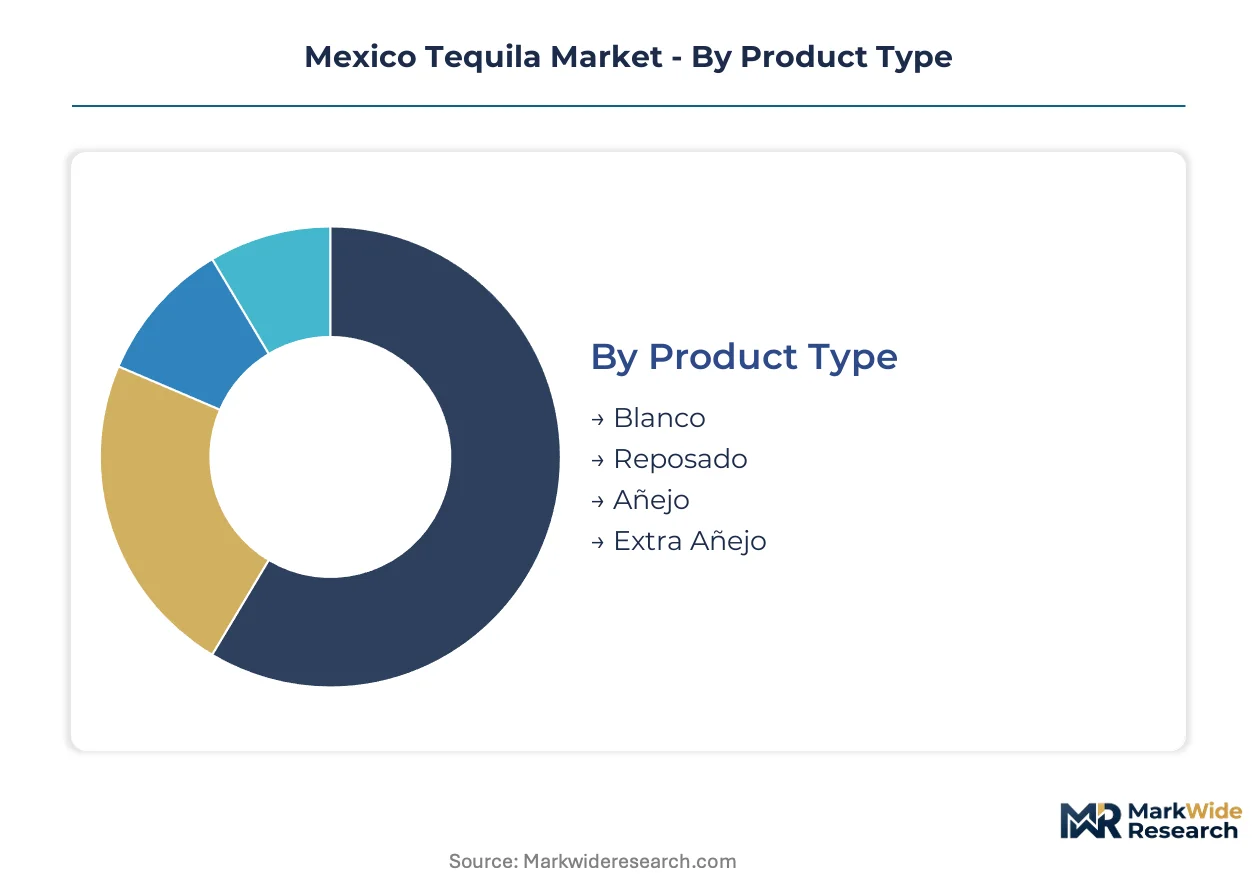
Segmentation in the Mexico Tequila Market reveals how production economics and consumption patterns diverge across certification grades, packaging formats, and channel access. Distillers configure their portfolios around aging duration investments and regional distribution advantages.
Product Type:
Supply concentration in Jalisco's Los Altos highlands shapes how distillers allocate barrel inventory across aging tiers.
- Blanco:Unaged expressions bottled immediately after distillation preserve raw agave character with zero oak contact. Volume throughput dominates in Mexico City's cantina networks and Guadalajara's casual dining corridors where price accessibility drives repeat purchase.
- Reposado:Two-month to one-year oak aging introduces vanilla and caramel notes while retaining agave brightness. Jalisco's estate distilleries prioritize this middle tier for US export programs where it bridges mainstream accessibility with premium perception.
- Añejo:One to three years in oak barrels develops deeper color and complexity for sipping occasions. CRT certification requirements for extended aging documentation add compliance overhead.
- Extra Añejo:Minimum three-year aging in limited oak inventory commands ultra-premium positioning. Cooperage constraints restrict volume scaling.
Blanco absorbs the bulk of installed capacity; Extra Añejo is expanding most quickly.
Packaging Type:
Cost tier differentiation across packaging formats determines margin capture and channel eligibility.
- Glass Bottle:Premium-weighted glass with embossed NOM markings dominates export-bound expressions. CRT traceability mandates favor this format for US and European shipments requiring blockchain-verified certification.
- PET Bottle:Lightweight polymer construction reduces freight costs for domestic volume distribution. Mexico's informal retail channels favor this format for Blanco price competitiveness.
- Tetra Pak:Aseptic carton technology enables single-serve cocktail formats in Guadalajara's convenience retail.
- Can:Aluminum format penetrates beach tourism zones and music festival venues where portability outweighs traditional presentation.
Glass Bottle commands the highest unit economics; Can is gaining share fastest in experiential consumption settings.
Distribution Channel:
Channel configuration determines margin retention and CRT compliance verification requirements.
- On-trade:Bars, restaurants, and hotels in Mexico City and Guadalajara generate premium pricing through cocktail program placement. Direct relationships with agave-forward establishments bypass distributor markups.
- Off-trade:Retail liquor stores and supermarket chains in Jalisco's urban centers concentrate volume throughput for standard-grade expressions.
- Online Sales:E-commerce platforms with CRT-verified NOM documentation expand reach to interior Mexican states with limited specialty retail.
- Duty-Free:Airport and border zone retail captures tourist expenditure with exclusive bottle formats and limited editions.
On-trade retains margin leadership; Online Sales shows steepest expansion trajectory as digital verification infrastructure matures.
Consumer Type:
Demographic segmentation aligns agave education levels with price tolerance and occasion sophistication.
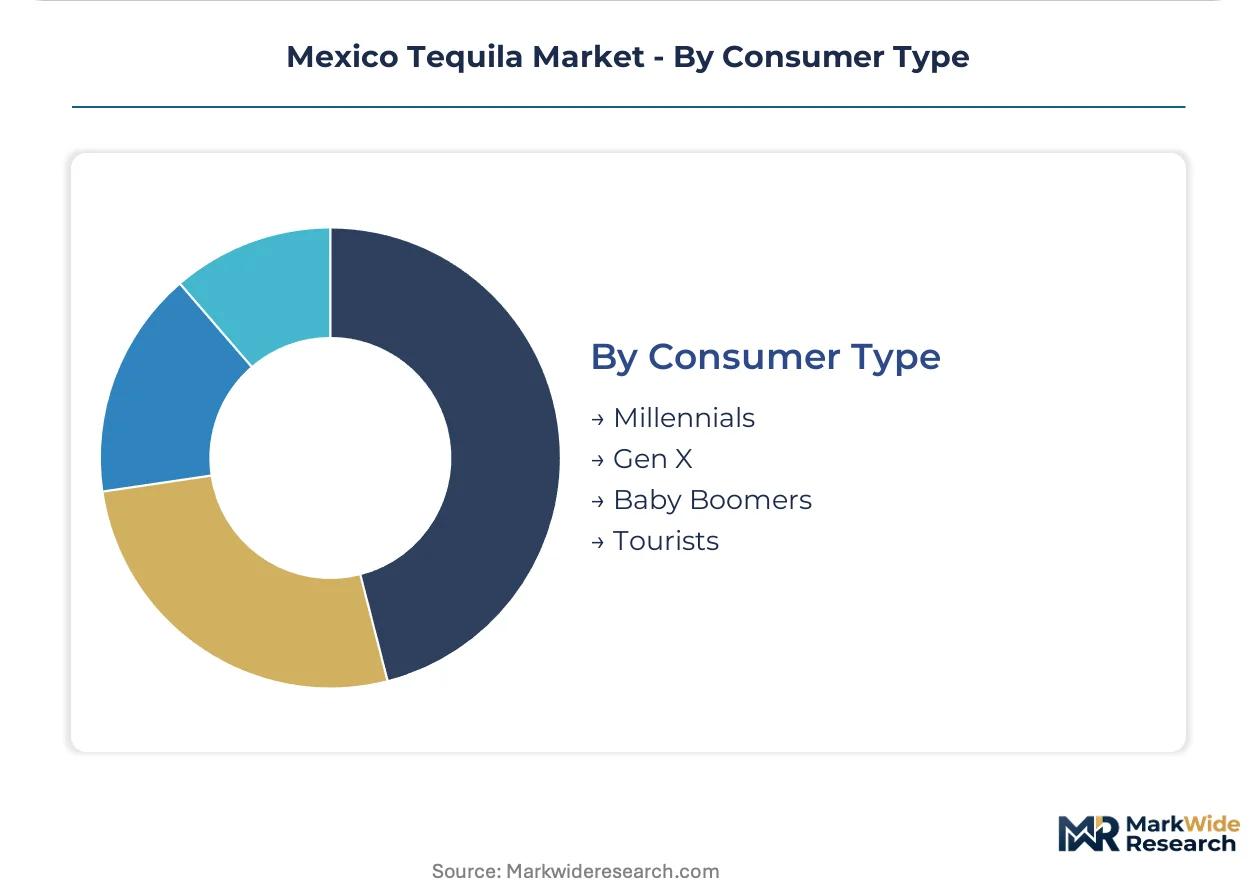
- Millennials:Urban professionals aged 25-40 in Mexico City prioritize craft cocktail authenticity and estate distillery provenance. Social media discovery drives trial of small-batch highland expressions.
- Gen X:Established households in Guadalajara and Monterrey favor Reposado and Añejo tiers for home entertaining and gift occasions.
- Baby Boomers:Loyalty to heritage brands and traditional serving rituals sustains volume in Jalisco's domestic market.
- Tourists:International visitors to Tequila town and Puerto Vallarta generate concentrated demand for souvenir-format bottles with CRT certification documentation.
Millennials absorb the bulk of premium innovation investment; Tourists deliver highest per-transaction value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for certified estate tequila concentrates in Mexico's central and western highlands, where CRT-regulated production zones align with established agave cultivation corridors and urban consumption centers.
Jalisco
Los Altos highland estates supply the majority of premium Weber blue agave for export-bound expressions. CRT maintains its headquarters and primary certification facilities in Guadalajara, streamlining NOM documentation for distilleries clustered across the Tequila Valley. The municipality of Tequila anchors tourism-driven direct-to-consumer retail, with heritage distilleries operating visitor programs that bypass traditional distribution tiers.
Mexico City Metro
Specialty cocktail bars in Polanco, Condesa, and Roma Norte drive premium on-trade pricing for small-batch highland expressions. The Secretariat of Economy coordinates export promotion frameworks from its federal offices, linking certified producers to US and European trade missions. Urban tasting rooms concentrate in the Centro Histórico, where regulatory allowances for limited self-distribution enable boutique distillers to capture full retail margins.
Nuevo León
Monterrey's industrial base supports packaging manufacturing and logistics infrastructure serving northern export corridors. The state's proximity to Texas border crossings reduces transit time for CRT-documented shipments entering US distribution. Local hospitality groups in San Pedro Garza García are expanding agave-forward beverage programs, creating secondary demand for Jalisco-sourced certified products.
Bajío Region
Guanajuato and Querétaro host expanding distillery operations seeking highland agave supply agreements outside saturated Jalisco zones. State economic development agencies are offering facility incentives to attract NOM-certified producers. León's leather and manufacturing heritage is translating into artisanal packaging clusters serving premium bottle formats.
Northern Border States
Baja California and Chihuahua concentrate duty-free retail operations capturing tourist expenditure at Tijuana and Ciudad Juárez crossings. CRT export documentation requirements are most stringently enforced at these corridors given US customs scrutiny. Ensenada's coastal tourism economy supports experiential consumption formats including beachside canned cocktail distribution.
Mexico Tequila Market Key Industry Players
Backward integration into captive agave supply dominates the current landscape as distillers seek insulation from seven-year harvest volatility. The market structure consolidates around heritage family holdings and multinational spirits portfolios, with mid-tier independents occupying specialized terroir niches. Three archetypes define competitive positioning: estate-integrated highland specialists, volume-scale Blanco producers, and ultra-premium aging-focused houses. Capacity expansion and on-site cooperage construction represent the dominant competitive moves, followed by direct-to-trade channel development in Mexico City and Guadalajara.
Among heritage-integrated specialists, Jose Cuervo anchors the estate-controlled archetype through its vast Los Altos plantation network. Patrón exemplifies vertical production control from field to bottle across its highland estate system. Herradura occupies a position emphasizing aging program autonomy through proprietary barrel construction. These three represent distinct strategic responses to CRT certification requirements and raw material security imperatives.
| Leading Market Players |
|---|
| El Jimador |
| 1800 Tequila |
| Jose Cuervo |
| Cazadores |
| Sauza |
| Patrón |
| Espolòn |
| Herradura |
| Don Julio |
| Others |
Cost & Logistics Intelligence
Agave piña harvest costs cascade through CRT-certified production tiers, with estate-grown Los Altos supply commanding premium positioning against spot-market dependent distillers in standard-grade Blanco channels. Highland terroir concentration creates pricing power for NOM-registered producers while non-integrated bottlers absorb volatility in raw material procurement.
Pricing Analysis
Volume throughput concentrates in unaged Blanco expressions where minimal barrel inventory and rapid production cycles compress margins, while Extra Añejo tiers capture concentrated value pools through extended cooperage investment and scarcity positioning. Price differentiation rests on CRT certification grade and estate versus spot-market agave sourcing, with Jalisco highland terroir commanding sustained buyer loyalty. Pricing pressure stems from seven-year agave harvest cycles exposing non-integrated distillers to raw material cost spikes. Cantina networks in Mexico City exhibit highest price sensitivity; ultra-premium collectors demonstrate least elasticity.
Supply Chain Analysis
Freight cost differentials favor Jalisco's Tequila Valley proximity to Guadalajara logistics hubs and US border crossings through Nuevo León, while interior Mexican states absorb elevated distribution expenses. Supply concentrates in Mexico's five CRT-designated states, with Weber blue agave cultivation anchored in Los Altos highlands and processing capacity clustering around Guadalajara. Raw material dependencies center on mature agave piñas, American and French oak for cooperage, and glass packaging for export-bound formats. Single-source vulnerability runs through estate-level agave supply agreements. Distribution runs through three-tier systems for standard volumes, with direct-to-trade relationships penetrating premium on-trade channels in metropolitan cores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Diffuser extraction technology is displacing traditional tahona milling for volume-scale Blanco production, creating bifurcated competitive terrain between artisanal heritage methods and industrial throughput optimization.
For Market Incumbents: To counter margin compression from high-pressure diffuser adoption at volume tier, secure captive Los Altos agave supply through long-term estate agreements and construct on-site cooperage for aging program autonomy. CRT certification investment creates defensible export positioning against counterfeit erosion. For New Entrants and Emerging Players: Capture white-space in Guadalajara and Mexico City direct-to-consumer channels where regulatory allowances for limited self-distribution enable full margin retention. Target agave-forward cocktail bars with estate-provenance storytelling bypassing traditional distributor markups. Deploy subscription club models for recurring revenue anchoring. For Investors and Strategic Acquirers: CRT digital traceability mandate enforcement acceleration is the leading indicator that blockchain-integrated NOM certification infrastructure will consolidate market access advantages. Focus acquisition screening on Jalisco highland estate holders with vertical field-to-bottle control and existing US export documentation. Watch for master distiller succession gaps signaling artisanal production continuity risk.| Strategic Initiative | Industry Significance |
|---|---|
| Estate Agave Supply Securement | Long-term Los Altos plantation agreements insulate distillers from seven-year harvest volatility cycles. |
| On-Site Cooperage Construction | Proprietary barrel programs enable Extra Añejo margin capture and oak profile differentiation. |
| CRT Certification Investment | NOM registration and blockchain traceability compliance unlock premium US and European channel access. |
| Direct-to-Trade Channel Development | Agave-forward bar relationships in Mexico City bypass distributor markups for margin retention. |
| Biomass Energy Recovery | Agave bagasse cogeneration systems reduce fossil fuel dependency in highland distillery operations. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across master distillers, CRT certification officers, agave plantation managers, and premium bar beverage directors. CRT NOM registration databases, Mexican Secretary of Economy export promotion documentation, and Jalisco state agricultural statistics provided supply-side validation. Bottom-up distillery capacity modeling and top-down consumption estimation were triangulated for cross-verification.
Data-stream reconciliation across production volume, export documentation, and channel shipment records informed the analytical framework. Segmentation dimensions spanned aging tier, packaging format, distribution channel, and regional consumption cluster. CAGRs were derived from trend extrapolation moderated by agave harvest cycle patterns and CRT regulatory enforcement trajectories. Agave maturity indices and cooperage inventory cycles served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to agave supply shocks, CRT policy shifts, and US trade framework adjustments. Outputs reflect documented assumptions around certification timeline stability and highland terroir supply concentration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Puncheon Barrel Market
Alcoholic Beverages
Champagne Market
Alcoholic Beverages
Craft Beer Market
Alcoholic Beverages
Canned Wine Market
Alcoholic Beverages
Cocktail Mixers Market
Alcoholic Beverages
Beer Line Cooling System Market
Alcoholic Beverages
Citrus Alcohol Market
Alcoholic Beverages
Premium Wine Cooler Market
Alcoholic Beverages
Pisco Market
Alcoholic Beverages
Alcoholic Ready-To-Drink (Rtds)/High Strength Premixes Market
Alcoholic Beverages
Sake Market
Alcoholic Beverages
RTD Cocktails Market
Alcoholic Beverages
Airport Duty-Free Liquor Market
Alcoholic Beverages
Irish Whiskey Market
Alcoholic Beverages
Barrel Liner Market
Alcoholic Beverages
Isoamyl Alcohol Market