
 Premixed Margarita Market | 2026-2036
Premixed Margarita Market Size, Share, and Industry Trends Forecast 2026-2036
Premixed Margarita Market Analytics
The premixed margarita category is consolidating around a sharp divergence between premium agave-forward formulations and commodity malt-beverage bases. Beam Suntory leverages its tequila portfolio to anchor authenticity claims in the premium tier. Bacardi Limited competes through rum-and-lime hybrid positioning that sidesteps pure tequila sourcing costs.
Premixed margaritas are shelf-stable, blended cocktails containing tequila or tequila-derived spirits, citrus flavoring, and stabilizers, typically packaged at 5% to 12.5% alcohol by volume for immediate consumption without bartender preparation. The Classic flavor profile dominates volume but Mango is accelerating fastest among younger demographics seeking tropical novelty. Cans command manufacturing investment due to recycling infrastructure and outdoor occasion compatibility, while Bag-in-Box occupies on-premise dispenser systems where margin pools concentrate for high-throughput venues.
The U.S. TTB governs alcohol content disclosure and colloidal stability claims, while FDA oversees non-alcoholic ingredient safety and allergen labeling for flavor compounds. State-level three-tier distribution laws fragment market access and force national brands to navigate wholesaler consolidation. Stakeholders must monitor evolving cannabis-infused beverage regulations and zero-proof line extensions that threaten to bifurcate the ready-to-drink shelf.
Market Dynamics
Three-tier distribution laws in the United States fragment market access and force national premixed margarita brands to navigate wholesaler consolidation, compressing margin pools and privileging scale players with dedicated distributor relationships.
Growth Catalysts
- TTB Labeling Modernization:Streamlined alcohol content disclosure rules reduce formulation-to-shelf timelines for new SKUs.
- Canned Format Adoption:Aluminum recycling infrastructure expansion enables outdoor occasion compatibility across Sun Belt states.
- Agave Supply Diversification:Jalisco Highlands plantation investment stabilizes premium tequila input costs for authentic formulations.
Market Restraints
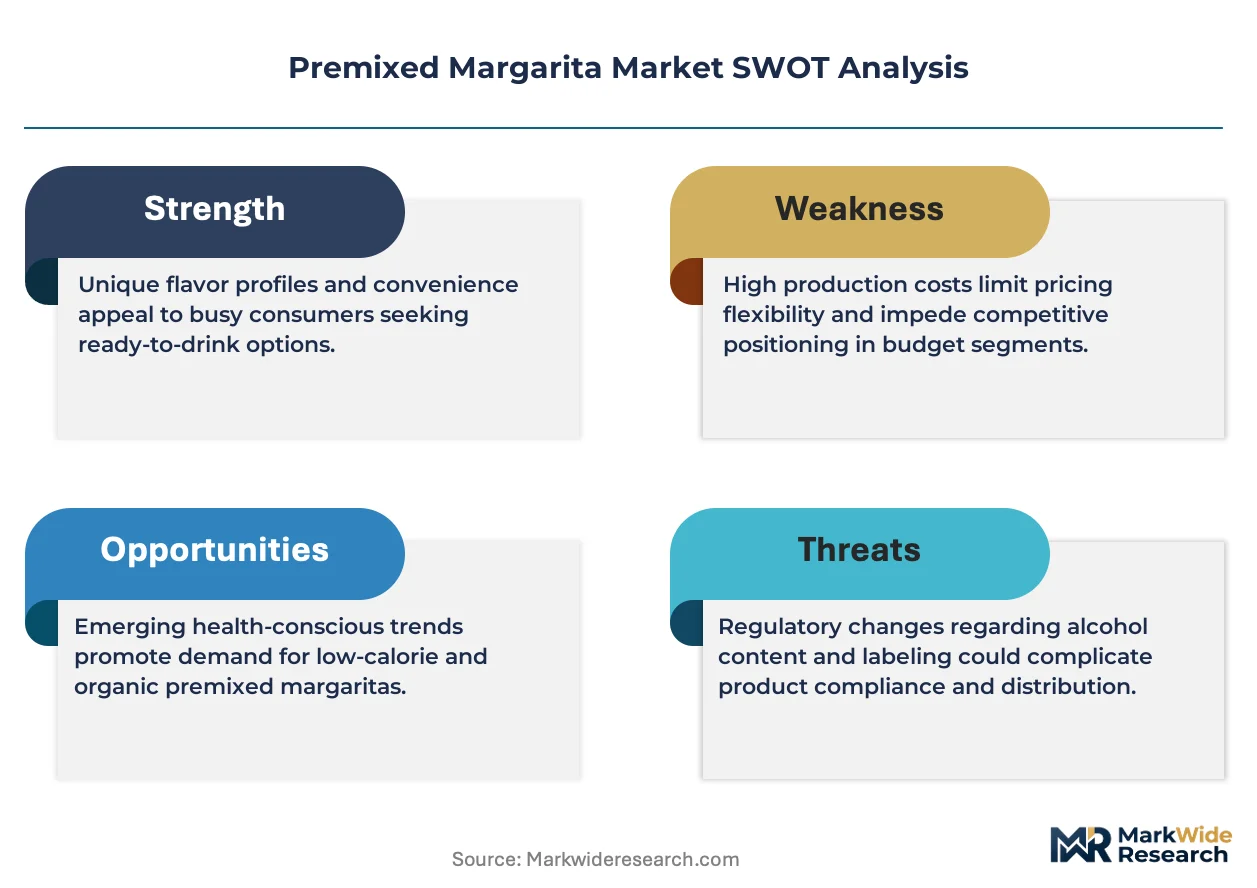
- Blue Weber Agave Volatility:Seven-year maturation cycles create input cost spikes when harvest shortfalls concentrate in specific Mexican microclimates.
- State Distribution Fragmentation:Three-tier laws in Texas and Florida force redundant wholesaler negotiations, elevating route-to-market expenses.
- Malt-Beverage Substitution:Commodity-based competitors undercut authentic tequila positioning on price without agave sourcing requirements.
Strategic Opportunities
- Zero-Proof Line Extensions:Non-alcoholic formulations capture incremental shelf space in California and New York as cannabis-infused beverage regulations mature.
- Bag-in-Box Dispenser Systems:On-premise high-throughput venues in Arizona and Nevada concentrate margin pools through reduced packaging waste.
- Mango Flavor Acceleration:Tropical novelty positioning captures younger demographic trial in Florida outdoor consumption occasions.
Industry Challenges
- Colloidal Stability Expertise:Citrus-oil emulsion chemistry requires specialized food science talent scarce outside established beverage hubs.
- Interstate Compliance Complexity:State-level formulation variations for alcohol content thresholds force redundant testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Premixed Margarita Market |
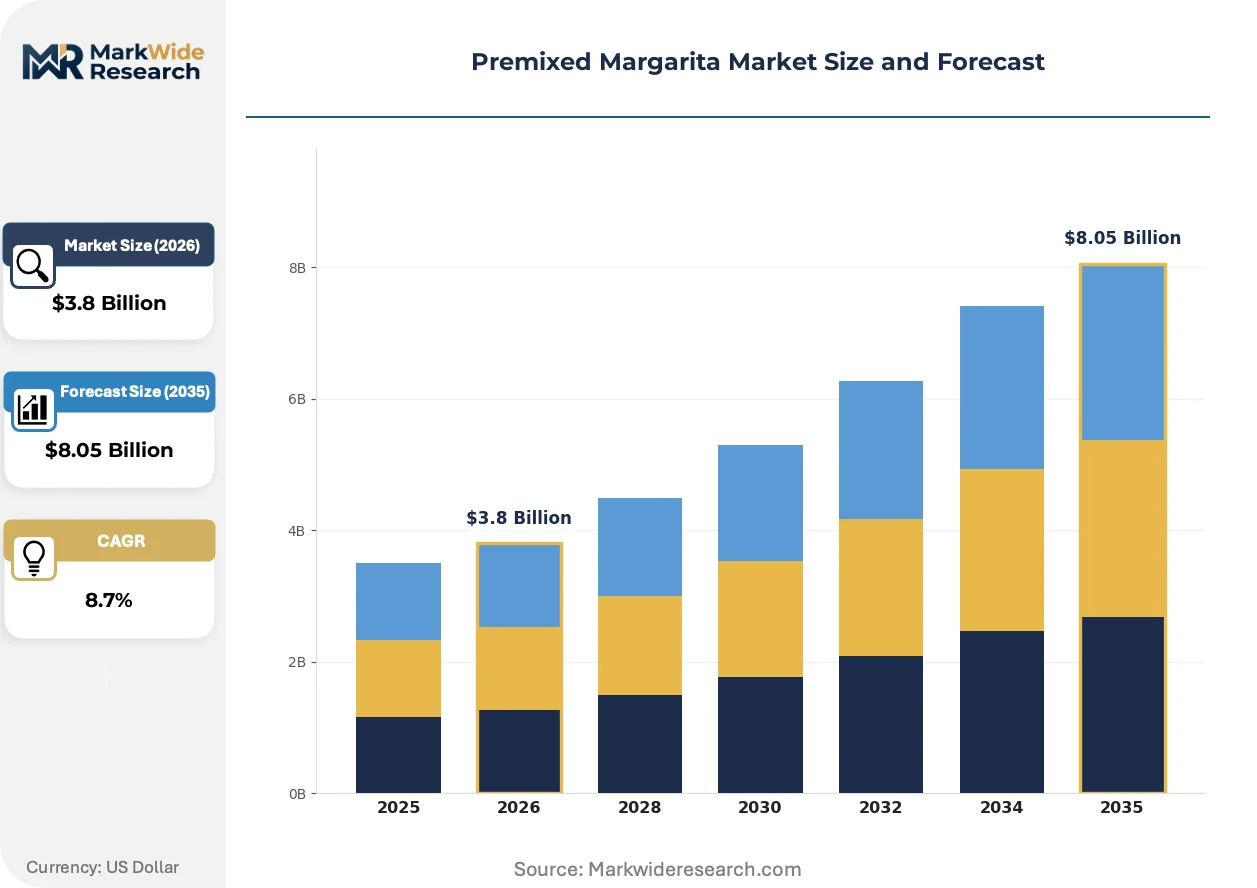
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic, Lime, Strawberry, Mango Packaging Type: Bottle, Can, Tetra Pak, Bag-in-Box Sales Channel: Retail, Online, Wholesalers, Events Alcohol Content: Low, Medium, High, Premium |
| Companies Covered | Beam Suntory, Bacardi Limited, E. & J. Gallo Winery, Brown-Forman, Pernod Ricard, Stateside Brands, Diageo, Constellation Brands, Anheuser-Busch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Premixed Margarita Market Evolving Landscape
Reformulation priorities are splitting the premixed margarita category between authenticity-forward agave positioning and cost-optimized malt bases, with packaging format choices increasingly determining channel access and margin structure.
High-pressure processing for citrus flavor retention is overtaking traditional thermal pasteurization in premium tier production. Small-batch distillers in Texas and California adopt cold-pressed lime oil stabilization to preserve volatile aromatic compounds. This technology compression enables twelve-month shelf stability without the cooked off-notes that previously limited authentic formulation distribution reach.
The U.S. TTB's evolving guidance on cannabis-derived ingredient labeling creates formulation uncertainty for hybrid product developers. Cross-jurisdictional compliance teams must reconcile federal alcohol standards with state-level THC beverage frameworks. California and Colorado manufacturers are responding with dual-SKU strategies that segregate production lines to prevent cross-contamination liability.
Convenience-store channel reset velocity has compressed new product introduction cycles from eighteen months to nine. Buyers at Circle K and 7-Eleven now demand slotting fee flexibility tied to velocity guarantees rather than upfront payments. This pattern is most visible in Texas and Florida, where outdoor consumption seasonality drives rapid flavor rotation requirements.
Premixed Margarita Market Segmentation
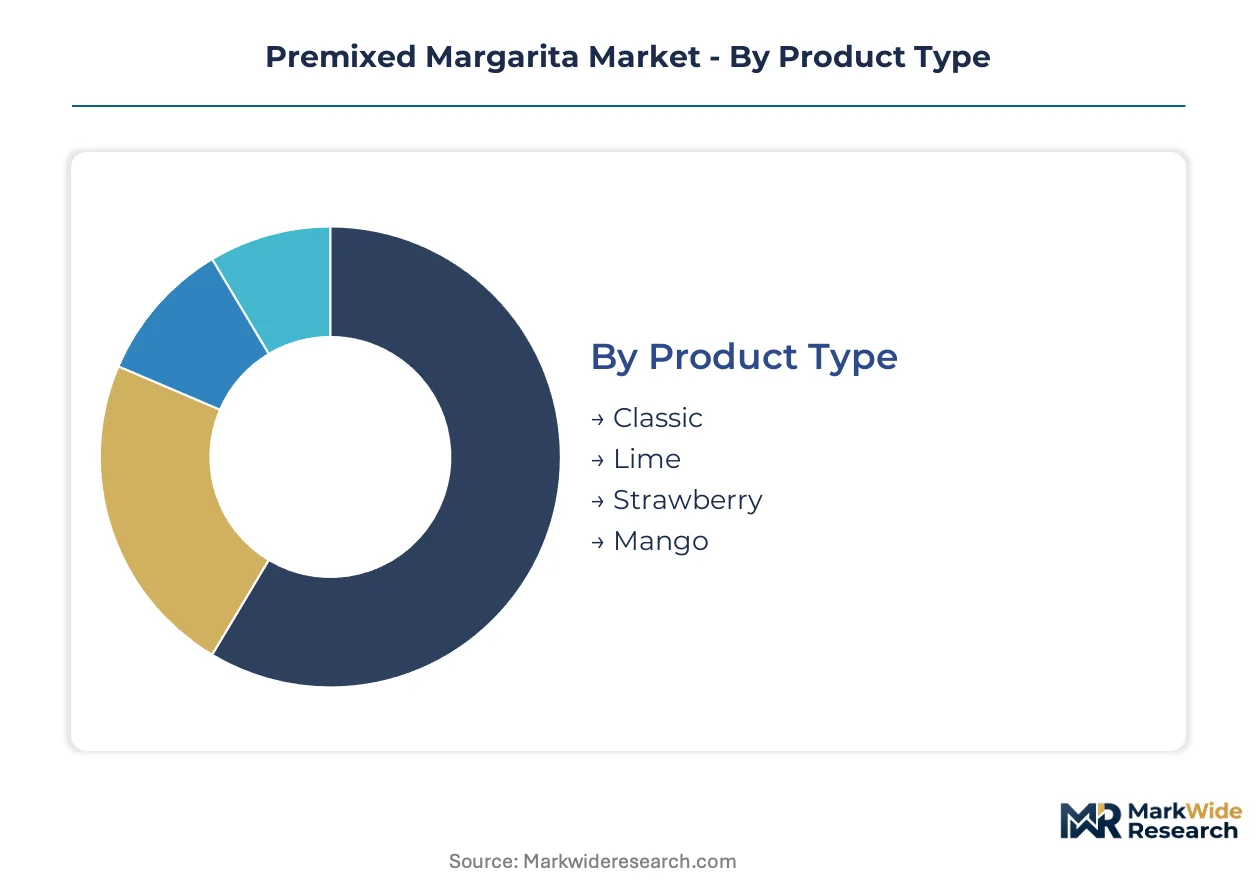
Premixed margarita manufacturers face divergent regulatory burdens across formulation types and distribution channels. TTB certification requirements vary sharply by alcohol content tier, while packaging format determines which state distribution laws apply.
Product Type:
TTB formulation approval cycles differ substantially by flavor profile, with agave-forward variants requiring extended laboratory verification of alcohol content stability.
- Classic:Blends of tequila or tequila-derived spirits with lime and triple sec flavoring at 5% to 12.5% ABV. Demand concentrates in Texas and California convenience-store channels where year-round outdoor consumption sustains baseline volume.
- Mango:Tropical fruit-forward formulations using natural or nature-identical mango esters layered over agave or malt bases. Florida and Arizona retailers report the steepest velocity gains among consumers under thirty-five seeking novelty rotation.
- Lime:Citrus-intense profiles emphasizing tartness over sweetness for on-premise dispenser compatibility.
- Strawberry:Berry-infused variants targeting female-skewing demographics in grocery retail sets.
Classic sits at the top of the volume ranking, with Mango climbing the fastest.
Packaging Type:
Cost tier stratification separates premium aluminum formats from economy multi-serve solutions, with margin structure dictating channel access.
- Can:Aluminum single-serve containers at 250ml to 355ml optimized for outdoor occasion portability and recycling infrastructure. Sun Belt state distributors prioritize can SKUs for golf course and beach venue penetration.
- Bag-in-Box:Multi-liter dispenser-compatible systems for on-premise high-throughput venues. Nevada and Arizona casino bars concentrate procurement here to minimize packaging waste handling costs.
- Bottle:Glass or PET formats for traditional retail shelf presence and home consumption rituals.
- Tetra Pak:Aseptic cartons targeting travel retail and stadium concession channels with lightweight logistics.
Can commands the broadest channel coverage, while Bag-in-Box delivers the highest per-unit margin in restricted on-premise environments.
Sales Channel:
Customer type fragmentation splits procurement behavior between impulse convenience purchases and planned online bulk buying.
- Retail:Grocery and convenience-store placements requiring slotting fee negotiations and velocity-based performance guarantees. Circle K and 7-Eleven buyers in Texas and Florida now demand nine-month product cycles rather than eighteen.
- Online:Direct-to-consumer and third-party platform sales subject to state shipping restrictions on alcohol volume limits.
- Wholesalers:Three-tier system intermediaries controlling access to on-premise accounts in fragmented state markets.
- Events:Temporary permits for festival and stadium concessions with localized TTB licensing requirements.
Retail absorbs the majority of volume throughput, with Online expanding most quickly as state shipping laws liberalize.
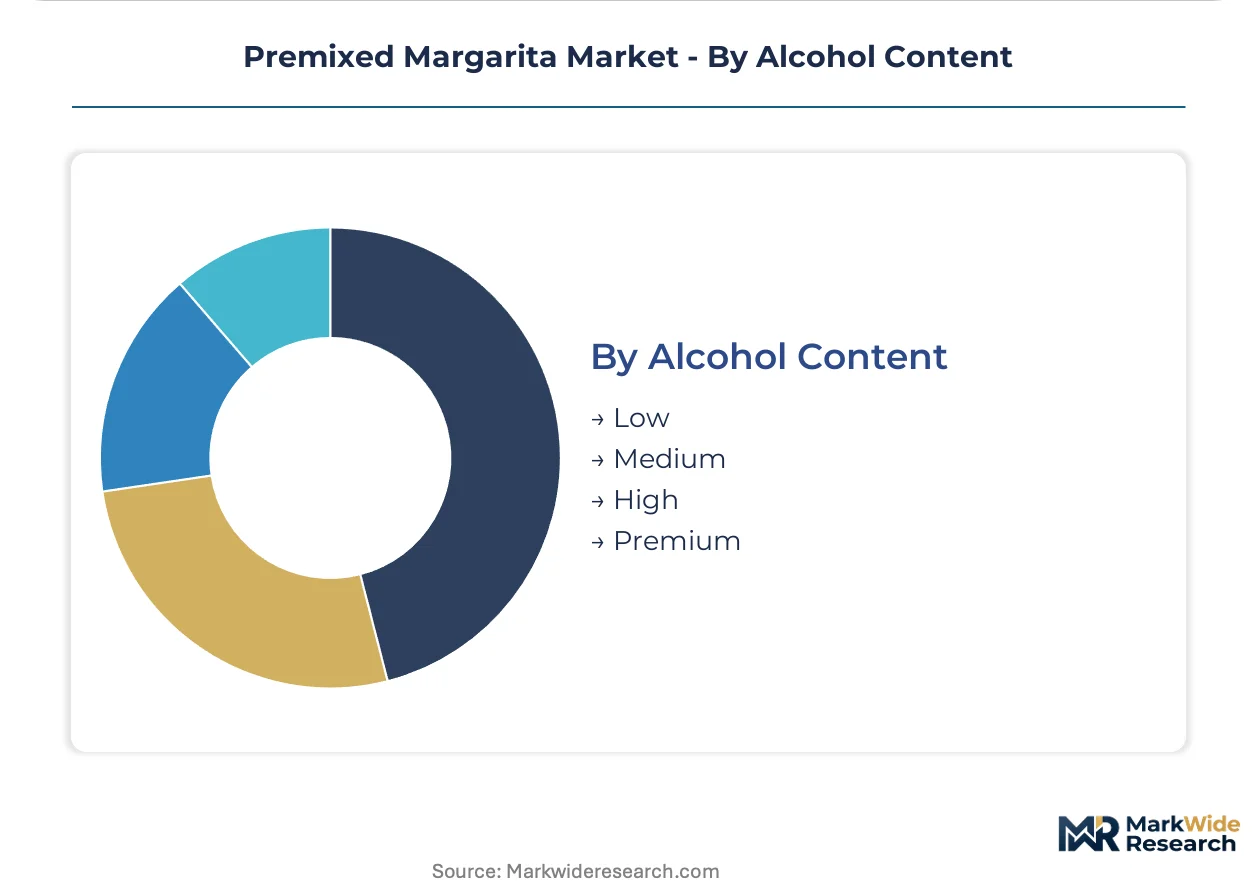
Alcohol Content:
Application context determines formulation strength, with on-premise dispenser systems requiring specific ABV ranges for equipment compatibility.
- Premium:10% to 12.5% ABV formulations using authentic tequila bases and cold-pressed lime oil stabilization. California and New York specialty retailers concentrate demand here for agave-forward authenticity claims.
- Medium:7% to 9.9% ABV mainstream positioning balancing flavor intensity with sessionability for extended outdoor consumption.
- Low:5% to 6.9% ABV entry-level price points competing directly with beer and seltzer alternatives.
- High:Above 12.5% ABV limited releases for mixology-substitution occasions requiring dilution.
Premium leads revenue per liter, with Medium capturing the widest demographic reach across age cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and Florida concentrate outdoor consumption occasions for premixed margaritas, while California drives premium agave-forward innovation through its specialty retail channel. The United States dominates absolute volume, though Mexico's Jalisco Highlands supply chain investments increasingly shape input cost structures for authentic formulations.
United States
Sun Belt states sustain year-round demand through golf course and beach venue channels. The TTB governs alcohol content disclosure and colloidal stability claims, forcing interstate formulation compliance. Texas and Florida distributors prioritize can formats for convenience-store reset velocity, compressing product introduction cycles to nine months.
Mexico
Jalisco Highlands plantation investment stabilizes Blue Weber agave supply for premium tequila bases. The country's federal environmental regulator oversees water usage permits for distillery operations in the denomination of origin zone. Guadalajara-based cooperatives are expanding cold-pressed lime oil stabilization capacity for export-ready formulations.
Canada
Provincial liquor board procurement concentrates demand in Ontario and British Columbia grocery channels. Health Canada regulates non-alcoholic ingredient safety for cross-border flavor compound shipments. Vancouver retailers are testing zero-proof line extensions as cannabis-infused beverage frameworks mature provincially.
United Kingdom
London specialty retailers drive demand for authentic agave-forward positioning in premium convenience formats. The Food Standards Agency governs allergen labeling for tropical flavor esters in imported formulations. Manchester-based distributors are negotiating slotting fee structures tied to velocity guarantees rather than upfront payments.
Australia
Queensland and New South Wales outdoor consumption occasions sustain canned format adoption through beach and stadium channels. The TGA oversees novel ingredient approvals for hybrid cannabis-alcohol formulations in development. Sydney-based importers are diversifying toward Bag-in-Box systems for on-premise casino and hotel dispenser deployment.
Premixed Margarita Market Competitive Landscape
Top-tier vendors anchor premium agave-forward positioning, while malt-beverage specialists compete on price without tequila sourcing requirements. The market structure splits between authenticity-claiming distillers and cost-optimized commodity formulators. Three archetypes dominate: heritage tequila houses leveraging vertical integration, rum-based hybrid producers sidestepping agave costs, and multi-category beverage conglomerates optimizing scale. Competitive moves concentrate on distributor relationship consolidation and cold-chain packaging technology licensing.
Within the heritage spirits tier, Beam Suntory and Bacardi Limited occupy positions defined by portfolio depth and geographic origin claims. Beam Suntory anchors authenticity through its tequila sourcing infrastructure, while Bacardi Limited exemplifies hybrid rum-and-lime positioning that bypasses pure agave requirements. E. & J. Gallo Winery represents the wine and spirits conglomerate archetype, leveraging existing three-tier distributor relationships for shelf placement velocity. These three entities sit within distinct competitive vectors—agave authenticity, cost-optimized hybridization, and scale-driven route-to-market efficiency—without overlapping strategic positioning.
| Leading Market Players |
|---|
| Beam Suntory |
| Bacardi Limited |
| E. & J. Gallo Winery |
| Brown-Forman |
| Pernod Ricard |
| Stateside Brands |
| Diageo |
| Constellation Brands |
| Anheuser-Busch |
| Others |
Value Network & Pricing Analysis
Captive agave sourcing through Jalisco Highlands plantation investment anchors both supply security and premium pricing power for authentic tequila-based formulations. This upstream control enables manufacturers to buffer Blue Weber harvest volatility while commanding shelf price premiums over malt-beverage substitutes.
Pricing Analysis
Capacity additions in Mexico's denomination of origin zone are reshaping price floors for premium agave-forward SKUs. Three-tier pricing structure across premium, standard, and economy levels separates authentic tequila formulations from malt-based alternatives and private-label entrants. Price differentiation rests on agave authenticity certification and cold-pressed lime oil stabilization quality. Cost compression in the economy tier is intensifying because malt-beverage competitors bypass seven-year agave maturation cycles. Convenience-store buyers in Texas and Florida exhibit highest price sensitivity, while Nevada casino procurement shows lowest.
Supply Chain Analysis
Domestic-content mandates in Mexico's denomination of origin zone are reshaping sourcing patterns for export-ready formulations. Geographic supply concentrates in Mexico, the United States, and Canada. Raw material dependencies center on Blue Weber agave hearts, cold-pressed lime oil, and aluminum can sheet. Supply chain risk stems from single-source vulnerability in Jalisco Highlands agave plantations. Distribution runs through three-tier wholesaler networks fragmented by state-level alcohol regulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The premixed margarita market functions as a regulatory compounder where TTB labeling modernization accelerates new SKU velocity and compresses formulation-to-shelf timelines.
For Market Incumbents: Deploy distributor relationship consolidation to secure slotting fee flexibility at Circle K and 7-Eleven. Deepen cold-chain packaging technology licensing for high-pressure processed citrus formulations. Malt-beverage substitution threatens authentic tequila positioning; counter through agave supply diversification into Jalisco Highlands cooperatives. Channel control at convenience-store resets remains the priority defensive lever. For New Entrants and Emerging Players: Direct-to-consumer platforms offer the lowest barrier entry for zero-proof line extensions in California and New York. White-space concentrates in cannabis-infused beverage hybrids as state THC frameworks mature. Mango flavor acceleration in Florida outdoor venues presents the most penetrable trial segment. Partner with Arizona and Nevada casino bars for Bag-in-Box dispenser pilot programs. For Investors and Strategic Acquirers: Roll-up economics work for regional craft distillers with captive agave contracts because three-tier fragmentation prevents national scale. Long-term viability favors authentic formulation specialists over malt-beverage commodity players. Target acquisition archetype: Texas or California small-batch distillers with cold-pressed lime oil stabilization capability. Monitor TTB guidance evolution on cannabis-derived ingredient labeling as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Agave Supply Diversification | Jalisco Highlands plantation investment stabilizes input costs against harvest volatility. |
| Cold-Press Stabilization Scale-Up | High-pressure processing preserves volatile aromatics for twelve-month shelf stability. |
| Zero-Proof Line Extension | Non-alcoholic formulations capture incremental shelf space as cannabis regulations mature. |
| Bag-in-Box Dispenser Deployment | Nevada and Arizona casino bars concentrate margin pools through reduced packaging waste. |
| Distributor Relationship Consolidation | Three-tier wholesaler partnerships secure velocity-based slotting fee structures at convenience chains. |
Research Methodology
Multiple input streams — executive interviews with tequila portfolio directors, procurement discussions with convenience-store category buyers, regulatory consultations with former TTB officials — were reconciled against secondary validation. Primary fieldwork captured formulation chemists at cold-press stabilization facilities, three-tier distributor account managers in Texas and Florida, and slotting fee negotiators at Circle K headquarters. Secondary sources encompassed FDA flavor compound safety filings, TTB colloidal stability guidance documents, and state-level alcohol shipping law databases. Bottom-up SKU velocity data and top-down category value estimates underwent iterative triangulation.
Data-stream reconciliation across the projection horizon applied segmentation modeling by formulation authenticity tier, packaging format, alcohol content band, and Sun Belt state cluster. CAGRs derived from trend extrapolation of convenience-store reset cycles and on-premise dispenser adoption curves. Industry-specific forecast inputs included Blue Weber agave plantation yield projections and aluminum recycling infrastructure expansion timelines.
The model assumes a particular technology adoption path; alternative pathways for high-pressure citrus processing would alter the outlook. Forecasts reflect assumptions on TTB regulatory stability, three-tier distribution law continuity, and agave harvest normalization. Alternative scenarios involving federal cannabis-beverage legalization or Jalisco drought conditions would revise trajectory materially. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Hip Flask Market
Alcoholic Beverages
Low-Alcohol Beer Market
Alcoholic Beverages
Pre-Mixed/RTD Alcoholic Drinks Market
Alcoholic Beverages
Russia Tequila Market
Alcoholic Beverages
Cider and Perry Market
Alcoholic Beverages
Craft Beer Market
Alcoholic Beverages
Roasted Malt Market
Alcoholic Beverages
Airport Duty-Free Liquor Market
Alcoholic Beverages
Europe Wine Coolers Market
Alcoholic Beverages
Vermouth Market
Alcoholic Beverages
Specialty Beer Market
Alcoholic Beverages
Uganda Spirits Market
Alcoholic Beverages
Alcohol Gummies Market
Alcoholic Beverages
Microbrewery Supplies Market
Alcoholic Beverages
Europe Kegs Market
Alcoholic Beverages
Nitro Cocktails Market