
 Middle East and Africa Kegs Market | 2026-2036
Middle East and Africa Kegs Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Kegs Market Foresight
Craft breweries and independent soft drink manufacturers is redrawing procurement patterns across the Middle East and Africa kegs landscape. Blefa GmbH leverages its precision-engineered stainless-steel fabrication to serve premium brewery clients in South Africa and the United Arab Emirates. Schaefer Container Systems anchors regional distribution through its established logistics partnerships with major beverage producers. Thielmann specializes in high-capacity industrial keg solutions that dominate distillery and large-scale brewery operations across the Gulf states.
Kegs are cylindrical vessels manufactured from stainless steel, aluminum, or food-grade polyethylene, typically featuring spear valves and chime rings for pressurized liquid dispensing in commercial beverage service. Wall thickness ranges from 1.5mm to 2.0mm for metal variants, with pressure ratings up to 3 bar ensuring carbonated product integrity during transport and storage. Metal Kegs command the largest installed base due to durability and established return-loop infrastructure, while Plastic Kegs represent the fastest-expanding category as weight reduction and one-way logistics gain traction among soft drink manufacturers and export-oriented wineries. Capacity segmentation shows 30L units capturing the dominant share in on-trade brewery supply, though 20L formats are displacing larger volumes in urban taprooms where space constraints and rotation speed matter.
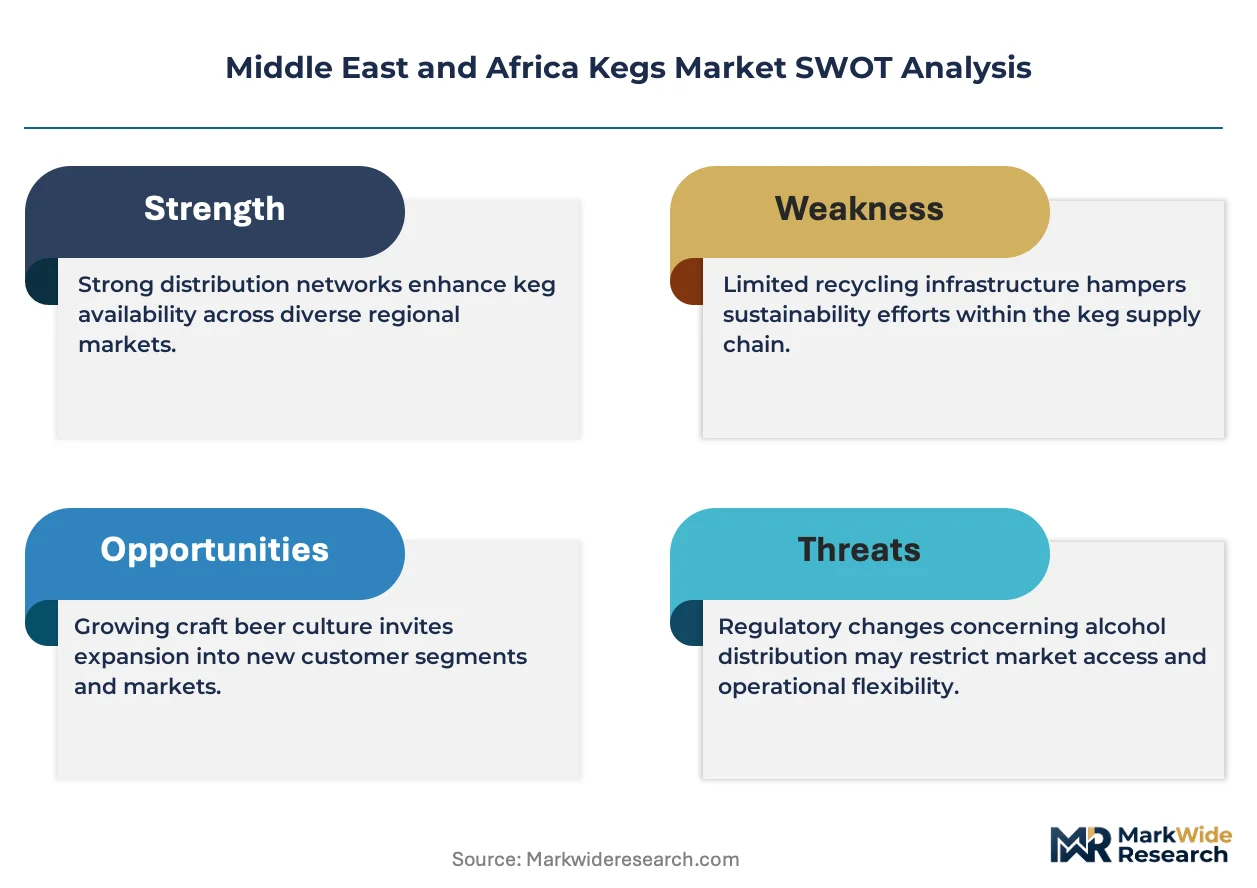
South Africa's National Regulator for Compulsory Specifications enforces pressure vessel safety standards that shape keg design and testing protocols across the region, while the UAE's Emirates Authority for Standardization and Metrology mandates food-contact material compliance for all imported beverage containers. The Gulf Cooperation Council's unified technical regulations for packaging materials create a harmonized compliance pathway for manufacturers seeking multi-country market access. Stakeholders must monitor evolving extended producer responsibility frameworks and assess whether returnable or single-use formats align with emerging deposit-return schemes across key African markets.
Market Dynamics
Sustainability mandates from South Africa's Department of Forestry, Fisheries and the Environment are accelerating the transition from single-use packaging to reusable keg systems across the region's beverage supply chain.
Growth Catalysts
- Extended Producer Responsibility frameworks:South Africa's evolving deposit-return schemes create direct financial incentives for breweries to adopt stainless-steel returnable formats over disposable alternatives.
- Gulf hospitality investment:Tourism infrastructure expansion across the United Arab Emirates and Saudi Arabia is generating premium keg procurement for on-premise consumption venues.
- Polyethylene material advances:Food-grade recyclable plastic kegs are capturing share among soft drink manufacturers seeking weight reduction for export logistics.
Market Restraints
- Stainless-steel input cost volatility:Nickel and chromium price fluctuations compress fabrication margins for metal keg producers serving price-sensitive African markets.
- Return-loop infrastructure gaps:Limited reverse logistics networks in Nigeria and Kenya extend asset recovery cycles and inflate total cost of ownership.
- Pressure vessel certification complexity:South Africa's National Regulator for Compulsory Specifications imposes multi-stage testing protocols that delay product commercialization.
Strategic Opportunities
- Nigerian craft brewery expansion:Independent beverage producers in Lagos and Abuja represent underpenetrated demand for 20L and 30L formats.
- Digital tracking integration:RFID-enabled keg fleet management is converging with blockchain provenance systems to reduce loss rates and improve asset utilization.
- GCC unified technical regulations:The Gulf Cooperation Council's harmonized packaging standards enable single-certification market access across six member states.
Industry Challenges
- Welding technician scarcity:Precision stainless-steel fabrication requires certified orbital welding specialists that remain concentrated in South Africa and the UAE.
- Multi-jurisdiction compliance timelines:Separate approvals from MOHAP in the UAE and the National Regulator in South Africa extend product launch cycles by 8-14 months.
- Legacy ERP integration friction:Returnable asset tracking systems require middleware development to connect with established brewery inventory platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Kegs Market |
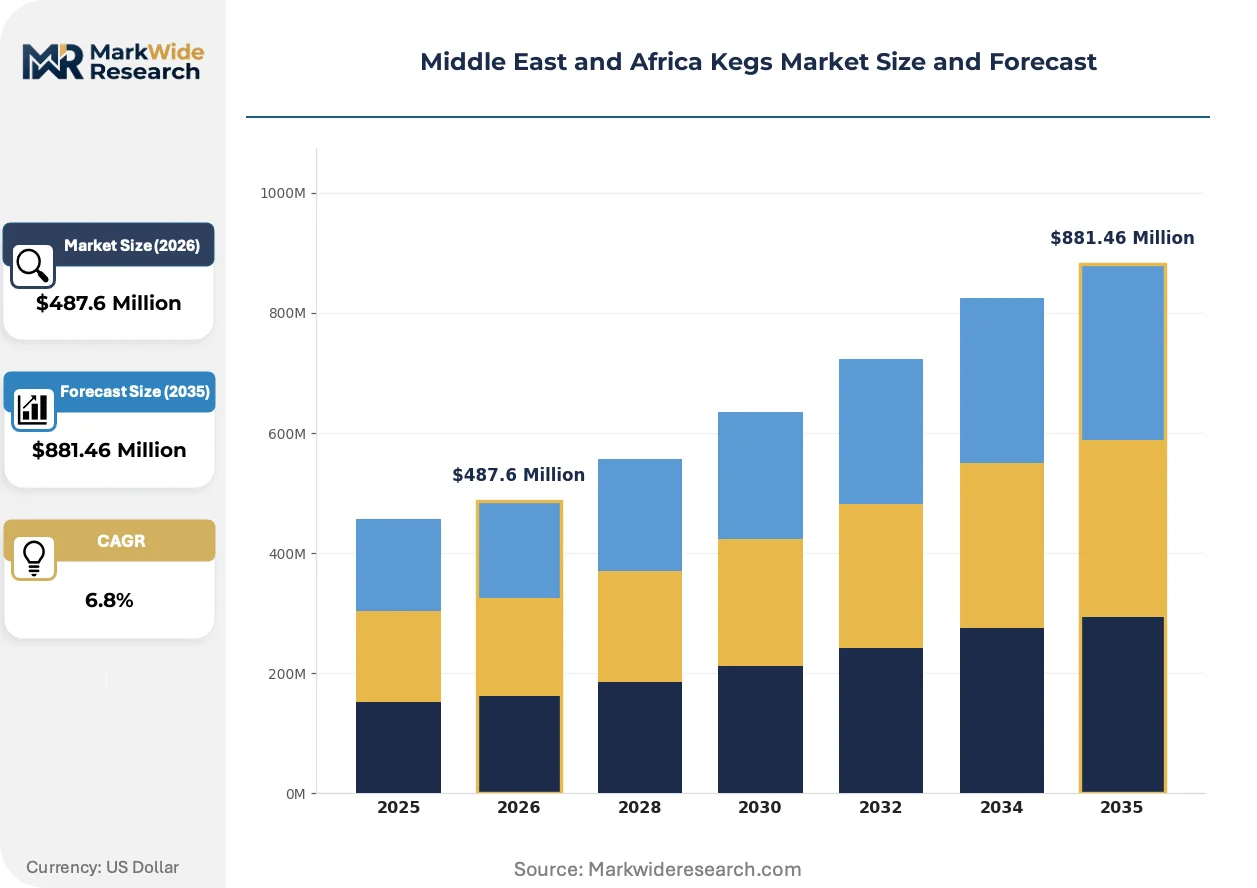
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Kegs, Plastic Kegs, Wooden Kegs, Specialty Kegs Industry Vertical: Breweries, Wineries, Distilleries, Soft Drink Manufacturers Capacity: 5L, 10L, 20L, 30L Distribution Channel: Direct Sales, Retail Outlets, Online Platforms, Wholesale Distributors |
| Companies Covered | Blefa GmbH, Schaefer Container Systems, Thielmann, Petainer, Ardagh Metal Packaging, Heineken N.V., Carlsberg Group, Anheuser-Busch InBev, OneCircle, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Kegs Market Shifts & Advancements
Material substitution and regulatory harmonization are compressing traditional procurement cycles while expanding addressable segments across the Middle East and Africa kegs landscape.
Polyethylene terephthalate (PET) barrier-layer kegs are decomposing the metal-dominant installed base by offering one-way logistics compatibility for wineries and soft drink exporters. Nigerian and Kenyan beverage distributors are adopting these formats for routes lacking reverse logistics infrastructure. The technology is decomposing the historical link between keg durability and geographic market viability, enabling premium beverage distribution into previously unreachable secondary cities.
South Africa's Department of Forestry, Fisheries and the Environment is enforcing mandatory extended producer responsibility for packaging waste, requiring beverage manufacturers to fund collection and recycling systems. This policy is redirecting capital expenditure toward returnable format fleets and away from single-use alternatives. Craft breweries in Cape Town and Johannesburg are responding by consolidating procurement around stainless-steel suppliers offering integrated fleet management services.
Taproom operators are unbundling after-sales service contracts from equipment procurement, selecting keg suppliers based on maintenance response time guarantees rather than upfront asset pricing. This behavior is fragmenting vendor relationships that historically bundled hardware and service. The shift is most visible in Dubai and Riyadh, where hospitality groups operate multi-brand venues requiring rapid keg rotation and technical support.
Middle East and Africa Kegs Market Segmentation
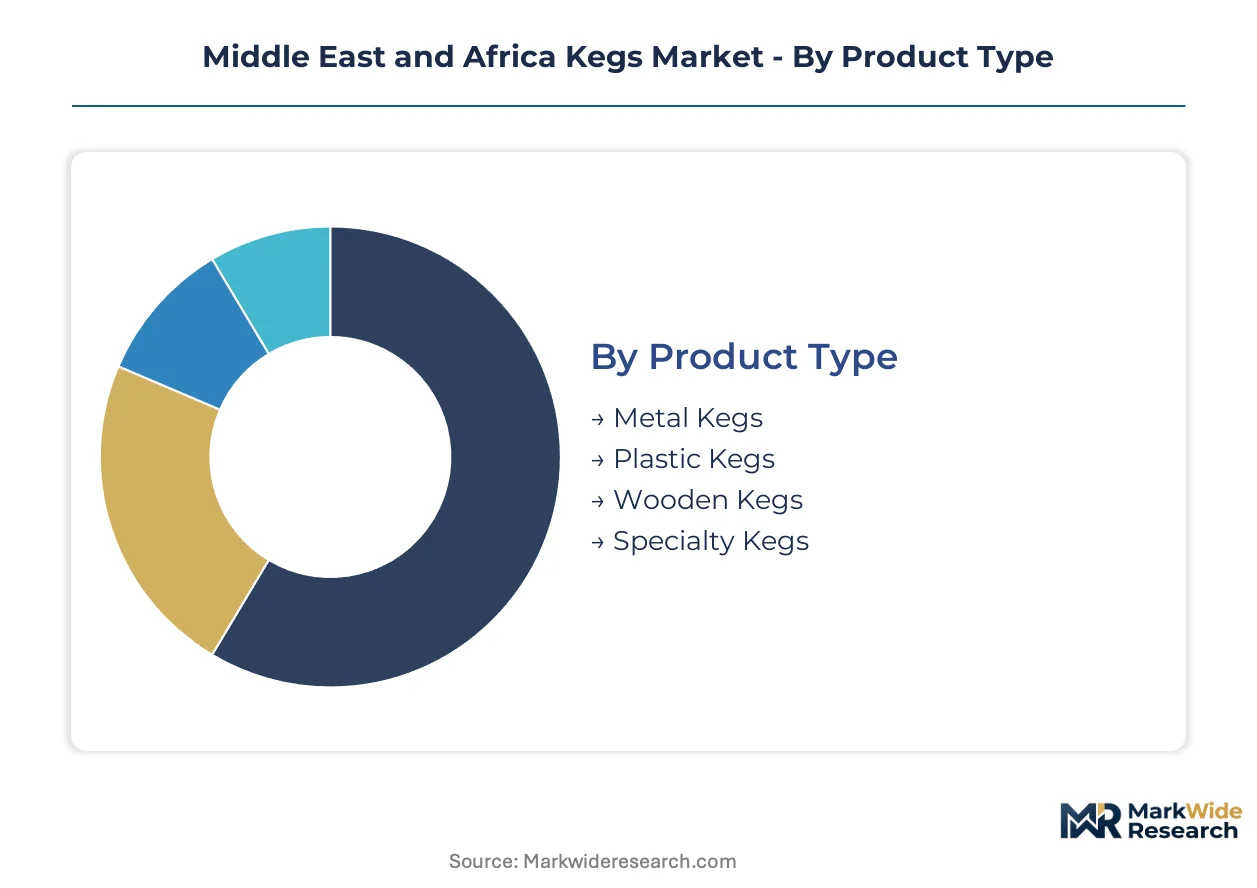
Keg procurement patterns across the Middle East and Africa diverge sharply by material durability, beverage chemistry, and route-to-market economics. Understanding these fault lines reveals where substitution pressures and infrastructure gaps reshape supplier priorities.
Product Type:
Plastic barrier-layer technologies are exerting the strongest substitution pressure on legacy formats, particularly where reverse logistics networks remain underdeveloped.
- Metal Kegs:Fabricated from 304-grade stainless steel with 1.5mm–2.0mm wall thickness and 3-bar pressure ratings, these vessels dominate brewery fleet investments across South Africa and the UAE. Return-loop infrastructure in Johannesburg and Cape Town sustains their economics despite nickel price volatility.
- Plastic Kegs:Food-grade polyethylene and PET barrier-layer constructions reduce empty weight by 60–70% versus metal equivalents, enabling one-way distribution to Nigerian and Kenyan secondary cities lacking keg-washing facilities. Soft drink manufacturers in Lagos are displacing metal formats for export routes.
- Wooden Kegs:Oak and chestnut constructions persist in specialty winery applications across Morocco and Lebanon, where traditional aging protocols command premium positioning.
- Specialty Kegs:Nitrogen-infused and insulated variants serve cold-brew coffee and kombucha producers in Dubai and Riyadh hospitality clusters.
Metal Kegs retain volume leadership across installed base metrics; Plastic Kegs hold the steepest expansion curve as logistics fragmentation spreads.
Industry Vertical:
Cost-tier stratification separates capital-intensive brewing operations from asset-light beverage categories with divergent keg ownership models.
- Breweries:Craft and industrial brewers across South Africa, Nigeria, and the UAE constitute the dominant procurement segment, with stainless-steel fleet investments tied to extended producer responsibility mandates from the Department of Forestry, Fisheries and the Environment.
- Wineries:Lebanese and Moroccan producers favor 20L formats for on-premise tasting room distribution, while South African exporters are testing PET kegs for European market trials.
- Distilleries:High-proof spirits producers in the Gulf states require specialized pressure-rated vessels with enhanced seal integrity for arid climate storage.
- Soft Drink Manufacturers:Coca-Cola bottlers and independent carbonated beverage producers in Kenya and Nigeria are adopting recyclable plastic kegs to bypass return-loop infrastructure gaps.
Breweries command the largest absolute keg fleet; Soft Drink Manufacturers are climbing the fastest as one-way logistics gain operational acceptance.
Capacity:
Application context dictates format selection, with space-constrained urban venues and high-rotation hospitality driving divergence from traditional volume norms.
- 30L:The standard brewery supply format dominates industrial brewing operations and large-format venues across the Gulf Cooperation Council, where throughput economics favor fewer changeouts per tap line.
- 20L:Urban taprooms in Cape Town, Johannesburg, and Dubai are displacing larger volumes where floor space constraints and rapid rotation speeds prioritize inventory velocity over per-unit cost.
- 10L:Niche positioning for premium specialty releases and pilot batch distribution among craft breweries testing market receptivity.
- 5L:Compact formats serve hotel minibars, airline catering, and residential direct-to-consumer trials in high-income Gulf households.
30L formats retain volume leadership in absolute deployment; 20L formats are gaining share fastest as urban hospitality density intensifies.
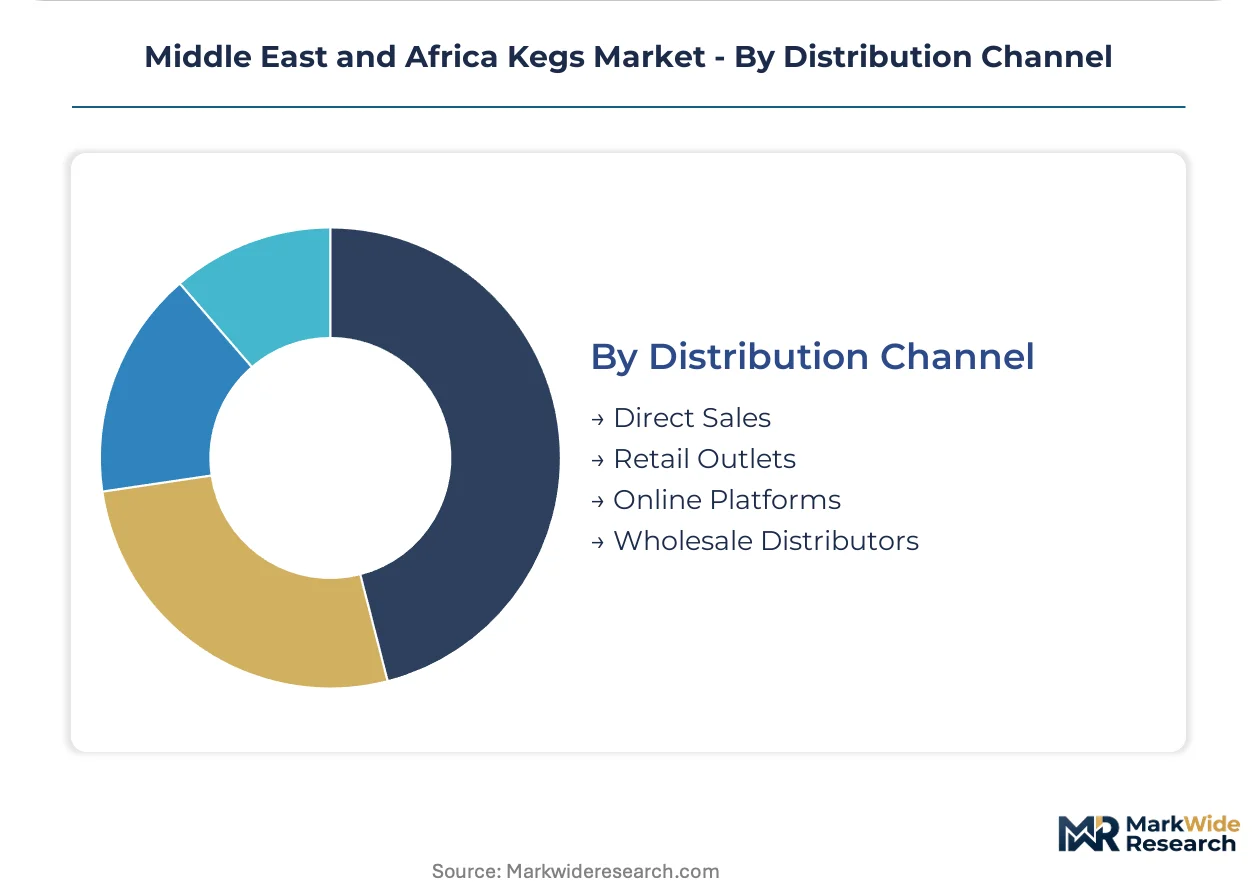
Distribution Channel:
Supply concentration varies sharply by customer scale, with integrated fleet management services bundling hardware and digital tracking for enterprise accounts.
- Direct Sales:Major brewery groups and hospitality chains in South Africa and the UAE negotiate directly with Blefa GmbH and Schaefer Container Systems for customized fleet deployments with embedded RFID tracking.
- Wholesale Distributors:Pan-African beverage logistics networks in Nigeria and Kenya aggregate fragmented craft brewery demand, though reverse logistics coordination remains a margin pressure point.
- Retail Outlets:Specialized hospitality equipment suppliers in Dubai and Riyadh serve independent venue operators with smaller lot sizes and faster delivery requirements.
- Online Platforms:Emerging digital procurement channels connect Nigerian and Kenyan craft breweries to European and Asian keg suppliers, though certification complexity delays fulfillment cycles.
Direct Sales retains volume leadership among enterprise accounts; Wholesale Distributors are expanding most quickly as craft brewery fragmentation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brewery procurement teams and hospitality groups concentrate demand across South Africa, the UAE, Nigeria, Saudi Arabia, and Kenya. Each market exhibits distinct infrastructure maturity and regulatory pressure points.
South Africa
Craft breweries in Cape Town and Johannesburg drive stainless-steel fleet investments as the National Regulator for Compulsory Specifications enforces pressure vessel testing protocols. The Department of Forestry, Fisheries and the Environment mandates extended producer responsibility for packaging waste. Return-loop infrastructure in Gauteng and Western Cape provinces sustains metal keg economics against plastic substitution.
United Arab Emirates
Hospitality groups in Dubai and Abu Dhabi generate premium keg procurement for on-premise consumption venues. MOHAP mandates food-contact material compliance for all imported beverage containers. Tourism infrastructure expansion across the Emirates creates demand for 30L formats in high-throughput hotel and entertainment districts.
Nigeria
Independent beverage producers in Lagos and Abuja represent underpenetrated demand for 20L and 30L formats. The country's national standards body regulates pressure equipment safety without harmonized regional frameworks. Distributors adopt recyclable plastic kegs for secondary cities lacking keg-washing facilities.
Saudi Arabia
Distilleries and large-scale brewery operations require specialized pressure-rated vessels for arid climate storage. SFDA oversees food-contact material standards for imported containers. Riyadh and Jeddah hospitality clusters drive procurement of nitrogen-infused and insulated specialty keg variants.
Kenya
Coca-Cola bottlers and independent carbonated beverage producers adopt recyclable plastic kegs to bypass return-loop infrastructure gaps. The country's national standards regulator enforces packaging safety requirements. Nairobi distribution networks aggregate fragmented craft brewery demand through wholesale channels.
Middle East and Africa Kegs Market Competitive Landscape
Player mix skews toward European precision fabricators and integrated beverage conglomerates with captive fleet operations. Market structure concentrates around stainless-steel specialists with established regional logistics partnerships and multinational brewers managing proprietary keg pools. Two strategic archetypes dominate: precision-engineered metal fabricators serving premium brewery clients, and diversified packaging groups offering material-flexible solutions. Competitive moves center on geographic expansion through local distributor alliances and portfolio diversification into recyclable plastic formats.
Among German-based fabricators, Blefa GmbH and Thielmann occupy positions within the precision-engineered tier, exemplifying stainless-steel specialization for pressure-rated beverage vessels. Schaefer Container Systems represents the integrated logistics archetype, anchoring regional distribution through established beverage producer partnerships.
| Leading Market Players |
|---|
| Blefa GmbH |
| Schaefer Container Systems |
| Thielmann |
| Petainer |
| Ardagh Metal Packaging |
| Heineken N.V. |
| Carlsberg Group |
| Anheuser-Busch InBev |
| OneCircle |
| Others |
Supply & Pricing Matrix
Polyethylene barrier-layer kegs displacing stainless-steel formats across Nigerian and Kenyan distribution networks simultaneously fragment supply geography toward Asian resin producers and compress pricing power for European metal fabricators serving price-sensitive African markets.
Pricing Analysis
Current-generation PET barrier-layer kegs trade at a 25-35% discount to legacy stainless-steel equivalents, while next-generation recyclable formats with enhanced oxygen barriers command modest premiums over standard plastic. Three-tier pricing structure across premium, standard, and economy levels separates RFID-enabled fleet-managed metal kegs from basic recyclable plastics and uncoated single-use alternatives. Pricing pressure stems from nickel and chromium volatility compressing fabrication margins for South African and UAE metal specialists. Small-scale craft breweries in Lagos and Nairobi exhibit highest price sensitivity, while integrated hospitality groups in Dubai prioritize service response guarantees over unit cost.
Supply Chain Analysis
Strait of Hormuz transit underwrites raw material flows for Gulf-based fabrication, with chokepoint exposure concentrated in containerized resin shipments from South Korea, China, and Thailand. Keg production draws from 304-grade stainless steel coils sourced from German and Italian mills, food-grade polyethylene resin from Saudi petrochemical complexes, and precision valve assemblies from German component specialists. Single-source vulnerability sits with orbital welding equipment concentrated among two European suppliers. Distribution runs through direct fleet contracts with major brewery groups, wholesale distributors aggregating fragmented craft demand, and specialized hospitality equipment suppliers serving independent venues.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent metal fabricators face a substitution defense against recyclable plastic formats that decompose historical links between keg durability and market viability across infrastructure-deficient African routes.
For Market Incumbents: Fortify return-loop infrastructure investments in Johannesburg and Cape Town to sustain stainless-steel economics against polyethylene substitution. Deepen captive supply of precision valve assemblies to offset welding technician scarcity compressing fabrication capacity. Prioritize RFID-enabled fleet management bundling to differentiate from asset-light plastic competitors. For New Entrants and Emerging Players: Lead with 20L PET barrier-layer formats targeting Nigerian craft breweries in Lagos and Abuja where keg-washing infrastructure remains absent. Penetrate Kenyan carbonated beverage distributors through wholesale channel partnerships bypassing direct sales requirements. Anchor go-to-market strategy on one-way logistics compatibility for export-oriented wineries testing European market trials. For Investors and Strategic Acquirers: The market sits at a material-transition phase that favors vertically integrated packaging groups with plastic-to-metal flexibility over pure-play metal fabricators. Long-term viability over the next decade rests on exposure to both return-loop infrastructure development and recyclable format adoption curves. Target acquisition archetypes include regional distributors with established reverse logistics networks and specialty keg innovators serving nitrogen-infused beverage segments. Watch deposit-return scheme implementation across key African markets as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Management Integration | RFID-enabled asset tracking reduces loss rates for brewery clients in South Africa and the UAE. |
| Material Portfolio Diversification | Recyclable plastic capacity expansion captures soft drink manufacturer demand across Nigeria and Kenya. |
| Regional Certification Harmonization | Gulf Cooperation Council unified standards enable single-approval market access across six member states. |
| Reverse Logistics Partnership | Third-party washing facility networks extend metal keg viability into secondary African cities. |
| Specialty Format Development | Nitrogen-infused and insulated variants serve cold-brew coffee producers in Dubai and Riyadh hospitality clusters. |
Research Methodology
Initial hypotheses were tested against primary input from brewery procurement directors, beverage distributor operations managers, hospitality group supply chain leads, and keg fabrication plant engineers and refined through secondary validation against customs trade databases, National Regulator for Compulsory Specifications filings, Gulf Cooperation Council technical regulation harmonization documents, and hospitality sector procurement disclosures. Bottom-up demand modeling across brewery fleet sizes, distributor route densities, and venue throughput requirements was triangulated with top-down market sizing from regional beverage production volumes and packaging mix disclosures.
Variance-decomposition across material substitution rates, regulatory implementation timelines, and infrastructure investment cycles shaped the analytical framework. Segmentation dimensions modeled include product type, industry vertical, capacity format, and distribution channel across the projection horizon. CAGRs were derived from installed base evolution, replacement demand patterns, and net new adoption curves. Forecast inputs incorporated extended producer responsibility mandate enforcement schedules from South Africa's Department of Forestry, Fisheries and the Environment and hospitality investment pipelines across the United Arab Emirates and Saudi Arabia.
The analysis sits within stated boundaries; outcomes outside sustained nickel price stability, GCC tourism investment continuity, or Nigerian distributor credit availability would require recalibration. Forecasts reflect documented assumptions regarding return-loop infrastructure development rates and recyclable plastic barrier-layer technology maturation. Practitioners should keep alternative scenarios live as deposit-return scheme legislation and polyethylene resin supply dynamics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Europe Craft Beer Market
Alcoholic Beverages
Sparkling Wine Market
Alcoholic Beverages
Low-Alcohol Beer Market
Alcoholic Beverages
High-End Chinese Spirits Market
Alcoholic Beverages
East Africa Alcoholic Beverages Market
Alcoholic Beverages
Premixed Cocktail Shots Market
Alcoholic Beverages
Cannabis-Based Alcoholic Beverages Market
Alcoholic Beverages
Japan Tequila Market
Alcoholic Beverages
Europe Wine Market
Alcoholic Beverages
Pineapple Beer Market
Alcoholic Beverages
CBD Wine Market
Alcoholic Beverages
Beer Adjuncts Market
Alcoholic Beverages
Asia-Pacific Alcoholic Beverage Market
Alcoholic Beverages
Wine Destemmer Market
Alcoholic Beverages
Vermouth Market
Alcoholic Beverages
Barware Market