
 Global Wine Coolers Market | 2026-2036
Global Wine Coolers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wine Coolers Market Outlook
The capital-intensity divergence between compressor-based incumbents and thermoelectric challengers is unwinding traditional margin structures in the wine cooler industry. Electrolux AB leverages its European manufacturing footprint to sustain premium positioning across built-in and freestanding lines. Haier Group Corporation anchors volume competition through integrated compressor supply chains and broad distribution in Asia-Pacific. EuroCave SAS differentiates via specialized cellar-grade climate control systems that command architectural-specification channels.
Wine coolers are climate-controlled refrigeration appliances engineered to maintain precise temperature ranges, typically between 45°F and 65°F, with humidity management and UV-resistant glass to preserve wine quality over extended storage periods. Freestanding units dominate residential installations due to placement flexibility, while built-in configurations capture margin pools tied to kitchen renovation cycles and custom cabinetry integration. Dual-zone capacity configurations lead growth as consumers segment red and white wine collections within single appliances, reflecting evolving consumption patterns rather than simple storage expansion.
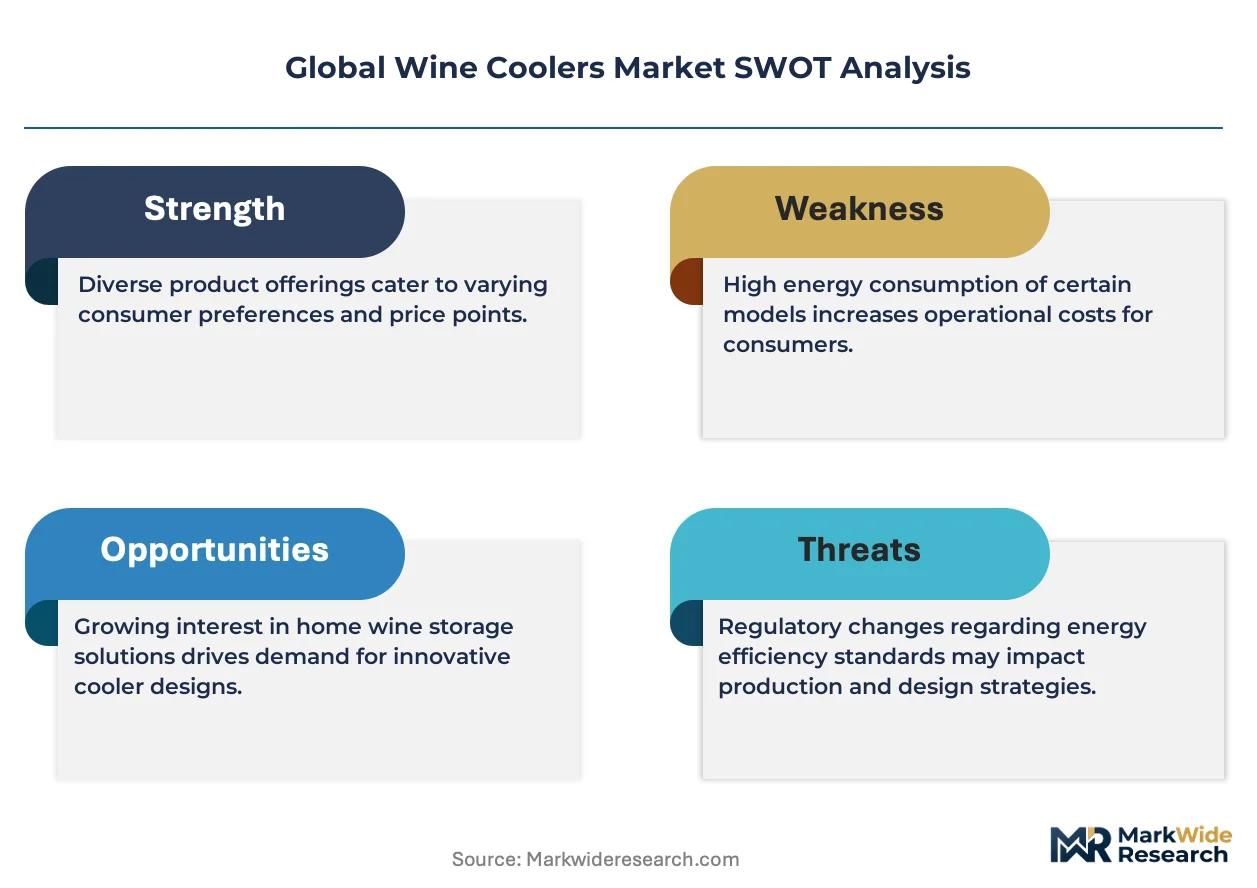
The U.S. Department of Energy appliance efficiency standards, the EU Ecodesign Directive, and China's GB standards for household refrigeration collectively compress allowable energy consumption thresholds and reshape product development priorities across manufacturing bases. REACH compliance in Europe and California's Title 20 regulations further constrain refrigerant selection and insulation material specifications, elevating compliance costs for cross-border suppliers. Stakeholders must monitor refrigerant phase-down schedules and regional efficiency tier upgrades to anticipate redesign cycles and inventory obsolescence risks.
Market Dynamics
Energy-efficiency mandates from the EU Ecodesign Directive and the U.S. Department of Energy are compressing margins for conventional compressor-based units while favoring thermoelectric and inverter-driven alternatives.
Growth Catalysts
- Residential kitchen renovation cycles:Premium appliance replacement in the United States and Germany is pulling built-in wine cooler specifications into mainstream home improvement budgets.
- REACH compliance thresholds:European insulation material standards are accelerating R-600a refrigerant adoption across manufacturing bases, opening redesign windows for efficient product lines.
- Dual-zone cooling technology:Thermoelectric systems with independent temperature chambers are capturing consumer preference for segmented red and white wine storage within single units.
Market Restraints
- Copper and steel input volatility:Compressor manufacturing and cabinet fabrication face margin pressure from commodity price swings in Chinese and Chilean metal supply chains.
- Compressor supply concentration:Secop and Embraco control over two-thirds of global hermetic compressor output, creating single-source vulnerability for mid-tier assemblers.
- Technical limitation in thermoelectric efficiency:Peltier modules struggle below 50°F setpoints, restricting their deployment in cellar-grade long-term storage applications.
Strategic Opportunities
- China's urban wine culture expansion:First-time appliance buyers in Shanghai and Shenzhen represent untapped volume for entry-level freestanding units under 50-bottle capacity.
- U.S. Inflation Reduction Act appliance rebates:State-level efficiency incentives are creating pull-through for inverter-driven models in California and New York replacement markets.
- Smart home integration convergence:Wi-Fi-enabled temperature monitoring combined with voice assistant compatibility is opening premium pricing tiers in connected kitchen ecosystems.
Industry Challenges
- Thermoelectric module sourcing complexity:Rare earth element dependency in bismuth telluride substrates requires qualification of alternative suppliers outside Chinese processing concentration.
- Cross-border certification timelines:UL, CE, and GB standard harmonization delays extend product launch windows by 8-14 months for multi-region manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wine Coolers Market |
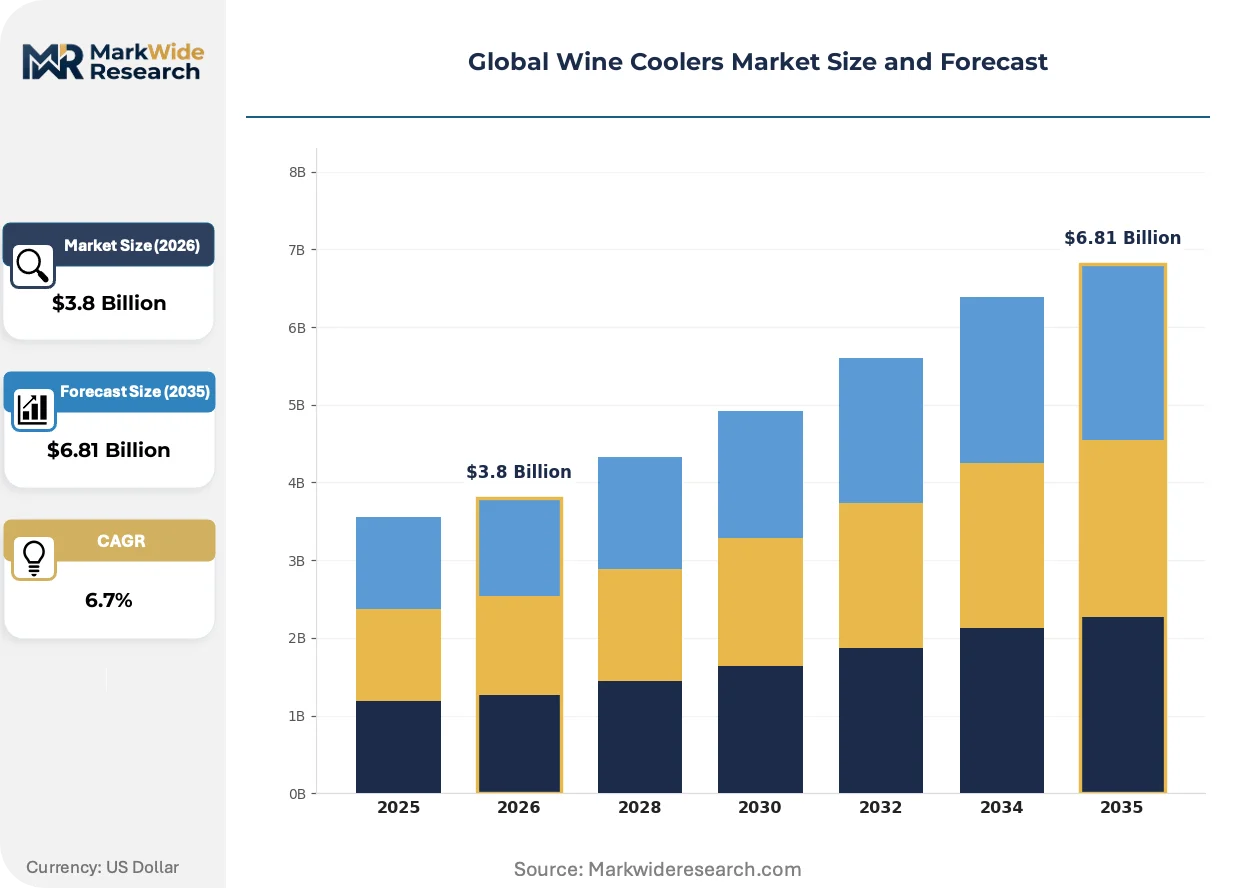
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freestanding, Built-in, Countertop, Commercial Capacity: Single Zone, Dual Zone, Multi-zone, Large Capacity Distribution Channel: Online Retail, Specialty Stores, Department Stores, Supermarkets End User: Households, Restaurants, Hotels, Wineries |
| Companies Covered | Electrolux AB, Haier Group Corporation, LG Electronics, Shenzhen VRBON Electrical Appliance Co., Ltd., EuroCave SAS, Allavino, Avanti Products Inc, U-Line, Whynter LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wine Coolers Market Strategic Shifts
Inverter-driven compressor technology is actively reshaping efficiency benchmarks while thermoelectric systems carve new entry-level segments. Regulatory pressure on refrigerant choice and connected appliance expectations are simultaneously redefining product architecture and go-to-market requirements.
Inverter compressors with variable-speed drives are supplanting fixed-speed reciprocating units in premium and mid-tier product lines. Kitchen renovation contractors in Germany and the United States are specifying these systems for built-in installations where noise reduction and energy labeling visibility matter. The shift is compressing margin pools for conventional compressor OEMs while rewarding electronics-integrated subsystem suppliers.
The EU F-Gas Regulation phase-down schedule is restricting hydrofluorocarbon refrigerant availability for imported compression systems. European manufacturers are accelerating R-600a and R-290 hydrocarbon transitions, requiring redesign of electrical safety enclosures and shipping logistics. Built-in product categories face the steepest compliance cost escalation due to tighter space constraints for flameproofing components.
Builder and architect specification channels are fragmenting as direct-to-consumer online platforms capture replacement-cycle purchases. Specialty kitchen retailers in France and the United States are losing share to manufacturer-owned e-commerce and home improvement big-box fulfillment networks. This channel rotation is most visible in freestanding unit categories where installation simplicity eliminates professional intermediary value.
Global Wine Coolers Market Segmentation
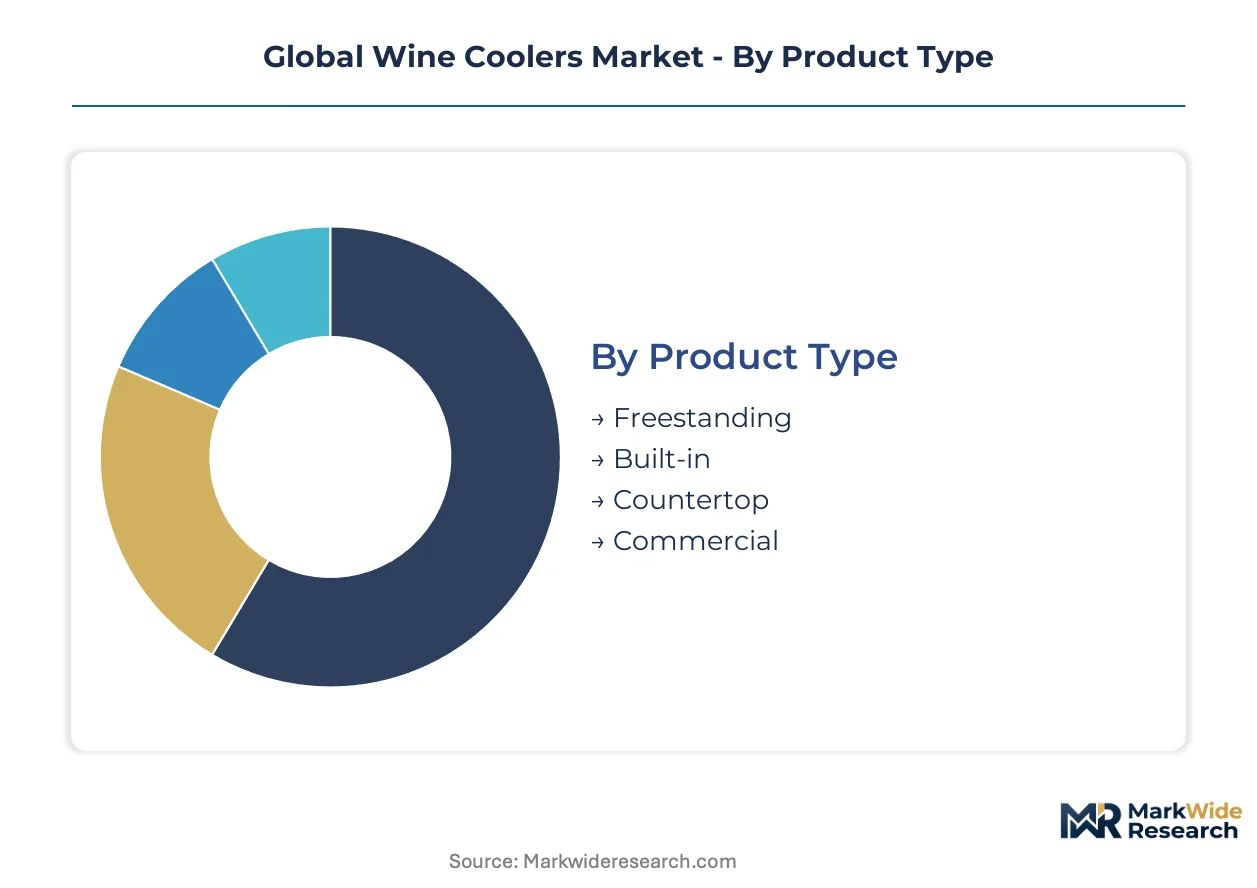
Wine cooler segmentation reflects divergent technical requirements across residential and commercial deployments. Product architecture, capacity configuration, channel strategy, and end-use application each create distinct margin pools and competitive dynamics.
Product Type:
Domestic demand concentrates in freestanding units across the United States and Germany, while built-in configurations track premium kitchen renovation cycles in export-led markets.
- Freestanding:Self-contained refrigeration systems with castor-mounted cabinets enable placement flexibility in residential spaces without cabinetry modification. Demand clusters in first-time appliance purchases across Shanghai and Shenzhen, driven by urban apartment dwellers seeking entry-level wine storage solutions.
- Built-in:Front-venting compressors and zero-clearance cabinetry interfaces integrate with custom kitchen millwork. German and U.S. kitchen renovation contractors specify these units where energy labeling visibility and noise reduction justify premium positioning.
- Countertop:Thermoelectric cooling modules in compact 6-12 bottle configurations serve space-constrained urban households.
- Commercial:High-capacity compressor banks with reinforced shelving withstand continuous operation in hospitality environments.
Freestanding holds the largest share; momentum sits with built-in as kitchen renovation budgets expand.
Capacity:
Cost tier stratification separates entry-level single-zone units from premium multi-zone systems with independent climate chambers.
- Dual Zone:Independent temperature chambers maintain separate setpoints for red and white wine collections within single appliances. U.S. and Chinese consumers increasingly prefer segmented storage configurations that reflect evolving consumption patterns rather than simple volume expansion.
- Multi-zone:Three or more isolated compartments with dedicated evaporators enable precise climate control for diverse varietal requirements. Architectural specification channels in France and California drive adoption where collectors require cellar-grade storage conditions.
- Single Zone:Uniform temperature maintenance suits budget-conscious households with homogeneous wine preferences.
- Large Capacity:100+ bottle configurations serve dedicated collectors and small commercial operations.
Dual Zone commands the premium tier; Multi-zone is climbing the fastest among renovation-driven replacement cycles.
Distribution Channel:
Volume concentration favors direct-to-consumer platforms, while specialty retail retains influence in specification-heavy built-in categories.
- Online Retail:Manufacturer-owned e-commerce and home improvement marketplace fulfillment capture freestanding replacement purchases. France and the United States show pronounced channel rotation as installation simplicity eliminates professional intermediary value.
- Specialty Stores:Kitchen design showrooms and appliance galleries provide specification support for built-in integration. German contractors rely on these channels where cabinetry coordination requires technical consultation.
- Department Stores:Mass-market positioning targets gift purchases and impulse appliance acquisitions.
- Supermarkets:Limited SKUs in seasonal displays capture entry-level countertop unit sales.
Online Retail dominates transaction volume; Specialty Stores defend margin in architect-specified projects.
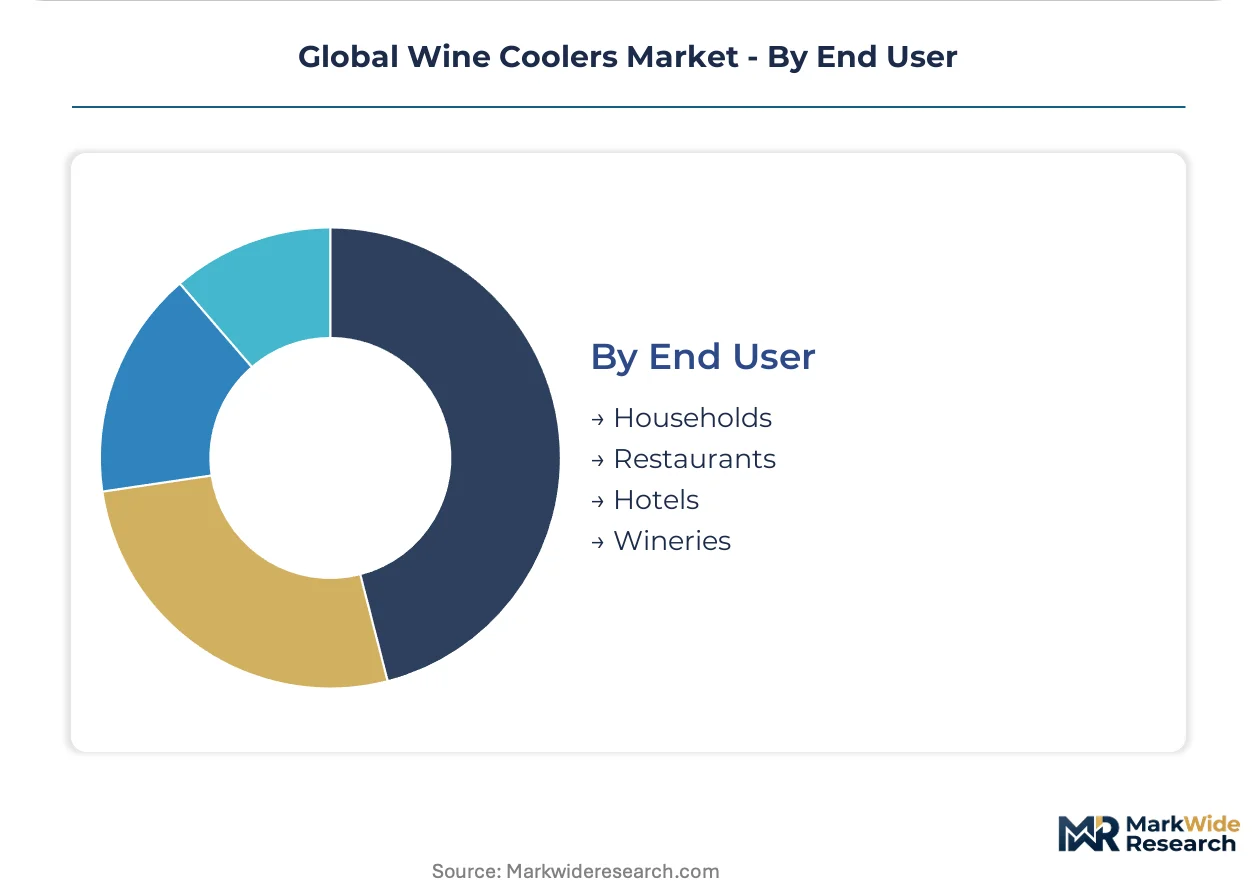
End User:
Application maturity separates established residential demand from emerging commercial deployment patterns.
- Households:Residential wine storage spans countertop units to built-in cellar systems across income segments. U.S. and German premium kitchen renovations pull built-in specifications into mainstream home improvement budgets.
- Restaurants:Front-of-house display coolers and back-of-house inventory systems require distinct temperature and humidity protocols. Urban dining clusters in Shanghai and New York drive replacement cycles as wine program investments expand.
- Hotels:In-room minibars and lobby display units prioritize noise reduction and aesthetic integration.
- Wineries:Tasting room presentation and laboratory sample storage create specialized requirements.
Households anchor absolute volume; Restaurants represent the steepest expansion trajectory as hospitality wine service investments recover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German and U.S. buyers absorb premium built-in specifications during renovation cycles. Chinese first-time purchasers gravitate toward entry-level freestanding units under 50-bottle capacity.
United States
Premium kitchen renovation cycles pull built-in wine cooler specifications into mainstream home improvement budgets. The Department of Energy appliance efficiency standards compress allowable energy consumption thresholds for imported compression systems. California and New York replacement markets show pronounced pull-through for inverter-driven models leveraging state-level efficiency incentives.
Germany
Kitchen renovation contractors specify front-venting built-in units where energy labeling visibility and noise reduction justify premium positioning. The EU Ecodesign Directive and F-Gas Regulation phase-down schedule accelerate R-600a hydrocarbon transitions across manufacturing bases. Bavarian and North Rhine-Westphalian kitchen design showrooms retain specification influence where cabinetry coordination requires technical consultation.
China
First-time appliance buyers in Shanghai and Shenzhen represent untapped volume for entry-level freestanding units. GB standards for household refrigeration reshape product development priorities across domestic manufacturing bases. Pearl River Delta fabrication clusters concentrate thermoelectric module assembly for export-oriented countertop configurations.
France
Architectural specification channels drive multi-zone adoption where collectors require cellar-grade storage conditions. REACH compliance thresholds constrain insulation material specifications and elevate cross-border supplier compliance costs. Île-de-France and Provence-Alpes-Côte d'Azur specialty kitchen retailers lose share to manufacturer-owned e-commerce as installation simplicity eliminates professional intermediary value.
Japan
Space-constrained urban households favor compact countertop thermoelectric configurations. METI efficiency labeling programs and JIS standards shape import requirements for foreign manufacturers. Kanto and Kansai metropolitan clusters concentrate demand for premium built-in integration with custom kitchen millwork.
Global Wine Coolers Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier. Compressor-based incumbents leverage captive supply chains and broad distribution networks. Thermoelectric challengers carve entry-level segments through simplified product architecture. Strategic moves concentrate on M&A for regional channel access and portfolio diversification across price tiers.
Among European appliance conglomerates, Electrolux AB anchors premium positioning across built-in and freestanding lines. Haier Group Corporation exemplifies volume competition through integrated manufacturing footprints and Asia-Pacific distribution density. EuroCave SAS occupies a specialist position within architectural-specification channels for cellar-grade climate control systems.
| Leading Market Players |
|---|
| Electrolux AB |
| Haier Group Corporation |
| LG Electronics |
| Shenzhen VRBON Electrical Appliance Co., Ltd. |
| EuroCave SAS |
| Allavino |
| Avanti Products Inc |
| U-Line |
| Whynter LLC |
| Others |
Value Chain & Pricing Dynamics
Ninety-day compressor inventory cycles at Secop and Embraco facilities compress pricing power for mid-tier assemblers while amplifying margin capture for integrated manufacturers with captive supply chains. This lead-time concentration shapes tiered pricing structures across built-in and freestanding categories.
Pricing Analysis
After-sales service contracts and replacement compressor warranties drive lifetime value for premium built-in lines. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and cabinetry integration complexity. Cost compression in entry-level thermoelectric tiers intensifies because Chinese module oversupply feeds spot-market pricing. First-time purchasers in Shenzhen and Shanghai exhibit highest price sensitivity; German kitchen renovation contractors absorb premium positioning for energy-labeled units.
Supply Chain Analysis
Panama Canal transit constraints and Red Sea routing disruptions expose just-in-time compressor delivery schedules to logistics volatility. Manufacturing gravity centers on China for thermoelectric module assembly, Germany for precision compressor components, and Mexico for U.S.-bound cabinet fabrication. Bismuth telluride substrates, copper refrigerant tubing, and low-emissivity glass panels anchor raw material dependencies. Single-source vulnerability concentrates in hermetic compressor supply. Distribution runs through home improvement big-box networks and manufacturer-direct e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wine cooler interoperability with smart home platforms creates platform-economics inflection as voice assistant integration and Wi-Fi monitoring reshape consumer expectations. This ecosystem shift rewards electronics-integrated subsystem suppliers over conventional refrigeration OEMs.
For Market Incumbents: Shield premium positioning by accelerating inverter-driven compressor transitions ahead of EU F-Gas Regulation phase-down deadlines. Secure R-600a hydrocarbon supply agreements before refrigerant availability constraints tighten. Deepen backward integration into thermoelectric module sourcing to offset rare earth element dependency risks from Chinese processing concentration. For New Entrants and Emerging Players: Smart home integration gaps in legacy OEM portfolios offer white-space entry through Wi-Fi-enabled temperature monitoring and voice assistant compatibility. Target China's first-time appliance buyers in Pearl River Delta urban clusters with entry-level freestanding units under 50-bottle capacity. Pursue direct-to-consumer e-commerce launch to bypass specialty retailer margin extraction. For Investors and Strategic Acquirers: Long-term, this sits as a connected-appliance infrastructure play because kitchen renovation cycles and regulatory efficiency mandates compound replacement demand for electronics-integrated systems. Acquisition candidates with thermoelectric IP and smart home platform certifications command strategic premium. Watch EU Ecodesign Directive tier upgrades as inflection signal for redesign cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Compressor Transition | Variable-speed drives meet DOE efficiency standards while reducing noise in built-in installations. |
| Hydrocarbon Refrigerant Adoption | R-600a and R-290 transitions align with EU F-Gas Regulation phase-down schedules. |
| Smart Home Platform Integration | Wi-Fi-enabled monitoring and voice assistant compatibility unlock premium pricing tiers. |
| Direct-to-Consumer Channel Expansion | Manufacturer-owned e-commerce captures freestanding replacement purchases from specialty retailers. |
| Thermoelectric Module Sourcing Diversification | Alternative bismuth telluride suppliers outside China reduce rare earth element concentration risk. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across kitchen renovation contractors, appliance procurement managers at home improvement retailers, thermoelectric module engineers, and compressor manufacturing executives. Secondary validation drew from U.S. Department of Energy appliance efficiency filings, EU Ecodesign Directive regulatory texts, Chinese GB standards documentation, and SEC 10-K disclosures from listed appliance manufacturers. Bottom-up capacity modeling and top-down consumption estimates were triangulated to anchor volume projections.
Across the analysis window, forecasts segment by product architecture, capacity configuration, distribution channel, and end-use application. CAGRs were derived from replacement cycle modeling, renovation spend elasticity, and regulatory compliance-driven redesign schedules. Inputs include kitchen renovation permit data, wine consumption demographic shifts, and efficiency standard upgrade timelines.
Forecasts assume regulatory continuity in EU Ecodesign Directive, U.S. Department of Energy appliance standards, and Chinese GB frameworks; material policy shifts would require re-modeling. Copper and steel commodity volatility, refrigerant phase-down acceleration, and smart home platform consolidation represent specific revision triggers. Practitioners should keep alternative scenarios live as efficiency tier upgrades and supply chain reconfiguration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Alcohol Gummies Market
Alcoholic Beverages
Canada Wine Coolers Market
Alcoholic Beverages
Organic Beer Market
Alcoholic Beverages
Mezcal Market
Alcoholic Beverages
Beer Adjuncts Market
Alcoholic Beverages
Middle East and Africa Alcoholic Beverage Market
Alcoholic Beverages
RTD Canned Cocktail Market
Alcoholic Beverages
Portable Keg System Market
Alcoholic Beverages
Alcoholic Drinks Market
Alcoholic Beverages
Airport Duty-Free Liquor Market
Alcoholic Beverages
US Frozen Cocktail Popsicles Market
Alcoholic Beverages
RTD Cocktails Market
Alcoholic Beverages
Black Beer Market
Alcoholic Beverages
Instant Wine Chillers and Refreshers Market
Alcoholic Beverages
Roasted Malt Market
Alcoholic Beverages
Hopped Malt Extract Market