
 North America Cheese Powder Market | 2026-2036
North America Cheese Powder Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cheese Powder Market Intelligence
Foodservice distribution channels for cheese powder is fragmenting as more manufacturers pursue direct-to-customer sales for bulk orders. Land O'Lakes leverages its extensive dairy cooperative network for a consistent supply of raw materials. Kerry Group competes on the basis of its wide portfolio of specialized flavor systems and ingredient blends. Kraft Heinz Ingredients sustains its market position through strong brand recognition in both retail and industrial segments within the United States and Canada.
North American cheese powder is a dehydrated dairy product created by spray-drying a slurry of one or more cheese varieties. This process yields a shelf-stable powder with a low moisture content, preserving the flavor profile of the original cheese. Its primary commercial purpose is to provide concentrated cheese flavor and functionality in dry-mix applications. Cheddar remains the dominant product type due to its versatility, while specialty powders like Asiago and Blue represent a faster-growing, higher-margin niche. In terms of application, snack seasoning and sauces constitute the largest volume segments.
The U.S. Food and Drug Administration (FDA) enforces strict standards for dairy product identity, labeling, and allergen declarations. Similarly, Health Canada's Food and Drug Regulations govern safety and composition requirements for cheese-derived ingredients sold in Canada. Adherence to these distinct national regulatory frameworks is essential for ingredient suppliers aiming for seamless cross-border trade. Formulators must also monitor evolving consumer preferences for clean-label and non-GMO ingredients.
Market Dynamics
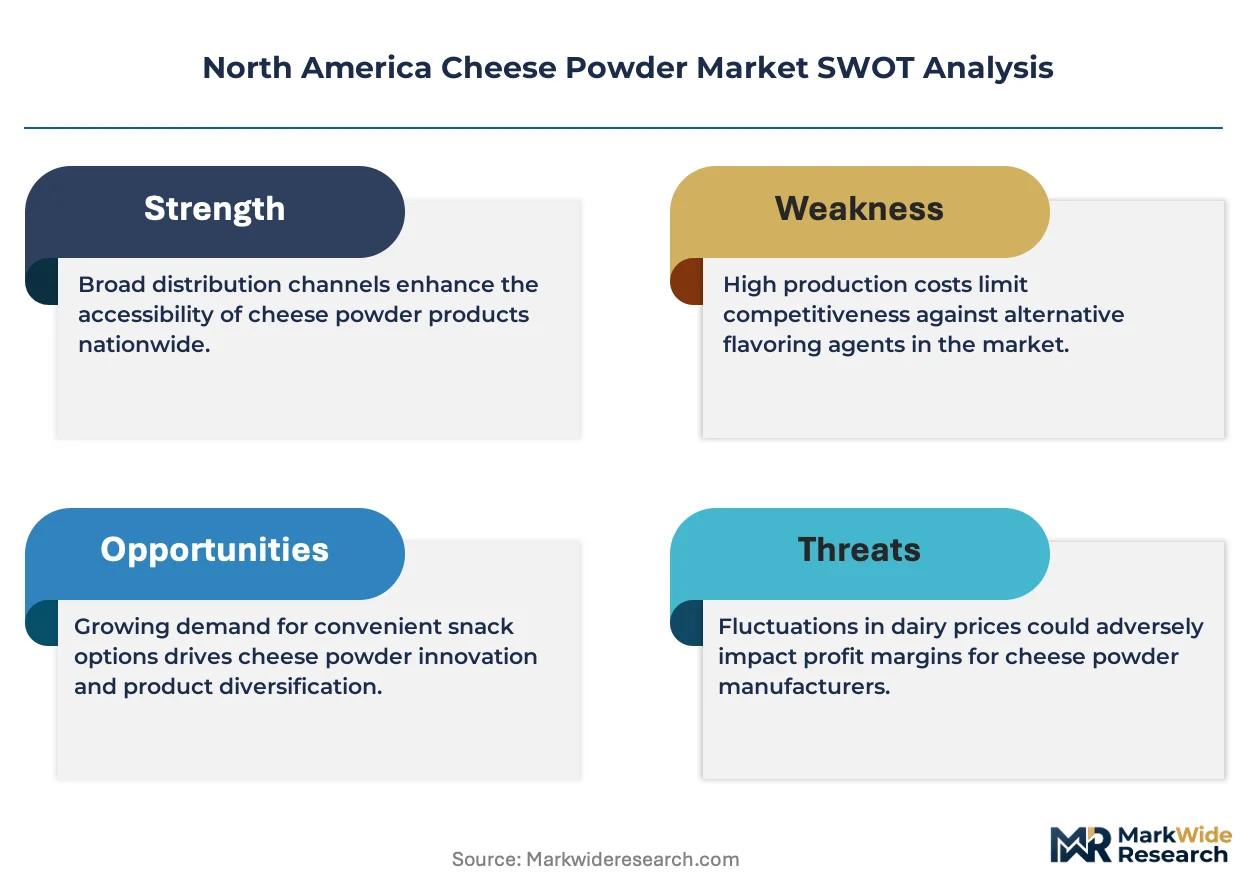
The North American cheese powder market is defined by the tension between commodity cheddar applications and the rising demand for clean-label, non-GMO ingredients. This dynamic forces producers to balance cost-efficiency with formulation transparency to meet evolving CPG and consumer standards.
Growth Catalysts
- Snack Seasoning Demand:The expanding savory snacks category in the United States and Canada provides a consistent volume driver for cheddar and specialty cheese powders used in topical seasonings.
- Clean-Label Formulation:Consumer and CPG manufacturer preference for simple, recognizable ingredients creates demand for cheese powders that can replace artificial flavors and texturizers in processed foods.
- Mexican Market Expansion:Growth in Mexico’s processed food manufacturing sector, particularly in sauces and baked goods, offers a significant new geographic market for North American powder exporters.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of raw milk, the primary feedstock for cheese production, directly impact manufacturing costs and create margin pressure for powder producers.
- Plant-Based Alternatives:The increasing sophistication of plant-based flavor systems, particularly those mimicking cheese, presents a substitution threat in vegan and flexitarian product lines.
- Regulatory Divergence:Differences in food additive and labeling standards between the U.S. FDA and Health Canada can complicate product formulation and increase compliance costs for cross-border trade.
Strategic Opportunities
- Pet Food Flavoring:The humanization of pets trend opens a new application frontier for cheese powder as a palatability enhancer in premium dog and cat food formulations.
- Organic and Specialty Powders:Developing certified organic, non-GMO, or single-origin cheese powders caters to a high-margin niche of clean-label and artisanal food manufacturers.
- Direct-to-Artisan Channels:E-commerce platforms enable direct sales of specialty powders like blue or goat cheese to small-batch producers, bypassing traditional large-volume distributors.
Industry Challenges
- Flavor Profile Consistency:Maintaining a consistent flavor and color profile from batch to batch, especially with natural cheese inputs, requires significant investment in quality control and sensory analysis capabilities.
- Reformulation Complexity:Removing additives to achieve a clean label often requires complex and costly reformulation efforts to maintain the powder's functional properties like flowability and solubility.
- Energy Consumption:The spray-drying process is highly energy-intensive, exposing manufacturers to volatile energy costs and increasing pressure to improve operational efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cheese Powder Market |
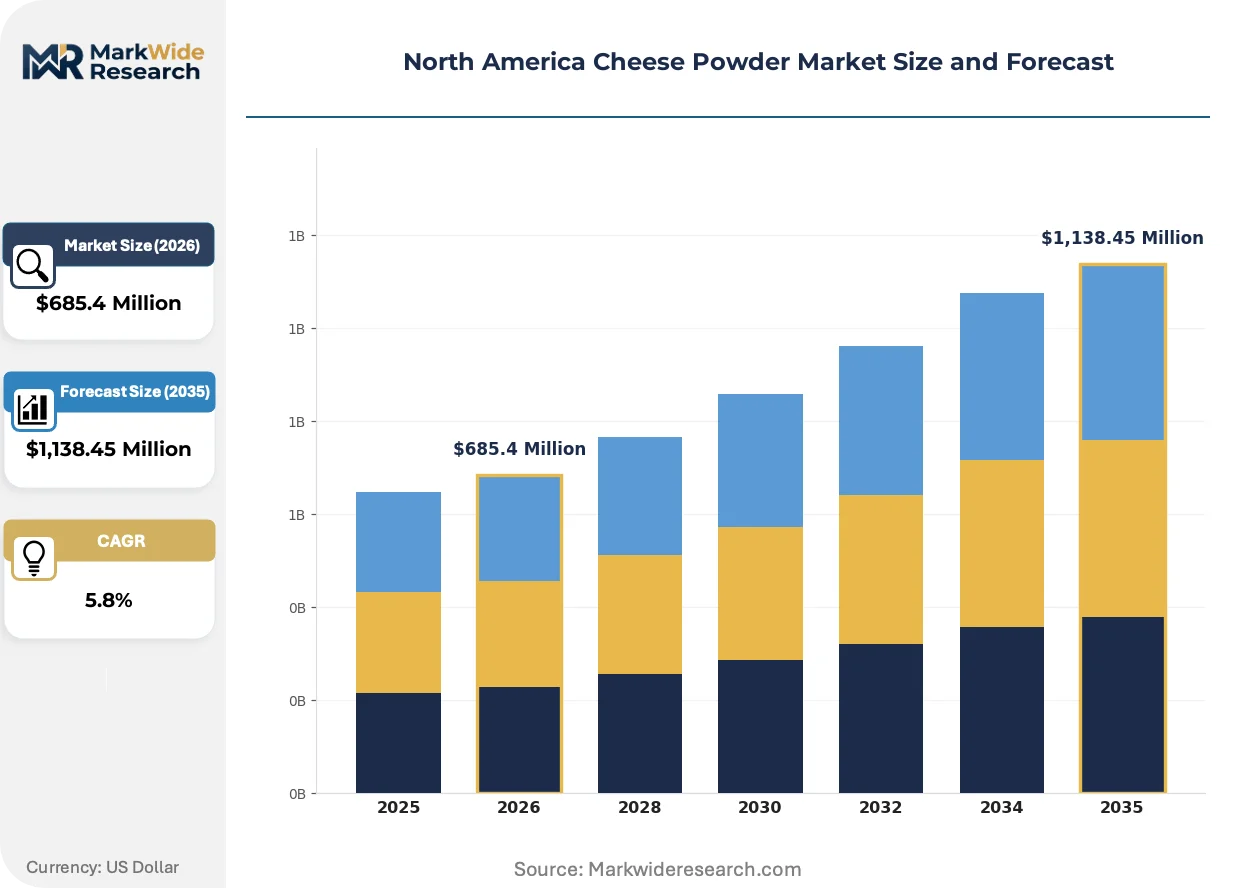
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cheddar, Parmesan, Mozzarella, Swiss, Blue, Asiago Application: Snack Seasoning, Bakery, Sauces, Soups, Ready Meals, Confectionery Packaging Type: Bulk Bags, Sachets, Stand-up Pouches, Jars, Tubs, Drums Customer Type: Food Manufacturers, Catering Services, Foodservice Distributors, Ingredient Suppliers, Institutional Buyers |
| Companies Covered | All American Foods, Cargill, Land O'Lakes, Commercial Creamery Company, Glanbia Foods, Kerry Group, Kraft Heinz Ingredients, Blue Grass Dairy, Dairy Farmers of America, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cheese Powder Market Strategic Shifts & Innovations
Product development in the cheese powder market is shifting focus from basic flavor delivery to advanced functional performance. This evolution is driven by formulators in the prepared foods sector demanding more sophisticated ingredient capabilities and transparent sourcing.
Microencapsulation is a key processing technology that protects volatile flavor compounds within a protective shell. Savory snack and dry soup mix manufacturers are steadily adopting it to guarantee flavor intensity and stability over a product's shelf life. This technology is collapsing the sensory gap between fresh cheese and powdered ingredients, enabling more authentic taste profiles in shelf-stable foods.
Heightened scrutiny from the U.S. Food and Drug Administration on allergen declarations, as mandated by FALCPA, is a primary regulatory driver. This compels ingredient producers to implement stringent cross-contamination protocols and provide detailed sourcing documentation for all dairy-derived components. The ready meal and bakery segments are most impacted, often necessitating dedicated processing equipment to ensure compliance and avoid costly recalls.
A notable behavioral shift is underway as food manufacturers move from sourcing cheese powder as a simple commodity to procuring it as a functional ingredient system. This disrupts the traditional volume-based sales model, favoring suppliers that offer deep application expertise and customization. This trend is most pronounced in the U.S. sauce and dip market, where texture, melt, and color are critical performance criteria.
North America Cheese Powder Market Segmentation
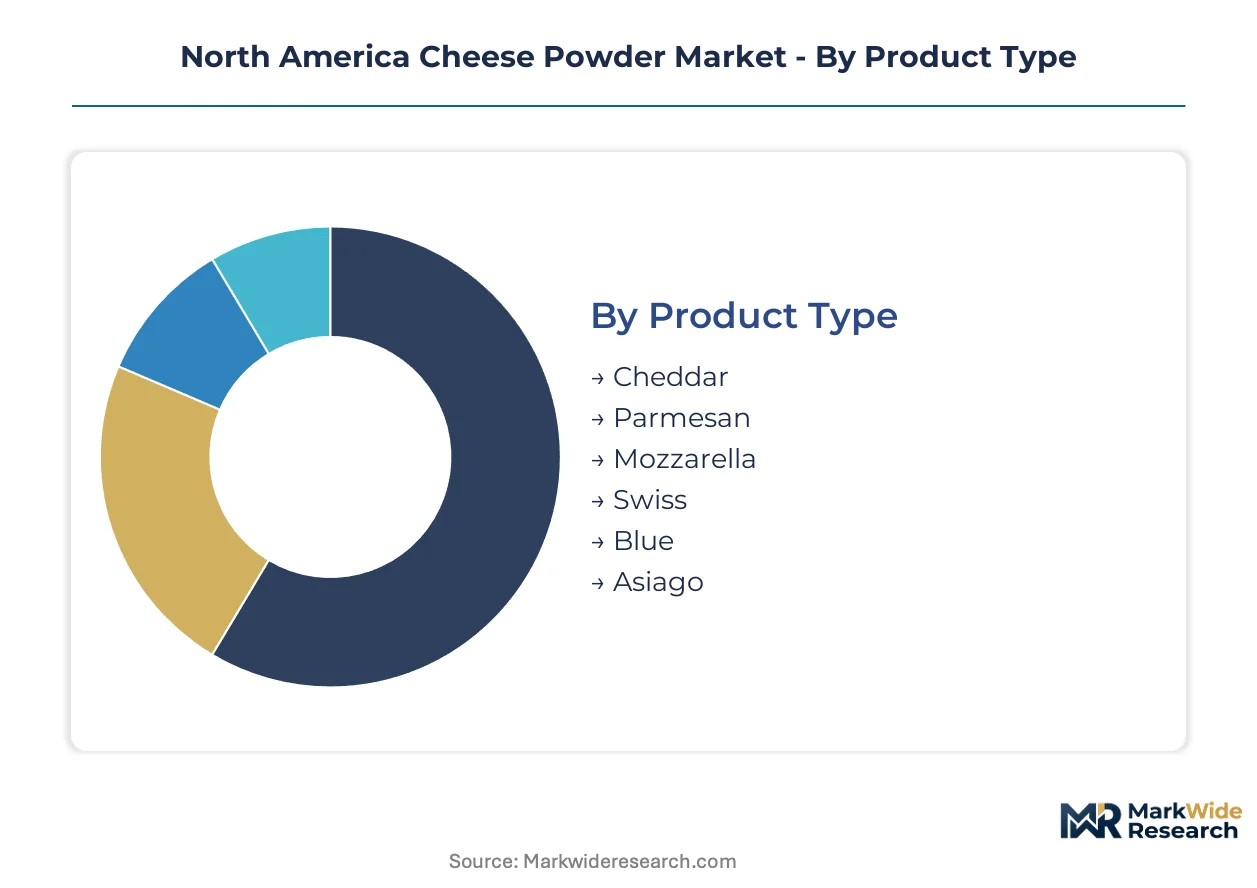
The North America cheese powder market segmentation highlights the diverse product offerings and application requirements that drive ingredient procurement across the region. Understanding these distinct segments allows suppliers to tailor product development and distribution strategies for specific customer needs and market niches in the United States, Canada, and Mexico.
Product Type:
The after-sales service intensity for cheese powders varies significantly by product type, reflecting differing formulation complexities and shelf-life requirements.
- Cheddar:This ubiquitous cheese powder offers a rich, sharp flavor, making it highly versatile. Demand concentrates heavily in snack seasoning across the United States, driven by established preference and cost-effectiveness.
- Blue:Characterized by pungent, earthy notes, blue cheese powder enhances specialty and gourmet products. Its application in high-margin prepared meals reflects evolving consumer preferences for sophisticated taste experiences.
- Parmesan:Offering a distinct nutty and salty flavor, Parmesan powder is widely utilized in Italian-inspired dishes and as a savory topping.
- Mozzarella:Known for its mild flavor and excellent melt, mozzarella powder finds application in frozen pizzas and ready-to-eat meals.
- Swiss:This powder delivers a sweet, nutty flavor, often incorporated into sauces, dips, and bakery items for a unique taste.
- Asiago:With a sharp, piquant flavor, Asiago powder caters to a niche seeking bold and authentic cheese notes in specialty snacks.
By volume, Cheddar leads the market. By growth pace, specialty varieties like Blue and Asiago represent the fastest-growing trajectory.
Application:
Application-specific demands dictate the required functional properties and flavor profiles from cheese powder suppliers, influencing product customization efforts.
- Snack Seasoning:Cheese powders are essential for topical applications on savory snacks, delivering concentrated flavor. Demand from the expanding snack category in the United States provides a consistent volume driver.
- Sauces:In sauce formulations, cheese powders contribute flavor, texture, and melt characteristics, crucial for products like dips. The U.S. dip market frequently requires specific functional performance.
- Bakery:Cheese powders enhance flavor and texture in baked goods, including crackers, breads, and savory pastries.
- Soups:These powders provide creamy texture and rich cheese flavor to instant and ready-to-serve soup mixes.
- Ready Meals:Cheese powders integrate into frozen and chilled ready meals, providing authentic dairy flavor and improving palatability.
- Confectionery:A smaller but growing segment, cheese powders create unique savory flavor combinations in confectionery items.
The largest volume uptake occurs in snack seasoning, while sauces demonstrate significant functional innovation.
Packaging Type:
Customer type preferences and logistical efficiencies heavily influence the selection of packaging types for cheese powder distribution across North America.
- Bulk Bags:Designed for large-scale industrial use, bulk bags facilitate efficient handling and storage of high volumes. Food manufacturers prioritize these for cost-effective procurement.
- Stand-up Pouches:Offering convenience and extended shelf life, stand-up pouches cater to smaller-batch producers and direct-to-consumer channels. E-commerce platforms support their use.
- Sachets:Small, single-serving sachets are common for portion control in ready meals or as seasoning packets.
- Jars:Jars provide a resealable option for retail consumers and smaller foodservice operations, preserving freshness.
- Tubs:Larger tubs are typically used in foodservice settings for easy access and storage of moderate volumes.
- Drums:Drums are employed for bulk transport and storage, particularly for international shipments or very large industrial users.
Industrial-scale procurement primarily utilizes bulk bags, contrasting with stand-up pouches for consumer-facing or small-batch applications.
Customer Type:
Supply concentration within the cheese powder market is often dictated by the purchasing power and specific requirements of different customer types.
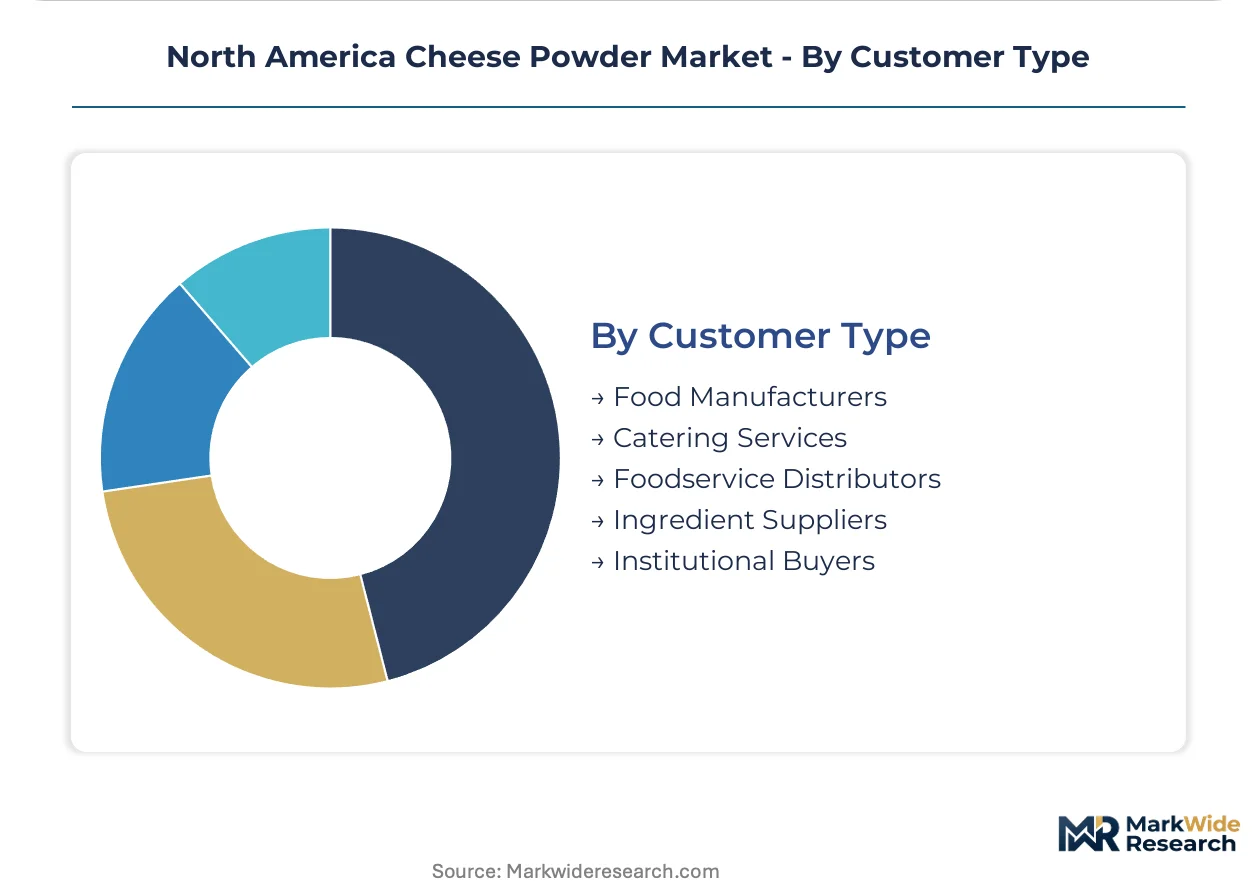
- Food Manufacturers:These customers require consistent quality, specific functional properties, and large volumes for their product lines. Their demand is driven by reliable ingredient supply for mass-produced foods.
- Foodservice Distributors:Acting as intermediaries, these distributors supply a wide range of cheese powders to restaurants and institutional kitchens. Their procurement focuses on product variety and efficient logistics.
- Catering Services:Catering businesses use cheese powders for convenience and flavor consistency in preparing meals for events.
- Ingredient Suppliers:These entities often purchase bulk cheese powder for further processing, blending, or repackaging for specialized markets.
- Institutional Buyers:Organizations like schools, hospitals, and government facilities procure cheese powders for large-scale meal preparation.
The largest direct procurement originates from food manufacturers, while foodservice distributors represent a critical intermediary in supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The extensive cross-border transportation networks, including major highways and rail corridors, underwrite North America's integrated supply chains for food ingredients. This robust infrastructure facilitates efficient movement of raw materials and finished products. Regional trade agreements further streamline ingredient procurement across the three primary markets.
United States
Snack seasoning and ready meal applications drive significant demand for cheese powders in the United States. The U.S. Food and Drug Administration (FDA) enforces strict standards for dairy product identity and allergen declarations. California and Wisconsin's dairy belts serve as key production hubs, supporting large-scale ingredient manufacturing.
Canada
Canadian food manufacturers seek cheese powders for savory snacks and various processed food items. Health Canada's Food and Drug Regulations govern safety and composition requirements for cheese-derived ingredients. Major food processing hubs in Ontario and Quebec concentrate demand for specialized cheese powder blends.
Mexico
Mexico's expanding processed food sector, particularly in sauces and baked goods, offers a substantial geographic market for North American exporters. COFEPRIS, Mexico's health regulatory agency, establishes food safety and labeling guidelines for imported ingredients. The Mexico City and Monterrey metropolitan areas represent growing centers for food manufacturing activity.
North America Cheese Powder Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the North American cheese powder market. The market exhibits a tiered structure with large, diversified food ingredient companies alongside specialized dairy processors. Strategic archetypes include global ingredient providers, regional dairy cooperatives, and flavor system innovators. Portfolio diversification and geographic expansion remain dominant competitive moves across the industry.
Among established ingredient suppliers, Kraft Heinz Ingredients exemplifies a strong market position through brand recognition in both retail and industrial segments. Land O'Lakes, leveraging its extensive dairy cooperative network, anchors the raw material supply chain. Kerry Group represents a specialized flavor systems provider, competing on its wide portfolio of ingredient blends.
| Leading Market Players |
|---|
| All American Foods |
| Cargill |
| Land O'Lakes |
| Commercial Creamery Company |
| Glanbia Foods |
| Kerry Group |
| Kraft Heinz Ingredients |
| Blue Grass Dairy |
| Dairy Farmers of America |
| Others |
Cost & Logistics Intelligence
Commodity volatility in raw milk, the primary feedstock, directly determines both pricing tier spreads and the overall supply chain shape for North American cheese powder. This fundamental input cost impacts all production segments.
Pricing Analysis
Volume-discount tiering structures characterize pricing across the North America cheese powder market. Pricing stratifies across premium, standard, and economy tiers, influenced by quality grade, clean-label certifications, and purchase volume. Pricing softness reflects intense competition from plant-based alternatives and fluctuating raw milk costs. Food manufacturers procuring commodity cheddar for high-volume applications exhibit the highest price sensitivity.
Supply Chain Analysis
Upstream feedstock, primarily raw milk, anchors the North American cheese powder supply chain. Geographic supply concentration centers in the United States and Canada, leveraging extensive dairy infrastructure. Raw material dependencies include specific cheese varieties like cheddar and mozzarella. Commodity price volatility for dairy inputs represents a significant structural risk. Distribution runs through large-scale industrial bulk bags for food manufacturers, with stand-up pouches serving direct-to-artisan channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America cheese powder market presents a fragmentation opportunity. Evolving clean-label and artisanal preferences create distinct niches for specialized product offerings.
For Market Incumbents: Insulate core market share by investing in advanced microencapsulation technologies to enhance flavor stability and authenticity. Expand certified organic and non-GMO product lines to counter the substitution threat from plant-based alternatives. Strengthen quality control and sensory analysis capabilities to maintain consistent flavor profiles, a critical lever against emerging competitors. Pursue strategic partnerships with large CPG firms to secure long-term supply contracts for functional ingredient systems.
For New Entrants and Emerging Players: Build out specialized portfolios targeting the pet food flavoring and direct-to-artisan channels. The specialty powder segment, particularly Asiago and Blue varieties, offers the most penetrable entry point due to higher margins and evolving consumer tastes. A specific go-to-market angle involves leveraging e-commerce platforms to offer niche certifications and single-origin cheese powders directly to small-batch producers. Focus on application expertise for unique functional requirements in these growing segments.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors agile, technology-driven ingredient specialists. Long-term viability is strong, driven by sustained demand for savory snacks and functional food ingredients over the next decade. Acquisition targets should include mid-sized specialty powder producers with proprietary processing technologies or robust clean-label portfolios. The adoption rate of microencapsulated ingredients in mainstream CPG products serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Microencapsulation Capacity | This initiative enhances flavor stability and authenticity, reducing the sensory gap between fresh and powdered cheese. |
| Develop Organic/Non-GMO Product Lines | Catering to clean-label preferences helps capture high-margin niches and mitigates substitution threats from plant-based alternatives. |
| Strengthen Direct-to-Customer Channels | Bypassing traditional distributors allows direct engagement with small-batch producers and artisan food manufacturers. |
| Invest in Pet Food Application R&D | Exploring cheese powder as a palatability enhancer opens a significant new application frontier in premium pet food. |
| Enhance Cross-Border Regulatory Compliance | Navigating distinct FDA and Health Canada standards streamlines trade and reduces compliance costs for ingredient suppliers. |
Research Approach
A spread of perspectives from food manufacturers' R&D leads, ingredient procurement managers, foodservice distributors, and regulatory affairs specialists converged on the working assumptions. This approach combined primary interviews with industry stakeholders and rigorous secondary validation. Secondary data sources included FDA filings, Health Canada Food and Drug Regulations, industry association reports, and specialized trade publications. Bottom-up and top-down triangulation ensured comprehensive data coherence.
Demand-supply-balance framing informed the analytical framework utilized across the projection horizon. Segmentation dimensions modeled included product type, application, packaging type, customer type, and clean-label certification. Compound annual growth rates were derived from historical data analysis and projected market shifts. Key industry-specific forecast inputs included raw milk price trends and evolving consumer preference for savory snacks.
Stress conditions across raw material price volatility and regulatory shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions concerning market stability and technological adoption. Geopolitical trade disruptions or unforeseen dairy supply shocks represent specific risk factors that could revise these forecasts. Cross-checking against national dairy board statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Phytosterols Market
Ingredients
Virgin Coconut Oil Market
Ingredients
Potato Peel Powder Market
Ingredients
Sea Buckthorn Berry Extract Market
Ingredients
Global Infant Nutrition Ingredients Market
Ingredients
Cold Pressed Oil Market
Ingredients
Anhydrous Caffeine Market
Ingredients
Mexico Sodium Reduction Ingredients Market
Ingredients
Meat Extract Market
Ingredients
Thinned Starch Market
Ingredients
Banana Flour Market
Ingredients
Citrus Based Dietary Fibers Market
Ingredients
Europe Amino Acid Market
Ingredients
Marine Collagen Ingredients Market
Ingredients
Bran Market
Ingredients
Dry Blended Products Market