
 Australia Alcohol E-Commerce Market | 2026-2036
Australia Alcohol E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Alcohol E-Commerce Market Insights
Australia is narrowing the fulfillment gap between metropolitan and regional alcohol delivery zones through expanded warehouse networks and localized distribution partnerships. Endeavour Group leverages its integrated retail and digital infrastructure to control last-mile logistics across state capitals. Dan Murphy's anchors online market presence through extensive SKU breadth and competitive pricing architecture. Woolworths competes via grocery ecosystem integration, embedding alcohol purchases within broader household shopping journeys.
Australia alcohol e-commerce denotes the digital retailing and fulfillment of alcoholic beverages through web-based platforms and mobile applications, requiring age-verification protocols, temperature-controlled logistics, and compliance with state-based liquor licensing regimes. The primary commercial purpose centers on expanding consumer access beyond traditional bottle shop footprints while reducing friction in repeat purchasing behavior. Wine dominates product type revenue contribution due to higher per-unit margins and established direct-to-producer relationships, though spirits is accelerating fastest among younger demographics seeking curated discovery experiences. Subscription services within delivery mode capture recurring revenue pools and reduce customer acquisition costs relative to on-demand alternatives.
TGA guidelines intersect with state liquor regulators including NSW Liquor and Gaming, Liquor Control Victoria, and the Western Australian Department of Local Government, Sport and Cultural Industries to govern labeling standards, promotional restrictions, and delivery hour limitations. The Australian Competition and Consumer Commission monitors platform pricing transparency and subscription cancellation practices. Stakeholders must track evolving state-level delivery law harmonization and platform fee regulation to anticipate margin compression or operational expansion pathways.
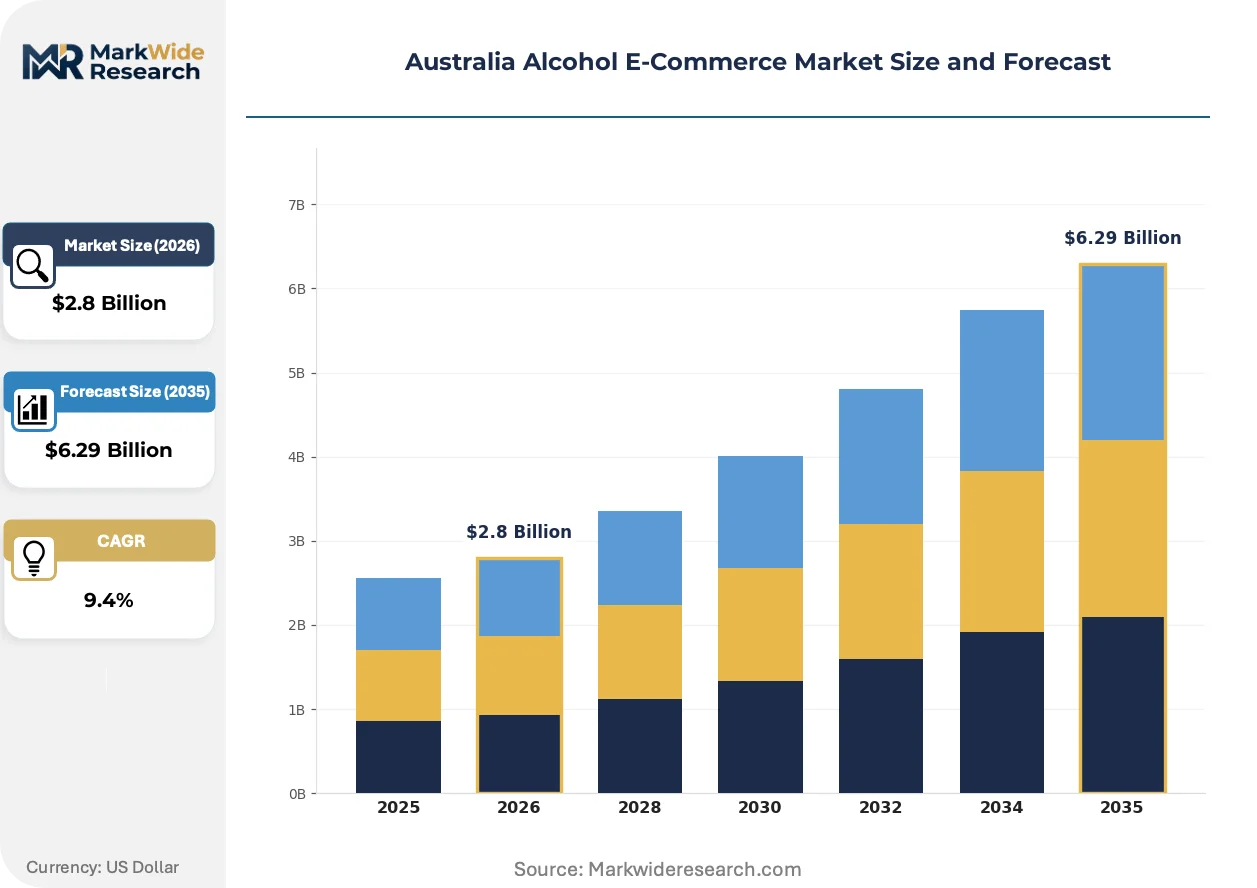
Market Dynamics
State-level liquor licensing harmonization is compressing delivery windows and flattening compliance costs across Australian jurisdictions, enabling platform operators to consolidate warehouse networks previously fragmented by regulatory arbitrage.
Growth Catalysts
- Direct-to-consumer shipping reforms:TGA alignment with state liquor regulators streamlines interstate fulfillment, reducing permit duplication for online retailers.
- Temperature-controlled logistics investment:Cold-chain infrastructure expansion in Sydney and Melbourne metro corridors protects wine quality during last-mile delivery.
- Subscription service adoption:Young urban professionals in capital cities lock in recurring revenue through curated discovery models, lowering customer acquisition costs relative to on-demand alternatives.
Market Restraints
- Delivery hour limitations:NSW Liquor and Gaming restrictions on late-night alcohol dispatch compress order windows and limit same-day fulfillment velocity.
- Regional fulfillment cost premiums:Sparse warehouse density outside state capitals forces platforms to absorb elevated last-mile costs or pass them to consumers.
- Promotional restrictions:Australian Competition and Consumer Commission scrutiny of subscription cancellation practices constrains aggressive customer acquisition tactics.
Strategic Opportunities
- Regional zone penetration:Expanded distribution partnerships in Queensland and Western Australia unlock underpenetrated markets beyond Sydney-Melbourne concentration.
- Spirits curation platforms:Younger demographics seeking discovery experiences drive demand for personalized recommendation engines and limited-release access.
- Grocery ecosystem embedding:Alcohol purchases integrated within broader household shopping journeys capture incremental basket share through convenience bundling.
Industry Challenges
- Age-verification protocol standardization:Inconsistent digital ID acceptance across state borders forces platforms to maintain redundant compliance systems.
- SKU breadth complexity:Dan Murphy's extensive catalog requirements strain inventory management systems and warehouse slotting efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Alcohol E-Commerce Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beer, Wine, Spirits, Cider Delivery Mode: Home Delivery, Click and Collect, Subscription Services, On-Demand Payment Method: Credit Card, PayPal, Digital Wallet, Bank Transfer Customer Type: Retail Consumers, Corporate Clients, Event Planners, Hospitality Sector |
| Companies Covered | Endeavour Group, Dan Murphy's, Woolworths, Coles Group, BWS, Liquorland, Bottle Stop, DoorDash, Vinomofo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Alcohol E-Commerce Market Trends and Innovations
Digital identity verification and predictive demand modeling are collapsing friction points in the Australian alcohol e-commerce value chain, reshaping how platforms acquire, retain, and fulfill orders across state jurisdictions.
Blockchain-enabled provenance tracking is collapsing information asymmetry between wine producers and end consumers. Boutique vineyards in Barossa Valley and Margaret River embed harvest-to-door traceability to command premium positioning. Young urban professionals verify origin claims instantly, compressing trust-building cycles that previously required physical cellar door visits.
Liquor Control Victoria's pilot program for extended delivery windows in metropolitan zones signals regulatory adaptation to platform economics. The reform permits evening dispatch slots previously restricted by legacy licensing frameworks. Melbourne-based operators are expanding fleet capacity to capture this incremental demand window before interstate competitors replicate the model.
Curated subscription boxes displace spontaneous on-demand purchasing among younger demographics seeking guided discovery. Spirits-focused platforms replace supermarket browsing with algorithmic personalization and limited-release access. Sydney and Melbourne corridors exhibit the highest subscription density, though regional adoption lags due to delivery frequency constraints and perceived value thresholds.
Australia Alcohol E-Commerce Market Segmentation
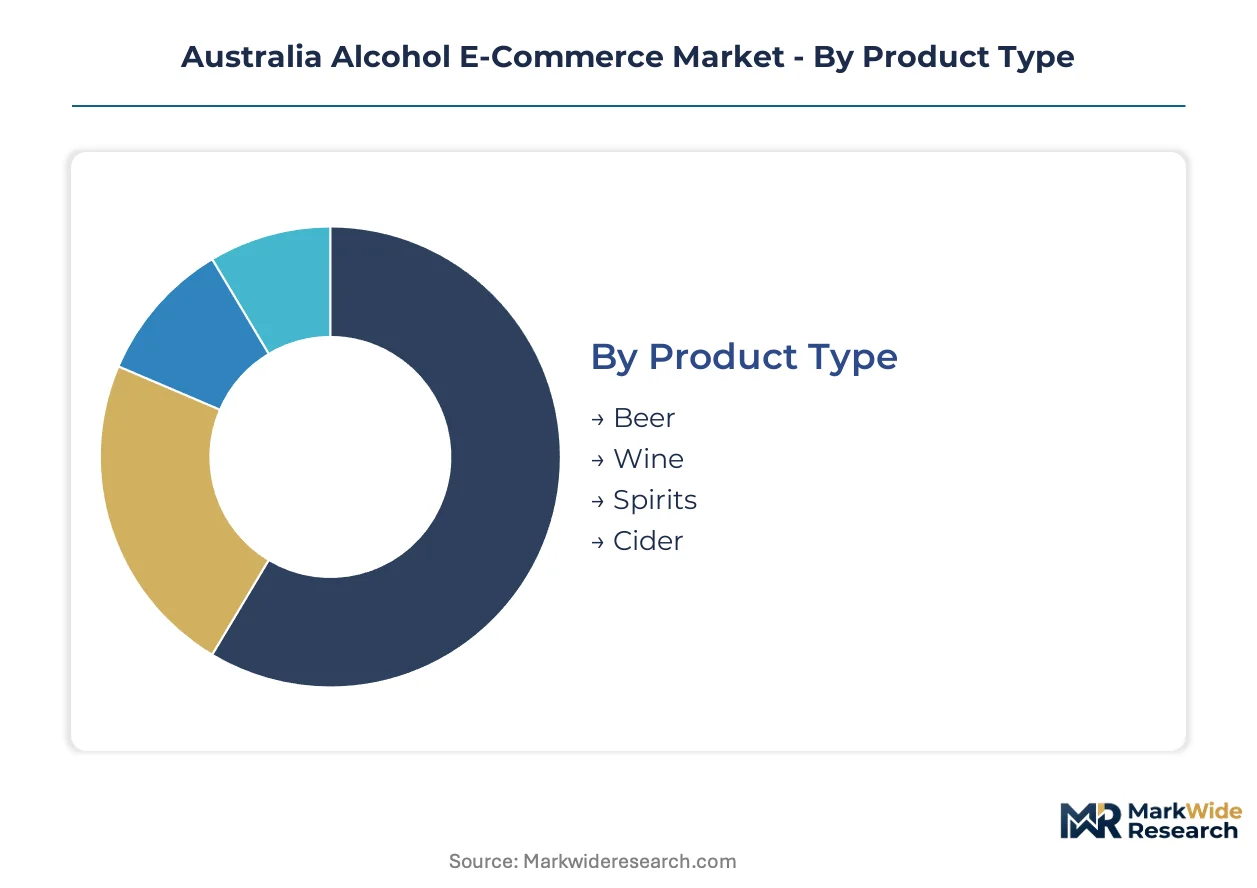
Australia alcohol e-commerce segmentation reveals how platform operators allocate fulfillment infrastructure and marketing spend across distinct consumption occasions and purchasing behaviors. Category boundaries determine warehouse slotting priorities, delivery fleet composition, and age-verification protocol intensity.
Product Type:
Cost tier differentiation across beverage categories shapes margin architecture and supplier relationship structures for Australian digital alcohol retailers.
- Wine:Higher per-unit margins and established direct-to-producer relationships anchor revenue contribution. Demand concentrates in Sydney and Melbourne metro corridors where temperature-controlled last-mile logistics protect quality during transit. Direct vineyard partnerships in Barossa Valley and Margaret River compress distribution layers.
- Spirits:Curated discovery experiences and limited-release access accelerate adoption among younger demographics seeking personalized recommendation engines. Urban professionals in capital cities drive subscription attachment for premium whiskey and gin categories.
- Beer:Volume-driven replenishment patterns dominate with lower per-cart values and higher frequency purchasing. Cold-chain requirements strain warehouse slotting efficiency during summer demand peaks.
- Cider:Seasonal consumption spikes align with warmer months and outdoor event calendars. Regional Victorian and Tasmanian producers leverage direct shipping reforms to bypass traditional wholesale channels.
Wine holds installed capacity. Spirits is rotating up the share rankings.
Delivery Mode:
Application context determines fulfillment velocity requirements and customer acquisition economics for platform operators competing across Australian state jurisdictions.
- Subscription Services:Recurring revenue pools reduce customer acquisition costs relative to on-demand alternatives through locked-in purchasing commitments. Young urban professionals in Sydney and Melbourne corridors exhibit highest density, though regional adoption lags due to delivery frequency constraints.
- Home Delivery:Standard dispatch windows accommodate planned consumption occasions with consolidated route optimization. Temperature-controlled logistics investment in metro corridors protects wine quality during extended transit times.
- Click and Collect:Hybrid fulfillment merges digital browsing efficiency with physical pickup convenience, capturing consumers prioritizing cost savings over immediacy.
- On-Demand:Compressed delivery windows serve impulse purchasing and immediate consumption needs. Late-night dispatch restrictions under NSW Liquor and Gaming regulations compress order windows and limit velocity.
Subscription Services holds installed capacity. On-Demand is rotating up the share rankings.
Payment Method:
Customer type and transaction value thresholds influence payment infrastructure investment and fraud prevention protocol layering across Australian alcohol e-commerce platforms.
- Credit Card:Dominant transaction rail for high-value wine purchases and subscription commitments, with integrated age-verification checks at authorization stage.
- Digital Wallet:Accelerating adoption among younger demographics seeking frictionless checkout experiences on mobile-optimized platforms.
- PayPal:Trusted intermediary for first-time purchasers hesitant to share direct financial credentials with unfamiliar alcohol retailers.
- Bank Transfer:Preferred for bulk corporate orders and event planner accounts requiring invoice-based reconciliation workflows.
Credit Card holds installed capacity. Digital Wallet is rotating up the share rankings.
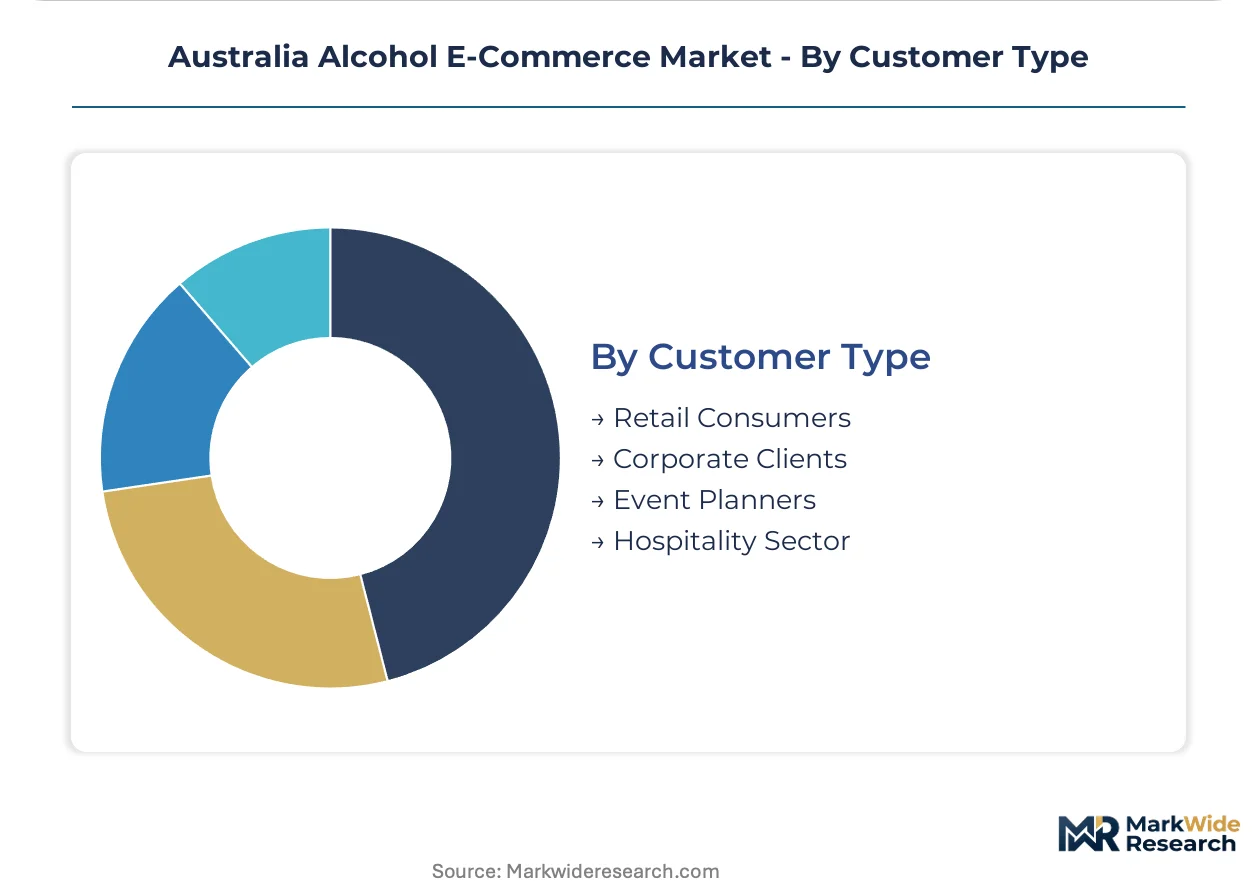
Customer Type:
Volume concentration and purchasing frequency patterns determine platform customization depth and account management resource allocation.
- Retail Consumers:Individual purchasers drive the majority of transaction volume through mixed basket behaviors spanning planned and impulse occasions. Grocery ecosystem embedding captures incremental share through convenience bundling with broader household shopping journeys.
- Hospitality Sector:Licensed venues require compliant invoicing, extended payment terms, and consistent supply reliability for menu continuity. Demand concentrates in Sydney and Melbourne metropolitan zones with dense restaurant and bar concentrations.
- Corporate Clients:Bulk gifting and office consumption programs require customized labeling and scheduled delivery coordination across multiple recipient addresses.
- Event Planners:Spike-driven demand patterns around wedding seasons and corporate calendar peaks strain inventory forecasting accuracy and temporary fulfillment capacity.
Retail Consumers holds installed capacity. Hospitality Sector is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Warehouse networks cluster along the eastern seaboard where population density and cold-chain infrastructure intersect. Interstate fulfillment corridors concentrate investment in temperature-controlled logistics that protect wine quality during transit.
New South Wales
Sydney metro corridors generate the highest order velocity through subscription service adoption among young urban professionals. NSW Liquor and Gaming regulations restrict late-night dispatch windows, compressing same-day fulfillment capacity. Barossa Valley producers leverage direct-to-consumer shipping reforms to bypass traditional wholesale layers.
Victoria
Melbourne's dense restaurant and bar concentration drives hospitality sector procurement through compliant invoicing platforms. Liquor Control Victoria's pilot program for extended evening delivery windows permits dispatch slots previously restricted by legacy frameworks. Inner-northern suburbs exhibit the highest subscription density for curated spirits discovery.
Queensland
Brisbane and Gold Coast corridors show accelerating demand for on-demand delivery among tourism-adjacent consumption occasions. State liquor licensing harmonization reduces permit duplication costs for interstate platform operators. Sunshine Coast warehouse partnerships remain underdeveloped relative to southern capitals.
Western Australia
Perth's geographic isolation forces elevated last-mile cost absorption or consumer price premiums. The Western Australian Department of Local Government, Sport and Cultural Industries governs delivery hour limitations that align with eastern state frameworks. Margaret River vineyards exploit direct shipping reforms to establish cellar door bypass channels.
South Australia
Adelaide's wine production proximity enables same-day fulfillment from consolidated distribution nodes. State-level licensing alignment with TGA guidelines streamlines interstate permit recognition. Fleurieu Peninsula producers embed blockchain-enabled provenance tracking to command premium positioning through harvest-to-door traceability.
Australia Alcohol E-Commerce Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fulfillment infrastructure and age-verification technology. The market structure tilts toward consolidated retail ecosystems that embed alcohol within broader grocery purchasing journeys. Three archetypes dominate: integrated retail-digital hybrids, pure-play subscription curators, and on-demand delivery aggregators. Competitive moves center on warehouse network expansion and subscription retention mechanics.
Among integrated retail-digital hybrids, Endeavour Group and Dan Murphy's exemplify the platform tier through control of last-mile logistics and extensive SKU breadth. Woolworths anchors grocery ecosystem embedding that captures incremental basket share through convenience bundling. These three occupy positions where digital infrastructure and physical retail footprints intersect, representing the dominant competitive formation in Australian alcohol e-commerce.
| Leading Market Players |
|---|
| Endeavour Group |
| Dan Murphy's |
| Woolworths |
| Coles Group |
| BWS |
| Liquorland |
| Bottle Stop |
| DoorDash |
| Vinomofo |
| Others |
Pricing and Supply Chain Analysis
Warehouse concentration in Sydney and Melbourne metro corridors concentrates margin capture with integrated retail-digital hybrids controlling last-mile temperature-controlled logistics. Cold-chain infrastructure investment barriers protect incumbent pricing power while forcing smaller operators toward subscription models or regional cost premiums.
Pricing Analysis
TGA alignment with state liquor regulators dictates the pricing tier structure across direct-to-consumer channels. Three-tier pricing structure across premium, standard, and economy levels separates curated vineyard partnerships from mass-market supermarket integration and on-demand aggregator markups. Price differentiation hinges on delivery velocity and provenance verification, with subscription services capturing least price-sensitive young urban professionals seeking discovery experiences. Cost compression in on-demand tiers intensifies because DoorDash and similar aggregators absorb regulatory compliance overhead without grocery ecosystem cross-subsidies.
Supply Chain Analysis
Tariff exposure between Australia and New Zealand dominates cross-Tasman wine logistics, though domestic fulfillment networks face greater structural pressure from regional warehouse density gaps. Distribution runs through Endeavour Group's consolidated nodes in Sydney, Melbourne, and Brisbane, with sparse Sunshine Coast partnerships forcing elevated last-mile costs. Raw material dependencies center on Barossa Valley and Margaret River grape supply, glass bottle manufacturing from China, and temperature-controlled packaging from Southeast Asia. Single-source vulnerability concentrates in cold-chain fleet capacity during summer demand peaks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
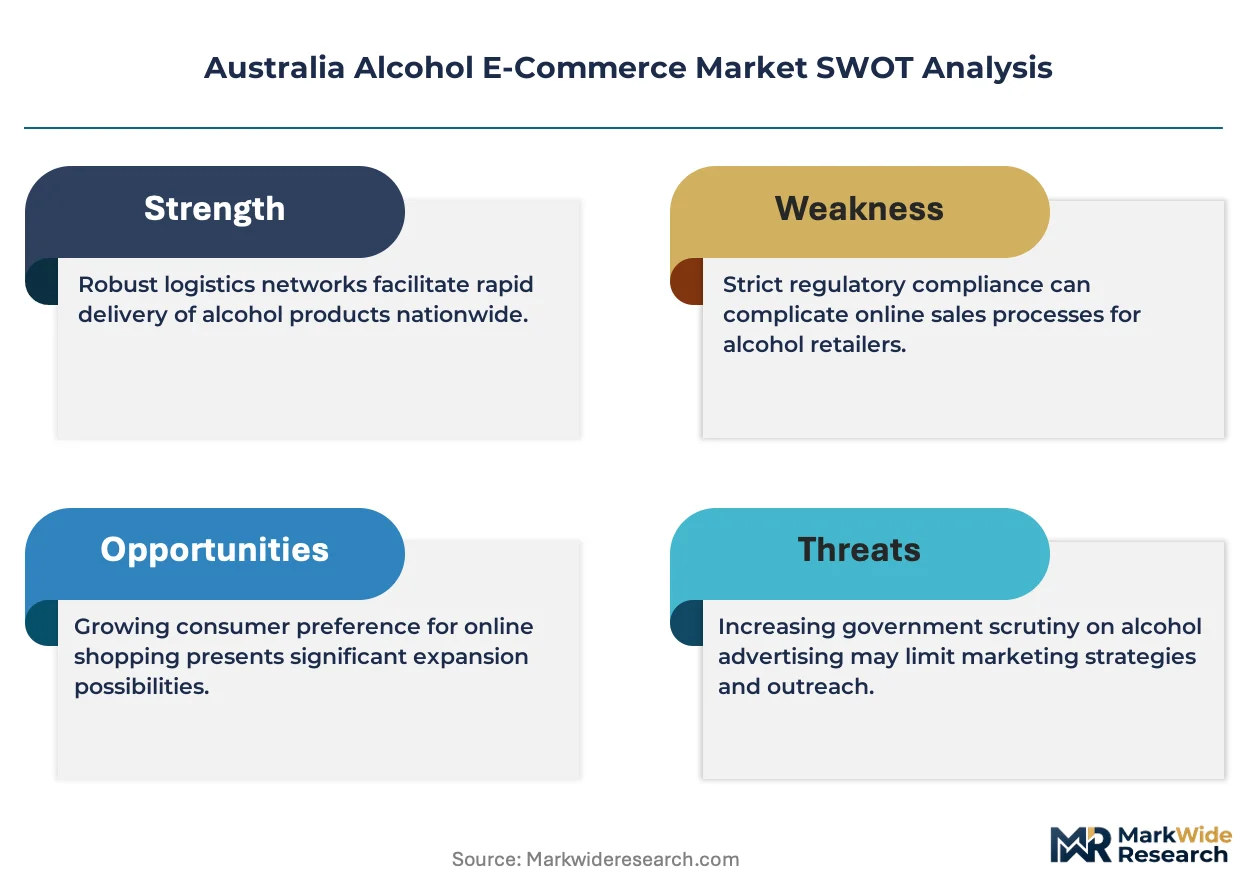
Australian alcohol e-commerce operates as a regulatory moat story where TGA and state liquor licensing entrenchment creates switching costs for consumers locked into verified age-authentication protocols and subscription discovery models.
For Market Incumbents: Build data network effects through predictive demand modeling that collapses inventory forecasting accuracy for curated subscription boxes. Deepen backward integration into Margaret River and Barossa Valley vineyard partnerships to secure limited-release allocation rights before spirits curation platforms scale. Threats concentrate in DoorDash's on-demand velocity and Vinomofo's demographic capture among younger discovery-seeking professionals. Leverage grocery ecosystem embedding at Woolworths and Coles to cross-subsidize alcohol logistics within broader household shopping journeys.
For New Entrants and Emerging Players: Establish a beachhead in Queensland's underdeveloped Sunshine Coast warehouse partnerships where incumbent cold-chain density lags southern capitals. Target hospitality sector procurement in Melbourne's dense restaurant corridors through compliant invoicing platforms that Endeavour Group's retail focus underweights. White-space sits in spirits curation for regional Victorian and Tasmanian cider producers leveraging direct shipping reforms to bypass wholesale layers. Go-to-market angle: algorithmic personalization for limited-release whiskey and gin discovery among inner-northern Melbourne suburbs.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed subscription curators possessing demonstrated retention mechanics but constrained warehouse network scale. Long-term viability favors platforms integrating age-verification technology with temperature-controlled logistics infrastructure across the analysis window. Acquisition target archetype: mid-cap spirits discovery platforms with 12-18 month runway to profitability and established Barossa Valley supplier relationships. Signal to watch: Liquor Control Victoria's extended delivery window pilot expansion into regional zones as regulatory adaptation indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Temperature-controlled warehouse investment in Brisbane and Perth protects wine quality during interstate transit. |
| Direct-to-Consumer Shipping Compliance | TGA alignment with state liquor regulators streamlines permit recognition across NSW, Victoria, and Western Australia. |
| Subscription Retention Technology | Predictive demand modeling for curated discovery boxes reduces customer acquisition costs relative to on-demand alternatives. |
| Blockchain Provenance Tracking | Harvest-to-door traceability embedded by Fleurieu Peninsula producers commands premium positioning through instant origin verification. |
| Grocery Ecosystem Integration | Alcohol purchases bundled within Woolworths household shopping journeys capture incremental basket share through convenience. |
Research Methodology
A spread of perspectives from platform operations directors, state liquor licensing compliance officers, vineyard supply chain managers, and cold-chain logistics providers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against TGA guideline publications, NSW Liquor and Gaming regulatory filings, and ACCC subscription practice disclosures. Customs records, temperature-controlled fleet capacity databases, and grocery ecosystem transaction data anchored bottom-up segmentation modeling. Top-down triangulation against Australian Bureau of Statistics alcohol retail trends ensured consistency across metropolitan and regional demand patterns.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, payment method, and customer type, with regional regulatory cluster and temperature-control requirement tier as industry-specific overlays. CAGRs derived from logistic adoption curves for subscription services and linear extrapolation for on-demand velocity, calibrated against historical platform growth trajectories. Forecast inputs incorporated Liquor Control Victoria pilot program expansion scenarios and direct-to-consumer shipping reform implementation timelines across state jurisdictions.
Sensitivities concentrate around state-level delivery hour harmonization pace, cold-chain fleet capacity expansion timing, and subscription cancellation regulation tightening. Forecasts reflect assumptions on regulatory adaptation velocity and consumer retention mechanics without claiming predictive certainty. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Global Red Wine Market
Alcoholic Beverages
South America Fermented Drinks Market
Alcoholic Beverages
Wine Fermentation Equipment Market
Alcoholic Beverages
Flavored Whiskey Market
Alcoholic Beverages
Grain Alcohol Market
Alcoholic Beverages
Fruit Beer Market
Alcoholic Beverages
US Wine Market
Alcoholic Beverages
Wine Destemmer Market
Alcoholic Beverages
CBD Wine Market
Alcoholic Beverages
RTD Cocktails Market
Alcoholic Beverages
Black Beer Market
Alcoholic Beverages
Japanese Whisky Market
Alcoholic Beverages
Italy Alcohol E-Commerce Market
Alcoholic Beverages
Asia-Pacific Kegs Market
Alcoholic Beverages
Australia and New Zealand Tequila Market
Alcoholic Beverages
Organic Alcoholic Beverages Market