
 Alcohol-Free Pineapple Beer Market | 2026-2036
Alcohol-Free Pineapple Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Alcohol-Free Pineapple Beer Market Insights
The capital-intensity divergence between multinational brewers and craft specialists is rotating competitive dynamics across the category. Heineken N.V. leverages its global brewing infrastructure to achieve scale economics in alcohol-free fermentation, while Athletic Brewing Company anchors its position through dedicated non-alcoholic production facilities and premium positioning. Budweiser competes on mainstream distribution density, particularly in North American retail channels where shelf-space agreements determine visibility.
Alcohol-free pineapple beer denotes a malt-based or fermented beverage containing less than 0.5% alcohol by volume, infused with pineapple-derived flavor compounds through cold-extraction or natural essence infusion, then carbonated to achieve standard beer mouthfeel and head retention. The product serves consumers seeking sensory complexity and social ritual without ethanol consumption, bridging functional beverage and craft beer categories. Craft Beer occupies the highest margin tier within product type segmentation, commanding premium pricing through small-batch positioning and ingredient transparency, while Lagers dominate volume throughput in conventional retail. Supermarkets and Online Retail channels are expanding fastest, displacing traditional on-premise consumption as home-based trial and subscription models gain traction among Health-Conscious Consumers and Athletes.
FDA labeling requirements for non-alcoholic beverages and the EU's Food Information to Consumers Regulation govern alcohol-content thresholds, ingredient declarations, and health-claim permissibility across the category's primary markets. Germany's BfR and the UK's Food Standards Agency enforce additional scrutiny on novel flavoring substances and fermentation byproducts, creating compliance layers that favor established players with regulatory affairs capacity. Stakeholders must monitor evolving low-alcohol taxonomies and cross-border e-commerce duty structures, as classification ambiguities threaten margin structures in emerging distribution channels.
Market Dynamics
EU labeling harmonization under the Food Information to Consumers Regulation is compressing formulation timelines and forcing breweries to rebuild supply chains around certified flavor houses and third-party analytical labs.
Growth Catalysts
- Health-Conscious Consumer Migration:Millennials and Gen Z in Germany and the United Kingdom are substituting alcohol-free tropical beverages for traditional beer in social settings, expanding addressable occasions beyond conventional consumption windows.
- REACH-Compliant Flavor Innovation:ECHA-approved natural pineapple extracts and cold-extraction technologies are enabling clean-label positioning that satisfies both EU Novel Food scrutiny and retailer sustainability scorecards.
- Craft Beverage Infrastructure:Dedicated non-alcoholic fermentation facilities in the United States are reducing cross-contamination risks and unlocking premium positioning previously reserved for alcoholic craft products.
Market Restraints
- Malt Supply Concentration:Specialty low-protein malts required for alcohol-free fermentation concentrate among German and Dutch suppliers, exposing margin structures to input bottlenecks.
- Flavor Stability Limitations:Pineapple-derived volatile compounds degrade rapidly in aqueous matrices, constraining shelf-life claims and forcing refrigerated distribution in ambient-dominant channels.
- Cross-Border Classification Friction:Germany's BfR and the Netherlands' NVWA apply divergent thresholds for fermentation byproduct reporting, fragmenting compliance costs across adjacent markets.
Strategic Opportunities
- Subscription Channel Penetration:Direct-to-consumer models in the United States are capturing repeat purchase data that enables flavor personalization and predictive inventory positioning.
- Athlete-Specific Positioning:Sports nutrition retailers in the United Kingdom are creating dedicated alcohol-free beverage sections that bypass conventional beer aisle competition entirely.
- EU Green Deal Packaging Incentives:Member state deposit-return schemes and recycled-content mandates are favoring breweries with in-house canning lines and regional sourcing certifications.
Industry Challenges
- Analytical Chemistry Talent Scarcity:Breweries lack in-house capability to validate sub-0.5% ABV claims under evolving BfR testing protocols, forcing reliance on third-party labs with extended turnaround times.
- Cold Chain Reconfiguration Costs:Flavor preservation requirements demand refrigerated transport assets that conflict with existing ambient beer distribution networks, requiring parallel logistics investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alcohol-Free Pineapple Beer Market |
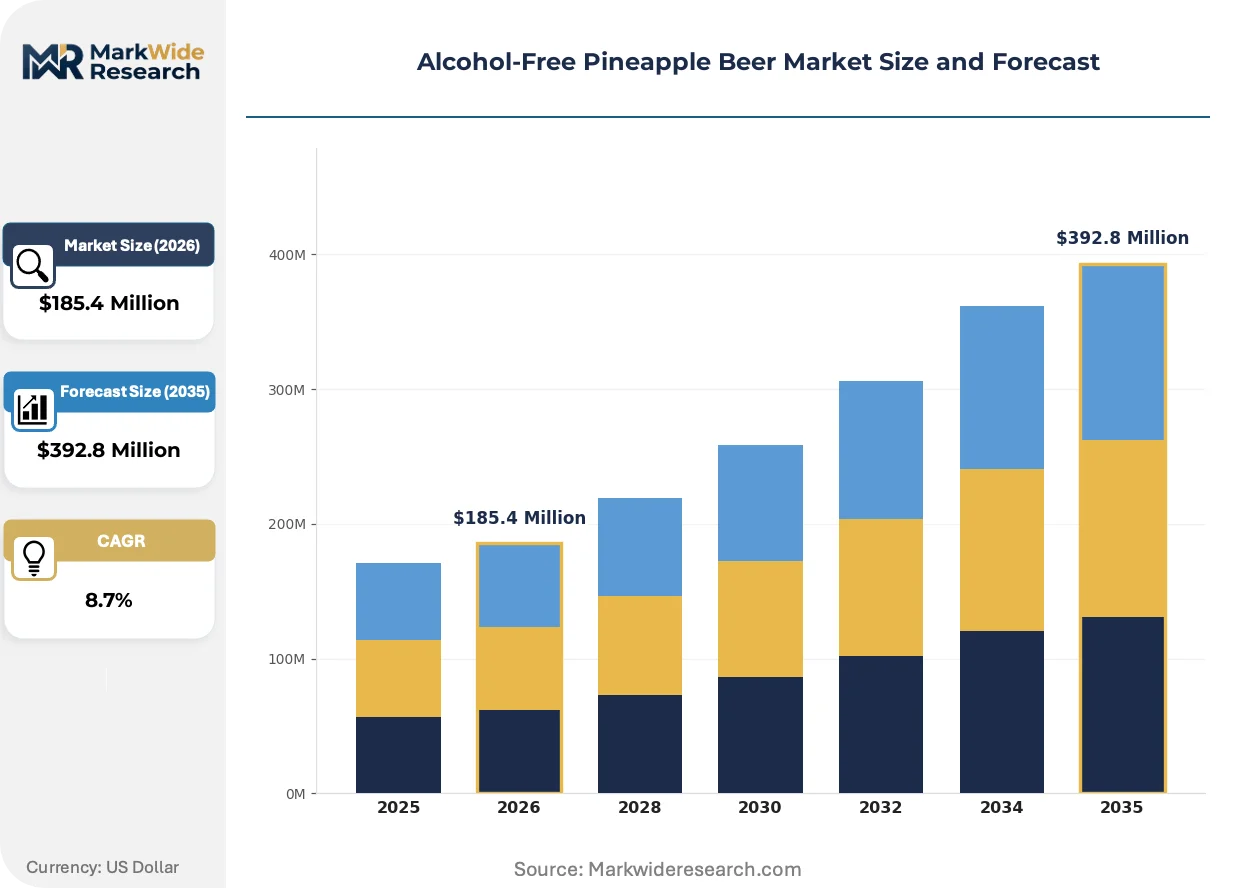
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $392.8 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Craft Beer, Lagers, Ales, Stouts Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Bars Customer Type: Health-Conscious Consumers, Non-Drinkers, Vegans, Athletes Packaging Type: Cans, Bottles, Kegs, Tetra Packs |
| Companies Covered | PEARL RIVER, QINGYI, Budweiser, Tsingtao, San Miguel Brewery, Heineken N.V., Anheuser-Busch InBev, Carlsberg Group, Athletic Brewing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alcohol-Free Pineapple Beer Market Trends and Innovations
Cold-extraction and essence-infusion technologies are fragmenting production methodologies, while regulatory precision around low-alcohol taxonomies forces simultaneous investment in compliance infrastructure and consumer education.
Controlled-atmosphere cold extraction is bifurcating the ingredient sourcing landscape. This technology preserves terpene profiles that heat-based methods destroy, enabling sensory parity with alcoholic craft equivalents. Premium-positioned breweries in Germany and the United States are adopting these systems at accelerated capital deployment cycles. The technology is bifurcating supplier tiers between certified flavor houses with analytical capabilities and commodity extract providers facing exclusion from retailer-approved vendor lists.
The EU's Food Information to Consumers Regulation is tightening declaration requirements for fermented beverages with flavor additions. Industrial consequence includes mandatory quantified ingredient listing and prohibited health claims that previously supported functional positioning. German and Dutch producers are most affected, responding with reformulated base beers that reduce additive dependency and simplify label architectures.
Home-based trial behavior is displacing on-premise discovery as the primary adoption pathway. Supermarkets and online retail channels are capturing occasion migration from bars and restaurants, particularly among health-conscious consumers seeking pantry-stocking convenience. This shift is most visible in the United Kingdom and Spain, where subscription services and curated variety packs now dominate initial brand exposure.
Alcohol-Free Pineapple Beer Market Segmentation
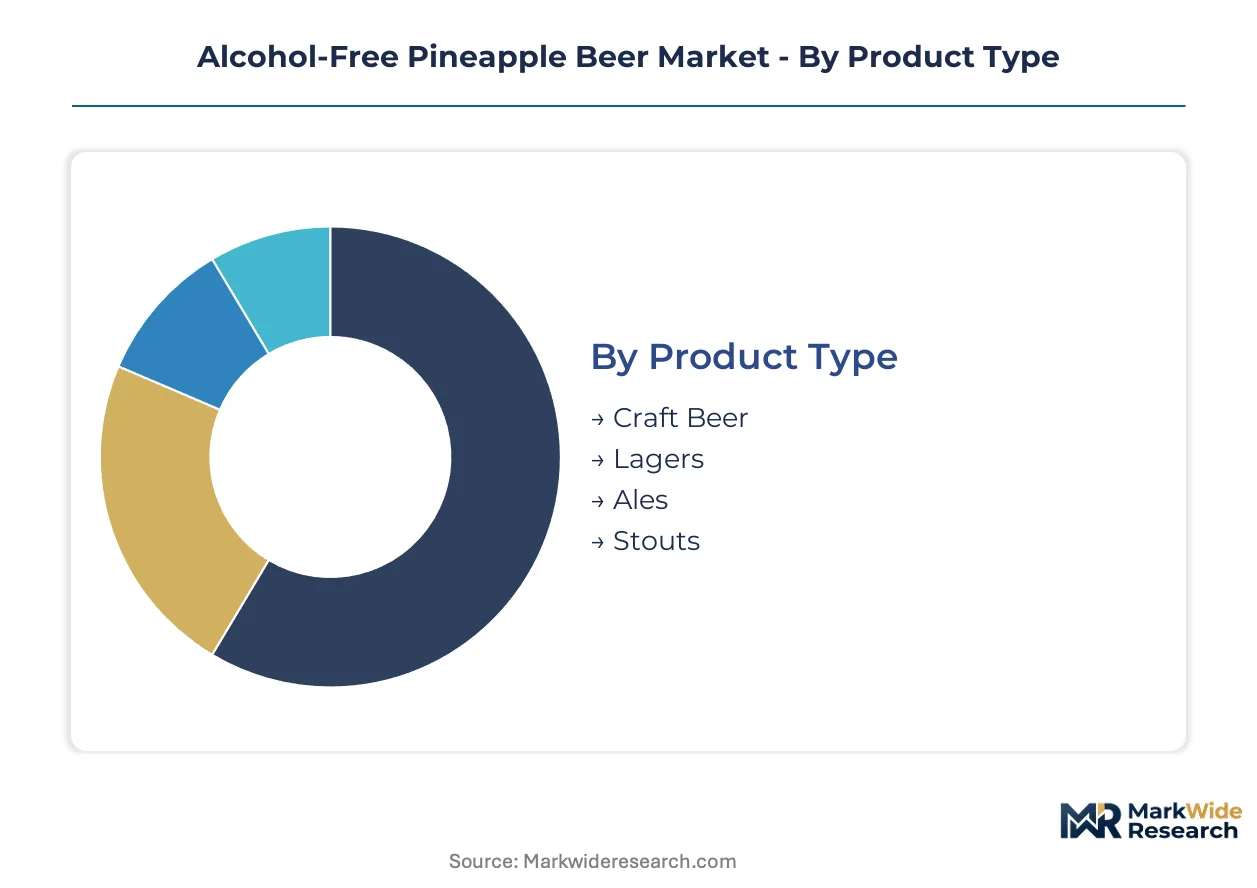
Segmentation in alcohol-free pineapple beer reveals how formulation choices, channel access, and consumer identity intersect to determine pricing power and loyalty patterns. Breweries calibrate production investments against these divides to optimize margin capture across divergent consumption occasions.
Product Type:
Craft Beer faces the most acute substitution pressure from premium mixers and functional beverages, while Lagers compete directly with mass-market soft drinks and mainstream non-alcoholic beer alternatives.
- Craft Beer:Small-batch production using specialty malts and cold-extracted pineapple essences achieves sensory complexity comparable to alcoholic craft equivalents. Demand concentrates in Germany and the United States among millennials seeking social ritual without ethanol, though premium pricing limits volume penetration.
- Lagers:Industrial-scale fermentation of low-protein malt bases produces consistent sub-0.5% ABV products with standardized flavor profiles. Volume concentrates in United Kingdom and Spanish supermarkets where price-sensitive trial drives repeat purchase.
- Ales:Top-fermented variants with fruit-forward aromatic profiles serve niche consumers seeking fuller mouthfeel than Lagers deliver.
- Stouts:Dark-roasted malt bases with pineapple accent notes occupy limited shelf space in specialty retailers targeting experimental flavor seekers.
Lagers anchors the volume base while Craft Beer gains share at the steepest rate.
Distribution Channel:
Channel selection determines temperature control requirements and margin retention, with cold-chain dependencies creating divergent capital intensity across routes to market.
- Supermarkets:Ambient and refrigerated aisle placement in Tesco, Carrefour, and Albert Heijn chains drives mass-market discovery. United Kingdom and German retailers are expanding dedicated alcohol-free sections that bypass conventional beer aisle competition.
- Online Retail:Direct-to-consumer and third-party platforms capture subscription-driven repeat purchases with predictive inventory positioning. United States platforms leverage consumer data for flavor personalization and curated variety packs.
- Specialty Stores:Health food and craft beverage boutiques provide education-intensive environments for premium positioning.
- Bars:On-premise trial occasions are contracting as home-based consumption displaces social discovery in Germany and Spain.
Supermarkets anchors the volume base while Online Retail expands most quickly.
Customer Type:
Identity-based positioning determines permissible health claims and permissible marketing channels under EU and FDA regulations.
- Health-Conscious Consumers:Calorie-aware millennials and Gen Z in Germany and United Kingdom substitute alcohol-free pineapple beer for traditional beer in social settings, expanding addressable occasions beyond conventional consumption windows.
- Athletes:Sports nutrition positioning targets post-workout hydration and electrolyte recovery narratives in United Kingdom specialty retailers, creating dedicated shelf space that bypasses conventional beer aisle competition.
- Non-Drinkers:Permanent abstainers from alcohol seek sensory complexity and social inclusion without ethanol consumption.
- Vegans:Plant-based certification requirements influence fining agent selection and labeling declarations in EU markets.
Health-Conscious Consumers anchors the volume base while Athletes climbs the fastest.
Packaging Type:
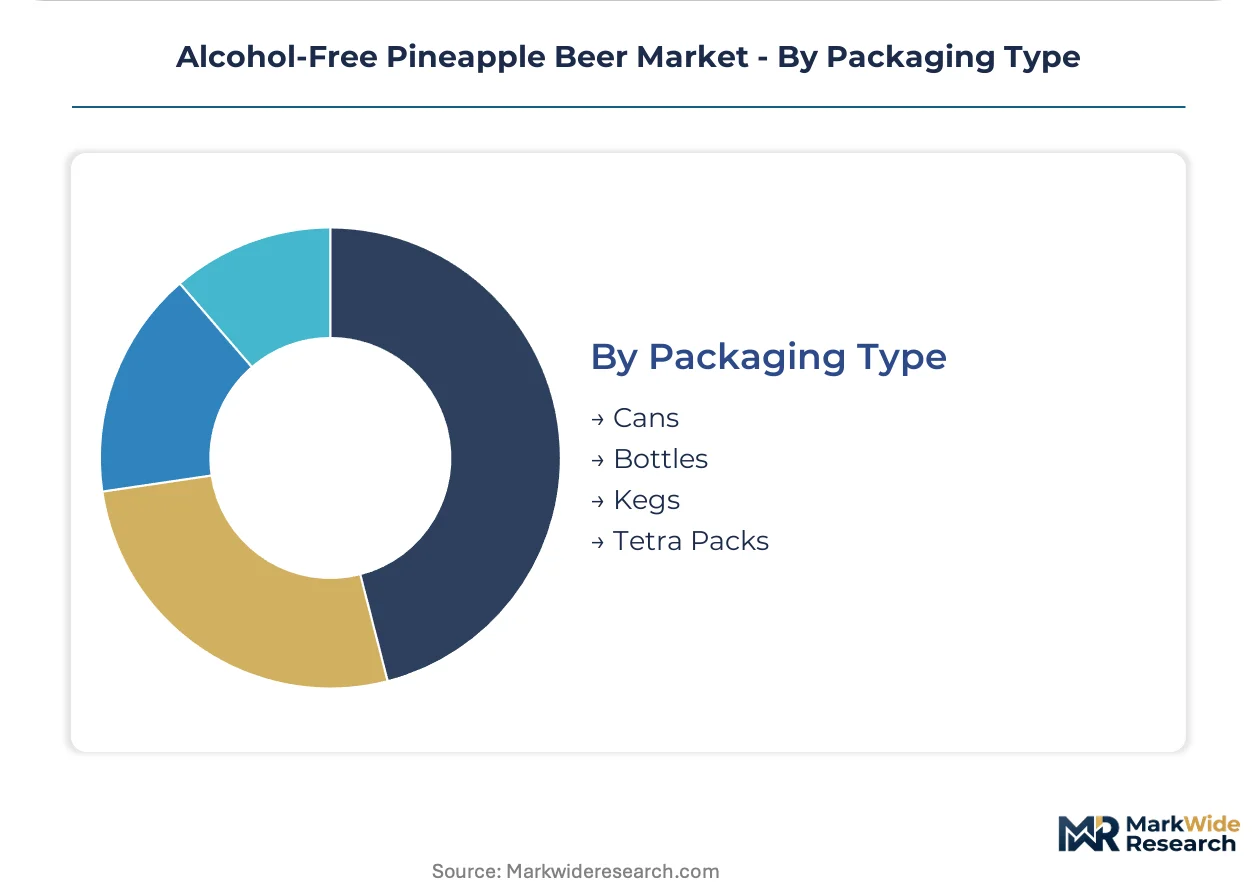
Packaging selection interacts with EU Green Deal incentives and deposit-return schemes to determine sourcing certification requirements and logistics configuration.
- Cans:Aluminum formats with recycled-content mandates align with German and Dutch deposit-return schemes and regional sourcing certifications favored by EU packaging regulations.
- Bottles:Glass formats serve premium positioning in Spanish and United Kingdom on-premise channels where aesthetic presentation supports price premiums.
- Kegs:Draught systems concentrate in German bars and restaurants with established alcohol-free tap infrastructure.
- Tetra Packs:Aseptic cartons enable ambient distribution with extended shelf life, though limited adoption in beer-category retailing constrains placement.
Cans anchors the volume base while Tetra Packs shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German retailers command 15-20% price premiums over Spanish supermarkets for identical alcohol-free pineapple beer SKUs, reflecting divergent consumer willingness to pay for clean-label positioning and refrigerated distribution infrastructure.
Germany
Health-conscious millennials in Berlin and Munich drive demand for cold-extracted pineapple essences in dedicated alcohol-free retail sections. The BfR enforces strict sub-0.5% ABV validation protocols and novel flavoring substance scrutiny. Bavarian brewing clusters around Munich leverage established non-alcoholic fermentation expertise to supply private-label programs for Aldi Süd and REWE.
United Kingdom
Subscription-driven trial behavior concentrates among London-based Gen Z consumers seeking pantry-stocking convenience over on-premise discovery. The Food Standards Agency mandates quantified ingredient declarations under evolving EU-aligned post-Brexit frameworks. Manchester and Birmingham distribution hubs support rapid fulfillment for online retail platforms capturing repeat purchase data.
United States
Craft beverage infrastructure investment accelerates in California and Colorado as dedicated non-alcoholic facilities reduce cross-contamination risks. FDA labeling requirements govern alcohol-content thresholds and health-claim permissibility for fermented beverages. San Diego and Denver brewing clusters pioneer small-batch cold-extraction systems for premium positioning in specialty retailers.
Spain
Price-sensitive volume consumption concentrates in Madrid and Barcelona supermarkets where standardized flavor profiles compete with mass-market soft drinks. Spanish food safety regulators apply EU Food Information to Consumers Regulation with additional scrutiny on tropical fruit additive categories. Andalusian retail corridors test ambient distribution models to bypass cold-chain cost structures.
Netherlands
Heineken's domestic market presence drives scale economics in alcohol-free fermentation for export-oriented production. The NVWA applies divergent fermentation byproduct reporting thresholds compared to adjacent German standards, fragmenting compliance costs. Rotterdam port logistics clusters enable efficient EU distribution for canned formats meeting deposit-return scheme requirements.
Alcohol-Free Pineapple Beer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the alcohol-free pineapple beer category. Multinational brewers with global infrastructure achieve scale economics in standardized lager production, while craft specialists capture premium margins through dedicated non-alcoholic facilities and cold-extraction capabilities. The competitive terrain separates into three strategic archetypes: multinational volume players, craft premium specialists, and private-label contract manufacturers. Dominant competitive moves include portfolio diversification into tropical flavor extensions and geographic expansion through cross-border e-commerce duty optimization.
Among multinational volume players, Heineken N.V. and Anheuser-Busch InBev occupy positions exemplifying scale-driven cost leadership, while Athletic Brewing Company represents the craft specialist archetype with dedicated non-alcoholic production infrastructure. Chinese brewers Tsingtao and Pearl River anchor the Asia-Pacific supply base for malt-derived beverage inputs. These named entities illustrate the geographic and strategic bifurcation between European premium positioning and Asian manufacturing scale.
| Leading Market Players |
|---|
| PEARL RIVER |
| QINGYI |
| Budweiser |
| Tsingtao |
| San Miguel Brewery |
| Heineken N.V. |
| Anheuser-Busch InBev |
| Carlsberg Group |
| Athletic Brewing Company |
| Others |
Pricing and Supply Chain Analysis
Cold-extracted pineapple essence substitution for heat-processed flavor concentrates simultaneously shifts sourcing geography toward German certified flavor houses and compresses premium-tier pricing spreads as sensory parity becomes commoditized.
Pricing Analysis
The customization-premium spread between small-batch craft positioning and mass-market lager formats runs wide in this category. Pricing stratifies across premium, standard, and economy tiers based on fermentation methodology and flavor extraction technology grade. Cost compression in the standard tier is intensifying because German and Dutch malt suppliers command input leverage. Health-conscious millennials in urban German markets show lowest price sensitivity, while Spanish supermarket shoppers exhibit highest elasticity.
Supply Chain Analysis
Just-in-time inventory strategies dominate among craft specialists with cold-extraction equipment, while multinational brewers maintain strategic stockpiles of low-protein specialty malts. Supply concentrates in Germany, the Netherlands, and the United States for fermentation inputs and flavor extraction infrastructure. Raw material dependencies center on Bavarian malt varieties, ECHA-certified pineapple terpenes, and aluminum canstock with recycled-content certification. Single-source vulnerability runs through German specialty malt suppliers. Distribution feeds from regional brewing clusters into supermarket chains and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
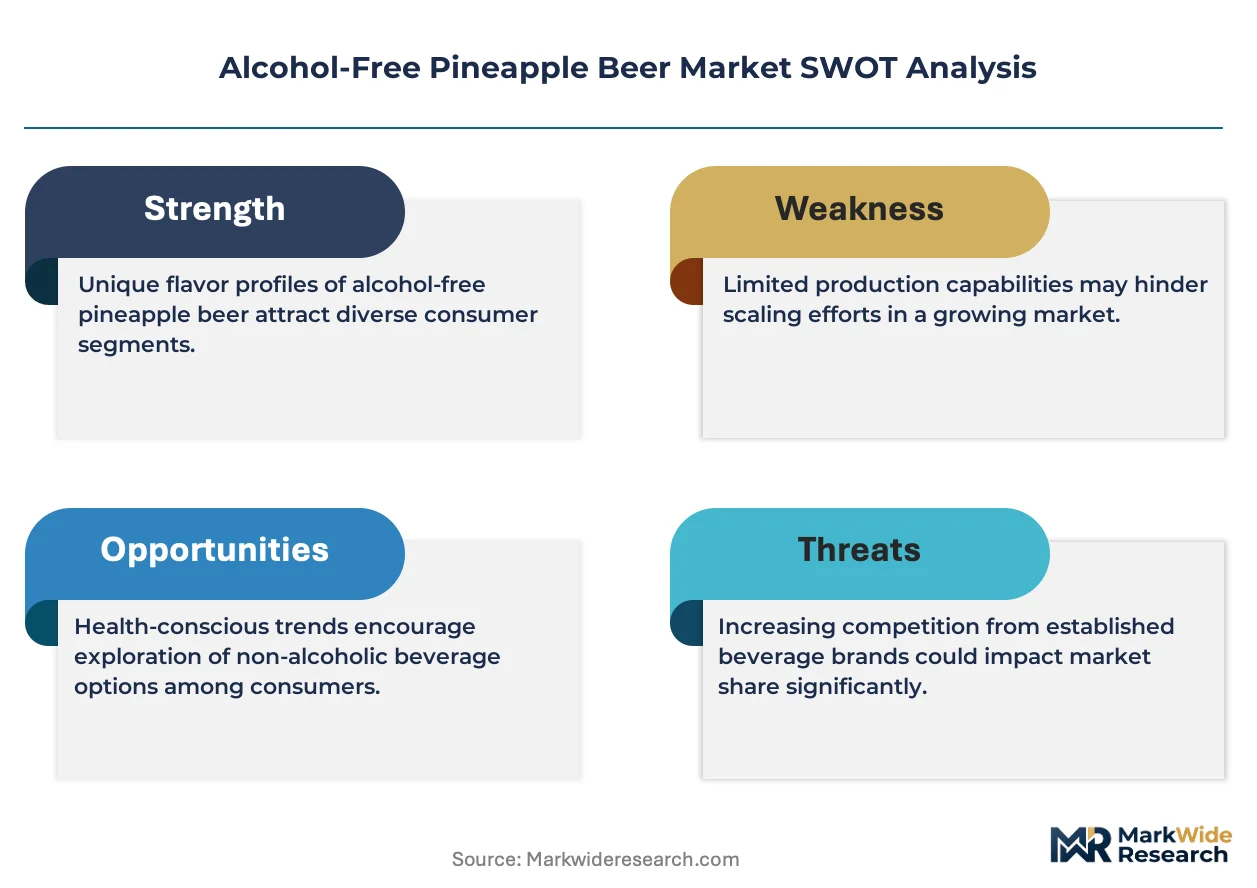
Alcohol-free pineapple beer represents a high-growth disruption justified by EU Food Information to Consumers Regulation tightening that favors breweries with pre-built compliance infrastructure over late entrants facing reformulation costs.
For Market Incumbents: Consolidate around dedicated non-alcoholic fermentation capacity to defend against craft specialists capturing premium shelf space. Acquire cold-extraction technology capabilities or partner with certified German flavor houses to lock in clean-label supply. Channel control through exclusive supermarket placement agreements in the United Kingdom and Germany remains critical.
For New Entrants and Emerging Players: EFSA novel food approval fast-tracks for natural pineapple extracts open regulatory pathways into EU markets faster than synthetic flavor routes. White-space targets include athlete-specific positioning in United Kingdom sports nutrition retail and subscription-driven personalization in United States direct-to-consumer channels. Go-to-market through curated variety packs bypasses single-SKU trial barriers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed craft beverage platforms that built dedicated non-alcoholic facilities during the pandemic-era investment wave. Long-term viability hinges on whether cold-chain infrastructure investments achieve scale economics before ambient-stable flavor technologies mature. The signal to watch is BfR validation protocol harmonization with NVWA standards, which would compress compliance costs for cross-border operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Extraction Technology Licensing | Grants access to ECHA-compliant terpene preservation methods required for EU clean-label positioning. |
| Backward Integration into Malt Supply | Captures Bavarian brewing cluster proximity and reduces exposure to German-Dutch supplier concentration. |
| Direct-to-Consumer Subscription Launch | Generates repeat purchase data for flavor personalization in United States health-conscious segments. |
| Athlete-Specific Certification Investment | Unlocks dedicated shelf space in United Kingdom sports nutrition retail bypassing conventional beer aisles. |
| EU Green Deal Packaging Compliance | Aligns with German deposit-return schemes and recycled-content mandates favoring regional canning lines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the analysis window, combining primary interviews with brand managers at multinational brewers, category buyers at Tesco and Carrefour, technical R&D directors at certified flavor houses, and supply planners at aluminum packaging suppliers with secondary validation. Secondary sources included EU Food Information to Consumers Regulation filings, BfR and NVWA guidance documents, ECHA REACH substance registrations, and customs data on malt and pineapple extract trade flows. Bottom-up volume triangulation against top-down value estimates anchored forecast robustness.
Across the projection horizon, the analytical framework modeled volume and value trajectories by product type segmentation, distribution channel configuration, customer identity archetype, and packaging format compliance tier. CAGRs were derived from trend extrapolation calibrated against historical substitution patterns between alcoholic and non-alcoholic beverage categories. Industry-specific forecast inputs included cold-extraction technology adoption curves and EU labeling harmonization implementation timelines.
Decision-makers should treat outputs as directional under base assumptions of sustained health-conscious consumer migration and stable regulatory classification for sub-0.5% ABV products; material deviation would warrant model refresh. Forecasts reflect assumptions of continued German-UK demand concentration and unimpaired cross-border e-commerce duty structures. Revision becomes warranted when flavor stability technology achieves ambient shelf-life parity or when BfR-NVWA regulatory divergence intensifies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
North America Beer Market
Alcoholic Beverages
Liquor Flavored Ice Cream Market
Alcoholic Beverages
Light-Flavor Liquor Market
Alcoholic Beverages
Mexico Tequila Market
Alcoholic Beverages
Cooking Wine Market
Alcoholic Beverages
Alcoholic Ready-To-Drink (Rtds)/High Strength Premixes Market
Alcoholic Beverages
Craft Wine Market
Alcoholic Beverages
Asia Pacific Wine Coolers Market
Alcoholic Beverages
Brewing Enzymes Market
Alcoholic Beverages
UK Tequila Market
Alcoholic Beverages
Grain Neutral Spirits Market
Alcoholic Beverages
Tonic Wine Market
Alcoholic Beverages
Mini Brew Fermenter Market
Alcoholic Beverages
Pineapple Beer Market
Alcoholic Beverages
Low-Alcohol Beer Market
Alcoholic Beverages
Beer Pasteurization Equipment Market