
 Beer Processing Market | 2026-2036
Beer Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Beer Processing Market Intelligence
The institutional knowledge of traditional brewmasters is unwinding the sector's historical reliance on manual intervention for quality control. Technology providers like GEA Group and Krones now embed this expertise into automated process control modules for fermentation and filtration. Global brewers such as Heineken N.V. leverage these systems to standardize product quality across international facilities. Anheuser-Busch InBev also competes by optimizing its vast supply chain for both mass-market and craft-style beverage production.
Beer processing encompasses the sequence of biochemical and physical transformations converting raw materials like malt and hops into a finished alcoholic beverage. Key stages include mashing to convert starches, fermentation at specific gravities, and maturation to develop distinct flavor and aroma profiles. Within processing technology, fermentation and filtration equipment represent core capital expenditures, defining both brewery capacity and product consistency. The craft breweries application segment is expanding quickly, creating demand for flexible and scalable processing solutions from suppliers.
Regulatory frameworks from the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) govern the use of processing aids like clarifiers and stabilizers. These standards directly influence ingredient sourcing decisions and require stringent process documentation for market access in North America and Europe. Navigating evolving water usage and effluent discharge regulations, such as those from the EPA in the United States, will be a critical determinant of operational viability for breweries.
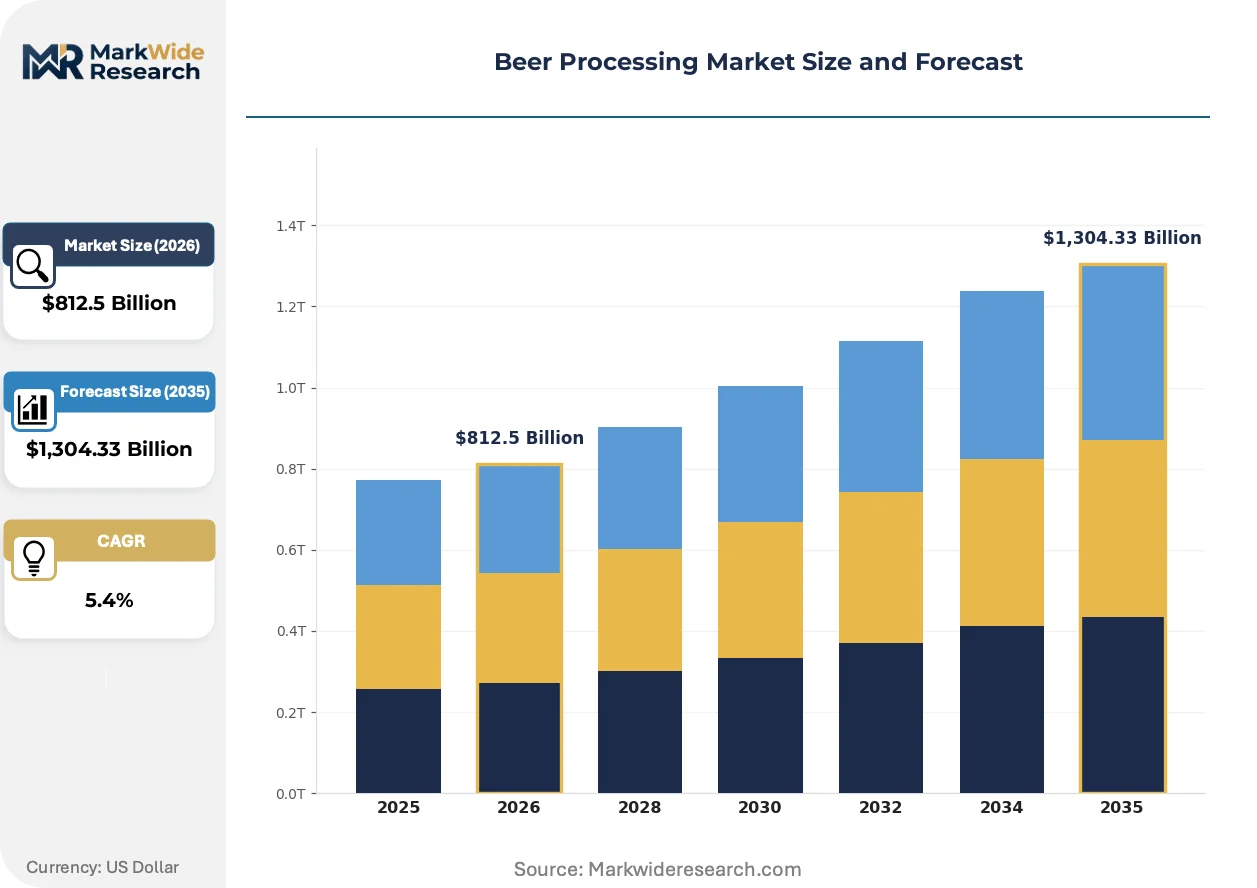
Market Dynamics
Process automation for fermentation and filtration is the central force shaping the market, enabling large-scale production while also providing the precision required by craft breweries to create differentiated, high-quality beverages and meet diverse consumer preferences.
Growth Catalysts
- Craft Brewery Expansion:The proliferation of microbreweries and brewpubs, particularly in markets like Brazil, creates sustained demand for scalable and flexible processing equipment to support product experimentation.
- Premiumization Trend:Consumer willingness to pay more for premium and craft beers with distinct flavor profiles drives investment in advanced mashing and maturation technologies for greater control.
- Process Automation:Adoption of automated control modules for fermentation standardizes quality, reduces manual intervention, and improves operational efficiency for brewers of all sizes.
Market Restraints
- Input Cost Volatility:Fluctuations in the price and availability of core raw materials, especially specialty hops and high-quality malt, create margin pressure and sourcing challenges for brewers.
- Stringent Water Regulations:Increasingly strict rules on water usage and effluent discharge, such as those from the EPA in the United States, impose significant compliance costs and operational constraints.
- High Capital Expenditure:The substantial upfront investment required for core processing equipment like industrial fermenters and filtration systems represents a major barrier to entry and expansion.
Strategic Opportunities
- Non-Alcoholic Beer Processing:Developing specialized equipment for dealcoholization, such as vacuum distillation or reverse osmosis systems, opens a rapidly expanding product category for technology providers.
- Emerging Market Penetration:Breweries in Southeast Asian countries represent an underpenetrated market for modern processing technologies as disposable incomes and beer consumption rise.
- AI and IoT Integration:Converging artificial intelligence with sensor data from the brewing process enables predictive quality control and optimized fermentation cycles, creating new service-based revenue streams.
Industry Challenges
- Brewing Expertise Gap:The shift from manual brewing to automated systems creates a need for personnel skilled in process engineering and data analysis, not just traditional brewing arts.
- Supply Chain Diversification:Managing complex logistics for a wide array of ingredients, from commodity malts to niche hops, strains the supply chains of large brewers producing craft-style beers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beer Processing Market |
| Market Size in 2026 | $812.5 Billion |
| Market Size in 2035 | $1,304.33 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Malt Extract, Liquid Yeast, Adjuncts, Enzymes, Stabilizers, Clarifiers Processing Technology: Filtration, Fermentation, Pasteurization, Carbonation, Maturation, Packaging Application: Brewpubs, Contract Brewing, Microbreweries, Taprooms, Craft Breweries End User: Commercial Breweries, Distributors, Beverage Wholesalers, Retail Chains, Hospitality Groups |
| Companies Covered | Anheuser-Busch InBev, Heineken N.V., China Resources Snow Breweries Limited, Carlsberg Group, Molson Coors Brewing Company, GEA Group, Krones, Alfa Laval, Diageo PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beer Processing Market Strategic Shifts & Innovations
Technology is creating a dual-track evolution in beer processing. Automation enables unprecedented scale and consistency for global brands, while simultaneously empowering smaller producers with the precision tools to compete on quality and product differentiation.
Process analytical technology integrates advanced sensors for real-time monitoring of variables like specific gravity and yeast health during fermentation. Both large industrial brewers and small craft producers are adopting these systems to ensure recipe adherence. This technology is bifurcating the competitive landscape into hyper-efficient, large-scale operations and data-driven, artisanal producers focused on nuanced quality.
The European Food Safety Authority's strict governance over processing aids, including clarifiers and stabilizers, mandates rigorous process validation. This forces equipment suppliers to design systems that ensure contaminant-free production and provide extensive documentation for market access in Europe. Filtration and purification equipment segments are most affected, needing to demonstrate full compliance with these standards.
A consumer-driven demand for ingredient transparency is reshaping sourcing strategies within the brewing industry. This movement disrupts conventional, multi-layered supply chains in favor of direct-from-farm procurement of hops and malt. The trend is most visible in North American and European craft beer markets, where product packaging often highlights the specific origin of its raw materials.
Beer Processing Market Segmentation
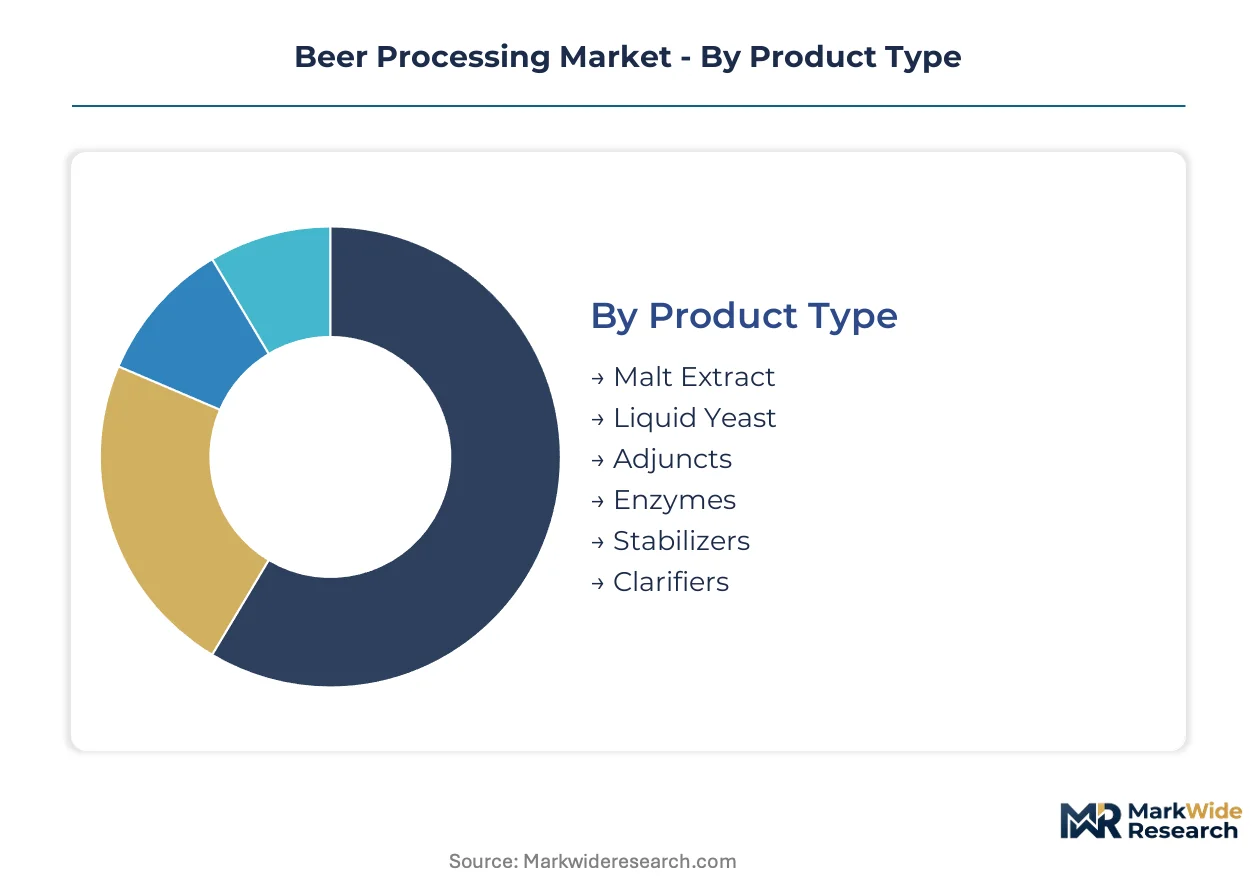
Segmentation within the beer processing market highlights the diverse technological requirements and operational models across the industry. Understanding these distinctions is crucial for suppliers developing specialized equipment and ingredients. This granular view informs strategic investments in automation and raw material innovation.
Product Type:
Regulatory frameworks from entities like the European Food Safety Authority (EFSA) and the U.S. Food and Drug Administration (FDA) heavily influence the acceptable use and sourcing of various product types in beer processing.
- Malt Extract:This concentrated syrup or powder provides fermentable sugars and flavor compounds derived from malted barley. Demand concentrates in global commercial breweries seeking consistent base ingredients and in craft breweries for specific flavor profiles.
- Liquid Yeast:Live cultures of Saccharomyces cerevisiae are essential for fermentation, converting sugars into alcohol and carbon dioxide. Demand is strong in craft breweries and microbreweries requiring specific yeast strains for distinct aroma and flavor development.
- Adjuncts:Non-malt fermentable ingredients like corn, rice, or wheat are used to modify beer body, flavor, or alcohol content.
- Enzymes:Processing aids like amylase facilitate starch conversion or improve filtration efficiency in large-scale brewing operations.
- Stabilizers:Ingredients such as PVPP or silica gel prevent haze formation and extend shelf life in packaged beers.
- Clarifiers:Fining agents like isinglass or carrageenan are used to remove suspended particles and improve beer clarity.
Established volume favors Malt Extract; emerging adoption favors Liquid Yeast for specialized craft brews.
Processing Technology:
Operational efficiency and product consistency drive investment across different processing technologies within breweries.
- Fermentation:This biochemical process converts sugars into alcohol and CO2 using yeast, defining the beer's fundamental characteristics. Demand concentrates in microbreweries and large-scale operations implementing automated control modules for precise temperature and gravity management.
- Filtration:Equipment for removing yeast, proteins, and other particles ensures clarity and extends shelf life, crucial for product quality. Demand for advanced filtration systems is high in European markets due to stringent EFSA regulations on product purity.
- Pasteurization:Heat treatment eliminates microorganisms, stabilizing packaged beer for extended shelf life, especially for global distribution.
- Carbonation:Introducing carbon dioxide at controlled levels creates the desired effervescence and mouthfeel in finished beer.
- Maturation:The conditioning phase allows flavors to develop and off-flavors to diminish before packaging.
- Packaging:This final stage involves filling, sealing, and labeling beer into bottles, cans, or kegs for market distribution.
Automated Fermentation solutions are experiencing the steepest expansion trajectory, while Packaging technologies optimize for speed and cost.
Application:
Different operational models within the brewing industry necessitate distinct processing equipment and scale.
- Craft Breweries:Independent breweries focusing on unique, high-quality, and often experimental beer styles drive demand for flexible and precise processing equipment. This segment's expansion, particularly in Brazil and North America, fuels innovation in small-batch systems.
- Microbreweries:Small-scale breweries producing limited volumes of beer, often for local consumption, require scalable and adaptable processing solutions. Their focus on product differentiation necessitates advanced mashing and fermentation control.
- Brewpubs:Establishments combining a brewery with a restaurant, producing beer primarily for on-site consumption, prioritize compact and visible brewing systems.
- Contract Brewing:Breweries that produce beer for other brands, requiring flexible systems to handle diverse recipes and production volumes.
- Taprooms:Retail spaces directly connected to a brewery, offering direct sales and consumption, often feature smaller, visible brewing setups.
The Craft Breweries segment demands flexible, high-precision equipment, while Contract Brewing requires versatile, high-throughput systems.
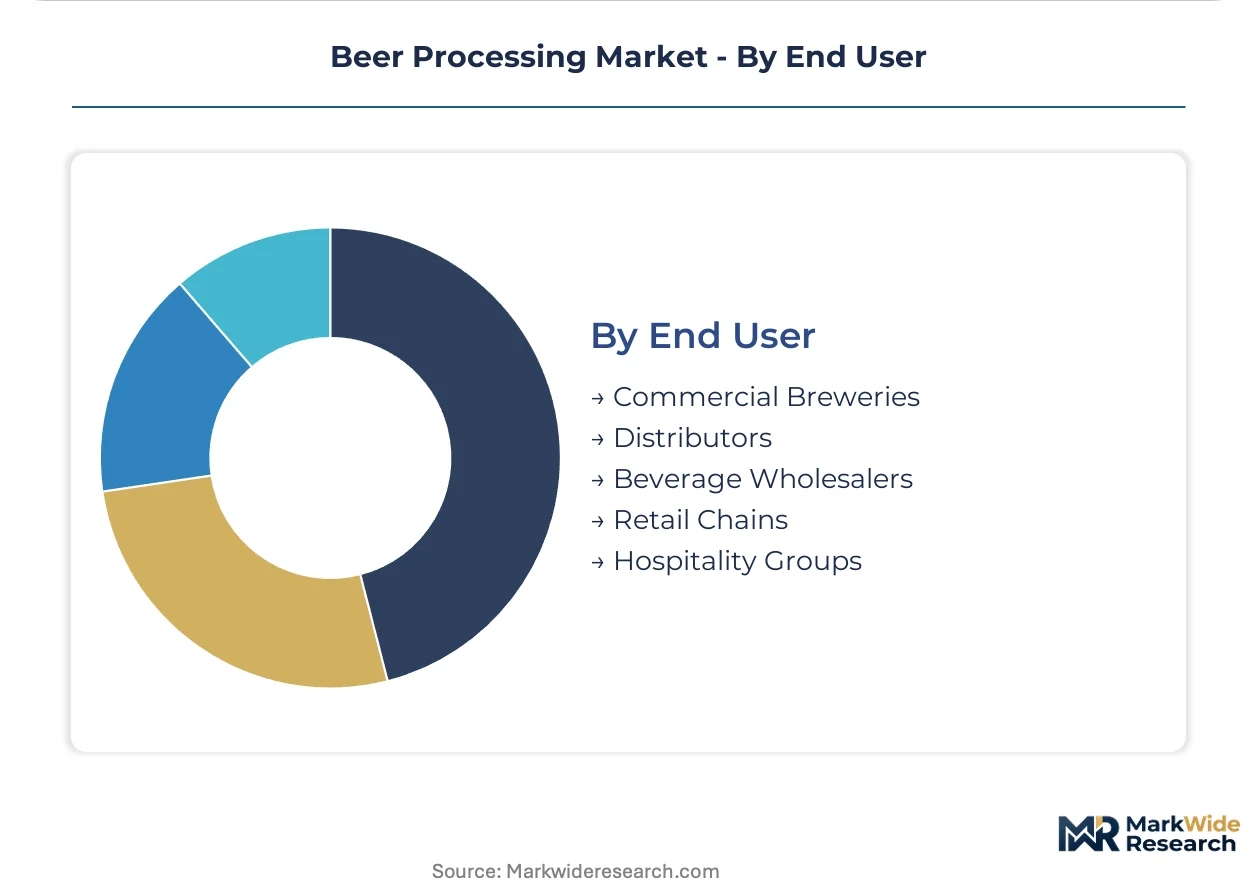
End User:
The role of different end-users within the beer supply chain dictates their specific processing and logistics requirements.
- Commercial Breweries:Large-scale producers like Heineken N.V. and Anheuser-Busch InBev focus on high-volume production, standardization, and global distribution. Their demand centers on automated, robust processing lines for efficiency and consistent quality.
- Retail Chains:Supermarkets and specialty stores require processing solutions that ensure product stability and shelf life for diverse beer portfolios. Their influence drives demand for efficient packaging and quality control systems.
- Distributors:Companies managing logistics and sales between breweries and retail outlets require efficient bulk handling and storage solutions.
- Beverage Wholesalers:Entities purchasing beer in large quantities from producers for resale to retailers and hospitality venues.
- Hospitality Groups:Hotels, restaurants, and bars serving beer on-premise, requiring reliable dispensing and storage systems.
Commercial Breweries prioritize scale and consistency, while Retail Chains demand product stability and market access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Food Safety Authority (EFSA) significantly influences beer processing standards across its member states, driving demand for compliant equipment and ingredients. Global expansion of craft breweries, coupled with consumer demand for diverse flavor profiles, necessitates advanced processing technologies worldwide. Operational efficiency and product consistency remain paramount for brewers of all scales.
Brazil
Consumer preferences for premium and craft beers are diversifying across Brazil, creating sustained demand for scalable processing solutions. Brazil's national health regulatory agency, ANVISA, governs food safety and ingredient approvals for all beverage production. The craft brewing scene in São Paulo state fosters innovation in small-batch systems and specialized equipment.
United States
Craft brewery expansion and the premiumization trend drive investment in advanced processing technologies within the United States. The U.S. Food and Drug Administration (FDA) and Environmental Protection Agency (EPA) regulate processing aids, water usage, and effluent discharge. The Pacific Northwest, particularly regions around Portland, remains a hub for craft brewing innovation and equipment demand.
Germany
Germany's deep-rooted brewing tradition fuels a consistent demand for high-quality, precise processing equipment. The German Reinheitsgebot (purity law) sets strict ingredient standards, impacting sourcing and processing technology choices. Bavaria, including cities like Munich, maintains a strong concentration of traditional breweries and advanced equipment manufacturers.
China
Rising disposable incomes and changing consumer tastes are increasing beer consumption and demand for diverse styles across China. China's national food safety standards (GB standards) regulate production processes and ingredient use in breweries. Coastal economic hubs like Shanghai and Guangzhou are witnessing growth in modern brewing facilities and associated technology adoption.
India
Urbanization and a growing middle class are driving demand for new beer styles, including craft and premium offerings, in India. The Food Safety and Standards Authority of India (FSSAI) oversees all food and beverage manufacturing, including beer processing. Bengaluru and Pune are emerging as centers for craft beer production and brewpub expansion.
Beer Processing Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the beer processing market. The market structure exhibits a tiered approach, with large industrial equipment providers serving global brewers and specialized firms catering to craft segments. Strategic archetypes include integrated brewing giants, dedicated processing equipment manufacturers, and ingredient suppliers. Dominant competitive moves involve continuous process automation innovation and extensive supply chain optimization.
At the scale-driven end, global brewers like Anheuser-Busch InBev and Heineken N.V. anchor volume production, leveraging advanced processing lines for efficiency. Equipment specialists such as GEA Group and Krones provide comprehensive solutions for fermentation, filtration, and packaging. Alfa Laval also occupies a significant position, offering vital components for heat exchange and separation technologies across the industry.
| Leading Market Players |
|---|
| Anheuser-Busch InBev |
| Heineken N.V. |
| China Resources Snow Breweries Limited |
| Carlsberg Group |
| Molson Coors Brewing Company |
| GEA Group |
| Krones |
| Alfa Laval |
| Diageo PLC |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements for key raw materials provide brewers with both supply access and price visibility for core ingredients. This structure helps stabilize production costs amidst volatile commodity markets, particularly for large commercial breweries.
Pricing Analysis
Geographic price spreads for specialty hops and malt vary significantly due to regional cultivation costs and logistics. The dominant pricing model for processing equipment remains project-based, reflecting customization and installation complexity. Price differentiation stems from the quality grade of ingredients and the customization level of automated systems. Pricing pressure is intensifying due to input cost volatility, particularly for specialty hops. Commercial breweries are highly sensitive to raw material cost fluctuations, while craft breweries are more sensitive to the upfront capital expenditure for advanced equipment.
Supply Chain Analysis
Logistics chokepoints for specialty ingredients, such as specific hop varieties from the Pacific Northwest in the United States or high-quality malt from Germany, introduce supply chain vulnerabilities. Geographic supply concentration for key inputs centers on Germany for traditional malts and equipment, and the United States for innovative hop varietals. Raw material dependencies include specialty hops, high-quality malt, and advanced sensor components for automation. Single-source vulnerability for niche yeast strains represents a structural risk. Distribution for processing equipment typically runs through direct sales channels from manufacturers like Krones and GEA Group.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beer processing equipment sales create significant service-attach opportunities, with AI and IoT integration for predictive quality control expanding faster than new hardware sales.
For Market Incumbents:
Compound existing automation expertise by acquiring niche AI analytics firms specializing in fermentation optimization. This mitigates the brewing expertise gap and strengthens competitive positioning against specialized software providers. Focus research and development on water recycling technologies to address stringent EPA and European effluent regulations. Expand presence in emerging Southeast Asian markets, leveraging existing global distribution networks for equipment sales.
For New Entrants and Emerging Players:
Customized software solutions for recipe management and real-time process optimization represent a service-layer gap for many mid-sized craft breweries. Target the microbrewery segment in Brazil and India with flexible, modular equipment bundles that integrate AI-driven fermentation insights. Offer subscription-based process analytical technology for precise quality control, reducing upfront capital expenditure for new players. Develop specialized dealcoholization systems for the growing non-alcoholic beer market.
For Investors and Strategic Acquirers:
Recurring-revenue conversion is highest among technology providers offering data analytics and predictive maintenance for automated brewing systems. Seek acquisition targets with strong intellectual property in AI/IoT for brewing or specialized dealcoholization equipment, offering long-term growth potential. A signal to watch is the increasing patent activity in sensor technology for real-time yeast health monitoring. Evaluate companies demonstrating robust compliance with evolving water usage regulations.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-driven Fermentation Optimization | Enables predictive quality control and reduces batch variation for global brewers. |
| Modular Dealcoholization System Development | Captures demand in the rapidly expanding non-alcoholic beer market segment. |
| Water Recycling and Effluent Treatment Solutions | Addresses stringent EPA and regional water usage regulations, ensuring operational viability. |
| Specialty Ingredient Supply Chain Digitization | Improves transparency and traceability for craft breweries responding to consumer demand. |
| Expansion into Southeast Asian Markets | Penetrates under-served regions with rising disposable incomes and diversifying beer consumption. |
Research Approach
A standing panel of brewmasters, process engineers, equipment manufacturers, and regulatory compliance officers provided ongoing calibration for market insights. This primary research was rigorously validated against secondary data from industry association reports, patent databases, and company financial filings. Bottom-up aggregation of segment data and top-down market sizing ensured robust triangulation.
Forecast outputs were consistently validated against external benchmarks from leading industry bodies and academic research institutions. The analytical framework modeled dimensions including product type, processing technology, application, and regional regulatory compliance. Compound annual growth rates were derived from historical trends, projected technological adoption, and evolving consumer preferences across the analysis window. Key inputs included craft brewery expansion rates and automation investment trends.
Forecasts assume regulatory continuity in U.S. FDA, EFSA, and ANVISA regimes; material policy shifts would require re-modeling. The analysis accounts for input cost volatility and global supply chain disruptions. Practitioners should keep alternative scenarios live as geopolitical events and technological advancements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Wine Aerator Market
Alcoholic Beverages
Global Brewery Filtration Market
Alcoholic Beverages
Germany Wine Coolers Market
Alcoholic Beverages
Fruit Brandy Market
Alcoholic Beverages
Single Serve Wine Market
Alcoholic Beverages
South Africa Beverages Market
Alcoholic Beverages
Cigar and Cigarillos Market
Alcoholic Beverages
Global Beer Market
Alcoholic Beverages
Premixed Cocktail Shots Market
Alcoholic Beverages
Luzhou-Flavor Liquor Market
Alcoholic Beverages
Beer Bottle Market
Alcoholic Beverages
E-Commerce Liquor Market
Alcoholic Beverages
Craft Beer Market
Alcoholic Beverages
United States Beer Market
Alcoholic Beverages
RTD Cocktails Market
Alcoholic Beverages
Commercial Beer Tap System Market