
 Wine Bags Market | 2026-2036
Wine Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Wine Bags Market Outlook
The gap between premium leather and cloth wine bags and commodity plastic alternatives is shifting from a price divide to a sustainability credential split. BUILT NY leverages thermal insulation technology to dominate the performance gift segment. Wine Box Company Limited anchors the UK market through specialized corrugated and wooden box formats. Richie Bags competes on jute and cotton craftsmanship for eco-conscious European buyers.
Wine bags are portable containers engineered from paper, cloth, plastic, or leather with specified closure mechanisms—zipper, string, magnetic, or snap—to protect bottles during transport and enhance presentation at point of sale or gifting. Their primary commercial purpose spans retail branding, direct-to-consumer shipping protection, and hospitality tableside service. The material type dimension shows paper and cloth outpacing plastic as regulatory pressure and brand sustainability commitments reshape procurement specifications. Within design style, eco-friendly variants command expanding shelf space while classic formats retain stable volume in traditional wine-producing regions.
REACH and the EU Packaging and Packaging Waste Regulation constrain plastic content and mandate recyclability disclosures across European supply chains. The FDA's indirect food contact material standards govern U.S. import specifications for wine bags sold through retail channels. California's SB 54 extended producer responsibility framework adds state-level compliance layers for brands distributing through West Coast ports. Stakeholders must monitor evolving extended producer responsibility schemes to determine whether regional manufacturing or material certification investments offer stronger margin protection.
Market Dynamics
EU Packaging and Packaging Waste Regulation enforcement is forcing material substitutions across European supply chains while specialty retailers convert wine bags into branded customer touchpoints.
Growth Catalysts
- REACH material compliance:Chemical registration requirements are eliminating non-compliant plastic substrates from EU distribution channels, opening shelf space for certified alternatives.
- Wine tourism corridors:France's Bordeaux and Burgundy regions generate concentrated gift-packaging demand where premium positioning commands sustained volume.
- Thermal insulation integration:Performance-engineered bags with temperature control are capturing direct-to-consumer shipping contracts from temperature-sensitive wine clubs.
Market Restraints
- Jute supply concentration:Bangladesh and Indian monsoon-dependent harvests create raw material volatility for eco-positioned bag producers.
- Leather tanning compliance:Chromium VI restrictions under REACH Annex XVII add certification costs that compress margins on premium artisan formats.
- Corrugated substitution:Wooden box formats face price competition from structurally engineered paperboard alternatives in the UK retail channel.
Strategic Opportunities
- California SB 54 frameworks:Extended producer responsibility mandates create first-mover advantage for brands establishing West Coast circular collection infrastructure.
- Hospitality tableside service:Restaurants in Italy and Spain are adopting branded wine bags as part of experiential dining presentation standards.
- Magnetic closure convergence:Integration of snap-fit polymer engineering with traditional cloth substrates enables premium repositioning at mid-tier price points.
Industry Challenges
- Recyclability disclosure timelines:EU harmonized labeling requirements demand accelerated testing protocols that strain smaller manufacturers' technical staffing.
- Multi-material separation:Bags combining leather handles, cloth bodies, and metal closures complicate end-of-life sorting infrastructure compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wine Bags Market |
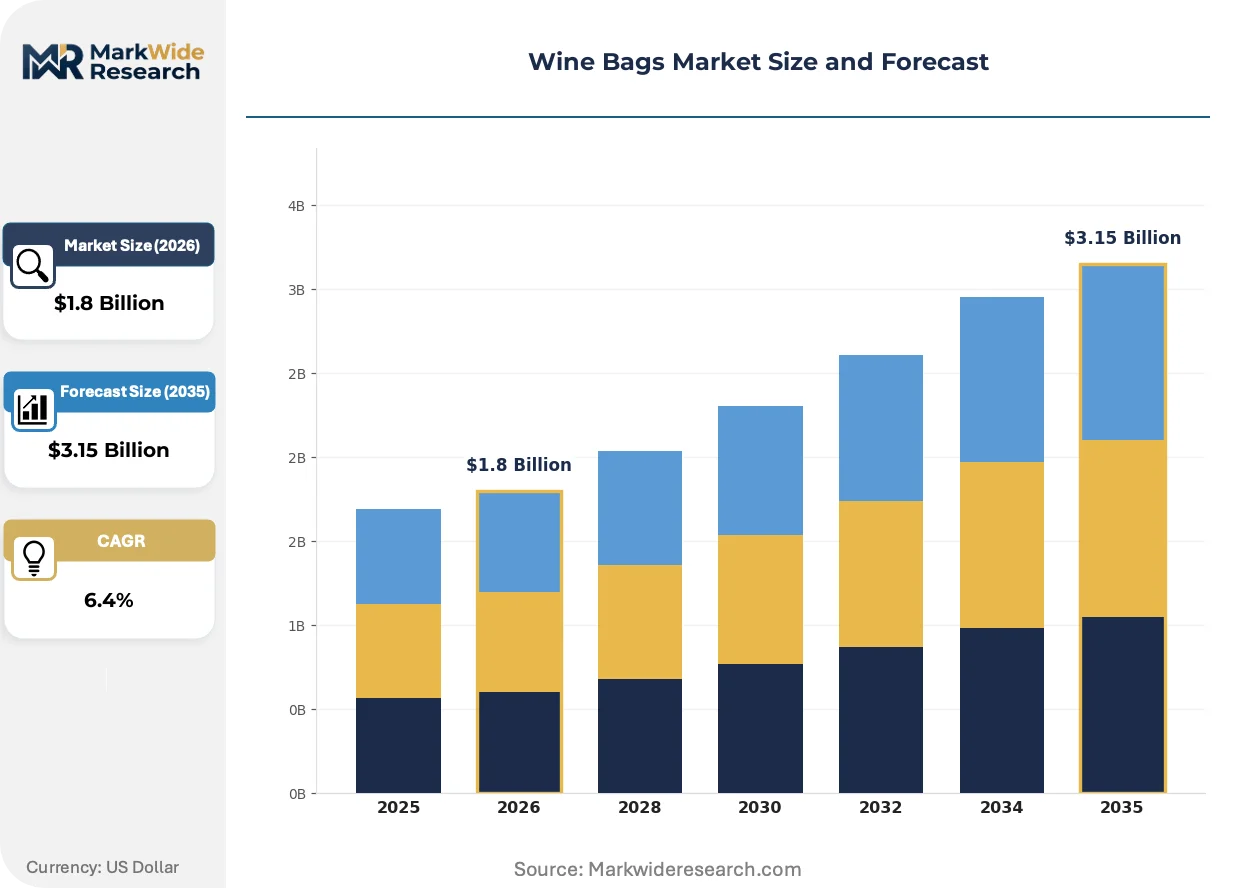
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Paper, Cloth, Plastic, Leather Closure Type: Zipper, String, Magnetic, Snap End User: Retailers, Distributors, Restaurants, Individuals Design Style: Classic, Modern, Eco-Friendly, Decorative |
| Companies Covered | Wine Box Company Limited, BUILT NY, Acorn Paper Products Company, Initi Bag Manufacturer, Richie Bags, Nangfa Manufacturing, DM Pack, PaperPak, Yiwu Youbai Packing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wine Bags Market Strategic Shifts
Material science advances and regulatory disclosure mandates are converging to redefine competitive advantage away from aesthetic differentiation toward verifiable sustainability credentials.
Phase-change material integration is rewriting thermal performance standards for wine transport. Temperature-buffering gel packs embedded within insulated bag walls extend safe transit windows from hours to days. Direct-to-consumer wine clubs in Germany and the Netherlands are specifying these formats for summer delivery contracts, compressing demand for basic neoprene sleeves that lack active temperature management.
REACH Annex XVII restrictions on persistent organic pollutants are tightening testing protocols for imported textile dyes. Suppliers serving EU markets must now document supply chain chemical compliance back to fiber cultivation. Italian leather goods manufacturers are responding by consolidating tanning partnerships within EU jurisdiction to reduce customs clearance friction and audit exposure.
Corporate gifting procurement is consolidating spend toward suppliers offering carbon footprint certification. Large employers in France and Switzerland now require Scope 3 documentation for promotional wine bag orders previously awarded on unit cost alone. This behavioral pivot favors vertically integrated producers with captive fiber sourcing and in-house lifecycle assessment capability over trading-house intermediaries.
Wine Bags Market Segmentation
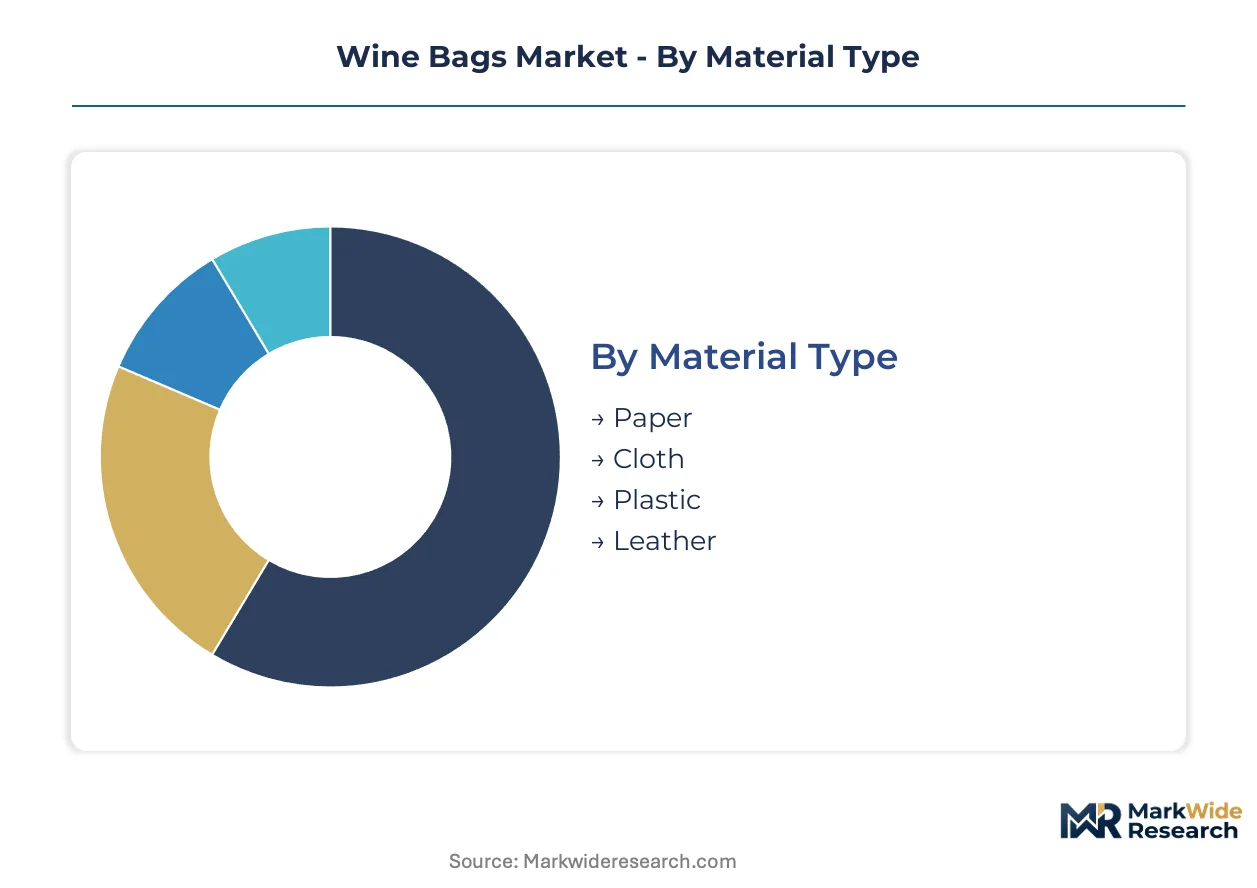
Wine bag procurement splits sharply between commodity volume plays and premium positioning strategies. Material choices now signal compliance posture as much as cost structure. Design style selection increasingly reflects end-use channel requirements rather than pure aesthetic preference.
Material Type:
Paper and cloth formats command premium shelf space while plastic fights regulatory headwinds across European distribution channels.
- Cloth:Cotton, jute, and canvas substrates dominate eco-positioned retail programs. REACH Annex XVII dye compliance requirements favor EU-sourced textile supply chains over Asian imports. Bordeaux wine tourism corridors specify cloth bags for gift-shop exclusivity.
- Paper:Kraft and corrugated constructions anchor direct-to-consumer shipping protection. German wine clubs specify paper formats with FSC chain-of-custody documentation for carbon accounting compliance.
- Plastic:Polypropylene and polyethylene formats retain cost-sensitive institutional volume. California SB 54 extended producer responsibility mandates accelerate phase-out timelines for single-use plastic wine sleeves.
- Leather:Full-grain and bonded leather constructions serve corporate gifting and hospitality tableside presentation. Chromium VI restrictions under REACH Annex XVII compress margins through certification overhead.
Mature deployment sits with plastic formats in high-volume retail channels. Newer deployment is concentrated in cloth and paper segments where sustainability credentials drive procurement decisions.
Closure Type:
Mechanism selection tracks price tier and reuse intensity rather than pure functional necessity.
- Magnetic:Snap-fit polymer engineering integrated with cloth substrates enables mid-tier premium repositioning. Italian leather goods manufacturers specify magnetic closures for hospitality presentation standards.
- Zipper:Nylon coil and metal zipper configurations dominate insulated thermal bag specifications. Temperature-sensitive wine clubs in the Netherlands require zipper-sealed compartments for gel pack retention.
- String:Cotton and jute drawcord closures serve artisan and eco-friendly design styles. Bangladeshi jute supply volatility creates procurement timing risk for string-dependent formats.
- Snap:Plastic and metal snap fasteners retain economy-tier volume in supermarket private-label programs. UK corrugated box specialists are displacing snap-closure bags with integrated lid formats.
Magnetic and zipper closures are expanding most quickly through premium hospitality and direct-to-consumer channels. String and snap formats defend position in cost-driven retail procurement.
End User:
Channel requirements diverge sharply between branding-intensive hospitality deployment and protection-focused logistics applications.
- Retailers:Specialty wine merchants convert bag programs into branded customer touchpoints with thermal insulation and magnetic closure specifications. France's independent wine retailers drive gift-oriented format innovation.
- Restaurants:Tableside presentation standards in Italy and Spain specify branded cloth or leather formats as experiential dining components. Magnetic closure integration supports single-hand operation during service.
- Distributors:Logistics-focused procurement prioritizes corrugated and paper formats for case-level shipping protection. UK wholesale channels favor engineered paperboard over wooden box alternatives on unit cost.
- Individuals:Direct-to-consumer demand concentrates in reusable insulated formats for wine club subscriptions and personal gifting. Temperature-buffering specifications are displacing basic neoprene sleeves.
Established volume concentrates with distributor and individual segments. Restaurant and specialty retailer channels are gaining share fastest through branded experience investments.
Design Style:
Aesthetic positioning now correlates directly with material compliance documentation rather than pure visual differentiation.
- Eco-Friendly:Unbleached kraft, organic cotton, and jute constructions with carbon footprint certification serve corporate gifting procurement. Swiss and French employers require Scope 3 documentation for promotional orders.
- Classic:Traditional leather and heavy canvas formats retain stable volume in Bordeaux and Burgundy wine tourism corridors. Gift-shop positioning commands sustained premium pricing.
- Modern:Minimalist geometric profiles with magnetic closures capture urban specialty retail placement. Thermal insulation integration differentiates modern formats from commodity alternatives.
- Decorative:Embossed, printed, and appliqué finishes serve seasonal and occasion-based gifting cycles. REACH textile dye compliance constrains decorative color palette options for EU-bound production.
Classic and decorative styles hold mature positions in traditional wine-producing regions. Eco-friendly and modern formats are climbing the fastest through sustainability-driven procurement restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bordeaux and Burgundy wine tourism corridors generate concentrated gift-packaging demand where premium positioning commands sustained volume. France's independent wine retailers drive format innovation through branded customer touchpoints. The EU Packaging and Packaging Waste Regulation tightens material compliance requirements across member states.
France
Bordeaux and Burgundy wine tourism corridors concentrate gift-oriented packaging demand with premium shelf positioning. REACH Annex XVII dye compliance requirements favor EU-sourced textile supply chains over Asian imports. Independent wine retailers in Lyon and Paris drive magnetic closure and thermal insulation specifications for branded bag programs.
Germany
Direct-to-consumer wine clubs in the Netherlands and Germany specify temperature-buffering gel pack formats for summer delivery contracts. The EU Packaging and Packaging Waste Regulation mandates recyclability disclosures that accelerate paper format adoption. Frankfurt and Hamburg logistics hubs prioritize FSC chain-of-custody documentation for carbon accounting compliance.
United Kingdom
Corrugated and wooden box formats anchor distributor procurement for case-level shipping protection. Extended producer responsibility frameworks add compliance layers for brands distributing through UK ports. London specialty retailers and Edinburgh wine merchants convert bag programs into branded hospitality touchpoints.
Italy
Restaurants in Milan and Rome adopt branded cloth and leather formats as experiential dining presentation standards. REACH chromium VI restrictions compress margins on premium artisan formats through certification overhead. Tuscany leather goods manufacturers consolidate tanning partnerships within EU jurisdiction to reduce customs clearance friction.
United States
California SB 54 extended producer responsibility mandates accelerate phase-out timelines for single-use plastic wine sleeves. FDA indirect food contact material standards govern import specifications for retail channel distribution. Napa Valley and Sonoma wine tourism clusters drive reusable insulated format demand for direct-to-consumer subscriptions.
Wine Bags Market Competitive Environment
Premium-margin players sit above commodity-margin players across material certification and thermal performance dimensions. The vendor base separates into three tiers: vertically integrated producers with captive fiber sourcing, specialized regional fabricators, and trading-house intermediaries lacking lifecycle assessment capability. Two dominant competitive moves are reshaping positioning: consolidation of tanning partnerships within EU jurisdiction to reduce REACH audit exposure, and establishment of West Coast circular collection infrastructure to capture California SB 54 first-mover advantage.
Specialists in thermal insulation technology occupy the performance gift segment, with BUILT NY representing this archetype through temperature-control engineering. Wine Box Company Limited anchors UK market positioning through corrugated and wooden box format specialization. Richie Bags exemplifies the eco-conscious European supplier archetype, competing on jute and cotton craftsmanship for sustainability-driven procurement.
| Leading Market Players |
|---|
| Wine Box Company Limited |
| BUILT NY |
| Acorn Paper Products Company |
| Initi Bag Manufacturer |
| Richie Bags |
| Nangfa Manufacturing |
| DM Pack |
| PaperPak |
| Yiwu Youbai Packing |
| Others |
Value Chain & Pricing Dynamics
Phase-change material integration into insulated bag walls is compressing cost economics for thermal performance tiers while simultaneously concentrating supply leverage among manufacturers with captive gel-pack sourcing. REACH Annex XVII compliance investments are reshaping supplier selection criteria, with certified EU textile chains commanding premium positioning against Asian import alternatives.
Pricing Analysis
Value-based pricing anchored to temperature-control performance and carbon-footprint certification now separates premium insulated formats from commodity sleeves. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and thermal specification intensity. Pricing pressure stems from corrugated paperboard substitution in UK distributor procurement, compressing margins on wooden box formats. Corporate gifting buyers in France and Switzerland demonstrate lowest price sensitivity, prioritizing Scope 3 documentation over unit cost.
Supply Chain Analysis
Workforce availability constraints in Bangladesh and Indian jute-processing regions are elevating raw material timing risk for eco-positioned bag producers. Manufacturing concentrates in China, India, and Bangladesh for textile substrates, with EU-based tanning partnerships consolidating for REACH chromium VI compliance. Supply chains draw from monsoon-dependent jute harvests, cotton cultivation belts, and petrochemical feedstocks for synthetic insulation layers. Single-source vulnerability sits with Bangladeshi jute supply for string-closure formats. Distribution runs through specialty wine retail channels, direct-to-consumer wine club logistics, and hospitality procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as REACH compliance overhead and thermal R&D investment requirements force trading-house intermediaries without lifecycle assessment capability toward exit.
For Market Incumbents: Hedge margin compression by consolidating tanning partnerships within EU jurisdiction to reduce customs clearance friction and audit exposure. Prioritize backward integration into phase-change material sourcing to defend thermal performance tier positioning against corrugated substitution threats. For New Entrants and Emerging Players: The mid-tier price-point gap between premium leather hospitality formats and economy plastic sleeves offers white-space entry through magnetic-closure cloth hybrids. Target German and Dutch direct-to-consumer wine clubs with temperature-buffering specifications. Pursue carbon-footprint certification as the primary go-to-market differentiator against uncertified Asian imports. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated packaging conglomerates seeking EU regulatory compliance capabilities. Long-term viability favors producers with captive fiber sourcing and in-house lifecycle assessment infrastructure over trading-house intermediaries. Watch for California SB 54 circular collection infrastructure deployment as inflection signal for West Coast market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| EU Tanning Partnership Consolidation | REACH Annex XVII chromium VI compliance reduces customs friction for Italian leather goods manufacturers. |
| Phase-Change Material Integration | Temperature-buffering gel packs extend safe transit windows for German and Dutch wine club contracts. |
| Carbon Footprint Certification Investment | Scope 3 documentation meets Swiss and French corporate gifting procurement mandates. |
| West Coast Circular Collection Infrastructure | California SB 54 extended producer responsibility creates first-mover advantage for market access. |
| Magnetic Closure Engineering Development | Snap-fit polymer integration with cloth substrates enables single-hand operation for Italian restaurant tableside service. |
Study Parameters
Trade publications, customs records, and EU regulatory filings formed the secondary backbone for supply chain mapping and compliance timeline tracking. Primary interviews with specialty wine retailers, hospitality procurement directors, wine club logistics managers, and textile certification auditors combined with secondary validation. Bottom-up and top-down triangulation anchored volume estimates across material type, closure mechanism, and end-user channel dimensions.
Bottom-up modeling built from individual country-level wine tourism corridor demand, wine club subscription growth patterns, and hospitality format adoption curves. Segmentation dimensions included material substrate, thermal performance tier, closure engineering complexity, and regional regulatory cluster. CAGRs derived from weighted average of historical volume trajectories and projected compliance-driven substitution elasticities. Forecast inputs incorporated REACH enforcement timelines, California SB 54 implementation phases, and phase-change material cost curves.
Inputs from regulatory databases and trade association disclosures were available through the study window; gaps in real-time wine club procurement data introduce uncertainty bands around direct-to-consumer segment projections. Forecasts reflect documented assumptions regarding compliance enforcement intensity and thermal technology adoption rates. Material deviation in REACH audit frequency or jute harvest volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Beer Stabilizers Market
Alcoholic Beverages
Alcoholic Beverages Market
Alcoholic Beverages
Cigar Market
Alcoholic Beverages
Gluten Free Alcoholic Drinks Market
Alcoholic Beverages
Decanter Market
Alcoholic Beverages
Woozy Bottle Market
Alcoholic Beverages
Beer Line Cooling System Market
Alcoholic Beverages
Canned Alcoholic Beverages Market
Alcoholic Beverages
Draught Beer Market
Alcoholic Beverages
Rice Wine Market
Alcoholic Beverages
France Alcohol E-Commerce Market
Alcoholic Beverages
Scotch Whisky Market
Alcoholic Beverages
India Alcohol Market
Alcoholic Beverages
Mead Beverage Market
Alcoholic Beverages
Roasted Malt Market
Alcoholic Beverages
Alcohol Market