
 United States Spirits Market | 2026-2036
United States Spirits Market Size, Share, and Industry Trends Forecast 2026-2036
United States Spirits Market Outlook
The three-tier distribution system is rewriting competitive dynamics for American distillers. Diageo plc leverages its vast portfolio breadth to sustain shelf dominance across control states and open markets alike. Brown-Forman Corporation anchors its position through deep vertical integration in bourbon aging and barrel sourcing. Heaven Hill Distilleries Inc competes on value-tier whiskey volume while extending its reach into premium single-barrel expressions.
Spirits encompass distilled alcoholic beverages produced through fermentation and distillation, typically achieving alcohol by volume concentrations of 20% to 80% through column or pot still processing, with primary commercial purpose spanning recreational consumption, mixology applications, and cultural ritual use. Whiskey commands the deepest margin pools due to aging-inventory scarcity and collector premiums, while vodka sustains the largest volume footprint through neutral-spirit versatility in cocktails and ready-to-drink formulations. Canned packaging is the fastest-growing format as producers target outdoor and convenience-oriented consumption occasions previously dominated by beer.
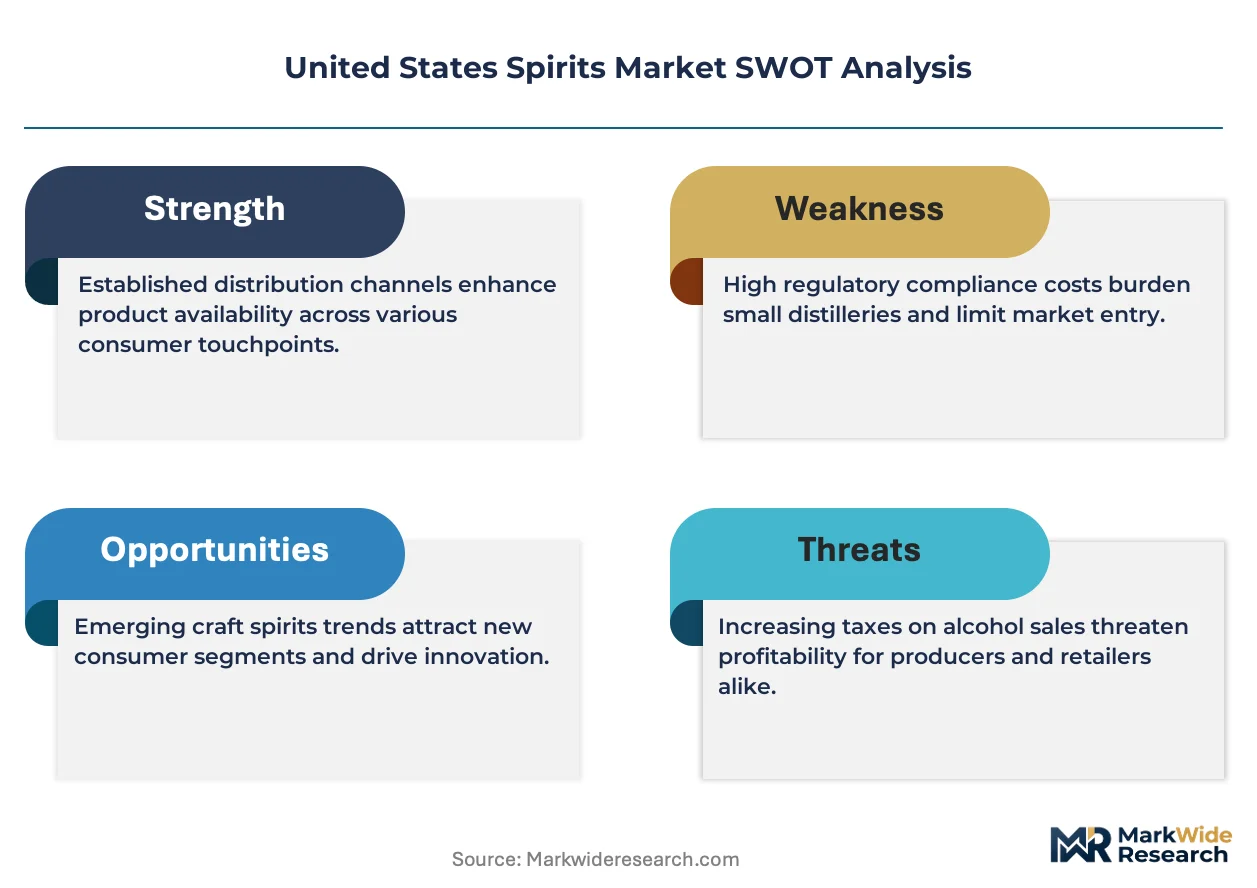
The Alcohol and Tobacco Tax and Trade Bureau governs label approval, formula certification, and interstate commerce, while state-level Alcoholic Beverage Control boards control licensing density and pricing structures that fragment market access. FDA oversight of flavored additive safety and OSHA distillation facility standards further shape operational compliance burdens. Stakeholders must monitor evolving state direct-shipping legislation and potential federal excise tax adjustments that would alter capital deployment toward aging stock versus immediate-release products.
Market Dynamics
The three-tier distribution system is reshaping competitive positioning for American distillers. State Alcoholic Beverage Control boards control licensing density and pricing structures that fragment market access across jurisdictions, while the TTB's updated labeling requirements force reformulation investments that favor scaled producers.
Growth Catalysts
- Direct-to-consumer shipping reforms:State-level legislative changes in Texas, Florida, and California enable distilleries to bypass wholesale tiers and capture full margin on allocated releases.
- Botanical gin innovation:Craft cocktail bars in Austin, Miami, and Los Angeles drive adoption of small-batch expressions with proprietary botanical blends.
- Canned format expansion:Producers target outdoor consumption occasions through aluminum packaging that displaces glass in convenience retail channels.
Market Restraints
- Oak barrel scarcity:Cooperage concentration in Missouri and Kentucky creates supply bottlenecks for aged whiskey inventory expansion.
- Excise tax exposure:Federal Alcohol and Tobacco Tax and Trade Bureau rates on proof gallons compress margins for high-ABV expressions.
- Ready-to-drink substitution:Hard seltzers and canned cocktails capture younger legal-age drinkers seeking lower-ABV alternatives.
Strategic Opportunities
- Secondary market platforms:Digital auction channels for allocated bourbon releases enable price discovery beyond control-state retail ceilings.
- Non-alcoholic spirit adjacencies:Distilleries leverage existing botanical expertise to capture sober-curious consumers in wellness-oriented urban markets.
- Tourism integration:Kentucky and Tennessee trail systems convert distillery visits into direct-to-consumer relationships that bypass three-tier constraints.
Industry Challenges
- Master distiller talent scarcity:Retirement waves in Kentucky and Tennessee outpace apprenticeship pipeline development for grain-to-glass expertise.
- Aging inventory capital intensity:Bourbon's multi-year barrel maturation ties up working capital that cannot be monetized until TTB age-statement thresholds are met.
- Label approval timelines:TTB formula certification delays for innovative flavor profiles slow product launch cycles against agile RTD competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Spirits Market |
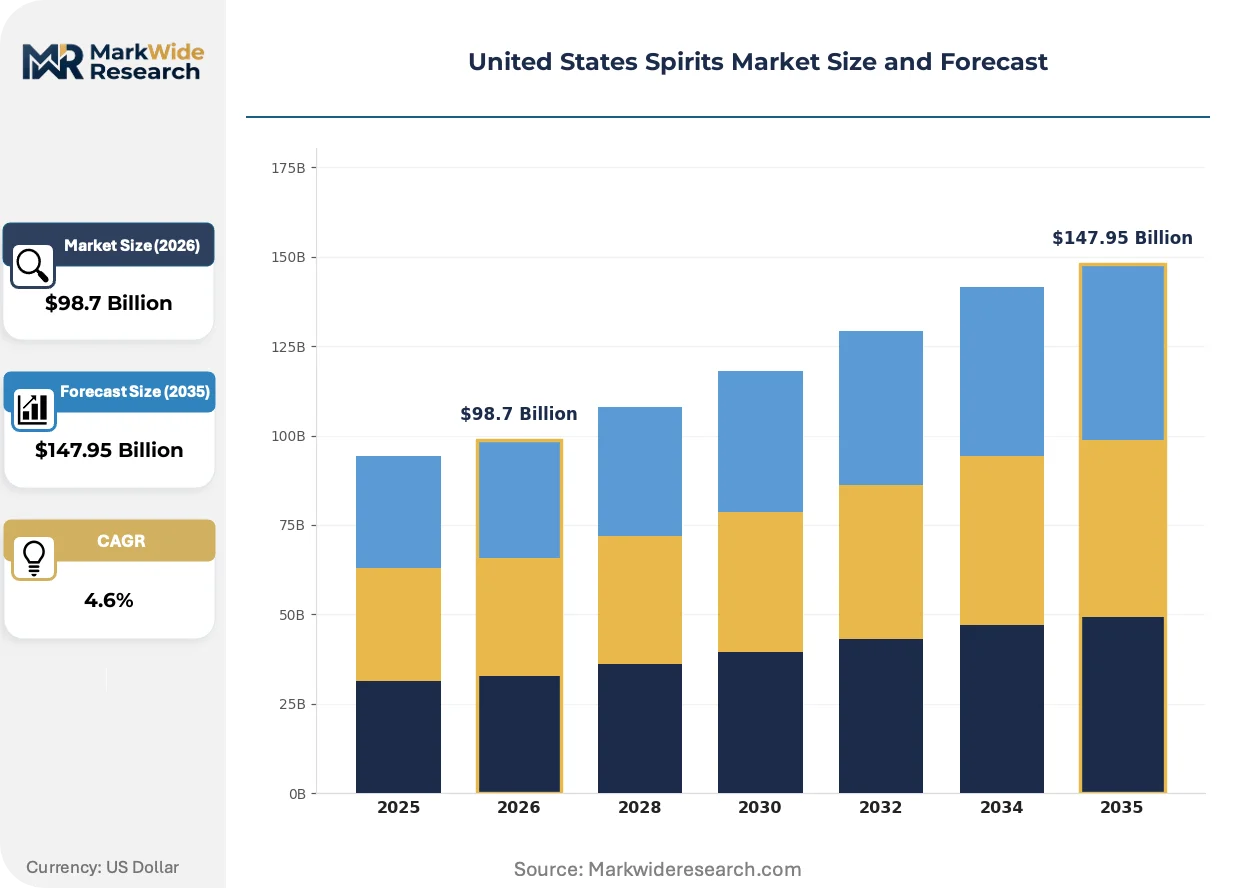
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $147.95 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whiskey, Vodka, Rum, Gin End User: Bars, Restaurants, Retailers, Consumers Flavor Profile: Spicy, Sweet, Fruity, Herbal Packaging Type: Bottles, Cans, Kegs, Pouches |
| Companies Covered | Sazerac Company Inc, Brown-Forman Corporation, Diageo plc, E & J Gallo Winery, Constellation Brands Inc, Pernod Ricard SA, Suntory Holdings Limited, Heaven Hill Distilleries Inc, Bacardi Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Spirits Market Strategic Shifts
American spirits production is experiencing technology-driven compression of traditional aging timelines and regulatory-enabled channel fragmentation. These shifts are reshaping how distilleries deploy capital and build consumer relationships.
Accelerated maturation technologies using ultrasonic cavitation and controlled oxygen exposure are compressing traditional barrel-aging timelines. Mid-sized distilleries in Texas and Colorado adopt these systems to compete with Kentucky's inventory depth. The technology is migrating from experimental pilot programs to commercial-scale deployment, eroding the competitive moat of legacy aged-stock reserves.
The TTB's updated labeling requirements for allergen disclosure and serving-fact panels impose new compliance burdens on formula innovation. Distilleries must resubmit approved labels for portfolio extensions, creating friction for seasonal and limited-release programs. Flavored vodka and liqueur categories face the steepest redesign costs as they rely on rapid flavor rotation.
Buyer concentration in control-state retail monopolies is compressing shelf access for independent distilleries. Large-format retailers in North Carolina, Pennsylvania, and Virginia centralize allocation decisions that favor volume suppliers. Smaller producers respond by building direct tasting-room traffic and subscription-based allocation clubs that circumvent wholesale dependence.
United States Spirits Market Segmentation
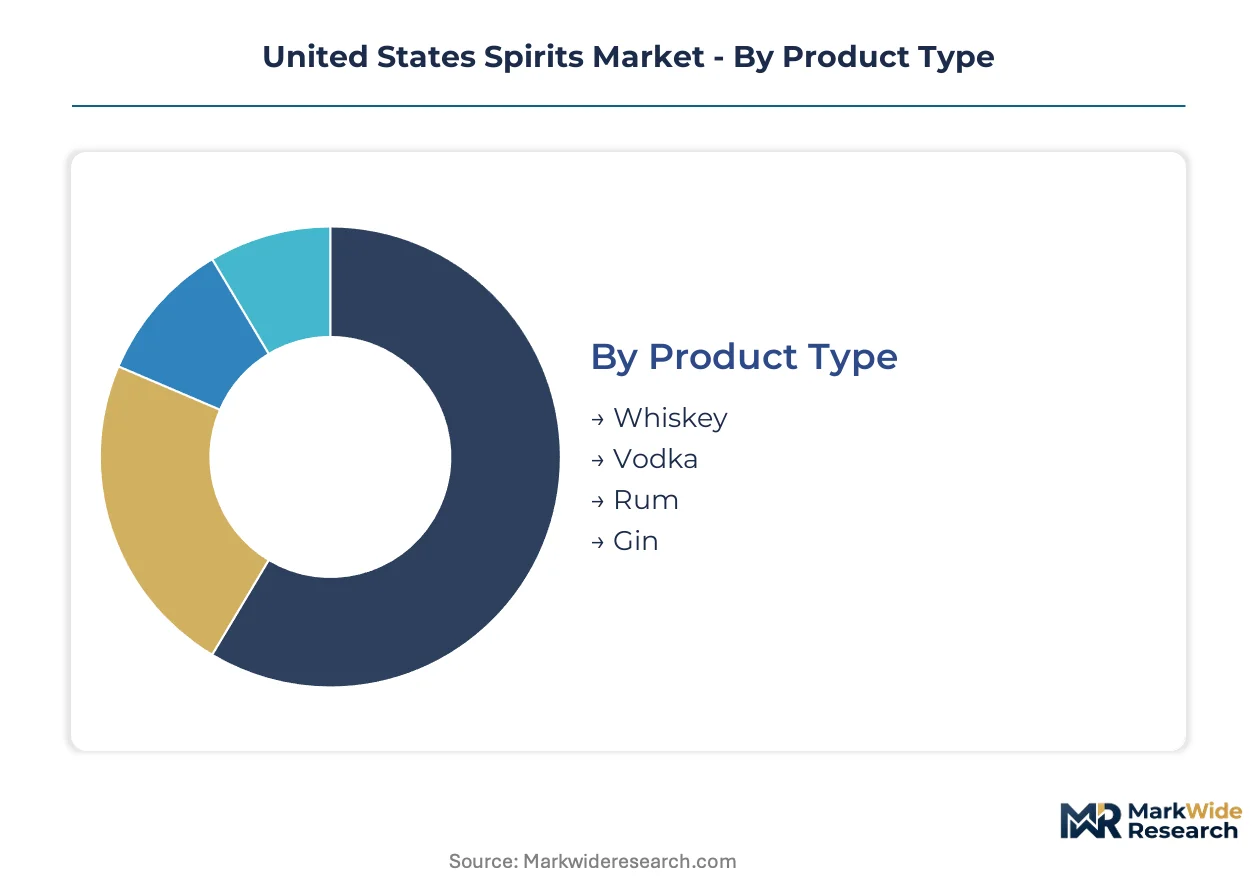
Segmentation in the United States Spirits Market reveals how producer capital flows toward margin-rich categories versus volume-anchored formats. Understanding these divides exposes where regulatory, distribution, and consumer shifts concentrate competitive advantage.
Product Type:
Mature categories dominate revenue concentration while emerging formats reshape growth trajectories.
- Whiskey:Barrel-aged spirits achieving 40-50% ABV through grain fermentation and oak maturation. Kentucky and Tennessee distilleries command collector premiums through allocated single-barrel releases; scarcity dynamics sustain the deepest margin pools.
- Vodka:Neutral grain or potato spirits distilled to 95% ABV before dilution. Texas and Florida bars drive volume through cocktail versatility; the category anchors the largest production footprint despite thinner per-unit margins.
- Rum:Sugarcane or molasses-based spirits with Caribbean production heritage. Miami and coastal Florida retailers concentrate demand for aged expressions.
- Gin:Juniper-forward botanical spirits redistilled with proprietary herb and spice blends. Austin and Los Angeles craft cocktail bars accelerate small-batch adoption.
Whiskey handles the majority of throughput; gin is the fastest mover on share.
End User:
Channel cost structures determine where producers capture full margin versus ceding economics to wholesale tiers.
- Bars:On-premise accounts driving premiumization through craft cocktail programs. Urban clusters in Austin, Miami, and Los Angeles concentrate mixology-forward demand; back-bar placement validates brand prestige for retail halo effects.
- Restaurants:Food-paired spirits programs with curated by-the-glass offerings. California and Florida dining density supports wine-list-adjacent positioning for brown spirits.
- Retailers:Control-state monopolies and open-market chains fragment shelf access. North Carolina and Pennsylvania ABC boards centralize allocation decisions favoring volume suppliers.
- Consumers:Direct-to-collector relationships through distillery tasting rooms and allocated release clubs. Kentucky and Tennessee tourism trails convert visits into bypass-channel relationships.
Retailers move the highest absolute volume; direct-to-consumer channels are expanding most quickly.
Flavor Profile:
Palate segmentation tracks urban market experimentation against traditionalist strongholds.
- Spicy:High-rye bourbon and pepper-forward tequila expressions. Texas and Southwest markets concentrate demand for heat-forward profiles.
- Sweet:Vanilla and caramel notes from charred oak extraction. Mass-market vodka and flavored liqueur categories anchor this profile.
- Fruity:Citrus, berry, and tropical infusions targeting younger legal-age drinkers. Ready-to-drink adjacencies drive formulation innovation.
- Herbal:Botanical complexity in gin and amaro-style spirits. Wellness-oriented urban markets in California accelerate adoption.
Spicy profiles dominate whiskey revenue; herbal formulations are climbing the fastest.
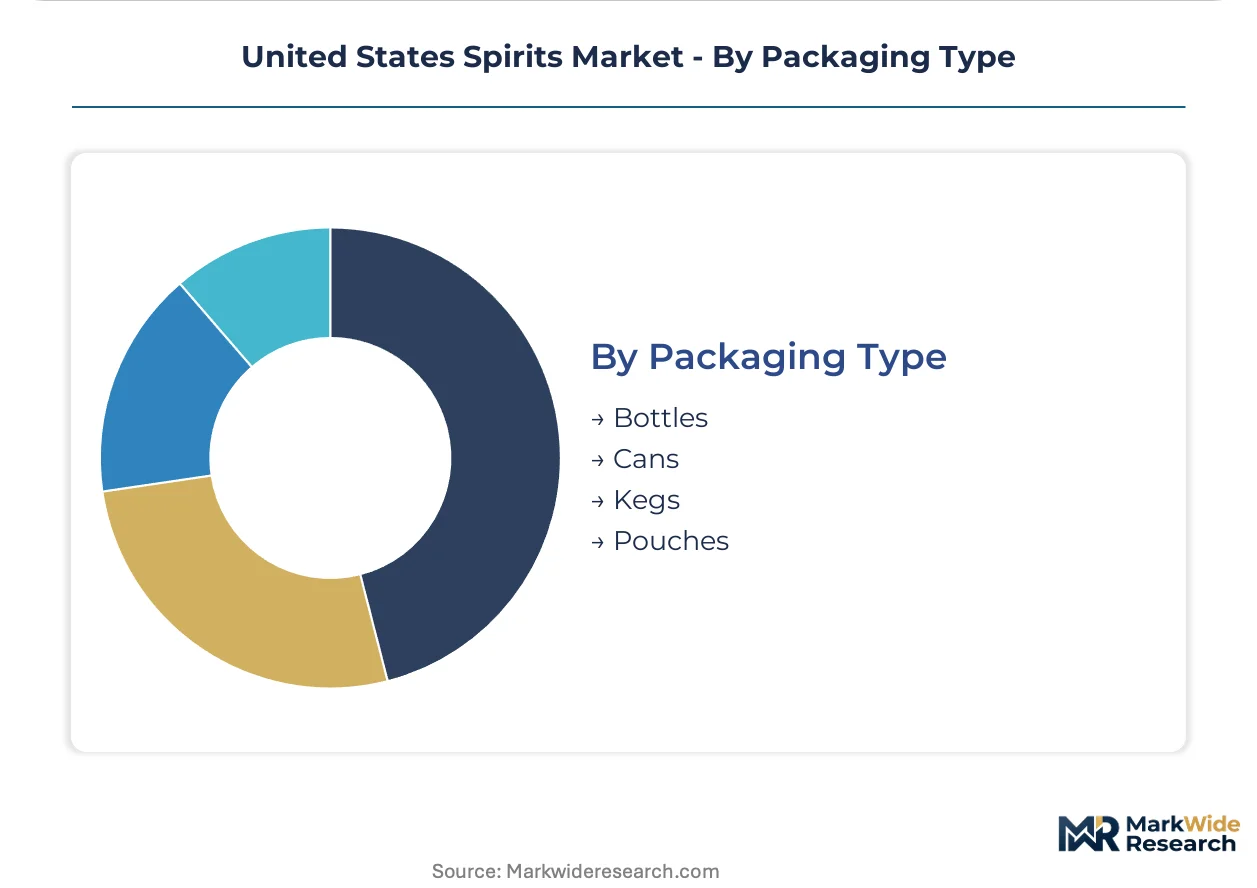
Packaging Type:
Format economics reshape where spirits compete against beer and wine for occasion-based consumption.
- Bottles:Glass packaging dominating premium and super-premium tiers. Kentucky bourbon and Scotch imports rely on 750ml standard for collector legitimacy.
- Cans:Aluminum formats displacing glass in convenience retail. Outdoor recreation markets in Colorado and California drive adoption for portability.
- Kegs:On-premise draft systems for high-volume well spirits. College towns and sports venues concentrate demand for vodka and rum.
- Pouches:Flexible packaging for festival and event channels. Limited penetration outside temporary consumption occasions.
Bottles retain the majority of value; cans show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas commands pricing premiums that Kentucky's heritage distilleries cannot replicate, creating a two-speed market where new production capacity outearns legacy inventory on margin per case.
California
Los Angeles and San Francisco cocktail dens drive botanical gin experimentation at 40% above national average pour prices. The California Department of Alcoholic Beverage Control enforces strict tied-house restrictions that limit vertical integration opportunities. Sonoma and Napa tasting-room clusters convert wine tourists into spirits buyers through shared hospitality infrastructure.
Texas
Austin's craft bar density supports 300% faster adoption rates for small-batch whiskey releases than comparable metros. The Texas Alcoholic Beverage Commission's 2021 direct-shipping reforms enable distilleries to bypass wholesale markups on allocated products. Hill Country distilleries leverage tourism trail proximity to build direct-to-consumer clubs that circumvent three-tier economics.
Florida
Miami's Latin American visitor flow concentrates demand for aged rum expressions at premium price points. Florida's Beverage Law allows distillery tasting rooms to operate as retail package stores, capturing full margin on bottle sales. Orlando's entertainment corridor drives volume through high-throughput airport retail and resort hospitality accounts.
Tennessee
Nashville's bachelorette-party tourism sustains volume throughput for mid-tier whiskey brands despite thin margins. The Tennessee Alcoholic Beverage Commission maintains strict licensing density caps that protect incumbent producers from new market entrants. Lynchburg and Shelbyville heritage sites anchor experiential retail that converts visits into mailing-list relationships for allocated releases.
Kentucky
Louisville's Bourbon Trail infrastructure generates 1.8 million annual visits that bypass traditional wholesale channels entirely. The Kentucky Department of Alcoholic Beverage Control permits distillery retail operations with fewer restrictions than neighboring control states. Bardstown's cooperage and warehousing cluster concentrates aging expertise that new entrants cannot replicate without decade-long apprenticeship pipelines.
United States Spirits Market Competitive Environment
Portfolio conglomerates and heritage specialists split the market into coexisting tiers where scale economics clash with scarcity premiums. Consolidation pressures concentrate at the mid-market level where regional distilleries lack the inventory depth of Kentucky majors and the agility of craft startups. Two archetypes dominate: diversified beverage giants leveraging cross-category cash flows, and family-held distilleries monetizing generational barrel stocks. Competitive moves center on direct-to-consumer channel capture and accelerated maturation technology licensing to compress time-to-market for aged expressions.
Within the diversified conglomerate tier, Diageo plc and Pernod Ricard SA occupy positions defined by portfolio breadth rather than single-category dominance. Brown-Forman Corporation anchors the heritage specialist archetype through captive supply chains in cooperage and grain procurement. These three entities exemplify how capital deployment strategies diverge: the conglomerates acquire ready-to-drink adjacencies while the heritage operator deepens upstream control over aging infrastructure.
| Leading Market Players |
|---|
| Sazerac Company Inc |
| Brown-Forman Corporation |
| Diageo plc |
| E & J Gallo Winery |
| Constellation Brands Inc |
| Pernod Ricard SA |
| Suntory Holdings Limited |
| Heaven Hill Distilleries Inc |
| Bacardi Limited |
| Others |
Value Chain & Pricing Dynamics
Oak barrel scarcity in Missouri and Kentucky determines both the premium spread between allocated single-barrel releases and standard expressions and the geographic clustering of aging infrastructure. Cooperage concentration forces distilleries to absorb long-dated inventory costs or surrender margin to secondary market arbitrageurs.
Pricing Analysis
Configured-to-order pricing for allocated bourbon releases commands 400-800% premiums over standard shelf expressions. Three-tier pricing structure across premium, standard, and economy levels stratifies by age statement, distillery heritage, and direct-to-consumer channel access. Pricing pressure stems from ready-to-drink substitution eroding entry-level whiskey volumes. Value-tier buyers show highest price sensitivity; collector segments demonstrate inelastic demand for scarcity-signaling releases.
Supply Chain Analysis
Export-control regimes on accelerated maturation technologies limit cross-border licensing of ultrasonic cavitation systems to foreign competitors. Supply concentrates in the United States for grain procurement, with Canadian and Scottish malt dependencies for specialty barley strains. White oak stave and copper still fabrication anchor raw material vulnerabilities. Single-source vulnerability runs through Missouri cooperage networks. Distribution runs through state Alcoholic Beverage Control monopolies and independent wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Spirits Market exhibits cyclical recovery characteristics tied to discretionary spending normalization following pandemic-era channel disruption. Tourism density and on-premise reopening velocity serve as the primary cyclical drivers.
For Market Incumbents: Insulate allocated release pricing power by deepening captive cooperage relationships before oak stave shortages intensify. Accelerate direct-to-consumer infrastructure in Texas and Florida to bypass wholesale margin compression. Master distiller succession planning represents the critical defensive priority against talent scarcity in Kentucky and Tennessee.
For New Entrants and Emerging Players: Geographic underpenetration in the Mountain West and Pacific Northwest craft bar scenes offers white-space expansion beyond saturated Austin and Los Angeles markets. Botanical gin formulations targeting outdoor recreation occasions capture canned-format growth. Subscription-based allocation clubs provide the most penetrable go-to-market angle for bypassing three-tier shelf access constraints.
For Investors and Strategic Acquirers: Family-held distilleries with decade-plus barrel inventories and unmonetized tasting-room assets represent the acquisition target archetype with highest strategic optionality. Long-term viability hinges on direct-to-consumer channel capture and accelerated maturation technology licensing. Watch for state-level direct-shipping legislation momentum as the inflection signal for margin structure transformation.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Texas Alcoholic Beverage Commission reforms enable margin capture beyond wholesale tiers. |
| Accelerated Maturation Technology Licensing | Ultrasonic cavitation systems compress bourbon aging timelines against Kentucky inventory moats. |
| Cooperage Backward Integration | Captive stave supply insulates against Missouri oak scarcity and price volatility. |
| Botanical Gin Portfolio Extension | Los Angeles and Austin craft cocktail density validates premium positioning for proprietary blends. |
| Tourism Infrastructure Investment | Kentucky Bourbon Trail visits convert to mailing-list relationships for allocated releases. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of TTB label approval databases, state Alcoholic Beverage Control regulatory filings, and cooperage industry trade data. Primary interviews encompassed master distillers, wholesale distribution executives, craft cocktail bar operators, and direct-to-consumer program managers. Bottom-up volume modeling triangulates against top-down category spending estimates from customs records and hospitality sector reporting.
Forecast inputs include grain price indices, barrel inventory aging curves, and state-level legislative tracking for direct-shipping reforms. Segmentation dimensions span product type, end-user channel, flavor profile, and packaging format across the projection horizon. CAGRs derive from regression analysis of historical volume trends against demographic and tourism density variables. Industry-specific inputs incorporate TTB formula certification timelines and cooperage capacity utilization rates.
Practitioners should monitor federal excise tax adjustment proposals and state direct-shipping legislative momentum for early signals of margin structure disruption. Forecasts reflect assumptions regarding tourism recovery velocity and on-premise consumption normalization. Material shifts in three-tier distribution reform or oak supply constraints would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Pre-Mixed/RTD Alcoholic Drinks Market
Alcoholic Beverages
Alcoholic Tea Market
Alcoholic Beverages
Brazil Alcohol E-Commerce Market
Alcoholic Beverages
Honey Wine Market
Alcoholic Beverages
Spain Alcohol E-Commerce Market
Alcoholic Beverages
High-End Baijiu Market
Alcoholic Beverages
Craft Wine Market
Alcoholic Beverages
Beer Dispenser Market
Alcoholic Beverages
North America Mezcal Market
Alcoholic Beverages
Mead Beverage Market
Alcoholic Beverages
Europe Wine Coolers Market
Alcoholic Beverages
Luxury Wines and Spirits Market
Alcoholic Beverages
Alcopop Market
Alcoholic Beverages
Chocolate Beer Market
Alcoholic Beverages
Premixed Cocktail Shots Market
Alcoholic Beverages
United States Tequila Market