
 Chestnut Market | 2026-2036
Chestnut Market Size, Share, and Industry Trends Forecast 2026-2036
Chestnut Market Intelligence
Modular retail packs combining fresh and roasted chestnuts in seasonal gift configurations is recalibrating how European and Asian buyers evaluate value. Roland Foods leverages its import infrastructure to sustain year-round North American availability. Qinhuangdao Yanshan Chestnut anchors China's export-grade supply through integrated orchard-to-processing operations. Windmill Organics differentiates via certified organic positioning across UK and continental European channels.
Chestnuts are edible nuts from Castanea species trees, containing approximately 50% water and 40% carbohydrates by fresh weight, with primary commercial use as a gluten-free flour source and whole roasted snack. Fresh chestnuts dominate volume trade but carry perishability constraints that compress margin realization. Roasted chestnuts capture premium pricing through convenience positioning in ready-to-eat snack channels. Processed chestnuts, including purees and flours, lead growth in bakery and confectionery applications where manufacturers substitute for wheat and almond inputs.
EFSA mycotoxin thresholds and EU food labeling rules shape import acceptance criteria for non-European suppliers. China's SAMR enforces GB standards for dried nut moisture content and additive limits that govern domestic processing scale. USDA grading standards for whole chestnuts influence US procurement patterns among food service distributors. Stakeholders must monitor evolving allergen labeling requirements across multiple jurisdictions while calibrating sourcing strategies between fresh seasonal peaks and processed product stability.
Market Dynamics
EFSA mycotoxin threshold tightening is compressing acceptable import windows for non-European chestnut suppliers, forcing processors to reconfigure sourcing calendars and testing protocols around seasonal harvest peaks.
Growth Catalysts
- EU allergen labeling mandates:Chestnut flour gains traction as a declared allergen-free alternative in gluten-free bakery formulations across EFSA-regulated markets.
- Hebei Province processing clusters:China's integrated orchard-to-facility infrastructure under GB standards reduces post-harvest loss rates for export-grade supply.
- Roasting automation:Continuous thermal processing systems extend shelf-stable product availability beyond traditional fresh windows.
Market Restraints
- Fresh perishability:50% water content by weight limits fresh chestnut distribution radius to 72-hour cold-chain corridors.
- Single-origin concentration:Qinhuangdao Yanshan processing dominance creates supply vulnerability during regional weather events.
- Almond flour substitution:Established gluten-free supply chains for almond and coconut inputs crowd shelf-space in retail baking aisles.
Strategic Opportunities
- India FSSAI nut classification:Pending tree nut standards revision could open import channels for processed chestnut purees into confectionery applications.
- Direct-to-consumer subscription:Seasonal fresh-roasted pairings bypass wholesale margin compression in European urban markets.
- Carbon accounting integration:EU Green Deal farm-to-fork traceability requirements favor orchard-integrated processors with verifiable emission data.
Industry Challenges
- Mycotoxin testing capacity:Laboratory backlog for aflatoxin and ochratoxin A verification extends EU import clearance timelines.
- Harvest labor availability:Manual burr collection requirements clash with rural workforce migration in Chinese and Italian producing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chestnut Market |
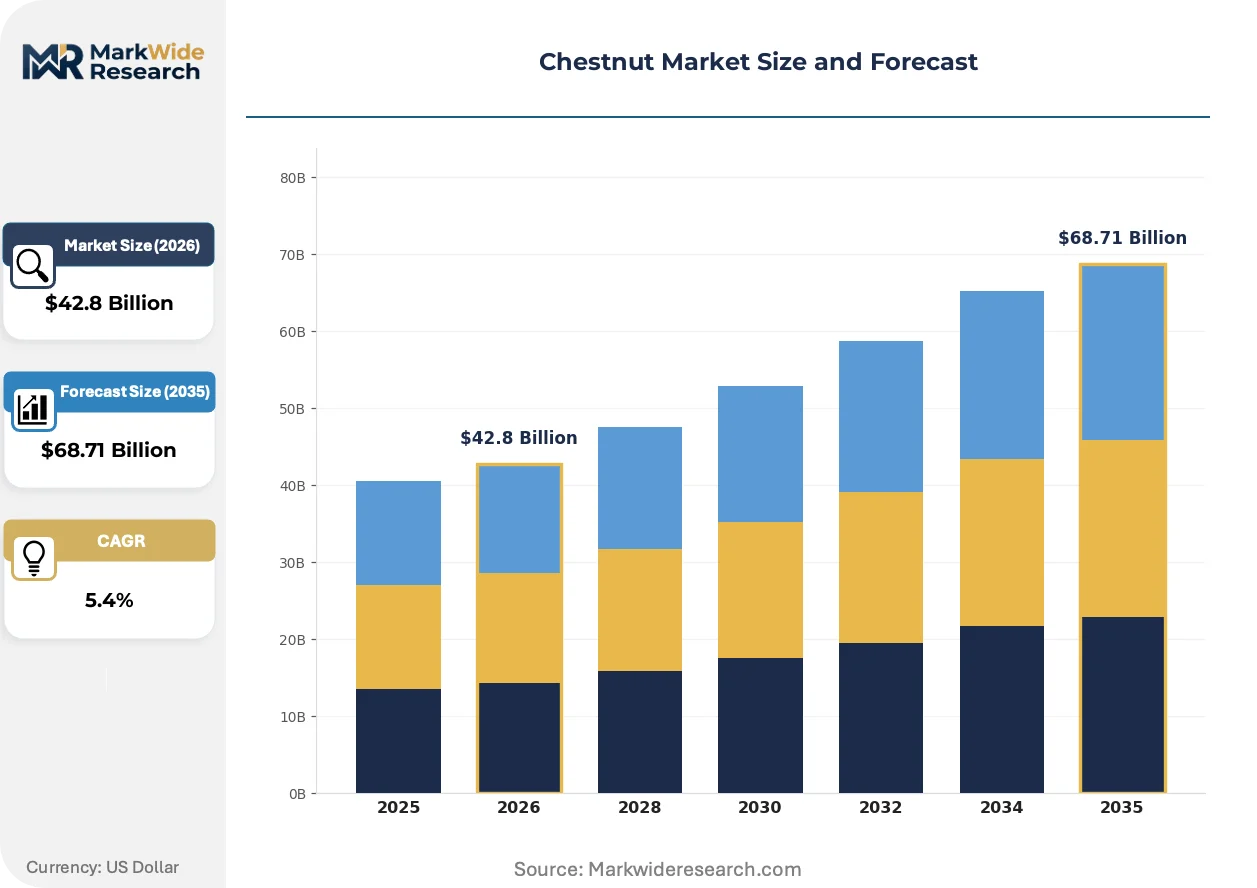
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $68.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Chestnuts, Roasted Chestnuts, Processed Chestnuts, Frozen Chestnuts, Dried Chestnuts Application: Confectionery, Bakery Products, Ready-to-Eat Snacks, Culinary Ingredients, Animal Feed Packaging Type: Plastic Bags, Paper Bags, Net Bags, Cartons, Vacuum Packs Customer Type: Food Manufacturers, Retailers, Food Service Providers, Wholesalers, Exporters |
| Companies Covered | Roland Foods, LLC., Washington Chestnut Company, Chestnut Growers, Inc., Windmill Organics Ltd, Kingfisher Foods Limited, Royal Nut Company, Conagra Foodservice, Inc., Qinhuangdao Yanshan Chestnut Co., Ltd., Route 9 Cooperative, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chestnut Market Strategic Shifts & Innovations
Processing technology and regulatory traceability are converging to restructure how chestnuts move from orchard to finished ingredient, with automation and certification protocols displacing traditional hand-sorting and paper-based provenance systems.
Modified atmosphere packaging for fresh chestnuts is modularizing how retailers manage seasonal inventory. UK and German supermarket chains now deploy shelf-ready pouches with embedded ethylene scavengers. This technology compresses the traditional wholesale-to-retail handling steps into a single direct delivery.
REACH-compliant food contact materials regulation is reshaping packaging specifications for processed chestnut exports into the European Union. Manufacturers must now submit migration testing for bisphenol alternatives in can linings. Italian and French puree suppliers have accelerated compliance timelines to maintain food service contracts.
Certification-driven procurement is fragmenting buyer-seller relationships in North American specialty food channels. Retailers now require organic and non-GMO verification as table stakes for shelf placement. This behavioral shift is most visible in US natural grocery chains where chestnut flour SKUs without third-party certification face delisting pressure.
Chestnut Market Segmentation
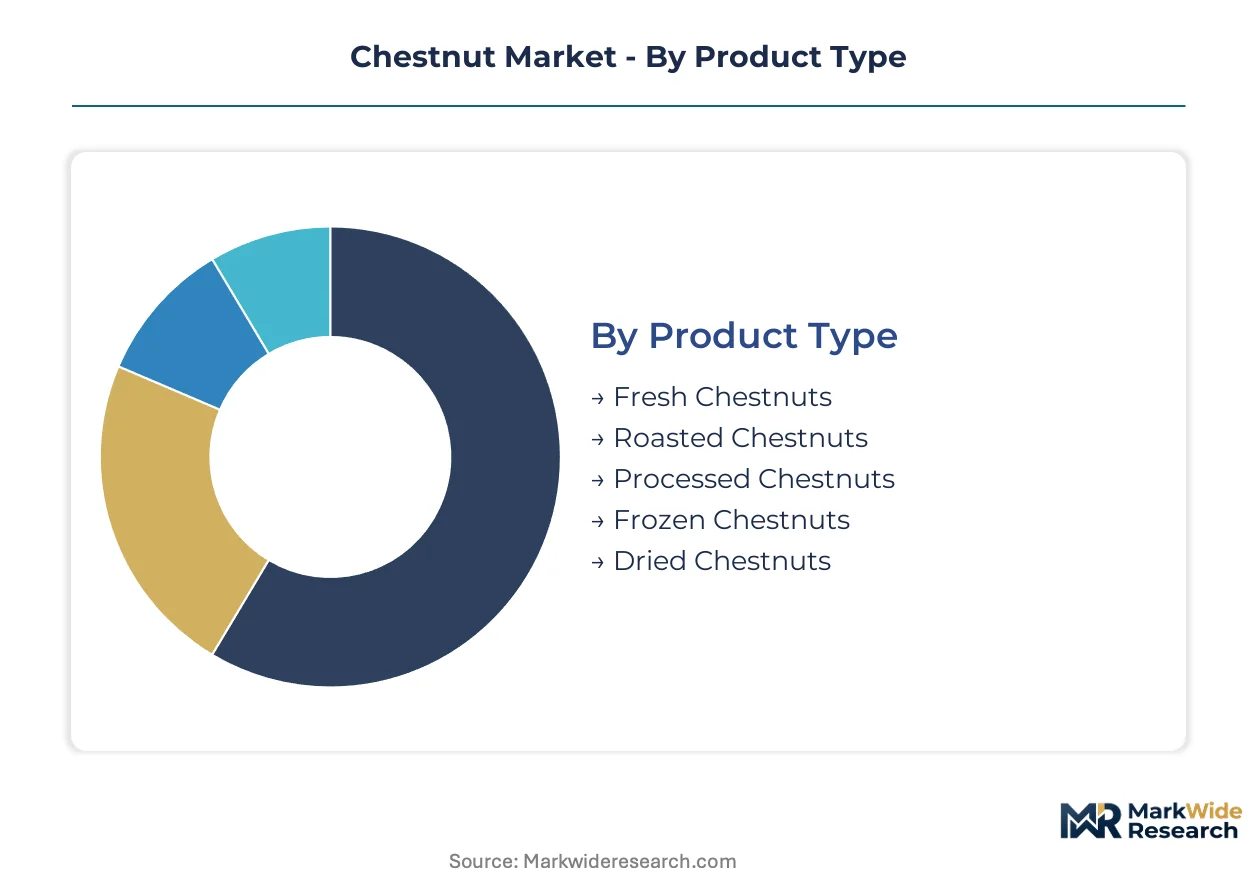
Segmentation in the chestnut market reveals how certification requirements, perishability constraints, and channel economics reshape procurement priorities across product categories. Buyers calibrate sourcing strategies against EFSA mycotoxin thresholds, USDA grading standards, and SAMR moisture specifications that vary sharply by segment.
Product Type:
Fresh chestnuts carry the heaviest certification burden under EFSA aflatoxin protocols and SAMR GB moisture standards, while processed variants face additive-limit scrutiny and frozen products navigate cold-chain compliance.
- Fresh Chestnuts:These contain approximately 50% water by weight and 40% carbohydrates, creating strict cold-chain dependencies. Demand clusters in China's Hebei Province processing corridors where Qinhuangdao Yanshan Chestnut maintains integrated orchard-to-facility operations under GB standards. Perishability compresses distribution radius to 72-hour refrigerated corridors.
- Processed Chestnuts:Purees and flours lead bakery and confectionery substitution for wheat and almond inputs. European manufacturers source these under REACH-compliant food contact material rules and EFSA allergen labeling mandates that favor declared allergen-free positioning.
- Roasted Chestnuts:Ready-to-eat positioning commands premium shelf space in urban European and Asian retail.
- Frozen Chestnuts:Extended shelf stability supports year-round North American availability through import infrastructure.
- Dried Chestnuts:Reduced moisture content aligns with long-haul export economics and traditional culinary applications.
Fresh chestnuts sit at the top of the volume ranking, with processed chestnuts climbing the fastest.
Application:
Cost tier differentiation separates commodity-scale animal feed from premium confectionery and bakery channels where organic certification commands price multiples.
- Bakery Products:Gluten-free flour substitution drives formulation shifts in EFSA-regulated markets. Chestnut flour gains traction where EU allergen labeling mandates require declared allergen-free alternatives. Roland Foods and Windmill Organics compete on certified organic positioning.
- Confectionery:Puree applications in European patisserie and Asian traditional sweets require REACH-compliant packaging migration testing. Italian and French suppliers accelerated compliance timelines to maintain food service contracts under bisphenol alternative scrutiny.
- Ready-to-Eat Snacks:Roasted formats capture convenience premiums through continuous thermal processing automation.
- Culinary Ingredients:Whole and chopped chestnuts serve restaurant and institutional procurement under USDA grading influence.
- Animal Feed:Lower-grade discards and processing byproducts feed into livestock nutrition at commodity price points.
Bakery products anchor current revenue concentration, with confectionery expanding most quickly on clean-label formulation demand.
Packaging Type:
Volume economics favor bulk cartons for industrial buyers while retail channel fragmentation drives specialty format proliferation.
- Vacuum Packs:Modified atmosphere technology with embedded ethylene scavengers enables UK and German supermarket chains to compress wholesale-to-retail handling into direct delivery. REACH-compliant materials regulation governs European export acceptance.
- Plastic Bags:Standard retail formats dominate mass-market distribution with cost-minimized specifications.
- Paper Bags:Biodegradable positioning aligns with EU Green Deal farm-to-fork traceability preferences.
- Net Bags:Seasonal gift configurations combine fresh and roasted chestnuts for European and Asian buyers.
- Cartons:Industrial-scale procurement by food manufacturers and exporters prioritizes handling efficiency.
Cartons sit at the top of the volume ranking, with vacuum packs climbing the fastest on shelf-life extension technology.
Customer Type:
Margin structure varies sharply: exporters and wholesalers operate on thin handling spreads while food manufacturers capture value-add through formulation integration.
- Food Manufacturers:Bakery and confectionery producers drive chestnut flour and puree demand under EFSA allergen labeling mandates. These buyers require third-party organic and non-GMO verification as table stakes for contract eligibility, with non-certified SKUs facing delisting pressure in US natural grocery channels.
- Retailers:UK and German supermarket chains now require shelf-ready pouches with embedded traceability data under EU Green Deal requirements. Direct-to-consumer subscription models bypass wholesale margin compression in European urban markets.
- Food Service Providers:Restaurants and institutional buyers source under USDA grading standards for whole chestnuts.
- Wholesalers:Intermediary handling concentrates in regional distribution hubs with cold-chain capabilities.
- Exporters:Integrated orchard-to-processing operations in Hebei Province reduce post-harvest loss rates for export-grade supply.
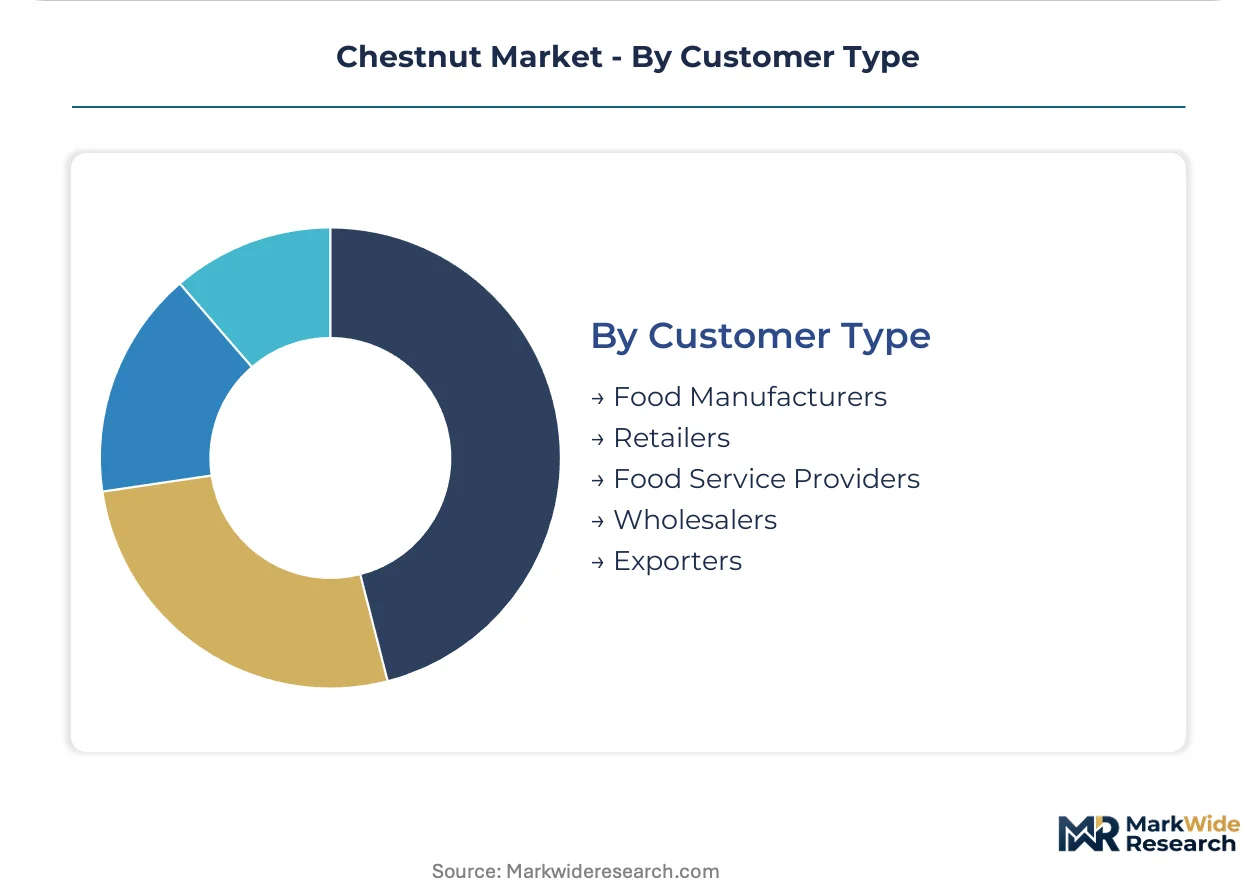
Food manufacturers sit at the top of the volume ranking, with retailers climbing the fastest on certification-driven procurement fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chestnut cultivation traces its commercial lineage to Mediterranean Europe and East Asia, where Castanea sativa and Castanea mollissima orchards supplied imperial kitchens and monastic estates centuries before industrial processing emerged.
China
Hebei Province's Qinhuangdao processing corridor anchors export-grade supply through integrated orchard-to-facility operations. SAMR enforces GB moisture standards and additive limits that govern domestic processing scale. The Yanshan mountain cluster reduces post-harvest loss rates via captive drying and sorting infrastructure.
Italy
Traditional patisserie demand and organic confectionery channels sustain premium puree and flour production. EFSA mycotoxin thresholds and REACH-compliant food contact material rules compress acceptable import windows for non-European suppliers. Piedmont and Tuscany maintain heritage roasting cooperatives alongside modern thermal processing automation.
United States
Food service distributors and natural grocery chains drive procurement under USDA grading standards for whole chestnuts. FDA allergen labeling requirements intersect with state-level organic certification programs. Appalachian and Pacific Northwest growing regions expand orchard acreage to reduce import dependency.
France
EU Green Deal farm-to-fork traceability requirements favor orchard-integrated processors with verifiable emission data. ANSM and CNIL oversight extends to supply chain digitalization tools. Corsica and Auvergne maintain artisan confiture and flour milling traditions serving Parisian restaurant supply.
United Kingdom
Supermarket chains deploy modified atmosphere packaging with embedded ethylene scavengers to compress wholesale-to-retail handling steps. FSA allergen guidance and post-Brexit import certification reshape sourcing calendars. Windmill Organics anchors certified organic positioning across UK and continental European channels.
Chestnut Market Key Industry Players
The competitive structure tilts toward vertically integrated orchard operators and import-specialist distributors rather than pure-play processors. Scale advantages concentrate in Chinese state-adjacent cooperatives with captive Hebei supply, while European and North American players compete on certification stacking and channel access. Three archetypes dominate: integrated originators controlling harvest-to-package workflows, certification-heavy brand marketers, and logistics-anchored importers sustaining year-round availability. Consolidation pressures favor backward integration into orchard ownership and strategic partnerships with retail private-label programs.
Among North American distributors, Roland Foods exemplifies the import-logistics archetype through sustained infrastructure investment, while Washington Chestnut Company and Chestnut Growers, Inc. represent domestic orchard-originators with regional processing footprints. On the certification-marketing vector, Windmill Organics occupies a position defined by organic verification requirements, and Qinhuangdao Yanshan Chestnut anchors the integrated-origin tier with captive Hebei supply chains. Route 9 Cooperative and Royal Nut Company sit within mid-scale specialist brackets focused on channel-specific format development.
| Leading Market Players |
|---|
| Roland Foods, LLC. |
| Washington Chestnut Company |
| Chestnut Growers, Inc. |
| Windmill Organics Ltd |
| Kingfisher Foods Limited |
| Royal Nut Company |
| Conagra Foodservice, Inc. |
| Qinhuangdao Yanshan Chestnut Co., Ltd. |
| Route 9 Cooperative |
| Others |
Cost & Logistics Intelligence
Hebei Province fresh chestnut spot prices cascade through three distinct valuation tiers as product moves from orchard gate through export-grade processing to retail-ready formats. Cold-chain logistics costs and EFSA mycotoxin certification requirements amplify spreads between commodity-grade feedstock and premium organic flour channels.
Pricing Analysis
Three-tier pricing structure across premium organic, standard food-grade, and commodity feedstock levels governs transaction economics. Premium-mid-economy pricing differentiation rests on organic certification under EU regulation and GB standard compliance tier. Cost compression in standard food-grade tiers is intensifying because roasting automation investments amortize across shorter seasonal windows. Animal feed buyers exhibit highest price sensitivity while European confectionery manufacturers absorb certification premiums for allergen-free positioning.
Supply Chain Analysis
Domestic-content mandates under China's GB standards and EU Green Deal farm-to-fork traceability requirements are reshaping sourcing toward orchard-integrated processors with verifiable emission data. Geographic supply concentration centers on China, Italy, and the United States as primary production clusters. Raw material dependencies draw from Castanea mollissima and Castanea sativa cultivation, seasonal labor pools, and REACH-compliant packaging inputs. Single-origin concentration in Hebei Province creates supply vulnerability during regional weather events. Distribution runs through integrated orchard-to-facility operators and import-specialist distributors sustaining year-round availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chestnut market functions as a stable compounder anchored by gluten-free formulation substitution in EFSA-regulated bakery channels. Clean-label demand and allergen-free positioning sustain pricing power across economic cycles.
For Market Incumbents: Anchor backward integration into Hebei Province orchard ownership to secure captive supply against regional weather volatility. Deepen certification stacking under EU organic and non-GMO verification to defend shelf placement in US natural grocery channels against almond flour substitution pressure. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting European urban markets to bypass wholesale margin compression. Target India's pending FSSAI tree nut standards revision for processed puree entry into confectionery applications where established gluten-free supply chains remain underpenetrated. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated originators controlling harvest-to-package workflows in Hebei Province with captive drying and sorting infrastructure. Five-to-ten year viability favors processors with verifiable carbon accounting data aligned with EU Green Deal requirements. Monitor EFSA mycotoxin threshold tightening as inflection indicator for laboratory testing capacity investments.| Strategic Initiative | Industry Significance |
|---|---|
| Orchard Ownership Integration | Captive Hebei supply reduces post-harvest loss exposure under SAMR GB moisture standards. |
| Certification Stacking Investment | Organic and non-GMO verification defends retail placement against delisting pressure in US natural grocery channels. |
| Roasting Automation Deployment | Continuous thermal processing extends shelf-stable availability beyond traditional fresh windows. |
| Direct-to-Consumer Channel Launch | Subscription models bypass wholesale margin compression in European urban markets. |
| Carbon Accounting Integration | Verifiable emission data aligns procurement with EU Green Deal farm-to-fork traceability mandates. |
Research Approach
Direct dialogue with chestnut orchard operators, food manufacturing procurement leads, EFSA regulatory affairs specialists, and cold-chain logistics providers grounds qualitative findings. Secondary validation draws from SAMR GB standard filings, EU REACH compliance databases, USDA grading bulletins, and customs trade records. Bottom-up orchard yield modeling and top-down bakery ingredient demand estimation enable triangulation across independent analytical paths.
Bottom-up volume construction aggregates orchard-level production estimates across Hebei Province, Italian Piedmont, and US Appalachian growing regions. Top-down demand calibration tracks bakery and confectionery formulation substitution rates, cold-chain distribution capacity, and retail SKU proliferation. Segmentation dimensions span product type, application channel, packaging format, and customer archetype. CAGRs derive from trend extrapolation of gluten-free flour adoption curves and allergen-labeling regulatory momentum.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA mycotoxin threshold revisions and Hebei Province weather disruption scenarios. Projections reflect documented assumptions around roasting automation adoption and India FSSAI regulatory timeline progression. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Bambara Beans Market
Nuts and Seeds
Tree Nut Allergy Market
Nuts and Seeds
Betel Nuts Market
Nuts and Seeds
Baru Nuts Market
Nuts and Seeds
United States Nuts Market
Nuts and Seeds
India Processed Cashew Market
Nuts and Seeds
Maca Market
Nuts and Seeds
Nuts and Nutmeals Market
Nuts and Seeds
Fat Free Peanut Butter Market
Nuts and Seeds
Almond with Shell Snack Market
Nuts and Seeds
Almond Products Market
Nuts and Seeds
Dry Fruits Market
Nuts and Seeds
Apricot Kernel Powder Market
Nuts and Seeds
North America Peanut Butter Market
Nuts and Seeds
Reduced Fat Peanut Butter Market
Nuts and Seeds
Walnut Market