
 Premium Spirit Market | 2026-2036
Premium Spirit Market Size, Share, and Industry Trends Forecast 2026-2036
Premium Spirit Market Intelligence
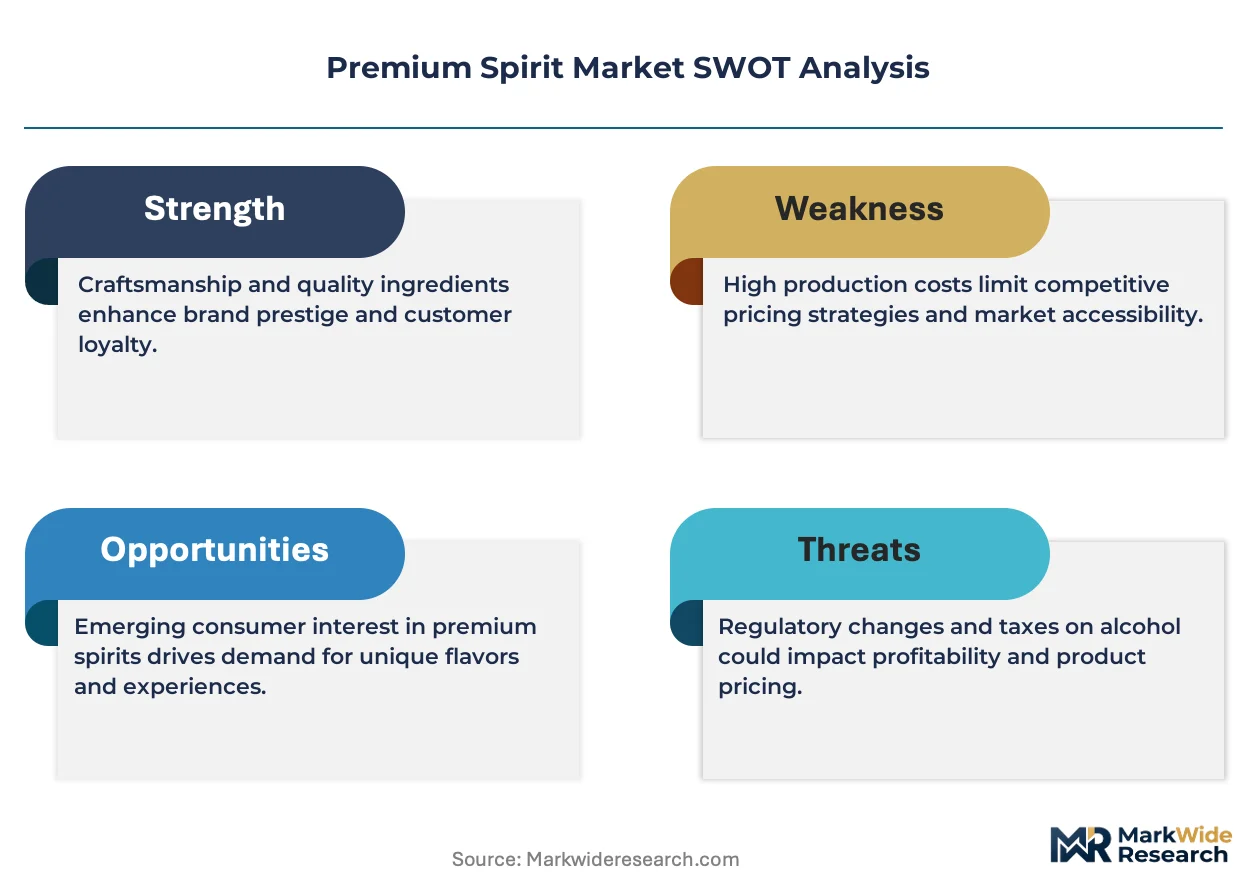
The European Union's Corporate Sustainability Reporting Directive (CSRD) is hardening consumer and investor expectations for transparent sourcing and production methods. Diageo PLC leverages its extensive global distribution network to introduce sustainable packaging initiatives across multiple brands. LVMH Moet Hennessy differentiates through its portfolio of prestige brands, emphasizing heritage and terroir-driven production. Pernod Ricard SA positions its portfolio to capture demand for both established luxury labels and innovative craft-style spirits.
Premium spirits are defined by superior raw materials, specific aging or distillation processes, and often adherence to strict geographical indications. They serve discerning consumers in on-trade and premium retail channels, justifying higher price points through quality and provenance. Whiskey, including single malts and aged bourbons, anchors value creation among all product types. The Ultra Premium and Prestige price tiers exhibit significant growth, driven by consumer demand for exclusivity and craftsmanship.
Marketing and labeling standards are governed by bodies such as the US Alcohol and Tobacco Tax and Trade Bureau (TTB) and the European Food Safety Authority (EFSA). These regulations dictate everything from age-gating in advertising to the legal definitions of spirit categories like 'Scotch Whisky' or 'Cognac'. Navigating the complex patchwork of international tariffs and local distribution laws remains a critical strategic challenge for brand owners.
Market Dynamics
A structural tension between global brand scalability and consumer demand for hyper-local provenance defines the premium spirit market. This forces producers to balance standardized luxury messaging with authentic, terroir-driven narratives for craft and small-batch offerings, shaping investment in both marketing and supply chains.
Growth Catalysts
- On-Trade Channel Expansion:Demand from luxury hotels and high-end cocktail bars in global cities like New York, London, and Shanghai elevates consumption, linking premium spirits to aspirational lifestyle experiences and justifying higher price points.
- Sustainable Packaging Mandates:The EU Green Deal’s circular economy action plan encourages innovation in lighter glass bottles and the use of recycled materials, creating a preference for brands demonstrating environmental responsibility through their packaging choices.
- Craft and Terroir Emphasis:A consumer shift towards products with demonstrable provenance and unique production methods, such as small-batch bourbons and single-estate tequilas, drives value creation and category expansion beyond traditional labels.
Market Restraints
- Complex Regulatory Patchwork:Navigating disparate labeling and marketing rules from bodies like the US TTB and the European Food Safety Authority (EFSA) increases compliance costs and slows market entry for new products.
- Raw Material Volatility:The supply of key inputs, particularly aged agave for tequila and specific barley varietals for single malt whisky, is subject to long agricultural cycles and climate-related risks, creating price instability.
- International Tariff Regimes:Retaliatory tariffs and complex trade agreements between major economic blocs, such as those impacting Scotch Whisky or American whiskey exports, create significant financial uncertainty and can disrupt established distribution channels.
Strategic Opportunities
- Emerging Market Penetration:Targeting the growing middle and upper classes in Southeast Asian nations like Vietnam and Thailand with entry-level premium brands offers a significant avenue for volume growth outside of saturated Western markets.
- Digital Channel Expansion:Developing sophisticated direct-to-consumer platforms allows brands to control the customer experience, gather valuable data, and bypass traditional three-tier distribution bottlenecks in markets like the United States.
- Blockchain for Provenance:Implementing blockchain technology to track products from distillery to consumer can enhance brand trust, combat counterfeiting in the ultra-premium segment, and justify price points for collectible bottles.
Industry Challenges
- Specialized Talent Scarcity:A shortage of experienced master distillers, master blenders, and coopers for barrel-making creates production bottlenecks and limits the ability of brands to scale artisanal production methods while maintaining quality.
- Sustainable Logistics Complexity:Balancing the need for protective, often heavy, glass packaging with corporate sustainability goals and the logistical challenges of global distribution creates significant operational friction and cost pressures.
- Digital Marketing Compliance:Enforcing strict age-gating and adhering to diverse advertising restrictions across digital platforms, particularly between jurisdictions like the US and France, presents a continuous operational and legal challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Premium Spirit Market |
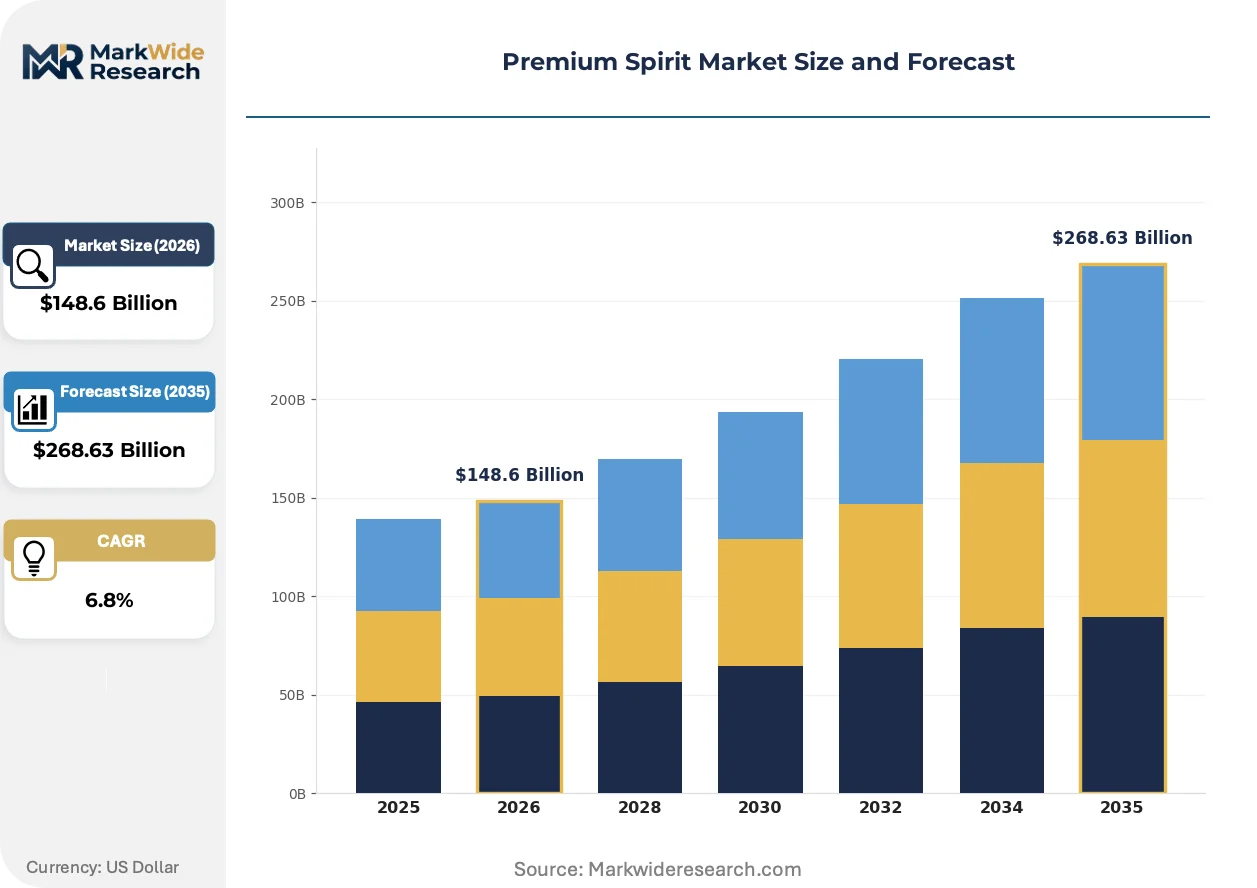
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $268.63 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whiskey, Gin, Vodka, Rum Flavor Profile: Herbal, Fruity, Spicy, Smoky Packaging Type: Glass Bottle, Cask, Tin, Keg Price Tier: Super Premium, Ultra Premium, Prestige, Luxury |
| Companies Covered | Brown Forman Corp., Suntory Global Spirits, Diageo PLC, LVMH Moet Hennessy, Constellation Brands Inc., Pernod Ricard SA, Campari Group, Sazerac Co. Inc., Bacardi and Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Premium Spirit Market Strategic Shifts & Innovations
A synthesis of technology and tradition is actively reshaping the premium spirit landscape. Innovations focus on amplifying markers of quality like provenance and craftsmanship, making heritage more transparent and verifiable for a new generation of consumers.
Precision fermentation and AI-driven distillation controls provide granular oversight of the production process, from yeast health to spirit cut points. Craft producers and established distilleries adopt these tools to ensure batch-to-batch consistency and experiment with new flavor profiles. This technological control is modularizing the art of distillation, enabling producers to isolate and replicate specific desirable characteristics across different product lines.
The European Union's Corporate Sustainability Reporting Directive (CSRD) mandates detailed, audited disclosures on environmental and social impacts. This regulation is forcing spirit producers to quantify and report on metrics like water usage in distillation, agricultural sourcing practices, and the carbon footprint of their global logistics. Consequently, brands operating in Europe are integrating verifiable sustainability data directly into their marketing, particularly within the whiskey and cognac categories.
Consumer purchasing behavior is shifting from single-brand loyalty to "repertoire" consumption, where individuals curate a collection of spirits across various categories. This trend de-emphasizes the traditional liquor store's focus on deep discounts for major brands, elevating the role of knowledgeable staff and curated online marketplaces. The shift is most visible in North American and European cities, where cocktail culture encourages experimentation with gin, tequila, and whiskey.
Premium Spirit Market Segmentation
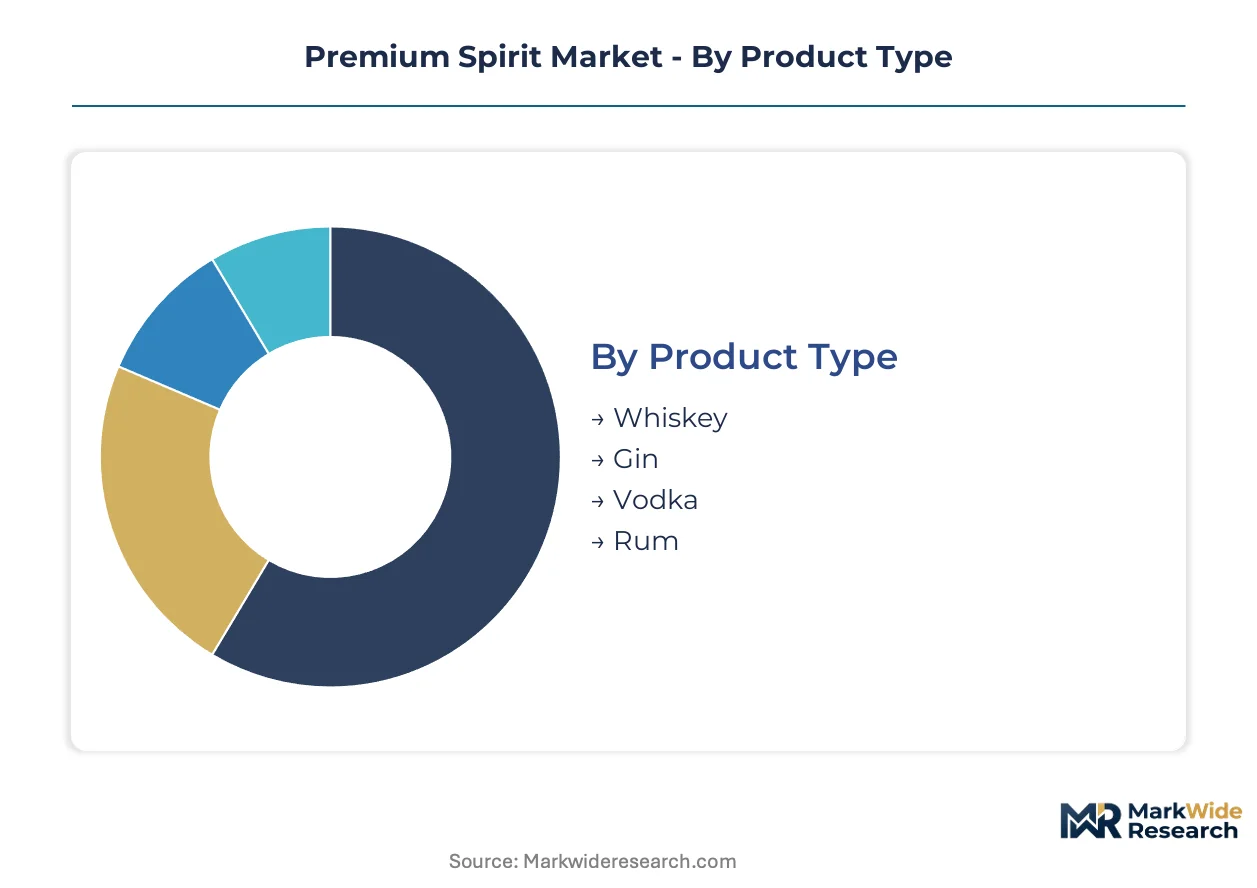
The premium spirit market's intricate structure reflects diverse consumer preferences and production methodologies. Understanding these segments is crucial for brands to effectively tailor product development, marketing strategies, and distribution channels. This analysis highlights the distinct characteristics that define each category within the sector.
Product Type:
The premium spirit market exhibits a clear bifurcation between high-volume categories and those commanding premium price points. Producers balance broad appeal with niche, artisanal offerings to capture market share across this spectrum.
- Whiskey:This category encompasses a broad range of distilled alcoholic beverages made from fermented grain mash, including single malts, bourbons, and rye. Value creation is anchored in whiskey, particularly aged variants, with strong demand in major urban centers across the United States and China.
- Gin:Gin is a distilled alcoholic beverage deriving its predominant flavor from juniper berries, often with other botanicals. Experimentation with diverse botanicals and production methods drives consumer interest in European and North American cocktail cultures.
- Vodka:Vodka is a clear distilled alcoholic beverage composed primarily of water and ethanol, often produced from grains or potatoes. It maintains a consistent presence in mixed drink formulations across global on-trade channels.
- Rum:Rum is a spirit made from sugarcane byproducts like molasses or directly from sugarcane juice, then aged in oak barrels. Demand for aged and spiced rum variants is expanding across Southeast Asian nations.
Mature deployment sits with Vodka. Newer deployment is concentrated in Rum.
Flavor Profile:
Consumer preferences for distinct taste experiences shape the flavor profile segment, influencing both product innovation and brand positioning. Distillers develop specific flavor notes to differentiate their premium offerings.
- Smoky:Characterized by a distinct peaty or wood-fired aroma and taste, often achieved through specific malting or aging processes. This profile is particularly sought after in single malt Scotch whiskies, with strong demand from discerning collectors in London and New York.
- Herbal:Defined by botanical notes such as juniper, coriander, or anise, typical of gins, absinthes, and some liqueurs. Craft gin producers leverage unique herbal blends to attract consumers in European cities.
- Fruity:Spirits with prominent notes of berries, citrus, or stone fruits, derived from distillation methods or infusions. These profiles appeal to consumers in warmer climates and those seeking refreshing cocktail bases.
- Spicy:Flavors featuring elements like cinnamon, clove, or black pepper, often found in aged rums, bourbons, or spiced liqueurs. This profile attracts consumers looking for complex and warming sensory experiences.
The market for traditional fruity profiles maintains stable demand. Innovation in spicy profiles exhibits the steepest expansion trajectory.
Packaging Type:
The choice of packaging type reflects both brand identity and evolving sustainability mandates. Producers must balance aesthetic appeal with environmental responsibility and logistical efficiency.
- Glass Bottle:The predominant packaging for premium spirits, offering aesthetic appeal, material inertness, and a perception of quality. The EU Green Deal encourages innovation in lighter glass and recycled content for glass bottles, influencing brand choices in France and Germany.
- Cask:Used primarily for aging and sometimes for direct sale of ultra-premium or collectible spirits, particularly whiskies and rums. Cask aging is critical for developing complex flavor profiles, with significant investment in Scotland and Kentucky.
- Tin:Less common for primary packaging, but used for gift sets or specialty editions, offering durability and a unique presentation. Tin packaging often features in travel retail channels for its protective qualities.
- Keg:Primarily used for on-trade distribution to cocktail bars and restaurants, allowing for efficient dispensing of high-volume spirits. This format supports speed of service in high-traffic establishments in cities like Shanghai.
Glass Bottle packaging dominates the market for premium spirits. Cask packaging serves a critical role in the production and ultra-premium segments.
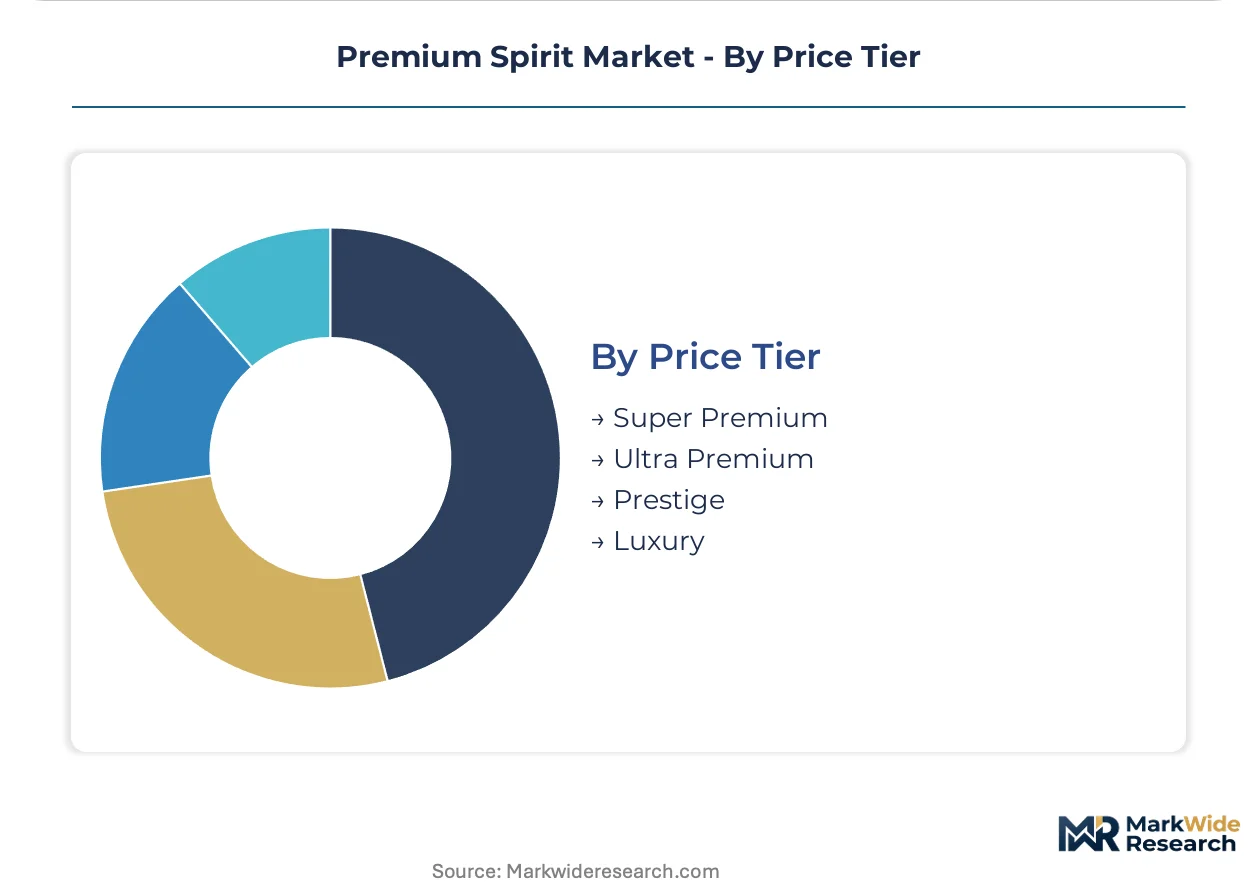
Price Tier:
Pricing tiers in the premium spirit market reflect product quality, exclusivity, and brand heritage. Consumers in these tiers seek unique experiences and artisanal craftsmanship.
- Ultra Premium:These spirits are characterized by superior raw materials, meticulous production, and often limited availability, justifying higher price points. The Ultra Premium tier shows significant growth, driven by consumers seeking exclusivity and craftsmanship in the United States.
- Prestige:Prestige spirits represent the pinnacle of quality and heritage, often with extensive aging or rare ingredients, targeting affluent collectors and connoisseurs. This tier exhibits substantial growth, appealing to consumers in China valuing provenance and rarity.
- Super Premium:Spirits in this tier offer enhanced quality and refined characteristics compared to standard offerings, often with distinct branding. Super Premium brands attract consumers upgrading from mass-market options in emerging Asian markets.
- Luxury:This tier encompasses the most exclusive and expensive spirits, often released in extremely limited quantities with bespoke packaging. Luxury spirits cater to ultra-high-net-worth individuals and collectors globally.
Ultra Premium and Prestige tiers are capturing market expansion. Super Premium maintains a broad consumer base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The premium spirit market shows a distinct split between traditional production hubs and expanding consumption centers. Global brands balance heritage with localized demand. This dynamic shapes investment in supply chains and marketing efforts, particularly in key urban markets.
United States
United States consumers demand craft and small-batch products, driving growth in the ultra-premium tier. The US Alcohol and Tobacco Tax and Trade Bureau (TTB) governs labeling and marketing standards for spirit categories. Major urban centers like New York and Los Angeles drive demand for high-end whiskies and bourbons.
China
Chinese consumers prioritize prestige brands, valuing provenance and rarity in their spirit choices. China's State Administration for Market Regulation (SAMR) oversees market supervision and quality standards for imported spirits. Major urban centers like Shanghai and Beijing exhibit strong demand for prestige whiskies and cognacs.
France
France remains a significant hub for heritage and terroir-driven production, particularly for Cognac. The EU Green Deal encourages lighter glass and recycled materials for packaging within France. The Cognac and Bordeaux regions maintain their global reputation for high-quality, geographically indicated spirits.
United Kingdom
The United Kingdom's vibrant cocktail culture and demand for single malts fuel premium spirit consumption. The European Food Safety Authority (EFSA) influences labeling standards for spirits sold in the UK, with post-Brexit trade agreements considered. London's luxury hotels and cocktail bars elevate consumption, especially for sought-after smoky Scotch whiskies.
Vietnam
Emerging market penetration in Vietnam targets the growing middle and upper classes with entry-level premium brands. Vietnam's Ministry of Industry and Trade regulates alcohol distribution and import tariffs. Urban centers like Ho Chi Minh City and Hanoi represent significant growth markets for spirits, including aged rum variants.
Premium Spirit Market Key Industry Players
The competitive structure tilts toward a tiered landscape, with global conglomerates dominating established categories. This market features large diversified portfolio holders, heritage brand specialists, and agile craft innovators. Producers engage in portfolio diversification to capture varied consumer preferences, including both traditional luxury and emerging craft styles. Geographic expansion into high-growth urban centers remains a key competitive move for securing new market share.
Within the global conglomerate archetype, companies like Diageo PLC and Pernod Ricard SA exemplify extensive distribution networks. These entities leverage their scale to introduce sustainable packaging initiatives and position portfolios for both established luxury labels and innovative craft-style spirits. LVMH Moet Hennessy, with its portfolio of prestige brands, represents the heritage brand specialist, emphasizing terroir-driven production and exclusive offerings. These major players collectively shape industry standards and consumer expectations across diverse premium spirit categories, often influencing sourcing and production methodologies.
| Leading Market Players |
|---|
| Brown Forman Corp. |
| Suntory Global Spirits |
| Diageo PLC |
| LVMH Moet Hennessy |
| Constellation Brands Inc. |
| Pernod Ricard SA |
| Campari Group |
| Sazerac Co. Inc. |
| Bacardi and Co. Ltd. |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's circular economy action plan gates qualified supply and premium-tier pricing access within the premium spirit market, influencing material choices and justifying sustainable product premiums.
Pricing Analysis
Value-based pricing anchors the premium spirit market, reflecting superior raw materials and demonstrable provenance. Price differentiation stems from meticulous production processes and brand heritage. Pricing softness runs through channels impacted by international tariff regimes, creating financial uncertainty for brand owners. Consumers in the Ultra Premium and Prestige tiers exhibit lower price sensitivity, while Super Premium buyers are more attuned to value propositions.
Supply Chain Analysis
Multi-tier distribution networks handle the complex movement of premium spirits from production to consumer across global markets. Geographic supply concentrates in France for Cognac, Scotland for Scotch whisky, and Kentucky for bourbon. The supply chain draws from critical raw materials like aged agave and specific barley varietals, creating dependencies. Raw material volatility presents a structural risk due to long agricultural cycles and climate-related factors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The premium spirit market presents a vertical-integration race, as brand owners pursue greater control over transparent sourcing and production methods. Implementing blockchain technology for provenance verification serves as a critical upstream lever.
For Market Incumbents: Anticipate evolving consumer and investor expectations for transparent sourcing and production by integrating verifiable sustainability data. Leverage extensive global distribution networks to introduce sustainable packaging initiatives, mitigating compliance costs from directives like the EU Green Deal. Invest in blockchain technology to enhance provenance tracking, combating counterfeiting in the ultra-premium segment. This proactive approach helps defend market share against agile craft innovators and regulatory shifts.
For New Entrants and Emerging Players: Begin with targeting underpenetrated emerging markets like Vietnam and Thailand, offering entry-level premium brands to growing middle-class consumers. Develop sophisticated direct-to-consumer platforms to control the customer experience and bypass traditional distribution bottlenecks in markets such as the United States. Emphasize unique terroir-driven narratives and craft production methods, appealing to consumers seeking authenticity beyond established luxury labels.
For Investors and Strategic Acquirers: Increased adoption of direct-to-consumer platforms is the leading indicator that digital channel expansion is reshaping market access and data acquisition. The premium spirit market demonstrates strong long-term viability, with significant growth projected in Ultra Premium and Prestige price tiers across the analysis window. Target agile craft producers with unique provenance or strong sustainability practices. Seek brands demonstrating successful digital marketing compliance across diverse jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Premium Tier Introduction | Introducing new ultra-premium offerings captures demand for exclusivity and craftsmanship among discerning consumers. |
| Digital Channel Expansion | Developing direct-to-consumer platforms allows brands to control customer experience and gather valuable market data. |
| Sustainable Packaging Initiatives | Implementing lighter glass and recycled materials aligns with EU Green Deal mandates and consumer environmental preferences. |
| Blockchain for Provenance | Utilizing blockchain technology enhances brand trust and combats counterfeiting in the high-value collectible spirit segment. |
| Emerging Market Penetration | Targeting growing middle and upper classes in Southeast Asia provides significant volume growth avenues. |
Research Approach
US TTB reports, EFSA publications, and EU Green Deal documents formed the secondary backbone for this analysis, providing foundational market data. Primary research involved combining in-depth interviews with industry stakeholders such as master distillers, brand managers, and luxury hotel F&B directors. This approach allowed for bottom-up and top-down triangulation, validating market sizing and growth projections across diverse data points.
Bottom-up analysis of market segments, validated by top-down industry trends, underpinned the forecast framework across the analysis window. Segmentation dimensions modeled included product type, flavor profile, packaging type, and price tier, alongside regional consumption patterns. Compound annual growth rates were derived from historical data and projected market drivers. Consumer purchasing behavior shifts and raw material availability served as key industry-specific forecast inputs.
Underlying measurement precision varies by segment; established categories like Whiskey and Vodka carry tighter precision than others. Forecasts reflect assumptions regarding geopolitical stability and raw material supply. International tariff regimes and raw material volatility represent specific risk factors that could revise projections. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Asia Pacific Wine Coolers Market
Alcoholic Beverages
India Gin Market
Alcoholic Beverages
Black Beer Market
Alcoholic Beverages
France Alcohol E-Commerce Market
Alcoholic Beverages
Alcohol-Free Pineapple Beer Market
Alcoholic Beverages
Vodka Market
Alcoholic Beverages
South Korea Tequila Market
Alcoholic Beverages
China Tequila Market
Alcoholic Beverages
Germany Tequila Market
Alcoholic Beverages
Oak Barrel Alternatives Market
Alcoholic Beverages
N-Hexyl Alcohol Market
Alcoholic Beverages
Bahrain Alcoholic Beverages Market
Alcoholic Beverages
Global Shortenings Market
Alcoholic Beverages
Cognac Market
Alcoholic Beverages
Pinot Noir Market
Alcoholic Beverages
East Africa Alcoholic Beverages Market