
 Single Serve Wine Market | 2026-2036
Single Serve Wine Market Size, Share, and Industry Trends Forecast 2026-2036
Single Serve Wine Market Outlook
Aluminum is rebalancing unit economics across single-serve wine formats by cutting shipping weight and enabling shelf-stable distribution without cork degradation. E&J Gallo Winery leverages its massive bottling infrastructure to maintain cost leadership in plastic cup and mini-bottle lines. Jackson Family Wines anchors its position through estate-sourced varietals packaged in premium can formats. Treasury Wine Estates competes via controlled retail placement in travel retail and duty-free channels.
Single serve wine denotes wine packaged in individual-portion containers, typically holding 187 milliliters, with shelf-life stabilization achieved through nitrogen flushing, screw-cap or pull-tab seals, and oxygen-barrier materials. The format serves on-premise hospitality, travel, outdoor recreation, and convenience retail where full-bottle opening creates waste or consumption barriers. Cans now lead volume growth due to recyclability and thermal conductivity advantages, while glass bottles retain dominance in premium airline and hotel minibar placements. Plastic cups occupy the budget tier with thin-margin, high-turnover economics at festivals and stadium events.
FDA oversees labeling accuracy and alcohol content declarations, while TTB enforces formula approvals and interstate commerce restrictions that shape how single-serve SKUs enter distribution. California's CalRecycle program and emerging extended producer responsibility frameworks in New York and Oregon push manufacturers toward aluminum and paper-based alternatives. Stakeholders must monitor how state-level deposit legislation and municipal composting infrastructure evolve to determine which material platforms justify capital commitment.
Market Dynamics
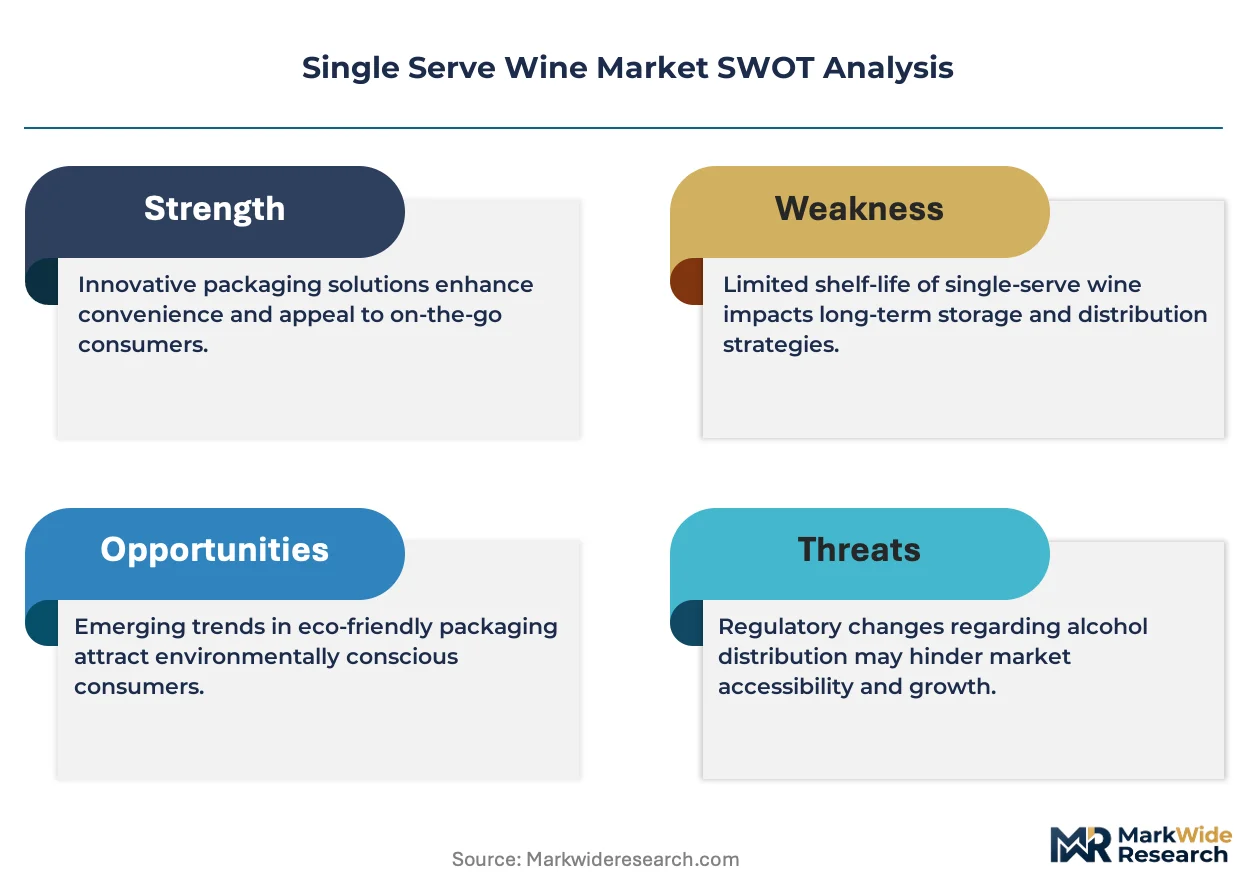
Aluminum can migration is compressing glass dependency across single-serve wine formats, forcing packaging infrastructure reinvestment while unlocking shelf-stable distribution economics previously locked to premium minibar placements.
Growth Catalysts
- Extended Producer Responsibility frameworks:CalRecycle in California and emerging mandates in New York and Oregon accelerate aluminum and paper-based packaging transitions, creating compliance-driven demand for recyclable single-serve formats.
- Airline inventory rationalization:Major carriers are expanding single-serve wine programs to reduce per-flight waste and simplify cabin service logistics, pulling volume toward 187-milliliter formats.
- Thermal conductivity advantages:Aluminum's rapid chilling properties enable outdoor recreation and convenience retail channels where ice bucket service is impractical, opening new consumption occasions.
Market Restraints
- TTB interstate commerce restrictions:Formula approval requirements and state-by-state shipping law fragmentation create SKU proliferation costs and limit direct-to-consumer scaling for smaller producers.
- Glass supply concentration:Premium airline and hotel minibar segments remain locked into glass bottle formats due to perceived quality signaling, constraining aluminum's addressable market share.
- Oxygen-barrier material costs:Nitrogen flushing and specialized liner technologies for aluminum cans impose per-unit cost premiums that compress margins at the budget tier.
Strategic Opportunities
- Duty-free channel expansion:Treasury Wine Estates and competitors are securing controlled retail placement in travel retail environments where single-serve formats solve passenger carry-on liquid restrictions.
- Festival and stadium direct distribution:Plastic cup formats occupy thin-margin, high-turnover economics at live events where traditional bottle service creates operational friction and waste liabilities.
- Direct-to-consumer shipping law liberalization:State-level reforms in the United States are gradually reducing regulatory barriers that currently fragment e-commerce fulfillment for single-serve assortments.
Industry Challenges
- Bottling line reconfiguration capex:Producers with legacy glass infrastructure face capital-intensive retooling to accommodate aluminum can filling, seaming, and labeling systems.
- Labeling compliance complexity:FDA alcohol content declaration accuracy requirements and TTB formula approval timelines create SKU launch delays that conflict with seasonal demand windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Serve Wine Market |
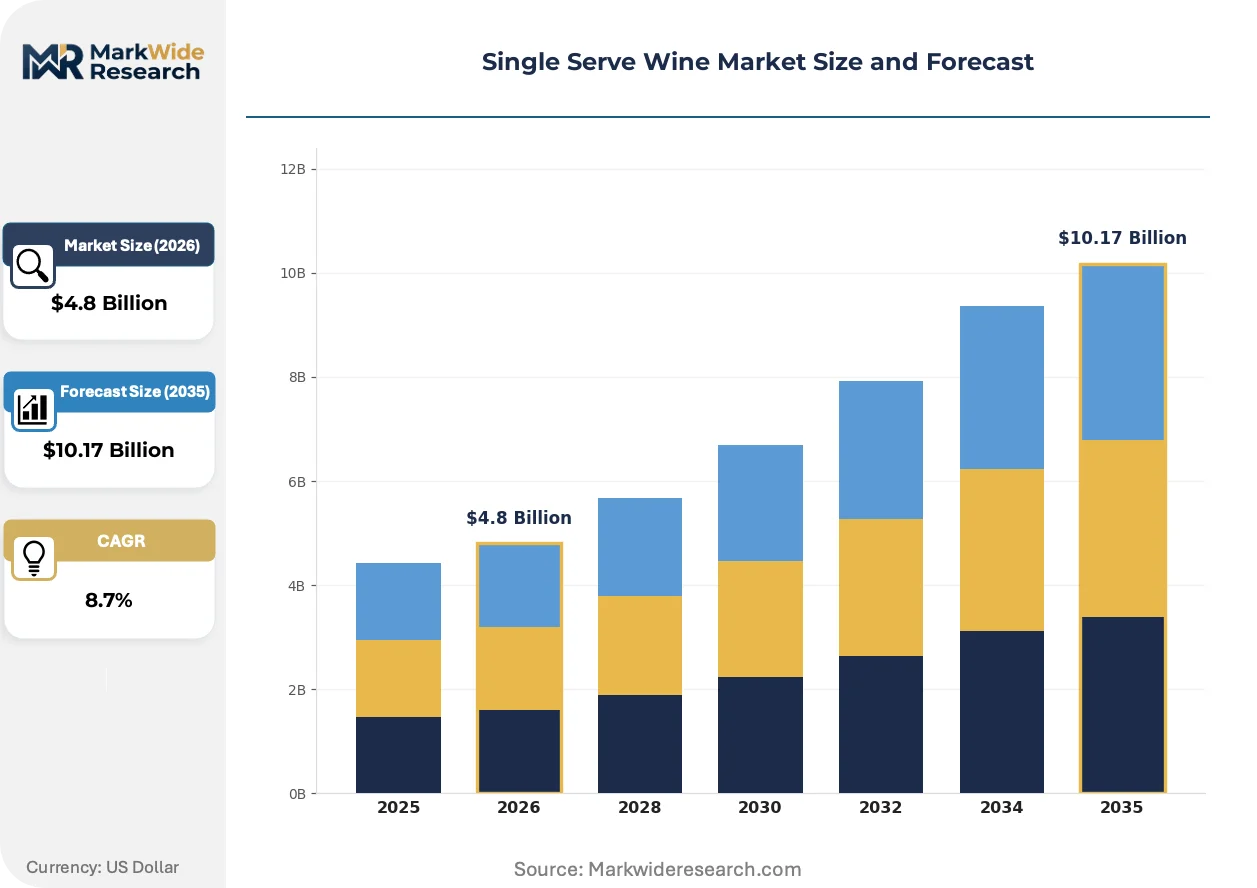
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Cups, Glass Bottles, Tetra Packs, Cans Distribution Channel: Retail Stores, Online Platforms, Events, Restaurants Customer Type: Millennials, Tourists, Event Attendees, Health-Conscious Consumers Price Tier: Premium, Mid-Range, Budget, Luxury |
| Companies Covered | Delicato Family Wines, Jackson Family Wines, E&J Gallo Winery, Ste. Michelle Wine Estates, Treasury Wine Estates, The Wine Group, Deutsch Family Wine & Spirits, Bronco Wine Company, Trinchero Family Wine & Spirits, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Serve Wine Market Strategic Shifts
Packaging material substitution is actively restructuring competitive economics across single-serve wine, with sustainability mandates and logistics efficiency converging to accelerate format experimentation beyond traditional glass dominance.
Aluminum can technology is overtaking glass in volume growth by enabling lighter shipping weights and eliminating cork degradation risks through nitrogen-flushed, pull-tab sealed construction. Outdoor recreation retailers and convenience chains are adopting aluminum at accelerating pace, compressing the historical premium attached to bottle formats and forcing estate wineries to justify glass through provenance storytelling rather than functional superiority.
REACH and EU Green Deal packaging sustainability targets are tightening material specifications for wine imports into European markets, creating compliance thresholds that favor aluminum recyclability credentials. Producers exporting to Germany, France, and the Netherlands are reformulating liner materials and deposit-return labeling to satisfy ECHA substance restrictions, with smaller estates facing disproportionate testing and certification burdens relative to integrated multinationals.
Buyer procurement is compressing toward assortment-based purchasing rather than single-varietal commitments, with hospitality chains and airline beverage managers negotiating category-wide single-serve wine contracts that span multiple price tiers and packaging formats. This consolidation of purchasing authority is visible most acutely in United States coastal markets where hotel groups and restaurant chains centralize beverage procurement at corporate headquarters, displacing property-level autonomy that previously accommodated regional supplier relationships.
Single Serve Wine Market Segmentation
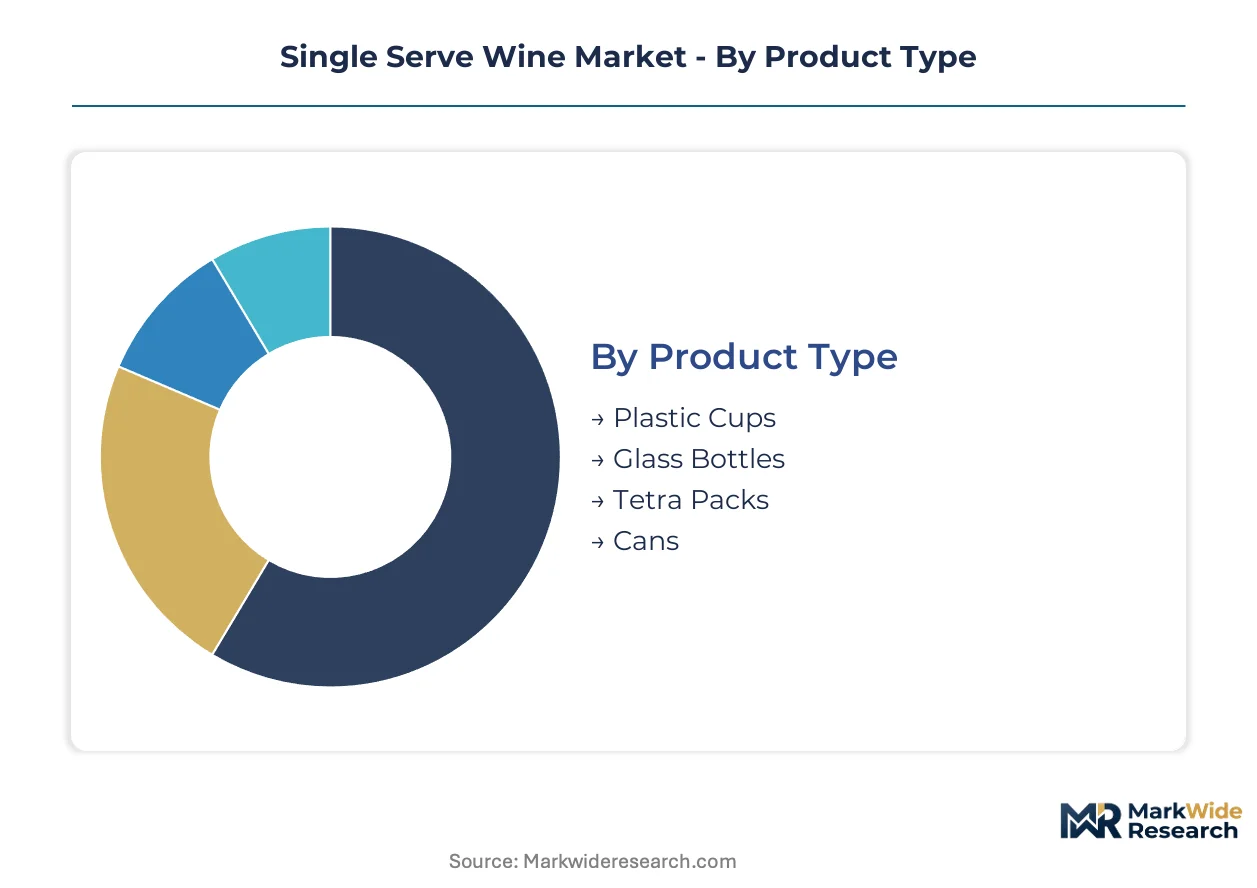
Single serve wine producers must align packaging formats and channel strategies with distinct consumption occasions, as airline procurement, festival logistics, and e-commerce fulfillment each impose incompatible technical and regulatory requirements. Segmentation reveals where capital deployment generates returns versus where thin margins demand operational efficiency.
Product Type:
Supply concentration in aluminum can manufacturing is reshaping format economics, with domestic canning capacity expansion outpacing glass bottling line investments across North American production facilities.
- Cans:Nitrogen-flushed aluminum construction eliminates cork degradation while cutting shipping weight by 60% versus glass. Demand is concentrating in outdoor recreation and convenience retail across California and Oregon, driven by CalRecycle extended producer responsibility mandates favoring recyclable formats.
- Glass Bottles:Premium 187-milliliter bottles with screw-cap seals dominate airline and hotel minibar placements where perceived quality signaling justifies higher unit costs. Supply concentrates in legacy bottling infrastructure operated by E&J Gallo Winery and Treasury Wine Estates.
- Plastic Cups:Thin-walled polyethylene terephthalate formats serve festival and stadium channels with high-turnover, low-margin economics where breakage and waste liability dominate procurement criteria.
- Tetra Packs:Aseptic carton construction with aluminum foil barriers occupies niche positions in European import markets where REACH compliance favors lightweight, rectangular shipping profiles.
Cans absorb the bulk of installed capacity expansion; plastic cups are expanding most quickly in event-driven channels.
Distribution Channel:
Cost tier stratification across channels separates premium placement economics from high-volume, low-margin fulfillment models.
- Retail Stores:Grocery and convenience chains stock aluminum cans in refrigerated sections, with shelf-space negotiations favoring producers with national distribution scale. TTB formula approval requirements fragment SKU availability across state lines.
- Online Platforms:Direct-to-consumer shipping law liberalization in states including New York and Texas is reducing regulatory barriers, though interstate commerce restrictions still complicate fulfillment for smaller estates.
- Restaurants:On-premise hospitality chains centralize procurement at corporate headquarters, displacing property-level autonomy with category-wide contracts spanning multiple price tiers.
- Events:Festival and stadium direct distribution operates on thin-margin, high-turnover economics where plastic cup formats minimize operational friction and waste liabilities.
Retail stores command the highest absolute volume; online platforms are climbing the fastest as state shipping reforms accumulate.
Customer Type:
Volume concentration among younger demographics is accelerating format experimentation beyond traditional glass dominance.
- Millennials:Digital-native consumers aged 28-43 drive aluminum can adoption through outdoor recreation and convenience retail, with purchase decisions influenced by sustainability credentials and portability.
- Event Attendees:Festival and stadium audiences accept premium pricing for chilled, ready-to-drink formats where queue time and consumption constraints override quality sensitivity.
- Tourists:Travel retail and duty-free channels serve passengers navigating liquid carry-on restrictions, with Treasury Wine Estates securing controlled placement in airport environments.
- Health-Conscious Consumers:Portion-controlled 187-milliliter formats align with moderation preferences, though this segment lacks the volume concentration of occasion-driven purchasers.
Millennials absorb the bulk of marketing investment; event attendees are gaining share fastest as live entertainment scheduling normalizes.
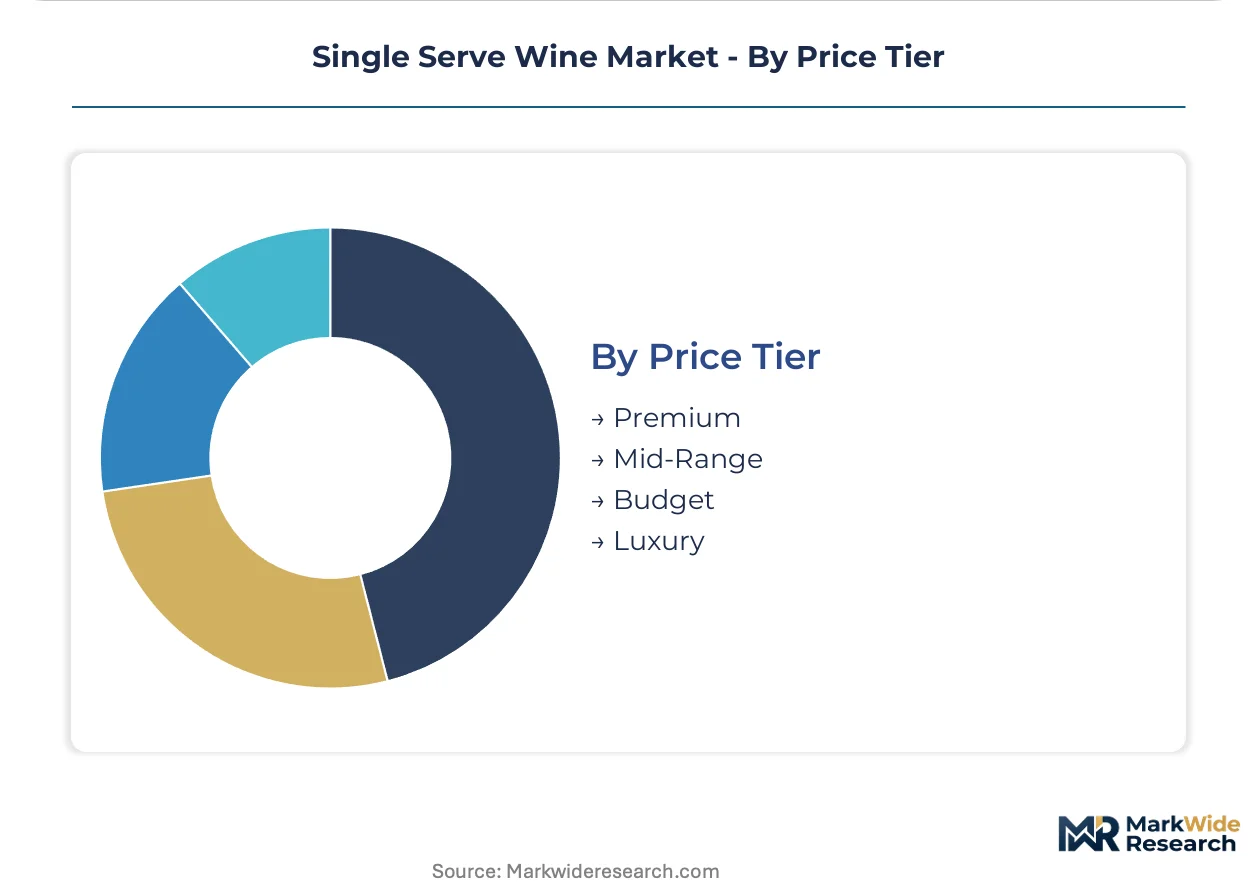
Price Tier:
Margin structure across tiers reflects packaging material costs and channel access fees rather than liquid quality differentiation alone.
- Budget:Plastic cup and value-can formats occupy thin-margin positions in stadium and festival channels where procurement decisions prioritize operational simplicity over provenance storytelling.
- Mid-Range:Aluminum cans with estate-sourced varietals target outdoor recreation and convenience retail, with Jackson Family Wines anchoring positioning through premium can construction.
- Premium:Glass bottles with screw-cap seals dominate airline and hotel minibar placements where corporate beverage managers negotiate category-wide contracts.
- Luxury:Limited-production estate bottlings in premium glass formats serve duty-free and gift channels with low volume but high absolute margin contribution.
Mid-range absorbs the bulk of volume growth; budget tiers are expanding most quickly in event-driven channels with high turnover velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, where direct-to-consumer shipping laws and on-the-go consumption culture support category expansion. Regulatory fragmentation across state lines shapes fulfillment economics. Material sustainability mandates in coastal states accelerate format transitions.
United States
Airlines and hospitality chains drive volume through inventory rationalization programs that reduce per-flight waste. TTB interstate commerce restrictions fragment SKU availability across state lines. California's CalRecycle extended producer responsibility framework pushes producers toward aluminum formats in the Napa-Sonoma cluster.
Germany
REACH compliance and EU Green Deal packaging targets tighten material specifications for wine imports. ECHA substance restrictions favor aluminum recyclability credentials. Producers exporting to Frankfurt and Munich retail channels reformulate liner materials to satisfy deposit-return labeling requirements.
France
Duty-free channel expansion in Paris Charles de Gaulle and Nice Côte d'Azur airports leverages single-serve formats to solve passenger liquid carry-on restrictions. ANSM labeling standards align with EU-wide sustainability directives. Bordeaux and Champagne house estates experiment with premium can construction for outdoor recreation export markets.
United Kingdom
Festival and stadium direct distribution channels adopt plastic cup formats for high-turnover summer events. Post-Brexit regulatory divergence from EU packaging rules creates compliance complexity for cross-border fulfillment. London-based hospitality groups centralize procurement contracts spanning multiple price tiers and packaging formats.
Australia
Thermal conductivity advantages of aluminum enable rapid chilling in outdoor recreation channels across Queensland and Western Australia. TGA-equivalent state food standards govern alcohol content declarations. Treasury Wine Estates anchors controlled retail placement in Sydney and Melbourne travel retail environments.
Single Serve Wine Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with estate wineries competing against volume producers on format innovation rather than liquid differentiation alone. The vendor base clusters around three strategic archetypes: integrated multinationals with legacy bottling infrastructure, family-owned estates pursuing premium can formats, and private-label specialists serving thin-margin event channels. Competitive moves concentrate on aluminum canning line investments and duty-free channel placement negotiations.
Within the integrated multinational tier, Treasury Wine Estates and E&J Gallo Winery exemplify divergent approaches to format economics. Jackson Family Wines occupies a position representing estate-sourced premium can construction. These three anchors illustrate how scale advantages and provenance storytelling compete for shelf-stable distribution economics previously locked to traditional glass formats.
| Leading Market Players |
|---|
| Delicato Family Wines |
| Jackson Family Wines |
| E&J Gallo Winery |
| Ste. Michelle Wine Estates |
| Treasury Wine Estates |
| The Wine Group |
| Deutsch Family Wine & Spirits |
| Bronco Wine Company |
| Trinchero Family Wine & Spirits |
| Others |
Value Chain & Pricing Dynamics
Airline procurement consolidation into category-wide contracts is compressing supplier margins while forcing packaging format standardization that favors aluminum can producers with scale. CalRecycle extended producer responsibility mandates in California add compliance premiums that reshape cost structures across material platforms.
Pricing Analysis
Volume concentrates in budget-tier plastic cup formats where thin margins demand high-turnover velocity, while premium glass bottles retain pricing power in airline and hotel minibar channels. Price differentiation hinges on packaging material costs and channel access fees rather than liquid quality alone. Cost compression in aluminum canning is intensifying because nitrogen-flushing and oxygen-barrier liner technologies impose per-unit premiums. Festival and stadium buyers exhibit highest price sensitivity, whereas duty-free channel managers prioritize operational simplicity over unit cost.
Supply Chain Analysis
Freight cost advantages of aluminum—cutting shipping weight by sixty percent versus glass—are reconfiguring distribution economics toward canning facilities in California, Oregon, and Texas. Raw material sourcing draws from domestic aluminum smelters, imported liner films, and nitrogen supply contracts. Single-source vulnerability concentrates in specialized canning line equipment where European and Asian manufacturers dominate. Distribution runs through consolidated beverage wholesalers serving retail chains, with direct-to-consumer fulfillment fragmenting around state-level shipping law variations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CalRecycle compliance costs function as a regulatory moat that advantages integrated producers with capital to absorb format transition investments, locking out smaller estates lacking aluminum canning infrastructure.
For Market Incumbents: Extend aluminum canning capacity in California and Oregon to capture extended producer responsibility compliance premiums before mandates spread to New York and Washington. Backward integration into nitrogen-flushing technology reduces per-unit cost exposure from specialized liner suppliers. Channel control through exclusive airline beverage contracts defends against estate wineries entering premium can formats. For New Entrants and Emerging Players: Festival and stadium direct distribution represents the most penetrable white-space target, with plastic cup formats avoiding capital-intensive canning infrastructure requirements. Outdoor recreation retailers in Pacific Northwest markets offer secondary entry points where sustainability credentials command shelf placement. A private-label positioning with event management companies enables volume accumulation without brand building costs. For Investors and Strategic Acquirers: Re-rating potential sits with family-owned estates possessing aluminum canning capabilities given duty-free channel expansion and state shipping law liberalization as catalysts. Long-term viability favors producers with format flexibility across glass, aluminum, and aseptic carton platforms. Watch TTB formula approval timeline compression as an inflection indicator for direct-to-consumer scaling economics.| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Canning Line Investment | CalRecycle compliance locks in shelf-stable distribution economics previously reserved for glass formats. |
| Duty-Free Channel Placement | Treasury Wine Estates and competitors secure controlled retail solving passenger liquid carry-on restrictions. |
| Backward Integration into Liner Technology | In-house nitrogen-flushing capability compresses per-unit cost premiums from specialized material suppliers. |
| Festival Direct Distribution Partnership | Plastic cup formats capture high-turnover event volume without breakage liability or waste penalties. |
| State Shipping Law Compliance Investment | TTB formula approval infrastructure enables e-commerce fulfillment as interstate commerce restrictions ease. |
Study Parameters
SEC 10-K filings, TTB formula approval databases, and CalRecycle extended producer responsibility reports formed the secondary backbone, supplemented by customs records tracking aluminum can imports and wine shipment volumes. Primary interviews with airline beverage procurement managers, hospitality chain category buyers, aluminum canning line engineers, and festival event logistics coordinators validated secondary findings. Bottom-up and top-down triangulation cross-checked facility capacity announcements against channel shipment data.
Bottom-up modeling aggregated individual producer capacity investments and channel placement wins, while top-down analysis tracked category velocity through retail scanner data and duty-free passenger flow metrics. Segmentation dimensions spanned packaging format, distribution channel, price tier, and regional regulatory cluster. CAGRs derived from curve-fitting historical volume trajectories against announced capacity expansions, with aluminum substitution rates and state shipping law reform timelines as wine-specific forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen TTB regulatory reversals, aluminum tariff fluctuations, and airline industry demand collapses. Forecasts reflect assumptions about extended producer responsibility mandate diffusion and canning line commissioning schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Global Premium Gin Market
Alcoholic Beverages
Light-Flavor Liquor Market
Alcoholic Beverages
Global Craft Vodka Market
Alcoholic Beverages
US Frozen Cocktail Popsicles Market
Alcoholic Beverages
Fruit Brandy Market
Alcoholic Beverages
Middle East and Africa Kegs Market
Alcoholic Beverages
Mushroom Beer Market
Alcoholic Beverages
CBD Wine Market
Alcoholic Beverages
Draught Beer Market
Alcoholic Beverages
Canada Tequila Market
Alcoholic Beverages
Wine Chocolate Market
Alcoholic Beverages
F-Style Jugs Market
Alcoholic Beverages
Woozy Bottle Market
Alcoholic Beverages
Cannabis-Based Alcoholic Beverages Market
Alcoholic Beverages
South Africa Beverages Market
Alcoholic Beverages
Canada Wine Coolers Market