
 Wind Turbine Gearbox Market | 2026-2036
Wind Turbine Gearbox Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Gearbox Market Intelligence
Procurement influence from Independent Power Producers and Renewable Energy Developers is rotating away from traditional, utility-led purchasing models. Winergy AG leverages its specialization in high-torque density gearboxes for the growing offshore segment. China High-Speed Transmission Equipment Group Co. Ltd. anchors a significant portion of the onshore market through its large-scale manufacturing capabilities, while Flender GmbH differentiates with its integrated drive system portfolio.
A wind turbine gearbox is a mechanical speed increaser, using complex gear arrangements to convert the rotor's low-speed rotation to the high-speed input required by the generator. These systems often employ gear ratios of approximately 1:90 to optimize power output. Planetary gearbox designs are becoming standard for high-capacity offshore wind farm applications due to their compact size and high torque capacity. In contrast, parallel shaft configurations maintain a significant presence in the legacy onshore wind turbine fleet.
Product design and market access are governed by multiple regulatory frameworks. Compliance with ISO 9001 standards for quality management is essential, while CE marking is mandatory for market entry in the European Union. In the United States, regulations from FERC influence grid connection requirements for new wind projects. Key strategic decisions for component suppliers will center on navigating the competitive pressure from direct-drive turbine technologies versus investing in next-generation gearbox reliability.
Market Dynamics
The central structural force shaping the wind turbine gearbox market is the technological race to increase torque density. This imperative is driven by the offshore wind sector's demand for multi-megawatt turbines, pushing gearbox designs to their mechanical and material limits.
Growth Catalysts
- National Energy Policies:China's dual carbon goals are accelerating the large-scale deployment of onshore and offshore wind capacity, creating sustained demand for locally manufactured gearbox components and entire drive trains.
- Offshore Wind Expansion:The build-out of large wind farms in regions like the North Sea and the US East Coast requires advanced, high-torque gearboxes capable of operating reliably in harsh marine environments.
- Planetary Gearbox Technology:The maturation of multi-stage planetary gear systems enables more compact and power-dense designs, which is critical for the nacelle architecture of next-generation turbines exceeding 10 MW capacity.
Market Restraints
- Direct-Drive Competition:The increasing technical viability and adoption of direct-drive (gearless) systems, particularly in the offshore segment, presents a significant substitution threat that limits the addressable market for gearbox manufacturers.
- Material Cost Volatility:Production costs are sensitive to price fluctuations in specialty inputs such as high-grade bearing steel and specialized lubrication fluids, impacting manufacturer margins and final component pricing.
- Reliability and Maintenance Burdens:Gearboxes remain a leading source of wind turbine failure and downtime, with high operational expenditures associated with repairs and replacements, especially in difficult-to-access offshore locations.
Strategic Opportunities
- Predictive Maintenance Integration:There is a significant opportunity in developing and integrating sensor-based condition monitoring and digital twin technologies to forecast failures, optimize maintenance schedules, and extend gearbox operational life.
- Emerging Market Entry:New government targets for wind power in Southeast Asian countries, including Vietnam and Taiwan, open new geographic markets for gearbox suppliers specializing in systems suited for typhoon-prone regions.
- Domestic Manufacturing Incentives:Policy frameworks like the US Inflation Reduction Act (IRA) create powerful financial incentives for establishing or expanding domestic manufacturing capacity for key renewable energy components, including gearboxes.
Industry Challenges
- Specialized Talent Scarcity:A shortage of technicians and engineers with the specialized mechanical and data analysis skills required for the design, manufacturing, and field servicing of complex planetary gear systems hampers industry growth.
- Grid Code Compliance:Adhering to a diverse and evolving set of national and regional grid connection codes, such as those set by FERC in the United States, adds complexity and cost to drivetrain system design and certification.
- Logistical Hurdles:The sheer size and weight of gearboxes for multi-megawatt offshore turbines create significant logistical challenges, demanding specialized vessels and port infrastructure for transport and installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Gearbox Market |
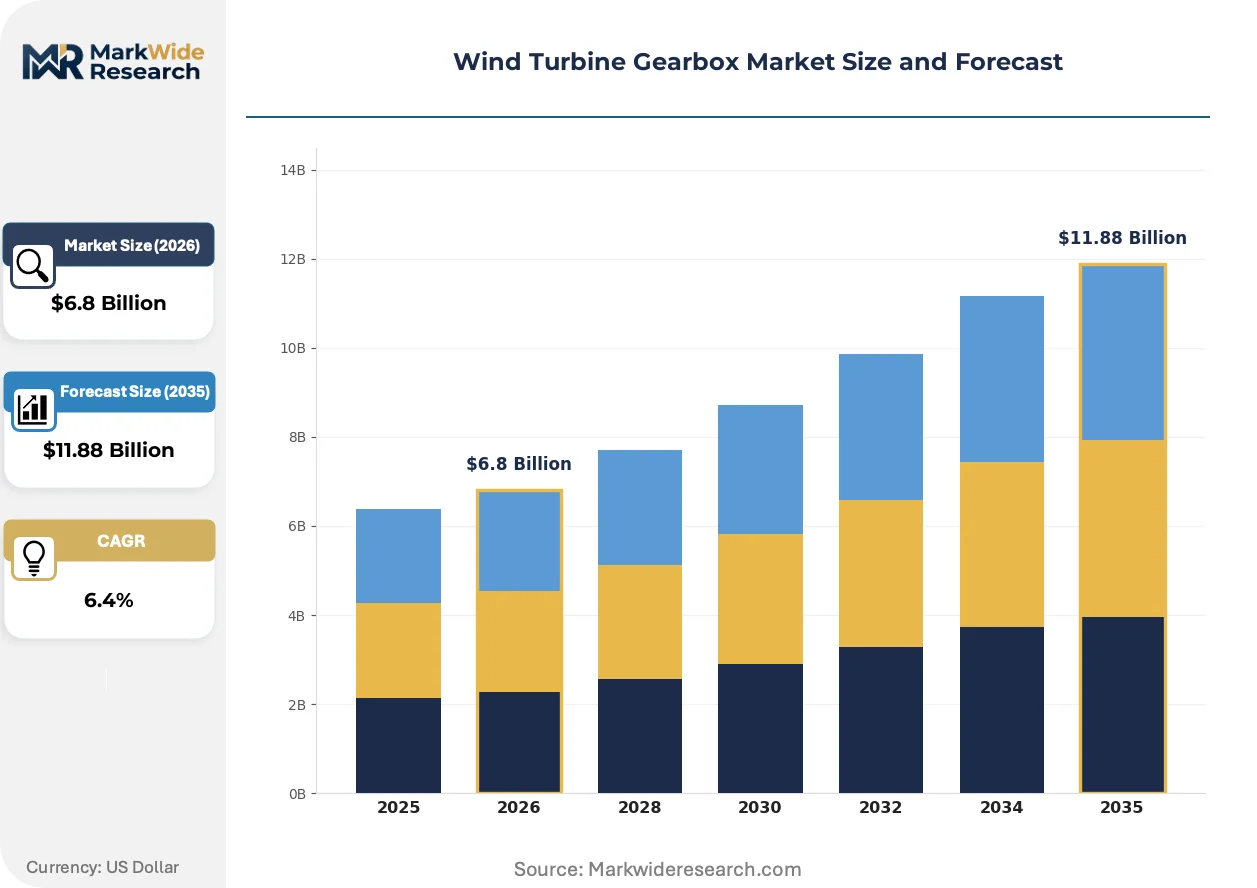
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parallel Shaft, Planetary, Hybrid, Epicyclic Technology: Hydraulic, Magnetic, Electric, Mechanical Application: Onshore Wind Farms, Offshore Wind Farms, Floating Wind Systems, Distributed Generation End User: Wind Farm Operators, Renewable Energy Developers, Independent Power Producers, Utilities |
| Companies Covered | Eickhoff Antriebstechnik GmbH, China High-Speed Transmission Equipment Group Co. Ltd., Winergy AG, Bonfiglioli Riduttori Spa, Siemens Gamesa Renewable Energy S.A., ZF Friedrichshafen AG, Chongqing Gearbox Co., Ltd., Flender GmbH, RENK AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Gearbox Market Strategic Shifts & Innovations
The wind turbine gearbox sector is defined by a dual focus on scaling power capacity for offshore applications while simultaneously enhancing component reliability to defend against gearless alternatives. This dynamic influences material science, design architecture, and service models across the industry.
Planetary gear systems provide the high torque capacity and compact footprint necessary for the next generation of wind turbines. Offshore project developers are standardizing on these designs for platforms that exceed 10 MW, driving rapid innovation in materials and lubrication. This adoption is bifurcating the supply chain, creating a high-performance, technologically intensive segment for offshore applications that is distinct from the established parallel-shaft designs serving the legacy onshore fleet.
In Europe, the CE marking framework, underpinned by the Machinery Directive, imposes strict requirements for product safety, reliability, and documentation. This regulatory pressure compels manufacturers to invest significantly in finite element analysis, prototype testing, and quality management systems compliant with standards like ISO 9001. The offshore segment is most affected, as the high cost of failure pushes asset owners and insurers to demand rigorous proof of compliance.
A notable behavioral shift involves asset owners bundling component supply with long-term service agreements directly from the turbine original equipment manufacturer. This model reduces the role of direct component procurement by independent power producers, transferring operational risk and maintenance responsibility to the OEM. The pattern is most prevalent in the mature offshore wind markets of Northern Europe, where financial de-risking is a primary concern for project stakeholders.
Wind Turbine Gearbox Market Segmentation
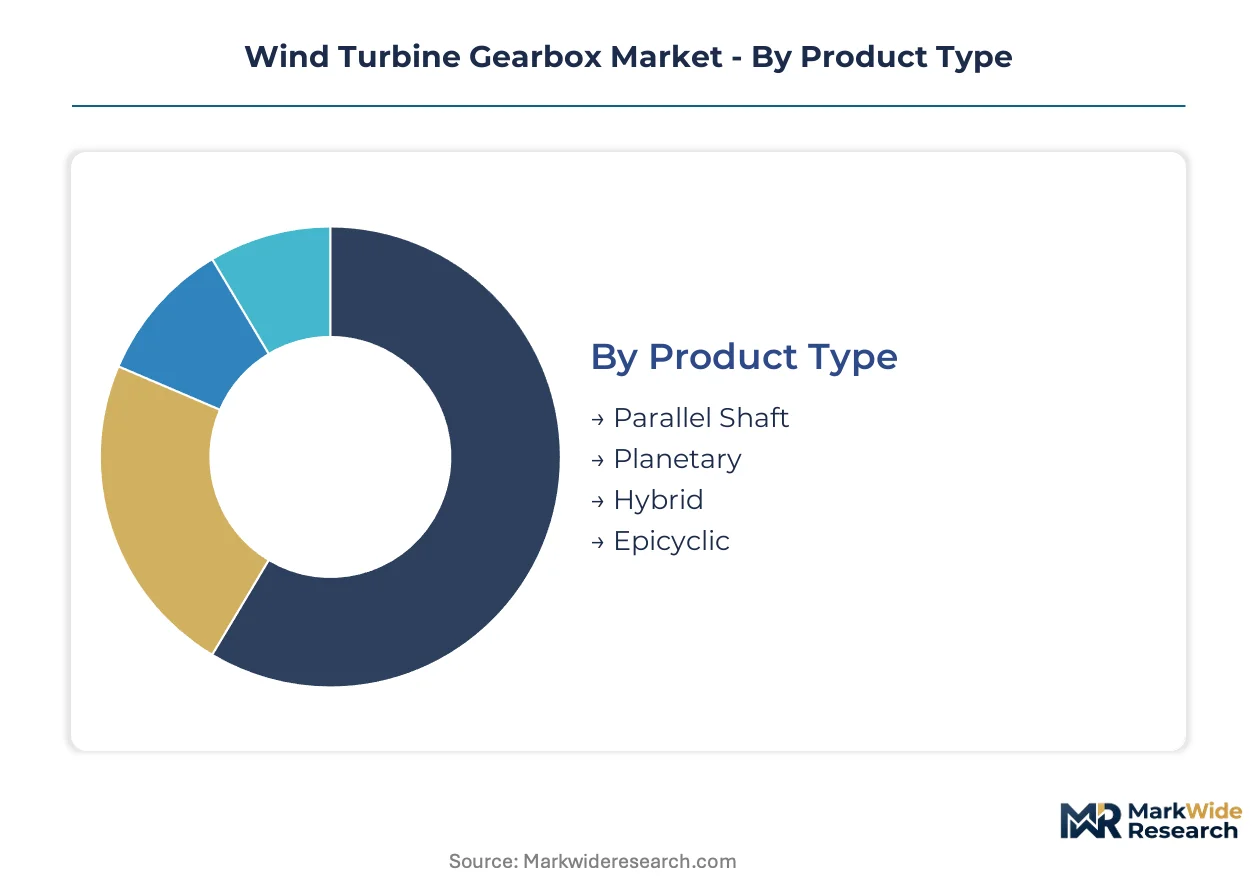
The Wind Turbine Gearbox Market segments offer a granular view of component demand, technology adoption, and end-user preferences across the global wind energy landscape. Understanding these distinctions is crucial for manufacturers to align product development with evolving market requirements and for investors to identify high-growth sub-sectors.
Product Type:
Gearbox product types distribute through distinct procurement channels, reflecting varying performance requirements for wind energy projects.
- Planetary:Compact, multi-stage gear systems designed for high torque density and efficiency in large-scale applications. Demand concentrates in multi-megawatt offshore wind farms, driven by the need for robust power transfer in harsh marine environments.
- Parallel Shaft:Utilizes multiple gears mounted on parallel shafts to achieve speed increase, known for its established design and manufacturing processes. Demand primarily serves the legacy onshore wind turbine fleet, valued for its proven reliability and lower manufacturing cost.
- Hybrid:Combines elements of planetary and parallel shaft designs to optimize performance and cost for specific turbine capacities.
- Epicyclic:A type of planetary gearing, often used in initial stages of multi-stage planetary systems due to its compact nature.
Planetary gearboxes dominate the installed base for high-capacity offshore projects. Hybrid systems are where expansion concentrates for specialized applications.
Technology:
Different gearbox technologies find application across diverse wind turbine designs, influencing overall system efficiency and maintenance profiles.
- Mechanical:Employs physical gears and shafts to convert low-speed rotor rotation to high-speed generator input. Demand is pervasive across both onshore and offshore wind applications, supporting the majority of installed turbine capacity.
- Electric:Refers to generator technologies, often associated with direct-drive systems that eliminate or reduce the need for a gearbox. Demand concentrates in the offshore segment as an alternative to geared systems, driven by reliability and maintenance reduction goals.
- Hydraulic:Utilizes hydraulic fluid power to transmit and multiply torque, offering flexibility in power conversion.
- Magnetic:Employs magnetic fields for power transmission, reducing mechanical wear and potentially improving efficiency.
Mechanical gearboxes retain the largest market share. Electric drive systems are gaining traction in gearless turbine designs.
Application:
The volume of gearbox deployments varies significantly across different wind energy applications, influenced by project scale and environmental conditions.
- Offshore Wind Farms:Requires gearboxes engineered for high power output and extreme durability in corrosive marine environments. Demand concentrates in European and East Asian coastal developments, driven by national energy policies and large-scale project deployment.
- Onshore Wind Farms:Utilizes gearboxes optimized for cost-efficiency and performance within accessible land-based installations. Demand is pervasive across established and emerging wind markets like China and the United States, supporting the largest global installed capacity.
- Floating Wind Systems:Gearboxes designed for turbines mounted on floating platforms, addressing deep-water wind resource utilization.
- Distributed Generation:Gearboxes for smaller wind turbines integrated into local grids or standalone power systems, emphasizing compact design.
Offshore wind farms are experiencing the most significant expansion. Floating wind systems represent a key future growth area.
End User:
End-user segments exhibit distinct procurement patterns for wind turbine gearboxes, shaped by their operational models and risk appetites.
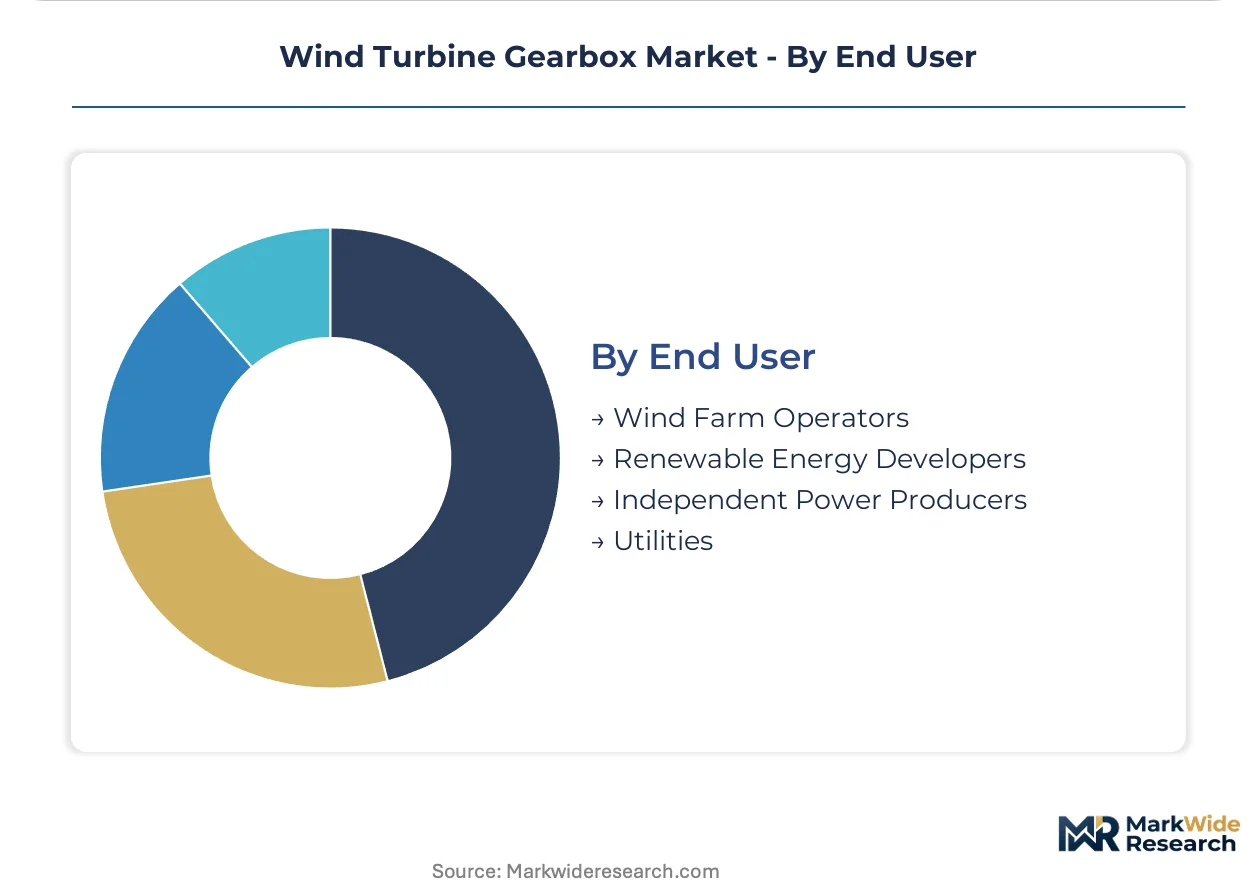
- Renewable Energy Developers:These entities initiate and manage wind farm projects, often dictating component specifications for new installations. Demand concentrates in regions with ambitious renewable energy targets, such as the EU and US, driving procurement of advanced gearbox systems.
- Independent Power Producers:IPPs own and operate power generation facilities, making long-term procurement decisions based on operational efficiency and reliability. Demand influences gearbox selection for large-scale wind projects globally, prioritizing proven performance and extended service life.
- Wind Farm Operators:Responsible for the day-to-day management and maintenance of operational wind farms, influencing replacement part procurement.
- Utilities:Large-scale power providers that own or contract wind energy, focusing on grid integration and long-term energy supply stability.
Renewable Energy Developers are strategically important for new project pipelines. Utilities maintain a significant influence on long-term procurement agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized port infrastructure along key coastlines underwrites the regional dynamics of the wind turbine gearbox market. Offshore wind farm developments, particularly in Europe and East Asia, necessitate robust logistics and manufacturing capabilities. This enables the efficient deployment of high-capacity gearboxes for multi-megawatt turbines.
China
China's ambitious dual carbon goals are driving unprecedented demand for wind turbine gearboxes. The government's push for renewable energy is supported by national GB standards for component quality. Manufacturing hubs in the Yangtze River Delta concentrate production for both domestic and export markets.
Germany
Germany's leadership in offshore wind technology fuels demand for advanced planetary gear systems. Compliance with CE marking is mandatory for market entry and product safety within the European Union. The North Sea coastal regions, particularly around Bremerhaven, serve as crucial logistics and assembly points for offshore wind projects.
United States
The United States is experiencing significant growth in its offshore wind sector, boosting demand for specialized gearboxes. The Inflation Reduction Act (IRA) provides substantial incentives for domestic manufacturing of wind components. The US East Coast, from Massachusetts to Virginia, is becoming a primary hub for offshore wind farm development and component supply.
Netherlands
The Netherlands, with its extensive North Sea wind farm projects, requires highly durable gearboxes for harsh marine environments. Adherence to EU Green Deal objectives influences procurement towards high-efficiency and reliable systems. The Port of Rotterdam plays a pivotal role as a logistical gateway for large-scale offshore wind turbine components.
Vietnam
Vietnam's emerging wind power sector, driven by national energy targets, presents new opportunities for gearbox suppliers. The country's policies aim to increase renewable energy capacity, including both onshore and offshore wind. Coastal provinces, especially in the south, are seeing increased investment in wind farm development.
Wind Turbine Gearbox Market Key Industry Players
Listed leaders compete with private specialists across application segments and technological specialization within the wind turbine gearbox market. The industry exhibits a tiered structure, with large industrial conglomerates alongside niche manufacturers focusing on specific turbine capacities. Strategic archetypes include global diversified power transmission providers, dedicated wind gearbox specialists, and integrated drive system suppliers. Capacity expansion in high-torque density designs and strategic partnerships for offshore project integration are dominant competitive moves among these players.
Specialists in high-torque density gearboxes for the growing offshore segment include Winergy AG, which leverages its expertise in advanced designs for multi-megawatt platforms. China High-Speed Transmission Equipment Group Co. Ltd. anchors a significant portion of the onshore market, exemplifying large-scale manufacturing capabilities and cost-effective production. Flender GmbH differentiates itself through an integrated drive system portfolio, occupying a position as a comprehensive solution provider for diverse turbine applications. These companies represent distinct approaches to market penetration and technology leadership across different wind energy sectors.
| Leading Market Players |
|---|
| Eickhoff Antriebstechnik GmbH |
| China High-Speed Transmission Equipment Group Co. Ltd. |
| Winergy AG |
| Bonfiglioli Riduttori Spa |
| Siemens Gamesa Renewable Energy S.A. |
| ZF Friedrichshafen AG |
| Chongqing Gearbox Co., Ltd. |
| Flender GmbH |
| RENK AG |
| Others |
Cost & Logistics Intelligence
The increasing technical viability of direct-drive turbine technologies, as a substitution dynamic, simultaneously reshapes supply geography by influencing manufacturing investment and exerts pricing pressure on traditional gearbox systems.
Pricing Analysis
Project-based pricing, often bundled with long-term service agreements, dominates the wind turbine gearbox market. Price differentiation stems from the certification level, such as CE marking for European entry, and the volume scale for multi-megawatt offshore applications. Pricing pressure stems from the competitive threat of direct-drive systems and material cost volatility for high-grade bearing steel. Renewable Energy Developers and Independent Power Producers prioritize proven performance and extended service life, making them less price-sensitive for critical offshore components, while onshore applications exhibit higher cost sensitivity.
Supply Chain Analysis
Manufacturers often employ a strategic-stockpile approach for critical components and materials, given the large size and long lead times for multi-megawatt gearboxes. Geographic supply concentration centers on China, which anchors onshore market production, and Germany, a hub for advanced planetary gear systems. Raw material dependencies include high-grade bearing steel and specialized lubrication fluids. A structural risk is the logistical hurdle associated with transporting massive components, requiring specialized port infrastructure. Distribution runs through direct sales from OEMs or component manufacturers to project developers and IPPs, often integrated into turbine supply contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story, primarily driven by the accelerating build-out of offshore wind capacity and ambitious national energy policies.
For Market Incumbents:Compound existing expertise in high-torque density gearboxes by investing in next-generation reliability R&D to counter direct-drive competition. Integrate advanced sensor-based condition monitoring and digital twin technologies into product offerings to extend operational life. Defend market share against material cost volatility by securing long-term supply agreements for critical inputs like specialized lubrication fluids. Expand manufacturing capacity in strategic regions like the US, leveraging incentives from the Inflation Reduction Act.
For New Entrants and Emerging Players:Differentiate on specialized applications, targeting the nascent floating wind systems segment with compact and robust designs. Focus on emerging markets in Southeast Asia, such as Vietnam and Taiwan, where specific environmental conditions like typhoons demand tailored gearbox solutions. A viable go-to-market angle involves offering integrated predictive maintenance services alongside component supply, leveraging data analytics for optimized asset management. The most penetrable segment for new entrants involves niche applications requiring customized hybrid gearbox solutions.
For Investors and Strategic Acquirers:The market sits at a sustained growth phase that favors specialized component manufacturers with proven high-torque density capabilities. Long-term viability over the next decade is strong, particularly for firms serving the expanding offshore wind sector. Acquisition targets should include companies with robust intellectual property in planetary gear systems and established supply chain relationships for critical materials. The signal to watch is the increasing average capacity of deployed offshore wind turbines, indicating demand for advanced gearbox technology.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Offshore Gearboxes | Increases supply for multi-megawatt turbine platforms, crucial for European and East Asian coastal developments. |
| Predictive Maintenance Technology Integration | Reduces downtime and operational expenditures, addressing a primary market restraint for asset owners. |
| Strategic Partnerships for Offshore Project Integration | Ensures seamless deployment of large components, critical for complex North Sea and US East Coast developments. |
| Advanced Material Science Investment | Enhances gearbox durability and torque capacity, pushing design limits for next-generation turbines. |
| Localized Manufacturing for Key Markets | Leverages policy incentives like the US IRA, reducing logistical hurdles and improving market access. |
Research Approach
Initial hypotheses were tested against primary input from Renewable Energy Developers, Independent Power Producers, Wind Farm Operators, and gearbox engineers, and refined through iterative analysis. This primary research was triangulated with extensive secondary validation from sources such as FERC filings, ISO 9001 certification databases, and national energy policy documents like China's dual carbon goals. The comprehensive approach combined bottom-up market sizing with top-down validation to ensure robust data integrity.
The analytical framework utilized variance decomposition to project market trajectory across the analysis window. Segmentation dimensions modeled included product type (e.g., Planetary, Parallel Shaft), technology (e.g., Mechanical, Electric), application (e.g., Offshore, Onshore), end user (e.g., Developers, IPPs), and turbine capacity. Compound annual growth rates were derived by analyzing historical trends and incorporating future growth catalysts and restraints identified in the market dynamics. Key industry-specific forecast inputs included offshore wind farm deployment schedules and national renewable energy targets.
The analysis sits within stated boundaries; outcomes outside significant shifts in global energy policy or material science breakthroughs would require recalibration. Forecasts reflect assumptions regarding technological adoption rates and regulatory stability, which are subject to external forces. Revision becomes warranted when direct-drive technology adoption or material cost volatility crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
North America Large Wind Turbine Market
Wind Energy Systems
Wind Energy Equipment Logistics Market
Wind Energy Systems
Wind Turbine Brakes Market
Wind Energy Systems
Quiet Wind Turbine Market
Wind Energy Systems
China Wind Turbine Rotor Blade Market
Wind Energy Systems
Wind Speed Alarm Market
Wind Energy Systems
Wind Electric Power Generation Market
Wind Energy Systems
Wind Turbine Lenses Market
Wind Energy Systems
Global Wind Power Coatings Market
Wind Energy Systems
Floating Wind Turbine Market
Wind Energy Systems
Wind Turbine Nacelle Market
Wind Energy Systems
Wind Blades NDT Market
Wind Energy Systems
Asia-Pacific Wind Turbine Rotor Blade Market
Wind Energy Systems
Multi-Rotor Wind Turbine Market
Wind Energy Systems
Global Wind Turbine Operations Market
Wind Energy Systems
France Wind Energy Market