
 Wind Turbine Nacelle Market | 2026-2036
Wind Turbine Nacelle Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Nacelle Market Outlook
Certified wind turbine technician availability is redrawing competitive boundaries across the nacelle supply chain. Siemens Gamesa Renewable Energy S.A. leverages its European training academy network to sustain installation and service throughput in mature markets. Ming Yang Smart Energy Group Co. Ltd. anchors its cost position through integrated nacelle-drivetrain manufacturing at its Guangdong facilities. General Electric Company competes on offshore platform scale, specializing in direct-drive architectures above 12 MW.
A wind turbine nacelle is the enclosed housing mounted atop the tower that contains the drivetrain, generator, yaw system, and power electronics, typically fabricated from welded steel frames with composite covers and weighing 50–400 tonnes depending on turbine rating; its primary purpose is to convert rotor torque into grid-synchronous electricity while protecting critical components from environmental loads. Offshore product types command premium engineering margins due to corrosion-resistant sealing and remote diagnostics requirements, while above 5 MW capacity segments absorb the majority of new R&D expenditure as rotor diameters exceed 200 meters. Direct drive technology segments are displacing gearbox configurations in offshore applications where reliability-critical maintenance access remains expensive and weather-dependent.
FAA obstruction lighting standards in the United States, ECHA REACH restrictions on rare-earth magnet coatings in Europe, and China's GB wind turbine grid compliance codes collectively shape nacelle material selection, electromagnetic compatibility testing, and export market access protocols. The EU Green Deal's renewable acceleration mechanisms tighten domestic content traceability requirements for nacelle assemblies destined for North Sea projects. Stakeholders must monitor evolving rare-earth supply chain disclosure rules and their cascading impact on permanent magnet generator sourcing strategies.
Market Dynamics
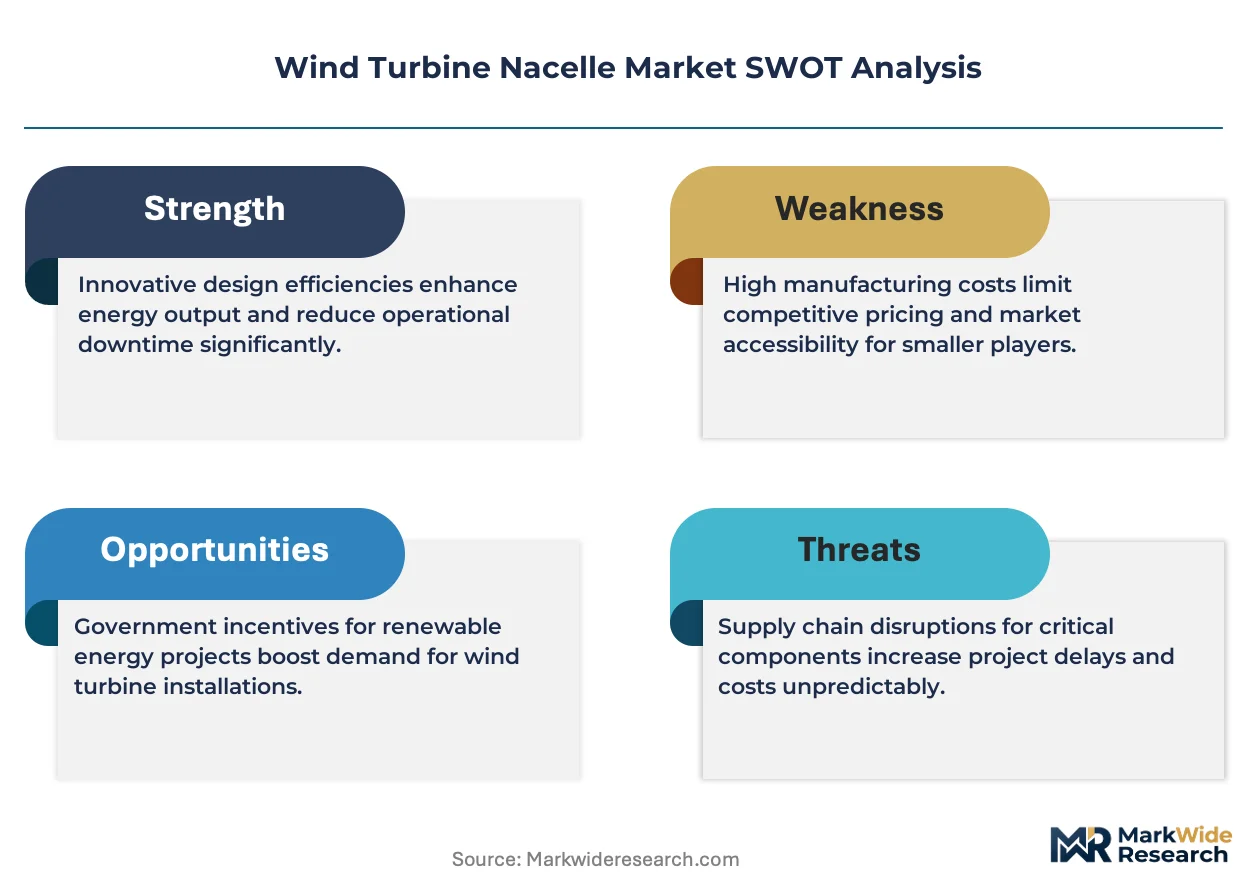
Direct-drive generator architectures above 12 MW are compressing gearbox supply chains while forcing nacelle OEMs to redesign structural load paths and thermal management systems for permanent magnet integration.
Growth Catalysts
- EU Green Deal domestic content rules:North Sea offshore developers now require traceable nacelle assembly origins, accelerating localized supply chain investments in Germany, Denmark, and the Netherlands.
- China GB wind turbine grid compliance codes:Mandatory low-voltage ride-through and reactive power capability specifications are driving power electronics upgrades across installed fleets.
- FAA obstruction lighting standards:New avian-safe lighting mandates in the United States are creating retrofit demand for integrated nacelle-mounted aviation warning systems.
Market Restraints
- Neodymium-dysprosium price volatility:Rare-earth magnet input costs swing with Chinese export quota decisions, squeezing direct-drive generator margins unpredictably.
- European converter supply concentration:IGBT and SiC power module production clusters in Germany and Austria create single-source vulnerability for nacelle power electronics.
- Port infrastructure dimensional limits:Existing heavy-lift quayside capacity at most North Sea harbors cannot accommodate 15 MW+ nacelle transport requirements without capital-intensive expansion.
Strategic Opportunities
- Floating offshore wind platforms:Japan and California markets are advancing pre-commercial projects where motion-compensated nacelle designs command engineering premiums.
- IRA domestic manufacturing tax credits:United States offshore wind lease stipulations now reward nacelle final assembly within qualified opportunity zones.
- Digital twin predictive maintenance:Convergence of vibration sensors with cloud-based physics models enables unbundled service contracts separate from turbine supply.
Industry Challenges
- Certified high-voltage technician scarcity:Grid interconnection work above 66 kV requires specialized training that European and North American labor pools currently undersupply.
- Type certification timeline compression:IEC 61400-22 design evaluation periods for novel nacelle architectures now lag behind developer construction schedules by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Nacelle Market |
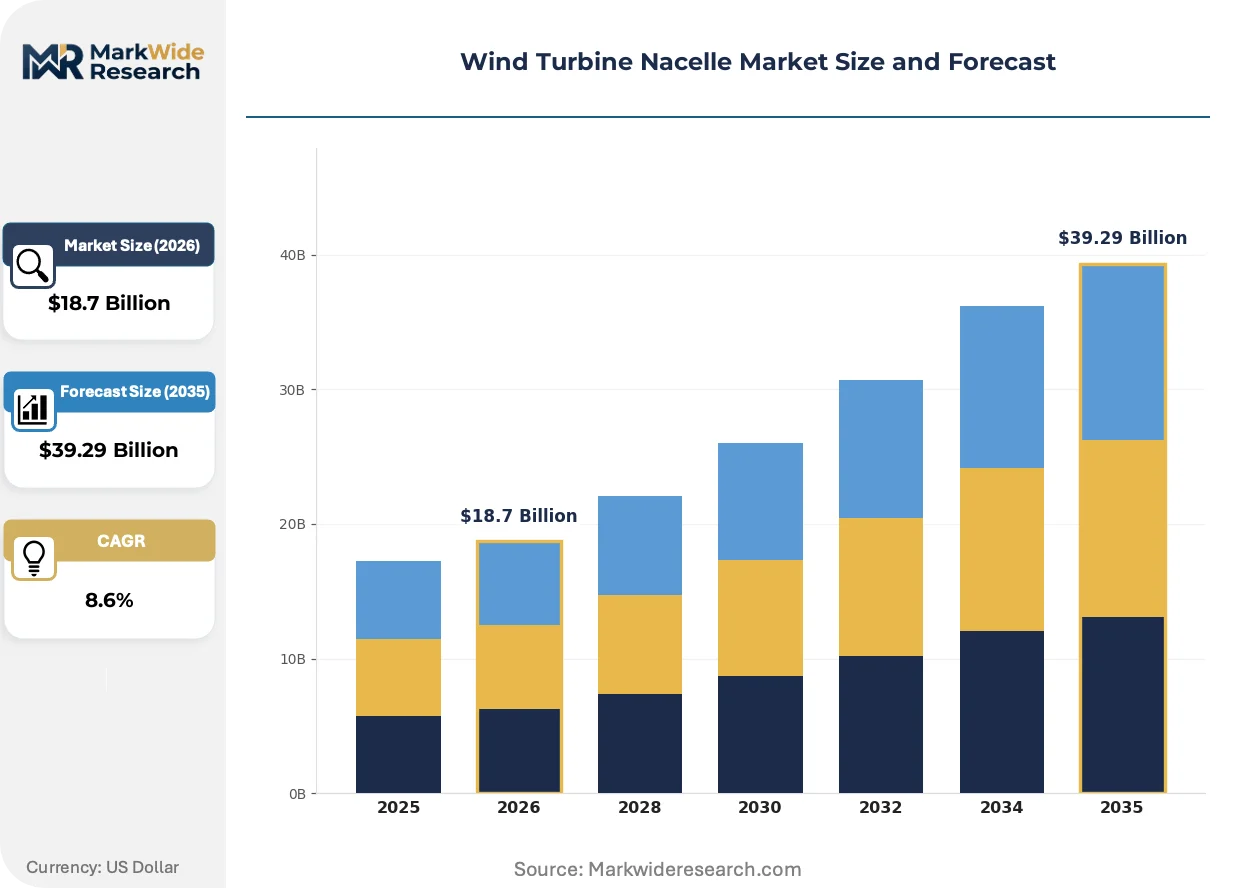
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Axis, Vertical Axis, Offshore, Onshore Technology: Direct Drive, Gearbox, Permanent Magnet, Variable Speed End User: Utilities, Independent Power Producers, Government, Commercial Capacity: Up to 1 MW, 1–3 MW, 3–5 MW, Above 5 MW |
| Companies Covered | Xinjiang Goldwind Science & Technology Co. Ltd., ENERCON GmbH, Vestas Wind Systems A/S, Ming Yang Smart Energy Group Co. Ltd., Suzlon Energy Limited, Siemens Gamesa Renewable Energy S.A., Nordex SE, Envision Energy Ltd., General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Nacelle Market Strategic Shifts
Power electronics packaging, rare-earth magnet chemistry, and remote diagnostic architectures are converging to redefine nacelle value engineering. These shifts compress physical footprints while extending service intervals in offshore environments.
Silicon carbide (SiC) power semiconductors are replacing silicon IGBTs in nacelle converter systems, cutting switching losses by half. Offshore developers in the North Sea are specifying SiC-based medium-voltage converters for turbines above 10 MW. The technology is miniaturizing converter cabinet volumes by 30-40%, freeing nacelle deck space for auxiliary systems.
REACH restrictions on hexavalent chromium coatings are forcing magnet surface treatment transitions to phosphate or organic passivation layers. European nacelle assemblers must now document coating chemistry through the full supply chain to ECHA. Permanent magnet generators for North Sea projects face the tightest compliance timelines, with 2026 sunset dates for legacy coating processes.
Long-term service agreements are unbundling from initial turbine supply contracts, with independent service providers now bidding 15-20 year drivetrain maintenance separately. Wind farm owner-operators in the United States are driving this split, seeking competitive tension between OEM and third-party service bids. The shift is most visible in Texas and Midwest markets where merchant power exposure incentivizes opex control.
Wind Turbine Nacelle Market Segmentation
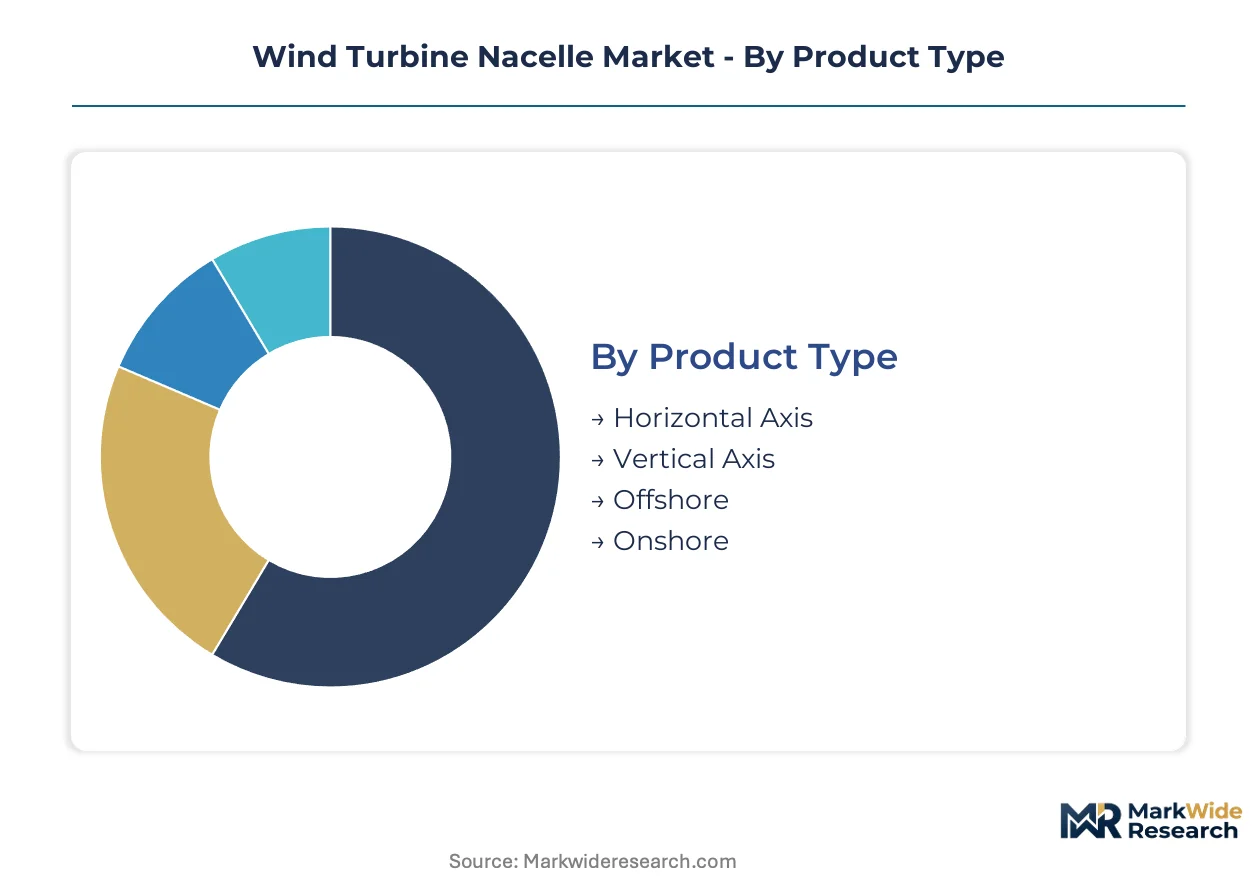
Nacelle procurement patterns diverge sharply across installation environments and power ratings. Segment boundaries determine sourcing strategy, certification requirements, and service contract structures for turbine OEMs and wind farm developers.
Product Type:
Domestic demand concentrates in onshore configurations across China and the United States, while offshore variants drive export-led revenue from European assembly facilities.
- Horizontal Axis:Dominant configuration featuring rotor shaft parallel to wind direction, typically three-bladed upwind designs. Demand clusters in the Great Plains of the United States and Inner Mongolia, driven by utility-scale procurement for low-wind-speed sites.
- Vertical Axis:Darrieus and Savonius variants with omnidirectional wind capture. Niche applications in urban distributed generation and remote telecommunications sites in Canada and Australia absorb limited volumes.
- Offshore:Corrosion-resistant sealing systems and integrated helicopter hoisting platforms distinguish these nacelles. North Sea developers in Germany, Denmark, and the Netherlands command premium engineering margins for 12 MW+ ratings.
- Onshore:Standardized transport dimensions and modular assembly protocols enable high-volume production. Chinese OEMs supply domestic wind corridors and Belt and Road export markets from coastal manufacturing bases.
Onshore configurations hold the largest share; momentum sits with offshore variants.
Technology:
Cost tiers separate established gearbox architectures from emerging direct-drive platforms, with permanent magnet systems commanding material cost premiums.
- Direct Drive:Eliminates gearbox through low-speed multi-pole generators, reducing mechanical failure points. Offshore projects above 10 MW in the North Sea specify this architecture to minimize weather-dependent maintenance access.
- Gearbox:Planetary and helical stages multiply rotor speed for conventional generators. Mature supply chains in Germany and China sustain cost competitiveness for onshore installations below 5 MW.
- Permanent Magnet:Neodymium-iron-boron rotor configurations maximize power density. ECHA REACH coating restrictions are forcing surface treatment transitions for European-sourced generators.
- Variable Speed:Power electronics enable rotor speed optimization across wind regimes. Full-converter architectures dominate above 3 MW ratings where grid code compliance requires reactive power capability.
Gearbox technology retains volume leadership; permanent magnet configurations are expanding most quickly.
End User:
Customer type determines financing structures, with utilities leveraging balance-sheet capacity against merchant power developers seeking tax equity partnerships.
- Utilities:Vertically integrated electric companies with regulated rate-base treatment. Procurement in Germany and Spain emphasizes 25-year asset life and standardized maintenance protocols.
- Independent Power Producers:Non-utility developers selling output under power purchase agreements. Merchant exposure in Texas and the UK drives opex minimization through competitive service bidding.
- Government:State-owned enterprises and public renewable energy authorities. China's state grid affiliates dominate procurement through centralized tender processes.
- Commercial:Corporate offtakers securing renewable energy credits for sustainability targets. Direct procurement by technology and retail corporations is rising in California and Northern Europe.
Utilities hold the largest share; commercial offtakers are gaining share fastest.
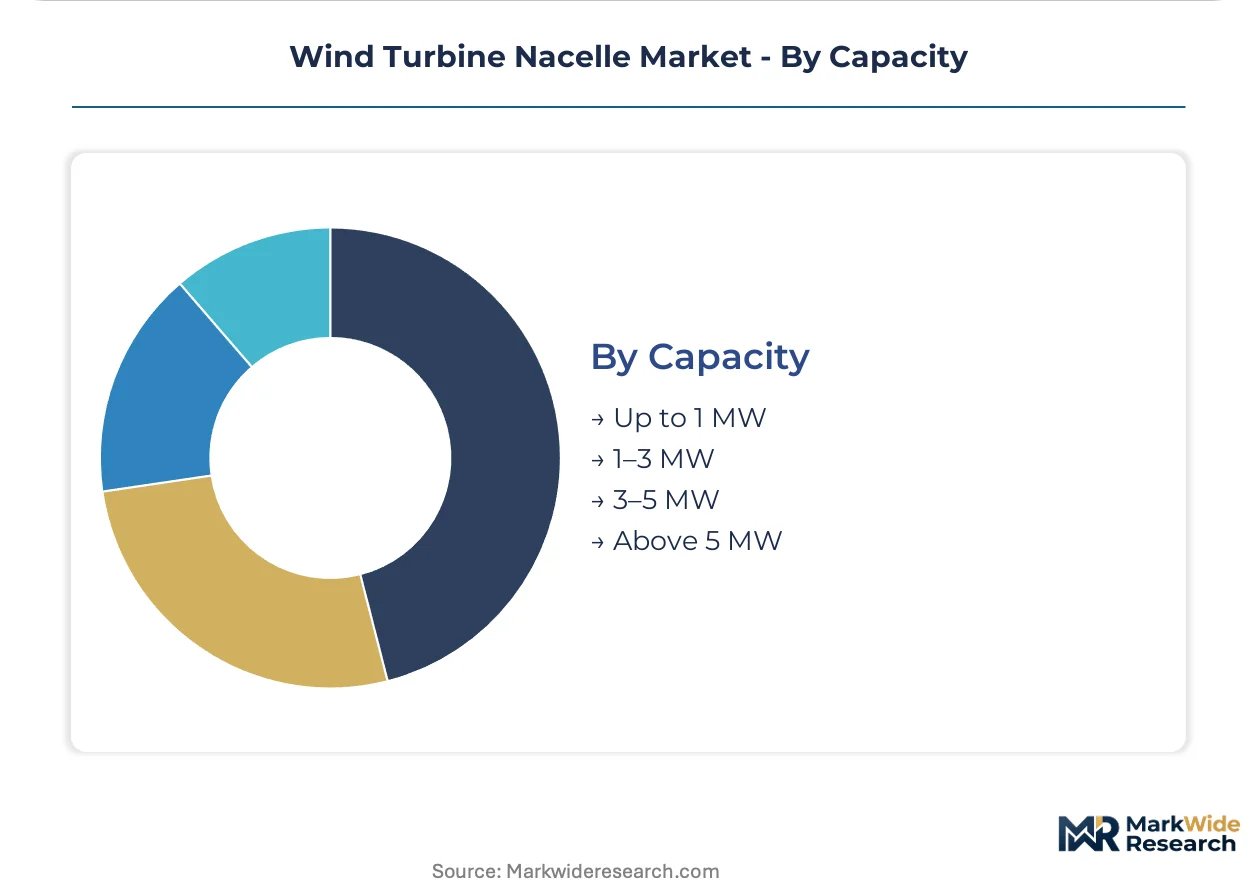
Capacity:
Physical scale determines transport logistics, with above-5 MW units requiring specialized heavy-haul permits and port infrastructure.
- Up to 1 MW:Compact nacelles suited to distributed generation and rural electrification. Retrofit demand in India and Southeast Asia sustains limited production lines.
- 1–3 MW:Workhorse segment for mature onshore wind markets. Repowering installations in California and Denmark replace aging turbines with upgraded drivetrains.
- 3–5 MW:Transition class bridging onshore and early offshore applications. Grid interconnection standards in China and Germany drive power electronics standardization.
- Above 5 MW:Megawatt-scale architectures with segmented generator components for transport. Port capacity constraints at most North Sea harbors limit deployment logistics for 15 MW+ designs.
The above-5 MW segment holds the largest share; momentum sits with 3–5 MW units for emerging market expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB wind turbine grid compliance codes anchor the dominant geography, driving power electronics standardization across the largest annual installation pipeline. European offshore markets tighten domestic content traceability through EU Green Deal mechanisms. North American lease stipulations now reward localized final assembly.
China
State grid affiliates dominate procurement through centralized tender processes, absorbing the majority of global nacelle volume. MIIT and GB standards mandate low-voltage ride-through and reactive power capabilities across installed fleets. Guangdong coastal manufacturing bases feed domestic wind corridors and Belt and Road export markets with integrated nacelle-drivetrain production.
Germany
North Sea offshore developers require traceable nacelle assembly origins, accelerating localized supply chain investments. ECHA REACH restrictions on rare-earth magnet coatings force surface treatment transitions for permanent magnet generators. Hamburg and Bremerhaven harbor clusters struggle with heavy-lift quayside capacity limits for 15 MW+ nacelle transport requirements.
United States
Merchant power exposure in Texas and the Midwest incentivizes opex control through competitive service bidding. FAA obstruction lighting standards create retrofit demand for integrated nacelle-mounted aviation warning systems. IRA domestic manufacturing tax credits reward nacelle final assembly within qualified opportunity zones across coastal lease areas.
Denmark
Tightened grid interconnection codes force nacelle redesigns for enhanced power electronics compliance in mature offshore zones. EU Green Deal renewable acceleration mechanisms tighten domestic content traceability for North Sea projects. Esbjerg port infrastructure requires capital-intensive expansion to accommodate next-generation nacelle dimensions.
Japan
METI advances pre-commercial floating offshore wind projects where motion-compensated nacelle designs command engineering premiums. Island geography and deep-water constraints favor direct-drive architectures minimizing weather-dependent maintenance access. Kyushu and Hokkaido development zones drive demand for specialized offshore sealing systems and remote diagnostics integration.
Wind Turbine Nacelle Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the nacelle supply chain. The market structure consolidates around integrated turbine OEMs with captive nacelle production, while specialized component suppliers occupy tiered positions beneath. Three archetypes dominate: European offshore specialists with training academy networks, Chinese integrated manufacturers with coastal production bases, and diversified industrial conglomerates with direct-drive platform scale. Competitive moves concentrate on vertical integration into permanent magnet supply chains and geographic expansion through localized assembly joint ventures.
Among European offshore specialists, Siemens Gamesa Renewable Energy S.A. and Vestas Wind Systems A/S exemplify the premium-tier archetype with established North Sea project footprints. Xinjiang Goldwind Science & Technology Co. Ltd. anchors the Chinese integrated manufacturer position, while General Electric Company occupies the diversified conglomerate tier with scale-driven offshore platform specialization.
| Leading Market Players |
|---|
| Xinjiang Goldwind Science & Technology Co. Ltd. |
| ENERCON GmbH |
| Vestas Wind Systems A/S |
| Ming Yang Smart Energy Group Co. Ltd. |
| Suzlon Energy Limited |
| Siemens Gamesa Renewable Energy S.A. |
| Nordex SE |
| Envision Energy Ltd. |
| General Electric Company |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between North Sea developers and European nacelle assemblers lock in multi-year supply access while fixing price visibility against rare-earth magnet cost swings. These structures transfer commodity volatility risk from turbine OEMs to project sponsors, insulating margins for permanent magnet generator configurations.
Pricing Analysis
Chinese-sourced nacelles trade at engineering margins 15-25% below European equivalents, reflecting integrated coastal manufacturing and GB standards compliance at scale. Three-tier pricing structure across premium offshore, standard onshore, and economy repowering tiers separates Siemens Gamesa and Vestas from Goldwind and Ming Yang at the top, with regional challengers occupying the bottom. Pricing pressure stems from neodymium-dysprosium quota volatility squeezing direct-drive generator margins unpredictably. Merchant IPPs in Texas and the UK exhibit highest price sensitivity, while regulated utilities in Germany absorb premium tiers for 25-year asset life guarantees.
Supply Chain Analysis
China dominates nacelle final assembly and drivetrain integration, while Germany and Denmark anchor power electronics and precision gearbox production. The supply chain draws from neodymium-iron-boron magnet processing in Inner Mongolia, IGBT module fabrication in Austria, and composite nacelle covers from Guangdong. Single-source vulnerability clusters around European converter production, where Infineon and ABB module capacity creates bottleneck risk for medium-voltage architectures. Distribution runs through port-centric heavy-lift logistics, with Hamburg, Bremerhaven, and Esbjerg handling North Sea outbound flows while Chinese coastal bases feed Belt and Road corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across floating offshore wind niches, where motion-compensated nacelle designs for Japan and California markets outpace standardized product development cycles. This demand-side shift rewards engineering specialists over integrated volume players.
For Market Incumbents: Shield installed base revenue through captive service contract renewal and backward integration into permanent magnet supply chains. The unbundling of long-term service agreements from initial turbine supply threatens OEM aftermarket margins, particularly in Texas and Midwest merchant markets where IPPs drive competitive bidding. Prioritize certification investment for 15 MW+ offshore platforms before IEC 61400-22 timeline compression widens.
For New Entrants and Emerging Players: Differentiate on motion-compensated architectures for floating wind platforms, where pre-commercial project pipelines in Japan and California lack established supplier relationships. Target California lease areas for IRA-qualified opportunity zone assembly, exploiting domestic content requirements that disadvantage pure-import strategies. Go-to-market through joint ventures with Japanese EPC contractors holding METI floating wind demonstration allocations.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier European power electronics specialists with SiC converter technology and existing North Sea project references, positioned for acquisition by nacelle OEMs seeking vertical control. Long-term viability hinges on regulatory alignment with ECHA REACH coating transitions and EU Green Deal traceability mandates. Watch for inflection in Chinese rare-earth export quota decisions, which signal margin compression or expansion for direct-drive generator dependent portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Permanent Magnet Supply | Secures neodymium-iron-boron access against Chinese quota volatility for direct-drive platforms. |
| SiC Power Electronics Migration | Reduces converter footprint 30-40% for 10 MW+ turbines specified by North Sea developers. |
| Floating Platform Joint Ventures | Captures engineering premiums in Japan and California pre-commercial project pipelines. |
| IRA-Qualified Domestic Assembly | Unlocks tax credit benefits for US offshore lease areas requiring localized final assembly. |
| Digital Twin Service Unbundling | Enables independent 15-20 year drivetrain maintenance contracts separate from turbine supply. |
Study Parameters
A spread of perspectives from nacelle OEM engineering directors, offshore project developers at European utilities, certified wind technician training providers, and power electronics procurement managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through IEC certification databases, FERC interconnection filings, EIA project tracking, and Chinese MIIT tender disclosure records. Bottom-up nacelle shipment tallies by rating class triangulated against top-down wind capacity installation forecasts across the analysis window.
Segmentation dimensions modeled include installation environment, drivetrain architecture, power rating tier, and end-user financing structure across the projection horizon. CAGRs derived from regression against historical capacity additions, adjusted for regulatory acceleration mechanisms and supply chain constraint scenarios. Forecast inputs incorporated port infrastructure expansion timelines for 15 MW+ heavy-lift capacity and rare-earth magnet coating compliance deadlines under ECHA REACH.
Decision-makers should treat outputs as directional under assumptions of continued IRA domestic content enforcement and EU Green Deal traceability implementation; material deviation in Chinese export policy or North Sea harbor investment would warrant model refresh. Recalibration cycles align with material shifts in grid interconnection code revisions and floating wind commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Asia-Pacific Wind Power Market
Wind Energy Systems
North America Large Wind Turbine Market
Wind Energy Systems
Europe Large Wind Turbine Market
Wind Energy Systems
Ireland Wind Energy Market
Wind Energy Systems
Offshore Wind Power Market
Wind Energy Systems
Global Marine Wind Turbine Market
Wind Energy Systems
North America Wind Power Market
Wind Energy Systems
Denmark Wind Energy Market
Wind Energy Systems
Drone Wind Turbine Blade Inspection Market
Wind Energy Systems
Sweden Wind Power Market
Wind Energy Systems
Wind Turbine Lenses Market
Wind Energy Systems
Global Small Wind Market
Wind Energy Systems
North America Wind Power Equipment Market
Wind Energy Systems
Wind Blades NDT Market
Wind Energy Systems
Global Wind Power Coatings Market
Wind Energy Systems
Offshore Wind Cable Market