
 Global Wind Power Coatings Market | 2026-2036
Global Wind Power Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wind Power Coatings Market Foresight
The EU Green Deal is restructuring procurement priorities across European wind supply chains, pushing asset owners toward longer-service coating systems. Jotun leverages its marine-grade fluoropolymer expertise to anchor blade protection contracts in North Sea developments. Hempel competes through specialized anti-corrosion formulations designed for monopile foundations in saline environments. AkzoNobel extends its position by integrating weather-resistant polyurethane lines with OEM manufacturer qualification programs.
Wind power coatings are protective material systems engineered to withstand cyclic loading, ultraviolet degradation, and electrolytic corrosion on turbine structures operating across variable climatic zones, typically formulated with epoxy or fluoropolymer binders applied through spray or brush deposition to extend component fatigue life. Epoxy-based systems dominate tower coating and foundation applications where substrate adhesion and cathodic protection compatibility prove critical. Polyurethane formulations lead blade protection segments where flexibility and UV resistance balance aerodynamic surface requirements. Fluoropolymer technology occupies premium nacelle covering roles where thermal stability and chemical inertness justify material cost premiums.
FDA, EPA, and OSHA frameworks in the United States govern worker exposure limits and volatile organic compound emissions during coating application, while REACH and RoHS regulations in Europe restrict hazardous substance content in imported coating materials. China's MEE enforces dual carbon goals that elevate performance standards for domestically produced anti-corrosion systems. Stakeholders must monitor evolving national carbon-border mechanisms and their cascading effects on coating qualification costs across manufacturing footprints.
Market Dynamics
Offshore wind farm operators are extending blade protection programs from 5-year to 10-year service intervals, forcing coating suppliers to reformulate for extreme marine fatigue cycles and cathodic compatibility with steel foundations.
Growth Catalysts
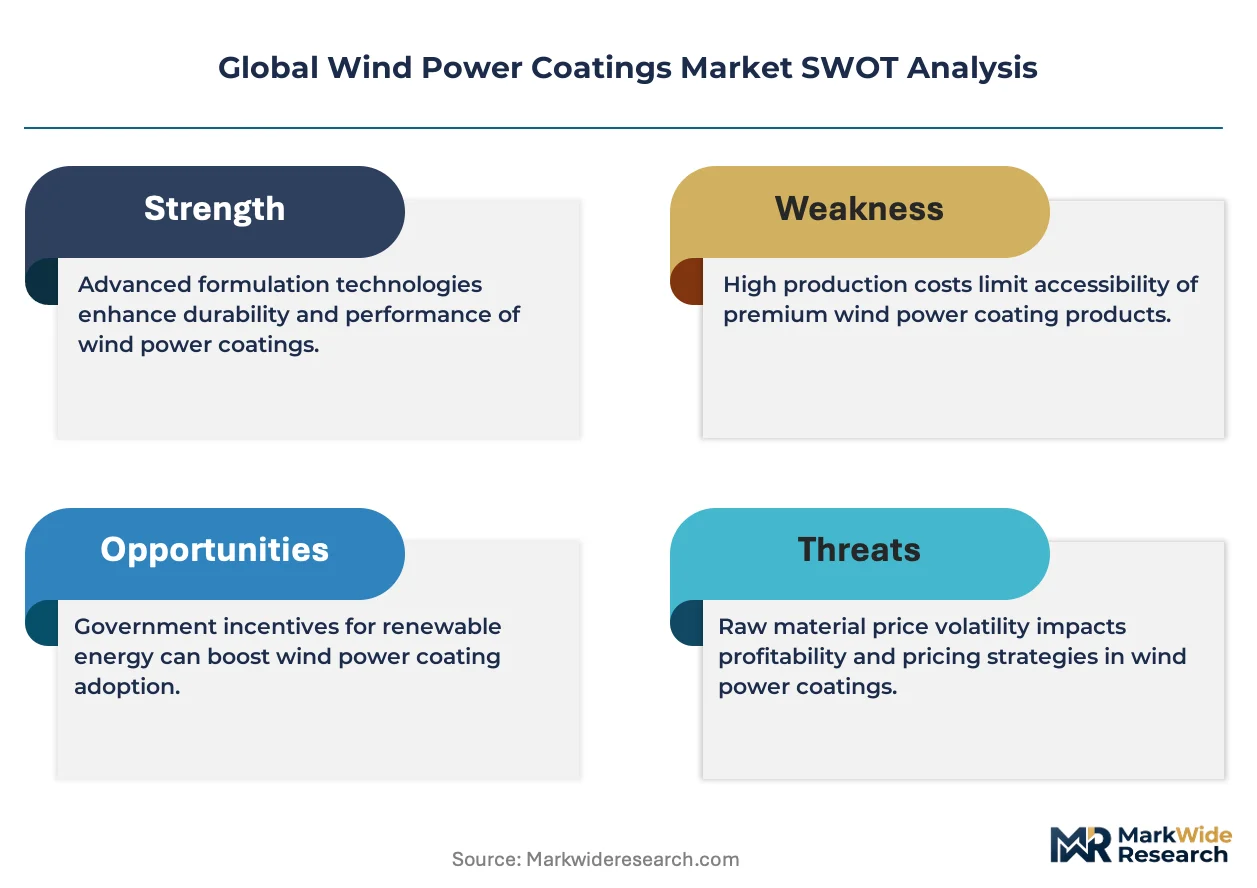
- EU Green Deal corrosion mandates:Tighter standards for turbine components in saline environments are mandating fluoropolymer upgrades across North Sea installations.
- China dual carbon enforcement:State-backed wind capacity additions under MEE supervision require specialized anti-corrosion formulations with enhanced UV stability.
- Epoxy tower coatings:Substrate adhesion improvements for monopile foundations are opening replacement cycles in aging onshore fleets.
Market Restraints
- Fluoropolymer feedstock concentration:PTFE resin supply concentrates among three chemical conglomerates, exposing coaters to volatile fluorochemical pricing.
- REACH substance restrictions:ECHA scrutiny of isocyanates in polyurethane hardeners is forcing reformulation investments without performance guarantees.
- Application labor scarcity:Certified spray technicians for nacelle fluoropolymer systems command wage premiums that compress contractor margins.
Strategic Opportunities
- Floating offshore platforms:Dynamic cable movement and splash-zone exposure in Portuguese and Scottish developments demand flexible coating architectures absent from fixed-foundation specifications.
- Blade leading-edge erosion:Rain droplet impact at tip speeds exceeding 90 m/s is driving interest in elastomeric polyurethane overlays as retrofits.
- Digital coating monitoring:Embedded sensor integration with blade health management systems creates recurring service revenue streams.
Industry Challenges
- OEM qualification timelines:Blade manufacturer certification programs for new coating chemistries extend 18-24 months, freezing formulation innovation cycles.
- Multi-substrate compatibility:Hybrid towers combining steel bases with composite nacelles require coating systems with mismatched thermal expansion coefficients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wind Power Coatings Market |
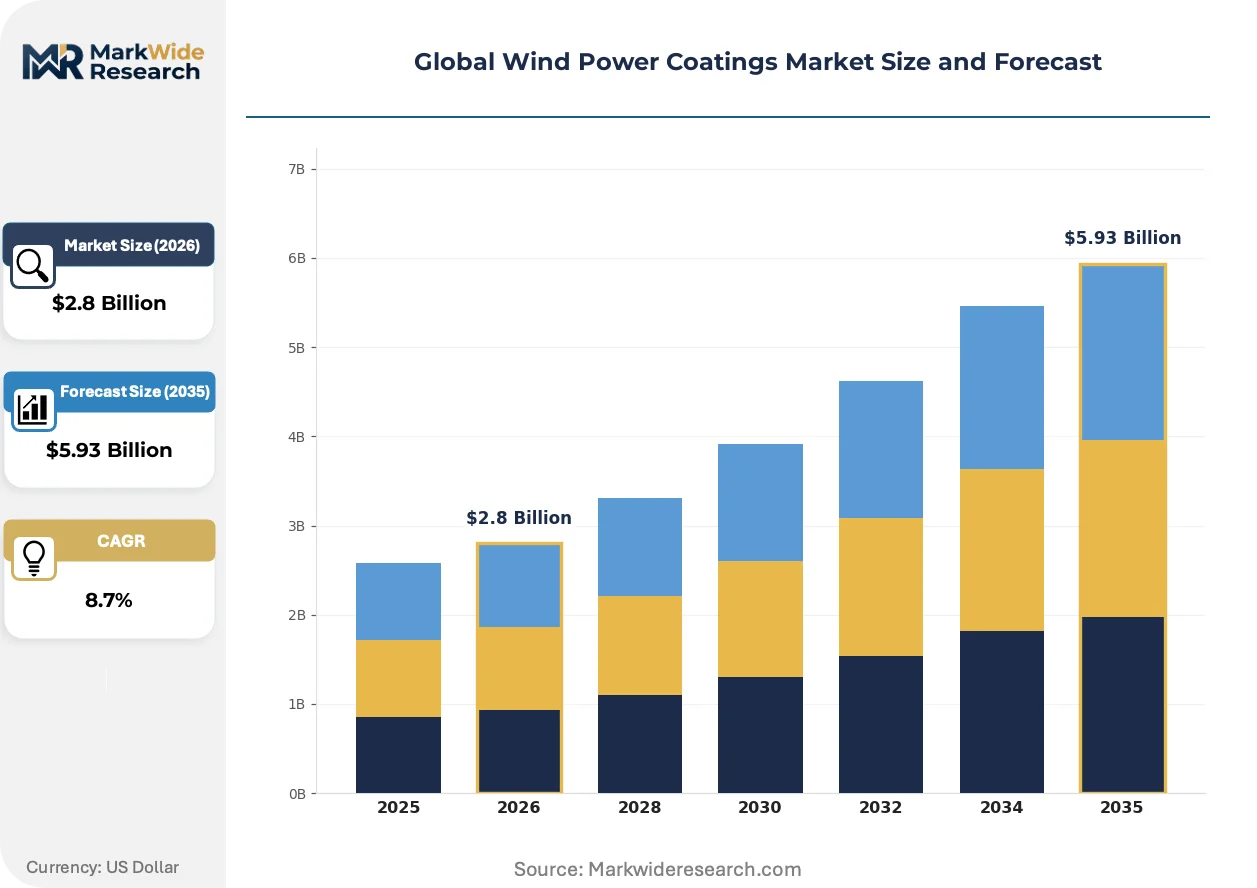
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Epoxy, Polyurethane, Fluoropolymer, Acrylic, Silicone, Alkyd Application Area: Blade Protection, Tower Coating, Nacelle Covering, Hub Coating, Foundation Coating, Lightning Protection Technology: Anti-Corrosion, Anti-UV, Weather Resistant, Hydrophobic, Anti-Fouling, Self-Healing End User: OEM Manufacturers, Maintenance Providers, Tier-1 Suppliers, Wind Farm Operators, Component Assemblers, Service Contractors |
| Companies Covered | Jotun, Teknos, Hempel, BASF Coatings, 3M, AkzoNobel, Mankiewicz, Sherwin Williams, PPG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wind Power Coatings Market Shifts & Advancements
Coating functionality is migrating from passive protection toward active performance monitoring, with material science convergence enabling real-time degradation sensing embedded within blade surfaces.
Ceramic-epoxy hybrid formulations are expanding into offshore monopile splash zones where conventional epoxies fail within 36 months. Danish and German foundation contractors are specifying these systems for 25-year design lives. The technology is compressing maintenance vessel deployment schedules by eliminating interim repair cycles.
REACH authorization requirements for chromium trioxide in anti-corrosion primers are forcing tower fabricators toward titanate and silane-based adhesion promoters. German steel coaters report 15% surface preparation cost increases during the transition. Baltic Sea projects are experiencing the most acute qualification delays as alternative chemistries prove incompatible with existing cathodic protection systems.
Asset owners are consolidating coating procurement under long-term service agreements that bundle application, inspection, and repair. Independent coating contractors in the North Sea basin are losing direct blade access to turbine OEM in-house service divisions. This concentration is most visible in UK Round 4 lease areas where operator-direct contracts now cover 60% of offshore blade maintenance spend.
Global Wind Power Coatings Market Segmentation
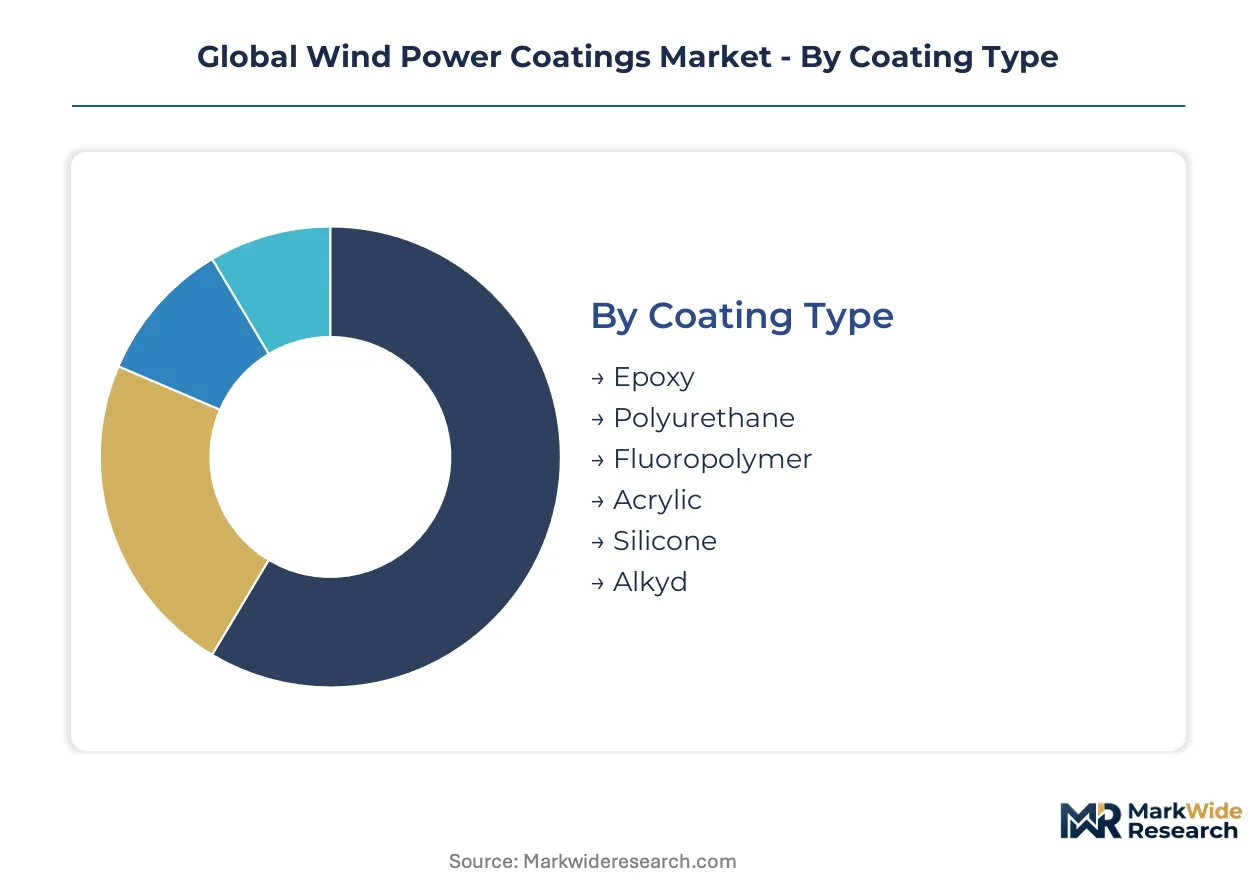
Coating specification directly determines turbine component longevity across marine, desert, and alpine installations. Segmentation reveals how formulation chemistry, application site, functional technology, and procurement channel each shape supplier strategy and pricing architecture.
Coating Type:
Formulation chemistry governs substrate adhesion, thermal cycling tolerance, and reapplication intervals across turbine architectures.
- Epoxy:Two-part thermoset systems deliver cathodic protection compatibility and superior adhesion to steel tower substrates. Demand concentrates in North Sea monopile foundations where saline immersion drives specification toward amine-cured formulations with extended pot life for offshore application windows.
- Polyurethane:Aliphatic isocyanate-based films provide elastomeric flexibility and UV stability for blade leading-edge protection. German and Danish blade OEMs specify these systems for 25-year design lives, though REACH scrutiny of isocyanate hardeners is forcing reformulation toward blocked prepolymer alternatives.
- Fluoropolymer:PTFE and PVDF resin systems occupy premium nacelle covering roles where thermal stability and chemical inertness justify material cost premiums.
- Acrylic:Water-borne emulsion coatings serve temporary protection and touch-up applications during turbine transport and staging.
- Silicone:Room-temperature vulcanizing formulations provide flexible sealing at composite-to-metal interfaces in hybrid tower designs.
- Alkyd:Traditional oil-modified polyester systems persist in maintenance repaint cycles for aging onshore fleets with lower performance requirements.
Mature deployment sits with epoxy systems. Newer deployment is concentrated in fluoropolymer formulations for extended-service offshore specifications.
Application Area:
Physical location on the turbine structure dictates film thickness, weathering exposure, and accessibility constraints for coating contractors.
- Blade Protection:Leading-edge erosion shields and full-surface UV barriers require aerodynamically smooth finishes compatible with composite substrates. Rain droplet impact at tip speeds exceeding 90 m/s drives specification toward elastomeric polyurethane overlays in Scottish and Portuguese offshore arrays.
- Tower Coating:Exterior weathering barriers and internal condensation control systems protect steel tubular structures. Chinese state-backed wind capacity additions under MEE supervision require specialized anti-corrosion formulations with enhanced UV stability for desert and coastal installations.
- Nacelle Covering:Thermal management and EMI shielding coatings protect generator and gearbox housings.
- Hub Coating:Pitch bearing interface protection and bolt corrosion prevention systems secure rotating connections.
- Foundation Coating:Splash-zone barriers and submerged cathodic protection compatibility layers extend substructure service life.
- Lightning Protection:Conductive surface coatings integrate with receptor systems to manage electrical discharge across blade surfaces.
Volume concentration centers on tower coating. Value expansion is climbing fastest in blade protection as service intervals extend from 5 to 10 years.
Technology:
Functional performance attributes separate commodity formulations from premium specifications qualified for extended warranties.
- Anti-Corrosion:Zinc-rich primers and barrier coatings protect steel substrates in saline and industrial atmospheres. REACH authorization requirements for chromium trioxide are forcing German tower fabricators toward titanate and silane-based adhesion promoters with 15% surface preparation cost increases.
- Anti-UV:Hindered amine light stabilizers and UV absorber packages prevent polymer degradation in blade gelcoats. Brazilian and Australian installations with high solar irradiance specify enhanced stabilizer loadings.
- Weather Resistant:Hybrid formulations combining epoxy toughness with polyurethane flexibility serve transitional climate zones.
- Hydrophobic:Fluorosilane surface treatments reduce ice accretion and dirt retention on blade surfaces.
- Anti-Fouling:Biocide-free silicone elastomer coatings prevent marine organism attachment on submerged foundation sections.
- Self-Healing:Microcapsule-based systems with latent curing agents enable autonomous repair of minor coating damage.
Procurement volume concentrates in anti-corrosion specifications. Technology investment is gaining share fastest in self-healing formulations for difficult-access offshore assets.
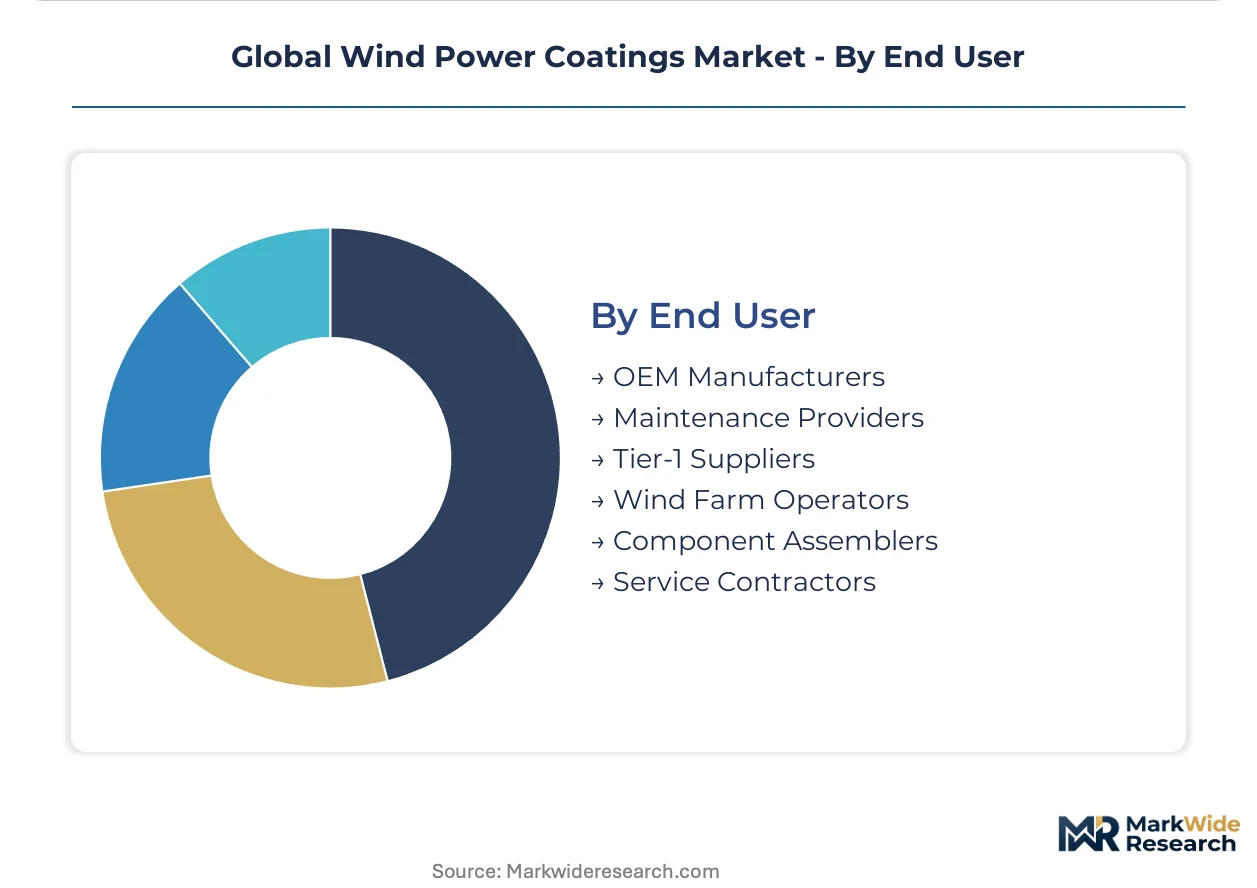
End User:
Procurement channel structure determines qualification requirements, contract duration, and margin capture for coating suppliers.
- OEM Manufacturers:Blade and nacelle producers specify qualified coating systems during original equipment fabrication. Vestas and Siemens Gamesa certification programs extend 18-24 months, freezing formulation innovation cycles for prospective suppliers.
- Wind Farm Operators:Asset owners consolidate coating procurement under long-term service agreements bundling application, inspection, and repair. UK Round 4 lease areas show operator-direct contracts covering 60% of offshore blade maintenance spend.
- Maintenance Providers:Independent service companies execute scheduled repaint and repair campaigns.
- Tier-1 Suppliers:Component subcontractors apply specified coatings under OEM direction.
- Component Assemblers:Tower and foundation fabricators source coatings for structural steel protection.
- Service Contractors:Rope-access and vessel-based teams perform corrective coating interventions.
Contract flow concentrates through OEM manufacturers. Procurement authority is shifting fastest toward wind farm operators seeking lifecycle cost control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam anchors European offshore coating demand through its North Sea port infrastructure serving blade transport and foundation staging. Danish and German North Sea developments drive specification toward 25-year marine-grade systems. Chinese state-backed wind corridors in coastal provinces reshape global formulation requirements.
China
State-backed wind capacity additions under MEE supervision require specialized anti-corrosion formulations with enhanced UV stability for desert and coastal installations. Dual carbon enforcement elevates performance standards for domestically produced coating systems. The Yangtze River Delta clusters blade OEM qualification programs with integrated coating application facilities.
Germany
REACH authorization requirements for chromium trioxide force tower fabricators toward titanate and silane-based adhesion promoters with 15% surface preparation cost increases. Baltic Sea projects experience acute qualification delays as alternative chemistries prove incompatible with existing cathodic protection systems. The North Rhine-Westphalia steel coating corridor consolidates cathodic protection expertise for monopile foundations.
United States
Offshore lease auctions in the Atlantic and Gulf of Mexico drive demand for marine-grade fluoropolymer systems qualified under EPA and OSHA frameworks governing worker exposure limits. FDA and EPA volatile organic compound emissions standards constrain application methods in coastal zones. Texas and Louisiana fabrication yards specialize in monopile coating for Caribbean and Atlantic export markets.
United Kingdom
UK Round 4 lease areas show operator-direct contracts covering 60% of offshore blade maintenance spend, consolidating procurement under long-term service agreements. EU Green Deal corrosion mandates tighten standards for turbine components in saline environments. Scottish floating offshore platforms in Portuguese and Scottish developments demand flexible coating architectures absent from fixed-foundation specifications.
Denmark
Dutch and German foundation contractors specify ceramic-epoxy hybrid systems for 25-year design lives in offshore monopile splash zones. Vestas certification programs extend 18-24 months, freezing formulation innovation cycles for prospective suppliers. Copenhagen-Aarhus corridor anchors blade OEM coating qualification with integrated health management system integration.
Global Wind Power Coatings Market Competitive Landscape
The competitive structure tilts toward marine-grade specialists with fluoropolymer expertise anchoring blade protection contracts. Consolidation concentrates procurement authority among turbine OEM in-house service divisions and state-backed Chinese fabricators. Two strategic archetypes dominate: marine coatings specialists leveraging offshore oil and gas heritage, and diversified chemical conglomerates integrating weather-resistant polyurethane lines with OEM qualification programs. Dominant competitive moves include vertical integration into captive coating application services and strategic partnerships for floating platform specification development.
Within the marine-grade specialist tier, Jotun and Hempel represent archetypes of North Sea blade protection and monopile anti-corrosion formulation respectively. AkzoNobel occupies a position among diversified chemical suppliers integrating polyurethane systems with OEM manufacturer programs. These three anchors illustrate how geographic proximity to offshore development zones and regulatory compliance heritage shape competitive positioning in extended-service coating procurement.
| Leading Market Players |
|---|
| Jotun |
| Teknos |
| Hempel |
| BASF Coatings |
| 3M |
| AkzoNobel |
| Mankiewicz |
| Sherwin Williams |
| PPG Industries |
| Others |
Supply & Pricing Matrix
Ceramic-epoxy hybrid formulation adoption for 25-year offshore monopile specifications simultaneously compresses maintenance vessel deployment schedules and concentrates procurement leverage among Danish and German foundation contractors with integrated application capabilities. REACH authorization timelines for chromium trioxide alternatives are extending qualification cycles, forcing coaters to absorb surface preparation cost premiums while OEM certification programs freeze pricing power for 18-24 month windows.
Pricing Analysis
Performance-guaranteed coating lifespans anchor value-based pricing structures across North Sea offshore developments, with 10-year blade protection warranties commanding material cost premiums over standard 5-year intervals. Three-tier pricing structure across premium fluoropolymer, standard polyurethane, and economy epoxy levels differentiates by certification grade and cathodic protection compatibility. Cost compression in mid-tier polyurethane formulations is intensifying because REACH scrutiny of isocyanate hardeners forces reformulation investments without commensurate performance gains. Independent coating contractors exhibit highest price sensitivity due to wage premiums for certified spray technicians, while turbine OEM in-house service divisions capture least-sensitive procurement through bundled long-term service agreements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand through Vestas and Siemens Gamesa qualification programs, while operator-direct contracts in UK Round 4 lease areas consolidate 60% of offshore blade maintenance spend under bundled procurement. PTFE resin feedstock concentrates among three chemical conglomerates in Germany, Japan, and the United States, exposing coaters to volatile fluorochemical pricing. Raw material dependencies rest on amine curing agents, zinc-rich primers, and titanate adhesion promoters as REACH restrictions displace chromium trioxide. Single-source vulnerability in fluoropolymer resin supply creates structural risk for premium nacelle coating specifications. Distribution runs through Rotterdam port infrastructure serving North Sea blade transport and foundation staging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal corrosion mandates function as a cost-of-compliance story, creating barrier-to-entry moats for coating suppliers with marine-grade fluoropolymer heritage and REACH authorization track records.
For Market Incumbents: Cement qualification program dominance by extending 18-24 month OEM certification timelines into exclusive formulation partnerships with Vestas and Siemens Gamesa blade divisions. Deepen captive coating application services through vertical integration of rope-access technician teams, defending against independent contractor margin erosion in UK Round 4 lease areas.
For New Entrants and Emerging Players: Independent foundation contractors in Portuguese and Scottish floating offshore platforms represent the most penetrable channel partner type, as dynamic cable movement specifications demand flexible coating architectures absent from incumbent fixed-foundation portfolios. Target ceramic-epoxy hybrid qualification gaps in Baltic Sea projects experiencing acute adhesion promoter transition delays.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified chemical conglomerates seeking marine-grade fluoropolymer expertise. Long-term viability favors suppliers with integrated health management system capabilities and REACH-compliant formulation pipelines. Watch ECHA substance restriction announcements as inflection indicators for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Development | Titanate and silane-based adhesion promoters displace chromium trioxide in German tower fabricator specifications. |
| Captive Application Service Integration | OEM in-house service divisions capture 60% of UK Round 4 offshore blade maintenance spend from independent contractors. |
| Floating Platform Specification Partnership | Portuguese and Scottish developments demand elastomeric polyurethane overlays for dynamic cable movement exposure. |
| Embedded Sensor Technology Licensing | Real-time degradation sensing creates recurring service revenue streams integrated with blade health management systems. |
| Long-Term Service Agreement Consolidation | Asset owners bundle application, inspection, and repair procurement under operator-direct contracts in North Sea developments. |
Research Methodology
Document review covered customs and trade data, SEC 10-K filings from listed chemical conglomerates, and ECHA substance authorization databases, complemented by interviews with plant managers at German and Chinese steel coating facilities, procurement leads at Vestas and Siemens Gamesa blade divisions, technical R&D directors at marine coatings specialists, and foundation contractors in Danish and Scottish offshore zones. Bottom-up volume estimates from coating consumption per megawatt installed capacity were triangulated against top-down market value reconstructions.
Historical installation growth patterns were cross-referenced against expert panel inputs from utility planning officers and EPC contractors to derive expansion trajectories across the projection horizon. Segmentation modeling captured coating type, application area, functional technology, and procurement channel dimensions. CAGRs were synthesized from capacity addition pipelines and replacement cycle intensities, with sensitivity testing against MEE dual carbon enforcement timelines and EU Green Deal implementation phases.
Several conditions sit outside the modeled scope, including force majeure disruptions to PTFE resin supply, unilateral regulatory acceleration beyond ECHA announced timelines, and breakthrough self-healing coating technologies achieving commercial scale. Forecasts reflect documented assumptions about OEM qualification program durations and cathodic protection system compatibility. Periodic stress-testing of base assumptions is recommended against evolving national carbon-border mechanisms and their cascading effects on coating qualification costs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Ireland Wind Energy Market
Wind Energy Systems
Onshore Wind Turbine (above 2.5MW) Market
Wind Energy Systems
Wind Turbine Forged Tower Flange Market
Wind Energy Systems
Global Small Wind Power Market
Wind Energy Systems
Thailand Wind Energy Market
Wind Energy Systems
Global Wind Power Equipment Market
Wind Energy Systems
Wind Turbine Yaw and Pitch Gearbox Market
Wind Energy Systems
Bladeless Wind Turbines Market
Wind Energy Systems
Global Small Wind Market
Wind Energy Systems
Quiet Wind Turbine Market
Wind Energy Systems
Offshore Wind Power Market
Wind Energy Systems
Netherlands Wind Energy Market
Wind Energy Systems
Airborne Wind Turbines Market
Wind Energy Systems
Sweden Wind Power Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Control System Market
Wind Energy Systems
Global Wind LIDAR Market