
 North America Gas Generator Market | 2026-2036
North America Gas Generator Market Size, Share, and Industry Trends Forecast 2026-2036
North America Gas Generator Market Analytics
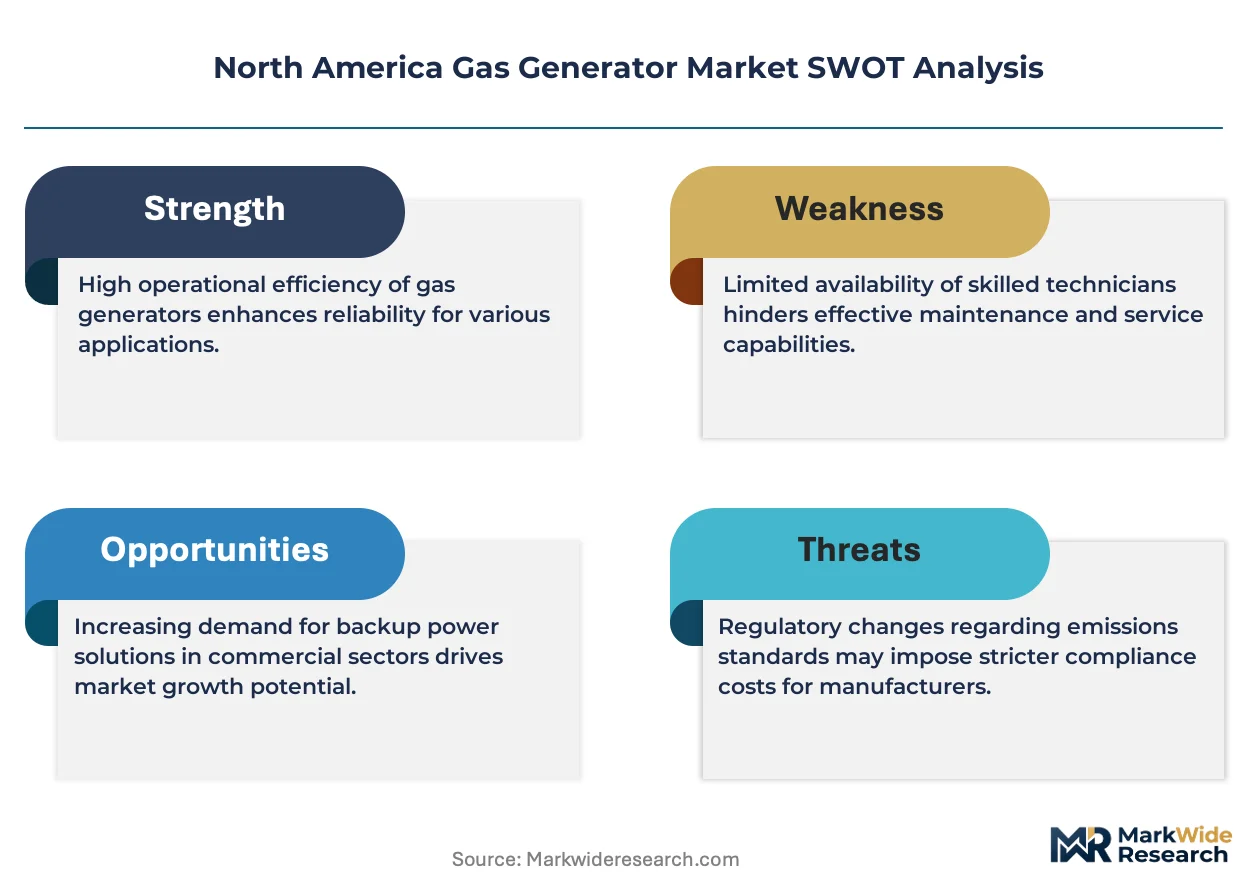
Certified generator technician availability is redrawing competitive boundaries across the North America gas generator landscape. Cummins Inc leverages its dense service network to sustain aftermarket revenue in remote oilfield locations. Caterpillar Inc anchors large-format stationary installations with in-house production of engine blocks and alternators.
North America gas generators are internal combustion engine-driven electromechanical devices that convert natural gas, propane, or biogas into electrical power through electromagnetic induction, typically operating at 3600 or 1800 RPM for 60 Hz output. These systems serve as primary or backup power sources for facilities requiring uninterrupted electricity during grid failures or in off-grid environments. Standby generators dominate commercial and industrial revenue streams due to mandatory uptime requirements in healthcare and data center applications, while portable units occupy a mature residential segment where price sensitivity limits margin expansion. The above 150 kW power rating tier carries the deepest margin pools, as engineering complexity and EPA Tier 4 compliance costs deter commoditization.
EPA stationary engine regulations, NHTSA transportable generator safety standards, and state-level air quality mandates in California and Texas shape product certification requirements and market access timelines. The EPA's Tier 4 final standards for non-road diesel engines have indirectly pushed dual-fuel and dedicated natural gas architectures as compliance pathways. Stakeholders must monitor state renewable gas tariff developments and utility interconnection rule changes to anticipate biogas generator deployment economics.
Market Dynamics
EPA Tier 4 final compliance deadlines are compressing product development cycles across the North America gas generator landscape, forcing manufacturers to re-engineer engine architectures around selective catalytic reduction and exhaust gas recirculation systems before 2028 certification windows close.
Growth Catalysts
- Data Center Buildout:Hyperscale operators in Texas and Virginia are expanding backup power fleets to meet 99.999% uptime SLAs, with natural gas units preferred over diesel for faster startup sequences and lower particulate emissions under state air quality mandates.
- Grid Instability:California's Public Utilities Commission has authorized accelerated interconnection timelines for behind-the-meter generation, driving commercial facility investments in standby gas systems to hedge against rolling blackouts during peak demand events.
- Dual-Fuel Architectures:Engine platforms capable of switching between pipeline natural gas and propane without hardware modification are capturing share in hurricane-prone Gulf Coast markets where fuel supply continuity determines operational resilience.
Market Restraints
- Platinum Group Metal Costs:SCR catalyst substrates rely on palladium and rhodium, with price volatility in South African mining output directly compressing margin structures for Tier 4-compliant engine producers.
- Service Network Concentration:Factory-authorized technician density clusters in metropolitan corridors, leaving remote oilfield and agricultural installations dependent on deferred maintenance schedules that degrade asset lifespans.
- Electrochemical Substitution:Lithium-ion battery energy storage systems paired with solar arrays are displacing gas generators in sub-500 kW commercial applications where runtime requirements fall below four hours.
Strategic Opportunities
- Renewable Natural Gas Tariffs:California and Oregon utility commission rulings on biomethane interconnection pricing create favorable dispatch economics for biogas-fueled generators at wastewater treatment and landfill facilities.
- Microgrid Integration:Texas ERCOT market reforms enabling distributed energy resource aggregation allow gas generator owners to participate in ancillary services markets previously restricted to centralized power plants.
- Industrial Heat and Power:Combined heat and power configurations are penetrating food processing and pharmaceutical manufacturing in the Midwest, capturing waste heat for process steam generation alongside electrical output.
Industry Challenges
- Certified Technician Scarcity:EPA Section 608 refrigerant handling credentials and manufacturer-specific electronic control training requirements have created bottlenecks in field service workforce expansion, particularly for digital engine management diagnostics.
- Emissions Testing Protocol Fragmentation:California Air Resources Board certification cycles run parallel to federal EPA timelines, forcing dual test cell investments and extending product launch schedules by 8-14 months for 50-state compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Gas Generator Market |
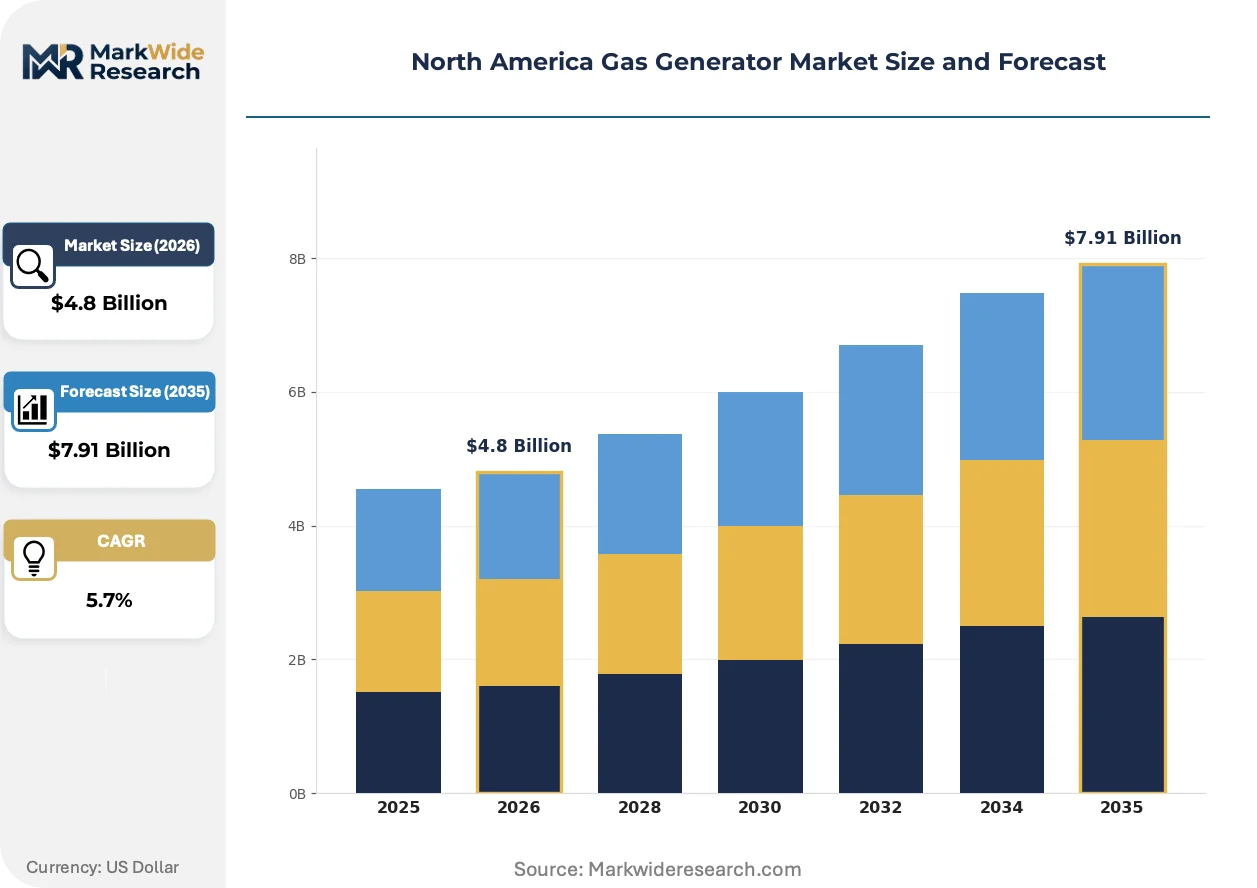
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Generators, Standby Generators, Stationary Generators, Inverter Generators Power Rating: Below 10 kW, 10-50 kW, 50-150 kW, Above 150 kW End User: Residential, Commercial, Industrial, Recreational Fuel Type: Natural Gas, Propane, Biogas, Others |
| Companies Covered | Caterpillar Inc, Generac Holdings Inc, Cummins Inc, Kohler Co, General Electric Company, Mitsubishi Heavy Industries Ltd, MTU Onsite Energy, Ingersoll Rand, Briggs and Stratton, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Gas Generator Market Evolving Landscape
Control system digitization and predictive maintenance platforms are restructuring competitive advantage around uptime guarantees rather than unit economics alone, with remote monitoring capabilities now table stakes for commercial and industrial procurement decisions.
Modular containerized generator packages are displacing traditional skid-mounted installations in data center and healthcare applications. Microsoft and Amazon Web Services procurement specifications now prioritize factory-integrated enclosures with pre-tested exhaust aftertreatment and sound attenuation. This shift compresses on-site construction timelines from weeks to days while reducing commissioning risk for critical facility managers.
EPA's Good Neighbor Plan ozone transport rule is tightening NOx emissions budgets for stationary engines in 23 upwind states. Industrial facility operators in the Ohio River Valley must retrofit or replace pre-Tier 4 equipment ahead of 2026 compliance deadlines. Engine manufacturers are responding with factory-remanufactured power modules that preserve existing alternators and enclosures while upgrading combustion and exhaust systems.
Power-as-a-service contracting models are emerging in the Texas and California commercial segments, with generator OEMs retaining asset ownership and charging per-kWh availability fees. This transfers capital burden from hospital and telecom buyers to equipment financiers while locking in decade-long maintenance revenue streams for service providers. The model is most visible in hurricane-exposed Florida municipalities seeking to offload disaster preparedness capital planning.
North America Gas Generator Market Segmentation
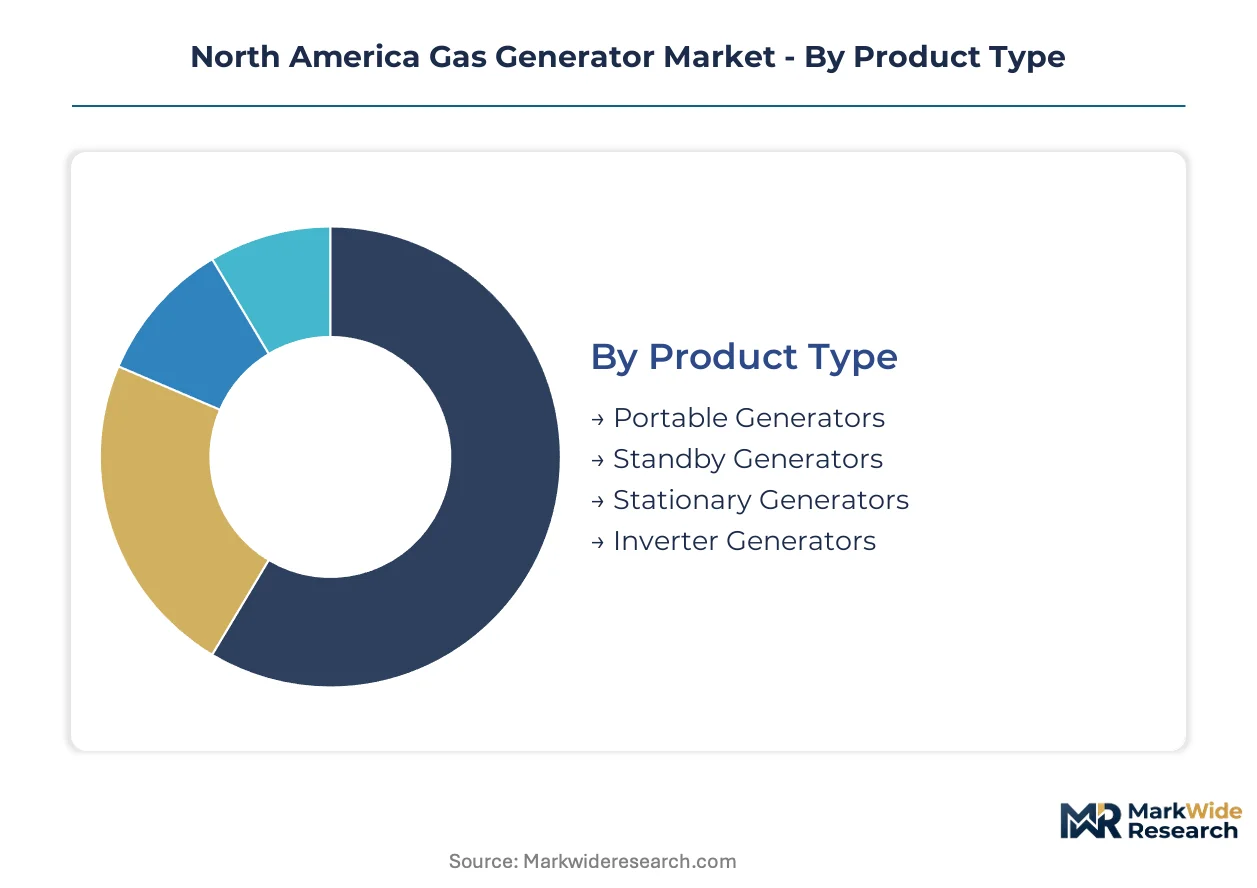
Segment boundaries in the North America gas generator market are shifting as battery storage substitutes encroach on lower power tiers and EPA emissions tiers bifurcate product architectures. Understanding substitution pressure across product, power, end-use, and fuel dimensions reveals where incumbents must defend position versus where new technology can capture share.
Product Type:
Lithium-ion battery systems are displacing portable and small standby units fastest, while large stationary installations retain insulation from electrochemical substitution due to runtime and capital cost requirements.
- Portable Generators:Compact, mobile units typically below 10 kW designed for temporary power at construction sites and residential outage response. Demand concentrates in hurricane-exposed Gulf Coast states where fuel logistics constrain battery alternatives; price compression limits margin expansion as import competition intensifies.
- Standby Generators:Permanently installed automatic-start systems serving as backup power for critical facilities. Healthcare networks in Texas and California anchor procurement volumes as Joint Commission accreditation mandates continuous power availability; EPA Tier 4 compliance costs favor natural gas over diesel architectures in air-quality non-attainment zones.
- Stationary Generators:Large-format prime power or extended-run backup systems serving industrial campuses and data centers. Data center operators in Northern Virginia and Dallas-Fort Worth metroplex drive specifications toward containerized, factory-integrated packages with pre-tested emissions controls.
- Inverter Generators:Variable-speed engine-generator sets producing clean sine wave output suitable for sensitive electronics. Recreational vehicle OEMs in Indiana and Michigan specify these for onboard power; weekend warrior segments in Pacific Northwest outdoor markets sustain replacement demand.
Standby generators retain volume leadership; inverter generators hold the steepest expansion curve as recreational electrification and remote work mobility reshape consumer preferences.
Power Rating:
Cost tier stratification aligns with customer sophistication and regulatory exposure, with premium engineering and compliance investments concentrating in the highest kilowatt brackets.
- Below 10 kW:Residential emergency backup and light commercial applications. Homeowners in Florida and Texas hurricane corridors sustain replacement cycles; retail channel price competition erodes service attachment rates.
- 10-50 kW:Small commercial facilities, restaurants, and retail storefronts. Independent grocery operators in California Public Utilities Commission jurisdictions install these to maintain refrigeration through Public Safety Power Shutoff events.
- 50-150 kW:Mid-size industrial loads and multi-tenant commercial buildings. Regional hospital systems in Midwest states deploy this tier for non-critical building loads; dual-fuel capability commands procurement premiums in propane-dependent rural markets.
- Above 150 kW:Large industrial processes, data center halls, and wastewater treatment facilities. Engineering complexity and EPA Tier 4 aftertreatment integration deter commoditization; factory-authorized service networks become decisive in procurement decisions.
Above 150 kW systems capture the deepest margin pools; below 10 kW units face the most intense price pressure from battery-inverter competition.
End User:
Application-specific uptime requirements and capital deployment timelines create divergent buying behaviors across customer categories.
- Residential:Single-family homeowners seeking outage protection for essential circuits. Storm-frequency geographies in Southeast and Texas sustain seasonal demand spikes; big-box retail distribution dominates procurement channels.
- Commercial:Retail, hospitality, and office facilities requiring business continuity. Financial services firms in New York and Chicago specify natural gas standby to maintain trading floor operations; lease financing structures reduce upfront capital barriers.
- Industrial:Manufacturing, processing, and extraction operations where power interruption incurs production losses. Permian Basin oilfield operators deploy portable natural gas units to power drilling rigs; flare gas utilization improves project economics.
- Recreational:Camping, boating, and tailgating enthusiasts prioritizing portability and noise reduction. Pacific Coast and Mountain West outdoor recreation corridors sustain premium pricing for inverter technology; seasonal demand concentration challenges inventory management.
Industrial end users command the highest per-unit expenditure; recreational buyers are gaining share fastest as outdoor lifestyle participation expands post-pandemic.
Fuel Type:
Supply infrastructure availability and emissions regulatory treatment differentiate fuel economics across North American geographies.
- Natural Gas:Pipeline-delivered methane serving stationary and large portable applications. Metropolitan corridor density in Northeast and Midwest enables lowest-cost fuel access; EPA Good Neighbor Plan ozone transport rules tighten NOx budgets in 23 upwind states.
- Propane:Stored liquid petroleum gas for remote or mobile installations. Rural residential and agricultural markets in Great Plains states depend on tank delivery logistics; dual-fuel engine platforms enable supply switching during pipeline disruption.
- Biogas:Renewable methane from anaerobic digestion at landfills, dairies, and wastewater facilities. California and Oregon utility commission rulings on biomethane interconnection pricing improve dispatch economics; carbon intensity scoring under state clean fuel standards enhances project returns.
- Others:Emerging and blended fuel formulations including hydrogen-natural gas mixtures and synthetic methane pilots. Industrial research consortia in Alberta and Texas Gulf Coast test combustion performance; infrastructure scale constraints limit near-term commercial deployment.
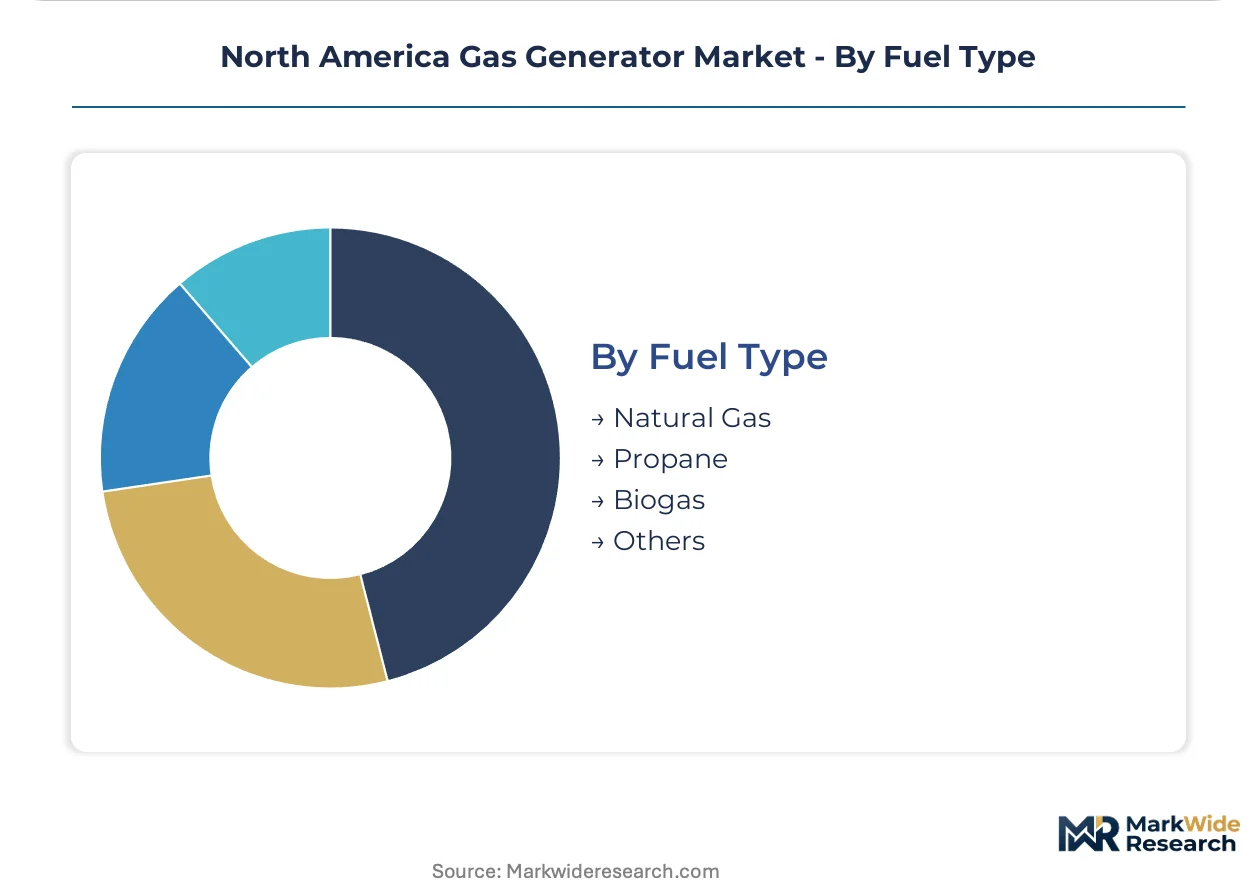
Natural gas retains installed base dominance; biogas is climbing the fastest as renewable natural gas tariffs and carbon accounting frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States gas generator market substantially exceeds Canadian and Mexican equivalents, driven by EPA compliance complexity and data center procurement concentration. Canadian buyers face thinner service networks and longer lead times for Tier 4-certified units. Mexican industrial users navigate fuel infrastructure gaps that compress achievable price premiums.
United States
Texas and California dominate procurement volumes through data center buildouts and grid instability hedging. EPA Tier 4 final standards compress product development cycles ahead of 2028 certification deadlines. Northern Virginia and Dallas-Fort Worth metroplex operators specify containerized factory-integrated packages with pre-tested emissions controls.
Canada
Alberta oil sands operations and Ontario manufacturing anchor demand for large-format stationary systems. Health Canada and Environment Canada coordinate stationary engine emissions regulations that generally align with EPA tiers but introduce province-specific testing protocols. Calgary and Edmonton industrial corridors concentrate procurement for combined heat and power applications.
Mexico
Northern border states and Mexico City industrial zones drive standby generator demand amid grid reliability concerns. Federal electricity commission interconnection rules and state-level air quality programs in Nuevo León shape product certification requirements. Monterrey manufacturing clusters increasingly specify dual-fuel architectures to navigate pipeline delivery interruptions.
North America Gas Generator Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America gas generator landscape. The market structures around a consolidated tier of full-system integrators and a fragmented base of component specialists and regional assemblers. Two strategic archetypes dominate: vertically integrated engine manufacturers with captive alternator production, and modular packaging specialists focused on containerized integration. Competitive moves concentrate on factory-remanufactured power modules and power-as-a-service contracting models that transfer capital burden to equipment financiers.
Within the integrated engine tier, Caterpillar Inc and Cummins Inc exemplify manufacturers with in-house production of engine blocks and alternators. Generac Holdings Inc occupies a position representing the standby power specialist archetype focused on automatic-start systems. These three anchors demonstrate how service network density and factory-authorized technician availability redraw competitive boundaries across remote oilfield and metropolitan corridor deployments alike.
| Leading Market Players |
|---|
| Caterpillar Inc |
| Generac Holdings Inc |
| Cummins Inc |
| Kohler Co |
| General Electric Company |
| Mitsubishi Heavy Industries Ltd |
| MTU Onsite Energy |
| Ingersoll Rand |
| Briggs and Stratton |
| Others |
Value Network & Pricing Analysis
Fourteen-week lead times for EPA Tier 4-certified engine blocks concentrate pricing power with manufacturers holding in-house casting capacity, while deferred maintenance penalties in remote deployments inflate total cost of ownership beyond sticker-price comparisons. Containerized generator packages command 15-25 percent premiums over skid-mounted equivalents as data center procurement teams prioritize commissioning speed and emissions pre-certification.
Pricing Analysis
Configured-to-order pricing for factory-integrated containerized systems runs 30-40 percent above standard skid-mounted configurations, with customization premiums widening as EPA certification complexity escalates. Three-tier pricing structure across premium, standard, and economy levels separates Tier 4-compliant stationary units from dual-fuel mid-tier offerings and import-sourced portable generators. Cost compression in below-50 kW portable tiers intensifies as lithium-ion battery-inverter bundles capture hurricane-season residential demand. Price sensitivity peaks among recreational buyers and residential homeowners, while data center operators prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
United States and Mexico anchor engine block casting and alternator winding operations, while Canada supplies specialized steel enclosures and emissions aftertreatment substrates. Platinum group metals for SCR catalysts draw from South African mining output and Russian refining capacity, creating margin volatility exposure. Single-source vulnerability concentrates in palladium supply chains, where automotive catalytic converter competition constrains generator-industry allocation. Distribution runs through factory-authorized dealer networks for commercial and industrial tiers, with big-box retail channels capturing residential portable volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams expand faster than hardware sales as predictive maintenance platforms and EPA-mandated emissions testing contracts convert transactional generator purchases into decade-long recurring relationships.
For Market Incumbents: Fortify factory-authorized technician density in Permian Basin oilfields and Northern Virginia data center corridors before emerging modular-packaging specialists capture service revenue. Backward integration into alternator production preserves margin pools as copper and rare-earth magnet costs fluctuate. Prioritize EPA Section 608 refrigerant handling credential programs to bottleneck competitor field service expansion. For New Entrants and Emerging Players: Lead with biogas-fueled generator offerings targeting California wastewater treatment facilities and Oregon landfill gas projects where renewable natural gas tariffs improve dispatch economics. Containerized packaging for sub-500 kW commercial microgrids represents the most penetrable white space, with ERCOT ancillary services market participation as the differentiated go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded generator divisions lacking standalone scale to justify Tier 4 compliance investments. Five-to-ten-year viability hinges on service network density rather than manufacturing footprint expansion. Monitor California Air Resources Board rulings on renewable gas interconnection pricing as the signal indicating biogas generator deployment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Factory-Remanufactured Power Modules | Preserves existing alternators while upgrading combustion systems for EPA Good Neighbor Plan compliance. |
| Power-as-a-Service Contracting | Transfers capital burden to equipment financiers while locking in long-term maintenance revenue streams. |
| Dual-Fuel Architecture Development | Enables fuel switching between pipeline natural gas and propane for hurricane-prone Gulf Coast resilience. |
| Predictive Maintenance Platform Deployment | Restructures competitive advantage around uptime guarantees rather than unit economics alone. |
| Renewable Natural Gas Certification | Captures California and Oregon utility commission tariff benefits for biogas-fueled installations. |
Research Methodology
A spread of perspectives from data center facility managers, EPA compliance officers, generator OEM product planners, and independent service dealer principals converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through EIA electricity reliability data, FERC interconnection filings, EPA stationary engine certification records, and state utility commission dockets. Bottom-up unit shipment estimates triangulated against top-down capital expenditure disclosures from hyperscale cloud operators.
Segmentation dimensions modeled include product type, power rating tier, end-use application, fuel architecture, and regional regulatory cluster across the projection horizon. CAGRs derived from regression analysis of historical shipment data against explanatory variables including grid outage frequency, data center construction permitting, and emissions regulation phase-in schedules. Industry-specific forecast inputs incorporate ERCOT market reform implementation pace and California biomethane interconnection tariff rulings.
Forecasts assume regulatory continuity in EPA Tier 4 final standards and state-level air quality mandates; material policy shifts would require re-modeling deployment timelines and compliance cost structures. Recalibration cycles align with material shifts in grid reliability events, hyperscale data center capex announcements, and platinum group metal price volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Marine Gensets Market
Generators
Asia-Pacific Portable Generator Market
Generators
India Diesel Generator Market
Generators
Gas Generator Sets Market
Generators
North West Europe Diesel Generator Market
Generators
Generator [Up to 100 Kva] Market
Generators
South America Generator Sets Market
Generators
Generator Sets Market
Generators
Asia-Pacific Generator Sets Market
Generators
Military Generator Market
Generators
China Gas Generator Market
Generators
North America Generator Sets Market
Generators
Silent Generator Market
Generators
Telecom Generator Market
Generators
Generator (Up to 20 Kva) Market
Generators
Gasoline Generator Market