
 Floating Wind Turbine Market | 2026-2036
Floating Wind Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Floating Wind Turbine Market Analysis
Scotland is tilting toward serial floating wind deployment through Crown Estate leasing rounds and port infrastructure upgrades at Aberdeen and Cromarty Firth. Equinor anchors its position through the Hywind Tampen project and deep-water operational experience. Principle Power leverages its WindFloat platform design to compete across Atlantic and Pacific project pipelines. GE Vernova sustains technology leadership through turbine scaling and offshore-specific drivetrain engineering.
Floating wind turbines are offshore electricity generators mounted on buoyant substructures anchored to seabed depths beyond 60 meters where fixed foundations prove uneconomical, utilizing steel or concrete hulls with dynamic cable systems to transmit power to shore. Semi-submersible platforms currently dominate active project pipelines due to favorable stability characteristics and established installation logistics. Spar buoy designs occupy niche deep-water applications where single-point mooring reduces capital intensity. Above 10 MW capacity segments attract the dominant share of engineering attention as turbine scaling directly improves project-level economics.
The EU Green Deal and F-Gas Regulation shape equipment standards and grid connection requirements across European project zones. EMA guidelines and national maritime regulators in Norway and Portugal enforce environmental impact thresholds that extend permitting timelines but reduce operational risk exposure. Stakeholders must monitor seabed lease auction designs and domestic content rules that determine supply chain localization requirements.
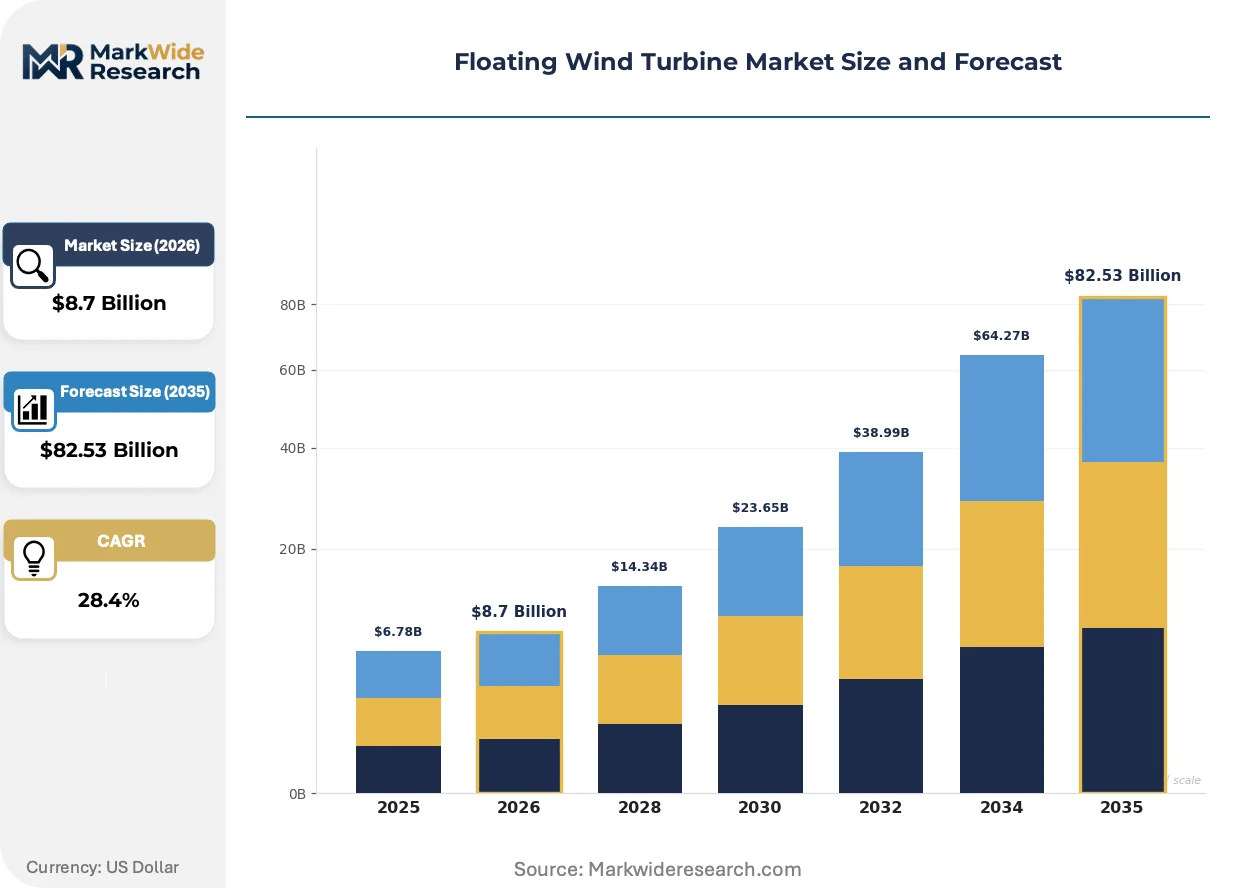
Market Dynamics
Foundation technology competition between semi-submersible, spar, and tension-leg platforms is compressing levelized cost of energy as developers optimize hull steel-to-power ratios for specific site conditions.
Growth Catalysts
- EU Green Deal:Binding offshore renewable targets in member state National Energy and Climate Plans are accelerating seabed lease auctions beyond fixed-bottom depth limits.
- Dynamic cable systems:High-voltage inter-array and export cable innovations rated for 66 kV and above are unlocking serial project deployment in 100-meter-plus water depths.
- Norway:State-backed offtake guarantees through Equinor and Statkraft are de-risking capital commitments for first-commercial arrays.
Market Restraints
- Steel price volatility:Hull fabrication consumes 8,000–15,000 tonnes of specialized marine-grade steel per platform, exposing project returns to commodity cycle swings.
- Port infrastructure concentration:Heavy-lift quayside capacity suitable for 5,000-tonne integrated turbine-platform assembly clusters at fewer than twelve European facilities.
- Grid connection queues:Transmission system operator reinforcement timelines in Scotland and Portugal extend energization schedules by 24–36 months beyond turbine readiness.
Strategic Opportunities
- Japan:Feed-in-tariff revisions and domestic content requirements under METI guidelines are opening Pacific-facing project pipelines previously blocked by seabed geology.
- Green hydrogen co-location:Electrolyzer integration at floating substations enables direct ammonia or e-fuel production, bypassing constrained onshore grid capacity.
- Portugal:Pre-commercial leasing rounds in the Atlantic zone offer test-bed status with streamlined environmental permitting for novel platform configurations.
Industry Challenges
- Marine warranty surveyor capacity:Classification societies DNV and Bureau Veritas face 18-month backlogs for hull and mooring certification, delaying financial close.
- Installation vessel scarcity:Heavy-lift crane vessels with 3,000-tonne-plus capacity are committed to fixed-bottom markets through 2027, constraining floating deployment windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floating Wind Turbine Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $82.53 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hybrids, Tension Leg, Spar Buoy, Semi-Submersible Installation Type: Fixed, Mobile, Portable, Offshore End User: Utilities, Independent Power Producers, Commercial, Residential Capacity: Below 2 MW, 2-5 MW, 5-10 MW, Above 10 MW |
| Companies Covered | Siemens Gamesa Renewable Energy, MHI Vestas Offshore Wind, GE Vernova, Vestas Wind Systems, Mingyang Smart Energy Group, Equinor, Ørsted, Principle Power, BW Ideol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floating Wind Turbine Market Emerging Trajectories
Platform engineering is converging with turbine scaling trajectories as 15 MW-plus machines force redesign of hull stability margins and dynamic load transfer mechanisms.
Concrete-based semi-submersible hulls are migrating from demonstration prototypes to commercial procurement specifications. EPCI contractors in Spain and France are adopting pre-stressed concrete designs that reduce steel mass by 40 percent while extending platform service life to 35 years. This material transition is compressing fabrication cost curves and enabling local supply chain participation in Mediterranean and Atlantic project zones.
The EU F-Gas Regulation is phasing down sulfur hexafluoride use in offshore switchgear, forcing manufacturers to accelerate dry air or vacuum-insulated alternatives for floating substations. Switchgear OEMs are redesigning 145 kV modules for marine environments without SF6 insulation. French and German project zones are experiencing the most acute procurement pressure as 2028 prohibition deadlines approach.
Power purchase agreement structures are fragmenting as offtakers demand route-to-market flexibility. Developers are unbundling construction-phase risk from operational-phase merchant exposure, selling tranches to strategic investors with differentiated return thresholds. This capital-stack innovation is most advanced in Scottish waters where Crown Estate lease terms accommodate multi-party ownership structures.
Floating Wind Turbine Market Segmentation
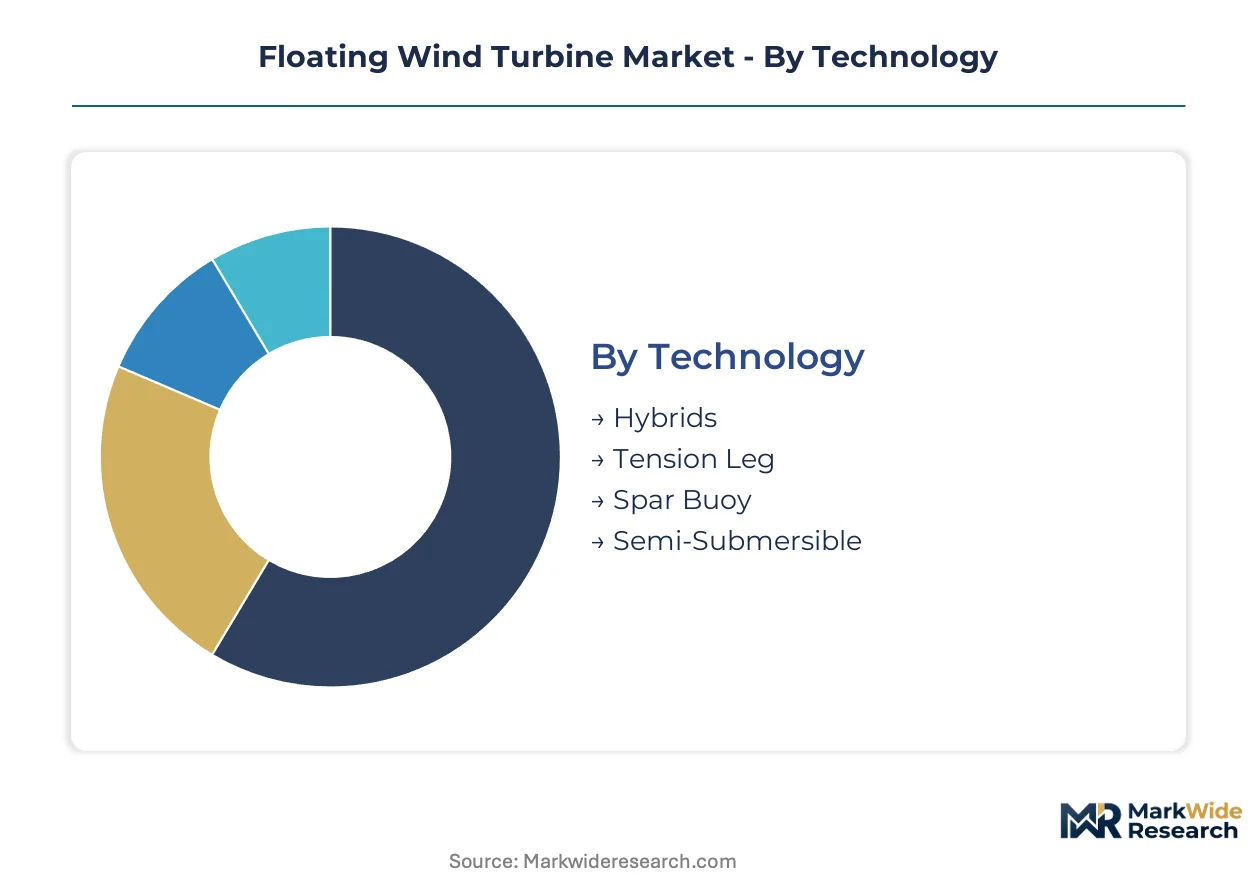
Technology choices in floating wind determine hull steel requirements, installation vessel specifications, and mooring system complexity. Capacity scaling and end-user risk profiles further fragment procurement patterns across project development pipelines.
Technology:
Platform architecture governs stability characteristics, water depth suitability, and capital intensity trade-offs across project zones.
- Semi-Submersible:Wide-base hull configurations distribute turbine loads across multiple columns, enabling quayside assembly and wet-tow deployment without heavy-lift vessels. Scotland and Portugal concentrate demand where water depths range 60–120 meters and port infrastructure supports integrated platform-turbine construction.
- Spar Buoy:Single deep-draft cylinder achieves stability through ballast-induced low center of gravity, minimizing steel mass per megawatt in waters exceeding 200 meters. Norway dominates deployment through Equinor's operational experience and state-backed offtake structures.
- Tension Leg:Vertical tether systems eliminate heave motion, reducing dynamic loading on tower and drivetrain components. Limited active projects due to complex tendon installation and anchor system costs.
- Hybrids:Combined spar-semi-submersible geometries optimize for specific metocean conditions. Early-stage demonstration status with single-unit deployments in Japan and France.
Semi-submersible platforms command the established base. The steepest expansion trajectory runs through spar buoy designs as deeper-water sites enter leasing rounds.
Capacity:
Turbine rating determines platform sizing, mooring line count, and dynamic cable specifications for power export.
- Above 10 MW:15 MW-class machines force redesign of hull stability margins and require triple-point mooring arrays. Engineering attention concentrates here as turbine scaling directly improves project-level economics and capacity factors.
- 5-10 MW:Mature turbine supply chains from fixed-bottom offshore projects enable faster platform certification. Pre-commercial arrays in Portugal and France utilize this segment to de-risk installation sequences.
- 2-5 MW:Early demonstration units and remote island electrification projects. Limited serial deployment due to inferior megawatt-scale economics.
- Below 2 MW:Research platforms and single-unit test beds. Marginal commercial relevance outside technology validation programs.
Above 10 MW turbines attract dominant procurement volumes. The fastest capacity segment gaining share is 5-10 MW as developers balance technology maturity against scale advantages.
End User:
Counterparty credit quality and offtake duration shape project finance structures and equity return thresholds.
- Utilities:Vertically integrated European operators seek long-dated renewable assets to meet decarbonization mandates. Scottish Power and RWE anchor demand through Crown Estate lease commitments.
- Independent Power Producers:Project developers unbundle construction risk from operational merchant exposure, selling tranches to strategic investors. Most advanced capital-stack innovation occurs in Scottish waters.
- Commercial:Corporate power purchase agreements from energy-intensive manufacturers seeking 24/7 renewable supply. Emerging demand segment with limited contracted volume to date.
- Residential:Community-owned micro-grids and island electrification. Negligible addressable market for utility-scale floating technology.
Utilities retain the dominant project ownership position. Independent power producers are expanding most quickly as financial investors acquire operational assets.
Installation Type:
Deployment methodology determines port requirements, vessel specifications, and weather window constraints.
- Offshore:Purpose-built floating substations with integrated high-voltage equipment and dynamic export cables. Standard configuration for utility-scale arrays in Norway and Scotland.
- Fixed:Permanent mooring systems with pre-installed anchor foundations. Dominant approach for commercial-scale projects requiring 25-year operational life.
- Mobile:Relocatable platforms for site assessment or temporary power supply. Niche applications in military and disaster response.
- Portable:Containerized substructure components for rapid assembly. Experimental concept with no commercial deployment.
Fixed installation systems anchor the commercial pipeline. Mobile configurations offer the steepest expansion potential for hybrid renewable-hydrogen applications requiring platform relocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aberdeen's deepwater port upgrades and Cromarty Firth heavy-lift quayside expansions are underwriting Scotland's serial deployment capacity. Norway's Stavanger cluster anchors North Sea operational expertise through integrated mooring and hull fabrication yards.
Scotland
Crown Estate leasing rounds in the North Sea and West of Orkney zones are releasing seabed blocks beyond 60-meter depths. The EU Green Deal mandates 60 GW offshore wind by 2030, accelerating Scottish auction timelines. Aberdeen and Cromarty Firth ports are integrating 5,000-tonne turbine-platform assembly lines.
Norway
Equinor's Hywind Tampen operational data is de-risking spar buoy deployments in 200-meter-plus waters. State-backed offtake guarantees through Statkraft are compressing project finance spreads. The Stavanger-Sandnes cluster concentrates hull steel fabrication and dynamic cable system integration.
Portugal
Pre-commercial Atlantic zone leasing rounds are attracting semi-submersible platform demonstrations. The EU F-Gas Regulation is forcing switchgear redesign for floating substations sited off Viana do Castelo. Port of Leixões is upgrading wet-tow launch capacity for serial WindFloat deployments.
Japan
METI feed-in-tariff revisions are unlocking Pacific-facing pipelines previously blocked by steep seabed gradients. Domestic content requirements are localizing platform steel fabrication to Nagasaki and Yokohama shipyards. The Goto Islands test zone is validating hybrid spar-semi-submersible geometries.
France
Atlantic and Mediterranean seabed auctions are mandating concrete hull specifications to reduce steel mass. EPCI contractors in Saint-Nazaire are adopting pre-stressed concrete designs with 35-year service life targets. The 2028 SF6 prohibition deadline is accelerating dry air switchgear procurement for floating substations.
Floating Wind Turbine Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream on turbine supply, dynamic cable systems, and mooring hardware. The competitive structure fragments across foundation designers, turbine OEMs, and marine EPCI contractors with limited cross-tier consolidation. Three archetypes dominate: integrated energy companies with operational project portfolios, specialized platform technology licensors, and turbine-scale manufacturers adapting offshore drivetrains. Dominant competitive moves include strategic partnerships between hull designers and port operators, plus technology licensing agreements that transfer platform IP across geographies.
Among European integrated energy players, Equinor and Ørsted exemplify the operational-experience archetype through accumulated deep-water project hours. Specialized platform technology sits with Principle Power and BW Ideol, representing divergent design philosophies in semi-submersible and tension-leg configurations. These five entities anchor the competitive landscape without exhaustive market coverage.
| Leading Market Players |
|---|
| Siemens Gamesa Renewable Energy |
| MHI Vestas Offshore Wind |
| GE Vernova |
| Vestas Wind Systems |
| Mingyang Smart Energy Group |
| Equinor |
| Ørsted |
| Principle Power |
| BW Ideol |
| Others |
Supply Flow & Price Mechanics
Heavy-lift vessel undercapacity across North Sea ports compresses installation windows and emboldens turbine OEMs to extract premium pricing for quayside assembly slots. Hull fabricators in Spain and France respond by locking in marine-grade steel contracts twelve months forward, passing commodity exposure through fixed-price EPCI structures.
Pricing Analysis
Three-tier pricing structure across integrated platform-turbine packages, standalone foundation supply, and component-level procurement segments the buyer universe. Premium tiering attaches to quayside-integrated assembly with full marine warranty coverage, while economy positioning targets hull-only supply for self-managed turbine integration. Cost compression in the mid-tier intensifies because concrete-based semi-submersible designs displace steel hulls at 40 percent material savings. Utilities with Crown Estate lease commitments exhibit lowest price sensitivity; independent power producers negotiating merchant offtake structures drive hardest bargain on installation risk transfer.
Supply Chain Analysis
Export-control restrictions on dynamic cable manufacturing equipment limit technology transfer to Korean and Chinese suppliers, constraining European project procurement flexibility. Hull steel fabrication concentrates in Spain, France, and Norway; turbine drivetrain assembly rests on Denmark and Germany. Specialized marine-grade steel, pre-stressed concrete formulations, and high-voltage inter-array cable systems constitute critical input dependencies. Single-source vulnerability runs through heavy-lift crane vessels with 3,000-tonne-plus capacity. Distribution feeds from integrated EPCI contractors to project developers through lump-sum turnkey contracting with milestone-based payment triggers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around Crown Estate leaseholders and state-backed offtakers in Norway, compressing supplier margins and forcing technology licensors toward performance-guarantee pricing.
For Market Incumbents: Harden platform design IP through patent thickets covering hybrid spar-semi-submersible geometries, then anchor fabrication capacity at Aberdeen and Cromarty Firth before port slot scarcity locks out competitors. Threat of concrete hull substitution from EPCI contractors in Saint-Nazaire demands backward integration into pre-stressed concrete formulation expertise. For New Entrants and Emerging Players: Pacific-facing project pipelines in Japan offer the most penetrable geography, where METI domestic content requirements have stalled established European platform licensors. Target semi-submersible demonstrations in the Goto Islands test zone, then leverage operational data for commercial-scale METI feed-in-tariff qualification. Go-to-market positioning should emphasize local steel fabrication partnerships with Nagasaki shipyards. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform technology licensors with multi-project royalty streams across Atlantic and Pacific basins. Long-term viability over the next decade hinges on portfolio diversification beyond single-design dependence. Acquisition targets should demonstrate operational project hours in 100-meter-plus water depths. The signal to watch is Crown Estate auction timing for West of Orkney blocks, which would validate serial deployment economics and re-rate platform IP valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Port Infrastructure Lock-Up | Aberdeen and Cromarty Firth quayside commitments secure 5,000-tonne assembly capacity ahead of competitor access. |
| Concrete Hull Technology Licensing | Pre-stressed concrete IP transfer to Mediterranean EPCI contractors reduces steel dependency and extends platform service life. |
| Dynamic Cable System Integration | 66 kV and above inter-array cable manufacturing partnerships with Korean suppliers bypass EU F-Gas Regulation procurement bottlenecks. |
| Green Hydrogen Co-Location | Electrolyzer integration at floating substations enables direct ammonia production, bypassing constrained Scottish grid connection queues. |
| Marine Warranty Surveyor Capacity Expansion | DNV and Bureau Veritas certification pipeline investments compress 18-month hull and mooring backlogs to accelerate financial close. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EIA offshore wind databases, Crown Estate leasing round documentation, and EU F-Gas Regulation implementation guidance. Project developer interviews, EPCI contractor procurement leads, utility planning officers, and marine warranty surveyors at classification societies provided ground-truth on installation economics and permitting timelines. Customs data on marine-grade steel shipments, IEA renewable energy investment flows, and FERC interconnection queue filings supplied demand-side validation. Bottom-up project pipeline aggregation triangulates against top-down market sizing from national offshore wind targets.
Forecast inputs span platform technology segmentation, turbine capacity scaling trajectories, water depth suitability thresholds, and regulatory framework evolution across the analysis window. Modeled dimensions include semi-submersible versus spar buoy versus tension-leg architecture, above-10 MW versus 5-10 MW capacity tiers, utility versus independent power producer ownership structures, and fixed versus mobile installation configurations. CAGRs derive from project-level LCOE compression curves and seabed lease auction timelines. Industry-specific inputs incorporate Equinor operational data from Hywind Tampen and Principle Power WindFloat deployment metrics.
Practitioners should monitor steel price volatility, heavy-lift vessel charter rate spikes, and grid connection queue extensions for early signals of forecast deviation. Forecasts reflect assumptions on EU Green Deal target continuity and F-Gas Regulation phase-down adherence. Material shifts in Crown Estate auction design, Norway state-backed offtake guarantee withdrawal, or Japan METI feed-in-tariff suspension would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Power Forgings Market
Wind Energy Systems
Taiwan Wind Energy Market
Wind Energy Systems
Germany Offshore Wind Energy Market
Wind Energy Systems
Middle-East and Africa Wind Power Market
Wind Energy Systems
Global Wind Power Equipment Market
Wind Energy Systems
Wind Power Composite Market
Wind Energy Systems
North America Wind Power Market
Wind Energy Systems
Wind Turbine Tower Market
Wind Energy Systems
Europe Direct Drive Wind Turbine Market
Wind Energy Systems
Germany Wind Energy Market
Wind Energy Systems
India Wind Energy Market
Wind Energy Systems
Wind Turbine Operation and Maintenance Market
Wind Energy Systems
North America Large Wind Turbine Market
Wind Energy Systems
United Kingdom Wind Energy Market
Wind Energy Systems
Sweden Wind Energy Market
Wind Energy Systems
Wind Energy Foundation Market