
 Substation Monitoring System Market | 2026-2036
Substation Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Substation Monitoring System Market Analysis
Utility buyers are unwinding legacy capital commitments as independent power producers and renewable energy providers capture a larger share of substation monitoring procurement. Schneider Electric leverages its integrated software-hardware stack to anchor European utility modernization programs. Siemens competes through deep domain expertise in high-voltage switching and protection systems. Sentient Energy specializes in fault-detection analytics for distribution networks, occupying a narrow but defensible technology niche.
A substation monitoring system integrates sensors, data loggers, communication devices, and supervisory control platforms to continuously measure transformer health, busbar temperature, circuit breaker status, and power quality parameters across voltage classes from 11 kV to 765 kV. These systems enable predictive maintenance, reduce unplanned outages, and support real-time grid balancing for utilities and industrial load centers. SCADA platforms retain the largest installed base but cloud-based deployment architectures are expanding fastest as utilities seek scalable analytics without on-premises infrastructure overhead. IoT-enabled sensor networks now dominate new installations, while AI-driven diagnostic modules command premium positioning due to their ability to reduce mean time to repair.
The US Federal Energy Regulatory Commission enforces mandatory reliability standards through NERC CIP that require continuous monitoring of critical substation assets, directly shaping product certification requirements for vendors serving North American utilities. India's Central Electricity Authority mandates communication protocol interoperability under IEC 61850 for all new substation automation projects, creating a compliance floor for market access. Stakeholders must weigh capital intensity against operational savings as grid operators transition from time-based maintenance to condition-based asset management frameworks.
Market Dynamics
Grid operators are abandoning scheduled maintenance calendars for condition-based asset management, forcing vendors to restructure hardware-software bundles around predictive analytics rather than periodic inspection hardware sales.
Growth Catalysts
- IEC 61850 Mandate:India's Central Electricity Authority requires protocol interoperability for all new substation automation, creating compliance-driven replacement cycles across state transmission utilities.
- NERC CIP Enforcement:The US Federal Energy Regulatory Commission mandates continuous critical asset monitoring, directly expanding certified product demand from North American transmission operators.
- Photovoltaic Interconnection:Utility-scale solar farms require real-time power quality monitoring to manage bidirectional flow and voltage fluctuation at 33 kV and 66 kV injection points.
Market Restraints
- Copper and Rare Earth Volatility:Sensor housings and magnetic components face input cost swings that compress hardware margins and delay utility procurement cycles.
- Legacy SCADA Lock-In:Proprietary communication protocols from 1990s installations create technical debt that raises integration costs for cloud-native monitoring platforms.
- Skilled Technician Scarcity:Utilities report insufficient field personnel trained in IEC 61850 configuration, slowing deployment timelines for digital substation retrofits.
Strategic Opportunities
- Distribution Network Extension:Medium-voltage rural feeders in India and Southeast Asia remain undermonitored, creating white space for compact, solar-powered sensor nodes.
- Edge-AI Convergence:On-device inference chips paired with thermal imaging cameras enable localized fault prediction without continuous backhaul bandwidth.
- Green Tariff Linkage:Renewable energy certificates in European markets increasingly require verified grid stability contributions, attaching monitoring data to revenue streams.
Industry Challenges
- Cybersecurity Certification Lag:NERC CIP Version 7 implementation timelines outpace vendor product recertification, creating compliance gaps for utilities with accelerated procurement schedules.
- Interoperability Testing Bottleneck:Multi-vendor IEC 61850 conformance verification requires specialized laboratory capacity that remains concentrated in Germany and Japan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Substation Monitoring System Market |
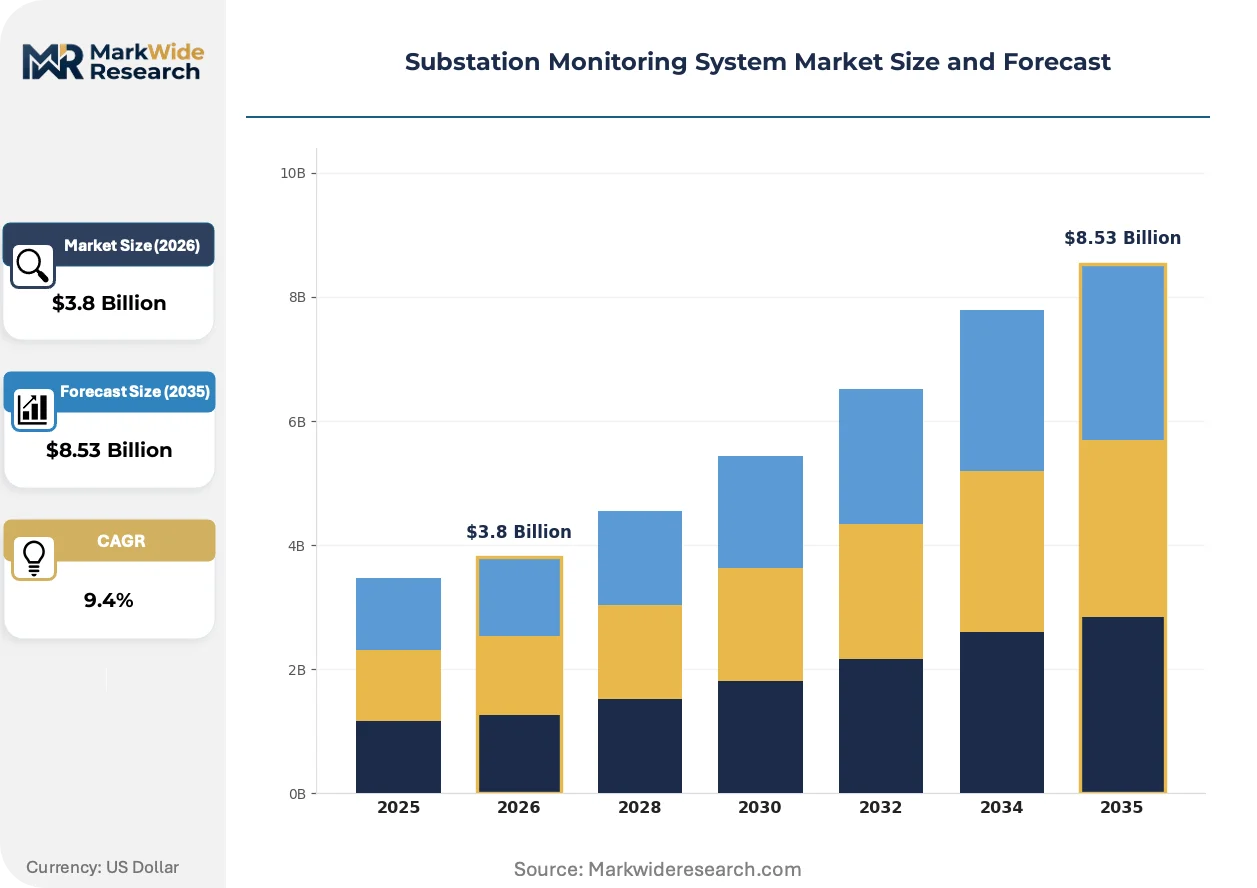
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
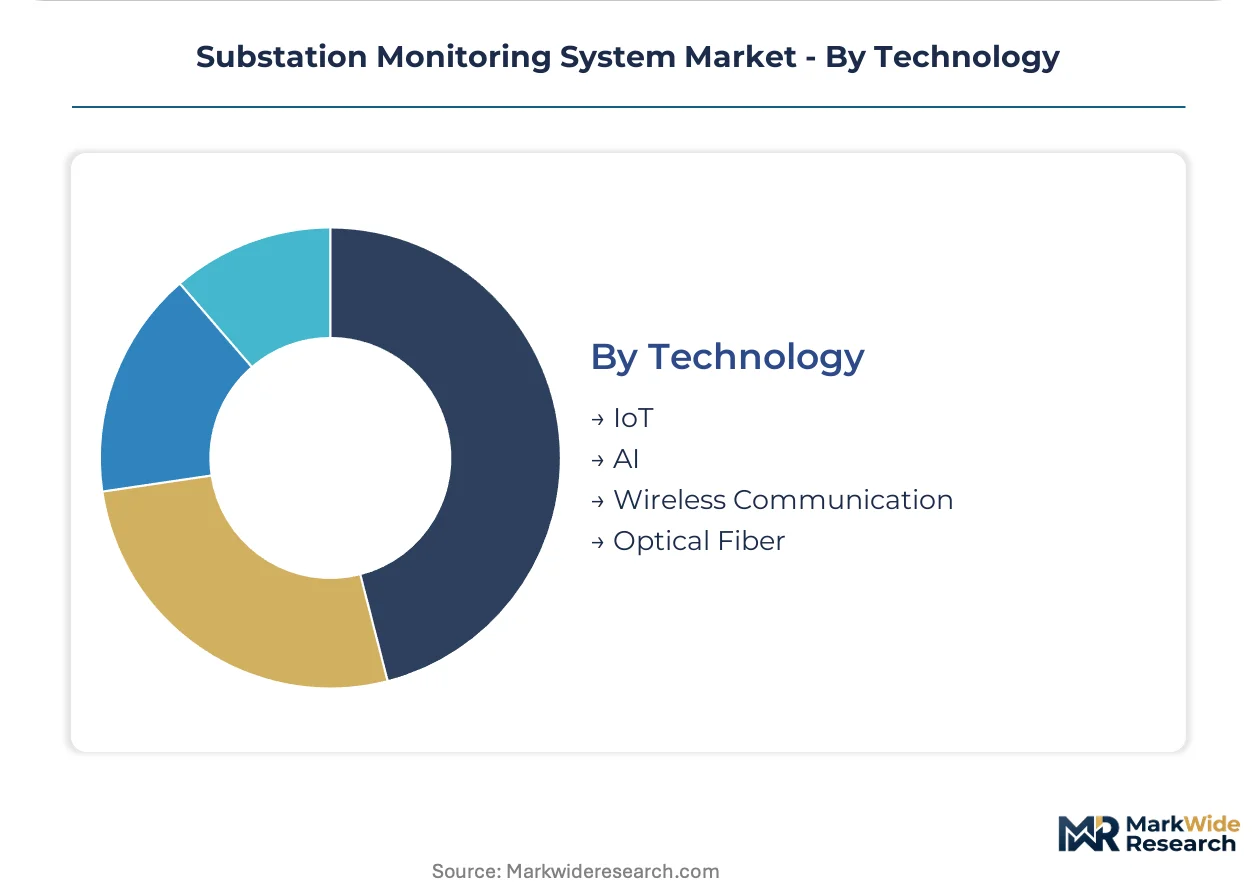
| Segmentation | Product Type: SCADA, Data Loggers, Sensors, Communication Devices End User: Utilities, Industrial Facilities, Renewable Energy Providers, Independent Power Producers Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Technology: IoT, AI, Wireless Communication, Optical Fiber |
| Companies Covered | ABB Ltd., Schneider Electric, Siemens, Eaton Corporation, Schweitzer Engineering Laboratories, Sentient Energy, Emerson Electric, GE Vernova, Honeywell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Substation Monitoring System Market Emerging Trajectories
Sensor-to-cloud architectures are fragmenting traditional SCADA hierarchies, enabling new entrants to bypass incumbent hardware channels through software-first deployment models.
Digital twin platforms for transformer health monitoring are bifurcating the vendor landscape. European transmission operators deploy high-fidelity thermal and dissolved gas analysis models for strategic 400 kV assets. Asian utilities adopt lighter, standardized templates for rapid rollout across distribution substations. The technology is bifurcating procurement into premium analytics suites versus commodity sensor networks.
REACH restrictions on per- and polyfluoroalkyl substances are accelerating fluorinated gas replacement in switchgear insulation. The European Chemicals Agency enforcement timeline compresses equipment refresh cycles for utilities with SF6-dependent switchyards. German and French grid operators now specify sealed-for-life vacuum interrupters with integrated pressure monitoring in new 145 kV installations.
Power purchase agreement structures now embed grid stability clauses that require independent verification of reactive power support and fault ride-through performance. Renewable asset owners in India and Brazil procure third-party monitoring services to document compliance for offtake contract renewals. This contractual shift transfers monitoring procurement decisions from EPC contractors to long-term asset operators.
Substation Monitoring System Market Segmentation
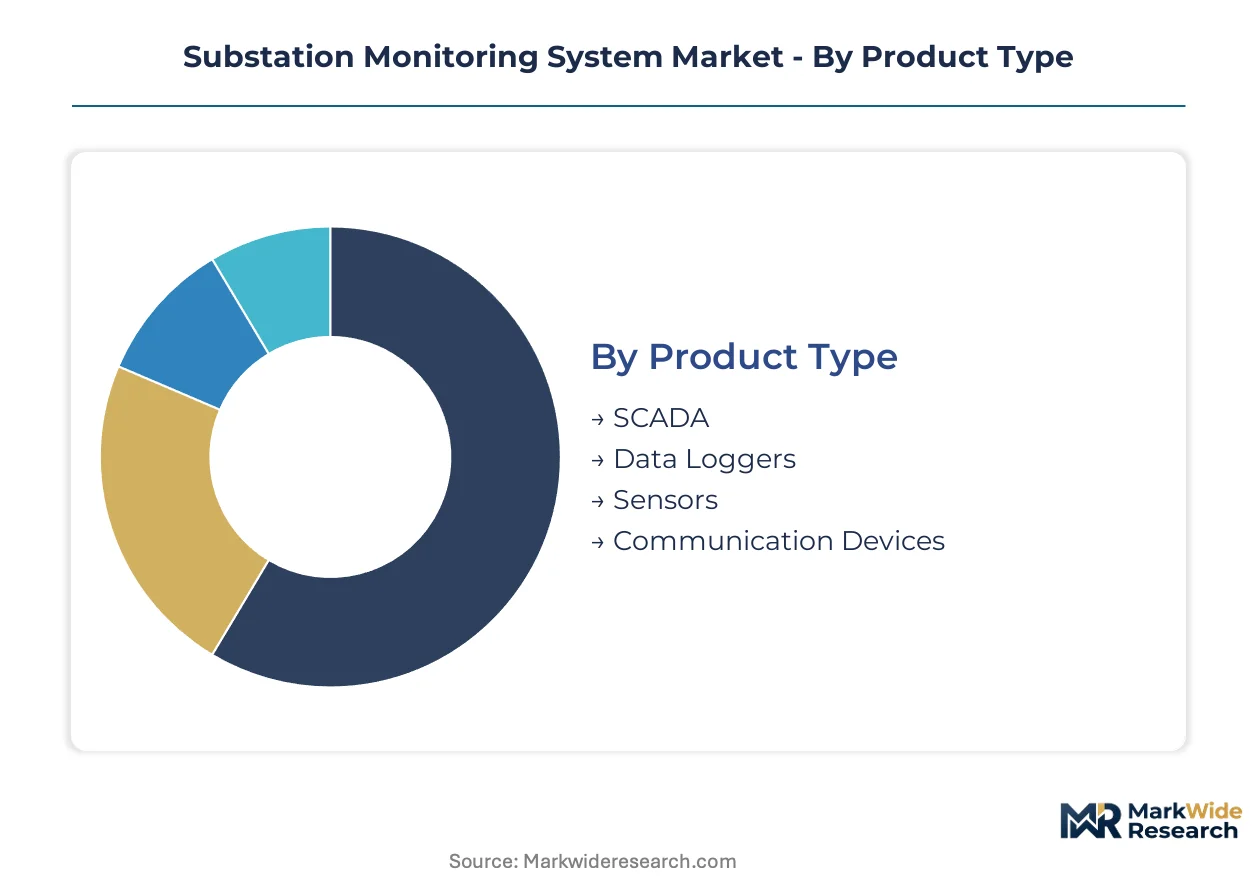
Substation monitoring procurement fragments across voltage classes, regulatory jurisdictions, and operational maturity levels. Buyers prioritize interoperability certifications over feature breadth, compressing vendor differentiation into compliance execution rather than raw technical specification.
Product Type:
FERC NERC CIP mandates in the US and CEA IEC 61850 directives in India create divergent certification burdens that reshape hardware-software bundling strategies.
- SCADA:Legacy supervisory platforms dominate installed base across transmission utilities. Indian state transmission utilities under CEA mandates drive replacement cycles as IEC 61850 compliance deadlines approach.
- Sensors:IoT-enabled thermal, partial discharge, and dissolved gas analysis units now anchor new installation specifications. Renewable energy providers in Gujarat and Rajasthan procure compact sensor arrays for 33 kV solar injection points.
- Data Loggers:Edge-capable acquisition devices with local storage buffer intermittent connectivity in rural feeders.
- Communication Devices:Protocol gateways bridge proprietary legacy buses to IEC 61850-9-2LE sampled value streams.
Established volume favors SCADA; emerging adoption favors Sensors.
End User:
Procurement authority is migrating from EPC contractors to long-term asset operators as power purchase agreements embed grid stability verification clauses.
- Utilities:State and private transmission operators under FERC jurisdiction in the US and CEA oversight in India account for bulk procurement. These buyers demand NERC CIP Version 7 certification and IEC 61850 Edition 2.1 conformance as table stakes.
- Renewable Energy Providers:Utility-scale solar and wind asset operators require real-time power quality monitoring for bidirectional flow management. Indian renewable developers face mandatory digital substation upgrades under national grid modernization directives.
- Industrial Facilities:Steel, cement, and petrochemical load centers deploy monitoring for internal power quality assurance and tariff optimization.
- Independent Power Producers:Merchant generators procure third-party monitoring services to document reactive power support for offtake contract renewals.
Contractual liability concentrates procurement among Utilities; margin expansion concentrates among Renewable Energy Providers.
Deployment:
Capital intensity thresholds and cybersecurity exposure determine architecture selection across voltage classes and regulatory environments.
- Cloud-Based:Scalable analytics without on-premises infrastructure overhead attracts mid-sized utilities with limited IT staffing. European transmission operators pilot centralized diagnostic platforms for distribution network fleets.
- Edge Computing:On-device inference chips enable localized fault prediction without continuous backhaul bandwidth. Asian utilities deploy edge-AI thermal imaging at 145 kV switching stations.
- On-Premises:Air-gapped SCADA retains dominance in critical 400 kV transmission hubs under strict NERC CIP perimeter controls.
- Hybrid:Tiered architectures isolate operational technology networks while feeding sanitized data to cloud analytics layers.
Security compliance preserves On-Premises share; operational flexibility drives Cloud-Based expansion.
Technology:
Component sourcing constraints and interoperability testing bottlenecks in Germany and Japan reshape technology roadmaps.
- IoT:Low-power wide-area sensor networks now dominate new installations across medium-voltage distribution. REACH restrictions on per- and polyfluoroalkyl substances accelerate hardware refresh cycles in European deployments.
- AI:Diagnostic modules command premium positioning through reduced mean time to repair. Machine learning models trained on transformer dissolved gas analysis data sets differentiate vendor offerings.
- Wireless Communication:Private LTE and 5G private networks replace licensed radio for substation-to-control-center links.
- Optical Fiber:IEC 61850-9-2LE process bus implementations drive fiber deployment in greenfield digital substations.
Installed base concentration rests with IoT; capability differentiation clusters around AI.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility procurement authority clusters among state transmission operators in India, merchant renewable developers in the United States, and integrated grid operators in Germany. Each buyer archetype imposes distinct certification requirements that reshape vendor market access. Regional regulatory fragmentation creates compliance-driven replacement cycles rather than organic technology refresh.
United States
Merchant solar and wind asset operators drive demand for power quality verification systems at 33 kV and 66 kV interconnection points. FERC enforces NERC CIP Version 7 standards that mandate continuous critical asset monitoring, directly expanding certified product procurement from transmission operators. Texas and California grid operators lead deployment of cloud-based diagnostic platforms for distributed renewable fleets.
India
State transmission utilities under CEA oversight face mandatory IEC 61850 protocol interoperability deadlines for all new substation automation projects. Renewable energy providers in Gujarat and Rajasthan procure compact sensor arrays for utility-scale solar injection points. National grid modernization directives compress procurement timelines across Maharashtra and Karnataka transmission zones.
Germany
ECHA REACH restrictions on per- and polyfluoroalkyl substances accelerate fluorinated gas replacement in switchgear insulation, compressing equipment refresh cycles. Transmission operators in North Rhine-Westphalia and Bavaria specify sealed-for-life vacuum interrupters with integrated pressure monitoring for new 145 kV installations. Green tariff structures attach monitoring data verification to renewable energy certificate revenue streams.
China
State Grid Corporation drives standardization of digital substation architectures across provincial transmission networks. MIIT promotes domestic IEC 61850 conformance testing capacity to reduce dependency on German and Japanese laboratories. Yangtze River Delta utilities pilot edge-AI thermal imaging at 220 kV switching stations for localized fault prediction.
Japan
METI funding supports development of high-fidelity digital twin platforms for strategic 400 kV transformer assets. Regional utilities in Kansai and Chubu regions adopt lighter, standardized monitoring templates for rapid distribution substation rollout. Domestic semiconductor fabricators supply on-device inference chips for edge computing deployments.
Substation Monitoring System Market Vendor Landscape
Player mix skews toward diversified electrical equipment conglomerates with integrated software-hardware stacks. Market structure concentrates among three to five integrated industrial groups that anchor transmission utility procurement channels alongside specialized sensor analytics firms occupying narrow technology niches. Two strategic archetypes dominate: full-stack platform vendors bundling SCADA with predictive analytics modules, and point-solution specialists in fault detection and thermal diagnostics. Competitive moves center on strategic partnerships with cloud infrastructure providers and portfolio diversification into edge-AI diagnostic modules.
Among integrated European industrial groups, ABB Ltd. and Schneider Electric exemplify the full-stack archetype with software-hardware integration spanning protection relays to supervisory platforms. Siemens occupies a position bridging high-voltage switching expertise with digital substation automation. Sentient Energy represents the specialist tier, anchoring distribution network fault-detection analytics. These three companies illustrate the competitive bifurcation between breadth-driven platform consolidation and depth-driven diagnostic specialization.
| Leading Market Players |
|---|
| ABB Ltd. |
| Schneider Electric |
| Siemens |
| Eaton Corporation |
| Schweitzer Engineering Laboratories |
| Sentient Energy |
| Emerson Electric |
| GE Vernova |
| Honeywell |
| Others |
Supply Flow & Price Mechanics
Vacuum interrupter substitution for SF6-dependent switchgear simultaneously shifts procurement toward German and Japanese component suppliers and compresses hardware margins as REACH compliance costs embed into equipment pricing. Indian state transmission utilities and European grid operators now negotiate multi-year framework agreements indexed to copper and rare earth price baskets, transferring commodity volatility risk between vendors and buyers.
Pricing Analysis
Cost-plus contracts with London Metal Exchange copper indexation dominate procurement for sensor housings and magnetic components. Price differentiation separates NERC CIP Version 7 certified systems from uncertified alternatives, with Indian CEA-mandated IEC 61850 conformance commanding additional protocol gateway premiums. Pricing pressure stems from legacy SCADA integration costs that inflate total deployment expenditure for cloud-native platforms. Renewable energy providers in Gujarat and Rajasthan exhibit highest price sensitivity due to competitive auction dynamics, while German transmission operators prioritize certification compliance over unit economics.
Supply Chain Analysis
Inventory buffers for edge-AI inference chips stretch to twenty-six weeks as Taiwanese semiconductor fabricators prioritize automotive and consumer electronics allocations. Component sourcing concentrates in Germany for IEC 61850 conformance testing equipment, Japan for high-fidelity dissolved gas analysis sensors, and China for IoT-enabled thermal imaging modules. Supply chain risk centers on single-source dependency for specialized laboratory certification capacity concentrated in Stuttgart and Yokohama. Distribution runs through authorized system integrators who bundle hardware installation with multi-year predictive analytics subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Substation monitoring procurement is transitioning toward service-attach models where predictive analytics subscriptions expand faster than capital hardware sales, particularly among Indian renewable developers seeking operational expenditure treatment for grid compliance investments.
For Market Incumbents: Shield installed base relationships by embedding proprietary AI diagnostic modules into existing SCADA architectures before cloud-native entrants displace periodic hardware refresh cycles. Acquire IEC 61850 Edition 2.1 pre-certification capacity in Germany to compress bid response timelines for Indian state transmission utility tenders. Prioritize backward integration into edge computing chip design to reduce dependency on Taiwanese semiconductor allocation priorities. For New Entrants and Emerging Players: Differentiate on solar-powered sensor node deployment for undermonitored medium-voltage rural feeders in Maharashtra and Karnataka where incumbent coverage remains sparse. Target compact dissolved gas analysis units for 33 kV solar injection points in Rajasthan where utility-scale renewable operators lack dedicated monitoring infrastructure. Pursue direct engagement with long-term asset operators rather than EPC contractors as power purchase agreement clauses transfer procurement authority. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed sensor analytics specialists holding narrow but defensible fault-detection technology positions. Five-to-ten year viability hinges on successful platform consolidation into full-stack offerings capable of capturing utility-scale procurement. Monitor NERC CIP Version 7 recertification timelines as inflection indicator for vendor compliance burden and competitive displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Combines SCADA legacy systems with cloud-native analytics layers for hybrid deployment architectures. |
| Acquisition of Specialist Firm | Captures fault-detection IP from narrow technology vendors like Sentient Energy's distribution network focus. |
| Geographic Expansion | Establishes IEC 61850 conformance testing capacity in India to bypass German and Japanese laboratory bottlenecks. |
| Strategic Partnership | Links monitoring data verification to European renewable energy certificate revenue streams under green tariff structures. |
| Product Launch | Introduces edge-AI thermal imaging modules for localized fault prediction at 145 kV switching stations. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators across India, Germany, and the United States; and secondary validation against FERC filings, CEA directives, EIA project databases, and IEC standard documentation. Primary fieldwork captured procurement authority migration patterns and certification timeline pressures. Secondary sources included customs records for sensor component trade flows, SEC disclosures from listed electrical equipment conglomerates, and national grid modernization policy texts. Bottom-up unit economics for sensor deployments were triangulated against top-down transmission utility capital expenditure aggregates.
Across the analysis window, the forecasting framework modeled volume and value trajectories by voltage class, deployment architecture, end-user segment, and regional regulatory cluster. Segmentation dimensions included product type differentiation between legacy SCADA and IoT-enabled sensor networks, deployment mode across cloud-based and edge computing architectures, and technology tier separating commodity hardware from AI-driven diagnostic modules. CAGRs were derived from fitted growth curves anchored to disclosed utility procurement pipelines and renewable interconnection queue data. Industry-specific inputs incorporated IEC 61850 mandate compliance deadlines and NERC CIP enforcement intensity variations.
Forecasts assume regulatory continuity in FERC NERC CIP enforcement, CEA IEC 61850 mandate timelines, and ECHA REACH restriction implementation; material policy shifts in these regimes would require re-modeling. Specific risks include copper and rare earth price volatility compressing hardware margins, skilled technician scarcity delaying digital substation retrofits, and cybersecurity certification lag creating compliance gaps. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
South America City Gas Distribution Market
Transmission and Distribution
Pipeline Monitoring System Market
Transmission and Distribution
Submarine Electricity Transmission Systems Market
Transmission and Distribution
Europe Active Network Management Market
Transmission and Distribution
Wireless Power Transmission Market
Transmission and Distribution
Digital Substation Market
Transmission and Distribution
Japan High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Canada High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
DC Distribution Network Market
Transmission and Distribution
Global Industrial Distribution Market
Transmission and Distribution
Transmission and Distribution Fault Detection Market
Transmission and Distribution
Underground Cabling EPC Market
Transmission and Distribution
Transmission Line Market
Transmission and Distribution
Middle East Gas Pipeline Infrastructure Market
Transmission and Distribution
Ring Main Unit Market
Transmission and Distribution
Power Transmission Component Market