
 Quiet Wind Turbine Market | 2026-2036
Quiet Wind Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Quiet Wind Turbine Market Analytics
Aerodynamic engineering talent scarcity is reorganizing how manufacturers allocate R&D budgets across Europe and Asia. Siemens Gamesa leverages its blade-design heritage to dominate low-noise offshore platforms. Vestas Wind Systems sustains competitive pressure through direct-drive gearless architectures that eliminate mechanical whine. Goldwind anchors Chinese supply with permanent-magnet generators purpose-built for near-silent operation.
Quiet wind turbines integrate aerodynamic shaping, advanced composite materials, and variable-speed control to reduce acoustic emissions below 40 decibels at source, serving residential zones, noise-sensitive wildlife corridors, and urban peripheries where conventional rotors face permitting barriers. Horizontal axis turbines occupy the bulk of current installed capacity, yet ducted turbines are capturing margin pools in built environments where space constraints and strict noise codes apply. Smart turbine technology with real-time pitch adjustment is expanding fastest among utility-scale repowering projects seeking community acceptance.
EPA noise guidelines in the United States, EU Green Deal renewable targets, and Germany's Federal Immission Control Act collectively tighten permissible sound levels and accelerate permit timelines for compliant systems. China's MIIT enforces GB standards for mechanical noise in distributed energy equipment, shaping export qualification requirements for domestic manufacturers. Stakeholders must monitor how municipal zoning boards reconcile decibel limits with height restrictions, as this tension determines addressable market geometry more than turbine efficiency alone.
Market Dynamics
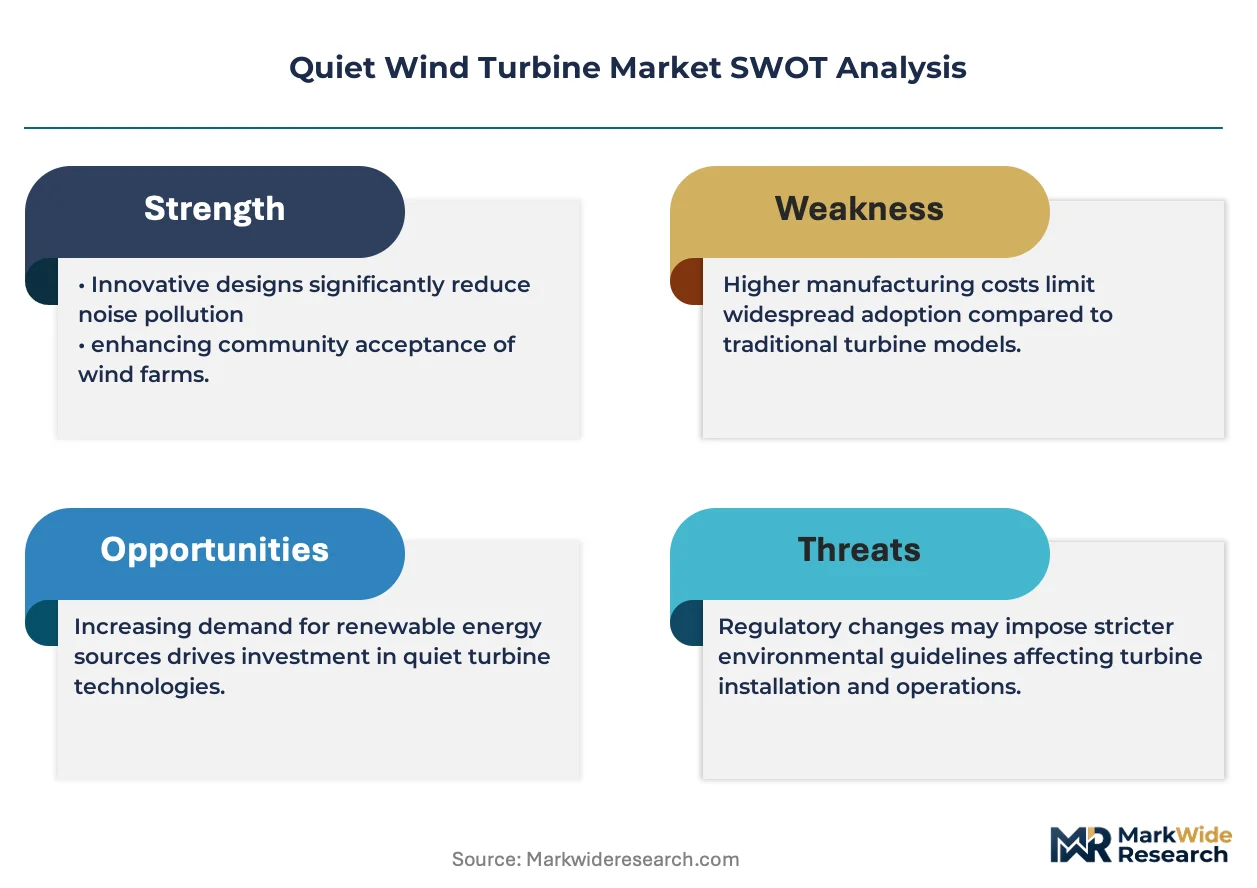
Municipal noise ordinances are compressing addressable installation zones faster than turbine efficiency gains can expand them, forcing manufacturers to prioritize decibel reduction over rated capacity in R&D allocation decisions.
Growth Catalysts
- EU Green Deal renewable targets:Binding national quotas for distributed generation accelerate permitting timelines for sub-45 dB systems in residential zones across Denmark, Germany, and Spain.
- Bladeless aerodynamic architectures:Vortex-induced vibration harvesters eliminate rotor noise entirely, opening wildlife corridors and peri-urban sites previously excluded by acoustic constraints.
- Basque Country zoning reforms:Municipal codes in San Sebastián and Bilbao now mandate sub-40 dB thresholds for new construction-adjacent installations, creating first-mover advantage for compliant suppliers.
Market Restraints
- Rare-earth magnet supply concentration:Neodymium processing dominance by Chinese refiners exposes permanent-magnet generator costs to export quota volatility and geopolitical friction.
- Advanced composite input costs:Carbon fiber prepreg prices fluctuate with aerospace sector demand, squeezing margin on noise-dampening blade shells and ducted shrouds.
- Acoustic certification timelines:Germany's Federal Immission Control Act requires 18-24 month field measurement protocols, delaying revenue recognition for new product variants.
Strategic Opportunities
- Coastal Denmark repowering wave:Aging onshore fleets in Jutland and Funen face 20-year replacement cycles, with community acceptance hinging on noise reduction guarantees.
- Real-time pitch-smart convergence:Integration of edge-computing controllers with aerodynamic shaping enables dynamic noise suppression during high-wind events.
- Bavarian agricultural co-operative channel:Farmer-owned energy associations bypass traditional utility procurement, purchasing direct from manufacturers with noise-performance service agreements.
Industry Challenges
- Aeroacoustic simulation talent scarcity:Computational fluid dynamics specialists with wind-noise expertise command premium compensation, constraining in-house design team scaling.
- Multi-jurisdiction certification burden:Separate acoustic test protocols under EPA guidelines, EU harmonized standards, and China's GB codes force redundant validation spend for export-oriented manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quiet Wind Turbine Market |
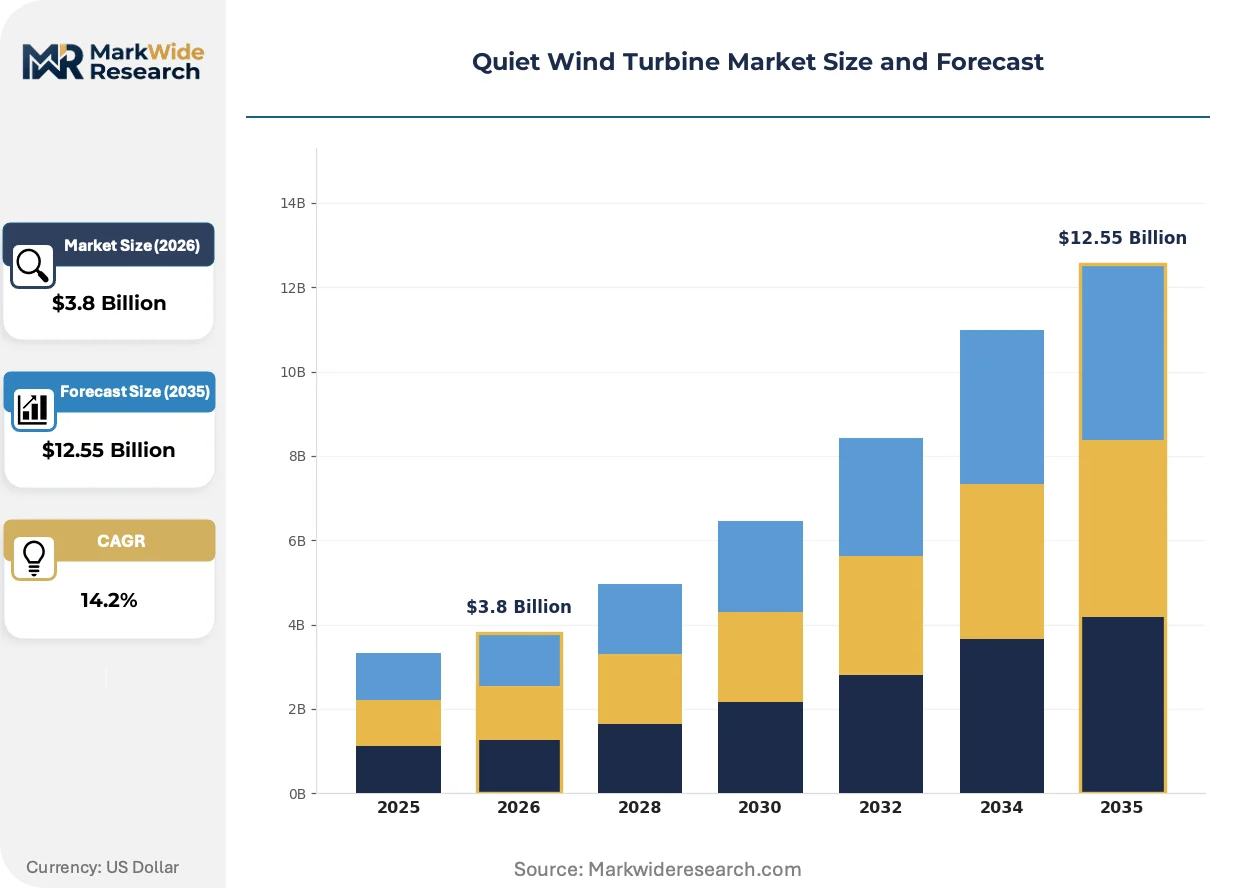
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Axis Turbines, Vertical Axis Turbines, Ducted Turbines, Floating Turbines End User: Utility Companies, Residential Consumers, Commercial Facilities, Government Projects Installation Type: Ground Mounted, Roof Mounted, Offshore, Hybrid Systems Technology: Gearless Systems, Direct Drive, Variable Speed, Smart Turbines |
| Companies Covered | Siemens Gamesa, GE Renewable Energy, Vestas Wind Systems, Nordex SE, Suzlon Energy, Enercon, Goldwind, Bergey Windpower, Northern Power Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quiet Wind Turbine Market Evolving Landscape
Acoustic engineering is displacing mechanical efficiency as the primary competitive differentiator, with control software and material science investments now outpacing traditional drivetrain optimization in manufacturer capex plans.
Bladeless vortex-induced vibration technology is bifurcating the small-wind segment. These systems harvest energy from oscillating masts rather than rotating blades, eliminating tip-speed noise entirely. Residential developers in noise-sensitive suburbs of Copenhagen and Munich are specifying vortex systems for rooftop and courtyard installations. The technology is bifurcating procurement criteria, splitting buyers between capacity-maximizing traditionalists and silence-prioritizing early adopters.
EU Green Deal implementation is tightening permissible sound levels through delegated acts under the Renewable Energy Directive. Member states must transpose stricter noise thresholds into national building codes by 2027, with Denmark and Germany already enforcing sub-40 dB night-time limits. Offshore platform manufacturers are responding with enlarged nacelle insulation and serrated trailing-edge additives.
Buyer preference is consolidating around noise-performance guarantees rather than rated capacity. Agricultural co-operatives in Bavaria and Schleswig-Holstein now contract for acoustic output levels with penalty clauses, supplanting traditional power-curve warranties. This specification shift is most pronounced where municipal zoning boards hold veto authority over installation permits.
Quiet Wind Turbine Market Segmentation
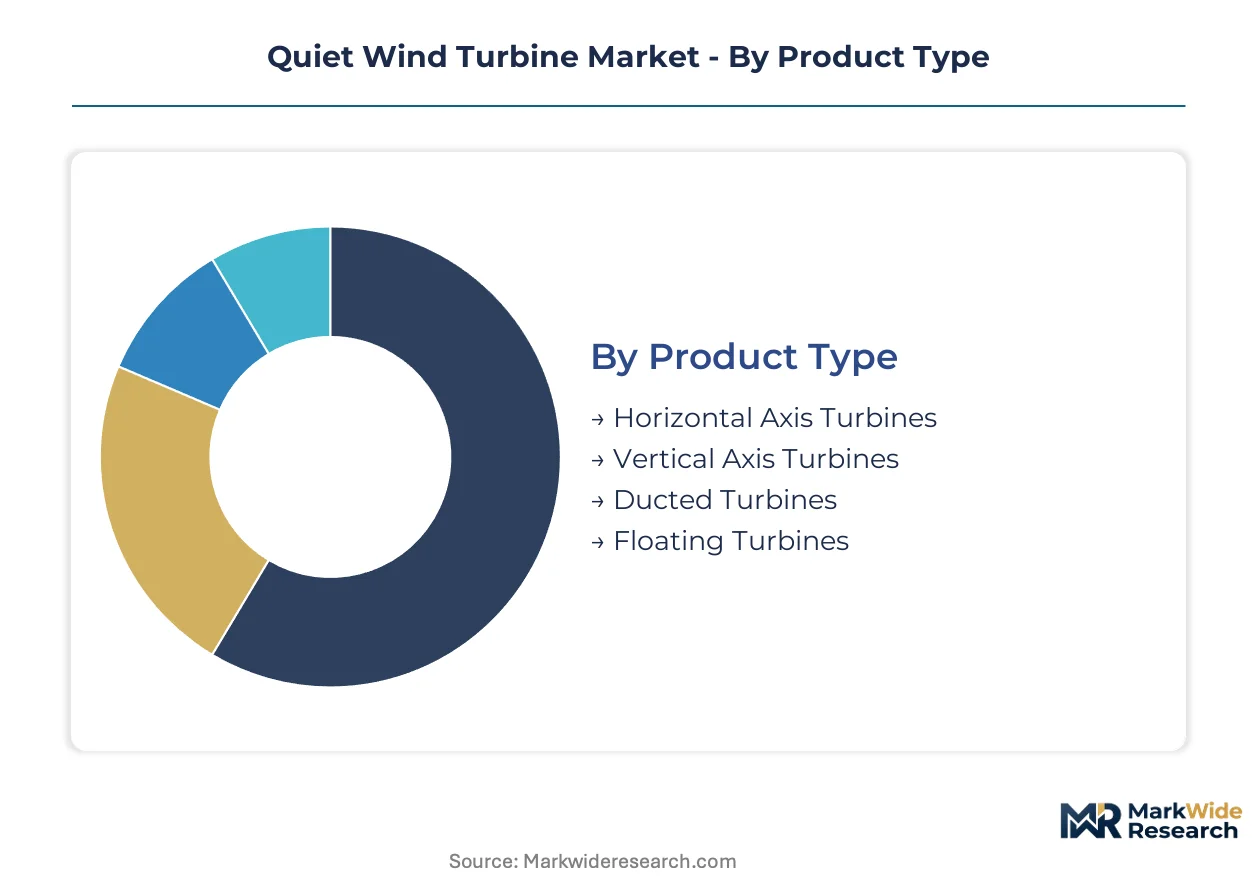
Segmentation in quiet wind turbines reveals how noise-performance specifications reshape procurement across installation environments and buyer types. Manufacturers align product architectures to distinct acoustic thresholds, drivetrain preferences, and mounting constraints that vary sharply between suburban homes and offshore utilities.
Product Type:
Horizontal axis turbines dominate export markets from Danish and Spanish manufacturing clusters, while ducted and vertical axis designs serve noise-constrained domestic installations in Germany and Denmark.
- Horizontal Axis Turbines:Conventional three-blade rotors with serrated trailing-edge modifications and enlarged nacelle insulation reduce source noise below 40 dB. Danish coastal repowering projects and German agricultural co-operatives specify these for capacity-maximizing sites where community acceptance hinges on acoustic guarantees.
- Ducted Turbines:Shrouded rotor architectures accelerate airflow through converging-diverging nozzles, enabling higher tip-speed ratios at lower rotational speeds. Basque Country municipal codes in San Sebastián and Bilbao mandate these for construction-adjacent installations under sub-40 dB thresholds.
- Vertical Axis Turbines:Savonius and Darrieus configurations eliminate directional tracking mechanisms, cutting mechanical noise sources. Residential consumers in Bavarian suburbs favor these for rooftop mounting where height restrictions limit horizontal-axis swept area.
- Floating Turbines:Semi-submersible platforms with tension-leg mooring systems extend quiet turbine deployment to deep-water sites. Spanish engineering clusters prototype these for Basque Country offshore zones where seabed-fixed foundations prove uneconomical.
Horizontal axis turbines hold the largest share; momentum sits with ducted turbines as municipal noise codes tighten across European residential zones.
End User:
Cost tiers separate procurement patterns, with premium acoustic-performance contracts commanding service agreements that standard capacity warranties cannot match.
- Utility Companies:Large-scale repowering projects in coastal Denmark prioritize noise-reduction guarantees over rated capacity, contracting for acoustic output levels with penalty clauses. Jutland and Funen replacement cycles drive specification shifts toward real-time pitch-smart convergence.
- Residential Consumers:Suburban households across Germany's Bavaria and Denmark's Zealand purchase distributed systems directly, bypassing traditional utility procurement. Noise ordinances compress addressable zones faster than efficiency gains expand them, forcing decibel prioritization in buying decisions.
- Commercial Facilities:Manufacturing campuses and logistics parks in Spain's Basque Country integrate rooftop and courtyard installations to meet corporate renewable targets. Space constraints favor compact ducted or vertical axis architectures.
- Government Projects:Municipal buildings and public infrastructure in noise-sensitive wildlife corridors specify bladeless vortex-induced vibration harvesters. These systems eliminate rotor noise entirely, opening sites previously excluded by acoustic constraints.
Utility companies anchor volume; residential consumers are climbing the fastest as distributed generation accelerates under EU Green Deal implementation.
Installation Type:
Volume concentration varies by mounting constraints, with ground-mounted systems scaling through agricultural co-operatives while roof-mounted deployments fragment across urban building stock.
- Ground Mounted:Agricultural land in Schleswig-Holstein and Bavaria accommodates larger swept areas with setback distances that satisfy night-time noise limits. Farmer-owned energy associations purchase direct from manufacturers with acoustic-performance service agreements.
- Roof Mounted:Urban peripheries and suburban zones in Copenhagen and Munich deploy compact vertical axis and ducted systems. Height restrictions and structural load limits constrain turbine selection to lightweight composite architectures.
- Offshore:Enlarged nacelle insulation and serrated trailing-edge additives address stricter EU delegated acts on platform noise. Danish and Spanish clusters compete for floating foundation contracts in deep-water sites.
- Hybrid Systems:Combined wind-solar installations optimize capacity factors across diurnal and seasonal variation. Basque Country zoning reforms incentivize these for construction-adjacent municipal projects.
Ground mounted retains the largest footprint; hybrid systems show steepest expansion trajectory as intermittency mitigation drives integrated procurement.
Technology:
Margin pools concentrate in control software and material science, with smart turbine investments outpacing traditional drivetrain optimization in manufacturer capex allocation.
- Gearless Systems:Direct-drive permanent-magnet generators eliminate mechanical whine from gearbox meshing frequencies. Chinese supply chains anchor production, though neodymium processing concentration exposes costs to export quota volatility.
- Direct Drive:Synchronous generators with full-power converters enable variable-speed operation across wind speed ranges. Vestas Wind Systems sustains competitive pressure through these architectures in Danish offshore markets.
- Variable Speed:Power electronics modulate rotor torque to minimize acoustic emissions during high-wind events. Real-time adjustment protocols integrate with edge-computing controllers for dynamic noise suppression.
- Smart Turbines:Sensor-embedded blades with predictive pitch control optimize aerodynamic shaping for acoustic performance. Utility-scale repowering projects specify these for community acceptance in noise-sensitive coastal zones.
Gearless systems dominate installed base; smart turbines gain share fastest as buyer preference consolidates around noise-performance guarantees over rated capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Federal Immission Control Act anchors the regulatory framework that shapes European demand patterns. Municipal zoning boards across Denmark, Spain, and Germany enforce decibel thresholds that compress installation zones faster than efficiency gains expand them.
Germany
Bavarian agricultural co-operatives purchase distributed systems directly from manufacturers with noise-performance service agreements. The Federal Immission Control Act mandates 18-24 month field measurement protocols for acoustic certification. Suburban zones around Munich deploy compact vertical axis architectures where height restrictions limit horizontal-axis swept area.
Denmark
Coastal repowering projects in Jutland and Funen face 20-year replacement cycles with community acceptance hinging on noise reduction guarantees. EU Green Deal delegated acts under the Renewable Energy Directive tighten permissible sound levels through national building code transposition. Copenhagen residential developers specify vortex-induced vibration systems for rooftop installations in noise-sensitive suburbs.
Spain
Basque Country municipal codes in San Sebastián and Bilbao mandate sub-40 dB thresholds for construction-adjacent installations. Zoning reforms incentivize hybrid wind-solar systems for municipal projects. Spanish engineering clusters prototype floating foundation turbines for deep-water offshore zones where seabed-fixed foundations prove uneconomical.
China
MIIT enforces GB standards for mechanical noise in distributed energy equipment, shaping export qualification requirements for domestic manufacturers. Neodymium processing concentration in Chinese refiners exposes permanent-magnet generator costs to export quota volatility. Goldwind anchors supply with permanent-magnet generators purpose-built for near-silent operation.
United States
EPA noise guidelines tighten permissible sound levels for residential-zone installations. Community acceptance barriers constrain utility-scale projects in noise-sensitive coastal zones. Distributed generation accelerates among suburban households seeking to bypass traditional utility procurement channels.
Quiet Wind Turbine Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the quiet wind turbine market. European incumbents with blade-design heritage dominate premium acoustic-performance contracts, while Chinese manufacturers anchor volume supply through integrated rare-earth magnet supply chains. Two strategic archetypes define competitive positioning: heritage engineering houses with aeroacoustic simulation capabilities, and scale-driven fabricators with permanent-magnet generator specialization. Dominant competitive moves include strategic partnerships for acoustic certification acceleration and geographic expansion into municipal zoning jurisdictions with sub-40 dB thresholds.
Among heritage European engineering houses, Siemens Gamesa and Vestas Wind Systems exemplify the acoustic-performance tier. Siemens Gamesa leverages blade-design heritage to dominate low-noise offshore platforms. Vestas sustains competitive pressure through direct-drive gearless architectures that eliminate mechanical whine. Goldwind represents the scale-driven Chinese archetype, anchoring supply with permanent-magnet generators purpose-built for near-silent operation.
| Leading Market Players |
|---|
| Siemens Gamesa |
| GE Renewable Energy |
| Vestas Wind Systems |
| Nordex SE |
| Suzlon Energy |
| Enercon |
| Goldwind |
| Bergey Windpower |
| Northern Power Systems |
| Others |
Value Network & Pricing Analysis
Permanent-magnet generator scale economies in Chinese manufacturing clusters compress price floors for gearless architectures while elevating entry barriers for European competitors lacking captive rare-earth supply. This concentration dynamic forces acoustic-performance premiums to absorb raw material volatility, reshaping how manufacturers allocate margin across noise-dampening R&D and input hedging.
Pricing Analysis
Geographic price spreads widen between Danish heritage engineering and Chinese volume supply, with acoustic certification grade and after-sales service bundling as primary differentiation drivers. Pricing pressure stems from carbon fiber prepreg cost volatility tied to aerospace sector demand, squeezing margin on composite blade shells. Agricultural co-operatives in Bavaria exhibit highest price sensitivity, while utility repowering projects in coastal Denmark prioritize noise-performance guarantees over unit economics.
Supply Chain Analysis
China anchors permanent-magnet generator fabrication and neodymium refining, while Denmark and Spain concentrate ducted turbine engineering and aeroacoustic simulation talent. The supply chain draws from carbon fiber prepreg, rare-earth magnets, and advanced composite resins as critical inputs. Single-source vulnerability in Chinese rare-earth processing exposes costs to export quota friction. Distribution runs through farmer-owned energy associations and direct manufacturer contracts, bypassing traditional utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aeroacoustic simulation expertise scarcity constrains product development velocity, with computational fluid dynamics specialists commanding premium compensation that outpaces manufacturing scale investments. This capability gap favors incumbents with established design heritage while forcing new entrants toward certification acceleration and niche segment specialization.
For Market Incumbents: Fortify blade-design IP through targeted acquisition of Basque Country and Copenhagen engineering clusters, countering emerging Spanish ducted turbine specialists. Deepen backward integration into carbon fiber prepreg supply through long-term offtake agreements with aerospace sector suppliers, insulating margin from input cost volatility. For New Entrants and Emerging Players: Germany's Federal Immission Control Act certification fast-track offers regulatory arbitrage for compliant product variants, opening white-space in Bavarian agricultural co-operative procurement. Target rooftop-mounted vertical axis architectures in Copenhagen and Munich suburbs where height restrictions exclude horizontal-axis competitors, leveraging direct-to-consumer channels with acoustic-performance service agreements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors heritage engineering houses with aeroacoustic simulation capabilities over scale-driven fabricators exposed to rare-earth supply concentration. Long-term viability hinges on control software and material science differentiation rather than drivetrain optimization. Monitor municipal zoning board decisions in Basque Country and Schleswig-Holstein as inflection indicators for addressable market geometry.| Strategic Initiative | Industry Significance |
|---|---|
| Acoustic Certification Acceleration | Compresses Germany's 18-24 month field measurement protocols to capture first-mover advantage in sub-40 dB municipal codes. |
| Backward Integration into Rare-Earth Supply | Mitigates Chinese neodymium export quota exposure for permanent-magnet generator cost stability. |
| Edge-Computing Controller Development | Enables real-time pitch adjustment for dynamic noise suppression during high-wind events. |
| Farmer-Owned Energy Association Partnerships | Bypasses traditional utility procurement in Bavaria and Schleswig-Holstein with direct manufacturer contracts. |
| Floating Foundation Prototyping | Extends quiet turbine deployment to Basque Country deep-water sites where seabed-fixed foundations prove uneconomical. |
Research Methodology
The analysis maps horizontal axis, ducted, vertical axis, and floating turbine architectures, each validated through utility planning officers, agricultural co-operative procurement leads, aeroacoustic engineering directors, and municipal zoning officials. Primary interviews with IPP project developers and EPC contractors combined with secondary validation from EIA data, IEA renewable deployment reports, FERC distributed generation filings, and EU Green Deal delegated act databases. Bottom-up installation capacity modeling and top-down regulatory constraint analysis triangulate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end user tier, installation configuration, and technology architecture. CAGRs derive from regulatory timeline analysis, replacement cycle assessment, and noise ordinance diffusion patterns. Forecast inputs incorporate municipal zoning board veto authority prevalence and acoustic certification queue lengths.
Underlying assumptions cover EU Green Deal national building code transposition schedules, with deviation risk concentrated in rare-earth export quota volatility and carbon fiber aerospace demand cycles. Forecasts reflect these conditions with recalibration cycles aligning with material shifts in municipal noise threshold enforcement and repowering project announcement velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Energy Equipment Market
Wind Energy Systems
Iran Wind Energy Market
Wind Energy Systems
Canada Wind Energy Market
Wind Energy Systems
Europe Direct Drive Wind Turbine Market
Wind Energy Systems
Greece Wind Energy Market
Wind Energy Systems
Wind Services Market
Wind Energy Systems
South America Wind Power Market
Wind Energy Systems
Wind Turbine Gearbox Vibration and Condition Monitoring Test Platforms Market
Wind Energy Systems
Belgium Wind Energy Market
Wind Energy Systems
Wind Turbine Pitch System Sales Market
Wind Energy Systems
Wind Turbine Yaw and Pitch Gearbox Market
Wind Energy Systems
Drone Wind Turbine Blade Inspection Market
Wind Energy Systems
Wind Blades NDT Market
Wind Energy Systems
Egypt Wind Energy Market
Wind Energy Systems
Global Wind Power Coatings Market
Wind Energy Systems
Wind Turbine Gearbox and Direct Drive Systems Market