
 Wind Electric Power Generation Market | 2026-2036
Wind Electric Power Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Electric Power Generation Market Analysis
Buyer consolidation among European power utilities is realigning procurement volumes toward long-term offtake agreements with technology-agnostic terms. GE Vernova leverages its integrated turbine-to-grid portfolio to capture multi-decade service contracts. Siemens Gamesa Renewable Energy anchors its position through specialized offshore direct-drive platforms. Vestas Wind Systems competes on modular nacelle architectures that reduce port logistics costs.
Wind electric power generation converts kinetic atmospheric energy into alternating current through aerodynamic rotor blades, drivetrains, and synchronous or doubly-fed induction generators rated from kilowatts to fifteen-plus megawatts, with capacity factors typically ranging twenty-five to fifty percent depending on wind regime and hub height. The primary commercial purpose is bulk decarbonized electricity supply to wholesale grids and industrial direct consumers. Horizontal axis turbines dominate installed capacity while offshore deployment captures expanding margin pools due to higher capacity factors and fewer siting constraints. Utility-scale projects command the majority of capital deployment, though distributed generation segments gain traction behind commercial and industrial meters.
The EU Green Deal and F-Gas Regulation constrain refrigerant choices in turbine transformer cooling systems, while the EPA tailors offshore environmental review timelines in United States federal waters. China's MIIT enforces grid-code compliance standards that favor domestically certified control system architectures. Stakeholders must monitor evolving domestic content thresholds and carbon-border adjustment mechanisms that threaten to bifurcate equipment supply chains into regulatory zones.
Market Dynamics
Offshore turbine scaling above twelve megawatts is compressing levelized cost trajectories while straining port infrastructure and heavy-lift vessel availability across Northern Europe and East Asia.
Growth Catalysts
- EU Green Deal grid interconnection mandates:Tightened approval timelines accelerate project pipelines in Germany and Denmark, forcing utilities to front-load procurement commitments.
- Direct-drive generator architectures:Elimination of gearbox maintenance reduces offshore operational expenditure, attracting capital from institutional infrastructure funds.
- China's MIIT grid-code compliance standards:Domestic certification requirements favor locally produced control systems, consolidating procurement within state-backed utility conglomerates.
Market Restraints
- Neodymium-dysprosium supply concentration:Rare earth permanent magnet dependency creates price volatility exposure concentrated in Chinese processing facilities.
- F-Gas Regulation refrigerant constraints:EU restrictions on turbine transformer cooling fluids force retrofit cycles and alternative chemistry validation timelines.
- Intermittency absorption limits:Grid balancing reserves in high-penetration markets require parallel storage investment, eroding project returns.
Strategic Opportunities
- Floating foundation platforms:Deep-water deployment beyond fixed-bottom limits unlocks Japan and South Korea's steep continental shelf zones.
- Power-to-X offtake integration:Green hydrogen electrolyzer co-location creates synthetic fuel revenue streams for German and Dutch North Sea clusters.
- Corporate renewable energy certificates:Industrial direct consumers in the United States bypass utility intermediaries through virtual power purchase agreements.
Industry Challenges
- Composite blade technician shortage:Specialized repair skills for carbon fiber structures lag fleet expansion in Scotland and Taiwan.
- Type certification timeline compression:Prototype-to-serial validation cycles for fifteen-megawatt platforms strain notified body capacity.
- Legacy SCADA integration friction:Retrofitting digital twin architectures onto twenty-year operational assets demands custom protocol bridging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Electric Power Generation Market |
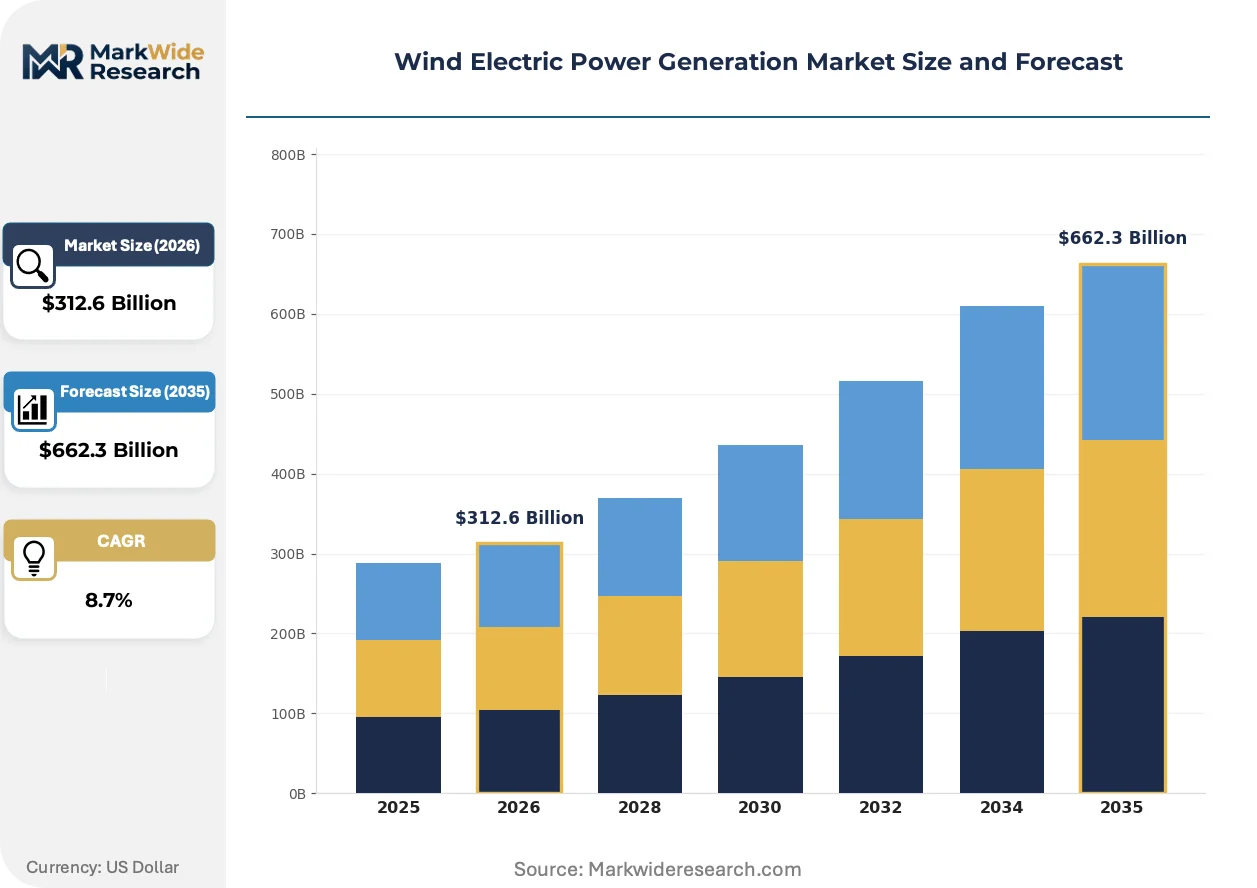
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Horizontal Axis, Vertical Axis, Offshore, Onshore Component: Turbine, Generator, Rotor Blade, Control System Deployment: Utility-Scale, Distributed, Small-Scale, Community End User: Power Utilities, Industrial, Commercial, Residential |
| Companies Covered | GE Vernova, Siemens Gamesa Renewable Energy, Vestas Wind Systems, NextEra Energy, Adani Green Energy, General Electric Renewable Energy, Enercon GmbH, Suzlon Energy, Nordex SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Electric Power Generation Market Emerging Trajectories
Modular nacelle assembly and segmented blade transport are dismantling traditional port-based manufacturing constraints, enabling factory replication at multiple coastal nodes.
High-temperature superconducting generators are expanding into direct-drive offshore platforms by eliminating rare earth dependencies while maintaining power density. Siemens Gamesa and GE Vernova accelerate prototype deployment in North Sea demonstration zones. This technology is expanding into twenty-megawatt-class turbines previously constrained by magnet mass and cooling complexity.
EPA offshore environmental review timeline tailoring in United States federal waters compresses permitting phases for floating wind leases. Developers must front-load marine mammal acoustic monitoring and fishing gear conflict mitigation. The Bureau of Ocean Energy Management's Gulf of Maine and California lease rounds absorb these procedural adjustments.
Long-term offtake agreements now dominate European utility procurement, displacing spot market merchant exposure and capturing construction finance at lower weighted average cost of capital. Vestas and Siemens Gamesa structure twenty-year service contracts with availability guarantees. German and Danish transmission system operators favor this contracted revenue visibility in interconnection queue prioritization.
Wind Electric Power Generation Market Segmentation
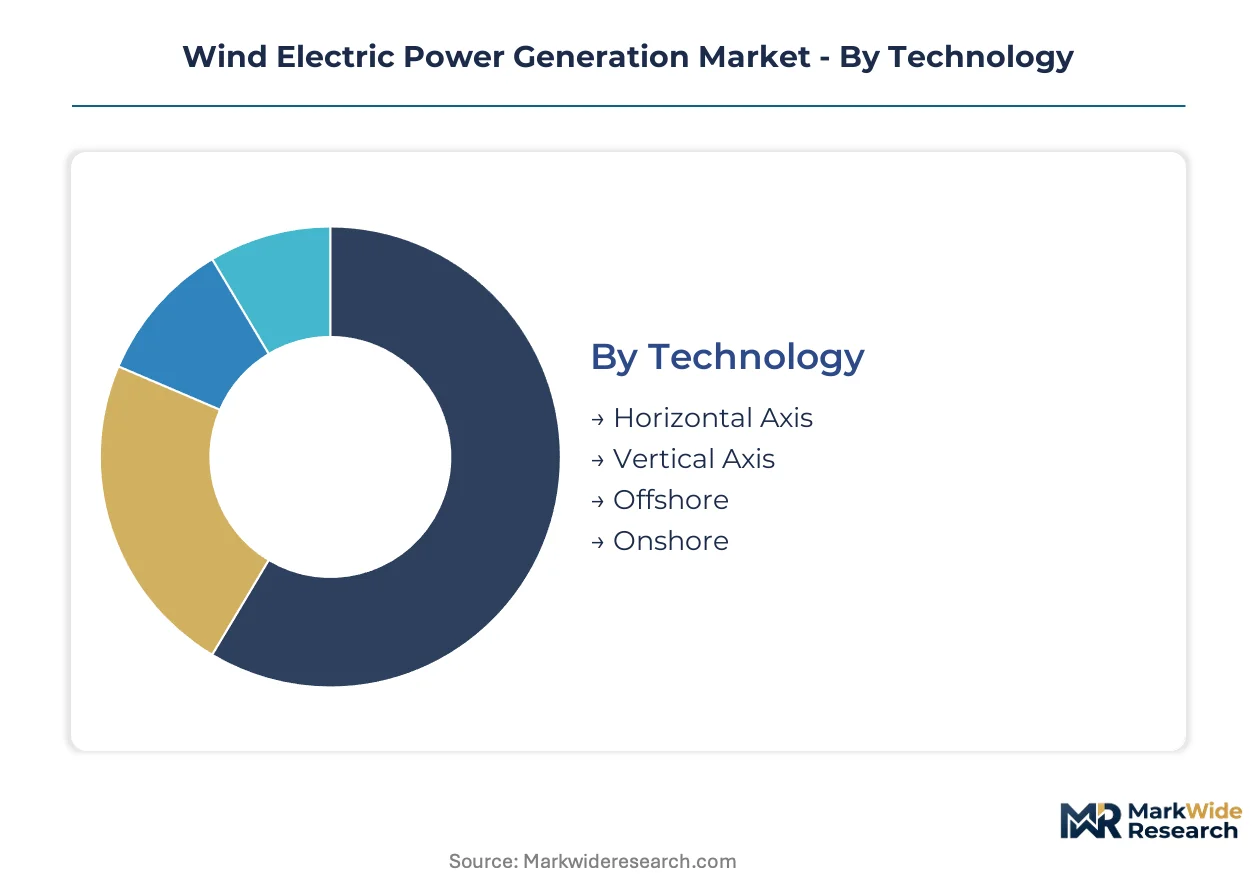
Technology choices determine capital intensity and operational expenditure profiles across wind power installations. Deployment scale drives grid interconnection requirements and offtake contract structures. Component sourcing strategies vary by turbine class and geographic manufacturing footprint.
Technology:
Horizontal axis platforms dominate installed megawatts while offshore configurations capture expanding margin pools through higher capacity factors.
- Horizontal Axis:Aerodynamic rotor blades mounted on upwind or downwind nacelles convert kinetic energy through drivetrains rated from kilowatts to fifteen-plus megawatts. German and Danish North Sea clusters favor this architecture for utility-scale procurement under EU Green Deal interconnection mandates.
- Offshore:Fixed-bottom and floating foundation systems access steadier wind regimes beyond coastal siting constraints. China's MIIT grid-code compliance standards favor domestically certified control architectures for state-backed utility conglomerates deploying in East Asian waters.
- Vertical Axis:Darrieus and Savonius configurations eliminate yaw mechanisms for distributed applications.
- Onshore:Land-based installations leverage existing transmission infrastructure with shorter development timelines.
Mature deployment sits with onshore horizontal axis platforms. Newer deployment is concentrated in offshore configurations.
Component:
Generator architecture choices separate direct-drive from geared systems with divergent maintenance profiles and rare earth exposure.
- Turbine:Nacelle assemblies integrate rotor hubs, drivetrains, and power conversion systems. Vestas and Siemens Gamesa compete on modular architectures that reduce port logistics costs across Northern European manufacturing nodes.
- Rotor Blade:Carbon fiber and glass-reinforced epoxy structures span sixty to one hundred-plus meters for utility-scale platforms. Scotland and Taiwan face composite blade technician shortages that lag fleet expansion requirements.
- Generator:Synchronous and doubly-fed induction units convert mechanical rotation to grid-synchronized alternating current.
- Control System:Pitch, yaw, and power electronics management platforms ensure grid-code compliance.
Capital allocation concentrates in turbine and blade assemblies. Control systems are climbing the fastest as digitalization priorities reshape procurement specifications.
Deployment:
Scale determines interconnection voltage levels and regulatory review complexity under national renewable energy frameworks.
- Utility-Scale:Projects exceeding one hundred megawatts connect at transmission voltage levels with dedicated substations. German transmission system operators prioritize interconnection queue positions for assets with twenty-year offtake visibility.
- Distributed:Behind-the-meter installations serve commercial and industrial loads without wholesale market participation. United States corporate renewable energy certificate demand drives virtual power purchase agreement structures.
- Small-Scale:Residential and agricultural systems rated below one hundred kilowatts.
- Community:Shared ownership models aggregate local capital for cooperative generation assets.
Investment flows cluster in utility-scale deployment. Distributed generation is gaining share fastest as industrial direct consumers bypass traditional utility intermediaries.
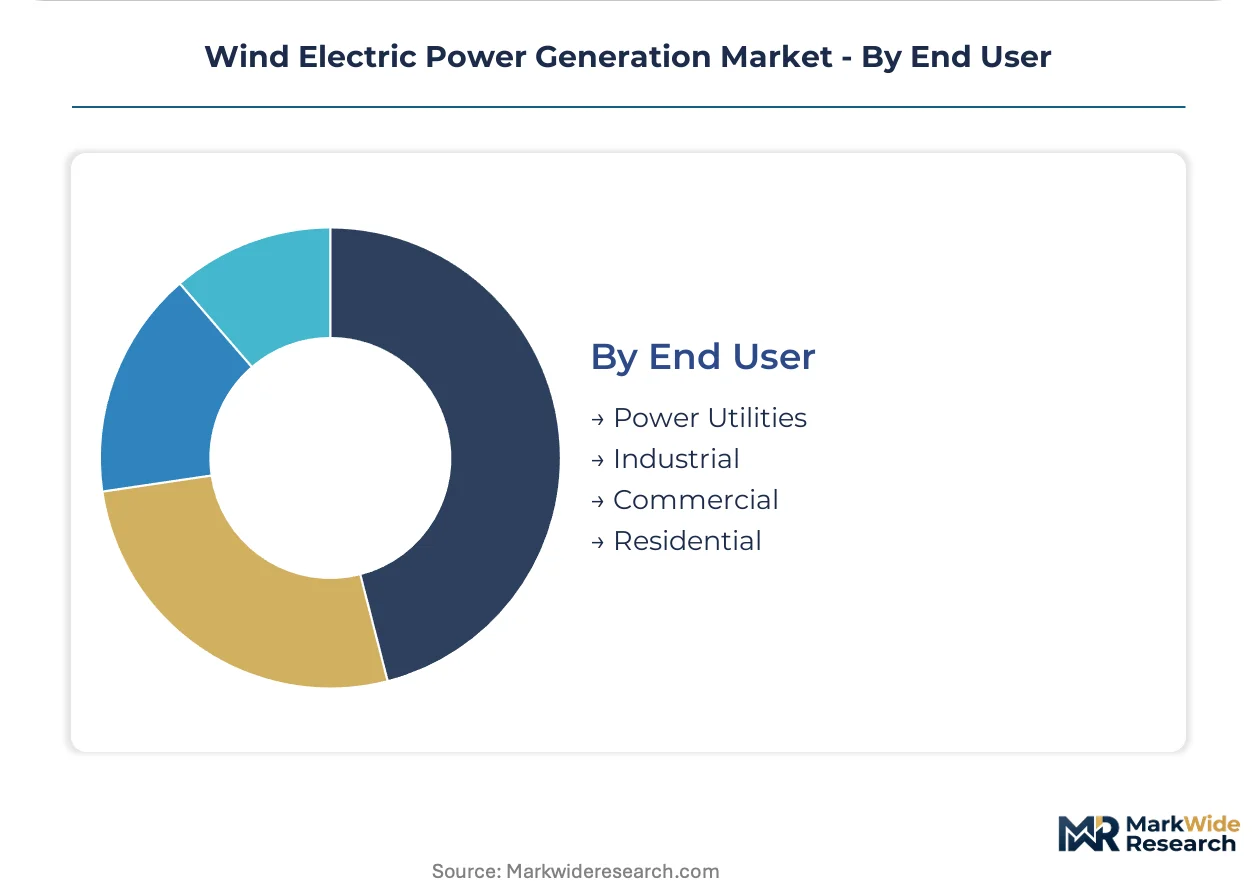
End User:
Procurement sophistication varies by counterparty credit quality and long-term energy price exposure management requirements.
- Power Utilities:Vertically integrated and independent generators procure through competitive auctions and bilateral contracts. European buyer consolidation is realigning procurement volumes toward technology-agnostic long-term offtake agreements.
- Industrial:Energy-intensive manufacturers seek price stability through direct renewable supply. Green hydrogen electrolyzer co-location in German and Dutch North Sea clusters creates synthetic fuel revenue streams.
- Commercial:Retail and office building operators prioritize sustainability targets.
- Residential:Individual households deploy rooftop and small turbine systems.
Contracted revenue visibility is strongest with power utilities. Industrial offtake is expanding most quickly as carbon-border adjustment mechanisms reshape supply chain energy procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth processing concentration in Chinese refining facilities anchors supply-side exposure for permanent magnet generators. Offshore lease auctions in Northern Europe and East Asian waters concentrate capital deployment. Grid interconnection queues in Germany and Denmark compress development timelines.
United States
Corporate renewable energy certificate procurement drives virtual power purchase agreement volumes. The EPA tailors offshore environmental review timelines for floating wind leases in federal waters. The Gulf of Maine and California lease rounds absorb procedural adjustments from the Bureau of Ocean Energy Management.
Germany
Transmission system operators prioritize interconnection queue positions for assets with twenty-year offtake visibility. The EU Green Deal grid interconnection mandates tighten project approval timelines. North Sea clusters favor utility-scale procurement under tightened regulatory frameworks.
China
State-backed utility conglomerates consolidate procurement within domestically certified control architectures. MIIT enforces grid-code compliance standards favoring locally produced systems. East Asian waters host expanding offshore deployment under centralized procurement structures.
Denmark
Long-term offtake agreements displace spot market merchant exposure in utility procurement. EU Green Deal mandates accelerate project pipelines with front-loaded procurement commitments. Danish manufacturing nodes specialize in modular nacelle architectures.
United Kingdom
Scotland faces composite blade technician shortages that lag fleet expansion requirements. The EU Green Deal framework influences grid interconnection standards through retained alignment mechanisms. Scottish waters host deep-water floating foundation demonstrations.
Wind Electric Power Generation Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue floating platform specialization and power-to-X integration. The market consolidates around integrated turbine-to-grid portfolios and specialized offshore direct-drive platforms. Strategic archetypes include full-service OEMs with multi-decade service contracts, component specialists in generator architectures, and vertically integrated energy developers with captive offtake. Dominant competitive moves encompass long-term service contract structuring and modular manufacturing replication at coastal nodes.
Within the integrated OEM tier, GE Vernova and Siemens Gamesa Renewable Energy exemplify contrasting technology positioning. Vestas Wind Systems anchors the modular architecture specialist segment. Among India-based developers, Adani Green Energy occupies a position in utility-scale renewable procurement. German engineering heritage is represented by Enercon GmbH and Nordex SE, which sit within the European mid-scale fabricator archetype.
| Leading Market Players |
|---|
| GE Vernova |
| Siemens Gamesa Renewable Energy |
| Vestas Wind Systems |
| NextEra Energy |
| Adani Green Energy |
| General Electric Renewable Energy |
| Enercon GmbH |
| Suzlon Energy |
| Nordex SE |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal grid interconnection mandates gate qualified supply access for turbine OEMs, compressing approval timelines while elevating premium-tier pricing for compliant platforms that meet accelerated procurement deadlines. German and Danish transmission system operators prioritize interconnection queue positions exclusively for assets demonstrating twenty-year offtake visibility, bifurcating the market between certified premium suppliers and non-compliant standard-tier competitors.
Pricing Analysis
Volume concentrates in long-term offtake agreements while margins accrue to service-integrated contracts. Project-based pricing dominates utility-scale procurement, with differentiation driven by certification tier under China's MIIT grid-code standards and after-sales availability guarantees. Cost compression in standard-tier onshore turbines intensifies as Chinese state-backed conglomerates consolidate domestic procurement. Industrial direct consumers in Germany exhibit lowest price sensitivity due to carbon-border adjustment exposure, while distributed commercial segments in the United States remain most price-sensitive.
Supply Chain Analysis
Composite blade technician shortages in Scotland and Taiwan constrain manufacturing throughput for carbon fiber structures spanning sixty to one hundred-plus meters. Supply concentrates in China for rare earth permanent magnet processing, Germany for precision drivetrain components, and Denmark for modular nacelle assembly. Neodymium-dysprosium dependencies from Chinese refining facilities create single-source vulnerability for direct-drive generator architectures. Distribution runs through port-based logistics nodes across Northern Europe and East Asia, with heavy-lift vessel availability emerging as a critical chokepoint.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation refrigerant constraints erect a barrier-to-entry moat for turbine OEMs with validated alternative cooling chemistries, forcing retrofit cycles that compliant incumbents monetize through premium service contracts.
For Market Incumbents: Deploy backward integration into rare earth magnet recycling to offset Chinese processing concentration exposure. Siemens Gamesa and GE Vernova should expand certified control system architectures ahead of China's MIIT enforcement waves, while Vestas accelerates modular nacelle replication at secondary coastal nodes to reduce port logistics vulnerability against heavy-lift vessel scarcity. For New Entrants and Emerging Players: Floating foundation platform specialists represent the most penetrable buyer archetype as Japan and South Korea's steep continental shelves unlock deep-water deployment beyond fixed-bottom limits. Power-to-X electrolyzer co-location in German and Dutch North Sea clusters offers white-space entry through synthetic fuel revenue stream integration. New entrants should structure technology licensing agreements with incumbent EPC contractors rather than competing head-to-head on turbine supply. For Investors and Strategic Acquirers: EPA offshore environmental review timeline compression for floating wind leases in United States federal waters is the leading indicator that permitting velocity will accelerate capital deployment into Gulf of Maine and California clusters. Acquisition targets should display captive offtake relationships with corporate renewable energy certificate buyers and demonstrated grid-code compliance across multiple regulatory jurisdictions. Watch for Bureau of Ocean Energy Management lease round absorption rates as the inflection signal for floating platform demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Offtake Agreement Structuring | Vestas and Siemens Gamesa capture construction finance at lower weighted average cost of capital through twenty-year visibility. |
| High-temperature Superconducting Generator Deployment | Eliminates rare earth dependencies while maintaining power density for twenty-megawatt-class offshore platforms. |
| Floating Foundation Platform Development | Unlocks Japan and South Korea deep-water zones previously inaccessible to fixed-bottom installations. |
| Power-to-X Electrolyzer Co-location | Creates synthetic hydrogen revenue streams for German and Dutch North Sea cluster operators. |
| Modular Nacelle Manufacturing Replication | Vestas reduces port logistics costs through factory duplication at multiple coastal nodes. |
Methodological Framework
Document review covered EIA generation statistics, IEA renewable energy outlooks, FERC interconnection filings, and EU Green Deal regulatory texts, complemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators across Germany, China, and the United States. Secondary validation incorporated project development databases, customs trade data for turbine component flows, and SEC filings from listed OEMs. Bottom-up capacity installation tracking triangulated against top-down policy target alignment.
Installed capacity and revenue estimates were produced through technology-by-technology build-up across horizontal axis, offshore, and emerging vertical axis configurations, segmented by deployment scale and end-user procurement sophistication. The analytical framework incorporated capacity factor assumptions by wind regime, grid interconnection queue prioritization rules under EU Green Deal mandates, and rare earth price volatility scenarios. CAGRs were derived from regression-weighted policy trajectory alignment against historical deployment velocity.
Revisions become necessary when MIIT grid-code enforcement timelines accelerate, EPA offshore review procedures shift, or neodymium-dysprosium processing concentration triggers supply disruption. Forecasts reflect assumptions around interconnection mandate adherence, floating foundation technology maturation, and corporate renewable energy certificate demand elasticity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Turbine Lenses Market
Wind Energy Systems
Quiet Wind Turbine Market
Wind Energy Systems
Wind Turbine Gearbox Vibration and Condition Monitoring Test Platforms Market
Wind Energy Systems
Wind Power SCADA Market
Wind Energy Systems
Medium-Speed Permanent Magnet Wind Turbine Generator System Market
Wind Energy Systems
Netherlands Wind Energy Market
Wind Energy Systems
Global Wind Power Coatings Market
Wind Energy Systems
Offshore Wind Cable Market
Wind Energy Systems
Lubricants for Wind Turbine Market
Wind Energy Systems
Wind Turbine Cables Market
Wind Energy Systems
Wind Energy Rescue System Market
Wind Energy Systems
Wind Turbine Scrap Market
Wind Energy Systems
Bladeless Wind Turbines Market
Wind Energy Systems
Latin America Wind Turbine Market
Wind Energy Systems
Poland Wind Energy Market
Wind Energy Systems
France Wind Energy Market