
 Electric Bus Charging Infrastructure Market | 2026-2036
Electric Bus Charging Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Bus Charging Infrastructure Market Analysis
Ultra-fast charging capability above 350 kW is unwinding legacy procurement specifications across the electric bus charging infrastructure landscape. Siemens AG leverages its grid-integration expertise to anchor large-scale depot projects in European transit hubs. ABB Ltd sustains technology leadership through high-power pantograph systems designed for opportunity charging at bus stops. BYD Auto Co. Ltd competes by bundling vehicle and charging hardware into unified fleet electrification packages.
Electric bus charging infrastructure comprises power conversion systems, connection interfaces, and energy management platforms engineered to deliver sustained high-current throughput for heavy-duty battery electric buses, typically operating at 480V to 800V DC with continuous ratings exceeding 150 kW per vehicle. DC fast charging occupies the dominant share of installed base value due to its compatibility with overnight depot replenishment cycles for full-size transit buses. Wireless charging represents a narrower but strategically significant segment where induction pad installations enable opportunity charging without mechanical connector wear. Depot charging infrastructure generates concentrated margin pools because site-specific electrical upgrades and civil works command premium engineering margins beyond hardware supply.
The Federal Transit Administration in the United States channels capital funding through competitive grant programs that require Buy America compliance for charging equipment, directly shaping supplier qualification criteria. China's MIIT enforces GB/T communication and safety standards that determine which charging systems interface with domestically manufactured electric buses. Europe's F-Gas Regulation and EU Green Deal emissions targets are pressuring municipal operators to accelerate fleet conversion timelines. Stakeholders must monitor evolving grid interconnection standards and utility rate structures, as these will determine total cost of ownership calculations more than charging hardware prices alone.
Market Dynamics
Ultra-fast charging above 350 kW is fragmenting legacy procurement specifications across municipal transit authorities, forcing simultaneous upgrades to grid interconnection hardware and bus electrical architectures. This technical inflection is compressing supplier qualification timelines and redrawing competitive boundaries between power electronics specialists and integrated fleet solution providers.
Growth Catalysts
- California's CARB depot charging mandates:The state's Advanced Clean Transit regulation requires zero-emission bus procurement targets that scale annually, compelling transit agencies to install high-power depot infrastructure ahead of vehicle fleet turnover.
- Battery-swapping interoperability:China's MIIT-enforced GB/T standards create unified mechanical and communication protocols, reducing fleet operator lock-in to single suppliers and accelerating infrastructure rollout across provincial transit networks.
- Grid-integrated energy management:Bi-directional charging capabilities enable bus batteries to participate in utility demand response programs, creating revenue streams that offset infrastructure capital costs for municipal operators.
Market Restraints
- Copper and silicon carbide supply concentration:Power semiconductor fabrication capacity concentrates in East Asian foundries, exposing charging system manufacturers to input cost volatility and extended lead times for high-voltage switching components.
- Utility interconnection queue delays:Distribution network upgrade approvals from regional grid operators routinely extend 18-24 months, creating structural bottlenecks that outpace hardware procurement cycles.
- Legacy fleet incompatibility:First-generation electric buses with 400V architectures cannot accept 800V charging throughput, segmenting infrastructure investment into parallel low-power and high-power asset classes.
Strategic Opportunities
- Wireless opportunity charging corridors:Inductive pad installations at high-frequency bus stops in Germany's Rhine-Ruhr metropolitan region enable continuous service extension without depot capacity expansion.
- F-Gas Regulation retrofit demand:Europe's phasedown of fluorinated greenhouse gases in cooling systems creates replacement cycles for thermal management equipment within existing charging infrastructure.
- Vehicle-to-grid aggregation platforms:Software layers that coordinate bi-directional power flows across dispersed bus fleets represent unclaimed margin pools beyond hardware supply.
Industry Challenges
- High-voltage electrical technician scarcity:Installation and maintenance of 800V DC systems requires specialized certification that outstrips current vocational training pipeline output in most transit markets.
- Multi-standard certification complexity:Charger manufacturers must simultaneously validate against GB/T, CCS, and CHAdeMO protocols to serve export markets, extending product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Bus Charging Infrastructure Market |
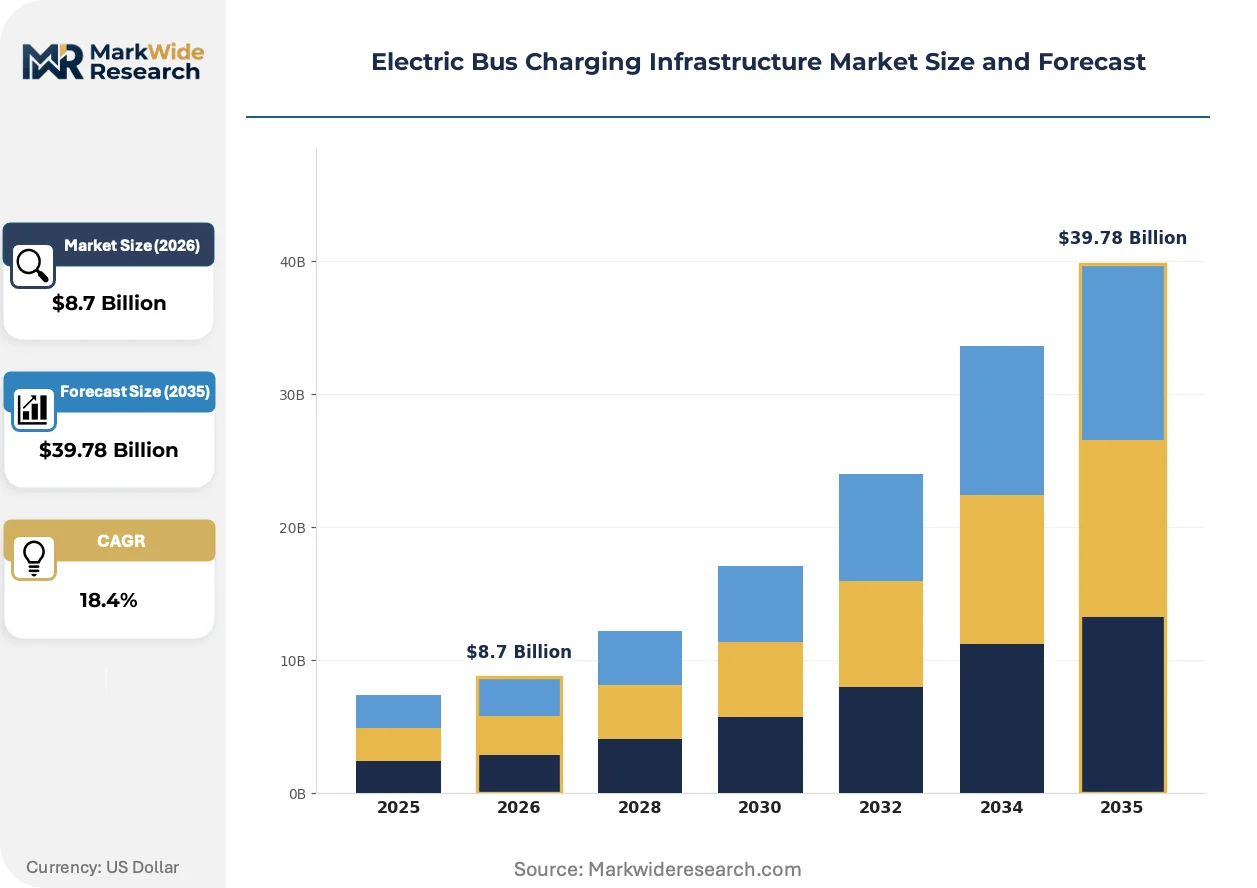
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charging Technology: DC Fast Charging, Wireless Charging, AC Charging, Ultra-Fast Charging Installation Type: Public Charging Stations, Depot Charging Infrastructure, On-route Charging, Standalone Chargers End User: Public Transport Authorities, Fleet Operators, Private Bus Operators, Urban Transit Agencies Charging Network: Open Network, Closed Network, Semi-closed Network, Proprietary Network |
| Companies Covered | Siemens AG, ABB Ltd, BYD Auto Co. Ltd, ChargePoint Inc., Proterra Inc., Kempower, SCHUNK Group, Bombardier Inc, EFACEC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Bus Charging Infrastructure Market Emerging Trajectories
Charging infrastructure is diverging into purpose-built architectures optimized for either overnight depot replenishment or distributed opportunity charging, with hardware specifications hardening around these distinct operational models rather than converging on universal designs.
Pantograph-based automated connection systems are fragmenting the opportunity charging segment. Transit operators in dense European corridors deploy these roof-mounted interfaces to eliminate driver handling time and connector wear. The technology compresses dwell-time windows at route terminals to under six minutes, enabling continuous service on routes previously requiring midday depot returns. This fragmentation is splitting supplier R&D budgets between mechanical automation and conductive cable management tracks.
The EU's F-Gas Regulation is accelerating thermal management redesign across charging infrastructure deployed in member states. Manufacturers must substitute fluorinated refrigerants in power conversion cooling systems with natural alternatives or engineered low-GWP fluids. This regulatory pressure most affects high-power depot installations in Germany and France, where operators are bundling cooling system retrofits with capacity expansion projects to minimize repeated site disruption.
Service unbundling is restructuring procurement relationships between transit authorities and infrastructure vendors. Municipal buyers increasingly separate hardware acquisition from long-term maintenance and software subscription components, enabling competitive rebidding of service contracts at mid-life asset points. This behavioral shift is most visible in United States transit agencies utilizing Federal Transit Administration capital grants, where Buy America compliance requirements for equipment differ from service contract sourcing rules.
Electric Bus Charging Infrastructure Market Segmentation
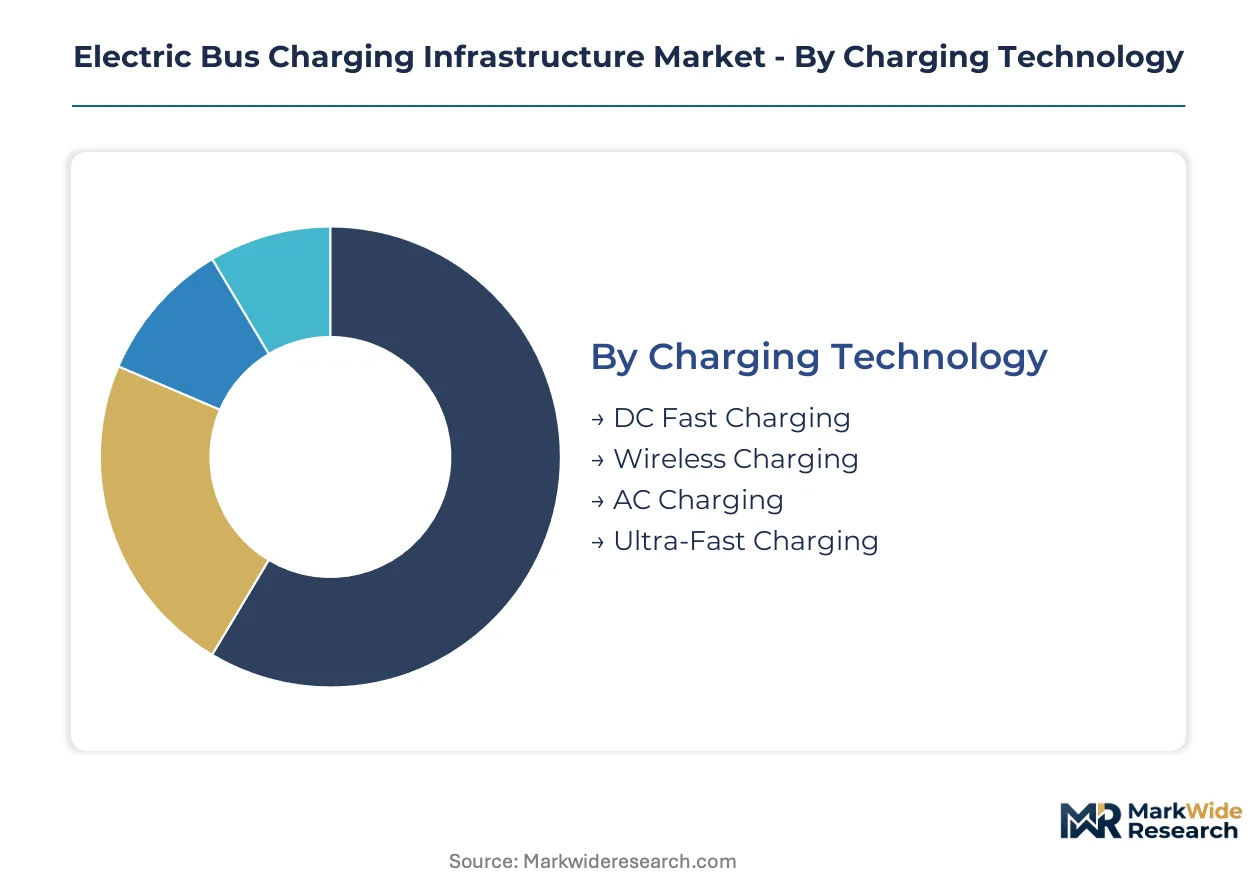
Segmentation in electric bus charging infrastructure reveals how procurement patterns diverge between high-frequency urban corridors and dispersed regional fleets. Technology choices and installation configurations determine grid interconnection requirements, capital intensity, and operational flexibility for transit operators.
Charging Technology:
Wireless charging faces the most acute substitution pressure as ultra-fast conductive systems achieve comparable dwell-time performance at lower capital cost per kilowatt.
- DC Fast Charging:Power conversion systems operating at 480V to 800V DC deliver sustained 150-350 kW throughput for overnight depot replenishment. Demand concentrates in California transit agencies responding to CARB mandates requiring zero-emission fleet conversion timelines.
- Ultra-Fast Charging:Systems exceeding 350 kW compress charging windows below 20 minutes but require 800V bus architectures and upgraded grid interconnection hardware. Deployment clusters in Germany's Rhine-Ruhr metropolitan region where continuous service models dominate procurement specifications.
- Wireless Charging:Inductive pad installations eliminate mechanical connector wear and enable driverless operation at route terminals.
- AC Charging:Lower-power overnight systems serve smaller shuttle fleets and legacy 400V bus architectures with reduced infrastructure investment.
DC Fast Charging retains volume leadership; Ultra-Fast Charging holds the steepest expansion curve.
Installation Type:
Cost tier stratification separates capital-intensive depot installations from distributed on-route hardware with lower civil works burden.
- Depot Charging Infrastructure:Site-specific electrical upgrades and civil works command premium engineering margins beyond hardware supply. Concentrated demand in China's provincial transit networks follows MIIT-enforced GB/T standardization that reduces fleet operator lock-in.
- On-route Charging:Pantograph-based automated connection systems at bus terminals compress dwell times under six minutes. Germany's municipal operators deploy these for continuous service on corridors previously requiring midday depot returns.
- Public Charging Stations:Shared infrastructure serving multiple fleet operators with standardized payment and access protocols.
- Standalone Chargers:Single-unit deployments for small-scale operators and rural transit routes with limited electrical grid capacity.
Depot Charging Infrastructure captures the largest capital allocation; On-route Charging is expanding most quickly in dense European corridors.
End User:
Customer type determines procurement scale, with public authorities leveraging federal grants while private operators prioritize total cost of ownership calculations.
- Public Transport Authorities:Municipal agencies in the United States channel Federal Transit Administration capital funding through competitive grant programs requiring Buy America compliance for charging equipment.
- Fleet Operators:Large-scale private and contracted operators bundle vehicle procurement with charging infrastructure into unified electrification packages.
- Urban Transit Agencies:City-level operators manage high-frequency corridor electrification with integrated grid demand response programs.
- Private Bus Operators:Smaller commercial fleets favor lower-capital AC charging and opportunistic public network access.
Public Transport Authorities dominate installed base value; Fleet Operators are gaining share fastest through bundled procurement models.
Charging Network:
Network architecture maturity stratifies between legacy proprietary systems and emerging open protocols that reduce supplier lock-in.
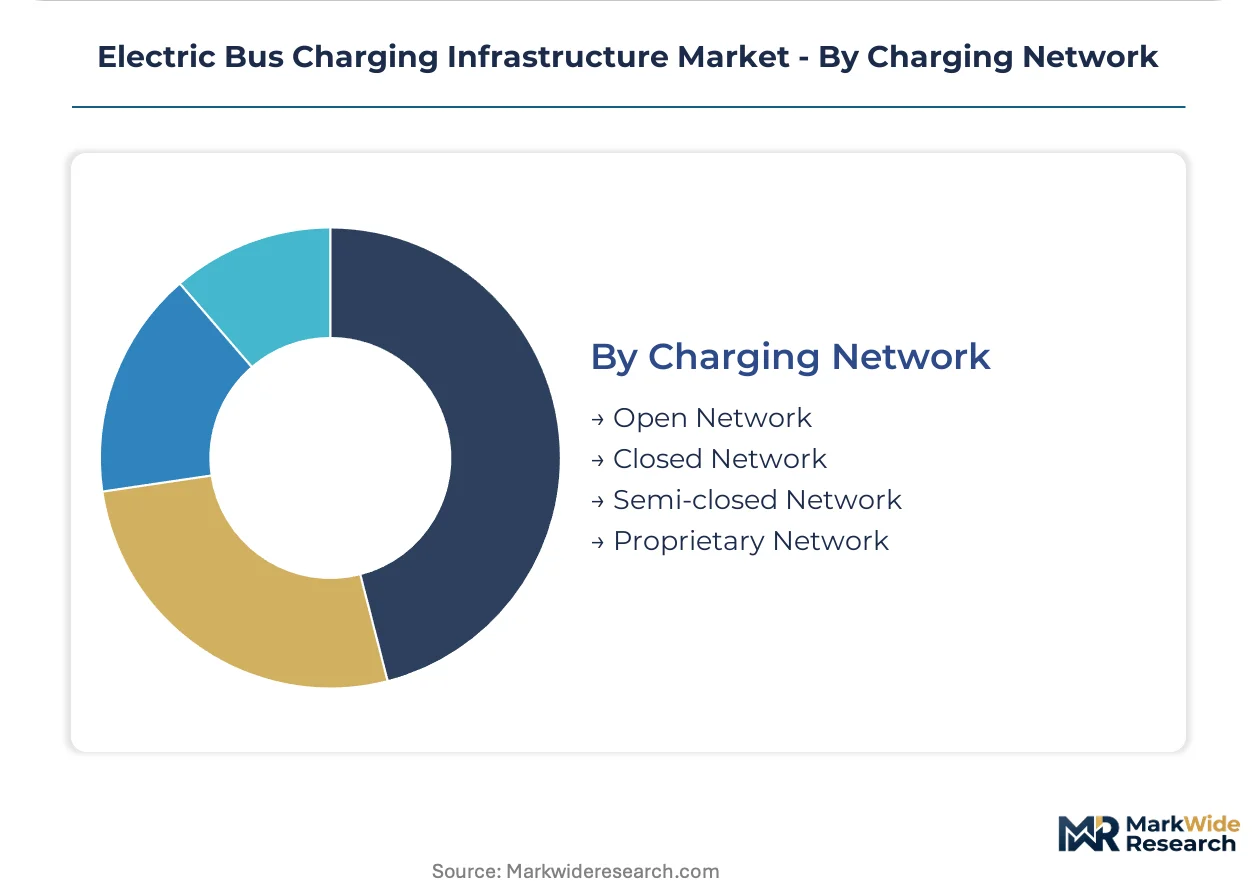
- Open Network:Interoperable communication protocols enable multi-supplier charger access and competitive service rebidding. European operators favor these under EU Green Deal emissions targets that accelerate fleet conversion timelines.
- Closed Network:Single-vendor systems with integrated maintenance and software subscriptions capture long-term revenue streams.
- Semi-closed Network:Restricted access models serving consortiums of regional transit agencies with shared infrastructure investment.
- Proprietary Network:Manufacturer-captive systems bundled with vehicle sales dominate early-generation deployments in China.
Open Network architectures are climbing the fastest as standardization mandates proliferate; Proprietary Network retains legacy installed base concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China exhibit the lowest price sensitivity due to state-coordinated procurement at scale, while private operators in India and Latin America face acute capital constraints that stretch payback calculations. Municipal authorities in Germany and California absorb premium infrastructure costs through federal grant mechanisms that shield local budgets. This elasticity divergence is fragmenting supplier pricing architectures across geographies.
United States
Federal Transit Administration capital grants require Buy America compliance for charging equipment, directly shaping vendor qualification pools. California's CARB Advanced Clean Transit regulation mandates escalating zero-emission bus procurement targets that compel depot infrastructure installation ahead of fleet turnover. Los Angeles Metro and San Francisco MUNI anchor the densest concentration of high-power depot projects.
Germany
Rhine-Ruhr metropolitan operators deploy pantograph-based automated connection systems to compress dwell times below six minutes on continuous-service corridors. The EU F-Gas Regulation accelerates thermal management retrofits across existing charging assets as fluorinated refrigerants phase down. Berlin and Hamburg transit authorities bundle cooling system upgrades with capacity expansion to minimize repeated site disruption.
China
Provincial transit networks scale deployment following MIIT-enforced GB/T standardization that reduces fleet operator lock-in to single suppliers. Battery-swapping interoperability protocols unify mechanical and communication interfaces across domestically manufactured buses. Shenzhen and Guangzhou anchor the largest depot charging installations serving high-frequency municipal corridors.
India
State-level urban transport authorities pilot electric bus fleets under centrally sponsored schemes with stringent total cost of ownership thresholds. The Ministry of Heavy Industries PLI scheme for automotive manufacturing extends incentives to charging infrastructure components produced domestically. Delhi and Mumbai metropolitan regions concentrate early procurement despite distribution grid capacity constraints.
Electric Bus Charging Infrastructure Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. European and Japanese industrial conglomerates anchor the high-reliability tier through grid-integration expertise and automation engineering, while Chinese vehicle manufacturers compete through bundled fleet electrification packages that compress procurement cycles. The market consolidates around three strategic archetypes: power electronics specialists, integrated fleet solution providers, and component subsystem suppliers. Dominant competitive moves include strategic partnerships between charging hardware vendors and bus OEMs, plus geographic licensing agreements that bypass direct market entry costs.
Among European-based industrial groups, Siemens AG and ABB Ltd occupy positions as archetypal power electronics specialists with deep grid-integration heritage. BYD Auto Co. Ltd exemplifies the integrated fleet solution archetype, representing vehicle manufacturers that bundle charging infrastructure with bus procurement to streamline operator decision-making. These three anchors illustrate how competitive positioning diverges between hardware-centric and solution-centric go-to-market models.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd |
| BYD Auto Co. Ltd |
| ChargePoint Inc. |
| Proterra Inc. |
| Kempower |
| SCHUNK Group |
| Bombardier Inc |
| EFACEC |
| Others |
Supply Flow & Price Mechanics
CARB's Advanced Clean Transit regulation gates supplier qualification and price differentiation simultaneously, as Buy America compliance requirements for Federal Transit Administration grants restrict vendor pools while premium engineering margins accrue to domestic-certified depot integrators serving California transit agencies.
Pricing Analysis
After-sales service contracts and long-term maintenance subscriptions drive lifetime value beyond hardware margins. Three-tier pricing structure across premium, standard, and economy levels segments by grid-integration complexity and thermal management certification grade. Cost compression in standard-tier depot hardware is intensifying because Chinese manufacturers bundle charging infrastructure with vehicle procurement. Private fleet operators in India and Latin America exhibit highest price sensitivity, while German municipal authorities absorb premium costs through federal grant mechanisms.
Supply Chain Analysis
Inbound logistics costs from East Asian semiconductor foundries through congested Pacific trade lanes amplify lead time volatility for silicon carbide power modules. Manufacturing concentrates in China, Germany, and South Korea for power conversion systems, with copper busbars and high-voltage capacitors sourced from Japanese and Taiwanese component specialists. Single-source vulnerability in silicon carbide wafer fabrication threatens charging system output schedules. Distribution runs through regional electrical infrastructure contractors who bundle hardware with site-specific civil works and utility interconnection services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric bus charging infrastructure market sits in early-cycle expansion, with zero-emission fleet mandates across California, Germany, and China's provincial networks accelerating penetration ahead of vehicle turnover curves.
For Market Incumbents: Compound grid-integration expertise into recurring software revenue layers that coordinate bi-directional power flows across dispersed bus fleets. Deepen backward integration into power semiconductor sourcing to insulate margins from East Asian foundry concentration. Secure CARB and FTA certification maintenance as emerging Chinese bundled-solution providers threaten hardware-only margins. For New Entrants and Emerging Players: Differentiate on wireless inductive pad architectures for opportunity charging corridors in Germany's Rhine-Ruhr metropolitan region where continuous service models dominate. Target India's state-level urban transport authorities piloting electric fleets under PLI scheme incentives with domestically manufactured thermal management subsystems. Pursue geographic licensing agreements that bypass direct market entry costs in European transit hubs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across ultra-fast charging deployments exceeding 350 kW as grid interconnection hardware upgrades outpace equipment costs. Five-to-ten year viability favors vehicle-to-grid aggregation platform specialists with software-layer margin capture beyond hardware supply. Monitor utility interconnection queue clearance velocities as the critical inflection signal for infrastructure deployment cadence.| Strategic Initiative | Industry Significance |
|---|---|
| Bi-directional Charging Certification | Enables bus batteries to participate in California ISO demand response programs. |
| GB/T Standard Licensing | Opens Chinese provincial transit networks to interoperable multi-supplier charging ecosystems. |
| Pantograph Automation Partnership | Compresses dwell times below six minutes on Rhine-Ruhr continuous-service corridors. |
| Thermal Management Retrofit Bundling | Aligns EU F-Gas Regulation compliance with capacity expansion in Berlin and Hamburg. |
| Vehicle-to-Grid Platform Development | Captures unclaimed software margins beyond hardware supply in municipal fleet deployments. |
Methodological Framework
A spread of perspectives from transit authority procurement directors, electrical infrastructure contractors, power electronics engineers, and utility interconnection planners converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FTA grant disbursement records, CARB compliance filings, MIIT standardization notices, and customs data for charging equipment trade flows. Bottom-up installation tracking and top-down fleet electrification mandate analysis triangulated market sizing.
Segmentation dimensions modeled include charging technology tier, installation type, end-user procurement authority, and network architecture maturity across the projection horizon. CAGRs derive from correlating fleet turnover timelines with infrastructure deployment lead times, incorporating utility interconnection queue durations and power semiconductor availability constraints.
Material uncertainties — utility rate structure revisions, grid interconnection standard updates, and battery chemistry shifts affecting charging profiles — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory mandate persistence and infrastructure grant continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Charging Management Software Market
Electric Vehicle Charging
Asia-Pacific Portable EV Charger Market
Electric Vehicle Charging
High Power Charger for Electric Vehicle Market
Electric Vehicle Charging
EV DC Fast Charger Market
Electric Vehicle Charging
United States Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
North America EV Charging Stations Market
Electric Vehicle Charging
India Electric Vehicle Charging Station Market
Electric Vehicle Charging
Japan Electric Vehicle Charging Station Market
Electric Vehicle Charging
United States Electric Vehicle Charging Systems and Equipment Market
Electric Vehicle Charging
EV Smart Charge Controller Market
Electric Vehicle Charging
Home Charging Piles Market
Electric Vehicle Charging
Electric Vehicle AC Charging Pile Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Operation Market
Electric Vehicle Charging
Norway Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Metals in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Charging Pile Cables Market