
 Asia-Pacific Wind Turbine Rotor Blade Market | 2026-2036
Asia-Pacific Wind Turbine Rotor Blade Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Wind Turbine Rotor Blade Market Outlook
GL certification for offshore wind rotor blades is unwinding the competitive field across the Asia-Pacific, raising barriers for manufacturers without marine-grade qualification cycles. TPI Composites leverages its established testing infrastructure to serve multiple OEM platforms across the region. Goldwind anchors its blade supply through captive production aligned with its turbine installations in China and abroad. Siemens Gamesa Renewable Energy competes on advanced aerodynamic designs purpose-built for typhoon-resistant offshore sites.
Wind turbine rotor blades are aerodynamic structures typically spanning 50 to 120 meters, constructed from fiberglass-reinforced epoxy or carbon fiber composites through vacuum infusion or prepreg layup processes, designed to capture kinetic energy from wind and transfer rotational torque to the generator hub. Fiberglass dominates material selection for onshore units due to cost efficiency, while carbon fiber penetrates extra-large offshore blades where stiffness-to-weight ratios determine performance limits. Horizontal axis technology leads installed capacity across the Asia-Pacific, though hybrid configurations attract R&D investment for low-wind sites. Utilities represent the primary end user segment, with procurement concentrated among state-backed generators in China and vertically integrated IPPs in India and Australia.
China's MIIT enforces GB standards for blade structural integrity and grid compatibility, while India's CEA mandates type certification for components connecting to national transmission networks. Australia's Clean Energy Regulator ties large-scale generation certificates to verified turbine performance, indirectly shaping blade specification requirements. Japan's METI guides offshore permitting through designated marine zones, influencing blade sizing for floating platform applications. Stakeholders must track how each national regulator calibrates certification stringency against domestic manufacturing capacity targets.
Market Dynamics
GL certification for offshore wind rotor blades is compressing the supplier base across the Asia-Pacific, as marine-grade qualification cycles raise capital barriers that exclude manufacturers lacking established testing infrastructure.
Growth Catalysts
- Dual carbon goals:China's MIIT mandates accelerate localized blade production requirements, forcing OEMs to establish captive manufacturing in coastal provinces.
- Floating platform development:Japan's METI-designated marine zones spur demand for extra-large blades engineered for typhoon-resistant offshore installations.
- PLI scheme incentives:India's CEA-mandated type certification for grid-connected components drives domestic blade fabrication capacity expansion.
Market Restraints
- Balsa core supply concentration:Ecuadorian and Papua New Guinean plantation capacity limits constrain sandwich panel production for lightweight blade structures.
- Carbon fiber cost volatility:Aerospace sector competition for Toray and SGL Carbon output squeezes margins for 100-meter-plus offshore blade programs.
- Marine-grade epoxy qualification:DNV GL and TÜV certification timelines extend 18-24 months, freezing new entrants from active project pipelines.
Strategic Opportunities
- Vietnam offshore licensing:Binh Thuan and Ninh Thuan province lease rounds create first-mover positioning for blade suppliers with floating foundation compatibility.
- Recyclable thermoplastic resins:Arkema and Covestro material systems enable end-of-life blade recovery, aligning with Australia's Clean Energy Regulator verification requirements.
- Retrofit blade extension:South Korean repowering sites at Gangwon and Jeolla provinces demand aerodynamic add-on kits for legacy 1.5-2.3 MW turbine fleets.
Industry Challenges
- Composite technician scarcity:Vacuum infusion and automated fiber placement skill gaps constrain throughput at new Chinese and Indian greenfield facilities.
- Root cause analysis complexity:Lightning strike and leading edge erosion failure modes require specialized NDT capabilities that lag behind installation scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Wind Turbine Rotor Blade Market |
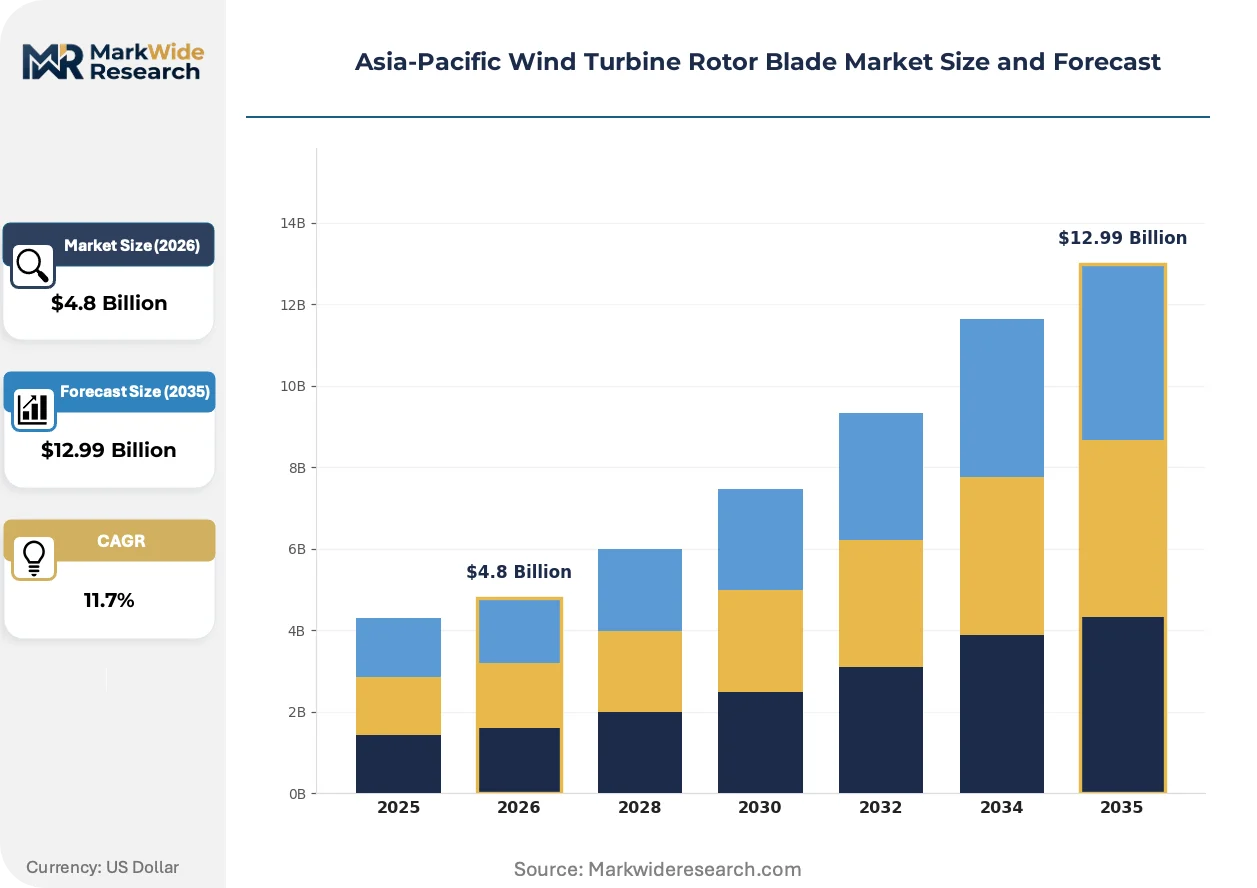
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Fiberglass, Carbon Fiber, Wood Epoxy, Steel Size: Small, Medium, Large, Extra Large Technology: Horizontal Axis, Vertical Axis, Ducted, Hybrid End User: Utilities, Industrial Developers, Independent Power Producers, Renewable Energy Companies |
| Companies Covered | TPI Composites, Goldwind, Vestas Wind Systems A/S, Envision Energy, Mingyang Smart Energy, Siemens Gamesa Renewable Energy, Lianyungang Zhongfu Lianzhong Composites Group, Dongfang Electric Corporation, LM Wind Power, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Wind Turbine Rotor Blade Market Strategic Shifts
Material substitution and manufacturing automation are restructuring competitive advantage in blade fabrication, compressing cost curves for extra-large offshore units while elevating quality thresholds.
Carbon fiber spar cap infusion is decomposing the traditional all-glass blade architecture that dominated onshore installations through 2020. Offshore developers in Jiangsu and Guangdong provinces now specify hybrid layup schedules for 110-meter-plus rotors. The technology is decomposing price premiums previously commanded by European blade specialists, enabling Chinese OEMs to capture gigawatt-scale export contracts.
CEA type certification mandates for grid-connected components are forcing design standardization across Indian manufacturing. The regulation compresses development cycles for domestic blade suppliers seeking to qualify for NTPC and SECI tenders. Tamil Nadu and Gujarat-based fabricators are consolidating around common mold platforms to accelerate certification throughput.
Direct OEM procurement of blade sets is displacing third-party supply arrangements that structured the market through 2022. State-backed generators in Shandong and Fujian provinces now negotiate integrated turbine-blade packages, squeezing independent blade manufacturers without captive turbine platforms. The shift is most visible in China's coastal offshore zones where single-source accountability reduces project execution risk.
Asia-Pacific Wind Turbine Rotor Blade Market Segmentation
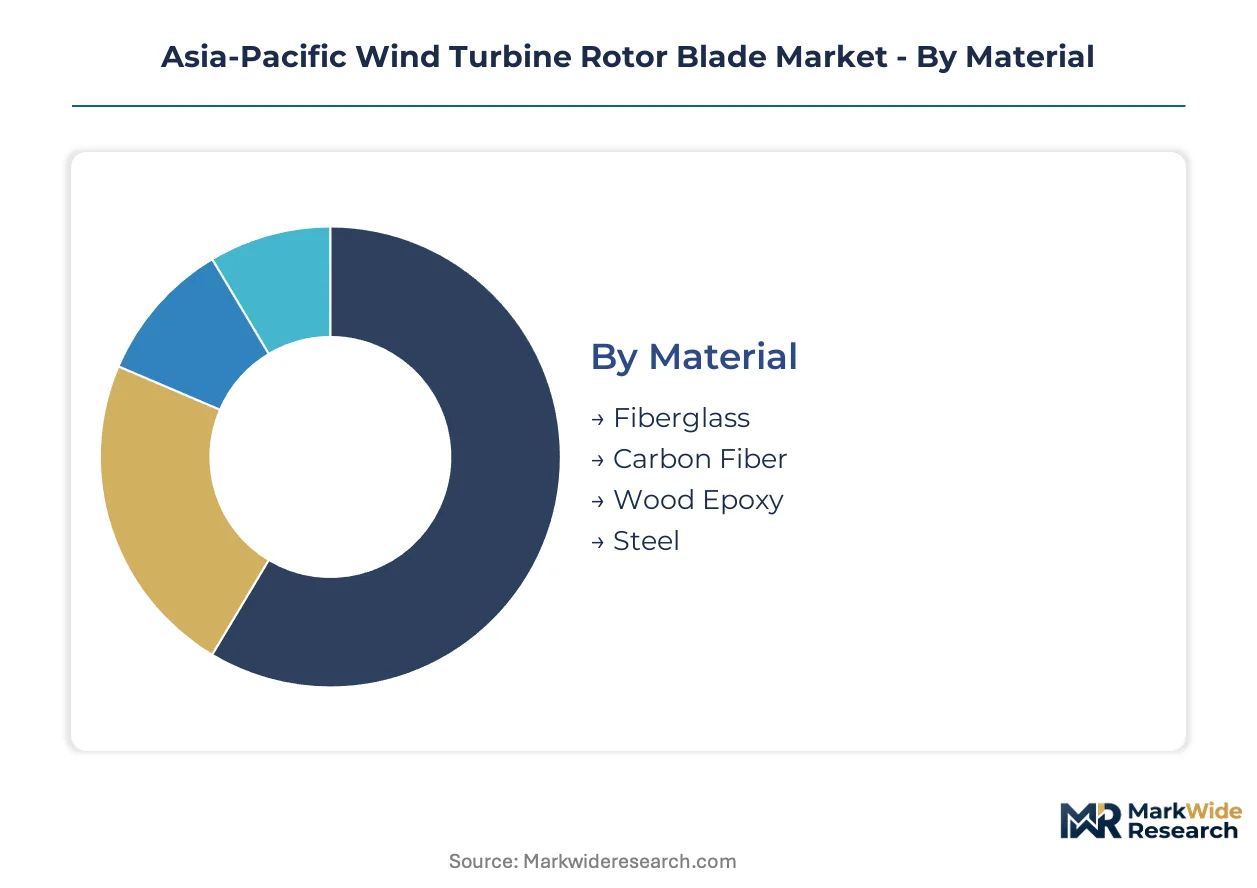
Rotor blade segmentation across the Asia-Pacific reflects divergent supply chain strategies between export-oriented coastal manufacturing and domestic-serving inland facilities. Material selection and sizing decisions trace directly to whether blades serve Jiangsu offshore arrays or Indian onshore wind parks.
Material:
Domestic procurement concentrates on cost-optimized fiberglass formulations, while export-grade offshore contracts specify carbon fiber hybrids requiring marine-grade epoxy systems.
- Fiberglass:Glass-reinforced epoxy dominates blade skins and webs across onshore installations below 100 meters. Jiangsu and Shandong fabricators source chopped strand mat from domestic suppliers to serve state-backed utility procurement concentrated in northern China.
- Carbon Fiber:Toray T800 and T1000 prepregs reinforce spar caps in 110-meter-plus offshore blades where stiffness-to-weight ratios determine fatigue life. Guangdong developers specify carbon fiber content above 15% by mass for typhoon-resistant platforms in the South China Sea.
- Wood Epoxy:Balsa and PVC core sandwich panels from Ecuadorian plantations supply leading edge reinforcement for lightweight blade architectures in Tamil Nadu manufacturing clusters.
- Steel:Spar cap inserts and root connection hardware utilize high-strength alloy forgings for hub interface durability across all blade size classes.
Fiberglass commands the established base. The steepest expansion runs through carbon fiber as offshore gigawatt-scale projects multiply.
Size:
Blade length directly determines whether manufacturing occurs at coastal export hubs or inland domestic-serving facilities with constrained logistics corridors.
- Small:Sub-50 meter blades serve distributed wind and repowering retrofits in South Korea's Gangwon province legacy fleet replacement programs.
- Medium:50-80 meter rotors anchor India's CEA-certified domestic supply base, with Gujarat and Tamil Nadu fabricators optimizing mold utilization for NTPC tender volumes.
- Large:80-110 meter blades capture Australia's Clean Energy Regulator-verified utility-scale onshore developments in Victoria and South Australia.
- Extra Large:110-meter-plus rotors require specialized transport vessels and port infrastructure available only at Fujian and Jiangsu manufacturing sites serving floating offshore platforms.
Medium blades retain volume leadership across installed base calculations. Extra large configurations gain share fastest as METI-designated marine zones in Japan and Vietnam's Binh Thuan licensing rounds activate.
Technology:
Technology selection tracks wind resource profiles and foundation constraints specific to each Asia-Pacific sub-region's development pipeline.
- Horizontal Axis:Upwind three-blade configurations dominate utility-scale procurement, with aerodynamic optimization from Goldwind and Envision driving hub height scaling across China's coastal provinces.
- Vertical Axis:Darrieus and Savonius variants attract R&D investment for urban distributed applications in Japan's constrained onshore sites and Australian remote mining operations.
- Ducted:Shrouded rotor concepts concentrate flow acceleration research at South Korean national laboratories for low-wind-speed site enhancement.
- Hybrid:Combined lift-drag mechanisms prototype at Indian Institute of Technology Madras for monsoon-pattern wind regimes with directional variability.
Horizontal axis technology holds the installed capacity majority. Hybrid configurations show the most rapid experimental deployment trajectory as low-wind site development accelerates.
End User:
Procurement authority concentrates among state-affiliated entities with direct MIIT or CEA mandate relationships, displacing merchant developer sourcing patterns.
- Utilities:State Grid Corporation of China and China Huaneng Group negotiate integrated turbine-blade packages for Shandong and Fujian offshore zones, eliminating third-party blade supplier margins.
- Industrial Developers:Steel, aluminum, and chemical conglomerates in India establish captive wind capacity under open access regulations, sourcing blades through EPC contractors with PLI scheme qualification requirements.
- Independent Power Producers:Vertically integrated renewable specialists in Australia aggregate portfolio-scale blade procurement across multiple OEM platforms to diversify technology risk.
- Renewable Energy Companies:Pure-play developers in Vietnam's emerging offshore sector partner with European turbine OEMs for blade supply tied to floating foundation technology transfer agreements.
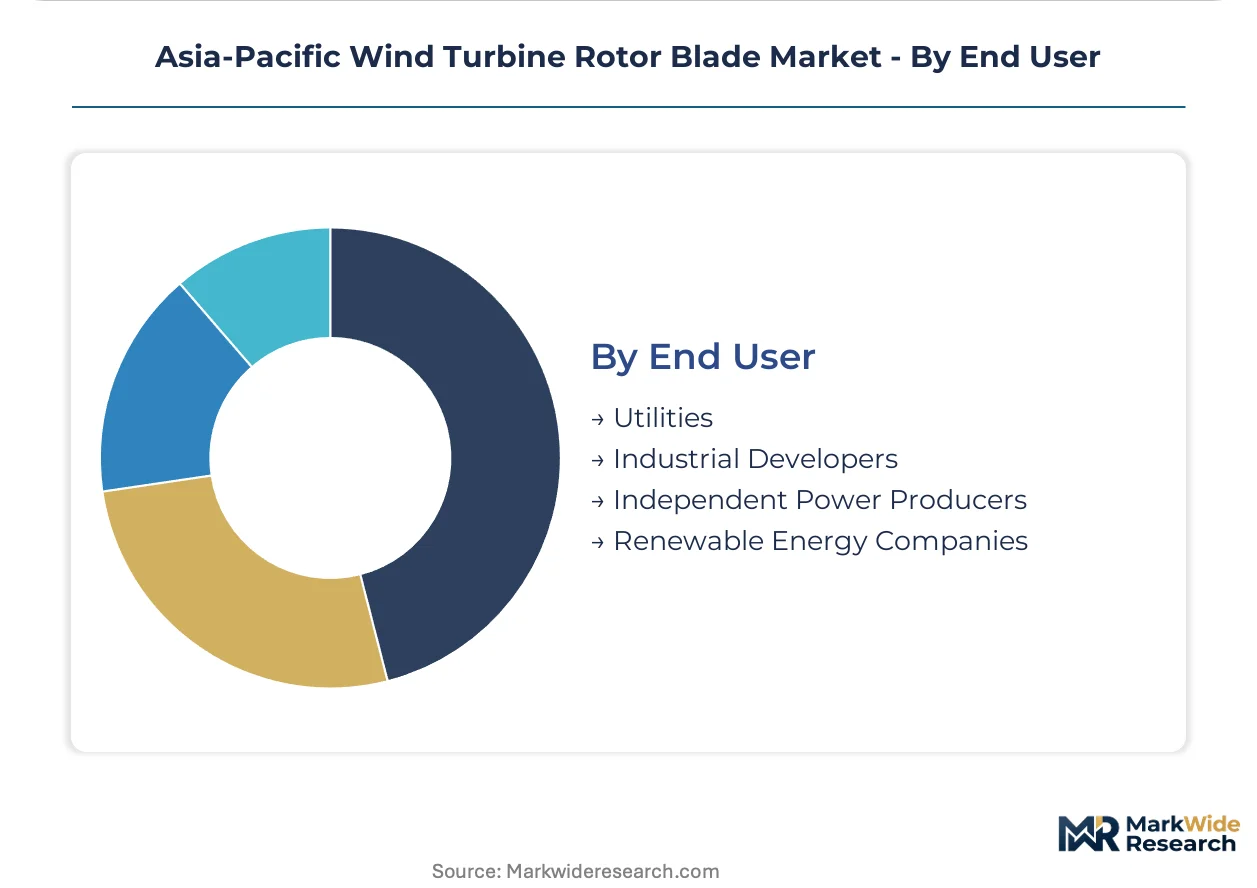
Utilities dominate procurement volume through state-backed generator consolidation. Renewable energy companies expand most aggressively as Vietnam, the Philippines, and Indonesia open offshore leasing rounds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-backed utilities and vertically integrated IPPs concentrate procurement authority across the Asia-Pacific, with procurement patterns diverging sharply between China's coastal offshore zones and India's inland domestic-serving clusters.
China
MIIT-mandated dual carbon goals force OEMs to establish captive blade manufacturing in Jiangsu and Fujian coastal provinces. GB standards for structural integrity and grid compatibility govern all blade specifications. Gigawatt-scale offshore projects at Yancheng and Fuzhou drive orders for 110-meter-plus extra-large rotors requiring specialized port infrastructure.
India
CEA type certification mandates for grid-connected components compress development cycles for domestic suppliers seeking NTPC and SECI tender qualification. The PLI scheme for renewable energy components accelerates localized fabrication requirements. Tamil Nadu and Gujarat manufacturing clusters consolidate around common mold platforms to accelerate certification throughput.
Japan
METI-designated marine zones spur demand for extra-large blades engineered for typhoon-resistant floating offshore platforms. Offshore permitting guidance influences blade sizing specifications for novel foundation applications. Chubu and Kyushu coastal prefectures host prototype testing for hybrid configurations targeting low-wind monsoon patterns.
Vietnam
Binh Thuan and Ninh Thuan province offshore lease rounds create first-mover positioning for blade suppliers with floating foundation compatibility. Emerging renewable energy companies partner with European turbine OEMs for technology transfer agreements. Southern coastal manufacturing greenfields face composite technician scarcity constraining vacuum infusion throughput.
Australia
The Clean Energy Regulator ties large-scale generation certificates to verified turbine performance, indirectly shaping blade specification requirements for utility-scale developments. Victoria and South Australia onshore projects anchor demand for 80-110 meter large-class rotors. Vertically integrated IPPs aggregate portfolio-scale procurement across multiple OEM platforms to diversify technology risk.
Asia-Pacific Wind Turbine Rotor Blade Market Competitive Environment
Player mix skews toward integrated turbine OEMs with captive blade supply, compressing margins for independent manufacturers without platform anchoring. The supplier base stratifies across three tiers: global blade specialists with marine-grade certification infrastructure, Chinese state-affiliated OEMs with dual carbon-mandated coastal manufacturing, and emerging domestic fabricators in India and Southeast Asia seeking CEA or equivalent qualification. Competitive moves concentrate on backward integration into carbon fiber spar cap production and strategic partnerships for floating platform technology transfer.
Among global blade specialists, TPI Composites and LM Wind Power exemplify the certification-heavy archetype serving multiple OEM platforms across the region. Within the integrated OEM tier, Goldwind and Siemens Gamesa Renewable Energy anchor competitive positioning through captive production aligned with turbine installation scale. These three companies occupy positions spanning the specialist-integrated spectrum, with geographic footprints reflecting divergent strategies toward offshore export markets versus domestic-serving volume.
| Leading Market Players |
|---|
| TPI Composites |
| Goldwind |
| Vestas Wind Systems A/S |
| Envision Energy |
| Mingyang Smart Energy |
| Siemens Gamesa Renewable Energy |
| Lianyungang Zhongfu Lianzhong Composites Group |
| Dongfang Electric Corporation |
| LM Wind Power |
| Others |
Value Chain & Pricing Dynamics
DNV GL and TÜV marine-grade certification timelines simultaneously gate supplier qualification and stratify price premiums across the Asia-Pacific blade market, compressing margins for uncertified fabricators while enabling certified specialists to command structural premiums on extra-large offshore contracts.
Pricing Analysis
Cost-plus contracts with carbon fiber and epoxy resin indexation dominate procurement between Chinese OEMs and coastal fabricators. Price differentiation hinges on certification tier—GL-certified suppliers capture 15-20% premiums over CEA-type-certified domestic peers—and volume scale, with gigawatt-scale offtake agreements compressing per-unit margins. Pricing pressure intensifies in the medium-blade segment as Tamil Nadu and Gujarat manufacturers consolidate around common mold platforms to accelerate NTPC tender qualification. State-backed utilities in Shandong and Fujian provinces exhibit lowest price sensitivity, prioritizing single-source accountability over procurement cost minimization.
Supply Chain Analysis
Inbound logistics costs from Shanghai and Ningbo port congestion constrain just-in-time delivery of Toray T800 prepregs to Jiangsu manufacturing clusters. Supply concentrates in China, India, and Vietnam, with carbon fiber spar caps drawing from Japanese and South Korean precursor supply. Raw material dependencies span Ecuadorian balsa core, marine-grade epoxy systems, and high-strength alloy root forgings. Single-source vulnerability runs through Papua New Guinean plantation capacity for sandwich panel cores. Distribution runs through direct OEM procurement of integrated turbine-blade packages, displacing third-party supplier channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific wind turbine rotor blade market is recovering from a cyclical trough driven by offshore licensing acceleration across Vietnam, Japan, and China's coastal provinces, with procurement volumes inflecting upward as METI and MIIT mandates activate project pipelines.
For Market Incumbents: Compound certification infrastructure advantages by extending GL-qualified testing capacity to serve floating platform blade formats for Japan's METI-designated marine zones. Deepen backward integration into carbon fiber spar cap production to offset aerospace sector competition for Toray and SGL Carbon output. Lock in long-term balsa core supply agreements with Ecuadorian plantation operators before Papua New Guinean capacity constraints tighten further. For New Entrants and Emerging Players: Anchor in Vietnam's Binh Thuan and Ninh Thuan province offshore lease rounds, where European turbine OEMs actively seek blade suppliers with floating foundation compatibility. Target South Korean repowering retrofits at Gangwon and Jeolla provinces, where aerodynamic add-on kits for legacy 1.5-2.3 MW fleets face limited domestic competition. Pursue technology transfer partnerships with established marine-grade certifiers to compress 18-24 month qualification timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across extra-large offshore blade manufacturing, as 110-meter-plus rotors require specialized port infrastructure and vacuum infusion automation. Prioritize acquisition targets with captive carbon fiber spar cap production and established relationships with state-backed Chinese utilities. Watch for inflection signals in Vietnam's offshore licensing velocity and India's PLI scheme disbursement rates to calibrate entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Marine-Grade Certification Investment | DNV GL qualification enables participation in Japan's METI-designated floating offshore zones. |
| Carbon Fiber Spar Cap Backward Integration | In-house Toray T800 prepreg processing insulates margins from aerospace sector demand spikes. |
| Floating Platform Technology Partnership | European OEM transfer agreements unlock Vietnam's Binh Thuan and Ninh Thuan lease rounds. |
| Repowering Retrofit Kit Development | Aerodynamic add-ons for South Korea's Gangwon legacy fleet address underserved replacement demand. |
| Balsa Core Supply Agreement | Long-term Ecuadorian plantation contracts secure lightweight sandwich panel feedstock against Papua New Guinean constraints. |
Study Parameters
A spread of perspectives from utility planning officers, IPP project developers, EPC contractors, and composite manufacturing engineers converged on the working assumptions governing blade demand trajectories. Primary fieldwork with blade fabricators in Jiangsu, Tamil Nadu, and Guangdong provinces was cross-referenced against secondary validation from MIIT GB standard filings, CEA type certification registries, IEA offshore wind reports, and customs trade data for carbon fiber and balsa core imports. Bottom-up installation forecasts were triangulated against top-down renewable capacity targets across the analysis window.
Segmentation dimensions modeled include material composition, blade size class, technology configuration, and end-user procurement authority across the projection horizon. CAGRs were derived from regression analysis of historic installation data against policy mandate timelines. Industry-specific forecast inputs encompassed floating platform deployment schedules in Japan's METI-designated marine zones and PLI scheme disbursement velocity for Indian domestic manufacturing.
Material uncertainties—balsa core supply disruptions, carbon fiber aerospace demand spikes, and certification timeline extensions—sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and offshore leasing round activation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Turbine Nacelle Market
Wind Energy Systems
Asia-Pacific Wind Power Market
Wind Energy Systems
Europe Small Wind Turbine Market
Wind Energy Systems
Taiwan Wind Energy Market
Wind Energy Systems
Wind Power Composite Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Drive Market
Wind Energy Systems
Wind Power SCADA Market
Wind Energy Systems
Wind Energy Rescue System Market
Wind Energy Systems
Wind Turbine Pitch Systems Market
Wind Energy Systems
Wind Electric Power Generation Market
Wind Energy Systems
Global Wind Automation Market
Wind Energy Systems
Floating Wind Turbine Market
Wind Energy Systems
Global Wind LIDAR Market
Wind Energy Systems
United States Wind Energy Market
Wind Energy Systems
Wind Turbine Rotor Blade Market
Wind Energy Systems
Wind Power Bolts Market