
 France Wind Energy Market | 2026-2036
France Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
France Wind Energy Market Analysis
Capital-intensity divergence between turbine OEMs and project developers is bifurcating competitive returns across the France wind energy value chain. Vestas Wind Systems A/S leverages its blade manufacturing footprint in Cherbourg to anchor servicing contracts along the Channel coast. EDF Renewables competes through its pipeline dominance in floating offshore zones. Siemens Gamesa Renewable Energy differentiates via direct-drive generator technology tailored to North Atlantic wind profiles.
France wind energy encompasses the conversion of kinetic wind resources into grid-connected electricity through horizontal-axis turbines with rotor diameters exceeding 150 meters for offshore applications and hub heights surpassing 90 meters for optimized onshore yield. The technology segment splits between mature onshore installations and nascent floating offshore platforms where water depths exceed 50 meters. Utility-scale deployment leads capital allocation, while independent power producers concentrate margin capture in distributed community wind configurations below 15 MW per site.
France's national energy regulator and grid operator enforce connection priority for renewable assets under the country's multi-annual energy program, while EU Green Deal carbon budgets tighten fossil displacement timelines. ANSM and CNIL oversight extends to worker safety and data governance for offshore logistics platforms. Stakeholders must monitor floating foundation certification pathways and port infrastructure readiness ahead of Atlantic lease auction rounds.
Market Dynamics
Floating offshore foundation certification under Bureau Veritas and DNV protocols is compressing project development timelines while reshaping capital allocation across the Atlantic coastline. The tension between port infrastructure readiness and turbine scaling requirements dominates developer strategic planning.
Growth Catalysts
- EU Green Deal carbon budgets:Binding national targets under the European Climate Law accelerate fossil displacement timelines and anchor long-term offtake agreements for utility-scale projects.
- Floating platform technology maturation:Semi-submersible and tension-leg foundation designs unlock development zones beyond 50-meter water depths off Brittany and the Mediterranean.
- Grid connection priority mechanisms:France's national energy regulator enforces renewable asset dispatch precedence under the multi-annual energy program, reducing curtailment risk.
Market Restraints
- Steel and rare earth input volatility:Permanent magnet generator supply concentrates among Chinese processors, exposing OEMs to dysprosium and neodymium price swings.
- Specialized vessel scarcity:Heavy-lift installation ships for 15 MW+ turbines number fewer than ten units across European fleets, creating Atlantic project queue bottlenecks.
- Aviation radar interference protocols:French military and civil aviation authorities impose turbine height restrictions near coastal defense installations, constraining rotor diameter optimization.
Strategic Opportunities
- Channel port infrastructure modernization:Le Havre and Saint-Nazaire expansion investments position Normandy as a floating foundation assembly hub serving Celtic Sea lease rounds.
- Green hydrogen offtake convergence:Electrolyzer co-location at offshore substations creates synthetic fuel revenue streams for projects with constrained grid export capacity.
- Community wind aggregation models:Agricultural cooperatives and municipal utilities capture margin in sub-15 MW distributed configurations below regulated auction thresholds.
Industry Challenges
- Offshore technician certification backlog:GWO and BZEE training capacity lags fleet expansion, extending commissioning schedules for floating platform maintenance crews.
- Grid code compliance testing delays:RTE network stability requirements for synthetic inertia provision extend type certification timelines for new turbine platforms.
- Foundation-wind turbine interface standardization:Proprietary mooring and dynamic cable designs fragment supply chains, inflating project-specific engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Wind Energy Market |
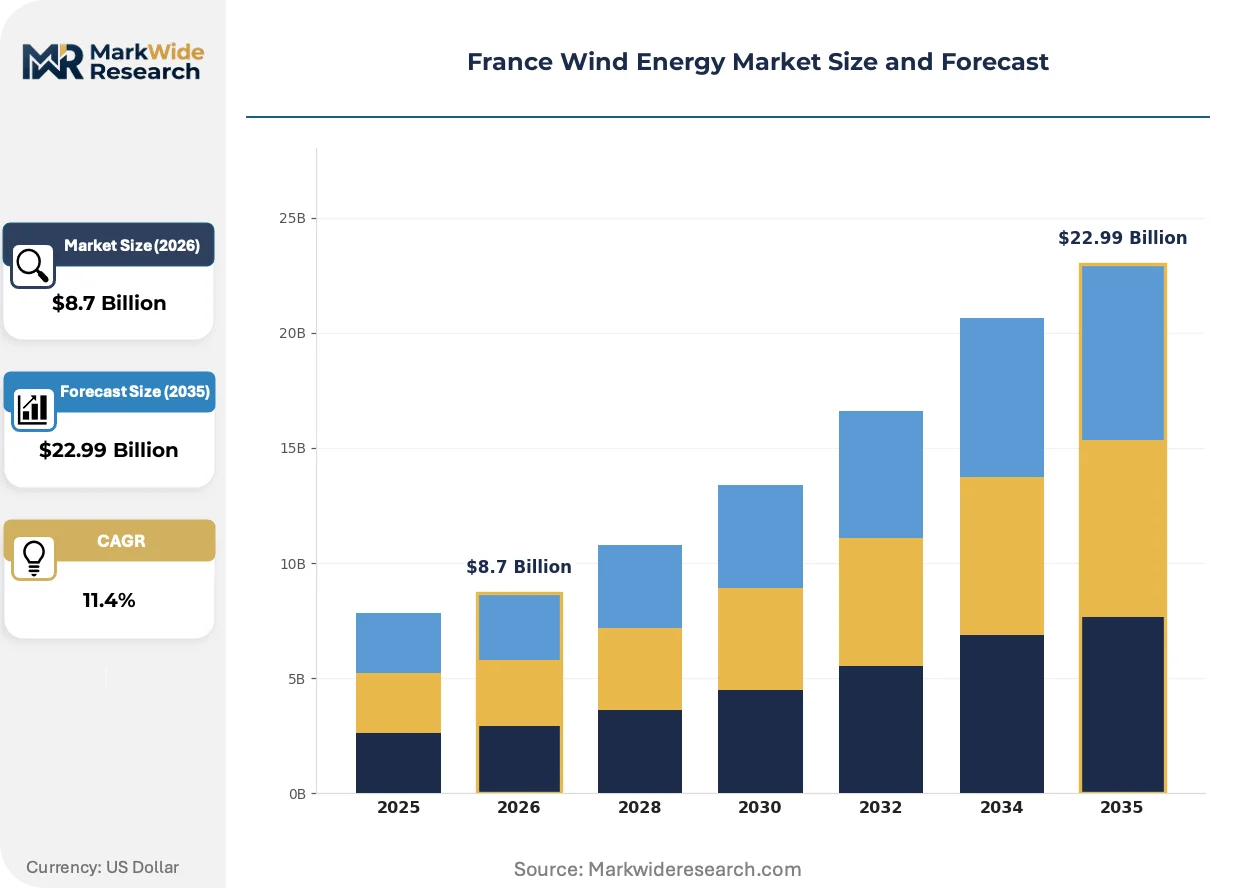
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Turbines, Blades, Nacelles, Generators Technology: Onshore, Offshore, Floating, Fixed Bottom Deployment: Utility-Scale, Distributed, Microgrid, Community End User: Utilities, Independent Power Producers, Government, Corporates |
| Companies Covered | Vestas Wind Systems A/S, General Electric Company, Engie SA, VSB France, Iberdrola, EDF Renewables, Siemens Gamesa Renewable Energy, Neoen SA, TotalEnergies SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Wind Energy Market Emerging Trajectories
Direct-drive generator architectures and modular blade manufacturing are compressing maintenance intervals while opening new coastal industrial zones. Regulatory pressure on embodied carbon in steel foundations is redirecting procurement specifications.
Permanent magnet direct-drive technology eliminates gearbox failure modes in North Atlantic salt spray conditions. EDF Renewables and independent developers are specifying these units for 50+ meter water depth zones where crane access is restricted. The technology is bifurcating competitive returns between OEMs with in-house magnet supply agreements and those exposed to spot market rare earth pricing.
France's offshore tender program under the Energy and Climate Law imposes escalating local content requirements on auction winners. Developers must now source foundation steel from European mills and commit to port investment guarantees. Floating platform projects in the Mediterranean zone face tightened environmental impact assessment timelines under revised EU Marine Strategy Framework Directive implementation.
Utility procurement teams are unbundling turbine supply from long-term service agreements, compressing OEM margin capture. Independent asset managers and infrastructure funds now negotiate direct maintenance contracts with specialized blade repair and drivetrain refurbishment providers. This disintermediation is most visible in the Channel coastal zone where Vestas' Cherbourg facility competes against third-party service entrants for post-warranty contracts.
France Wind Energy Market Segmentation
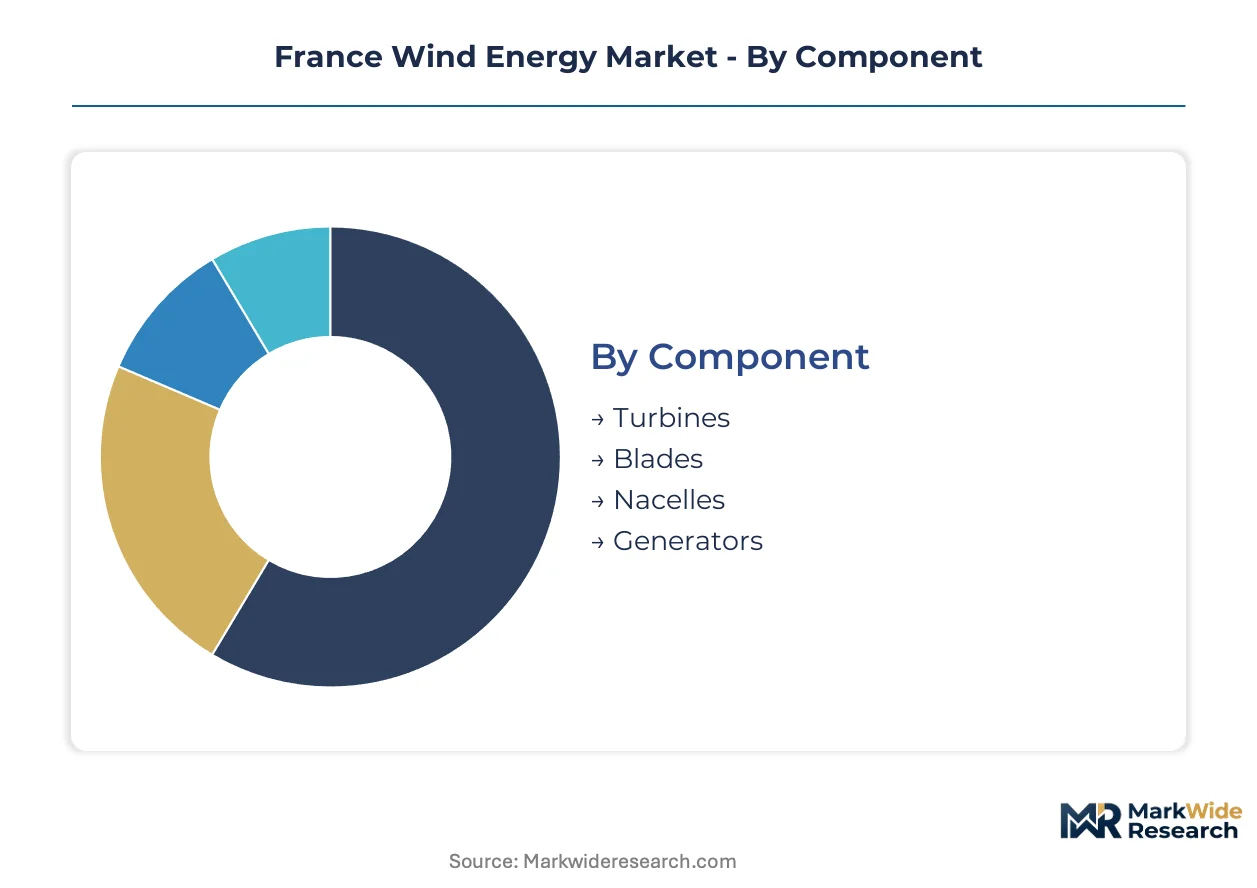
Segmentation in the France wind energy market reveals how regulatory obligations, technology maturity, and capital intensity distribute value capture across the value chain. Each dimension exposes distinct competitive dynamics between incumbent utilities, specialized OEMs, and emerging independent developers.
Component:
ANSM certification requirements and EU Green Deal embodied carbon standards differentiate procurement specifications across hardware categories, forcing developers to trace supply chain provenance for foundation steel and rare earth magnets.
- Turbines:Horizontal-axis units with rotor diameters exceeding 150 meters for offshore applications and hub heights surpassing 90 meters for optimized onshore yield. Demand concentrates along the Atlantic coastline, particularly in Brittany and Normandy, where French utilities are accelerating procurement of offshore wind capacity under the country's multi-annual energy program.
- Blades:Modular manufacturing designs using carbon fiber and glass fiber composites, with lengths exceeding 80 meters for utility-scale offshore units. Procurement is shifting toward port-proximate production facilities, with Vestas leveraging its Cherbourg footprint to anchor servicing contracts along the Channel coast.
- Nacelles:Housing assemblies integrating drivetrain, generator, and control systems, with direct-drive architectures eliminating gearbox components. These units face extended type certification timelines under RTE network stability requirements.
- Generators:Permanent magnet direct-drive and doubly-fed induction designs, with magnet supply concentrating among Chinese processors exposing OEMs to dysprosium and neodymium price volatility.
Turbines handle the majority of throughput; blades are expanding most quickly on share as port infrastructure investments enable larger rotor dimensions.
Technology:
Water depth and seabed geology determine technology selection, with Bureau Veritas and DNV certification protocols compressing development timelines for floating platforms while fixed-bottom designs mature in shallower zones.
- Onshore:Mature installations in agricultural and coastal plains with hub heights optimized for wind shear profiles. Demand concentrates in community wind configurations below 15 MW per site where independent power producers capture margin in distributed setups.
- Offshore:Fixed-bottom foundations in water depths below 50 meters, primarily along the Atlantic coastline. EDF Renewables competes through pipeline dominance in these zones where grid connection priority mechanisms reduce curtailment risk.
- Floating:Semi-submersible and tension-leg foundation designs unlocking development zones beyond 50-meter water depths off Brittany and the Mediterranean. These projects face tightened environmental impact assessment timelines under revised EU Marine Strategy Framework Directive implementation.
- Fixed Bottom:Monopile and jacket structures for shallower offshore zones, with foundation steel sourcing requirements mandating European mill procurement under France's offshore tender program.
Onshore retains the largest installed base; floating platforms are gaining share fastest as lease auctions open deeper Atlantic waters.
Deployment:
Scale thresholds determine auction eligibility and regulatory treatment, with the multi-annual energy program prioritizing utility-scale assets while sub-15 MW configurations operate below regulated procurement mechanisms.
- Utility-Scale:Projects exceeding 100 MW capacity, dominating capital allocation and long-term offtake agreements. These assets benefit from grid connection priority under France's national energy regulator enforcement.
- Distributed:Sub-15 MW installations serving industrial or agricultural loads, with independent power producers concentrating margin capture in these configurations.
- Microgrid:Islanded or weakly grid-connected systems integrating storage and demand response, emerging in Corsica and overseas territories with constrained transmission infrastructure.
- Community:Agricultural cooperative and municipal utility ownership models, capturing margin below regulated auction thresholds through aggregated procurement.
Utility-Scale handles the majority of throughput; Community is climbing the fastest on share as local content requirements favor municipal participation.
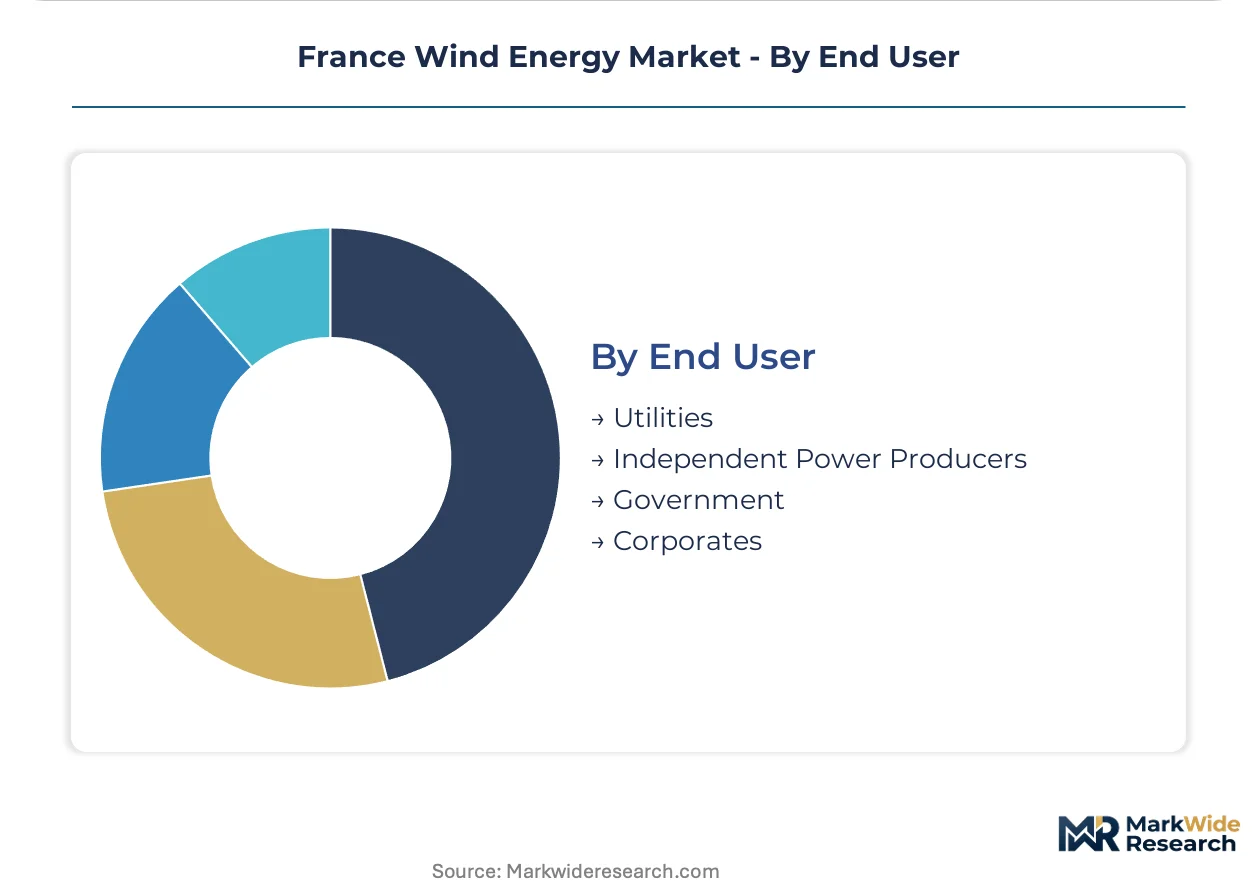
End User:
Balance sheet capacity and offtake structuring differentiate procurement strategies, with utilities leveraging regulated asset base treatment while corporates pursue virtual power purchase agreements.
- Utilities:EDF and Engie anchoring fleet expansion through regulated tariff mechanisms and offshore tender wins. These players dominate floating offshore zones and grid-scale storage co-location.
- Independent Power Producers:Infrastructure funds and specialized developers capturing margin in distributed and community configurations, negotiating direct maintenance contracts with third-party service providers.
- Government:Public procurement for defense installations and overseas territories, facing aviation radar interference protocols that constrain turbine height optimization near coastal defense sites.
- Corporates:Industrial offtakers securing renewable energy certificates through virtual power purchase agreements, with demand emerging from data center and electrolyzer operators in Normandy port zones.
Utilities handle the majority of throughput; Corporates show the steepest expansion trajectory as green hydrogen offtake convergence creates synthetic fuel revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Brittany and Normandy outstrips Mediterranean zones due to Atlantic wind resource density and port infrastructure readiness. The EU Green Deal carbon budgets and France's offshore tender program create divergent development timelines across coastal sub-regions. Regional concentration maps directly onto foundation assembly capacity and grid connection priority queues.
Brittany
Floating platform demand concentrates off the Breton coast where water depths exceed 50 meters. The EU Marine Strategy Framework Directive tightens environmental impact assessment timelines for semi-submersible projects. Saint-Brieuc and Brest anchor foundation manufacturing clusters where Bureau Veritas certification protocols compress development schedules.
Normandy
Fixed-bottom installations dominate capital allocation in the Channel zone with water depths below 50 meters. France's multi-annual energy program enforces grid connection priority for assets off Le Havre. The port's heavy-lift quay expansion positions it as a turbine assembly hub serving Celtic Sea lease rounds.
Pays de la Loire
Onshore repowering drives blade replacement cycles across agricultural plains south of the Loire estuary. ANSM safety oversight extends to tower climbing protocols for technician crews. Nantes-Saint-Nazaire hosts logistics platforms where Vestas anchors Channel coast servicing contracts.
Occitanie
Mediterranean floating pilots face constrained port infrastructure compared to Atlantic counterparts. CNIL data governance rules apply to offshore logistics platform telemetry systems. Port-la-Nouvelle and Sète cluster foundation engineering consultancies serving tension-leg design development.
Hauts-de-France
Community wind configurations below 15 MW capture margin in Picardy agricultural cooperatives. The national energy regulator's dispatch precedence rules reduce curtailment risk for distributed assets. Amiens and Lille anchor municipal utility procurement teams aggregating sub-auction threshold projects.
France Wind Energy Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the France wind energy value chain. Turbine OEMs with direct-drive generator architectures command premium positioning in floating offshore zones, while project developers with pipeline dominance capture regulated returns through utility-scale auctions. Three archetypes structure competition: integrated European OEMs with blade manufacturing footprints, French utility affiliates with regulated asset base treatment, and independent infrastructure funds unbundling turbine supply from long-term service agreements. M&A activity concentrates on port infrastructure assets and floating foundation engineering capabilities, while strategic partnerships link electrolyzer operators to constrained grid export projects.
Among Denmark-based OEMs, Vestas Wind Systems A/S exemplifies the port-proximate manufacturing archetype through its Cherbourg facility anchoring Channel coast servicing contracts. Siemens Gamesa Renewable Energy occupies a position within the direct-drive technology tier, with permanent magnet generator supply concentrating among Chinese processors. EDF Renewables represents the utility-affiliated developer archetype, competing through pipeline dominance in floating offshore zones where RTE network stability requirements extend type certification timelines.
| Leading Market Players |
|---|
| Vestas Wind Systems A/S |
| General Electric Company |
| Engie SA |
| VSB France |
| Iberdrola |
| EDF Renewables |
| Siemens Gamesa Renewable Energy |
| Neoen SA |
| TotalEnergies SE |
| Others |
Supply Flow & Price Mechanics
Permanent magnet substitution for doubly-fed induction generators redraws procurement geography toward Chinese rare earth processors while compressing margin structures for European OEMs lacking captive magnet supply. This input shift simultaneously elevates spot price exposure for dysprosium and neodymium while forcing developers to renegotiate long-term offtake terms around volatile raw material pass-through clauses.
Pricing Analysis
The customization-premium spread separates standard-configured onshore turbines from floating offshore units requiring site-specific foundation engineering. Project-based long-term offtake contracts dominate, with price differentiation driven by certification tier under Bureau Veritas protocols and vertical integration depth in magnet supply. Cost compression in the standard onshore tier is intensifying because Chinese OEMs are entering European procurement auctions. Independent power producers show highest price sensitivity due to thin balance sheet capacity, while utility affiliates absorb premium pricing for floating platforms to secure pipeline dominance.
Supply Chain Analysis
China controls permanent magnet processing and rare earth oxide refining, while European mills anchor foundation steel supply under France's local content mandates. The supply chain draws from Chinese dysprosium processors, German gearbox specialists, and Danish blade manufacturers. Single-source vulnerability concentrates in heavy-lift installation vessels, with fewer than ten European units capable of handling 15 MW+ turbines. Distribution runs through port-proximate assembly hubs at Cherbourg, Saint-Nazaire, and Le Havre, with logistics platforms feeding Atlantic lease zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
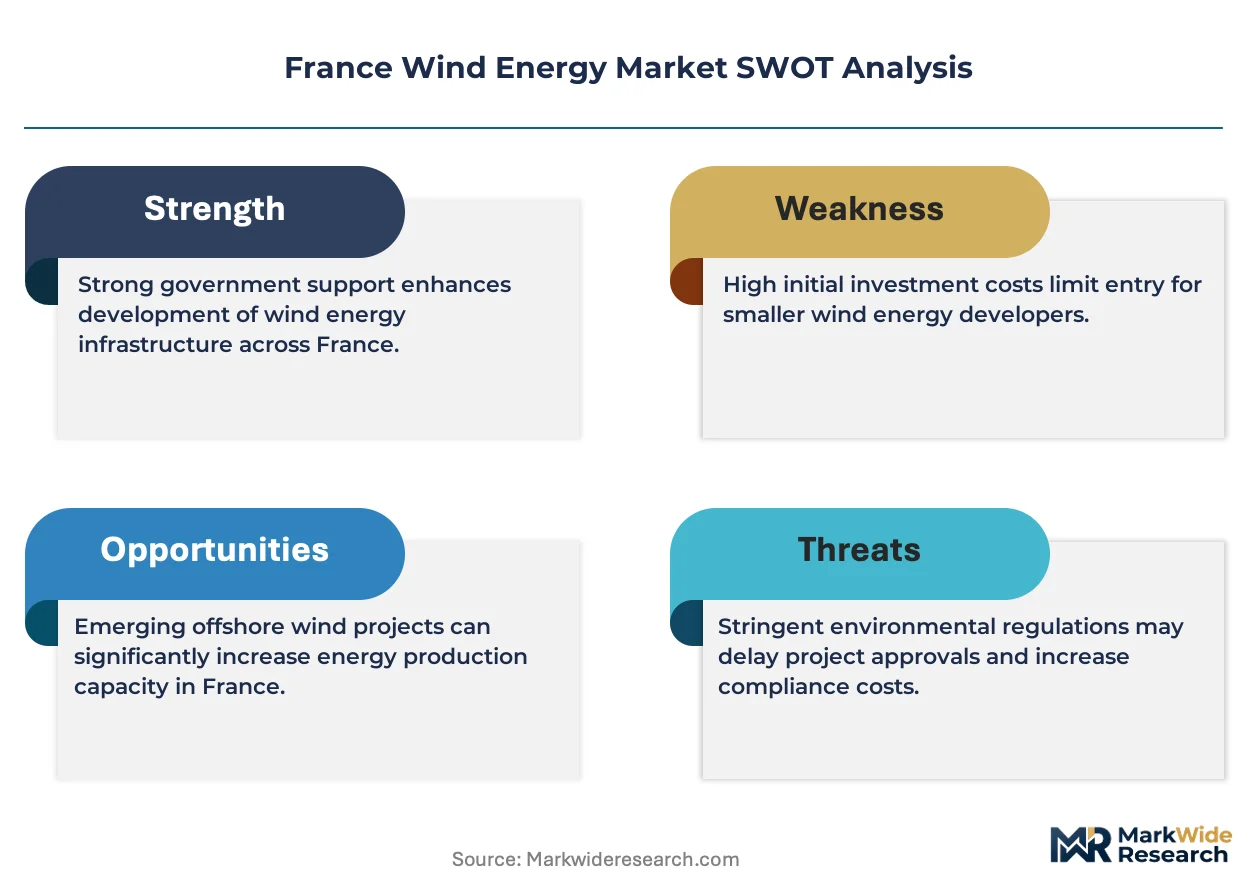
This market requires substitution defense against solar-plus-storage hybrids that are capturing corporate offtake contracts previously reserved for offshore wind. French utilities must navigate this threat while preserving auction pipeline viability.
For Market Incumbents: Shield floating platform margins through backward integration into foundation engineering capabilities at Saint-Nazaire and Brest. Secure captive magnet supply agreements with Chinese processors before spot price volatility escalates. EDF Renewables and Engie SA must preempt solar-plus-storage encroachment by bundling green hydrogen offtake into constrained grid export projects.
For New Entrants and Emerging Players: Post-warranty blade repair services represent a service-layer gap where Vestas' Cherbourg footprint faces limited third-party competition. Target community wind configurations below 15 MW in Hauts-de-France agricultural cooperatives, where municipal aggregation models bypass regulated auction thresholds. Enter through direct maintenance contracts with independent asset managers unbundling turbine supply from OEM service agreements.
For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors port infrastructure owners over pure-play developers. Long-term viability hinges on floating platform certification speed and electrolyzer co-location economics. Monitor Bureau Veritas approval timelines for semi-submersible designs as the inflection signal for Atlantic lease round competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Floating Foundation Certification | Bureau Veritas and DNV protocols compress development timelines for Brittany deep-water zones. |
| Port Infrastructure Expansion | Le Havre heavy-lift quay investments position Normandy as Celtic Sea assembly hub. |
| Green Hydrogen Co-location | Electrolyzer integration at offshore substations creates synthetic fuel revenue streams. |
| Magnet Supply Backward Integration | Captive agreements with Chinese processors hedge dysprosium spot price exposure. |
| Community Wind Aggregation | Municipal utility procurement below auction thresholds captures margin in distributed configurations. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators; and secondary validation through IEA deployment databases, RTE grid connection queues, EU Green Deal carbon budget filings, and Bureau Veritas certification registries. Bottom-up project pipeline aggregation triangulated against top-down national energy program targets.
Across the analysis window, the forecast framework modeled capacity additions by technology segment, water depth classification, and regional grid type. CAGRs derived from regression against historical auction award volumes and connection priority queue progression. Key inputs included floating platform cost curves, rare earth price trajectories, and port infrastructure readiness timelines.
Underlying assumptions cover EU Green Deal enforcement continuity and French offshore tender schedule adherence, with deviation risk concentrated in heavy-lift vessel availability and aviation radar clearance protocols. Recalibration cycles align with Atlantic lease auction outcomes and RTE grid code revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Sweden Wind Energy Market
Wind Energy Systems
Norway Wind Energy Market
Wind Energy Systems
Wind Turbine Shaft Market
Wind Energy Systems
South Korea Wind Energy Market
Wind Energy Systems
Offshore Wind Power Market
Wind Energy Systems
Floating Wind Power Market
Wind Energy Systems
Wind Turbine Blades Market
Wind Energy Systems
Australia Wind Energy Market
Wind Energy Systems
Asia-Pacific Large Wind Turbine Market
Wind Energy Systems
Wind Turbine Yaw and Pitch Gearbox Market
Wind Energy Systems
Ecuador Wind Energy Market
Wind Energy Systems
Germany Wind Energy Market
Wind Energy Systems
Bladeless Wind Turbines Market
Wind Energy Systems
Global Wind Power Coatings Market
Wind Energy Systems
Wind Turbine Gearbox Vibration and Condition Monitoring Test Platforms Market
Wind Energy Systems
Wind Turbine Operation and Maintenance Market