
 Wind Speed Alarm Market | 2026-2036
Wind Speed Alarm Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Speed Alarm Market Analytics
Silicon photonics is decoupling wind speed alarm costs from traditional mechanical anemometer manufacturing. Vaisala leverages proprietary ultrasonic sensor architectures to sustain premium positioning in meteorological-grade installations. Campbell Scientific anchors its competitive stance through deep calibration protocols for extreme-climate deployments.
A wind speed alarm detects velocity thresholds through rotational, thermal, or optical measurement principles and triggers safety protocols when preset limits exceed operational boundaries; cup anemometers typically measure from 0.3 to 50 meters per second with accuracy within two percent. The device protects infrastructure ranging from construction cranes to wind turbines by enabling automated shutdown or alert cascades. Digital technology leads installed value as smart sensor platforms integrate edge computing and predictive maintenance algorithms. Wireless installations represent the fastest-expanding category where remote monitoring eliminates cabling costs across distributed wind farms. Fixed installations retain volume dominance in aviation and permanent meteorological stations where continuous hardwired reliability remains non-negotiable.
FAA instrument landing system requirements and IEC 61400 turbine safety standards shape product certification pathways and compliance costs for manufacturers serving aviation and renewable energy sectors. EPA regional haze regulations and OSHA crane safety mandates further expand addressable demand across construction and industrial applications. Stakeholders must weigh sensor fusion investments against single-instrument reliability as end users consolidate platforms and demand multi-hazard detection from unified hardware architectures.
Market Dynamics
Offshore wind farm operators are consolidating sensor platforms under unified hazard-detection architectures, compressing procurement cycles and forcing hardware suppliers to integrate multi-parameter capabilities or exit premium segments.
Growth Catalysts
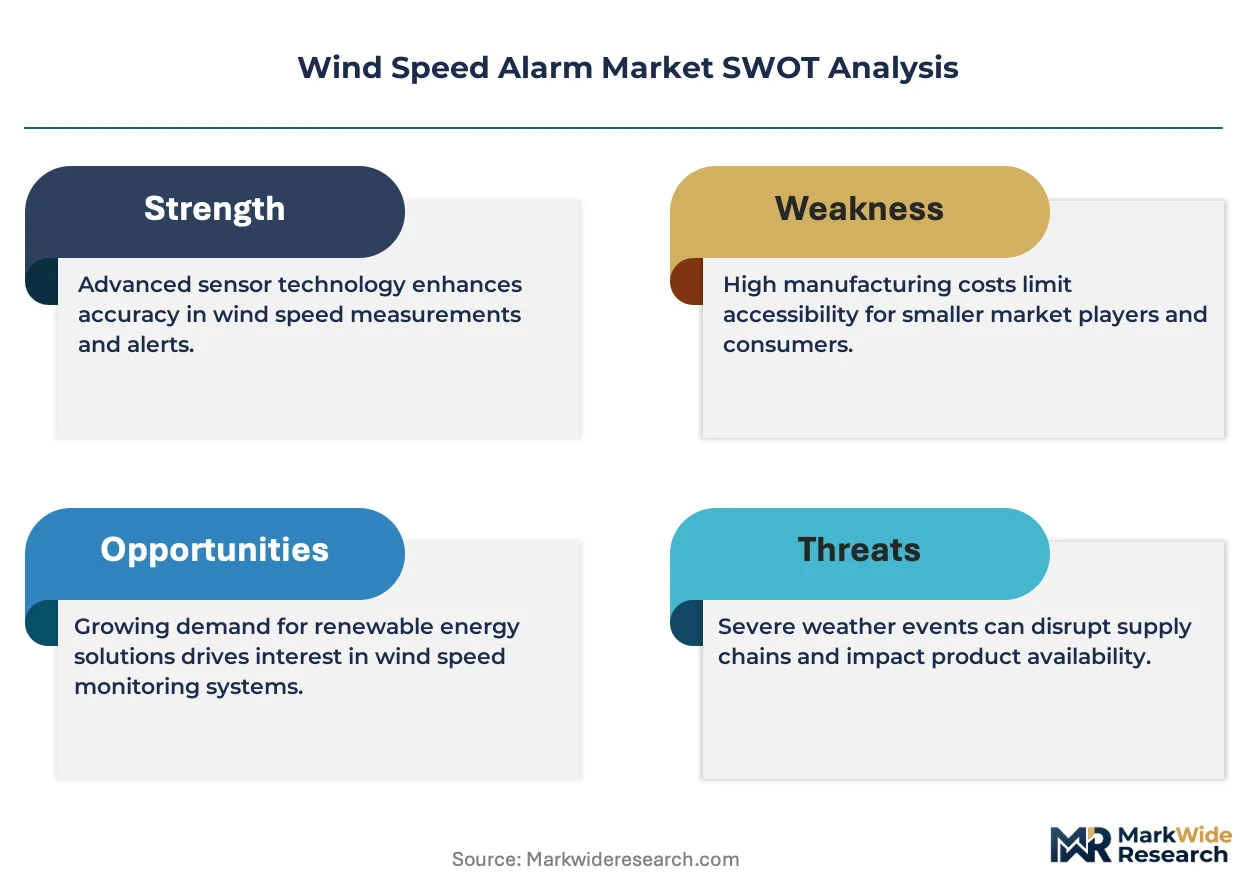
- IEC 61400 turbine protection mandates:European offshore operators must install certified wind speed alarms as condition for grid connection permits, creating baseline demand across North Sea developments.
- Wireless telemetry adoption:Elimination of submarine cabling costs across distributed turbine arrays accelerates replacement of legacy hardwired anemometer networks.
- Construction crane safety enforcement:OSHA mandates in the United States trigger retrofit demand for boom-mounted velocity sensors on infrastructure projects exceeding specified height thresholds.
Market Restraints
- Silicon photonics component concentration:Specialized optical chip fabrication concentrates among Asian foundry operators, exposing supply chains to single-source vulnerability.
- Calibration infrastructure scarcity:Accredited wind tunnel facilities for meteorological-grade certification remain limited to Germany, the United Kingdom, and Denmark, extending lead times.
- Ultrasonic sensor cost premium:Solid-state measurement architectures command multiples over mechanical cup anemometers, constraining penetration in price-sensitive construction applications.
Strategic Opportunities
- India offshore wind pre-development:Lease auctions in the Gulf of Khambhat and Gulf of Mannar create first-mover positioning for turbine protection system suppliers ahead of commercial operation dates.
- Edge computing convergence:Integration of on-chip AI inference with optical sensors enables predictive maintenance algorithms that differentiate premium offerings from commodity hardware.
- FAA NextGen weather requirements:Modernized instrument landing system specifications in the United States mandate upgraded anemometer accuracy classes, opening retrofit cycles at regional airports.
Industry Challenges
- Meteorological calibration expertise gap:Field technicians capable of traceable wind tunnel verification against ISO 17713-1 standards remain scarce, forcing manufacturers to maintain captive service networks.
- Legacy analog integration friction:Digital sensor platforms face protocol translation complexity when interfacing with existing SCADA architectures at older onshore wind installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Speed Alarm Market |
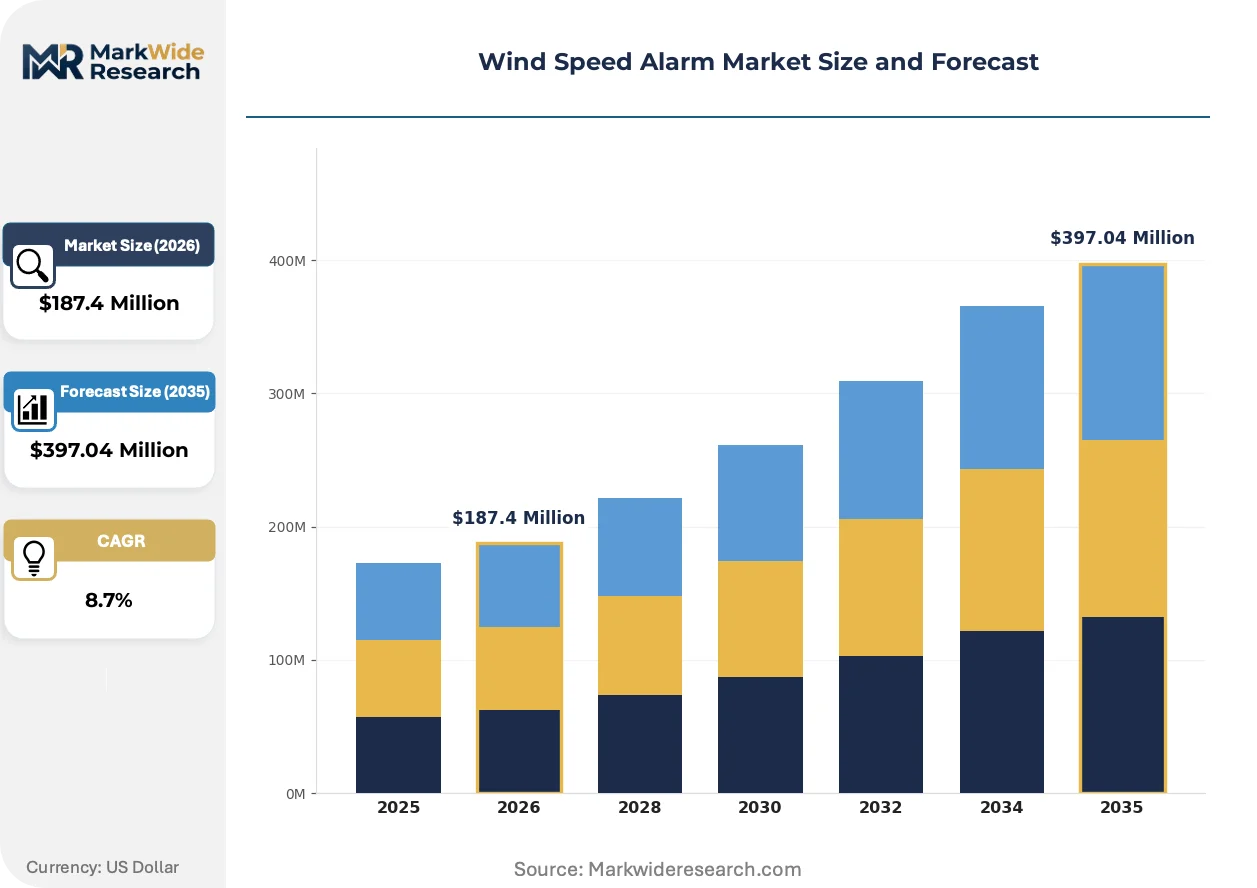
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anemometer, Cup Anemometer, Laser Doppler Anemometer, Hot Wire Anemometer End User: Agriculture, Renewable Energy, Meteorology, Aviation Technology: Digital, Analog, Wireless, Smart Sensors Installation: Fixed, Portable, Cloud-Integrated, Remote Monitoring |
| Companies Covered | Vaisala, Gill Instruments, Campbell Scientific, PCE Deutschland GmbH, Comptus, Maximum Weather Instruments, Belfort Instrument, Scarlet Tech, Davis Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Speed Alarm Market Evolving Landscape
Silicon photonics and solid-state sensing are collapsing the traditional distinction between meteorological-grade precision and industrial-grade durability, enabling single-platform architectures that span aviation, offshore energy, and construction verticals.
Optical MEMS wind sensors are automating threshold detection through chip-scale interferometry that eliminates moving parts entirely. Offshore wind farm operators in Germany and Denmark are deploying these packages at scale for nacelle-mounted applications. The technology is automating turbine protection decisions previously requiring human-in-the-loop verification, compressing emergency response latency from seconds to milliseconds.
EU Green Deal implementation is tightening F-Gas Regulation compliance for thermal anemometer cooling systems used in extreme-climate meteorological stations. Manufacturers serving European aviation and research markets must redesign thermal mass flow architectures or exit affected product lines. IEC 61400-12-1 edition updates are accelerating this transition by incorporating solid-state measurement as preferred practice for turbine power performance verification.
Sensor-as-a-service contracting is displacing capital purchase models among distributed wind farm operators managing portfolios across multiple jurisdictions. Danish and British offshore developers now procure wind speed monitoring through performance-guaranteed subscriptions bundling hardware, calibration, and data analytics. This shift concentrates vendor selection authority with procurement teams rather than engineering departments, favoring suppliers with integrated service platforms over component specialists.
Wind Speed Alarm Market Segmentation
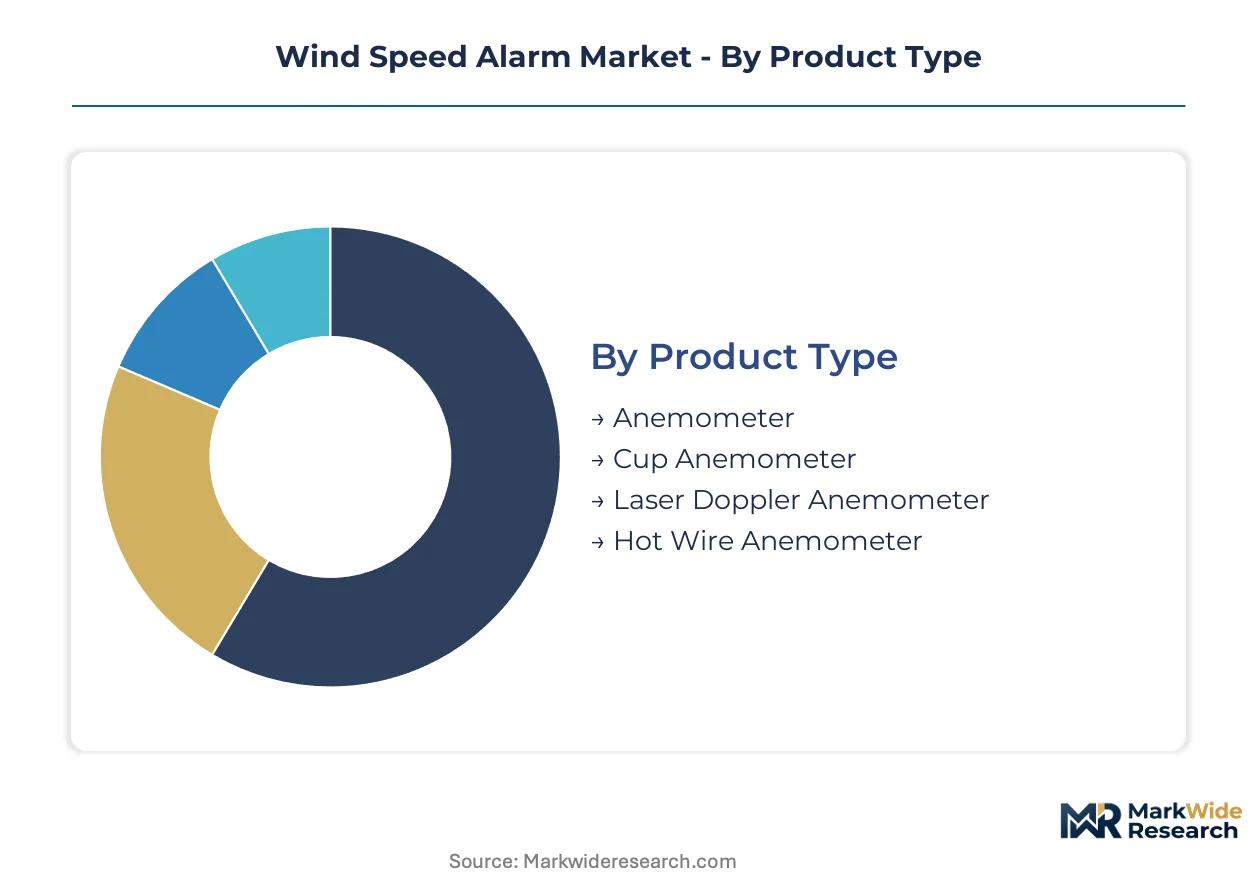
Wind speed alarm segmentation reveals how certification requirements fragment procurement across aviation, offshore energy, and meteorological applications. Each dimension carries distinct regulatory burdens that shape supplier qualification pathways and customer switching costs.
Product Type:
IEC 61400-12-1 certification mandates separate turbine-grade anemometers from general industrial instruments, while FAA instrument landing system approvals govern aviation procurement.
- Anemometer:Encompasses ultrasonic and mechanical architectures measuring velocity through acoustic time-of-flight or rotational displacement. Offshore wind developers in Germany and Denmark specify these for nacelle-mounted turbine protection under grid connection permit conditions.
- Cup Anemometer:Rotating three-cup assemblies deliver proven reliability from 0.3 to 50 meters per second with accuracy within two percent. Legacy installations across North Sea wind farms retain these for baseline compliance despite solid-state alternatives gaining share.
- Laser Doppler Anemometer:Non-intrusive optical measurement using coherent light scattering eliminates mechanical wear in research-grade deployments.
- Hot Wire Anemometer:Thermal mass flow sensing through heated filament resistance changes serves laboratory velocity profiling with microsecond response times.
Cup anemometer installations sit at the top of the volume ranking, with ultrasonic anemometer configurations climbing the fastest.
End User:
Customer concentration varies sharply by procurement cycle length, with aviation and offshore energy locking suppliers into decade-long service agreements while agriculture and construction drive spot purchasing.
- Renewable Energy:Offshore wind farm operators mandate redundant velocity monitoring for turbine cut-out and restart sequencing. IEC 61400 standards require certified alarms as condition for operational permits across British and Danish lease areas.
- Aviation:FAA instrument landing system specifications dictate anemometer accuracy classes for runway wind shear detection. Regional airports in the United States face retrofit deadlines under NextGen modernization timelines.
- Meteorology:National weather services deploy research-grade sensors requiring ISO 17713-1 traceable calibration against limited accredited wind tunnel facilities.
- Agriculture:Irrigation scheduling and frost protection applications prioritize cost over precision, constraining penetration of meteorological-grade hardware.
Renewable energy commands the largest procurement volumes, with aviation exhibiting the steepest expansion trajectory as NextGen retrofit cycles accelerate.
Technology:
Platform architecture determines integration complexity with existing SCADA networks and predictive maintenance capability deployment.
- Digital:Edge-computing-enabled sensors process threshold detection locally while streaming telemetry to centralized analytics platforms. Offshore operators in the United Kingdom consolidate these with vibration and temperature monitoring under unified hazard-detection architectures.
- Smart Sensors:On-chip AI inference automates anomaly classification and predictive maintenance scheduling without cloud dependency. Danish developers procure these through sensor-as-a-service subscriptions bundling hardware, calibration, and analytics.
- Wireless:Eliminates submarine cabling costs across distributed turbine arrays, accelerating replacement of hardwired legacy networks.
- Analog:Continuous voltage output signals persist in older onshore installations where protocol translation complexity impedes digital platform adoption.
Digital platforms lead installed value, with smart sensor configurations gaining share fastest through performance-guaranteed contracting models.
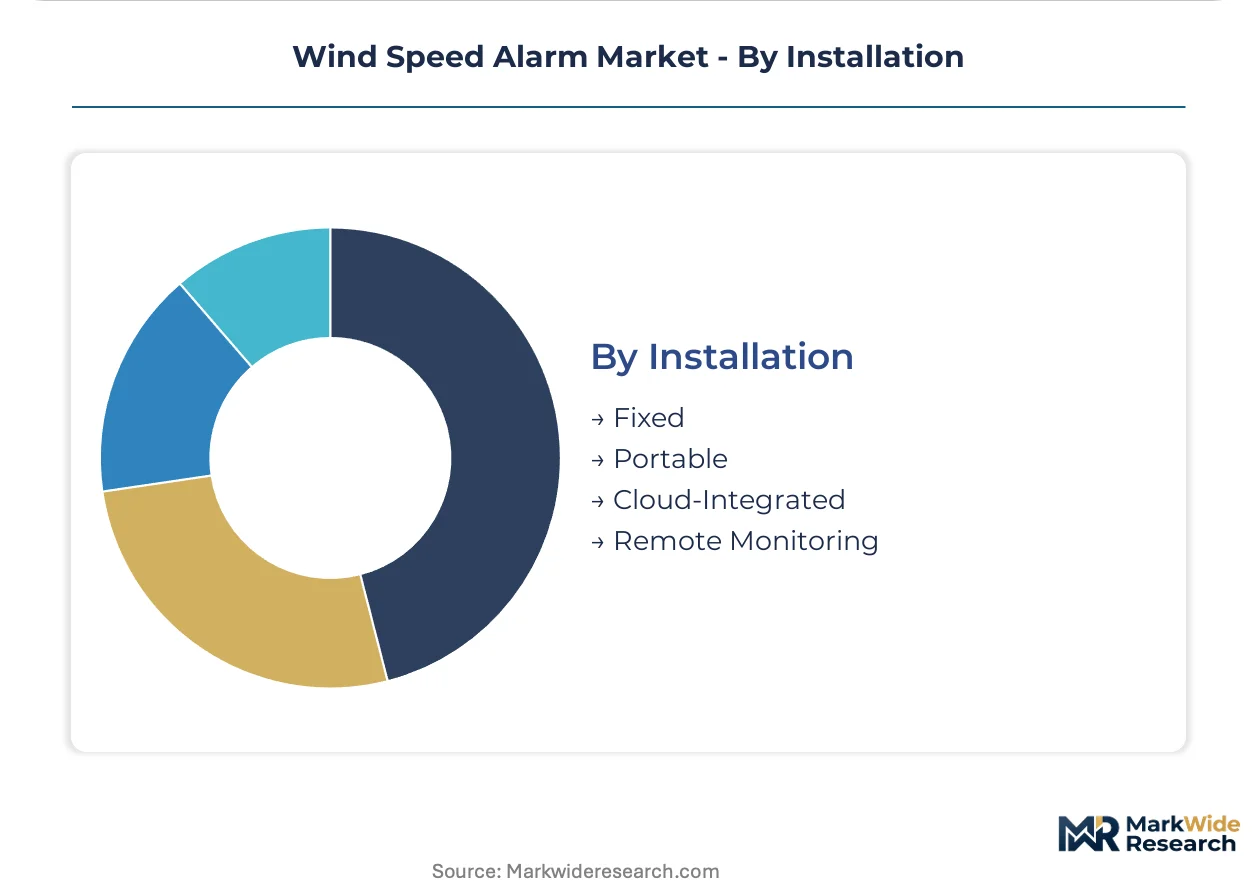
Installation:
Deployment mode shapes total cost of ownership through cabling infrastructure, calibration access, and cybersecurity architecture requirements.
- Fixed:Permanent hardwired installations deliver continuous reliability for aviation and meteorological stations where downtime is non-negotiable. FAA instrument landing systems mandate these for primary runway anemometer positions.
- Remote Monitoring:Cellular or satellite-linked sensors enable centralized oversight of distributed construction crane fleets and agricultural stations without field technician dispatch.
- Portable:Battery-powered units support temporary construction site monitoring and emergency response deployment where permanent infrastructure is impractical.
- Cloud-Integrated:Direct API connectivity to meteorological data services and turbine SCADA platforms streamlines multi-site portfolio management for offshore wind operators.
Fixed installations dominate cumulative deployed base, with remote monitoring configurations expanding most quickly as distributed renewable portfolios proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Sea offshore wind clusters dominate procurement volumes as turbine protection mandates tighten under IEC 61400 standards across European lease areas.
Germany
Offshore developers in the Baltic Sea and North Sea mandate redundant nacelle-mounted velocity sensors for grid connection compliance. The country's Federal Maritime and Hydrographic Agency enforces turbine safety certification as a condition for operational permits. Bremerhaven and Cuxhaven anchor manufacturing and service hub activity for sensor calibration and deployment logistics.
United Kingdom
Dogger Bank and Hornsea wind zones drive demand for wireless telemetry systems that eliminate submarine cabling costs. The Crown Estate lease conditions require certified wind speed alarms under Health and Safety Executive guidelines. Grimsby and Hull concentrate installation and maintenance operations for Round 4 and 5 offshore developments.
Denmark
Kriegers Flak and Thor offshore zones accelerate solid-state sensor deployment through sensor-as-a-service contracting models. The Danish Energy Agency mandates IEC 61400-12-1 certified instruments for feed-in tariff eligibility. Esbjerg functions as the primary North Sea logistics and equipment staging port for regional developers.
United States
Atlantic Coast offshore lease areas from Massachusetts to Virginia trigger demand for FAA-compliant anemometers alongside turbine protection systems. OSHA crane safety mandates drive retrofit installations across construction projects exceeding height thresholds. Houston and New Orleans anchor Gulf Coast supply chain and calibration service operations.
India
Gulf of Khambhat and Gulf of Mannar pre-development activity creates positioning opportunities for turbine protection suppliers ahead of commercial operation dates. The Ministry of New and Renewable Energy drafts offshore wind safety standards aligned with IEC frameworks. Gujarat and Tamil Nadu concentrate port infrastructure and fabrication yard capacity for emerging lease auctions.
Wind Speed Alarm Market Competitive Landscape
Global majors compete with regional champions across certification depth and service network density, producing a tiered structure where meteorological-grade precision commands premium positioning. The vendor base separates into three strategic archetypes: precision sensor specialists with accredited calibration capabilities, industrial instrumentation generalists serving construction and agriculture verticals, and integrated platform providers bundling hardware with predictive analytics. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers seek wind tunnel accreditation and offshore service coverage.
Among precision instrumentation specialists, Vaisala and Campbell Scientific exemplify the premium-tier archetype through deep calibration protocols and extreme-climate deployment expertise. PCE Deutschland GmbH occupies a position within the industrial-grade segment, representing European manufacturing presence for cost-sensitive construction applications. These three anchors illustrate how competitive positioning stratifies across certification grade rather than geographic origin alone.
| Leading Market Players |
|---|
| Vaisala |
| Gill Instruments |
| Campbell Scientific |
| PCE Deutschland GmbH |
| Comptus |
| Maximum Weather Instruments |
| Belfort Instrument |
| Scarlet Tech |
| Davis Instruments |
| Others |
Value Network & Pricing Analysis
Silicon photonics manufacturing migration from mechanical assembly to semiconductor foundry processes is collapsing unit economics while concentrating production among Asian optical chip fabricators, simultaneously enabling cost-down trajectories and creating single-source vulnerability for European and North American alarm system integrators.
Pricing Analysis
Input-cost pass-through from specialized optical component sourcing is reshaping tier boundaries across the wind speed alarm market. Three-tier pricing structure across meteorological-grade, industrial-certified, and economy-level hardware reflects certification depth and calibration protocol intensity. Cost compression in construction-grade cup anemometers is intensifying because Asian mechanical sensor manufacturers are absorbing margin erosion to maintain volume share. Renewable energy developers exhibit lowest price sensitivity due to turbine protection compliance mandates, while agricultural irrigation operators drive hardest bargain negotiations.
Supply Chain Analysis
Domestic-content mandates in India's offshore wind pre-development zones are forcing turbine protection suppliers to establish local assembly partnerships ahead of commercial lease auctions, fragmenting previously centralized procurement channels. Component fabrication concentrates in Germany, China, and Taiwan for optical MEMS dies, precision cup assemblies, and wireless telemetry modules. Supply chains draw from silicon photonics wafers, ultrasonic transducer ceramics, and marine-grade enclosure materials. Single-source vulnerability in Asian foundry capacity for optical interferometry chips exposes lead time volatility. Distribution runs through offshore wind EPC contractors, regional aviation instrumentation distributors, and direct sensor-as-a-service platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through solid-state sensor premiumization and sensor-as-a-service recurring revenue models that capture calibration and predictive maintenance value over hardware depreciation cycles.
For Market Incumbents: Deploy captive wind tunnel accreditation investments to lock out competitors from IEC 61400-12-1 certification pathways. Consolidate multi-parameter sensor platforms under unified hazard-detection architectures to preempt procurement consolidation by offshore wind operators. Defend against silicon photonics commoditization through deep calibration protocol differentiation and extreme-climate deployment expertise. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Indian offshore wind pre-development zones offers white-space positioning ahead of commercial operation dates. Target construction crane retrofit markets under OSHA enforcement timelines where certification requirements remain less stringent than aviation or renewable energy verticals. Pursue sensor-as-a-service contracting models to bypass capital procurement cycles and establish recurring revenue foundations. For Investors and Strategic Acquirers: Valuations sit cheapest among industrial-grade instrumentation generalists lacking accredited calibration infrastructure but possessing established manufacturing footprints. Five-to-ten-year viability favors precision sensor specialists with meteorological-grade certification depth and captive service network density. Watch for IEC 61400 edition updates mandating solid-state measurement as inflection signal for mechanical anemometer obsolescence cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Wind Tunnel Accreditation Investment | Captive calibration infrastructure locks IEC 61400-12-1 certification pathways against competitor entry. |
| Sensor-as-a-Service Platform Launch | Recurring revenue bundling hardware, calibration, and analytics displaces capital purchase models among Danish developers. |
| Optical MEMS Manufacturing Partnership | Semiconductor foundry access secures silicon photonics supply for solid-state turbine protection systems. |
| Multi-Parameter Sensor Integration | Unified hazard-detection architectures compress procurement cycles for North Sea offshore wind operators. |
| India Local Assembly Establishment | Domestic-content compliance positions suppliers for Gulf of Khambhat lease auction awards. |
Research Methodology
Multiple input streams — primary interviews with offshore wind project developers, aviation instrumentation procurement officers, and meteorological calibration technicians; secondary validation through IEC standard documentation, FAA instrument landing system specifications, and EPC contractor equipment procurement databases; plus customs trade records for anemometer component flows — were reconciled through bottom-up installation forecasting and top-down market sizing triangulation.
Historical deployment trajectories across Germany, the United Kingdom, and Denmark were cross-referenced against panel input from sensor manufacturers and wind farm operators to anchor growth assumptions over the projection horizon. Segmentation modeling spanned measurement technology architecture, certification grade tier, end-use vertical, and installation mode. CAGRs were derived from installed base replacement cycles, regulatory mandate timelines, and wireless telemetry adoption curves specific to offshore wind array configurations.
Caveats apply where IEC 61400 standard revision timing, Asian foundry capacity constraints, or Indian offshore wind auction delays could materially shift the outlook. Forecasts reflect documented assumptions regarding turbine protection mandate enforcement consistency and solid-state sensor cost-down trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Power Market
Wind Energy Systems
India Wind Industry Market
Wind Energy Systems
Wind Turbine Blades Market
Wind Energy Systems
Wind Blades NDT Market
Wind Energy Systems
Global Wind Power Coatings Market
Wind Energy Systems
Denmark Wind Energy Market
Wind Energy Systems
Floating Wind Turbine Market
Wind Energy Systems
United States Wind Energy Market
Wind Energy Systems
Europe Direct Drive Wind Turbine Market
Wind Energy Systems
Wind Electric Power Generation Market
Wind Energy Systems
Peru Wind Energy Market
Wind Energy Systems
Wind Power Forgings Market
Wind Energy Systems
Asia-Pacific Large Wind Turbine Market
Wind Energy Systems
Offshore Wind Tower Market
Wind Energy Systems
Middle-East and Africa Wind Power Market
Wind Energy Systems
Sweden Wind Power Market