
 Multi-Rotor Wind Turbine Market | 2026-2036
Multi-Rotor Wind Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Rotor Wind Turbine Market Foresight
Offshore procurement channels is tilting toward multi-rotor configurations as developers seek higher capacity density per foundation. Siemens Gamesa leverages its offshore manufacturing footprint to anchor supply commitments across European lease rounds. GE Renewable Energy competes through direct-drive technology leadership in the high-wattage offshore segment. Xinjiang Goldwind Science & Technology extends its position in onshore multi-rotor pilot installations across Asia-Pacific markets.
Multi-rotor wind turbines integrate multiple rotor assemblies on a single support structure, typically achieving rated capacities between 2 MW and 15 MW per unit with rotor diameters spanning 80 to 220 meters depending on configuration. The design maximizes swept area per foundation footprint, reducing levelized cost of energy for offshore and constrained-land applications. Horizontal axis configurations dominate installed base due to mature aerodynamic efficiency and established supply chains for blade manufacturing. Variable pitch technology leads growth trajectories as grid codes tighten frequency response requirements across utility-scale deployments. Gearbox-based drivetrains retain margin concentration in retrofit markets where operators prioritize proven maintenance protocols over direct-drive capital premiums.
The EU Green Deal and F-Gas Regulation constrain refrigerant choices in turbine transformer cooling systems, while IEC 61400 offshore design standards govern structural certification for multi-rotor load cases. BOEM lease stipulations in United States federal waters increasingly specify wake mitigation and radar interference parameters that multi-rotor layouts must satisfy. Stakeholders must monitor evolving grid interconnection standards in Denmark and Germany where multi-rotor clusters face harmonic resonance scrutiny during commissioning protocols.
Market Dynamics
Offshore foundation economics are forcing capacity density per square kilometer upward as lease costs escalate and wake losses from traditional spacing constrain project returns. Developers now optimize array layouts around multi-rotor units that multiply swept area without multiplying seabed footprint or electrical infrastructure.
Growth Catalysts
- EU Green Deal streamlining:Accelerated environmental permitting under revised offshore frameworks in Danish and German waters compresses development timelines for novel turbine configurations.
- Wake mitigation mandates:BOEM lease stipulations in United States federal waters now require demonstrated wake reduction, favoring multi-rotor layouts with tighter spacing algorithms.
- Transformer cooling refrigerant phase-outs:F-Gas Regulation constraints on sulfur hexafluoride and hydrofluorocarbon alternatives drive demand for redesigned thermal management systems compatible with multi-rotor electrical architectures.
Market Restraints
- Foundation load complexity:Multi-rotor dynamic loading patterns exceed standard monopile fatigue assumptions, requiring bespoke structural certification that extends engineering cycles.
- Blade supply concentration:Carbon fiber preform manufacturing clusters in China and Spain create input vulnerability for the extended blade sets multi-rotor configurations demand.
- Harmonic resonance risk:IEC 61400 offshore design standards impose stringent grid interconnection testing that multi-rotor clusters struggle to satisfy during commissioning protocols.
Strategic Opportunities
- Japanese offshore expansion:METI feed-in tariff revisions and newly designated general sea areas create first-mover positioning for floating multi-rotor pilots in depths exceeding 50 meters.
- Direct-drive convergence:Permanent magnet generator technology from onshore turbines is migrating offshore, enabling simplified drivetrains that reduce nacelle mass per rotor in multi-rotor assemblies.
- Radar interference mitigation:Military aviation authorities in the United Kingdom and Germany are procuring stealth-compatible blade coatings, opening premium service contracts for multi-rotor operators near defense installations.
Industry Challenges
- Composite repair technician scarcity:Multi-rotor blade counts multiply damage probability while certified repair crews remain concentrated at original equipment manufacturer facilities.
- Load case certification delays:DNV and Lloyd's Register lack standardized frameworks for simultaneous multi-rotor extreme event modeling, forcing project-specific engineering assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Rotor Wind Turbine Market |
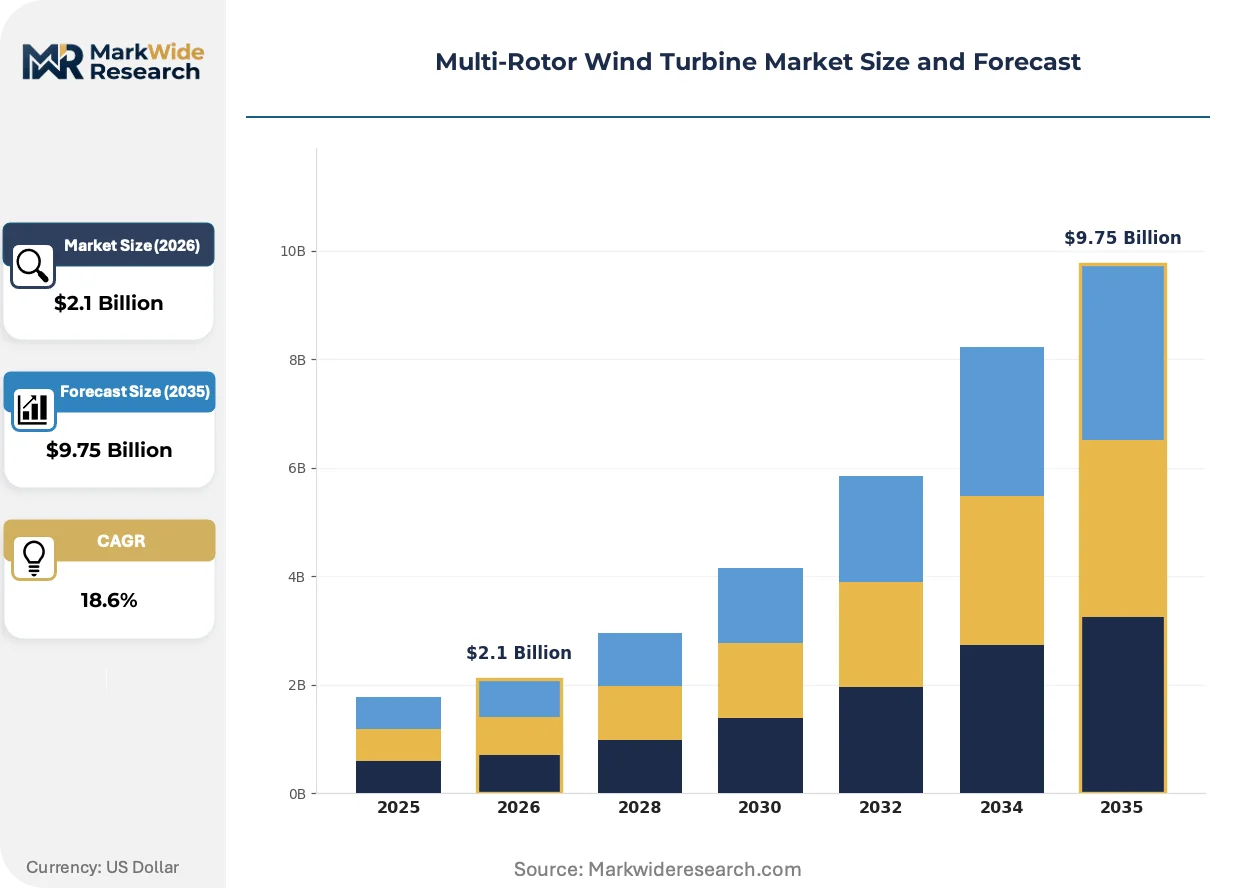
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $9.75 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Axis, Vertical Axis, Offshore, Onshore Technology: Fixed Pitch, Variable Pitch, Direct Drive, Gearbox Application: Residential, Commercial, Industrial, Utility Scale End User: Energy Producers, Government Agencies, Private Developers, Research Institutions |
| Companies Covered | Siemens Gamesa, MHI Vestas Offshore Wind, GE Renewable Energy, Enercon GmbH, Nordex SE, Xinjiang Goldwind Science & Technology, Sinovel Wind Group, Suzlon Energy Limited, Fortis Wind Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Rotor Wind Turbine Market Shifts & Advancements
Digital twin architectures are compressing design-validation cycles for novel turbine configurations. Simulation fidelity improvements now permit aerodynamic load prediction without full-scale prototype deployment.
Blade-mounted lidar systems are virtualizing wake characterization in operational arrays. Offshore developers in the North Sea basin deploy these sensors across multi-rotor test beds to validate spacing optimization algorithms before commercial scaling. Real-time data feeds are displacing static wake models in foundation design specifications.
EU F-Gas Regulation amendments now mandate refrigerant global warming potential thresholds below 750 for transformer cooling circuits. Turbine manufacturers in Denmark and Germany are retrofitting thermal management architectures to accommodate CO2 or hydrofluoroolefin alternatives. Offshore multi-rotor platforms face disproportionate compliance burden due to centralized transformer vaults serving multiple generators.
Utility procurement departments are unbundling operations and maintenance contracts from turbine supply agreements. Danish and German offshore lease holders now tender multi-rotor fleets under separate performance-based service tiers. Independent service providers with specialized climbing systems for multi-nacelle structures are capturing aftermarket share previously held by original equipment manufacturers.
Multi-Rotor Wind Turbine Market Segmentation
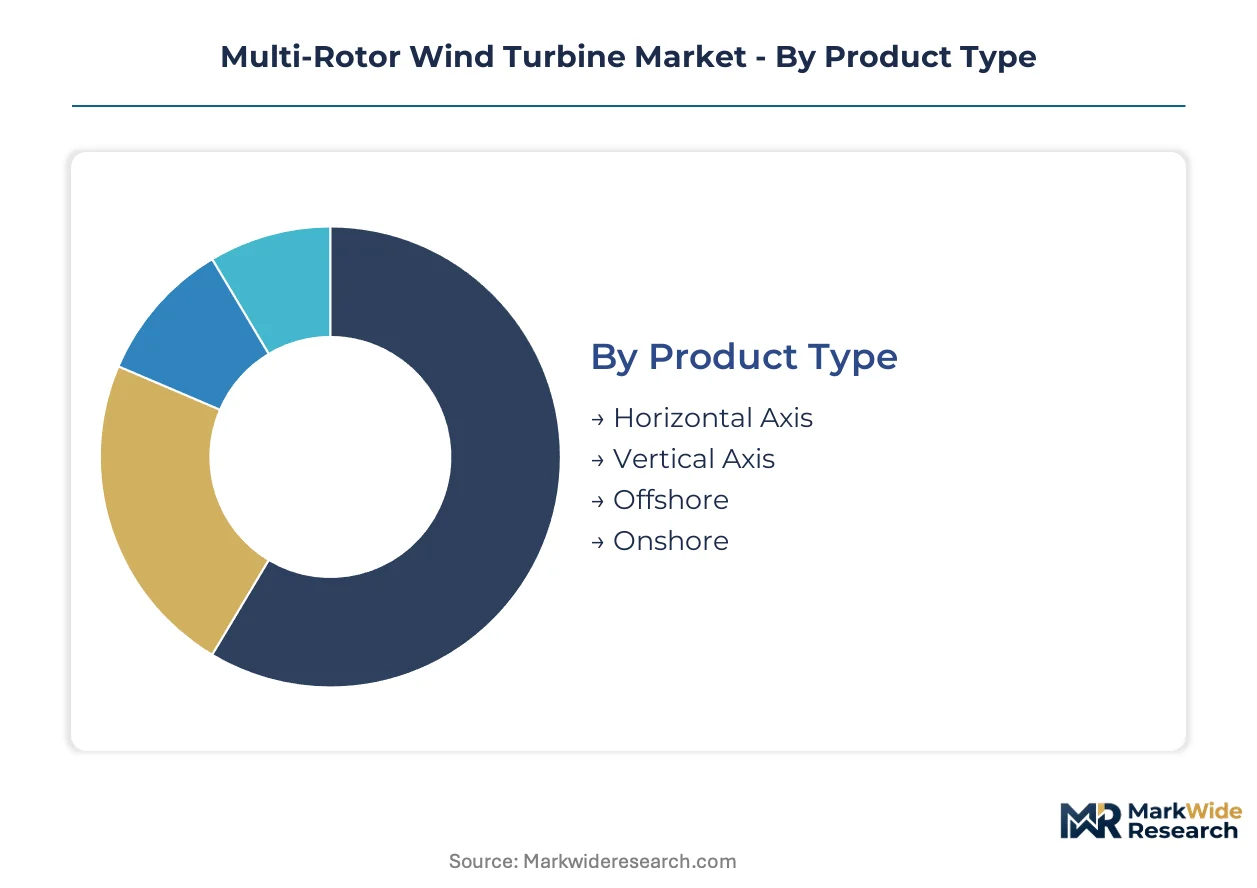
Multi-rotor turbine configurations diverge sharply across installation environments and grid-connection requirements. Each segment carries distinct certification burdens, foundation economics, and O&M protocols that reshape procurement decisions for developers and utilities.
Product Type:
Horizontal axis designs anchor offshore installations where swept area efficiency determines foundation ROI, while vertical axis pilots address urban noise and vibration constraints.
- Horizontal Axis:Dominant aerodynamic configuration employs two or three rotors atop a single support structure, with blade lengths reaching 110 meters per rotor in North Sea deployments. Danish and German utility-scale developers specify these units for lease rounds where wake mitigation algorithms justify tighter array spacing. Established volume favors Horizontal Axis; emerging adoption favors Vertical Axis.
- Vertical Axis:Darrieus and Savonius derivatives rotate around a central vertical shaft, eliminating yaw mechanisms and reducing nacelle complexity for distributed generation. Japanese floating pilot programs in depths exceeding 50 meters test these configurations where gyroscopic stability simplifies platform design.
- Offshore:Salt-rated electrical architectures and corrosion-resistant transformer vaults serve multiple generators from centralized foundation footprints. BOEM lease stipulations in United States federal waters mandate radar interference mitigation for these installations near coastal defense installations.
- Onshore:Constrained-land deployments in Asia-Pacific markets utilize multi-rotor density to maximize output per easement acre, particularly where agricultural co-use restricts tower spacing.
Foundation load complexity tilts procurement toward Horizontal Axis for deep-water leases; land-use restrictions sustain Onshore demand in agricultural regions.
Technology:
Power conversion architectures separate retrofit markets seeking maintenance familiarity from greenfield projects prioritizing nacelle mass reduction.
- Variable Pitch:Individual blade angle control enables real-time aerodynamic braking and frequency response compliance under tightening grid codes. German network operators require these systems for offshore clusters facing harmonic resonance scrutiny during commissioning protocols. Variable Pitch captures the steepest expansion trajectory as grid codes tighten; Fixed Pitch retains residual share in remote microgrid installations.
- Direct Drive:Permanent magnet generators eliminate gearbox maintenance burdens, reducing nacelle mass per rotor in floating multi-rotor assemblies. Siemens Gamesa and GE Renewable Energy deploy these architectures in high-wattage offshore segments.
- Fixed Pitch:Simplified mechanical design with stall-regulated power curves suits small-scale residential and commercial installations where control system cost outweighs efficiency gains.
- Gearbox:Multi-stage planetary and helical gear systems concentrate maintenance expertise at OEM facilities, creating aftermarket lock-in for utility fleets with established service contracts.
Gearbox retrofits dominate existing fleet extensions; Direct Drive claims newbuild preference in floating and ultra-high-capacity segments.
Application:
Scale thresholds determine whether multi-rotor economics justify bespoke foundation engineering or modular deployment.
- Utility Scale:Arrays exceeding 50 MW aggregate capacity employ multi-rotor units to compress electrical infrastructure costs per megawatt-hour. North Sea basin developers in Danish, German, and Dutch territorial waters optimize these configurations around wake reduction mandates.
- Industrial:Captive power for manufacturing campuses leverages multi-rotor density to meet baseload demands without expanding land footprints. EU Green Deal accelerated permitting streamlines these installations for energy-intensive sectors.
- Commercial:Mid-sized deployments for data centers and logistics facilities balance capacity density against interconnection voltage limitations at distribution-level substations.
- Residential:Small multi-rotor pilots address estate-scale generation where single-turbine visual impact faces local zoning opposition.
Utility Scale commands foundation engineering investment; Commercial applications climb fastest as C&I procurement unbundles from utility supply agreements.
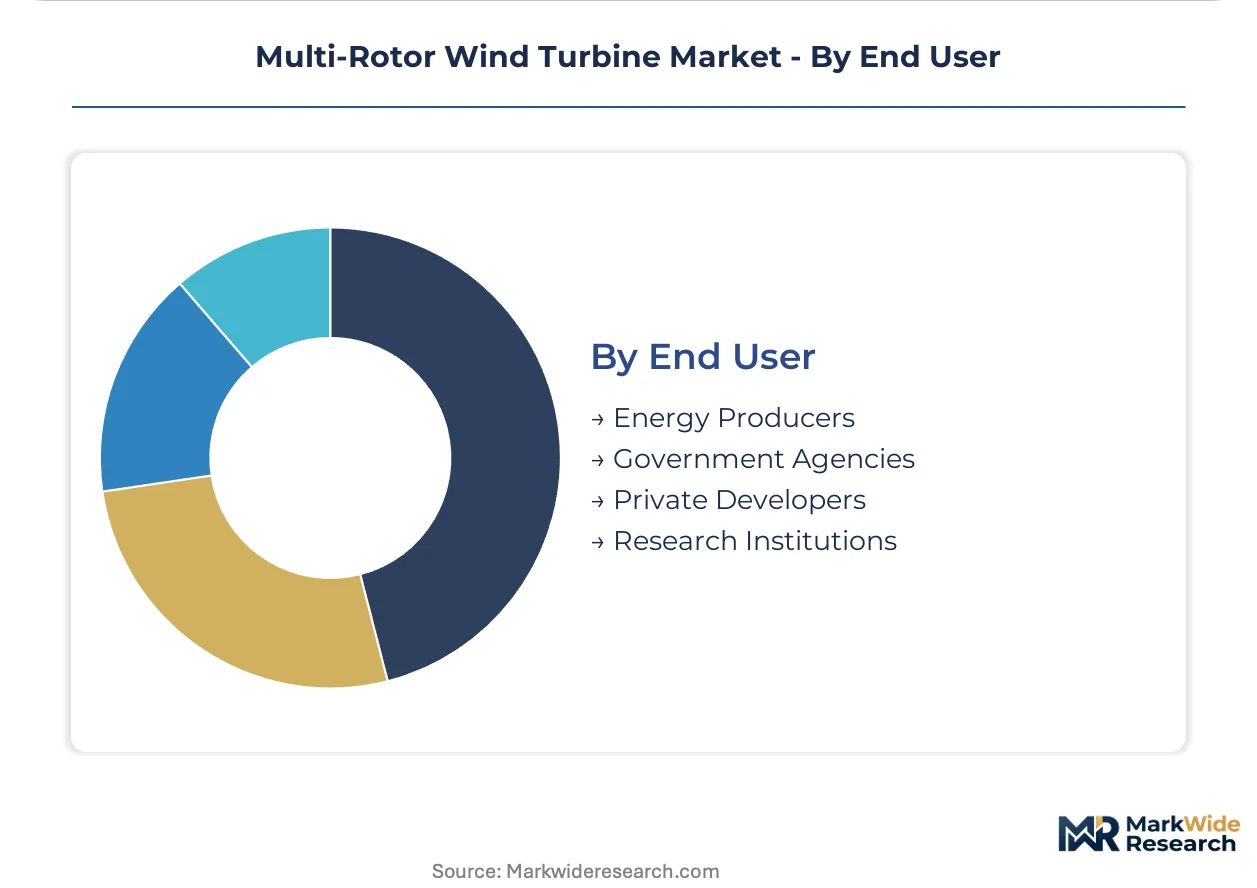
End User:
Procurement sophistication varies from regulated lease auctions to experimental research programs testing novel load cases.
- Energy Producers:Orsted, RWE, and Equinor tender multi-rotor fleets under performance-based service tiers, unbundling O&M from turbine supply agreements. These entities drive standardization pressure on IEC 61400 offshore certification frameworks.
- Private Developers:Independent project sponsors navigate BOEM lease rounds and EU auction mechanisms, bearing front-loaded development risk for novel configurations lacking operational track records.
- Government Agencies:Military aviation authorities in the United Kingdom and Germany procure stealth-compatible blade coatings, creating premium service contracts for installations near defense installations.
- Research Institutions:Technical universities and national laboratories validate wake models and digital twin architectures at reduced scale before commercial deployment.
Energy Producers consolidate procurement volume; Research Institutions generate the intellectual property that de-risks subsequent commercial adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Danish offshore lease premiums command three times the installation economics of Spanish onshore corridors, creating stark deployment incentives across European waters. German North Sea bidding rounds absorb capital commitments that Mediterranean markets cannot match. This pricing-power asymmetry concentrates multi-rotor innovation in high-tariff jurisdictions while southern European adoption lags on merchant price exposure.
United States
BOEM lease stipulations now mandate wake mitigation demonstrations for Gulf of Maine and California floating developments. The Inflation Reduction Act production tax credits de-risk first-of-kind multi-rotor arrays in federal waters. Massachusetts and New York offtake agreements anchor Atlantic Coast procurement clusters where transmission queue reforms accelerate interconnection timelines.
Germany
Network operators in the North Sea basin impose harmonic resonance testing that multi-rotor clusters must satisfy before grid synchronization. The EU Green Deal streamlined permitting compresses development cycles for Borkum Riffgrund and Heligoland lease extensions. Bremerhaven manufacturing corridors host blade preform facilities supplying Danish and Dutch territorial developments.
Denmark
Ørsted and Copenhagen Infrastructure Partners tender multi-rotor fleets under performance-based service tiers unbundled from turbine supply agreements. National energy agency reforms eliminated double-permitting requirements for demonstration projects in Danish territorial waters. Esbjerg port infrastructure handles heavy-lift components for floating pilot programs testing multi-rotor load cases.
China
Xinjiang Goldwind Science & Technology extends manufacturing footprints across coastal provinces for offshore multi-rotor pilot installations. Dual carbon goals under MEE guidance accelerate utility-scale procurement in Jiangsu and Guangdong lease rounds. Yangtze River Delta fabrication clusters produce extended blade sets for domestic and Asia-Pacific export markets.
Japan
METI feed-in tariff revisions designate general sea areas beyond 50-meter depths for floating multi-rotor demonstrations. Port infrastructure constraints in Nagasaki and Akita prefectures limit component import scale for novel configurations. Chubu Electric and JERA anchor procurement consortia testing gyroscopic stability in multi-rotor floating platforms.
Multi-Rotor Wind Turbine Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on blade preform and generator subsystems. Market structure tilts toward consolidated offshore supply where Siemens Gamesa and MHI Vestas anchor procurement commitments across European lease rounds. Three archetypes dominate: full-system OEMs with offshore manufacturing footprints, drivetrain technology licensors, and blade preform specialists concentrated in carbon fiber clusters. Competitive moves center on unbundled O&M service tiers and direct-drive technology migration from onshore to offshore architectures.
Among European-based full-system integrators, Siemens Gamesa and Enercon GmbH occupy positions exemplifying divergent technology philosophies across gearbox and direct-drive architectures. GE Renewable Energy represents the North American premium-tier entrant competing through high-wattage offshore segment focus. Xinjiang Goldwind Science & Technology anchors Chinese manufacturing scale for Asia-Pacific pilot deployment programs.
| Leading Market Players |
|---|
| Siemens Gamesa |
| MHI Vestas Offshore Wind |
| GE Renewable Energy |
| Enercon GmbH |
| Nordex SE |
| Xinjiang Goldwind Science & Technology |
| Sinovel Wind Group |
| Suzlon Energy Limited |
| Fortis Wind Energy |
| Others |
Supply & Pricing Matrix
Yangtze River Delta fabrication clusters anchor carbon fiber preform capacity for extended blade sets, translating upstream concentration into asymmetric pricing power for multi-rotor configurations demanding 110-meter-plus rotor diameters. Blade supply tightness in European markets amplifies configured-to-order premiums against standard catalog offerings.
Pricing Analysis
Configured-to-order premiums for multi-rotor arrays run 15-25 percent above standard horizontal-axis units due to bespoke foundation engineering and simultaneous load-case certification. Price differentiation hinges on IEC 61400 offshore certification tier and wake mitigation algorithm complexity specified in BOEM lease stipulations. Cost compression in the onshore segment intensifies as Xinjiang Goldwind and domestic Chinese manufacturers scale standardized multi-rotor platforms for agricultural co-use deployments. Utility-scale energy producers in Denmark and Germany exhibit lowest price sensitivity given lease cost absorption through production tax credit structures, while commercial and industrial offtakers in Asia-Pacific markets negotiate aggressively on per-megawatt-hour service tiers.
Supply Chain Analysis
Carbon fiber feedstock draws from Chinese, Spanish, and Japanese precursor manufacturing clusters, with epoxy resin systems concentrated in German and South Korean chemical corridors. Multi-rotor assemblies rest on rare-earth permanent magnet supply from Chinese separation facilities and electrical steel laminations sourced from Japanese and Indian rolling mills. Single-source vulnerability concentrates in carbon fiber preform autoclave capacity, where Yangtze River Delta and Basque Country facilities serve overlapping demand pools. Distribution runs through Bremerhaven and Esbjerg heavy-lift port infrastructure for North Sea basin deployments, with modular component staging at Nagasaki and Guangdong harbors for Asia-Pacific floating pilot programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-rotor wind turbine adoption sits in early-cycle expansion as EU Green Deal streamlining and BOEM wake mitigation mandates compress development timelines for novel configurations below traditional monopile project horizons.
For Market Incumbents: Pre-empt direct-drive technology migration by securing permanent magnet generator supply agreements before rare-earth processing capacity tightens under Chinese export license reforms. Anchor Bremerhaven or Esbjerg manufacturing footprints to capture Danish and German utility-scale procurement volume as lease rounds accelerate. Defend against independent service providers by unbundling performance-based O&M contracts with proprietary climbing systems for multi-nacelle structures. For New Entrants and Emerging Players: Pursue Japanese floating multi-rotor demonstrations in METI-designated general sea areas beyond 50-meter depths, where gyroscopic stability requirements favor simplified vertical-axis configurations lacking incumbent patent density. Target commercial and industrial captive power segments in EU Green Deal accelerated permitting corridors for energy-intensive manufacturing campuses. Lead with blade-mounted lidar integration as a differentiated wake characterization service layer. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-technology convergence play because multi-rotor architectures compress electrical infrastructure costs per megawatt-hour while digitizing array optimization through real-time sensor feeds. Acquisition targets cluster around blade preform specialists with carbon fiber autoclave capacity and independent service providers with multi-nacelle climbing system certifications. Signal to monitor: BOEM lease round participation rates for floating multi-rotor configurations versus fixed-bottom monopile bids.| Strategic Initiative | Industry Significance |
|---|---|
| Wake Mitigation Technology Licensing | BOEM lease stipulations now mandate demonstrated wake reduction algorithms for Gulf of Maine developments. |
| Direct-Drive Generator Manufacturing Scale-Up | Permanent magnet technology migration from onshore to offshore reduces nacelle mass per rotor in floating assemblies. |
| Carbon Fiber Blade Preform Capacity Expansion | Yangtze River Delta and Basque Country autoclave bottlenecks constrain extended blade set availability for multi-rotor configurations. |
| Performance-Based O&M Service Tier Unbundling | Danish and German offshore lease holders now tender multi-rotor fleets under separate service agreements. |
| Floating Platform Joint Venture | Japanese METI feed-in tariff revisions designate general sea areas for gyroscopic stability pilot programs. |
Research Methodology
A spread of perspectives from utility planning officers, independent power producer project developers, EPC contractors, and grid operators converged on the working assumptions driving multi-rotor adoption curves. Primary fieldwork across Danish, German, and Japanese offshore lease round participants combined with secondary validation from EIA generation databases, IEA renewable energy reports, FERC interconnection filings, and BOEM lease stipulation documents. Bottom-up project pipeline aggregation and top-down regulatory scenario modeling triangulated volume and value estimates across the analysis window.
Demand-supply balance framing anchored the analytical approach, with segmentation modeling across horizontal versus vertical axis configurations, fixed versus floating foundation types, and utility-scale versus commercial application tiers. CAGRs derived from project development timeline compression under EU Green Deal streamlining and BOEM environmental review acceleration, cross-referenced against blade manufacturing capacity expansion schedules and rare-earth magnet supply constraints.
Sensitivities concentrate around F-Gas Regulation amendment timing for transformer cooling refrigerant thresholds, carbon fiber preform capacity allocation between aerospace and wind energy demand pools, and harmonic resonance testing protocol evolution at German network operators. Cross-checking against IEA offshore wind deployment benchmarks and national energy agency procurement announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Turbine Tower Market
Wind Energy Systems
New Zealand Wind Energy Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Control System Market
Wind Energy Systems
Global Wind Turbine Operations Market
Wind Energy Systems
Wind Power Composite Market
Wind Energy Systems
Iran Wind Energy Market
Wind Energy Systems
United States Wind Energy Market
Wind Energy Systems
South America Wind Power Market
Wind Energy Systems
Poland Wind Energy Market
Wind Energy Systems
Offshore Wind Anchoring Market
Wind Energy Systems
Greece Wind Energy Market
Wind Energy Systems
Wind Turbine Yaw and Pitch Gearbox Market
Wind Energy Systems
Wind Turbine Pitch System Sales Market
Wind Energy Systems
Wind Turbine Operation and Maintenance Market
Wind Energy Systems
Taiwan Wind Energy Market
Wind Energy Systems
Offshore Wind Power Market