
 Wind Blades NDT Market | 2026-2036
Wind Blades NDT Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Blades NDT Market Insights
China is rewriting competitive dynamics in wind blade inspection services as its offshore wind build-out accelerates along the Fujian and Guangdong coastlines. MISTRAS Group leverages its integrated platform capabilities to serve utility-scale asset owners across multiple continents. Eddyfi Technologies specializes in advanced ultrasonic phased array systems for composite defect detection. SkySpecs dominates automated drone-based blade surveys, reducing turbine downtime for maintenance providers.
Wind blades NDT encompasses non-destructive evaluation techniques applied to fiber-reinforced polymer composite structures, typically employing frequencies between 0.5 and 15 MHz for ultrasonic flaw detection in glass and carbon fiber laminates up to 150 mm thick. These methods identify delamination, voids, and fatigue cracks without compromising blade structural integrity, enabling predictive maintenance decisions that extend operational life beyond 25 years. Automated drone inspection systems represent the fastest-growing technology segment as asset owners prioritize throughput and technician safety over manual rope-access methods. Ultrasonic testing anchors the inspection type category due to its established reliability for subsurface defect characterization in thick composite sections. OEMs occupy the most concentrated end-user margin pool, though maintenance providers are expanding share as installed turbine fleets age beyond warranty periods.
The EU Green Deal and REACH framework mandate stricter material traceability and environmental compliance for wind turbine components entering European markets. DNV classification standards and ISO 17020 accreditation requirements shape service provider qualification thresholds, directly influencing procurement criteria for offshore wind developers. FORCE Technology and SGS navigate these evolving certification landscapes through accredited laboratory networks in Northern Europe. Stakeholders must monitor how national renewable energy auctions integrate inspection clause mandates into power purchase agreements.
Market Dynamics
Automated drone inspection systems are compressing turnaround times for offshore blade surveys while EU Green Deal certification mandates force asset owners to document defect histories across 25-year operational lifespans. This dual pressure is restructuring service provider qualifications and procurement criteria.
Growth Catalysts
- EU Green Deal mandates:The framework's renewable energy targets tighten certification requirements for turbine components entering European markets, forcing asset owners to adopt formalized inspection protocols.
- Offshore wind farm expansion:North Sea cluster development in Germany drives concentrated demand for blade inspection services as utility-scale operators multiply turbine deployments.
- Phased array ultrasonics:Advanced ultrasonic systems enable subsurface defect characterization in thick composite sections up to 150 mm, extending predictive maintenance capabilities.
Market Restraints
- Carbon fiber supply concentration:Raw material sourcing for blade manufacturing clusters in specific supplier geographies, exposing inspection service providers to input cost volatility.
- ISO 17020 accreditation barriers:DNV classification standards and laboratory accreditation requirements create qualification thresholds that limit new entrant participation in offshore procurement.
- Rope-access technician dependency:Manual inspection methods persist for complex damage verification, constraining throughput scalability despite automation advances.
Strategic Opportunities
- Fujian and Guangdong coastlines:China's offshore wind build-out creates underpenetrated demand for inspection services as domestic fleet scale accelerates.
- Drone-AI convergence:Automated aerial platforms integrating machine vision analytics compress survey duration while improving defect detection consistency.
- REACH framework tailwinds:Material traceability requirements for European market entry incentivize inspection data monetization and compliance documentation services.
Industry Challenges
- Composite NDT technician scarcity:Specialized expertise in ultrasonic phased array interpretation for fiber-reinforced polymer structures outpaces training pipeline output.
- Legacy turbine integration:Aging onshore fleets built to earlier design standards require inspection protocol adaptation, complicating service standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Blades NDT Market |
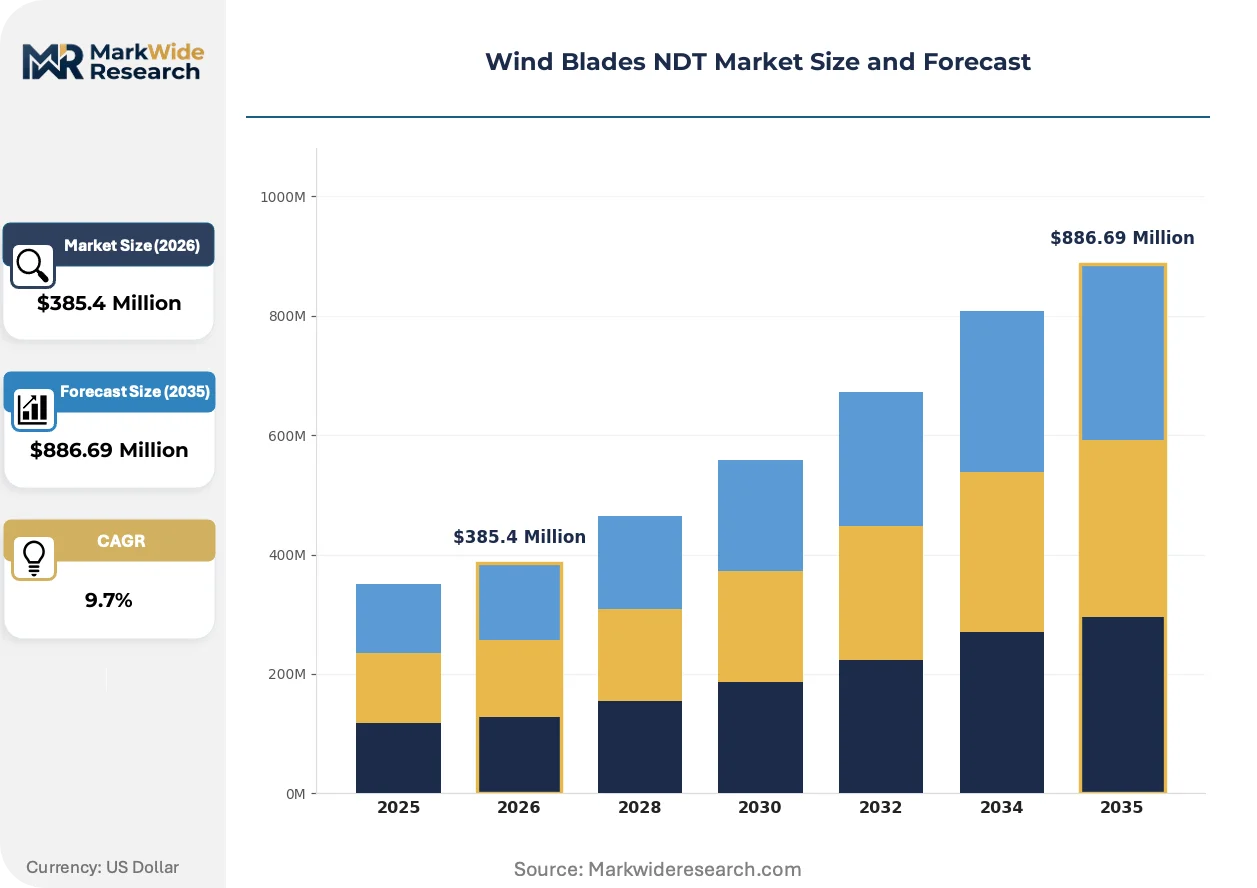
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $886.69 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Inspection Type: Ultrasonic Testing, Visual Inspection, Eddy Current Testing, Radiographic Testing End User: OEMs, Maintenance Providers, Research Institutions, Asset Owners Application: Structural Integrity, Quality Assurance, Lifecycle Management, Risk Assessment Technology: Automated Systems, Drone Inspection, Manual Techniques, Integrated Platforms |
| Companies Covered | MISTRAS Group, Eddyfi Technologies, SkySpecs, Aerones, SGS, DNV, FORCE Technology, Bladefence, Dolphitech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Blades NDT Market Trends and Innovations
Digital inspection platforms are displacing manual documentation workflows while regulatory data requirements harden. Three developments are restructuring competitive positioning.
Phased array ultrasonic testing is virtualizing subsurface defect characterization for thick composite laminates. OEM warranty departments and independent service providers adopt these systems to reduce destructive sampling requirements. The technology is virtualizing quality assurance workflows by enabling remote expert review of inspection data without blade removal.
REACH framework amendments tighten material traceability mandates for wind turbine components entering EU markets. Industrial consequence includes mandatory defect history documentation spanning manufacturing through end-of-life decommissioning. Offshore wind developers in the North Sea region respond by embedding inspection clause mandates directly into power purchase agreements.
Asset owners now unbundle inspection services from bundled maintenance contracts, creating direct procurement relationships with specialized NDT providers. Traditional OEM service channels face disintermediation as utility-scale operators seek independent verification for aging fleet management. Germany's North Sea offshore clusters exhibit this pattern most visibly, with operators prioritizing technician safety and survey throughput over legacy supplier relationships.
Wind Blades NDT Market Segmentation
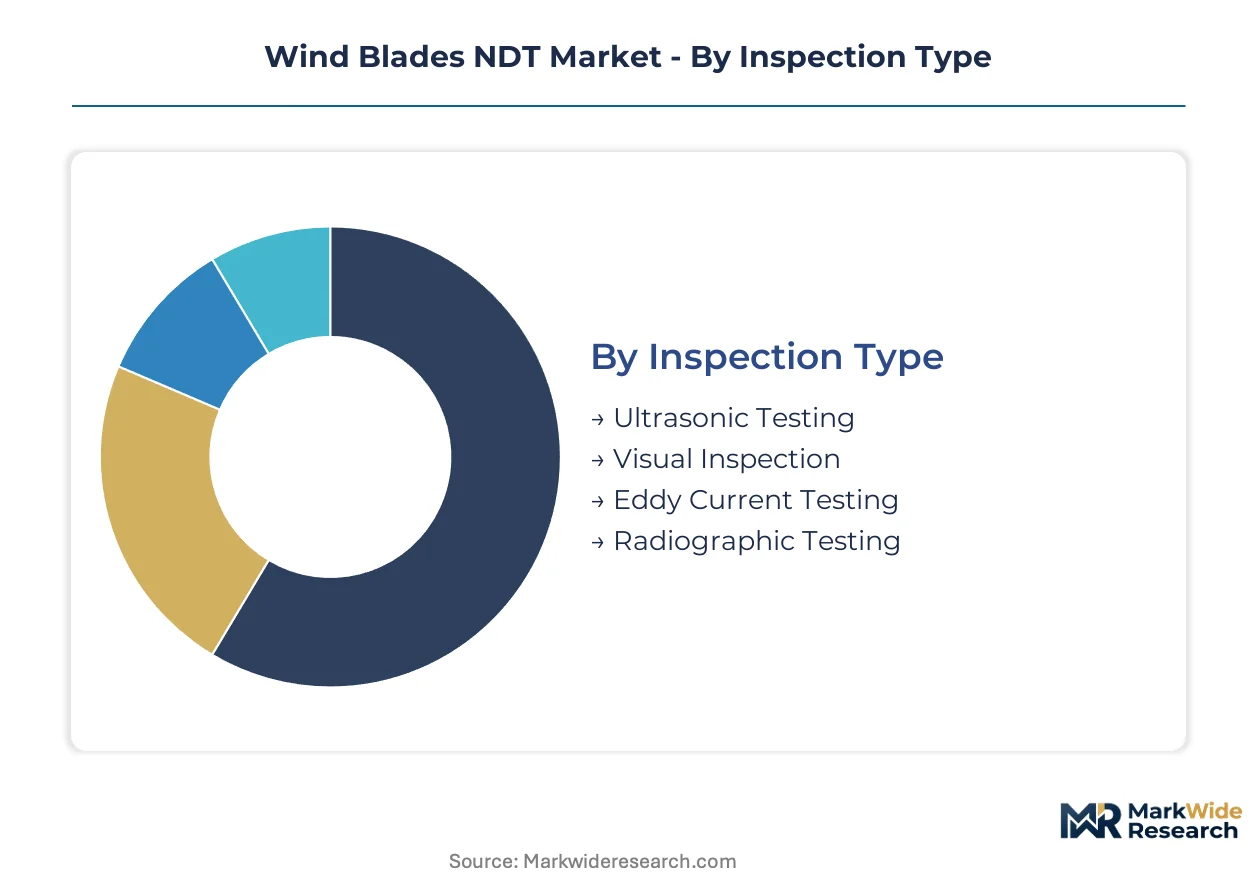
Wind blade inspection markets fragment across four critical dimensions that determine procurement patterns and margin capture. Each segmentation axis reveals distinct competitive dynamics between established protocols and emerging automation platforms reshaping service delivery economics.
Inspection Type:
Mature volumetric methods anchor current revenue while emerging electromagnetic techniques gain traction in specific defect categories.
- Ultrasonic Testing:Phased array systems operating at 0.5–15 MHz penetrate glass and carbon fiber laminates up to 150 mm thick for subsurface delamination detection. German North Sea offshore clusters deploy these systems for mandatory certification compliance under DNV standards.
- Visual Inspection:Surface-level defect identification through optical magnification and structured lighting remains the baseline protocol for routine blade surveys. Maintenance providers in aging European onshore fleets rely on visual methods for cost-effective screening before deploying advanced techniques.
- Eddy Current Testing:Electromagnetic induction methods detect near-surface cracks in metallic lightning protection systems embedded within composite structures.
- Radiographic Testing:X-ray and gamma-ray imaging provides through-thickness void characterization for manufacturing quality assurance in OEM facilities.
Ultrasonic Testing handles the majority of throughput; Drone-integrated Visual Inspection is climbing the fastest on share.
End User:
Customer type stratification reflects diverging procurement sophistication between warranty-period operators and post-warranty fleet managers.
- OEMs:Original equipment manufacturers integrate NDT protocols into manufacturing quality gates and warranty service networks. Vestas and Siemens Gamesa facilities in Denmark and Spain maintain captive inspection capabilities for new blade certification.
- Maintenance Providers:Independent service contractors deliver recurring inspection programs for utility-scale asset owners. These providers expand market presence as turbine fleets age beyond manufacturer warranty periods across Germany and the UK.
- Research Institutions:Universities and national laboratories develop next-generation defect characterization methods for composite degradation modeling.
- Asset Owners:Direct procurement from wind farm operators seeking independent verification outside OEM service channels.
OEMs retain concentrated margin pools; Maintenance Providers are expanding share most rapidly as fleet aging accelerates.
Application:
Use-case differentiation separates compliance-driven documentation from predictive analytics enabling operational life extension.
- Structural Integrity:Defect mapping for load-bearing composite sections determines repair versus replacement decisions. Offshore installations in the North Sea prioritize structural assessments due to accessibility constraints and replacement cost exposure.
- Quality Assurance:Manufacturing-stage verification ensures blade conformity to design specifications and certification requirements. REACH framework traceability mandates intensify documentation demands for EU market entry.
- Lifecycle Management:Long-term degradation tracking supports 25-plus year operational planning and end-of-life decommissioning strategies.
- Risk Assessment:Insurance and financing due diligence require standardized defect reporting for coverage and collateral valuation.
Quality Assurance commands the largest current expenditure; Lifecycle Management shows the steepest expansion trajectory as fleet aging concentrates.
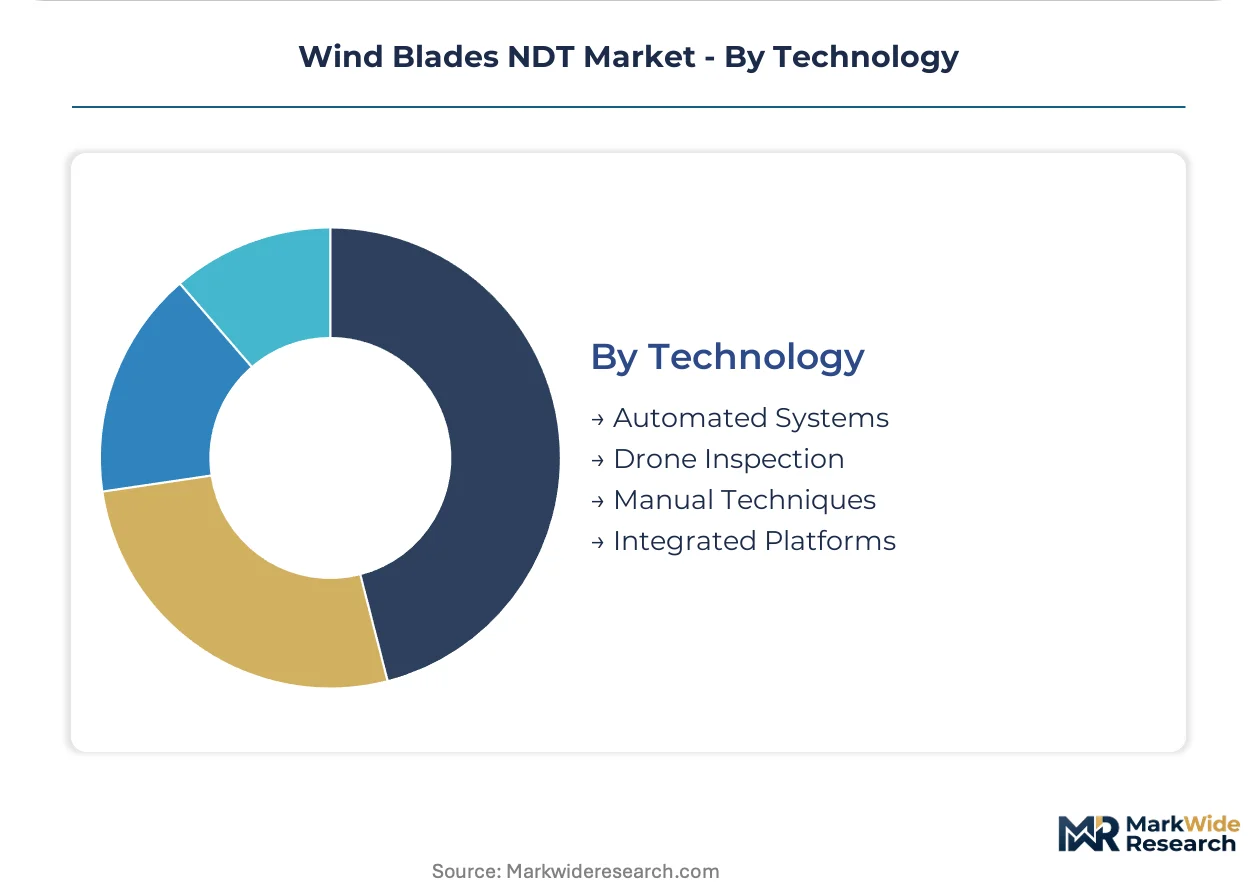
Technology:
Automation intensity divides the competitive landscape between labor-dependent legacy methods and capital-intensive platform investments.
- Automated Systems:Robotic crawlers and fixed-sensor arrays execute repeatable inspection protocols without technician exposure to hazardous heights. These systems gain preference in German offshore clusters where safety regulations restrict rope-access operations.
- Drone Inspection:Aerial platforms equipped with high-resolution cameras and thermal sensors compress survey duration from days to hours. Fujian and Guangdong coastline developments in China drive adoption for rapid fleet scaling.
- Manual Techniques:Rope-access and ground-based inspection persist for complex damage verification requiring tactile assessment.
- Integrated Platforms:Unified software systems aggregate multi-source inspection data for predictive maintenance analytics.
Drone Inspection is gaining share fastest; Automated Systems handle concentrated throughput in regulated offshore environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal anchors European demand dynamics for wind blade inspection services, with Germany's North Sea offshore clusters driving concentrated procurement volumes. National renewable energy auctions across multiple jurisdictions embed inspection mandates into power purchase agreements, reshaping service provider qualification thresholds.
Germany
North Sea offshore wind expansion concentrates demand for automated drone and ultrasonic inspection systems. The country's Federal Maritime and Hydrographic Agency enforces strict certification protocols for turbine components in marine environments. Port cities like Bremerhaven and Cuxhaven host growing service provider networks supporting utility-scale asset owners.
China
Fujian and Guangdong coastline developments accelerate domestic fleet scaling for offshore wind installations. The Ministry of Ecology and Environment's dual carbon goals tighten manufacturing compliance requirements for blade producers. Xiamen and Shenzhen industrial zones attract inspection technology providers serving state-owned utility operators.
United States
Great Plains onshore wind repowering programs and Atlantic Coast offshore lease auctions expand addressable market scope. The Federal Aviation Administration regulates commercial drone operations for blade surveys, creating operational compliance layers for service providers. Texas and Iowa maintenance hubs concentrate technician training programs for aging fleet management.
United Kingdom
Dogger Bank and Hornsea offshore zones drive specialized inspection demand for harsh marine conditions. The Health and Safety Executive mandates rope-access safety protocols that accelerate automated system adoption. Aberdeen and Grimsby port infrastructure supports vessel-based blade survey operations for North Sea clusters.
Denmark
Øresund and Kattegat strait installations require corrosion-focused inspection protocols for salt-laden environments. Danish Energy Agency certification standards influence broader European procurement criteria for blade integrity assessment. Copenhagen and Esbjerg harbor facilities anchor OEM captive service capabilities and independent provider networks.
Wind Blades NDT Market Competitive Landscape
Integrated platform providers and specialized technology developers split the market between comprehensive service delivery and focused equipment supply. The vendor base concentrates around three strategic archetypes: multinational inspection conglomerates with accredited laboratory networks, drone-automation specialists compressing survey timelines, and advanced sensor manufacturers enabling subsurface defect characterization. Dominant competitive moves include geographic expansion into offshore wind clusters and technology licensing partnerships bridging equipment and service capabilities.
Within the multinational service tier, MISTRAS Group and SGS occupy positions spanning utility-scale asset owners across multiple continents. Drone-automation specialists exemplified by SkySpecs anchor the technology-driven segment with automated aerial survey platforms. FORCE Technology represents the accredited laboratory archetype, navigating DNV classification standards through Northern European facility networks. These three company groupings illustrate how qualification thresholds and procurement unbundling reshape competitive positioning.
| Leading Market Players |
|---|
| MISTRAS Group |
| Eddyfi Technologies |
| SkySpecs |
| Aerones |
| SGS |
| DNV |
| FORCE Technology |
| Bladefence |
| Dolphitech |
| Others |
Pricing and Supply Chain Analysis
Carbon fiber supply concentration in specific supplier geographies exposes inspection service providers to input cost volatility that compresses margin tiers while forcing geographic diversification of equipment sourcing. This dual pressure widens pricing spreads between ISO 17020-accredited premium providers and unaccredited regional competitors while reshaping procurement patterns toward long-term sensor supply agreements.
Pricing Analysis
German North Sea offshore clusters command 20-35% price premiums over Chinese Fujian and Guangdong markets due to DNV certification requirements and technician safety regulations. Three-tier pricing structure across premium, standard, and economy levels separates DNV-accredited ultrasonic phased array services from visual drone surveys and unaccredited manual rope-access methods. Pricing pressure stems from drone-technology commoditization compressing aerial survey margins. Maintenance providers exhibit highest price sensitivity as they compete for utility-scale asset owner contracts, while OEM warranty departments prioritize certification compliance over unit cost.
Supply Chain Analysis
Phased array ultrasonic equipment manufacturing concentrates in Denmark, Germany, and the United States through specialized NDT sensor producers. Raw material dependencies include piezoelectric ceramics, carbon fiber composite reference standards, and high-frequency signal processing chips. Single-source vulnerability in advanced piezoelectric materials creates qualification bottlenecks for new equipment entrants. Distribution runs through accredited laboratory networks and OEM service channels, with direct procurement from asset owners accelerating for drone-based visual inspection platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in ultrasonic phased array interpretation for fiber-reinforced polymer structures outpaces training pipeline output, creating persistent capability gaps that advantage incumbents with captive technician development programs.
For Market Incumbents: Pre-empt drone-automation specialists by acquiring machine vision analytics capabilities before commoditization erodes premium positioning in visual inspection segments. Secure backward integration into carbon fiber reference standard production to insulate margins from raw material volatility. Prioritize ISO 17020 accreditation expansion into China's Fujian and Guangdong industrial zones ahead of domestic competitor qualification. For New Entrants and Emerging Players: China's Fujian and Guangdong coastline developments offer underpenetrated demand for inspection services as state-owned utility operators scale offshore fleets without established incumbent relationships. Target maintenance provider procurement unbundling from OEM channels in Germany's North Sea clusters where asset owners seek independent verification. Enter through drone-AI convergence partnerships that compress survey duration while avoiding capital-intensive ultrasonic equipment investments. For Investors and Strategic Acquirers: EU Green Deal certification mandates reshape the acquisition landscape by elevating accredited laboratory networks above equipment-only vendors in strategic value. Five-to-ten year viability favors integrated platform providers combining sensor manufacturing, data analytics, and accredited service delivery. Monitor national renewable energy auction inspection clause integration as the inflection signal for compliance-documentation service valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Drone-AI Platform Integration | Machine vision analytics from SkySpecs compress survey timelines while improving defect detection consistency for utility-scale operators. |
| Accreditation Network Expansion | ISO 17020 and DNV certification investments by FORCE Technology create procurement barriers that protect premium pricing in European offshore clusters. |
| Phased Array Ultrasonic Licensing | Eddyfi Technologies' sensor partnerships enable maintenance providers to add subsurface defect capabilities without captive R&D expenditure. |
| Geographic Expansion into China | Xiamen and Shenzhen industrial zone presence captures state-owned utility procurement as Fujian and Guangdong offshore build-out accelerates. |
| Compliance Documentation Monetization | REACH framework defect history databases create recurring revenue streams from asset owners facing 25-year operational lifespan mandates. |
Research Methodology
A standing panel of wind farm maintenance directors, NDT technician training program leads, offshore project developers, and utility-scale asset owner procurement officers provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with equipment manufacturers and service providers alongside secondary validation through DNV classification filings, EU Green Deal regulatory documentation, and national renewable energy auction records. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators for composite materials demand and offshore wind capacity deployment.
Scenario-bracketing framed projections across regulatory acceleration, technology substitution, and supply chain disruption pathways. Segmentation dimensions modeled include inspection type, end-user category, application purpose, and automation technology tier alongside regional regulatory cluster differentiation. CAGRs derived from installed fleet aging curves and offshore wind capacity pipelines rather than historical trend extrapolation. Industry-specific forecast inputs incorporated blade degradation modeling parameters and technician certification pipeline outputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese drone-automation specialists or accelerated EU Green Deal enforcement would shift outcomes materially. Quarterly review of national renewable energy auction inspection clause mandates and DNV accreditation application backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Offshore Wind Turbine Blade Leading-Edge Defect Inspection Equipment Market
Wind Energy Systems
North America Large Wind Turbine Market
Wind Energy Systems
Wind Turbine Gearbox Market
Wind Energy Systems
Wind Turbine Cables Market
Wind Energy Systems
Offshore Wind Cable Market
Wind Energy Systems
Global Wind LIDAR Market
Wind Energy Systems
Global Small Wind Power Market
Wind Energy Systems
Iran Wind Energy Market
Wind Energy Systems
Asia-Pacific Wind Power Market
Wind Energy Systems
Wind Cones Market
Wind Energy Systems
Wind Power Market
Wind Energy Systems
North America Wind Power Equipment Market
Wind Energy Systems
Vertical Axis Wind Turbine Market
Wind Energy Systems
Wind Power Composite Market
Wind Energy Systems
North America Wind Power Market
Wind Energy Systems
Wind Energy Foundation Market