
 Wind Turbine Components Market | 2026-2036
Wind Turbine Components Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Components Market Intelligence
Independent power producers are collapsing the traditional utility-dominated procurement model as merchant offtake and corporate PPAs gain favor. Vestas Wind Systems A/S anchors European blade engineering through integrated aerodynamic design centers. GE Vernova leverages its gas-turbine service infrastructure to cross-sell offshore drivetrain maintenance contracts. Siemens Gamesa Renewable Energy competes on direct-drive permanent-magnet generators that eliminate gearbox failure modes in salt-air environments.
Wind turbine components encompass the structural and electromechanical subsystems that convert kinetic wind energy into grid-synchronous electricity, including rotor blades exceeding 100 meters in length cast from glass-fiber-reinforced epoxy, steel towers rated for 100-year fatigue cycles, and pitch control systems regulating aerodynamic stall margins. Blades manufactured from carbon fiber hybrid laminates command premium positioning as rotor diameters scale beyond 220 meters for offshore installations. Gearbox demand faces structural compression as direct-drive architectures displace planetary stages in multi-megawatt platforms. Tower segments in high-strength steel dominate onshore economics while concrete-steel hybrid designs penetrate offshore foundations.
The EU Green Deal and its domestic content requirements reshape supply chain geography for European project developers. China's GB standards and MIIT efficiency mandates enforce nacelle certification thresholds that filter technology imports. Stakeholders must monitor how blade recyclability regulations under ECHA REACH protocols alter composite material specifications and incumbent supplier qualification timelines.
Market Dynamics
Direct-drive permanent-magnet generators are eliminating gearbox failure points in offshore installations, forcing incumbent drivetrain suppliers to abandon planetary architectures or retreat to onshore niches. This technology substitution cascades through blade aerodynamics, foundation engineering, and service contract structures.
Growth Catalysts
- EU Green Deal domestic content thresholds:European project developers must source specified component shares from within the bloc, redirecting supply chain investment toward nacelle assembly facilities in Denmark and blade molding centers in Spain.
- Corporate renewable PPAs:Technology companies and data center operators are signing long-term offtake agreements directly with wind asset owners, bypassing traditional utility intermediaries and accelerating turbine deployment timelines.
- Carbon fiber hybrid laminates:These materials enable 220-meter rotor diameters for offshore platforms, capturing higher capacity factors and reducing levelized cost thresholds for North Sea and Baltic developments.
Market Restraints
- Neodymium supply concentration:Rare-earth magnet processing concentrates in China's Jiangxi and Inner Mongolia provinces, exposing direct-drive generator manufacturers to export quota volatility and geopolitical friction.
- Blade recyclability mandates:ECHA REACH protocols are pressuring glass-fiber-reinforced epoxy formulations that lack economically viable end-of-life pathways, threatening incumbent composite suppliers with qualification delays.
- Steel tower fatigue certification:High-strength steel grades required for 150-meter hub heights face extended testing protocols, stretching project development cycles and freezing capital in pre-construction phases.
Strategic Opportunities
- Floating offshore foundations:Concrete-steel hybrid substructures unlock deep-water sites off Portugal, Norway, and Japan where fixed-bottom economics fail, creating new demand for dynamic cable systems and station-keeping components.
- Blade remanufacturing services:Early-generation onshore assets approaching end-of-design-life present refurbishment revenue streams, with leading edge erosion repair and aerodynamic vortex generator retrofit extending operational tenure.
- India's PLI scheme for renewable manufacturing:Production-linked incentives for domestic nacelle and blade capacity are attracting component suppliers to Gujarat and Tamil Nadu industrial corridors.
Industry Challenges
- Composite technician scarcity:Vacuum-assisted resin transfer molding and automated fiber placement require specialized labor pools that training institutions in Germany, Denmark, and the US have failed to scale proportionally with installation targets.
- Grid code synchronization:Type-certified power converters must demonstrate fault-ride-through capability under evolving transmission operator standards, forcing firmware revisions that delay commissioning schedules.
- Inter-array cable installation:Offshore wind farms demand precision burial of medium-voltage circuits across irregular seabed topography, where vessel availability bottlenecks and weather windows compress construction seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Components Market |
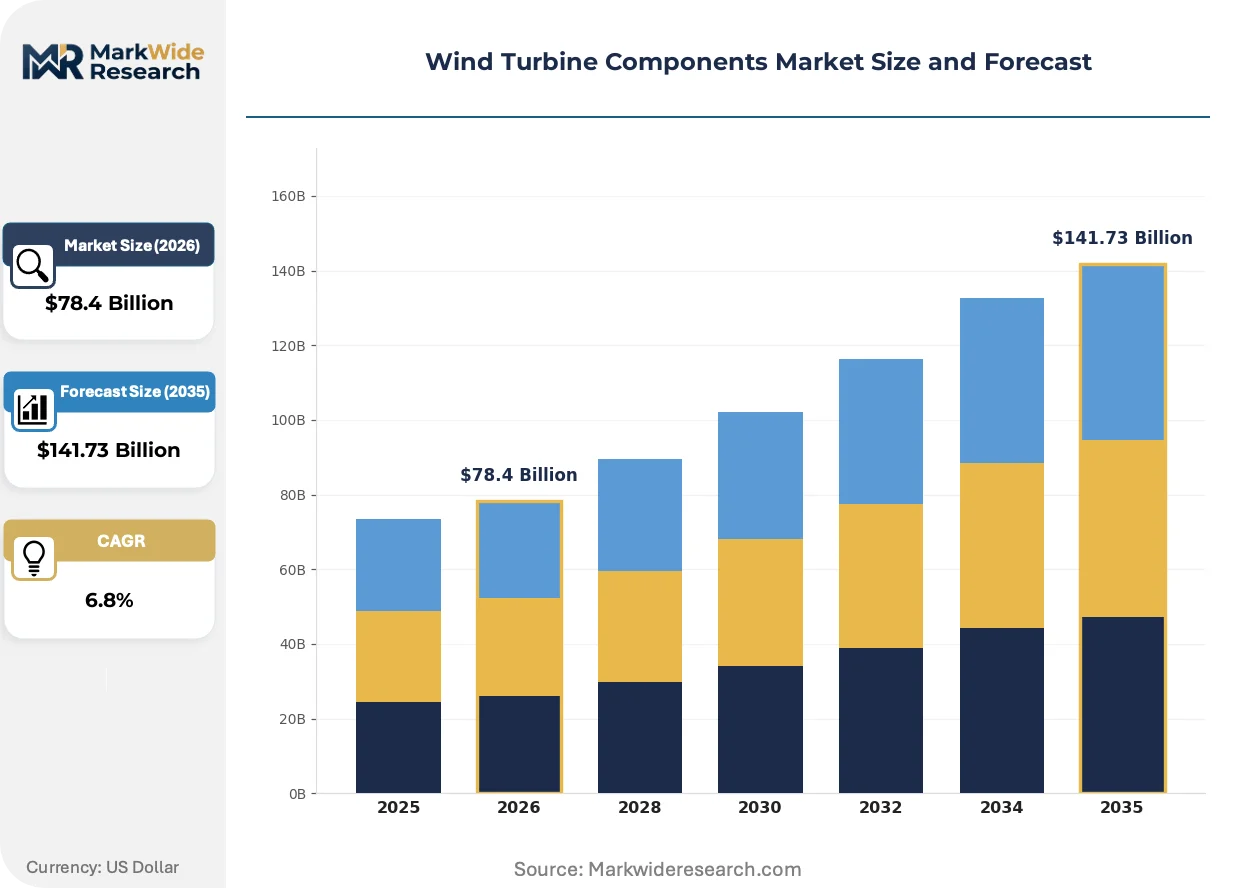
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Blades, Gearbox, Tower, Controller Material: Steel, Carbon Fiber, Aluminum, Composite End User: Utilities, Independent Power Producers, OEMs, Project Developers Installation Type: Onshore, Offshore, Hybrid, Repowering |
| Companies Covered | GE Vernova, Nordex SE, Vestas Wind Systems A/S, Envision Energy, Mingyang Smart Energy, Siemens Gamesa Renewable Energy, ENERCON GmbH, Shanghai Electric Wind Power Group Co., Ltd., Goldwind, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Components Market Strategic Shifts & Innovations
Material science breakthroughs and procurement model fragmentation are converging to rewrite component specifications and supplier qualification pathways. Three developments merit particular attention.
Direct-drive permanent-magnet generators eliminate gearbox maintenance burdens in salt-air environments. Offshore developers in the North Sea and Baltic markets are specifying these architectures for all new multi-megawatt platforms. This configuration is displacing planetary drivetrain suppliers from premium offshore segments and compressing their addressable market to onshore installations below 4 MW capacity.
ECHA REACH blade recyclability mandates are forcing composite material substitutions ahead of 2030 enforcement horizons. Glass-fiber-epoxy formulations face qualification barriers unless manufacturers demonstrate thermoplastic resin compatibility or pyrolysis recovery pathways. European blade producers are accelerating partnerships with chemical recyclers in the Netherlands and Germany to secure feedstock circularity credentials.
Merchant offtake structures are unbundling component procurement from engineering-procurement-construction wrap contracts. Independent power producers now source blades, towers, and drivetrains through separate competitive tenders, fragmenting supplier relationships that turbine OEMs previously controlled. This pattern concentrates in Texas and Australian wind corridors where merchant exposure appetite runs highest.
Wind Turbine Components Market Segmentation
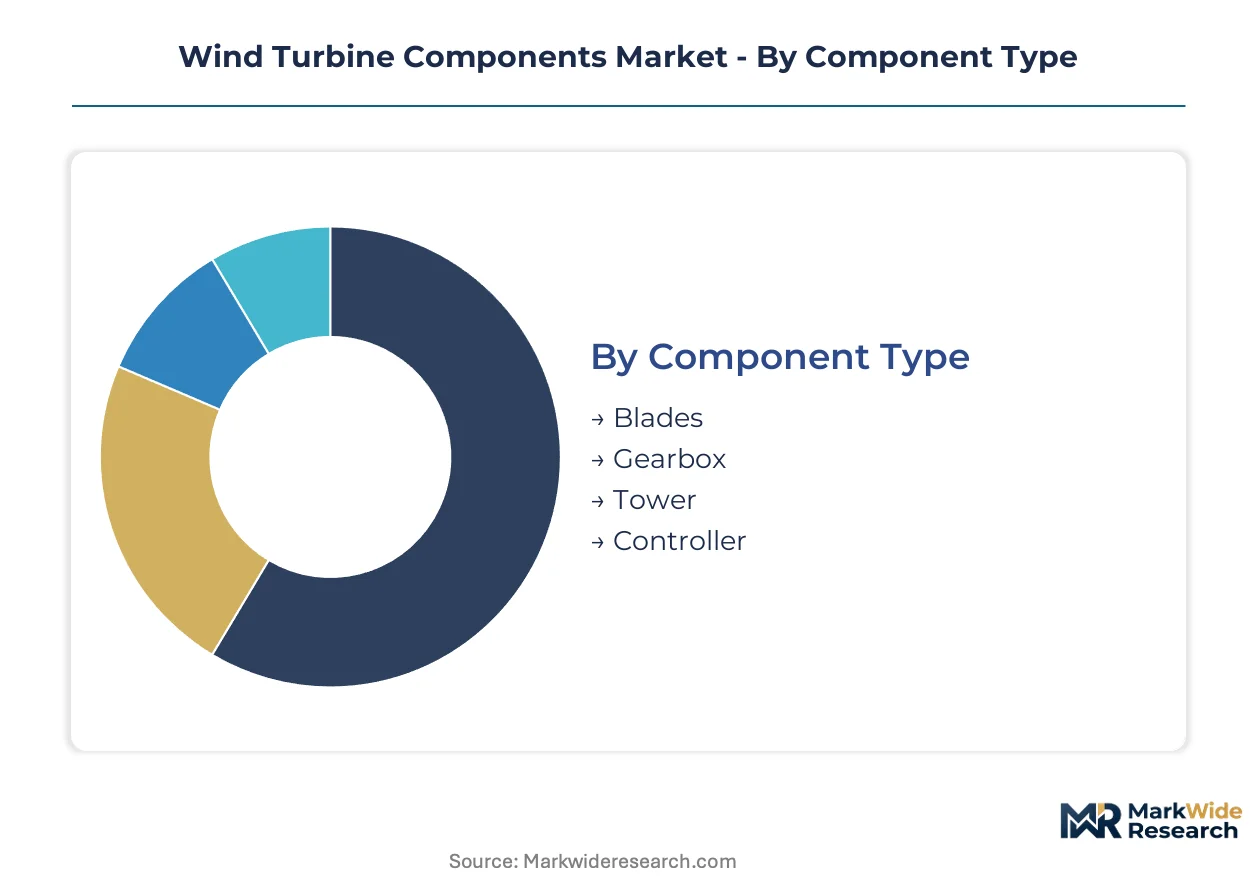
Component specifications diverge sharply between onshore cost optimization and offshore reliability premiums. Material selection and procurement channel economics determine margin capture across each segment tier.
Component Type:
Blades and towers concentrate capital intensity and aftermarket service revenue, while controllers and gearboxes face technology substitution pressures.
- Blades:Glass-fiber-reinforced epoxy laminates exceeding 100 meters in length dominate onshore platforms. Demand clusters in China where Mingyang and Goldwind operate integrated molding facilities near coastal assembly hubs, driven by GB standards enforcing fatigue certification thresholds.
- Tower:High-strength steel segments rated for 100-year fatigue cycles anchor onshore economics. Procurement concentrates with independent power producers in Texas and Australian merchant corridors seeking hub heights above 150 meters for capacity factor optimization.
- Gearbox:Planetary stage architectures face displacement from direct-drive generators in offshore specifications.
- Controller:Pitch regulation systems and power converters require firmware revisions for evolving grid code synchronization.
The dominant share belongs to blades, while towers are closing the gap fastest through hub height escalation.
Material:
Carbon fiber hybrids command price premiums for offshore scale, while steel and aluminum compete on fabrication speed and transport logistics.
- Carbon Fiber:Hybrid laminates enable 220-meter rotor diameters for offshore installations. Developers in the North Sea and Baltic markets specify these materials for multi-megawatt platforms, constrained by ECHA REACH recyclability mandates pressuring thermoplastic resin adoption.
- Steel:High-strength grades for tower segments and nacelle beds dominate unit volume. China's MIIT efficiency mandates enforce domestic content thresholds that filter technology imports, redirecting supply chain investment toward European nacelle assembly facilities.
- Aluminum:Lightweight housings for nacelle enclosures and hub castings reduce transport costs.
- Composite:Glass-fiber formulations face qualification barriers without demonstrated pyrolysis recovery pathways.
Steel retains volume leadership, though carbon fiber expands most quickly in offshore specifications.
End User:
Procurement authority is fragmenting from utility intermediaries toward merchant-exposed asset owners and direct corporate offtakers.
- Independent Power Producers:Merchant offtake structures unbundle component procurement from engineering-procurement-construction wrap contracts. These stakeholders source blades, towers, and drivetrains through separate competitive tenders in Texas wind corridors where corporate PPA appetite runs highest.
- Utilities:Traditional integrated procurement models persist in regulated markets with cost-of-service ratemaking. European utilities face EU Green Deal domestic content requirements reshaping supply chain geography toward Spanish blade molding centers and Danish assembly facilities.
- OEMs:Captive component production strategies vary across Vestas, GE Vernova, and Siemens Gamesa integration levels.
- Project Developers:Early-stage site aggregation specialists rely on turbine OEM procurement channels.
Independent power producers are gaining share fastest, while utilities defend position in regulated jurisdictions.
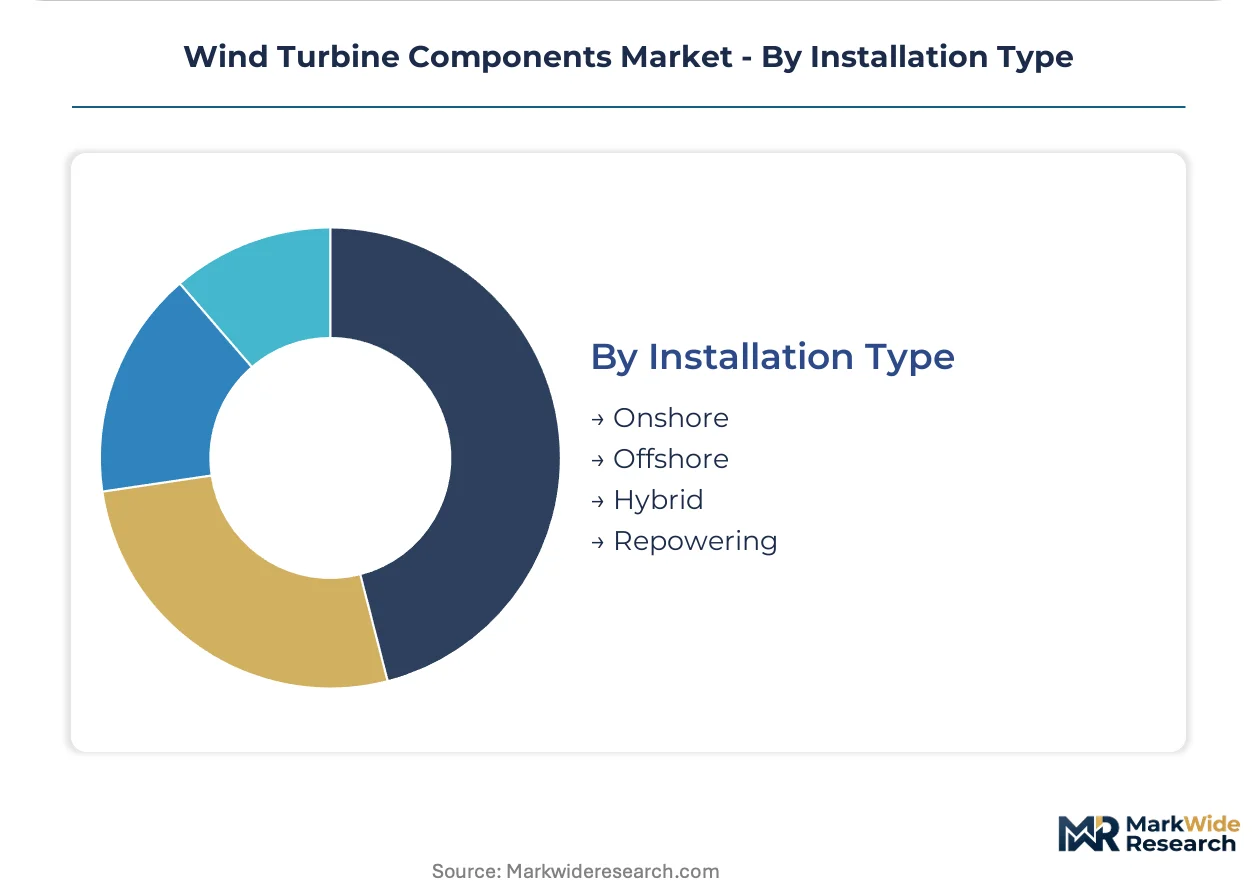
Installation Type:
Offshore foundations and repowering retrofits capture premium pricing, while onshore volume sustains supplier base consolidation.
- Offshore:Concrete-steel hybrid substructures and dynamic cable systems unlock deep-water sites off Portugal, Norway, and Japan. Direct-drive permanent-magnet generators eliminate gearbox failure points in salt-air environments, forcing drivetrain supplier specialization.
- Repowering:Early-generation onshore assets approaching end-of-design-life present blade remanufacturing revenue streams. Leading edge erosion repair and aerodynamic vortex generator retrofit extend operational tenure for German and Danish fleet operators.
- Onshore:Steel tower segments and standard hub heights dominate unit deployment.
- Hybrid:Co-located wind-solar configurations require integrated power conversion and storage coupling.
Onshore maintains volume dominance, yet offshore commands the steepest expansion trajectory through floating foundation deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Esbjerg in Denmark anchors North Sea offshore logistics, channeling nacelle assembly flows and blade transport corridors. Qingdao and Tianjin ports in China handle carbon fiber laminate imports for Mingyang and Goldwind molding clusters. German North Sea grid interconnects at BorWin and HelWin hubs synchronize offshore generation capacity.
China
MIIT efficiency mandates enforce GB standards certification thresholds that filter nacelle technology imports. Domestic content rules redirect supply chain investment toward coastal assembly hubs in Guangdong and Jiangsu provinces. Yangtze River Delta clusters concentrate blade molding capacity near Shanghai Electric and Goldwind facilities.
Germany
ECHA REACH blade recyclability protocols pressure thermoplastic resin adoption across composite supply chains. The KBA certifies tower fatigue ratings for 150-meter hub height deployments. North Rhine-Westphalia hosts drivetrain engineering centers serving North Sea offshore specifications.
United States
FERC interconnection queue reforms compress pre-construction cycles for merchant-exposed Texas wind corridors. The IRA production tax credit structures anchor independent power producer procurement timelines. Gulf Coast ports at Corpus Christi and Houston handle blade imports for Great Plains deployment.
Denmark
EU Green Deal domestic content thresholds reshape nacelle sourcing toward Esbjerg and Aalborg assembly facilities. Vestas Wind Systems A/S anchors blade aerodynamic design centers serving Baltic developments. Copenhagen port infrastructure channels floating foundation components for Norwegian deep-water sites.
India
CEA grid code synchronization mandates force power converter firmware revisions for fault-ride-through compliance. PLI scheme incentives attract blade and nacelle suppliers to Gujarat and Tamil Nadu industrial corridors. Mundra port handles steel tower segment imports for Rajasthan wind zones.
Wind Turbine Components Market Key Industry Players
Concentration sits with integrated turbine OEMs that control blade molding and nacelle assembly through captive supply. Three archetypes define competitive positioning: European engineering specialists with aerodynamic design centers, Chinese scale-driven fabricators with coastal cluster integration, and diversified industrial conglomerates leveraging cross-divisional service infrastructure. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players securing port access and composite technician pipelines.
Among European engineering specialists, Vestas Wind Systems A/S and Siemens Gamesa Renewable Energy occupy positions defined by direct-drive generator architectures and offshore reliability premiums. ENERCON GmbH represents the German precision-manufacturing archetype with onshore-focused drivetrain specialization. Chinese scale-driven fabricators include Mingyang Smart Energy and Goldwind, exemplifying coastal cluster integration and domestic content compliance. GE Vernova sits within the diversified industrial tier, leveraging gas-turbine service infrastructure for cross-selling offshore maintenance contracts.
| Leading Market Players |
|---|
| GE Vernova |
| Nordex SE |
| Vestas Wind Systems A/S |
| Envision Energy |
| Mingyang Smart Energy |
| Siemens Gamesa Renewable Energy |
| ENERCON GmbH |
| Shanghai Electric Wind Power Group Co., Ltd. |
| Goldwind |
| Others |
Cost & Logistics Intelligence
EU Green Deal domestic content thresholds gate both supplier qualification timelines and price differentiation between European-certified and import-tier component streams. This regulatory architecture compresses margins for non-compliant suppliers while enabling premium capture by nacelle assemblers meeting bloc-origin mandates.
Pricing Analysis
Volume-discount tiering structures separate merchant-exposed independent power producers procuring at scale from utility intermediaries negotiating bundled engineering-procurement-construction wraps. Price differentiation hinges on fatigue certification grade for steel tower segments and blade recyclability credentials under ECHA REACH protocols. Cost compression in standard-grade onshore components intensifies as Chinese fabricators export surplus capacity. Merchant offtakers in Texas corridors exhibit highest price sensitivity, while European offshore developers prioritize reliability premiums over unit economics.
Supply Chain Analysis
Rare-earth magnet processing chokepoints in China's Jiangxi and Inner Mongolia provinces tether direct-drive generator supply to export quota volatility. Raw material flows draw from Brazilian iron ore, Australian bauxite, and Mongolian neodymium concentrate. Single-source vulnerability concentrates in carbon fiber precursor supply from Japan and South Korea. Distribution runs through captive nacelle assembly clusters at Esbjerg, Qingdao, and Aalborg, with blade molding co-located near coastal installation hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized composite technician pipelines and certified fatigue-testing laboratory access constitute binding constraints that separate viable suppliers from qualified incumbents. This capability scarcity rewards early investment in workforce development and accreditation infrastructure.
For Market Incumbents: Compound defensive positioning through backward integration into carbon fiber recycling partnerships and captive blade remanufacturing service networks. Direct-drive generator substitution threatens planetary gearbox suppliers; retreat to onshore niches below 4 MW capacity or absorb permanent-magnet generator engineering capabilities through targeted hiring in North Rhine-Westphalia. For New Entrants and Emerging Players: Differentiate on thermoplastic resin formulations that satisfy ECHA REACH recyclability mandates ahead of 2030 enforcement horizons. White-space opportunity concentrates in floating offshore foundation substructures for Portuguese and Norwegian deep-water sites. Target India's PLI scheme corridors in Gujarat and Tamil Nadu for nacelle assembly partnerships with domestic IPPs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed blade remanufacturing specialists holding European leading-edge repair certifications. Long-term viability favors suppliers with demonstrated pyrolysis recovery pathways and port-adjacent molding capacity. Monitor neodymium export quota announcements from Chinese regulators as inflection indicators for direct-drive generator cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Blade Remanufacturing Service Buildout | Captures early-generation asset refurbishment demand from German and Danish fleet operators. |
| Thermoplastic Resin Qualification Investment | Secures ECHA REACH recyclability credentials ahead of composite material substitution deadlines. |
| Port-Adjacent Nacelle Assembly Expansion | Reduces blade transport costs for 100-meter-plus components destined for North Sea offshore sites. |
| Permanent-Magnet Generator Engineering Acquisition | Addresses gearbox displacement risk through direct-drive drivetrain capability integration. |
| Composite Technician Training Pipeline Development | Alleviates vacuum-assisted resin transfer molding labor scarcity constraining installation targets. |
Research Approach
Cross-validation between executive interviews at Vestas and Siemens Gamesa engineering centers and secondary trade data anchors the qualitative findings on technology substitution trajectories. Primary fieldwork encompassed IPP procurement directors, EPC contractors, composite plant managers, and grid interconnection specialists across Denmark, Germany, China, and Texas. Secondary sources incorporated IEA wind technology reports, FERC interconnection queue filings, ECHA REACH substance dossiers, and MIIT efficiency standard updates. Bottom-up component demand modeling triangulates against top-down capacity installation projections.
Sensitivity analysis across neodymium price volatility bands and domestic content threshold scenarios shapes the forecast framework over the projection horizon. Segmentation dimensions span component type, material grade, end-user procurement authority, and installation environment. CAGRs derive from iterative convergence between supply-side capacity buildout schedules and demand-side offtake contract pipelines. Industry-specific inputs include blade length scaling curves, tower hub height escalation rates, and floating foundation deployment timelines.
Material uncertainties — rare-earth export quota shocks, ECHA recyclability enforcement delays, and floating foundation cost breakthroughs — sit outside the modeled envelope. Forecasts reflect documented assumptions on technology adoption rates and regulatory implementation schedules. Practitioners should keep alternative scenarios live as EU Green Deal domestic content thresholds and Chinese MIIT certification mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Power Infrastructure Market
Power Equipment
India Power EPC Market
Power Equipment
Asia-Pacific Gas Turbine Market
Power Equipment
Power Grid Primary and Secondary Fusion Equipment Market
Power Equipment
Asia-Pacific Gas Turbine MRO Market
Power Equipment
Industrial Gas Turbine Sales Market
Power Equipment
Power Cables Market
Power Equipment
Cogeneration Equipment Market
Power Equipment
Deaerators Market
Power Equipment
Russian Federation Power EPC Market
Power Equipment
United Arab Emirates Power EPC Market
Power Equipment
Kazakhstan Power EPC Market
Power Equipment
Egypt Power EPC Market
Power Equipment
Japan Power EPC Market
Power Equipment
Global Transformerless UPS Market
Power Equipment
Chad Power EPC Market