
 Wide Bandgap Semiconductors Market | 2026-2036
Wide Bandgap Semiconductors Market Size, Share, and Industry Trends Forecast 2026-2036
Wide Bandgap Semiconductors Market Intelligence
Market Context
Japanese substrate producers is expanding SiC boule capacity to meet backlog from automotive inverter programs. Wolfspeed anchors North American supply through its vertically integrated silicon carbide fabrication from crystal growth to packaged modules. Infineon Technologies dominates European design-ins for traction inverters at BMW, Volkswagen, and Hyundai-Kia. GaN Systems competes in consumer power adapters and data center PSUs with discrete devices rated above 650V.
Technical Definition and Segments
Wide bandgap semiconductors are compound or crystalline materials with electronic bandgaps exceeding 2.3 electron volts, enabling operation above 200°C with breakdown fields roughly ten times that of silicon, which makes them essential for high-efficiency power conversion and RF transmission systems. Silicon Carbide leads material revenue due to traction inverter penetration, while Gallium Nitride captures the fastest expansion in RF components and consumer power supplies where switching frequency above 1 MHz shrinks magnetics. Power Electronics commands the largest application value pool, though Electric Vehicles represents the steepest trajectory as 800V architectures replace 400V platforms.
Regulatory Frame
The EPA, EU Green Deal efficiency mandates, and China's dual carbon goals from MEE collectively tighten minimum performance standards for grid-tied inverters and onboard chargers. RoHS and REACH in Europe plus state-level ZEV mandates in California constrain material choices and accelerate qualification timelines for new device packages. Stakeholders must monitor how automotive OEMs reconcile functional safety ISO 26262 requirements with the shorter technology lifecycles inherent to wide bandgap qualification protocols.
Market Dynamics
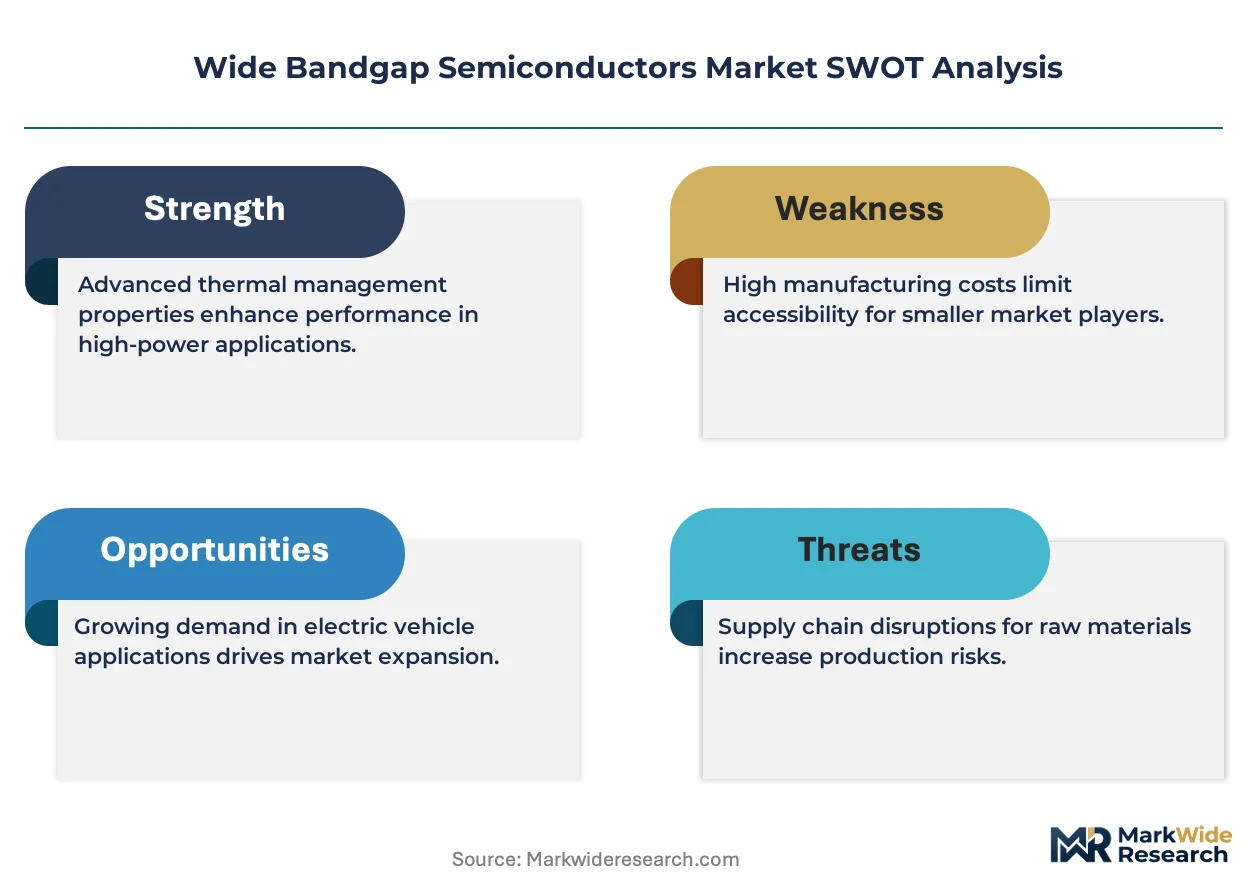
The transition from 400V to 800V electric vehicle architectures is compressing design cycles and forcing simultaneous retooling across substrate growth, epitaxy, and module packaging stages.
Growth Catalysts
- EU Green Deal efficiency mandates:Grid-tied inverter standards and onboard charger regulations in Europe are mandating minimum conversion efficiencies above 98 percent, eliminating silicon IGBTs from new platform designs.
- 800V traction inverters:Automotive OEMs in Germany, South Korea, and the United States are redesigning powertrain architectures around silicon carbide MOSFETs to reduce charging times and extend driving range.
- Substrate capacity expansion:Japanese crystal growth facilities are scaling 150mm and 200mm SiC boule output to address order backlogs from tier-one inverter suppliers.
Market Restraints
- High-purity silicon carbide feedstock costs:Sublimation-grade graphite crucibles and argon gas consumption account for 40 percent of substrate manufacturing cost, constraining margin expansion at wafer suppliers.
- Single-source epitaxy equipment:MOCVD and HVPE reactor supply concentrates among German and Japanese vendors, creating 18-month lead times for capacity expansion.
- Copper wire bonding limitations:Traditional interconnect technologies face electromigration failures above 175°C junction temperatures, forcing costly silver sintering process adoption.
Strategic Opportunities
- Indian PLI scheme for semiconductors:Production-linked incentives for compound semiconductor fabs are attracting substrate and epitaxy investments to address domestic automotive and solar inverter demand.
- RF gallium nitride for 5G base stations:Macro-cell and small-cell deployments in sub-6 GHz bands are consuming high-electron-mobility transistors for massive MIMO arrays.
- Data center power supply consolidation:Titanium-efficiency server PSUs operating above 1 MHz switching frequency are displacing silicon super-junction MOSFETs in hyperscale facilities.
Industry Challenges
- ISO 26262 functional safety certification:Automotive inverter programs require ASIL-D rated gate drivers and fault detection circuits, extending qualification timelines by 18 to 24 months.
- Wafer defect density control:Basal plane dislocations in 150mm SiC substrates propagate into active device layers, reducing yield at power module assembly.
- Legacy silicon supply chain reconfiguration:Foundries and OSATs must retool wire bonding, die attach, and molding processes to accommodate wider bandgap thermal and electrical properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wide Bandgap Semiconductors Market |
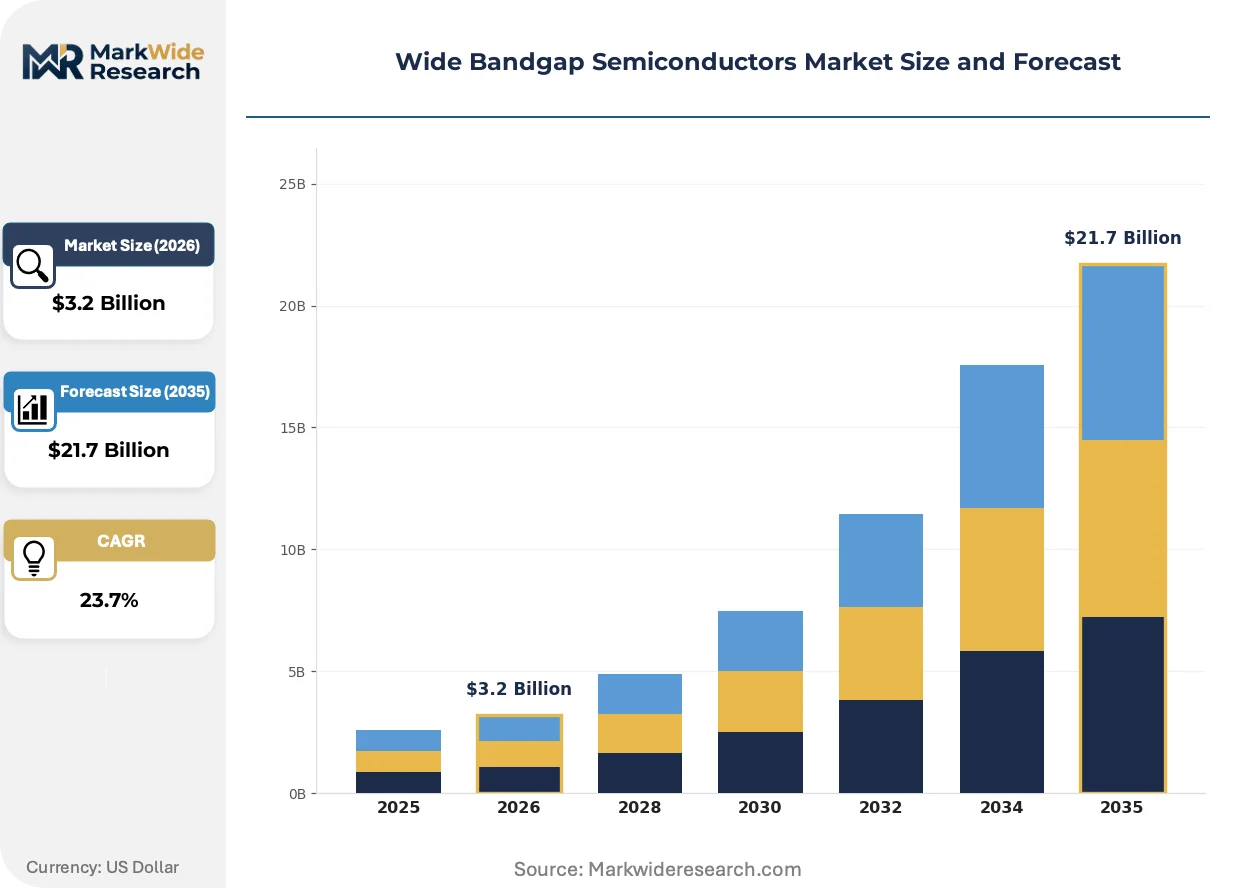
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $21.7 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Silicon Carbide, Gallium Nitride, Diamond, Zinc Oxide, Aluminium Nitride Device Type: Power MOSFET, Schottky Diode, JFET, IGBT, Transistor Application: Power Electronics, RF Components, LED Lighting, Electric Vehicles, Renewable Energy End User Industry: Consumer Electronics, Aerospace, Telecommunications, Defense Systems, Semiconductors |
| Companies Covered | ON Semiconductor, Texas Instruments, Infineon Technologies, GaN Systems, Mitsubishi Electric, Wolfspeed, Rohm Semiconductor, NXP Semiconductors, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wide Bandgap Semiconductors Market Strategic Shifts & Innovations
Process automation and materials science advances are collapsing the traditional separation between crystal growth, device fabrication, and system-level integration in wide bandgap supply chains.
Automated defect inspection during SiC boule growth is automating real-time temperature and pressure adjustments in sublimation furnaces. Tier-one substrate producers in Japan and Germany are deploying machine vision systems that reduce micropipe density variation by half. This automation is compressing the feedback loop between crystal growth and wafer slicing, enabling faster qualification cycles for automotive inverter programs.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of dielectric coolants and thermal interface materials used in power module packaging. European module assemblers must qualify fluorine-free alternatives by 2026 without sacrificing thermal conductivity above 3 W/mK. Traction inverter suppliers serving BMW and Volkswagen are accelerating validation of phase-change materials and graphite-based thermal pads.
Direct sourcing contracts between automotive OEMs and substrate producers are bypassing traditional semiconductor distributors. Hyundai-Kia and Ford have established multi-year supply agreements with Japanese crystal growth facilities, locking volume at fixed pricing. Germany exhibits the most advanced procurement restructuring, with inverter suppliers negotiating wafer-level commitments rather than packaged device purchases.
Wide Bandgap Semiconductors Market Segmentation
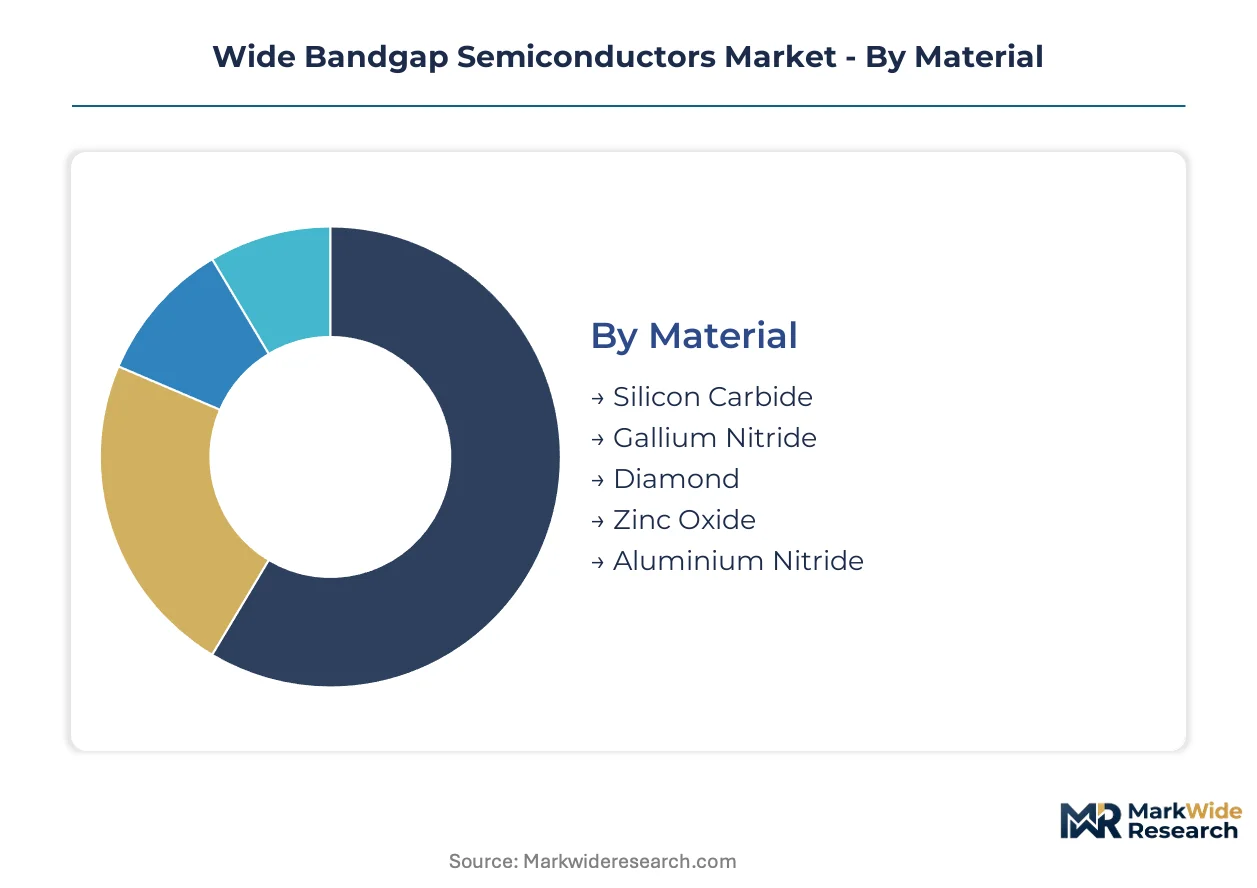
Wide bandgap semiconductor procurement divides sharply between high-volume automotive programs demanding SiC traction inverters and premium RF applications sourcing GaN HEMTs for 5G infrastructure. Material purity specifications, switching frequency requirements, and thermal management architectures create distinct supply chains that rarely overlap.
Material:
Silicon Carbide commands volume share through established 150mm wafer supply chains, while Gallium Nitride captures premium pricing in RF and consumer power segments.
- Silicon Carbide:Crystalline compound with 3.26 eV bandgap enables 1200V+ blocking voltage and junction temperatures exceeding 200°C. Demand concentrates in German automotive OEMs redesigning 800V traction inverters, driven by EU Green Deal efficiency mandates eliminating silicon IGBTs.
- Gallium Nitride:III-V semiconductor with 3.4 eV bandgap supports switching frequencies above 1 MHz with lower gate charge than silicon. Deployment concentrates in data center power supplies and 5G base station amplifiers, where magnetics miniaturization justifies die cost premiums.
- Diamond:Ultra-wide 5.5 eV bandgap material with thermal conductivity five times copper, limited to defense and satellite applications by synthesis costs.
- Zinc Oxide:Piezoelectric wide bandgap compound serving UV optoelectronics and transparent electronics in specialized sensor applications.
- Aluminium Nitride:6.2 eV bandgap substrate material for deep-UV LEDs and high-thermal-conductivity heat spreaders in RF power modules.
Mature deployment sits with Silicon Carbide. Newer deployment is concentrated in Gallium Nitride.
Device Type:
Power MOSFETs generate the steepest expansion trajectory as unipolar switching devices displace bipolar silicon IGBTs across voltage classes above 600V.
- Power MOSFET:Voltage-controlled unipolar switch with negligible switching losses compared to silicon alternatives. Automotive inverter programs in South Korea and the United States specify trench-gate SiC MOSFETs for 800V battery electric platforms, compressing design cycles to match vehicle launch timelines.
- Schottky Diode:Majority-carrier rectifier with zero reverse recovery charge, essential for boost PFC stages in onboard chargers. German tier-one suppliers qualify 1200V SiC Schottkys for combined inverter-charger modules.
- JFET:Normally-on vertical channel device offering lowest specific on-resistance per die area, deployed in circuit breaker and solid-state relay applications.
- IGBT:Bipolar silicon-insulated gate device with wide bandgap anti-parallel diodes, transitional architecture in legacy industrial motor drives.
- Transistor:RF power transistors including GaN HEMTs for macro-cell base stations and radar systems, where high electron mobility enables efficient power amplification at millimeter-wave frequencies.
Volume concentration favors Power MOSFETs. Premium positioning attaches to RF Transistor variants.
Application:
Power Electronics anchors revenue through industrial motor drives and grid-tied inverters, while Electric Vehicles generates the steepest demand slope as 800V architectures proliferate.
- Power Electronics:Encompasses industrial variable frequency drives, solar inverters, and uninterruptible power supplies requiring 600V-1700V switching devices. Chinese solar inverter manufacturers specify SiC modules to meet MEE dual carbon efficiency targets.
- RF Components:Base station power amplifiers and radar transmitters exploiting GaN's high breakdown field and thermal stability. Sub-6 GHz massive MIMO deployments in Japan and South Korea consume high-electron-mobility transistors for beamforming arrays.
- LED Lighting:Solid-state illumination using GaN-based blue emitters with phosphor conversion, mature market with limited wide bandgap semiconductor growth.
- Electric Vehicles:Traction inverters, onboard chargers, and DC-DC converters operating at 400V-800V battery voltages. German automotive OEMs and tier-one suppliers are redesigning inverter architectures around silicon carbide MOSFETs to extend driving range.
- Renewable Energy:Wind turbine converters and utility-scale solar inverters above 1 MW rating, where SiC modules reduce cooling system mass and improve grid code compliance.
Installed base concentrates in Power Electronics. Capacity expansion targets Electric Vehicles.
End User Industry:
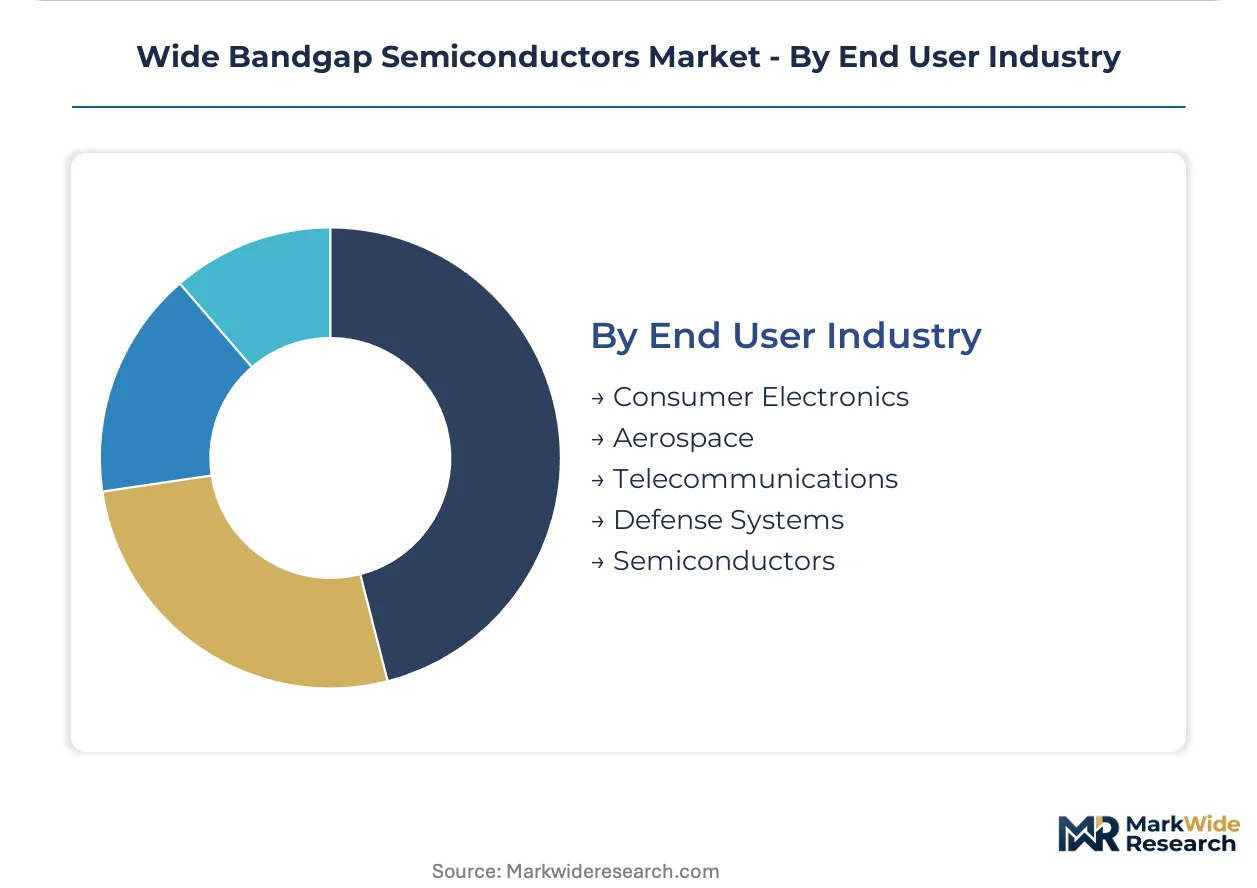
Consumer Electronics drives GaN adoption in compact chargers, while Aerospace and Defense sustains premium pricing for radiation-hardened and high-reliability devices.
- Consumer Electronics:Smartphones, laptops, and appliances requiring compact, efficient power adapters. GaN Systems and competitors supply discrete devices above 650V for USB-C PD chargers operating above 1 MHz switching frequency.
- Aerospace:Satellite power conditioning and aircraft actuation systems demanding radiation tolerance and wide temperature operation. NASA and ESA programs specify hermetic SiC packaging for deep-space missions.
- Telecommunications:5G macro-cells, small-cells, and data center power infrastructure. Hyperscale facilities in the United States displace silicon super-junction MOSFETs with GaN-based titanium-efficiency server PSUs.
- Defense Systems:Radar, electronic warfare, and directed energy weapons requiring high-power RF amplification. U.S. Department of Defense programs fund domestic GaN-on-SiC foundry capacity.
- Semiconductors:Capital equipment and materials suppliers serving the fabrication ecosystem, including MOCVD reactor manufacturers and SiC substrate producers.
High-volume procurement characterizes Consumer Electronics. Longest qualification cycles attach to Aerospace.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity silicon carbide feedstock from Japanese sublimation furnaces and German graphite crucible suppliers anchors geographic production patterns. Automotive inverter demand in Germany, electric vehicle rollout in China, and defense RF programs in the United States reshape regional investment priorities.
Germany
Automotive OEMs and tier-one suppliers in Bavaria and Baden-Württemberg are redesigning 800V traction inverter architectures around silicon carbide MOSFETs. The EU Green Deal mandates minimum conversion efficiencies above 98 percent for grid-tied inverters and onboard chargers, eliminating silicon IGBTs from new platform designs. Stuttgart and Ingolstadt host concentrated engineering centers where BMW, Volkswagen, and Hyundai-Kia suppliers negotiate direct wafer-level procurement contracts.
China
MEE dual carbon goals and national carbon-neutrality mandates tighten efficiency standards for power electronics across solar inverter and EV charger manufacturing. Yangtze River Delta and Pearl River Delta clusters concentrate domestic substrate and epitaxy investments targeting combined inverter-charger modules. State-backed foundries in Jiangsu and Guangdong provinces scale 150mm SiC boule output to address order backlogs from domestic automotive programs.
United States
EPA efficiency mandates and state-level ZEV mandates in California accelerate qualification timelines for new wide bandgap device packages. Wolfspeed anchors North American supply through vertically integrated silicon carbide fabrication from crystal growth to packaged modules in North Carolina. Department of Defense programs fund domestic GaN-on-SiC foundry capacity for radar and electronic warfare applications.
Japan
METI industrial policy supports substrate producers expanding SiC boule capacity to meet backlog from automotive inverter programs. Tokyo and Osaka metropolitan areas concentrate MOCVD and HVPE reactor manufacturing, creating equipment supply bottlenecks with 18-month lead times. Toyota and Honda suppliers in Aichi Prefecture qualify trench-gate SiC MOSFETs for 800V battery electric platforms.
South Korea
MFDS regulatory alignment with ISO 26262 functional safety requirements extends automotive inverter qualification timelines by 18 to 24 months. Hyundai-Kia has established multi-year supply agreements with Japanese crystal growth facilities, locking volume at fixed pricing. Gyeonggi-do and Ulsan industrial complexes host concentrated power module assembly for domestic EV platforms.
Wide Bandgap Semiconductors Market Key Industry Players
Global majors compete with regional champions across substrate fabrication, epitaxy equipment, and power module packaging. The vendor base stratifies into three tiers: integrated substrate-to-module suppliers, discrete device specialists, and equipment-dependent foundries. Strategic archetypes include vertically integrated crystal growers, fabless GaN innovators, and automotive-qualified module assemblers. Capacity expansion and direct OEM supply agreements constitute the dominant competitive moves.
Among integrated substrate suppliers, Wolfspeed and Rohm Semiconductor exemplify the vertically integrated archetype controlling boule growth through packaged modules. Infineon Technologies occupies a position within the automotive-qualified tier, dominating European design-ins for traction inverters. GaN Systems represents the fabless innovation model competing in consumer power adapters and data center PSUs.
| Leading Market Players |
|---|
| ON Semiconductor |
| Texas Instruments |
| Infineon Technologies |
| GaN Systems |
| Mitsubishi Electric |
| Wolfspeed |
| Rohm Semiconductor |
| NXP Semiconductors |
| STMicroelectronics |
| Others |
Cost & Logistics Intelligence
EU Green Deal efficiency mandates gating automotive inverter design-ins simultaneously constrain qualified supplier pools and sustain premium-tier pricing power for SiC substrate producers meeting ASIL-D certification thresholds. Buyers without multi-year wafer-level commitments face allocation rationing during capacity expansion phases.
Pricing Analysis
Warranty and field-failure liability coverage differentiate automotive-grade SiC module pricing from unbundled discrete device sales. Three-tier pricing structure across automotive-qualified, industrial-grade, and consumer electronics tiers reflects ISO 26262 certification investment amortization. Cost compression in consumer GaN adapters intensifies as Chinese foundries scale 650V device output. Data center PSU procurement teams exhibit lowest price sensitivity due to efficiency-driven total cost of ownership calculations.
Supply Chain Analysis
Single-source vulnerability sits with Japanese MOCVD reactor manufacturers supplying epitaxy equipment to substrate producers worldwide. High-purity SiC feedstock draws from German graphite crucible specialists, Japanese crystal growth facilities, and emerging Chinese boule operations. Tariff exposure on semiconductor manufacturing equipment creates procurement timing risk for capacity expansion programs. Distribution runs through direct OEM supply agreements bypassing traditional semiconductor distributors, particularly for German automotive inverter programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wide bandgap semiconductor supply remains structurally constrained by 18-month lead times for sublimation furnace capacity, propping pricing power for qualified substrate producers with captive crystal growth operations.
For Market Incumbents: Anticipate margin compression from Chinese substrate entrants by securing long-term argon gas supply contracts and qualifying secondary graphite crucible sources. Lock automotive OEMs into wafer-level procurement agreements before 200mm SiC boule standardization erodes trench-gate MOSFET differentiation. Prioritize backward integration into high-purity silicon carbide powder synthesis to defend cost position against emerging Chinese boule producers. For New Entrants and Emerging Players: India's PLI scheme for compound semiconductors opens a window for substrate and epitaxy investments targeting domestic solar inverter and two-wheeler EV demand. Penetrate the RF GaN segment for sub-6 GHz 5G small-cell deployments where incumbent capacity concentrates on macro-cell base stations. Pursue fabless design house partnerships with Japanese foundries holding excess MOCVD capacity. For Investors and Strategic Acquirers: Hyundai-Kia's direct sourcing contracts with Japanese crystal growth facilities is the leading indicator that automotive OEMs will bypass distributors to secure wafer supply, favoring substrate producers with proven boule quality. Target acquisition candidates with demonstrated micropipe density control below 0.5 per square centimeter and existing automotive qualification pipelines. Monitor Japanese substrate producer capital expenditure announcements as the inflection signal for supply-demand balance shifts.| Strategic Initiative | Industry Significance |
|---|---|
| 150mm to 200mm SiC Wafer Transition | Enables die cost reduction for 800V traction inverters at BMW and Volkswagen. |
| Automotive ASIL-D Certification Investment | Creates qualification moat against industrial-grade SiC suppliers seeking automotive entry. |
| Direct OEM Wafer Supply Agreements | Locks volume commitment from Hyundai-Kia and Ford, bypassing distributor margin capture. |
| GaN-on-SiC Foundry Capacity Buildout | Addresses U.S. Department of Defense radar and electronic warfare sourcing requirements. |
| Fluorine-Free Thermal Interface Qualification | Meets REACH restrictions for BMW and Volkswagen traction inverter programs by 2026. |
Research Approach
Document review covered SEC filings from substrate and device manufacturers, ECHA REACH restriction notices, and automotive OEM supplier qualification databases, complemented by interviews with SiC substrate procurement managers at German tier-one suppliers, epitaxy equipment engineers at Japanese MOCVD manufacturers, and power module packaging specialists at Korean OSATs. Bottom-up demand modeling from vehicle production databases triangulated against top-down capacity announcements from crystal growth facilities.
Segment-level outputs across material type, device architecture, voltage rating, and end-use application were generated across the analysis window. CAGRs were derived from installed base replacement curves for silicon IGBTs and new platform adoption rates for 800V EV architectures. Forecast inputs incorporated EU Green Deal efficiency mandate implementation timelines and Chinese MEE dual carbon target enforcement intensity.
Caveats apply where Japanese sublimation furnace delivery delays or basal plane dislocation yield excursions could materially shift the outlook for SiC substrate supply availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
China Discrete Semiconductors Market
Semiconductors
India Semiconductor Market
Semiconductors
Semiconductor Bonding Market
Semiconductors
Logic Semiconductor Market
Semiconductors
Global Copper Indium Gallium Selenide (CIGS) Solar Cells Market
Semiconductors
High Reliability Semiconductor Market
Semiconductors
Japan Discrete Semiconductors Market
Semiconductors
Semiconductor Market
Semiconductors
Semiconductor IP Market
Semiconductors
Global Automotive Semiconductor Market
Semiconductors
Gaas Wafer Market
Semiconductors
Global Organic Semiconductor Market
Semiconductors
Germanium Semiconductor Market
Semiconductors
Semiconductor in Military and Aerospace Market
Semiconductors
South Korea Discrete Semiconductors Market
Semiconductors
Smartphone Battery Market