
 USB Wall Charger Market | 2026-2036
USB Wall Charger Market Size, Share, and Industry Trends Forecast 2026-2036
USB Wall Charger Market Insights
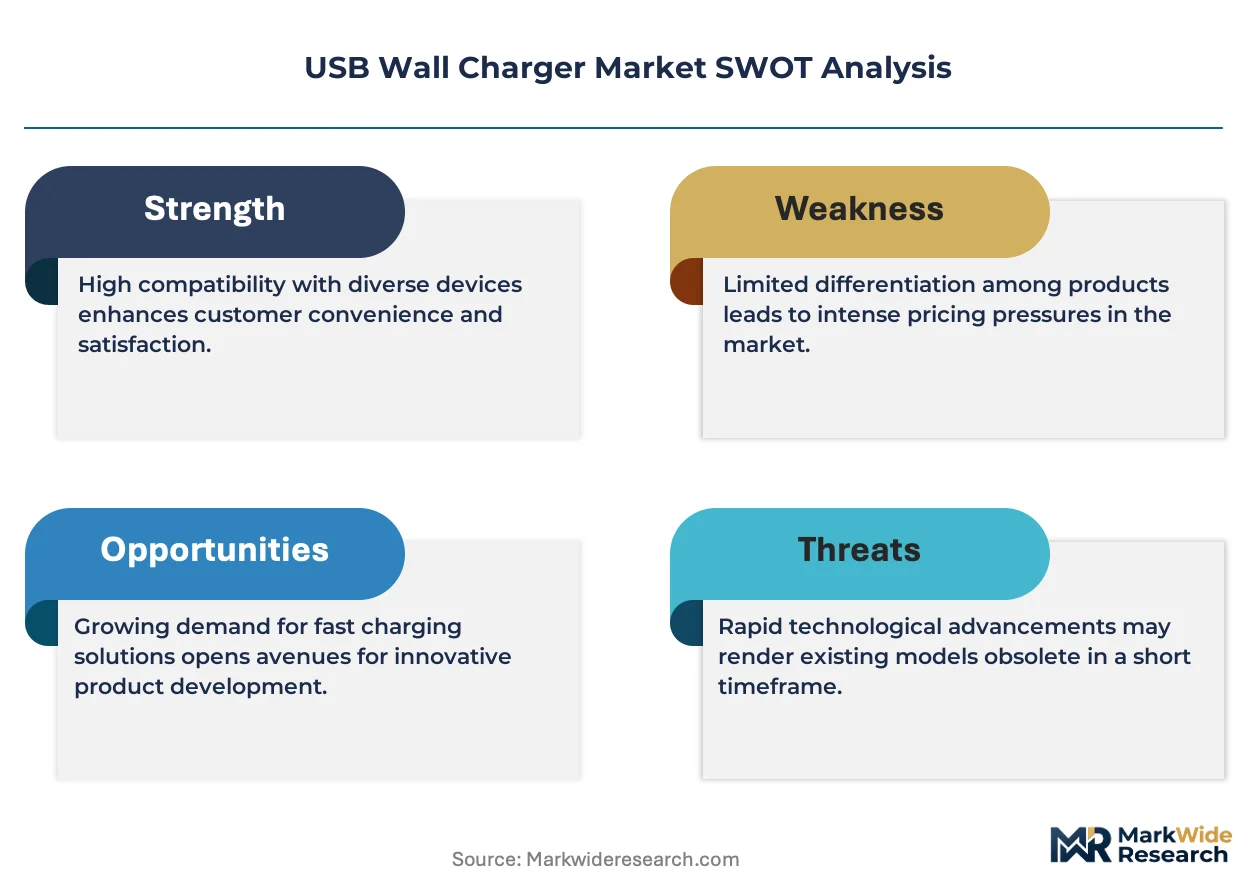
Gallium nitride is expanding its displacement of silicon in high-density charger architectures, cutting thermal footprints while boosting wattage output in compact form factors. Anker Innovations leverages vertical integration across GaN supply partnerships to sustain cost leadership in multi-port segments. Samsung Electronics anchors premium positioning through proprietary Super Fast Charging protocols bundled with flagship devices. Apple differentiates via MagSafe ecosystem lock-in, while Xiaomi Corporation competes aggressively on price-performance ratios across Asian retail channels.
A USB wall charger converts alternating current from wall outlets into regulated direct current for rechargeable devices, typically employing switching-mode power supplies with output specifications ranging from five watts to over one hundred watts depending on protocol support. GaN and Power Delivery technology segments command widening margin pools as consumers upgrade from legacy USB Type-A hardware toward universal USB Type-C solutions. Multi-port configurations represent the fastest-growing product type as households consolidate charging infrastructure for simultaneous smartphone, tablet, and laptop replenishment. Aftermarket suppliers occupy fragmented retail channels where brand recognition and safety certification visibility determine shelf placement economics.
The EU's common charger mandate under the Radio Equipment Directive compels USB Type-C port standardization, eliminating proprietary connector fragmentation across member states. India's BIS compulsory registration scheme blocks uncertified imports while China's GB standards govern domestic manufacturing quality thresholds. Stakeholders must monitor regulatory divergence between harmonized European requirements and emerging economy certification timelines that complicate unified product platform strategies.
Market Dynamics
GaN semiconductor adoption and EU regulatory mandates are compressing product lifecycles while fragmenting certification requirements across export markets. Manufacturers face simultaneous pressure to raise power density and harmonize compliance documentation.
Growth Catalysts
- EU Radio Equipment Directive:The common charger mandate eliminates proprietary connector fragmentation, forcing USB Type-C standardization across member states and expanding addressable market for universal accessories.
- Multi-device households:Laptop-tablet-smartphone convergence creates replacement demand for high-wattage multi-port chargers capable of simultaneous fast-charging protocols.
- GaN foundry scaling:Taiwan and mainland China semiconductor clusters are driving cost curves down for gallium nitride wafers, enabling premium features at mid-market price points.
Market Restraints
- Silicon carbide substrate costs:Alternative wide-bandgap materials face input price volatility that constrains margin expansion for second-tier manufacturers.
- Shenzhen-Shenzhen supply concentration:Over 70 percent of global charger assembly capacity sits within a 200-kilometer corridor, exposing buyers to single-point disruption risks.
- Thermal dissipation physics:Power density above 100W in sub-100cc enclosures hits material limits absent active cooling, capping compact form factor ambitions.
Strategic Opportunities
- India BIS registration gap:Compulsory certification requirements block uncertified imports, creating protected aftermarket channels for compliant domestic assemblers.
- Vehicle USB-C integration:Automotive OEMs are embedding high-power charging ports as standard equipment, opening fleet and aftermarket automotive segments.
- Wireless charging convergence:Qi2 magnetic alignment standards are merging with USB-PD negotiation protocols, enabling hybrid dock-wall charger combinations.
Industry Challenges
- EMC pre-certification talent scarcity:Electromagnetic compatibility testing expertise concentrates in Shenzhen and Hamburg labs, creating bottlenecks for new market entrants.
- Dual carbon compliance documentation:China's MEE environmental disclosure rules and EU CSRD supply chain reporting impose overlapping audit burdens on component sourcing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USB Wall Charger Market |
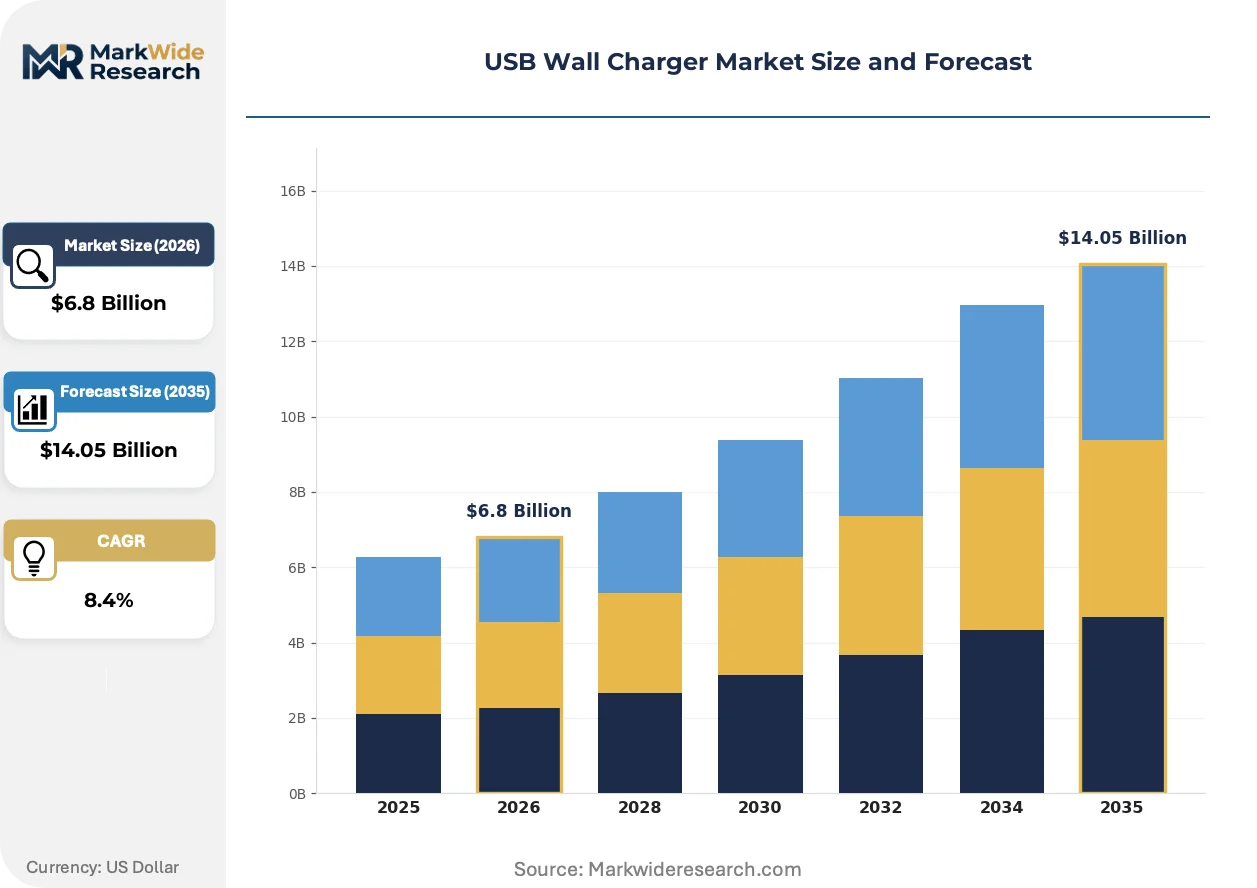
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Port, Dual Port, Multi-Port, Quick Charge, Wireless Charging Technology: USB Type-A, USB Type-C, GaN, Power Delivery, Qualcomm Quick Charge Application: Smartphones, Tablets, Laptops, Wearable Devices, Portable Speakers Customer Type: Consumer Electronics Manufacturers, OEMs, Aftermarket Suppliers, Retailers |
| Companies Covered | Anker Innovations, Belkin International, Koninklijke Philips, Aukey, RAVPower, Samsung Electronics, Apple, Xiaomi Corporation, Baseus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USB Wall Charger Market Trends and Innovations
Power electronics miniaturization and regulatory harmonization pressures are compressing design cycles while expanding protocol complexity. Manufacturers must now balance thermal performance, universal compatibility, and carbon footprint transparency.
GaN power integrated circuits are integrating active clamp flyback topologies with integrated drivers, collapsing component count in 65W and above designs. Enterprise procurement teams and premium consumer segments are adopting these architectures within 18-month refresh windows. The technology is integrating controller, driver, and power stage functions that previously required discrete implementation, enabling credit-card-sized 100W chargers.
REACH substance restrictions and RoHS amendments are phasing out specific flame retardants and stabilizers used in charger housings and PCB substrates. Compounders must reformulate engineering plastics without halogenated additives while maintaining UL94 V-0 ratings. European distributors are now requiring full material disclosure documentation upstream, shifting compliance burden to molders and resin suppliers.
Enterprise buyers are consolidating vendor panels and demanding multi-year total cost of ownership guarantees rather than unit pricing. Procurement teams at technology leasing firms and hospitality chains are replacing spot purchasing with framework agreements covering installation, failure replacement, and end-of-life recovery. This concentration is most visible in North American commercial real estate and co-working space fit-outs, where charging infrastructure is becoming a tenant amenity specification.
USB Wall Charger Market Segmentation
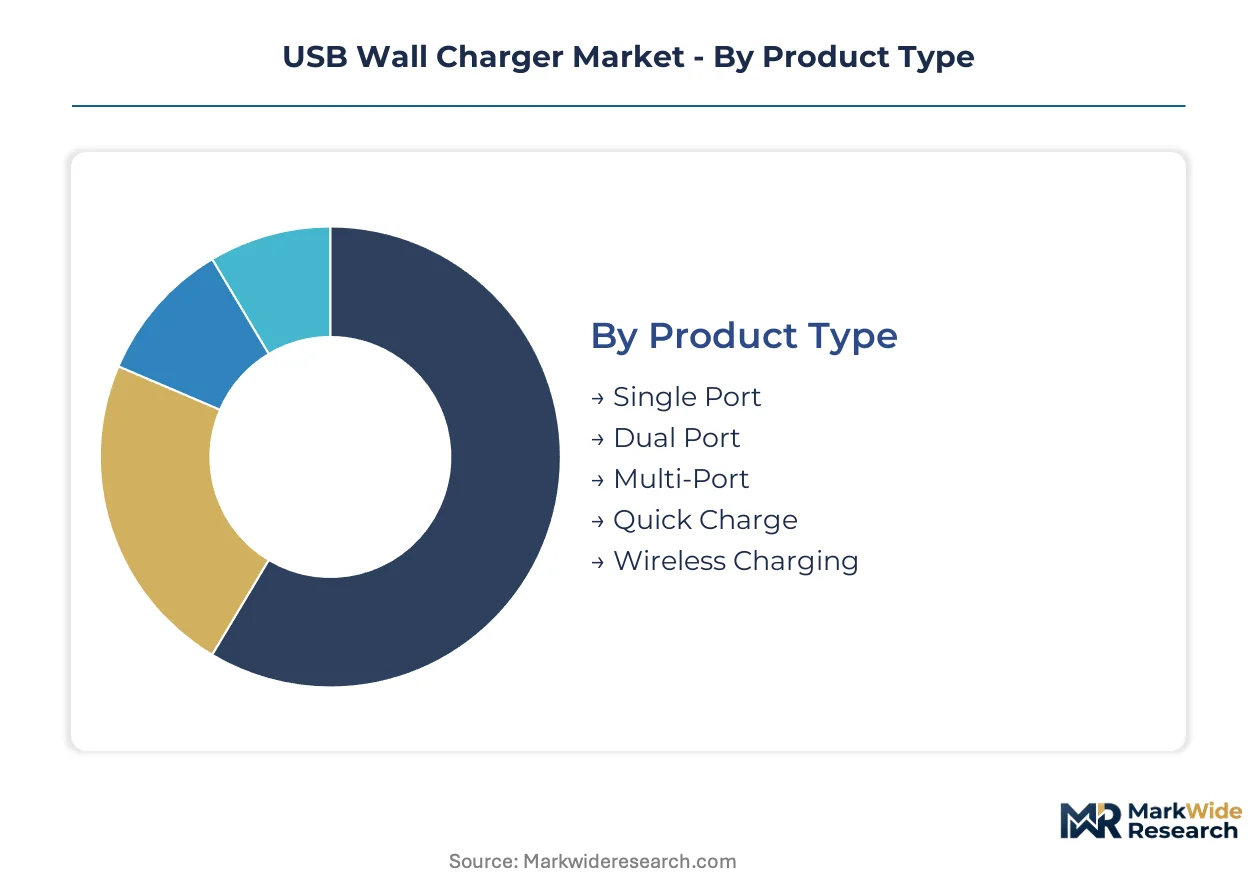
USB wall charger segmentation reflects divergent paths in power density, connector standardization, and procurement channel economics. Technology choices now determine margin structure more than volume scale, while application convergence is collapsing traditional product boundaries.
Product Type:
Port configuration drives physical form factor and thermal design requirements across residential and commercial installations.
- Multi-Port:Households consolidating laptop-tablet-smartphone replenishment demand simultaneous protocol negotiation across 65W to 100W outputs. North American co-working space fit-outs and hospitality chains specify these as tenant amenities, compressing procurement into framework agreements.
- Quick Charge:Proprietary voltage negotiation algorithms from Qualcomm and others enable 0-50% replenishment in under 30 minutes for compatible handsets. Aftermarket channels in India and Southeast Asia move these units through mobile accessory retail clusters where certification visibility determines shelf placement.
- Single Port:Legacy replacement demand persists in price-sensitive bulk procurement for corporate device fleets.
- Dual Port:Couples and small households favor this midpoint between minimalism and consolidation.
- Wireless Charging:Qi2 magnetic alignment standards are merging with USB-PD negotiation, enabling hybrid dock-wall combinations.
Multi-Port leads on scale; Quick Charge leads on momentum.
Technology:
Semiconductor material and protocol architecture now separate premium positioning from commodity replacement cycles.
- GaN:Gallium nitride power integrated circuits integrate active clamp flyback topologies with embedded drivers, collapsing component count in 65W-plus designs. Taiwan and mainland China foundry scaling is driving cost curves toward mid-market price points.
- Power Delivery:USB-PD protocol negotiation enables dynamic voltage scaling from 5V to 20V, supporting laptop replenishment through standardized USB Type-C cables. Enterprise procurement teams specify PD 3.1 compliance for device fleet standardization.
- USB Type-C:The EU Radio Equipment Directive mandates this connector for all handheld devices, eliminating proprietary fragmentation.
- USB Type-A:Legacy hardware replacement demand concentrates in emerging economy price-sensitive segments.
- Qualcomm Quick Charge:Backward-compatible voltage negotiation persists in Android handset accessory bundling.
GaN commands premium shelf positioning; Power Delivery is climbing the fastest as enterprise procurement consolidates.
Application:
Device power requirements are converging upward, collapsing traditional wattage tier boundaries.
- Laptops:USB-PD 100W protocol support enables ultrabook replenishment from compact wall units, displacing proprietary barrel-connector adapters. Corporate technology leasing firms specify multi-year total cost of ownership guarantees covering installation and failure replacement.
- Smartphones:Handset OEM bundling shifts toward USB Type-C, expanding aftermarket replacement demand as consumers upgrade from inbox accessories.
- Tablets:Pro and Air-class devices now require 30W to 45W sustained input, bridging smartphone and laptop power tiers.
- Wearable Devices:Low-wattage magnetic puck charging maintains distinct form factor requirements.
- Portable Speakers:Outdoor and party-class units are adopting USB-C input for unified cable ecosystems.
Smartphones anchor volume concentration; Laptops show the steepest expansion trajectory as work-from-anywhere hardware refreshes accelerate.
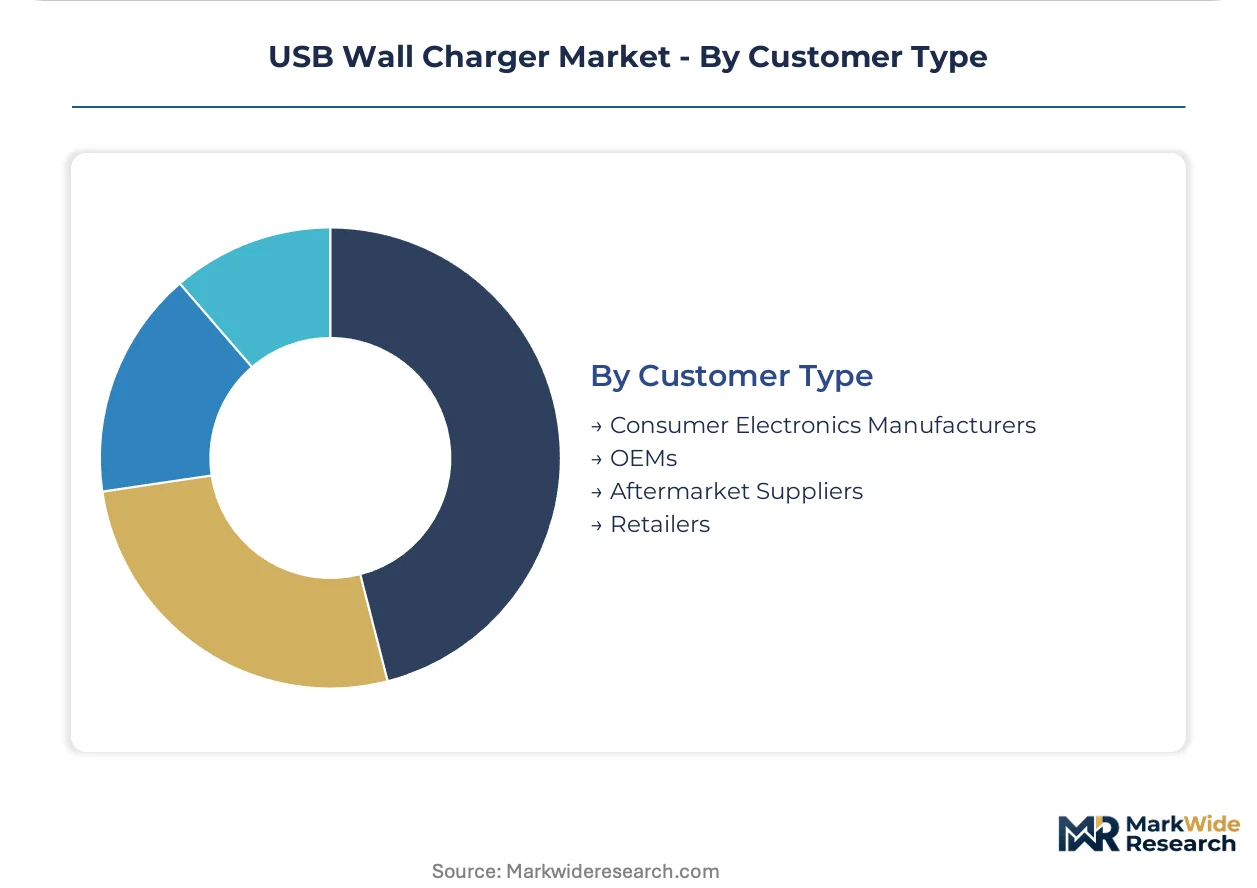
Customer Type:
Channel economics diverge sharply between bundled OEM supply and fragmented aftermarket retail.
- Aftermarket Suppliers:Brand recognition and safety certification visibility determine shelf placement economics in India's mobile accessory bazaars and North American electronics retail. BIS compulsory registration blocks uncertified imports, creating protected channels for compliant domestic assemblers.
- Retailers:Enterprise buyers at hospitality chains and commercial real estate operators are consolidating vendor panels and demanding installation, failure replacement, and end-of-life recovery services.
- Consumer Electronics Manufacturers:Handset and laptop OEMs specify inbox charger bundling with proprietary protocol support.
- OEMs:Automotive manufacturers are embedding high-power USB-C ports as standard equipment, opening fleet and aftermarket segments.
Aftermarket Suppliers dominate transaction velocity; Retailers are gaining share fastest as enterprise procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors global charger assembly capacity, with over seventy percent of worldwide production concentrated within a two-hundred-kilometer corridor spanning Guangdong Province. This manufacturing gravity shapes sourcing patterns across all major demand centers.
China
Guangdong and Jiangsu provinces drive export volume through vertically integrated semiconductor packaging and molding operations. MIIT enforces GB standards for domestic manufacturing quality thresholds. The Pearl River Delta cluster around Shenzhen and Dongguan houses GaN foundry partnerships and active clamp flyback topology integration.
United States
Enterprise procurement at hospitality chains and commercial real estate operators consolidates vendor panels for charging infrastructure amenities. FCC Part 15 governs electromagnetic compatibility certification for imported units. California and Texas distribution hubs handle bulk replenishment for technology leasing firms and co-working space fit-outs.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg embed high-power USB-C ports as standard equipment, opening fleet and aftermarket segments. The EU Radio Equipment Directive mandates USB Type-C standardization across member states. Hamburg and Munich serve as EMC pre-certification hubs for European market entry.
India
Aftermarket channels in Maharashtra and Karnataka move units through mobile accessory retail clusters where BIS registration visibility determines shelf placement. BIS compulsory registration scheme blocks uncertified imports, creating protected channels for compliant domestic assemblers. Delhi-NCR and Chennai host emerging charger assembly operations targeting price-sensitive replacement demand.
Japan
Consumer preference for compact form factors sustains premium positioning for high-density GaN architectures. METI oversees electrical appliance safety standards under the Denan Law. Tokyo and Osaka distribution networks prioritize certified products with full material disclosure documentation for REACH compliance.
USB Wall Charger Market Competitive Landscape
Technology licensing dominates the current landscape as semiconductor foundries and power IC designers monetize GaN integration IP. The vendor base clusters into three tiers: integrated OEMs bundling proprietary protocols, specialist accessory brands competing on certification visibility, and contract manufacturers serving private-label retail programs. Strategic archetypes include GaN early-movers leveraging foundry partnerships, multi-port specialists targeting household consolidation trends, and automotive-focused suppliers embedding vehicle USB-C integration. Portfolio diversification and geographic expansion represent the dominant competitive moves as players navigate divergent certification timelines across export markets.
Among China-based fabricators, Anker Innovations and Baseus occupy positions exemplifying vertical integration across GaN supply partnerships and multi-port segment leadership. Samsung Electronics anchors the integrated OEM tier through proprietary Super Fast Charging protocols bundled with flagship devices. Apple sits within the ecosystem lock-in archetype via magnetic alignment standards that merge with USB-PD negotiation protocols.
| Leading Market Players |
|---|
| Anker Innovations |
| Belkin International |
| Koninklijke Philips |
| Aukey |
| RAVPower |
| Samsung Electronics |
| Apple |
| Xiaomi Corporation |
| Baseus |
| Others |
Pricing and Supply Chain Analysis
GaN wafer costs cascade through three pricing tiers as foundry scaling in Taiwan and mainland China compresses input expenses for premium architectures while silicon-based alternatives defend share in price-sensitive bulk procurement. Shenzhen assembly clusters translate component savings into tiered positioning across North American retail, European distributor networks, and Indian aftermarket channels where BIS certification visibility commands shelf placement premiums.
Pricing Analysis
Input-cost pass-through from GaN semiconductor foundries drives tier compression as Taiwan Semiconductor Manufacturing and mainland China packaging houses expand 6-inch wafer capacity. Three-tier pricing structure across premium GaN, standard silicon-PD, and economy USB-A levels separates based on wattage density and protocol complexity. Pricing pressure stems from Shenzhen-Shenzhen supply concentration enabling rapid feature replication across private-label programs. Aftermarket suppliers in India and Southeast Asia exhibit highest price sensitivity, while enterprise procurement at North American hospitality chains prioritizes total cost of ownership guarantees over unit economics.
Supply Chain Analysis
Freight cost volatility from Guangdong Province export hubs to North American distribution centers and European port complexes shapes inventory positioning strategies for seasonal retail cycles. Manufacturing concentrates in China, Taiwan, and Vietnam where semiconductor packaging and plastic molding operations cluster within 200-kilometer corridors. Raw material dependencies span gallium nitride wafers, copper magnet wire, and flame-retardant engineering plastics subject to REACH substance restrictions. Single-source vulnerability concentrates in Shenzhen assembly capacity exposed to regional disruption risks. Distribution runs through electronics retail chains, mobile accessory bazaars, and direct-to-consumer platforms with divergent certification documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
USB wall charger demand compounds steadily as multi-device households consolidate charging infrastructure and regulatory mandates accelerate replacement cycles across consumer electronics supply chains.
For Market Incumbents: Extend GaN foundry partnerships to lock in wafer allocation ahead of mid-market price erosion, while deepening certification investment for India's BIS registration scheme to defend aftermarket shelf placement against emerging domestic assemblers. Threats concentrate in private-label entrants replicating multi-port architectures through Shenzhen contract manufacturers. Priority levers include captive supply of active clamp flyback controller ICs and EMC pre-certification capacity expansion in Hamburg and Shenzhen labs. For New Entrants and Emerging Players: Begin with automotive USB-C integration segments where fleet procurement and aftermarket vehicle fit-outs remain underpenetrated by established accessory brands. White-space targets include embedded high-power charging ports for commercial real estate tenant amenities and hybrid dock-wall combinations leveraging Qi2 magnetic alignment. Most penetrable geography centers on India's protected BIS-compliant channels where certification barriers block incumbent import volumes. Go-to-market angle emphasizes installation and failure replacement service bundling for enterprise hospitality procurement panels. For Investors and Strategic Acquirers: Consolidation pressure builds where GaN topology IP and EMC pre-certification talent concentrate among mid-cap specialists lacking scale to negotiate foundry volume discounts. Long-term viability frames this market as a replacement-demand compounder tethered to device refresh cycles and regulatory harmonization mandates. Acquisition target archetype includes GaN early-movers with active clamp flyback integration expertise and established India BIS registration pathways. Signal to watch: divergence between European harmonized standards and emerging economy certification timelines forcing dual-SKU product strategies.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Partnership Expansion | Secures wafer allocation from Taiwan Semiconductor Manufacturing for 65W-plus architectures. |
| BIS Registration Acceleration | Unlocks protected aftermarket channels in Maharashtra and Karnataka retail clusters. |
| Automotive USB-C Integration | Captures fleet procurement from Bavarian and Baden-Württemberg OEM standardization programs. |
| EMC Pre-Certification Capacity Buildout | Reduces bottlenecks at Hamburg and Shenzhen labs for European market entry. |
| Enterprise Service Bundling | Aligns with North American hospitality chain framework agreements covering installation and recovery. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with power electronics procurement managers, semiconductor foundry account executives, EMC testing laboratory directors, and mobile accessory retail distributors with secondary validation. Secondary sources encompassed MIIT GB standard filings, BIS compulsory registration databases, FCC Part 15 equipment authorization records, EU Radio Equipment Directive implementation guidance, and SEC 10-K disclosures from listed component suppliers. Bottom-up demand modeling across port configurations and wattage tiers triangulated against top-down semiconductor wafer shipment aggregates.
Historical reference periods anchored the projection horizon to documented replacement cycle patterns and regulatory implementation timelines without year-specific anchoring. Segmentation dimensions modeled spanned port configuration, semiconductor technology, power delivery protocol, application device category, and regional certification cluster. CAGRs derived from fitted growth curves applied to installed base turnover assumptions and protocol migration rates. Industry-specific inputs included GaN wafer cost curve trajectories from Taiwan and mainland China foundry expansion plans and EU common charger mandate compliance deadlines.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting Guangdong export corridors, breakthrough solid-state power conversion technologies displacing GaN architectures, and pandemic-scale logistics disruptions reconfiguring ocean freight networks. Forecasts reflect documented assumptions regarding foundry scaling timelines and regulatory harmonization velocity. A model refresh is warranted upon material change in EU-India regulatory divergence patterns or GaN-on-silicon carbide substrate cost breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Breadboards Market
Electronic Components
Pulse Width Modulation Controllers Market
Electronic Components
Ceramic Capacitors Market
Electronic Components
Power Inductors Market
Electronic Components
Crystal Oscillators Market
Electronic Components
Ceramic Disc Capacitor Market
Electronic Components
Digital Class-D Amplifier Market
Electronic Components
Frequency Control and Timing Devices Market
Electronic Components
Audio and Visual Public Address System Market
Electronic Components
High Temperature Capacitor Market
Electronic Components
Global Circuit Protection Market
Electronic Components
Docking Station Market
Electronic Components
Flexible Heater Market
Electronic Components
Asia Pacific Safety Relays and Timers Market
Electronic Components
Graphics Add-In Board (AIB) Market
Electronic Components
Printed Circuit Board Market