
 Digital Semiconductors Market | 2026-2036
Digital Semiconductors Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Semiconductors Market Outlook
Foundry capacity in East Asia is hardening as the primary constraint on digital semiconductor availability. TSMC leverages its dominance in advanced-node manufacturing to anchor global supply for high-performance computing and AI accelerators. Samsung Electronics competes through vertical integration across memory and logic, while Intel positions its IDM strategy to regain process leadership.
Digital semiconductors are integrated circuits that process discrete binary signals through transistor-based architectures, typically fabricated on silicon wafers using photolithography with feature sizes now reaching angstrom-scale precision. Their primary purpose is to execute computational, control, and signal-processing functions across electronic systems. Microprocessors command substantial margin pools in data center and personal computing applications, while FPGAs are gaining structural importance in adaptive AI inference workloads where programmability offsets volume economics. Automotive Systems represent the fastest-growing application segment as electrification architectures demand real-time processing for powertrain control and sensor fusion.
The U.S. CHIPS and Science Act, the EU Chips Act, and China's MIIT dual carbon goals are reshaping where fabrication capacity locates and which technologies receive sovereign subsidy. FDA and NHTSA standards in the United States, alongside ECHA REACH compliance in Europe, impose material purity and reliability requirements that filter market access for automotive-grade and medical-adjacent digital components. Stakeholders must monitor which regulatory jurisdictions successfully convert subsidy authorizations into operational wafer starts, as this determines cost-competitive supply availability for the next fabrication cycle.
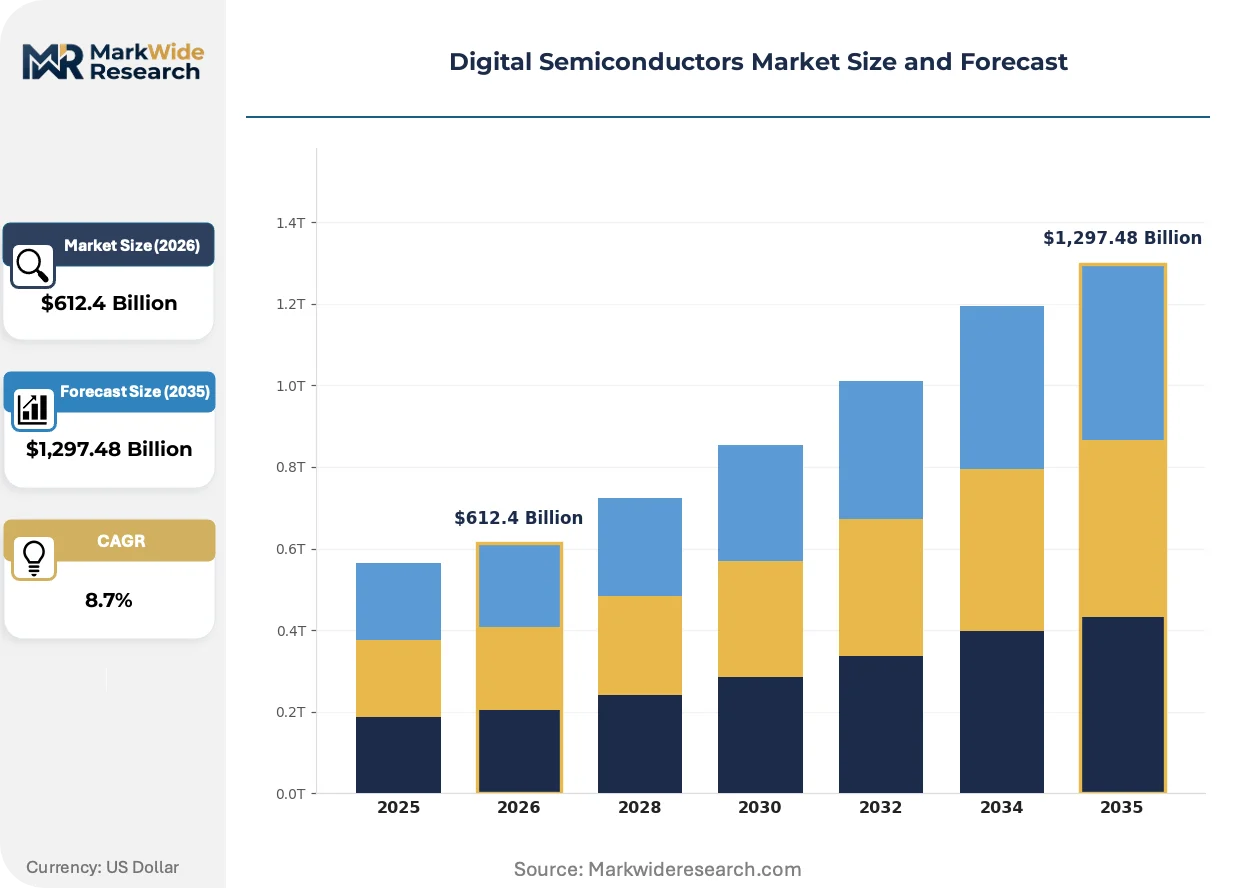
Market Dynamics
Foundry capacity concentration in Taiwan and sovereign subsidy races across Germany, Japan, and the United States are redrawing where advanced-node wafers originate and who controls access to them.
Growth Catalysts
- Automotive electrification architectures:Battery management systems and inverter controls require real-time digital processing, expanding semiconductor content per vehicle as OEMs deploy 800V platforms and silicon carbide powertrains.
- The EU Chips Act:Subsidy authorizations exceeding €43 billion are accelerating cleanroom construction in Dresden and Leuven, attracting equipment vendors and specialty chemical suppliers to co-locate.
- Advanced packaging:Chiplet-based designs using 2.5D and 3D integration are extending Moore's Law economics without sole reliance on lithography shrinks, opening new margin pools for OSATs.
Market Restraints
- Neon gas supply concentration:Ukrainian purification facilities historically supplied half of global semiconductor-grade neon; sustained conflict has forced fabs to qualify alternative sources in Algeria and China at elevated cost.
- Extreme ultraviolet lithography tool scarcity:ASML's annual output of high-NA EUV systems remains capped below ten units, constraining 2nm-class ramp schedules for all but the most capitalized foundry customers.
- ECHA REACH substance restrictions:Per- and polyfluoroalkyl substance phaseouts are complicating wet chemistry formulations used in etch and clean processes, requiring multi-year reformulation cycles.
Strategic Opportunities
- India's semiconductor mission:PLI scheme disbursements and Dholera fab site development are attracting display driver and power management IC specialists seeking tariff-advantaged access to domestic electronics manufacturing.
- Edge AI inference at automotive tier-1s:Sensor fusion processors for L2+ autonomy are migrating from centralized domain controllers to distributed smart cameras, creating socket opportunities for low-latency accelerators.
- Japan's METI semiconductor revitalization:Kioxia-Western Digital merger facilitation and Rapidus 2nm consortium funding are rebuilding logic fabrication competence on Hokkaido and Kyushu.
Industry Challenges
- Process engineer scarcity:Atomic-scale deposition and etch expertise resides with a shrinking cohort of specialists trained at IMEC, TEL, and Applied Materials; universities in Arizona and Saxony are struggling to replicate this tacit knowledge pipeline.
- Automotive qualification timelines:AEC-Q100 Grade 0 certification for under-hood temperatures demands 18-24 months of stress testing, compressing design windows for electrification platforms with 36-month vehicle development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Semiconductors Market |
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,297.48 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Digital Signal Processors, Microprocessors, FPGAs Application: Consumer Electronics, Telecommunications, Automotive Systems, Industrial Automation Technology: CMOS, BiCMOS, GaN, SiGe End User: OEMs, Tier-1 Suppliers, Distributors, Aftermarket Providers |
| Companies Covered | NVIDIA, TSMC, Broadcom, Intel, Samsung Electronics, Qualcomm, AMD, Texas Instruments, MediaTek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Semiconductors Market Strategic Shifts
Silicon photonics, sovereign capacity mandates, and disaggregated procurement models are simultaneously redefining how digital semiconductors are fabricated, regulated, and acquired across computing and automotive end-uses.
Silicon photonics is converging with CMOS logic to overcome electrical interconnect bandwidth limits in AI training clusters. Hyperscale datacenter operators in Oregon and Ireland are deploying co-packaged optics at 51.2 Tbps switch capacities, collapsing power consumption per bit transmitted. This convergence is compressing the market for traditional pluggable transceivers while elevating photonic foundry partnerships with GlobalFoundries and Tower Semiconductor.
The EU AI Act's risk classification framework imposes conformity assessment obligations on high-risk AI systems incorporating digital semiconductors. Medical device and autonomous vehicle manufacturers must now document chip-level traceability and bias mitigation capabilities through notified body review. German automotive OEMs are responding by mandating ISO 26262 ASIL-D certification for all neural network accelerators deployed in L3 autonomy platforms.
Consolidated procurement consortia among European automotive tier-1s are displacing individual foundry negotiations. Bosch, Continental, and ZF have formed a joint silicon sourcing entity to secure 28nm and 40nm capacity at GlobalFoundries Dresden and TSMC specialty nodes, pooling volume commitments and qualification costs. This behavior is most visible in power management and microcontroller categories where single-source exposure previously dominated.
Digital Semiconductors Market Segmentation
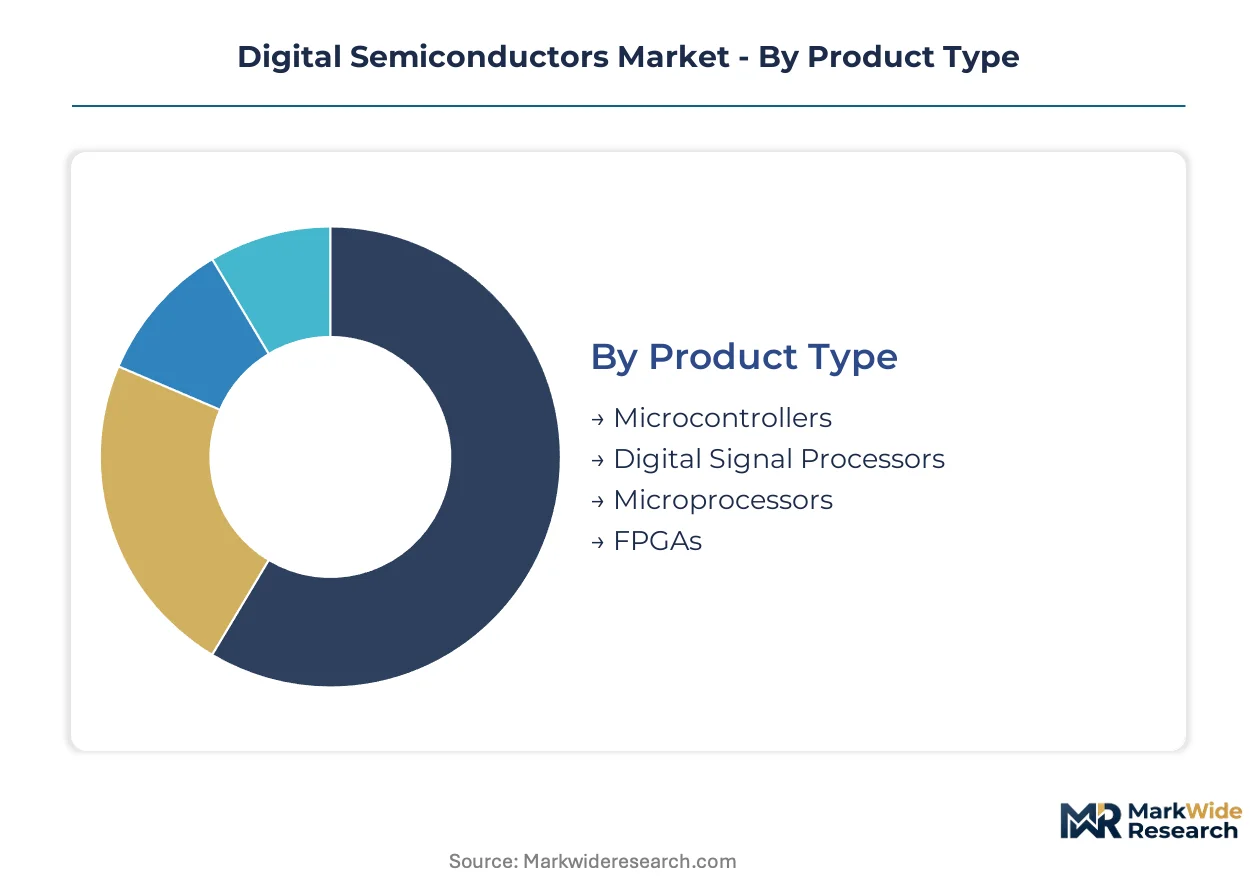
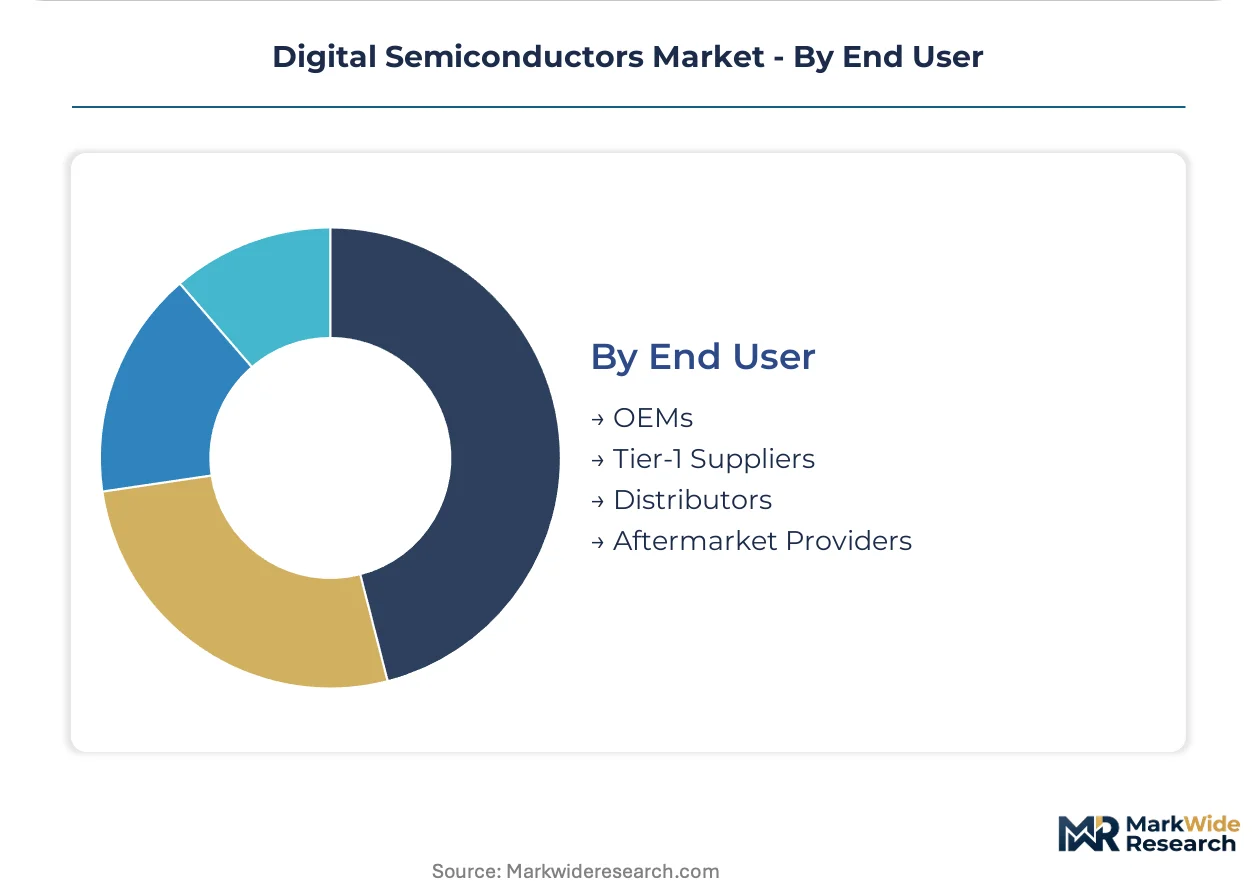
Digital semiconductor procurement varies sharply by segment in certification burden, cost tier, and supply chain configuration. Buyers must map these dimensions against their own qualification timelines and volume profiles.
Product Type:
Microprocessors carry ISO 26262 ASIL-D and AEC-Q100 Grade 0 burdens for automotive deployment; FPGAs face EU AI Act conformity assessments for high-risk inference applications.
- Microcontrollers:Embedded control units integrate CPU core with memory and peripherals on single die. Automotive body electronics and powertrain modules in Germany and Japan concentrate demand as 800V electrification architectures proliferate. Leading the category by volume: Microcontrollers. Growing fastest: FPGAs.
- Digital Signal Processors:Specialized arithmetic units execute multiply-accumulate operations for real-time signal conditioning. 5G baseband processing in South Korea and base station deployments across India drive procurement under BIS and TRAI equipment certification frameworks.
- Microprocessors:General-purpose compute engines with complex instruction pipelines dominate data center and personal computing sockets. Hyperscale operators in Oregon and Ireland specify chiplet-based designs with co-packaged optics.
- FPGAs:Field-programmable gate arrays enable post-fabrication logic reconfiguration for adaptive AI inference workloads. Sensor fusion processors for L2+ autonomy migrate from centralized domain controllers to distributed smart cameras at Continental and Bosch.
Microcontrollers anchor volume; FPGAs climb fastest on AI inference demand.
Application:
Automotive Systems command the steepest certification stack with AEC-Q100, ISO 26262, and NHTSA traceability; Consumer Electronics operate under lighter FCC and CE self-declaration regimes.
- Consumer Electronics:Smartphones, tablets, and wearables require compact, thermally constrained processors. Qualcomm and MediaTek supply 4nm mobile SoCs to assembly plants in Vietnam and India under BIS electronics manufacturing PLI schemes.
- Telecommunications:Base station infrastructure and optical transport equipment demand high-reliability digital components. Ericsson and Nokia procurement in Sweden and Finland specifies extended temperature grade FPGAs for rural cell tower deployments.
- Automotive Systems:Electrification architectures demand real-time processing for battery management, inverter control, and sensor fusion. 800V silicon carbide powertrains at BMW and Hyundai expand semiconductor content per vehicle through domain controller consolidation.
- Industrial Automation:Programmable logic controllers and motor drives require deterministic latency and electromagnetic immunity. Siemens and Rockwell Automation specify IEC 61131-3 compliant processors for smart factory deployments in Saxony and Michigan.
Automotive Systems expands most quickly on electrification; Consumer Electronics retains volume leadership.
Technology:
CMOS dominates cost-sensitive volume; GaN and SiGe carry premium pricing for RF and power applications requiring specialized foundry access.
- CMOS:Complementary metal-oxide-semiconductor logic provides the foundational transistor architecture for digital integration. TSMC, Samsung, and Intel foundries in Taiwan, South Korea, and Arizona concentrate leading-edge and mature-node capacity for this technology class.
- BiCMOS:Bipolar-CMOS integration combines high-speed bipolar transistors with low-power CMOS for mixed-signal processing. RF transceivers in 5G mmWave modules and automotive radar sensors at NXP and Infineon leverage this technology.
- GaN:Gallium nitride wide-bandgap semiconductors enable high-frequency switching for power electronics and RF amplification. Navitas and Infineon supply GaN power ICs to notebook adapter and data center power supply manufacturers under stricter efficiency mandates from DOE and EU Ecodesign.
- SiGe:Silicon-germanium heterojunction bipolar transistors deliver GHz-range performance at lower cost than III-V compounds. Tower Semiconductor and GlobalFoundries produce SiGe BiCMOS for automotive radar and satellite communication front-ends.
CMOS commands volume supremacy; GaN gains fastest on power density requirements.
End User:
OEMs and Tier-1 Suppliers carry direct regulatory liability; Distributors and Aftermarket Providers operate under lighter traceability obligations.
- OEMs:Original equipment manufacturers specify semiconductor content for finished electronic systems. Tesla, Apple, and Samsung Electronics negotiate directly with foundries for leading-edge wafer allocation, bypassing distribution for critical silicon.
- Tier-1 Suppliers:Bosch, Continental, and Denso integrate semiconductors into subsystems for vehicle OEMs. These suppliers pool procurement through consolidated sourcing entities to secure 28nm and 40nm capacity at GlobalFoundries Dresden.
- Distributors:Arrow Electronics and Avnet manage inventory and logistics for mid-volume customers lacking direct foundry relationships. Distributors qualify alternative sources for mature-node microcontrollers and power management ICs during supply constraints.
- Aftermarket Providers:Independent repair and refurbishment specialists source legacy semiconductors for extended product support. These buyers depend on distributor excess inventory and authorized aftermarket programs from NXP and Renesas.
Tier-1 Suppliers drive fastest procurement growth; OEMs retain largest direct spend.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity neon gas extraction in Ukraine's Black Sea corridor historically anchored Eastern European supply chains for lith-grade feedstock, forcing fabs worldwide to requalify Algerian and Chinese purification sources at elevated cost.
United States
CHIPS Act disbursements exceeding $52 billion are accelerating cleanroom construction in Chandler, Arizona and Albany, New York. The NHTSA mandates AEC-Q100 traceability for all automotive-grade silicon deployed in advanced driver-assistance platforms. Intel's IDM 2.0 fabrication complex in Ohio represents the largest greenfield logic investment since the 1990s.
Germany
BMW and Volkswagen procurement teams are consolidating 800V powertrain semiconductor demand through joint sourcing entities. The EU Chips Act channels €43 billion toward Dresden and Leuven fab clusters under ECHA REACH substance compliance frameworks. Bosch's 300mm facility in Dresden now qualifies 28nm automotive microcontrollers for European OEM electrification timelines.
China
MIIT dual carbon mandates are redirecting foundry investment toward mature-node specialties in power management and display drivers. SAMR antitrust reviews have slowed foreign equipment procurement for leading-edge expansion. Yangtze Memory Technologies and SMIC anchor domestic fabrication in Wuhan and Shanghai with concentrated state-backed capitalization.
Japan
Rapidus consortium funding from METI targets 2nm logic production on Hokkaido by 2027, rebuilding process competence lost to TSMC and Samsung. Kioxia and Western Digital merger facilitation concentrates NAND flash supply from Yokkaichi and Kitakami. Automotive tier-1s at Denso and Renesas qualify SiGe BiCMOS for 77GHz radar modules under JIS reliability standards.
South Korea
Samsung Electronics and SK Hynix dominate memory fabrication in Pyeongtaek and Icheon, anchoring global DRAM and NAND supply. The MFDS regulates traceability for medical-adjacent semiconductors in diagnostic imaging equipment. Government K-Chips subsidies are diversifying beyond memory into system semiconductors for AI accelerators and automotive SoCs.
Digital Semiconductors Market Competitive Environment
Global majors compete with regional champions across foundry access and sovereign subsidy capture, producing a tiered structure where capital intensity filters participation. The vendor base concentrates around three strategic archetypes: integrated device manufacturers seeking process leadership, pure-play foundries monetizing capacity scarcity, and fabless designers extracting architecture value. Dominant competitive moves include backward integration into captive wafer supply and strategic partnerships for advanced packaging capacity.
Within the foundry tier, TSMC anchors advanced-node availability for hyperscale compute and AI accelerators, while Samsung Electronics occupies a position spanning memory and logic fabrication. Among IDM revitalization efforts, Intel exemplifies the capital-intensive push to regain process parity through sovereign-subsidized domestic capacity. NVIDIA represents the fabless architecture archetype, extracting margin through GPU and AI accelerator design without fabrication ownership.
| Leading Market Players |
|---|
| NVIDIA |
| TSMC |
| Broadcom |
| Intel |
| Samsung Electronics |
| Qualcomm |
| AMD |
| Texas Instruments |
| MediaTek |
| Others |
Value Chain & Pricing Dynamics
Neon gas spot prices from Ukrainian and Algerian purification facilities cascade through lithography cost structures into tiered wafer pricing at foundries serving automotive and hyperscale compute segments. Contract structures for AEC-Q100 Grade 0 silicon bundle 18-24 month qualification warranties against unit price premiums, while unbundled spot purchases for consumer-grade microcontrollers trade at narrower margins with limited traceability guarantees.
Pricing Analysis
Warranty and qualification bundling separates automotive-grade silicon from commodity tiers, with AEC-Q100 and ISO 26262 ASIL-D certifications commanding sustained premiums against unqualified consumer alternatives. Three-tier pricing structure across automotive-certified, industrial-grade, and consumer-economy levels reflects divergence in stress-testing investment and failure-liability exposure. Cost compression in mature-node microcontrollers intensifies as consolidated procurement consortia pool volume commitments at GlobalFoundries Dresden and TSMC specialty nodes. Tier-1 automotive suppliers exhibit lowest price sensitivity due to traceability mandates, while aftermarket refurbishment specialists face acute margin pressure on legacy socket sourcing.
Supply Chain Analysis
Domestic-content mandates under the U.S. CHIPS Act and EU Chips Act are redirecting equipment procurement and wafer starts toward Arizona, Dresden, and Leuven clusters. Geographic concentration rests on Taiwan for leading-edge logic, South Korea for memory fabrication, and Japan for specialty SiGe and power discrete processes. Raw material dependencies draw from Ukrainian and Algerian neon purification, Chinese rare earth processing, and Belgian photoresist chemical formulation. Single-source vulnerability around ASML EUV lithography systems constrains 2nm-class ramp schedules for all foundry customers. Distribution runs through consolidated Tier-1 sourcing entities pooling demand at Bosch, Continental, and Denso alongside direct OEM negotiations at Tesla and Apple.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around capital intensity barriers, with sovereign subsidy capture and process engineer scarcity forcing sub-scale foundry customers toward acquisition or exit.
For Market Incumbents: Anchor advanced-node leadership through captive EUV tool allocation and HBM3E packaging partnerships, while defending mature-node sockets against emerging Indian and Chinese foundry entrants via AEC-Q100 qualification lock-in at European automotive OEMs. Process engineer scarcity at IMEC-trained cohorts limits rapid competitor replication of atomic-scale deposition expertise. For New Entrants and Emerging Players: Direct-to-Tier-1 digital procurement platforms offer lower customer acquisition friction than foundry direct sales for mid-volume microcontroller and power management IC buyers. India's Dholera fab site and PLI tariff advantages present the most penetrable geography for display driver and PMIC specialists lacking legacy automotive qualification burdens. Target automotive edge-AI inference sockets migrating from centralized domain controllers to distributed smart camera modules at Continental and Bosch. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialty analog and power discrete IDMs with captive 200mm capacity in Germany and Japan as automotive electrification demand outstrips mature-node supply expansion. Long-term viability over the next fabrication cycle hinges on sovereign subsidy conversion into operational wafer starts rather than authorized disbursements. Monitor qualification timeline compression at AEC-Q100 Grade 0 as the inflection signal for automotive socket accessibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Wafer Supply | Intel's IDM 2.0 strategy secures leading-edge capacity against TSMC allocation constraints. |
| Advanced Packaging Partnership | Co-packaged optics deployment at 51.2 Tbps collapses power consumption for hyperscale switches. |
| Consolidated Procurement Consortium Formation | Bosch, Continental, and ZF pool volume commitments to secure 28nm capacity at GlobalFoundries Dresden. |
| Sovereign Subsidy Capture | EU Chips Act disbursements exceeding €43 billion accelerate cleanroom construction in Leuven and Dresden. |
| Chiplet-Based Design Adoption | 2.5D and 3D integration extends Moore's Law economics without sole reliance on lithography shrinks. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with foundry operations executives, Tier-1 automotive procurement directors, semiconductor equipment vendor sales leads, and ECHA regulatory affairs specialists. Secondary validation drew from SEC 10-K disclosures, EU Chips Act implementation reports, FDA medical device semiconductor guidance, and IHS Markit vehicle production databases. Bottom-up wafer demand modeling and top-down foundry revenue triangulation cross-checked segment-level outputs.
Granularity-level modeling disaggregated projections across product type, application, technology node, and end-user archetype throughout the forecast period. Segmentation dimensions included automotive electrification content per vehicle, data center AI accelerator deployment, and sovereign capacity buildout progress by geography. CAGRs were derived from fitted growth curves against historical wafer shipment trajectories, with sensitivity testing around EUV tool delivery schedules and automotive qualification timeline compression.
The model holds under sustained sovereign subsidy disbursement and stable neon gas requalification timelines; deviation in ASML equipment export restrictions or sustained Taiwan Strait logistics disruption would shift foundry capacity availability assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Logic Semiconductor Market
Semiconductors
IV-IV Compound Semiconductor Market
Semiconductors
Chiplets Market
Semiconductors
Semiconductor in Military and Aerospace Market
Semiconductors
Wide Bandgap Semiconductors Market
Semiconductors
Japan Discrete Semiconductors Market
Semiconductors
Global Copper Indium Gallium Selenide (CIGS) Solar Cells Market
Semiconductors
South Korea Discrete Semiconductors Market
Semiconductors
Semiconductor Market
Semiconductors
Asia Pacific Flash Memory Market
Semiconductors
Global Computer Microchip Market
Semiconductors
Germanium Semiconductor Market
Semiconductors
Organic Electronics Market
Semiconductors
Global Organic Semiconductor Market
Semiconductors
Resistive RAM Market
Semiconductors
Semiconductor Target Market